
 Scanning Electron Microscopes (SEM) Market | 2026-2036
Scanning Electron Microscopes (SEM) Market Size, Share, and Industry Trends Forecast 2026-2036
Scanning Electron Microscopes (SEM) Market Insights
Semiconductor inspection is repositioning as the dominant demand vector within the SEM landscape. Thermo Fisher Scientific leverages its cryo-EM adjacent expertise to anchor high-resolution semiconductor metrology workflows. JEOL Ltd. sustains leadership in electron optics manufacturing through in-house column production. Hitachi High-Tech Corporation differentiates via focused ion beam integration with SEM platforms for failure analysis.
Scanning Electron Microscopes employ focused electron beams with accelerating voltages typically ranging from 0.1 to 30 kV to generate topographical and compositional imagery at nanometer resolution, serving quality control and materials characterization across industrial and academic settings. Field Emission SEM systems command premium positioning due to their superior beam coherence for sub-nanometer imaging, while Environmental SEM variants address growing demand for hydrated or non-conductive sample analysis without extensive preparation. Semiconductor inspection applications absorb the largest share of installed base upgrades as node shrinkage below 3nm demands angstrom-level defect detection.
FDA oversight of diagnostic SEM applications in healthcare facilities, combined with EPA hazardous substance restrictions on electron microscope manufacturing inputs, elevates compliance costs for new market entrants. CE marking under the EU MDR and RoHS substance limitations constrain component sourcing and extend product validation cycles. Stakeholders must monitor evolving dual-use export controls on electron beam technology as geopolitical competition over semiconductor tooling intensifies.
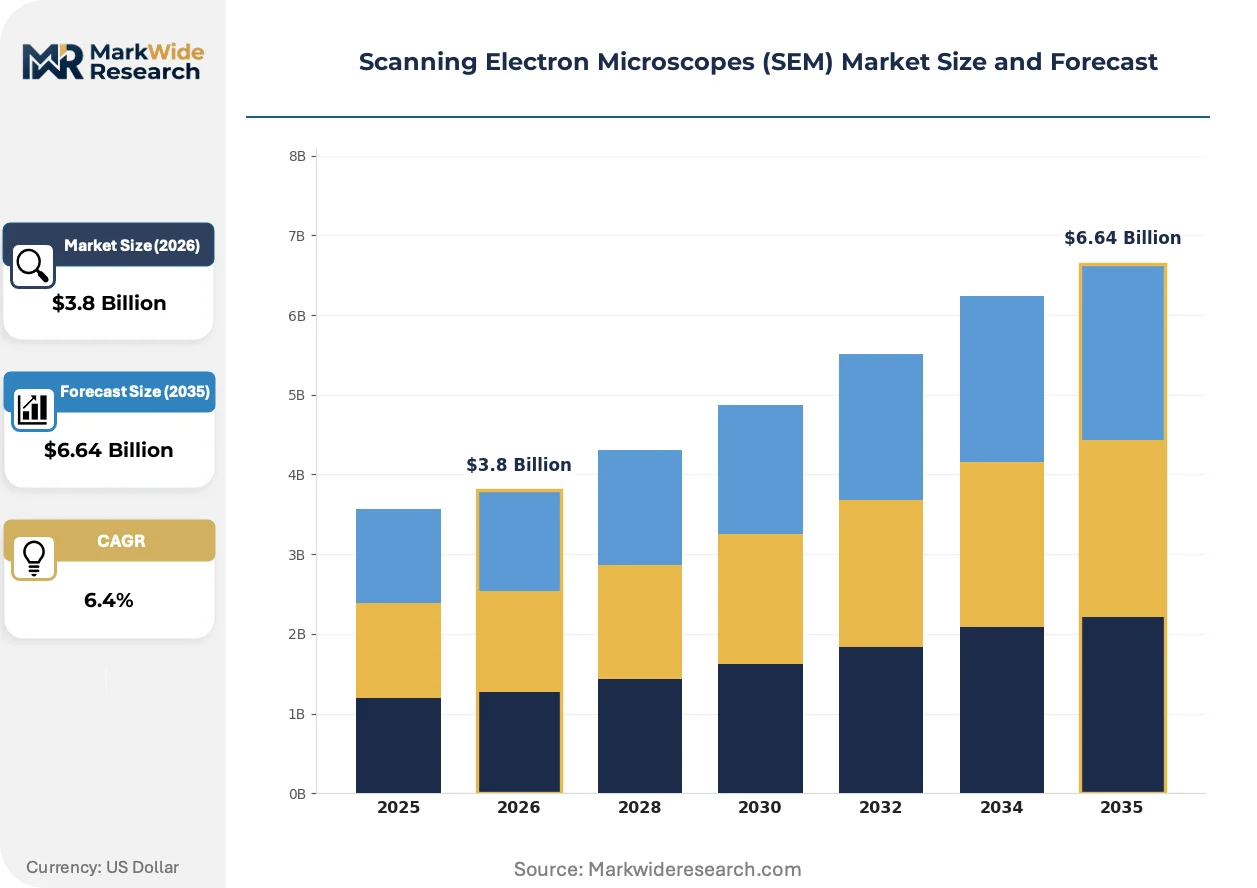
Market Dynamics
Node shrinkage below 3nm in semiconductor fabrication is forcing angstrom-level metrology requirements that strain existing electron optics capabilities and accelerate replacement cycles across foundry inspection floors.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of sulfur hexafluoride and perfluorocarbons is compelling manufacturers to redesign vacuum systems and electron column seals, creating upgrade demand for compliant instrument platforms.
- South Korea's Pyeongtaek cluster:Samsung and SK Hynix expansion around this semiconductor hub concentrates procurement volume for high-throughput defect review SEMs.
- Environmental SEM variants:Hydrated sample imaging without conductive coating protocols is opening materials science and biological applications previously blocked by preparation constraints.
Market Restraints
- Electron source material volatility:Tungsten filament and CeB6 cathode supply concentrates in Chinese rare earth processing, exposing cost and availability risk to column manufacturers.
- RoHS substance restrictions:Lead-free solder mandates and cadmium limitations in EU electronics manufacturing extend validation timelines for new instrument designs by 8-14 months.
- Atomic force microscopy substitution:AFM platforms achieve comparable sub-nanometer resolution for surface roughness applications at lower capital intensity, pressuring entry-level SEM positioning.
Strategic Opportunities
- India's PLI scheme for semiconductors:Domestic fab incentives at Gujarat and Assam sites will seed first-wave metrology demand as fabrication capacity localizes.
- Cryo-EM workflow convergence:Integration of vitrification sample handling with semiconductor failure analysis is creating hybrid instrumentation categories for 3D architecture debugging.
- CE marking under EU MDR:Diagnostic SEM applications in pathology labs now require medical device certification, opening premium service contracts for compliant platform vendors.
Industry Challenges
- Electron optics specialist scarcity:Column alignment and aberration correction expertise concentrates among retiring JEOL and Hitachi veterans, constraining service network expansion.
- Dual-use export control complexity:US Commerce Department restrictions on electron beam lithography adjacent technology are delaying licensing for advanced SEM shipments to Chinese research institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scanning Electron Microscopes (SEM) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard SEM, Field Emission SEM, Low Vacuum SEM, Environmental SEM Application: Material Science, Nanotechnology, Semiconductor Inspection, Life Sciences End User: Research Laboratories, Academic Institutions, Electronics Manufacturers, Healthcare Facilities Technology: Electron Beam Technology, X-ray Spectroscopy, 3D Imaging, Automated Analysis |
| Companies Covered | Thermo Fisher Scientific, Hitachi High-Tech Corporation, JEOL Ltd., Carl Zeiss, TESCAN Orsay Holding, Bruker Corporation, Oxford Instruments, Leica Microsystems, FEI Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scanning Electron Microscopes (SEM) Market Trends and Innovations
Artificial intelligence inference at the instrument edge is compressing image interpretation timelines and displacing offline workstation workflows across high-volume manufacturing floors.
Machine learning-based autofocus and stigmation correction is overtaking manual operator adjustment in semiconductor inspection applications. TSMC and Intel foundries now deploy this capability across 300mm wafer lines. The technology is compressing recipe setup time from hours to minutes while reducing skilled operator dependency.
The EU's F-Gas Regulation mandates refrigerant phase-down schedules through 2030 for vacuum pump systems. Equipment suppliers must redesign cooling architectures using hydrofluoroolefin alternatives. Semiconductor OEMs in Germany and France are prioritizing instrument platforms with certified low-global-warming-potential specifications.
Service contract unbundling is fragmenting traditional full-coverage agreements into modular tiers. Academic institutions and mid-tier foundries now procure column maintenance separately from software support and detector calibration. Japan's national laboratory network exhibits this pattern most acutely, driving vendors toward à-la-carte pricing structures.
Scanning Electron Microscopes (SEM) Market Segmentation
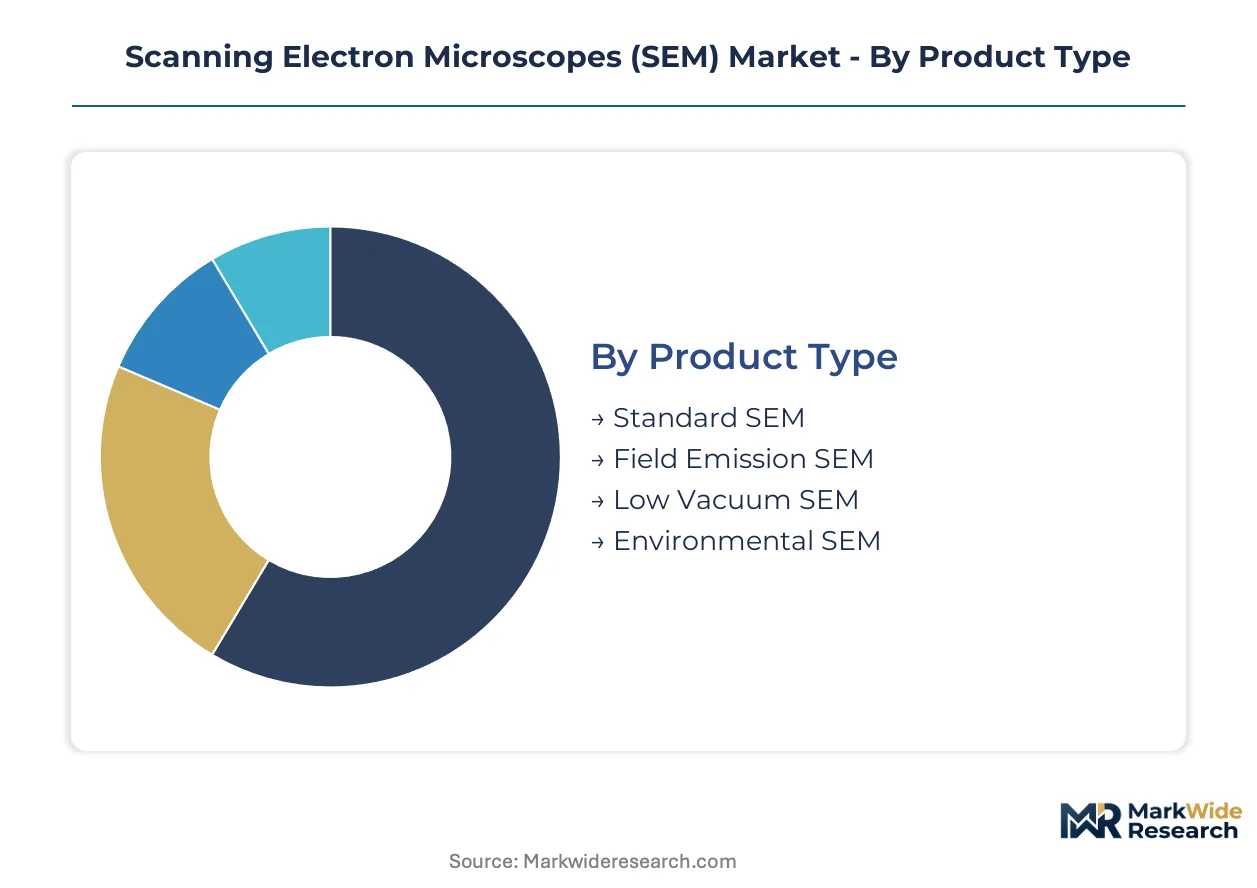
SEM procurement patterns diverge sharply across product architectures and end-use environments. Technical specifications governing beam coherence, vacuum requirements, and sample handling protocols determine pricing tiers and replacement cycles for each segment category.
Product Type:
Electron column manufacturing concentrates among Japanese and European specialists with proprietary optical designs.
- Field Emission SEM:Cold or Schottky emitters deliver superior beam coherence for sub-nanometer resolution. Samsung and TSMC foundries in South Korea and Taiwan absorb the majority of high-end unit shipments as angstrom-level metrology becomes mandatory below 3nm nodes.
- Standard SEM:Tungsten thermionic sources serve routine quality control and educational workflows. Academic institutions across Germany, Japan, and the United States maintain the largest installed base of these workhorse systems for materials characterization training.
- Low Vacuum SEM:Variable pressure chambers accommodate non-conductive specimens without conductive coating. Geological survey departments and archaeological conservation labs in France and Italy drive replacement demand.
- Environmental SEM:Pressurized sample chambers enable hydrated biological and soft material imaging. Pharmaceutical development facilities in Switzerland and the United Kingdom are expanding adoption for live-cell observation protocols.
Field Emission SEM absorbs the bulk of installed capacity; Environmental SEM is expanding most quickly as biological applications broaden.
Application:
Capital allocation across application areas tracks regional industrial specialization and national research priorities.
- Semiconductor Inspection:Wafer-level defect review and critical dimension measurement at sub-10nm precision. Foundry clusters around Pyeongtaek, Hsinchu, and Dresden concentrate procurement volume for high-throughput platforms.
- Material Science:Fracture surface analysis, grain structure mapping, and compositional profiling. German automotive suppliers and Japanese steelmakers deploy these systems for failure analysis and alloy development.
- Life Sciences:Cellular ultrastructure imaging and tissue pathology applications. Research hospitals in Boston and Stockholm are upgrading to cryo-compatible configurations for vitrified specimen analysis.
- Nanotechnology:Quantum dot characterization and carbon nanotube metrology. National laboratory networks in the United States and China sustain demand for specialized low-voltage imaging configurations.
Semiconductor Inspection commands the dominant share of new capital expenditure; Life Sciences is gaining share fastest as clinical diagnostic applications mature.
End User:
Procurement authority and budget cycles vary substantially across institutional categories.
- Electronics Manufacturers:Integrated device makers and contract foundries operate the highest utilization rates. Intel, Samsung, and TSMC facilities in Arizona, Pyeongtaek, and Tainan drive continuous upgrade cycles.
- Research Laboratories:National and corporate R&D centers require multi-modal flexibility. Max Planck Institutes and RIKEN campuses in Germany and Japan maintain diverse instrument portfolios.
- Academic Institutions:University core facilities serve multiple departments with shared access models. Public university systems in California and Texas are consolidating procurement through cooperative purchasing agreements.
- Healthcare Facilities:Hospital pathology departments and clinical reference labs. Mayo Clinic and Karolinska Institutet in the United States and Sweden are piloting diagnostic SEM workflows under FDA and EMA frameworks.
Electronics Manufacturers deploy the greatest installed capacity; Healthcare Facilities are climbing the fastest as regulatory pathways for diagnostic SEM crystallize.
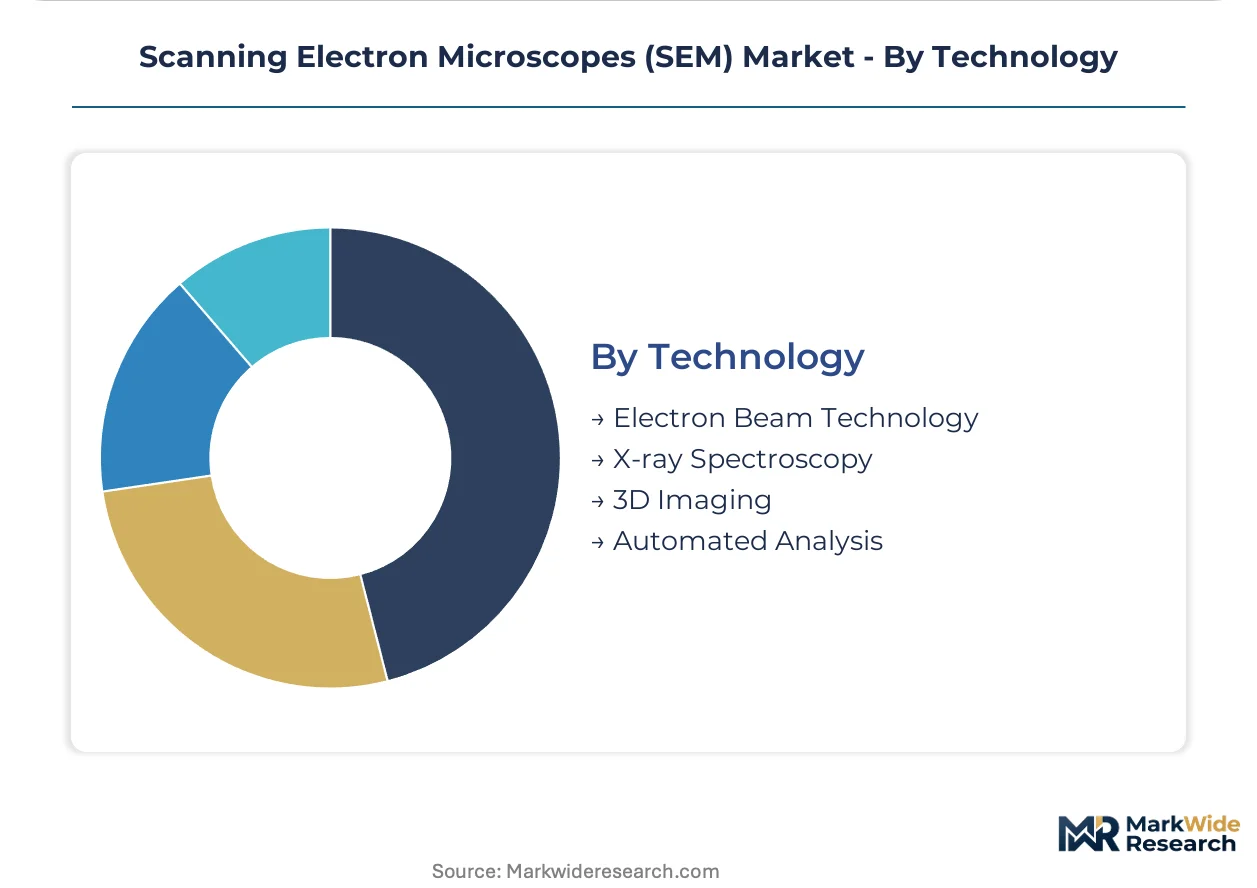
Technology:
Detector and software architectures are repositioning competitive differentiation among established vendors.
- Electron Beam Technology:Primary imaging modality with accelerating voltage and probe current control. Aberration-corrected columns from JEOL and Hitachi dominate advanced semiconductor metrology.
- 3D Imaging:Serial sectioning and tomographic reconstruction for volumetric analysis. Neuroscience research centers at MIT and ETH Zurich are driving adoption for connectomics applications.
- Automated Analysis:Machine learning-driven defect classification and recipe optimization. TSMC has deployed this capability across its 300mm wafer inspection lines in Taiwan.
- X-ray Spectroscopy:Energy-dispersive and wavelength-dispersive elemental analysis. Mining and metallurgy labs in Australia and Canada rely on these configurations for quantitative compositional mapping.
Electron Beam Technology anchors the majority of functional deployments; Automated Analysis is accelerating fastest as labor constraints intensify in high-volume manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pyeongtaek's semiconductor special economic zone concentrates the highest density of high-throughput SEM procurement. Samsung and SK Hynix expansion programs anchor equipment demand across East Asian fabrication corridors.
United States
Intel's Arizona and Ohio fab investments drive angstrom-level metrology demand. FDA oversight of diagnostic SEM applications in hospital pathology labs elevates compliance requirements for clinical instrument vendors. Greater Boston's research hospitals pilot cryo-EM workflows for vitrified tissue analysis.
South Korea
Samsung's 3nm node ramp at Pyeongtaek accelerates field emission SEM replacement cycles. MFDS medical device registration requirements extend validation timelines for diagnostic configurations. The Gwangju-Jeonnam corridor hosts secondary metrology demand from display panel manufacturers.
Japan
Tsukuba's national laboratory network sustains demand for multi-modal electron microscopy platforms. METI's semiconductor resilience subsidies support domestic instrument procurement. Osaka-Kobe industrial belt steelmakers deploy environmental SEM variants for fracture surface analysis without conductive preparation.
Germany
Automotive suppliers in Baden-Württemberg utilize SEM platforms for alloy development and failure analysis. EU F-Gas Regulation mandates hydrofluoroolefin refrigerant transitions for vacuum pump systems. Dresden's silicon Saxony cluster concentrates foundry inspection demand from Bosch and GlobalFoundries operations.
China
Domestic fab construction in Shanghai and Beijing strains electron optics supply chains. Dual-use export controls from the US Commerce Department delay licensing for aberration-corrected column shipments. Yangtze Memory Technologies and SMIC facilities drive localized metrology procurement despite technology access constraints.
Scanning Electron Microscopes (SEM) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates among Japanese and European column producers with proprietary optical designs. Three archetypes dominate: integrated conglomerates with adjacent life sciences portfolios, pure-play electron optics specialists, and analytical instrument houses with spectroscopy integration. Consolidation activity targets cryo-EM workflow convergence and semiconductor failure analysis hybridization.
Among diversified technology conglomerates, Thermo Fisher Scientific represents the life sciences-anchored archetype with cryo-EM adjacent expertise. JEOL Ltd. and Hitachi High-Tech Corporation exemplify the pure-play electron optics specialist model with in-house column manufacturing capabilities. These three occupy distinct positioning vectors based on vertical integration depth and end-market concentration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Hitachi High-Tech Corporation |
| JEOL Ltd. |
| Carl Zeiss |
| TESCAN Orsay Holding |
| Bruker Corporation |
| Oxford Instruments |
| Leica Microsystems |
| FEI Company |
| Others |
Pricing and Supply Chain Analysis
Field emission SEM systems command substantial premiums over thermionic alternatives, with that performance chasm translating into divergent sourcing strategies across the electron optics supply chain. Japanese column manufacturers capture pricing power through captive cathode production, while standard SEM vendors face margin compression from tungsten filament cost volatility.
Pricing Analysis
Expedited delivery timelines carry 15-25% pricing premiums for aberration-corrected field emission systems bound for Pyeongtaek and Dresden foundries. Three-tier pricing structure across premium, standard, and economy levels stratifies by beam coherence specifications and detector configuration. Cost compression in entry-level thermionic systems is intensifying because Chinese rare earth processing concentrates CeB6 cathode supply. Academic institutions exhibit highest price sensitivity, while semiconductor OEMs prioritize throughput metrics over capital expenditure.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's semiconductor self-sufficiency directives are reshaping sourcing patterns for electron column assemblies. Column manufacturing concentrates in Japan, Germany, and the Czech Republic, with aberration-corrected optics drawing from proprietary JEOL and Hitachi optical designs. Tungsten filaments, CeB6 cathodes, and precision electromagnetic coils constitute critical input dependencies. Single-source vulnerability concentrates in Chinese rare earth processing for cathode materials. Distribution runs through direct OEM relationships for high-end systems and regional distributors for academic configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron optics specialist scarcity constrains service network expansion, propping pricing for maintenance contracts and sustaining incumbent margins despite capital equipment cyclicality.
For Market Incumbents: Anticipate atomic force microscopy substitution pressure in surface roughness applications by deepening aberration-correction R&D investment and securing exclusive service contracts with TSMC and Intel foundries. Backward integration into CeB6 cathode production mitigates Chinese supply concentration risk. Prioritize cryo-EM workflow convergence for 3D semiconductor architecture debugging. For New Entrants and Emerging Players: Capture India's PLI-driven domestic fab buildout in Gujarat and Assam before established vendors consolidate metrology procurement relationships. Environmental SEM variants for pharmaceutical development facilities in Switzerland and the United Kingdom represent the most penetrable white space. Pursue à-la-carte service contract unbundling to compete against full-coverage incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in life sciences conglomerates seeking cryo-EM adjacent capabilities and semiconductor OEMs verticalizing into failure analysis tooling. Long-term viability hinges on aberration-correction IP depth and installed base service attachment rates. Watch dual-use export control licensing delays to Chinese research institutions as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cryo-EM Workflow Convergence | Hybrid instrumentation for 3D semiconductor architecture debugging captures TSMC and Intel qualification programs. |
| Backward Integration into Cathode Production | In-house CeB6 manufacturing insulates JEOL and Hitachi from Chinese rare earth processing volatility. |
| Service Contract Unbundling | À-la-carte pricing structures penetrate Japan's national laboratory network and mid-tier foundry segments. |
| Environmental SEM Platform Expansion | Pressurized chamber variants unlock pharmaceutical development facilities in Basel and Cambridge. |
| Aberration-Correction R&D Investment | Sub-angstrom resolution capabilities defend positioning against AFM substitution in sub-3nm node inspection. |
Research Methodology
Trade publications, patent filings, and customs records formed the secondary backbone, supplemented by primary interviews with electron optics engineers, semiconductor metrology directors, university core facility managers, and aftermarket service heads. Bottom-up and top-down triangulation validated procurement volume estimates across foundry, academic, and healthcare segments. Secondary sources included SEM vendor technical specifications, EU F-Gas Regulation compliance filings, and national laboratory instrument procurement databases.
Bottom-up modeling aggregated segment-level demand across product architectures, while top-down cross-checks anchored against regional fab capacity announcements and research funding allocations. Segmentation dimensions spanned emitter technology, vacuum configuration, end-use environment, and regional regulatory cluster. CAGRs derived from instrument replacement cycle analysis and node shrinkage-driven upgrade intensity. Forecast inputs incorporated dual-use export control licensing timelines and F-Gas Regulation phase-down schedules.
The model holds under stable geopolitical conditions for electron beam technology trade; deviation in export control enforcement or rare earth supply disruptions would shift replacement cycle assumptions. Forecasts reflect documented assumptions regarding node migration timelines and regulatory compliance cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Benchtop Ph Meters Market
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
Air Sampler Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Infrared Spectroscopy Devices Market
Analytical Instruments
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Metallurgical Microscope Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Analytical Instrumentation for Food Applications Market
Analytical Instruments
Network Analyzers Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Analytical Balance Market