
 Process Analytical Instrumentation Market | 2026-2036
Process Analytical Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Process Analytical Instrumentation Market Analytics
Pharmaceutical-grade PAT specifications is rotating toward higher-resolution mass spectrometry and inline chromatography platforms. ABB Ltd leverages its automation-software stack to embed analytical instruments within distributed control architectures. Emerson Electric Co. sustains competitive positioning through DeltaV-integrated spectroscopy modules that reduce sampling latency. Endress+Hauser Group Services AG anchors its presence in hygienic process connections for bioreactor monitoring applications.
Process analytical instrumentation comprises inline and at-line devices that measure chemical composition, physical properties, and molecular structure during manufacturing operations, typically operating at temperatures from -40°C to 400°C and pressures up to 100 bar to enable real-time decision-making without production interruption. Spectrometers and chromatography systems constitute the core revenue base where replacement cycles and compliance upgrades generate recurring demand, while mass spectrometers represent the fastest-expanding product tier as biopharma facilities adopt multi-attribute monitoring for complex therapeutics. Optical technology dominates installed capacity given its non-destructive measurement capabilities, though electrochemical platforms retain strong positions in aqueous process streams where pH and dissolved oxygen monitoring remain critical.
FDA process analytical technology guidance and EU EMA process validation frameworks mandate documented analytical control strategies for commercial drug substance and drug product manufacturing, directly shaping instrument qualification protocols and software validation requirements. ISO 17025 accreditation standards and USP general chapters on analytical instrument qualification further constrain vendor design choices and customer procurement criteria. Stakeholders must monitor evolving regulatory expectations around data integrity and artificial-intelligence-enabled analytical models to anticipate qualification burden shifts and compliance technology investments.
Market Dynamics
Continuous manufacturing mandates from FDA and EMA are compressing batch release cycles from weeks to hours, forcing pharmaceutical manufacturers to requalify entire analytical workflows around real-time data streams rather than offline laboratory verification.
Growth Catalysts
- EMA process validation standards:European pharmaceutical facilities must demonstrate continuous process verification, driving inline spectrometer deployments for active pharmaceutical ingredient monitoring.
- Bioreactor sensor density:Single-use bioprocessing vessels now integrate twelve to sixteen analytical probes per unit, multiplying instrument counts per manufacturing line.
- German chemical cluster concentration:BASF, Bayer, and Boehringer Ingelheim facilities in Ludwigshafen and Ingelheim sustain chromatography system refresh cycles.
Market Restraints
- High-purity optical fiber costs:Silica-based fiber bundles for Raman probes experience price volatility tied to semiconductor-grade silicon tetrachloride supply.
- Detector chip foundry concentration:InGaAs photodiode production concentrates in Taiwanese semiconductor fabs, creating single-source vulnerability for NIR spectrometer manufacturers.
- USP Chapter 1058 friction:Analytical instrument qualification requirements extend deployment timelines by four to six months for FDA-regulated facilities.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad lack PAT infrastructure, creating greenfield instrument demand.
- Cell and gene therapy:Viral vector production requires multi-attribute mass spectrometry monitoring for critical quality attributes not captured by traditional assays.
- AI-enabled spectral interpretation:Machine learning models trained on pharmaceutical Raman libraries reduce method development time from months to days.
Industry Challenges
- Spectroscopy method development expertise:Pharmaceutical firms report twelve-to-eighteen-month vacancies for chemometricians capable of building multivariate calibration models.
- Legacy DCS integration:Twenty-year-old distributed control systems in chemical plants lack digital communication protocols for modern smart sensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Process Analytical Instrumentation Market |
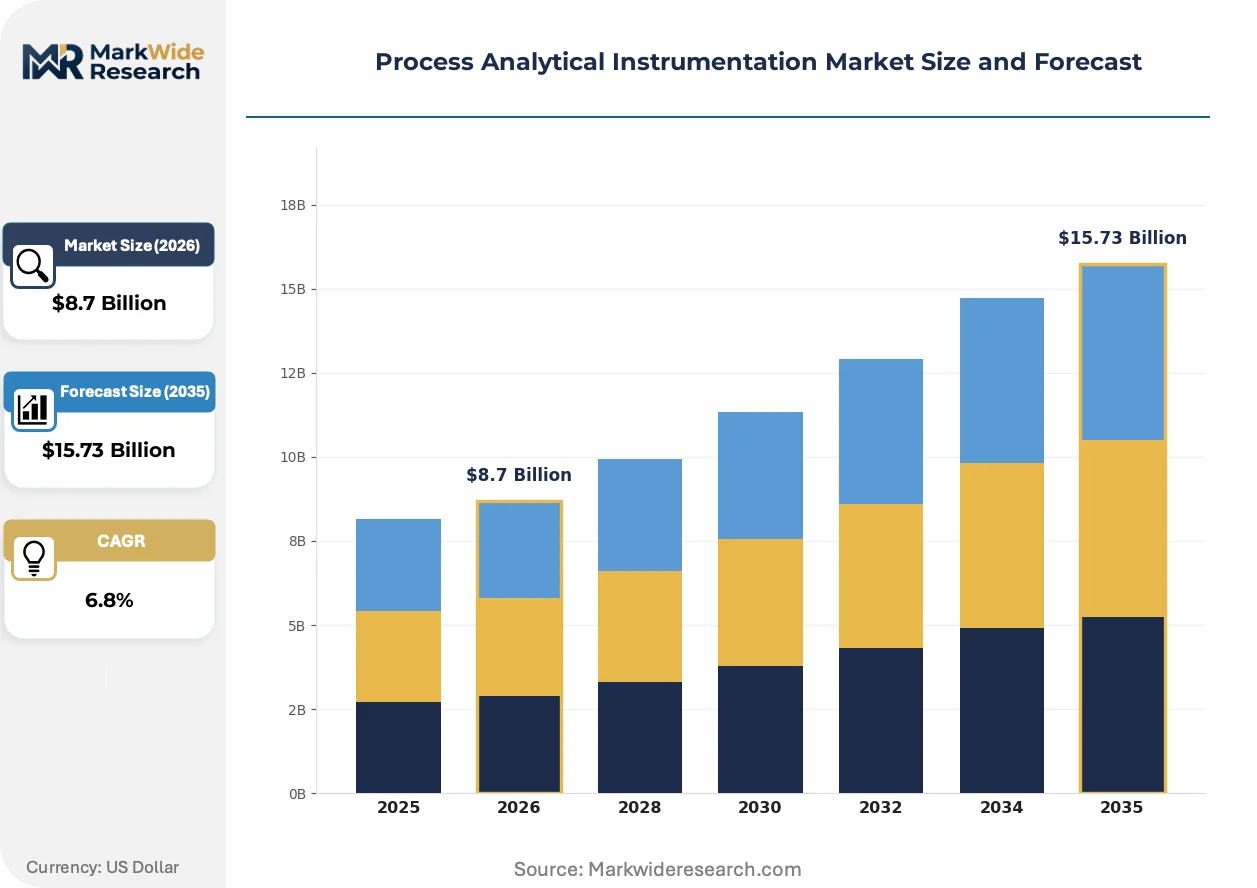
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectrometers, Chromatography Systems, Mass Spectrometers, Analyzers Technology: Optical, Electrochemical, Thermal, Magnetic End User: Pharmaceuticals, Chemicals, Food & Beverage, Biotech Application: Quality Control, Process Optimization, Research & Development, Compliance |
| Companies Covered | ABB Ltd, Siemens AG, Emerson Electric Co., Endress+Hauser Group Services AG, Thermo Fisher Scientific Inc., Agilent Technologies, Inc., Danaher Corporation, Mettler Toledo, PerkinElmer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Process Analytical Instrumentation Market Evolving Landscape
Modular analytical platforms are displacing monolithic systems as manufacturers prioritize swap-out maintainability over integrated permanence. This architectural shift reduces qualification burden and accelerates technology refresh cycles.
Raman spectroscopy is fragmenting the near-infrared dominance in solid-dose pharmaceutical manufacturing. Tablet press manufacturers now embed compact Raman probes directly into compression tooling for real-time uniformity monitoring. Pfizer and Novartis facilities in Ireland and Switzerland have completed validation of these integrated systems, establishing precedent for wider adoption.
EU AI Act risk classification frameworks are reshaping software validation requirements for instruments employing machine learning-based spectral interpretation. Analytical software classified as high-risk AI must demonstrate explainability and human oversight capabilities. Chromatography data systems from vendors serving European pharmaceutical markets are now embedding algorithmic transparency features.
Service unbundling is disrupting traditional instrument procurement in North American biopharma. Buyers now separate hardware acquisition from validation, training, and maintenance contracts, awarding these elements to specialized third-party service providers. This purchasing pattern is most pronounced in Boston and San Francisco metro clusters where dedicated PAT engineering consultancies have established presence.
Process Analytical Instrumentation Market Segmentation
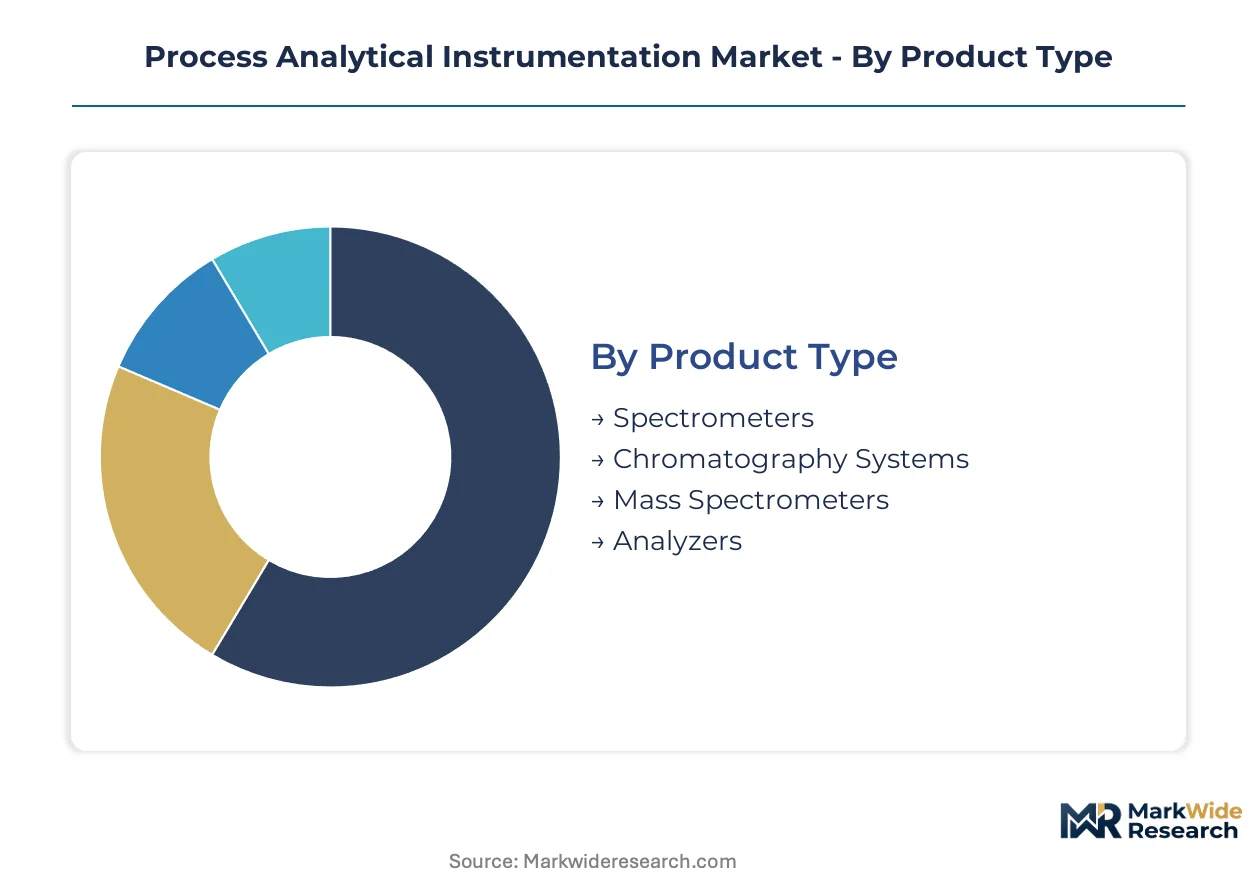
Process analytical instrumentation vendors configure product portfolios around measurement modality, integration complexity, and regulatory burden. Segment boundaries blur as hybrid platforms combine spectroscopic and chromatographic capabilities within single housings.
Product Type:
Margin pools concentrate in replacement cycles and qualification services rather than initial hardware sales, with recurring revenue streams from software validation and consumables dominating vendor profitability.
- Spectrometers:Near-infrared and Raman platforms constitute the revenue base for pharmaceutical solid-dose manufacturing, with probe configurations optimized for tablet press integration. German chemical clusters in Ludwigshafen sustain demand for process-grade Fourier-transform infrared systems in polymerization monitoring.
- Chromatography Systems:Inline high-performance liquid chromatography units enable real-time release testing for active pharmaceutical ingredients, compressing batch verification from weeks to hours. FDA Quality by Design mandates drive qualification investments that extend deployment timelines by four to six months.
- Mass Spectrometers:Multi-attribute monitoring platforms for complex biologics command premium positioning through software-intensive data interpretation capabilities.
- Analyzers:Dedicated gas and liquid analyzers serve utility and environmental compliance applications with standardized calibration protocols.
Spectrometers hold installed capacity. Mass spectrometers are rotating up the share rankings.
Technology:
Technology selection pivots on destructiveness constraints and sample matrix complexity, with optical methods dominating aqueous and solid streams while electrochemical platforms retain positions where ionic specificity matters.
- Optical:Non-destructive measurement capabilities span ultraviolet through near-infrared wavelengths, with Raman scattering gaining traction for crystallinity monitoring in pharmaceutical wet granulation. Silica fiber bundle costs for probe transmission create margin pressure tied to semiconductor-grade silicon tetrachloride supply volatility.
- Electrochemical:pH and dissolved oxygen sensors maintain essential positions in bioreactor control loops, with twelve to sixteen probes now standard per single-use vessel. Hygienic connection designs from Swiss and German component suppliers determine integration feasibility.
- Thermal:Differential scanning calorimetry and thermogravimetric platforms serve polymorph screening in early-stage pharmaceutical development.
- Magnetic:Nuclear magnetic resonance process analyzers enable molecular structure confirmation without chromatographic separation for complex natural products.
Optical platforms anchor current deployment. Electrochemical sensor density is climbing the fastest.
End User:
End-user procurement authority concentrates in quality assurance departments for regulated industries and operations engineering for chemical processing, with divergent priorities around validation documentation versus uptime reliability.
- Pharmaceuticals:Continuous manufacturing mandates from FDA and EMA compress analytical decision cycles, requiring embedded sensors capable of real-time critical quality attribute verification. Contract development and manufacturing organizations in India lack PAT infrastructure, creating greenfield demand.
- Chemicals:BASF and Bayer facilities drive chromatography refresh cycles tied to process analytical technology upgrades in bulk active ingredient production. Legacy distributed control systems in German plants constrain smart sensor integration.
- Food & Beverage:Inline near-infrared platforms monitor moisture and fat content in continuous processing lines with less stringent qualification requirements than pharmaceutical applications.
- Biotech:Viral vector production for cell and gene therapy demands multi-attribute mass spectrometry monitoring beyond traditional assay capabilities.
Pharmaceuticals command qualification premiums. Biotech is expanding most quickly.
Application:
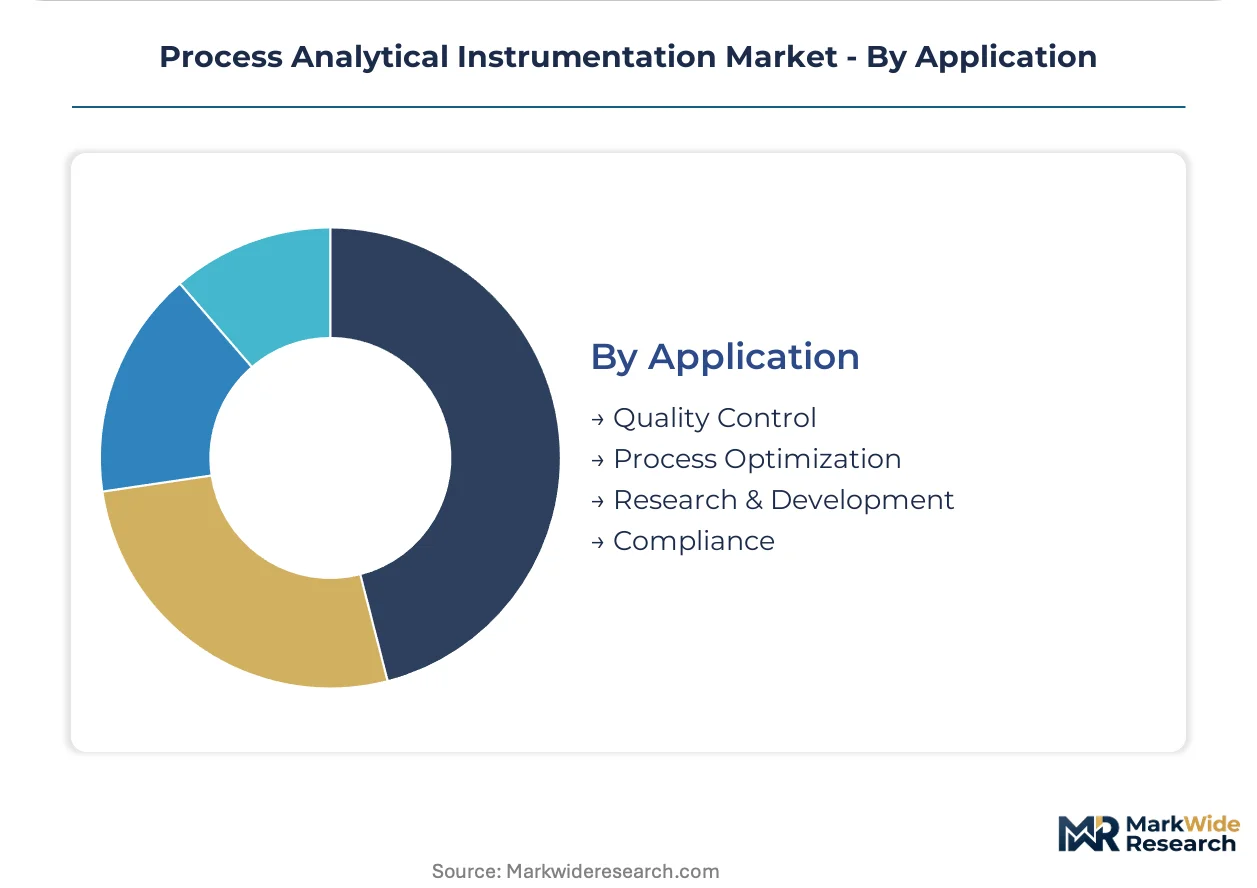
Application scope determines software architecture complexity, with compliance-driven deployments requiring audit trails and electronic signature capabilities that quality control applications may lack.
- Quality Control:Real-time release testing eliminates offline laboratory bottlenecks, with spectroscopic methods displacing traditional wet chemistry for identity and assay verification. EU AI Act risk classifications now reshape validation requirements for machine learning-enabled spectral interpretation.
- Process Optimization:Multivariate statistical process control leverages analytical data streams for predictive adjustment of reaction parameters, reducing yield variation in continuous pharmaceutical manufacturing.
- Research & Development:Method development for spectroscopic platforms requires scarce chemometric expertise, with twelve-to-eighteen-month vacancies reported for multivariate calibration specialists.
- Compliance:ISO 17025 accreditation and USP Chapter 1058 instrument qualification create documentation burdens that extend procurement cycles and sustain service revenue pools.
Quality control holds installed capacity. Process optimization is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in process analytical instrumentation tilt toward net-importing pharmaceutical economies while manufacturing-intensive chemical exporters sustain domestic procurement. Currency volatility and semiconductor supply constraints are reshaping regional purchasing patterns.
United States
FDA Quality by Design mandates and continuous manufacturing pilots at Merck and Pfizer sites drive spectrometer deployments. The agency's 2023 process analytical technology guidance tightens software validation requirements for real-time release testing. Boston and San Francisco metro clusters host dedicated PAT engineering consultancies that unbundle service contracts from hardware procurement.
Germany
BASF, Bayer, and Boehringer Ingelheim facilities in Ludwigshafen and Ingelheim sustain chromatography system refresh cycles tied to process analytical technology upgrades. EMA process validation standards mandate continuous process verification, accelerating inline spectrometer adoption for active pharmaceutical ingredient monitoring. Baden-Württemberg polymerization plants anchor demand for process-grade Fourier-transform infrared systems.
India
Contract development and manufacturing organizations in Hyderabad and Ahmedabad lack PAT infrastructure, creating greenfield instrument demand. CDSCO alignment with ICH Q8-Q12 guidelines elevates analytical control strategy requirements for export-oriented facilities. Maharashtra and Gujarat pharmaceutical corridors attract vendor direct sales teams bypassing traditional distribution channels.
Switzerland
Novartis and Roche continuous manufacturing investments compress batch verification timelines from weeks to hours. Swissmedic guidance on analytical instrument qualification extends deployment timelines but sustains premium pricing for validated systems. Basel and Zurich biologics facilities drive multi-attribute mass spectrometry demand for complex therapeutic monitoring.
China
NMPA pharmacopoeia revisions incorporate process analytical technology principles for domestic biologics manufacturing. Yangtze River Delta pharmaceutical clusters in Jiangsu and Zhejiang provinces expand single-use bioreactor deployments with embedded sensor arrays. Local instrument vendors capture mid-tier chromatography segments while foreign suppliers dominate mass spectrometry.
Process Analytical Instrumentation Market Competitive Landscape
Listed leaders compete with private specialists across automation integration depth and service bundling flexibility. The vendor base stratifies into three tiers: diversified industrial conglomerates with distributed control system integration capabilities, focused analytical instrument specialists with deep application expertise, and emerging regional challengers competing on qualification speed. Strategic moves center on modular platform architectures that reduce customer qualification burden and unbundled service models that separate hardware acquisition from validation support.
Within the automation-integrated tier, ABB Ltd and Siemens AG exemplify conglomerate positioning through embedded analytical modules within process control architectures. Emerson Electric Co. occupies a position between industrial automation and dedicated analytical instrumentation, leveraging DeltaV integration capabilities. Endress+Hauser Group Services AG anchors the hygienic process connection specialization segment for bioreactor monitoring applications.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Emerson Electric Co. |
| Endress+Hauser Group Services AG |
| Thermo Fisher Scientific Inc. |
| Agilent Technologies, Inc. |
| Danaher Corporation |
| Mettler Toledo |
| PerkinElmer, Inc. |
| Others |
Value Network & Pricing Analysis
FDA Quality by Design certification tiers simultaneously gate supplier qualification and stratify price positioning across pharmaceutical-grade versus industrial-grade instrument tiers. This regulatory filtering concentrates margin capture among vendors with validated software stacks while compressing pricing power for unqualified competitors serving non-regulated segments.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade and after-sales service bundling drive price differentiation, with FDA-validated systems commanding substantial premiums over ISO-tier alternatives. Pricing pressure stems from Taiwanese foundry concentration for detector chips, which squeezes margins for mid-tier spectrometer vendors. Contract development and manufacturing organizations in India exhibit highest price sensitivity due to greenfield budget constraints, while Swiss biologics facilities show lowest sensitivity given qualification-driven procurement.
Supply Chain Analysis
Taiwan Strait transit vulnerabilities expose InGaAs photodiode supply chains to geopolitical disruption risks. Manufacturing concentrates in Germany, Switzerland, and the United States for precision optical assemblies, while China dominates mid-tier chromatography component fabrication. Raw material dependencies include semiconductor-grade silicon tetrachloride for Raman probe fibers, rare-earth dopants for laser sources, and specialty ceramics for high-pressure flow cells. Single-source vulnerability runs through Taiwanese semiconductor fabs. Distribution runs through authorized channel partners with qualification expertise, bypassing commodity electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Process analytical instrumentation sits in early-cycle expansion as continuous manufacturing mandates from FDA and EMA compress batch verification timelines from weeks to hours, forcing greenfield sensor deployments across pharmaceutical facilities.
For Market Incumbents: Shield installed base revenue through backward integration into consumables and qualification services, countering modular platform disruptors. Prioritize certification investment for EU AI Act compliance on machine learning-enabled spectral interpretation software. Capacity addition in Indian CDMO corridors defends share against emerging regional challengers. For New Entrants and Emerging Players: Anchor in viral vector production monitoring for cell and gene therapy, where multi-attribute mass spectrometry demand outpaces established vendor capacity. Hyderabad and Ahmedabad CDMO clusters offer the most penetrable geography given PAT infrastructure gaps. A go-to-market angle through unbundled validation services bypasses incumbent hardware bundling. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core analytical divisions amid portfolio streamlining pressures. Long-term viability hinges on software-intensive data interpretation capabilities rather than hardware commoditization. Watch FDA guidance evolution on artificial-intelligence-enabled analytical models as inflection indicator for qualification burden shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Architecture | Reduces customer qualification burden and accelerates technology refresh cycles for pharmaceutical manufacturers. |
| AI-Enabled Spectral Interpretation | Machine learning models trained on pharmaceutical Raman libraries compress method development timelines dramatically. |
| Service Unbundling | Separates hardware acquisition from validation contracts, enabling specialized third-party engineering consultancies. |
| Geographic Expansion into India | CDMO corridors in Hyderabad and Ahmedabad present greenfield demand for PAT infrastructure deployment. |
| Regulatory Pre-Certification Investment | EU AI Act compliance for high-risk analytical software secures premium positioning in European pharmaceutical markets. |
Research Methodology
Operator-level perspectives from plant engineers, quality assurance directors, regulatory affairs specialists, and procurement leads anchored the qualitative base. Primary interviews combined with secondary validation from FDA guidance documents, EMA process validation frameworks, ISO 17025 accreditation records, and USP general chapters. Bottom-up instrument deployment counts triangulated against top-down market sizing from vendor revenue disclosures and trade flow analysis.
Sensitivity analysis tested forecast robustness across alternative regulatory adoption timelines and semiconductor supply scenarios. The analytical framework modeled segmentation across product type, technology modality, end-user industry, and application scope throughout the forecast period. CAGRs derived from instrument replacement cycle analysis, compliance-driven upgrade intensity, and penetration rate assumptions for continuous manufacturing adoption. Industry-specific inputs included bioreactor sensor density trajectories and AI-enabled spectral interpretation adoption curves.
Material uncertainties — regulatory guidance revisions, semiconductor foundry disruption, and chemometrician labor scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions on EMA process validation enforcement intensity and FDA real-time release testing adoption rates. Practitioners should keep alternative scenarios live as EU AI Act implementation timelines and Taiwanese supply chain resilience evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Benchtop Ph Meters Market
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
Global Laboratory Electronic Balance Market
Analytical Instruments
XRF Analyzer Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
AFM Probe Market
Analytical Instruments
Laser Probe Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market