
 Abbe Refractometers Market | 2026-2036
Abbe Refractometers Market Size, Share, and Industry Trends Forecast 2026-2036
Abbe Refractometers Market Analysis
Pharmaceutical quality control is hardening as the dominant end-use vertical for Abbe refractometers, displacing traditional educational procurement. Anton Paar GmbH leverages its Austrian precision engineering heritage to dominate high-end laboratory installations across European pharma hubs. METTLER TOLEDO sustains broad channel control through integrated balances-and-analytics portfolios that bundle refractometry into larger lab workflows. Atago Co., Ltd. specializes in compact handheld designs that occupy price-sensitive segments in Asian food safety applications.
An Abbe refractometer measures refractive index using a prism and telescope arrangement at controlled temperature, typically achieving precision to four decimal places for liquid sample characterization. The instrument determines concentration, purity, and optical properties in chemical and biological samples through critical angle detection. Digital benchtop units command the largest margin pools as laboratories replace aging optical models with thermostatted, software-connected systems. Handheld refractometers represent the fastest-growing product category, driven by field-deployable food safety and petrochemical testing protocols. Automated sampling technology is displacing manual operation in production monitoring environments where throughput and operator consistency determine compliance outcomes.
FDA instrument validation requirements under 21 CFR Part 11 shape software and data integrity specifications for refractometers sold into US pharmaceutical laboratories. EMA GMP Annex 15 guidelines and ISO 17025 calibration standards enforce traceable measurement uncertainty documentation across European installations. REACH chemical safety obligations and RoHS material restrictions constrain prism coatings and housing alloys in EU-bound equipment. Stakeholders must monitor evolving dual-use export controls on precision optical components and decide whether captive calibration service networks or third-party partnerships better secure long-term installed-base revenue.
Market Dynamics
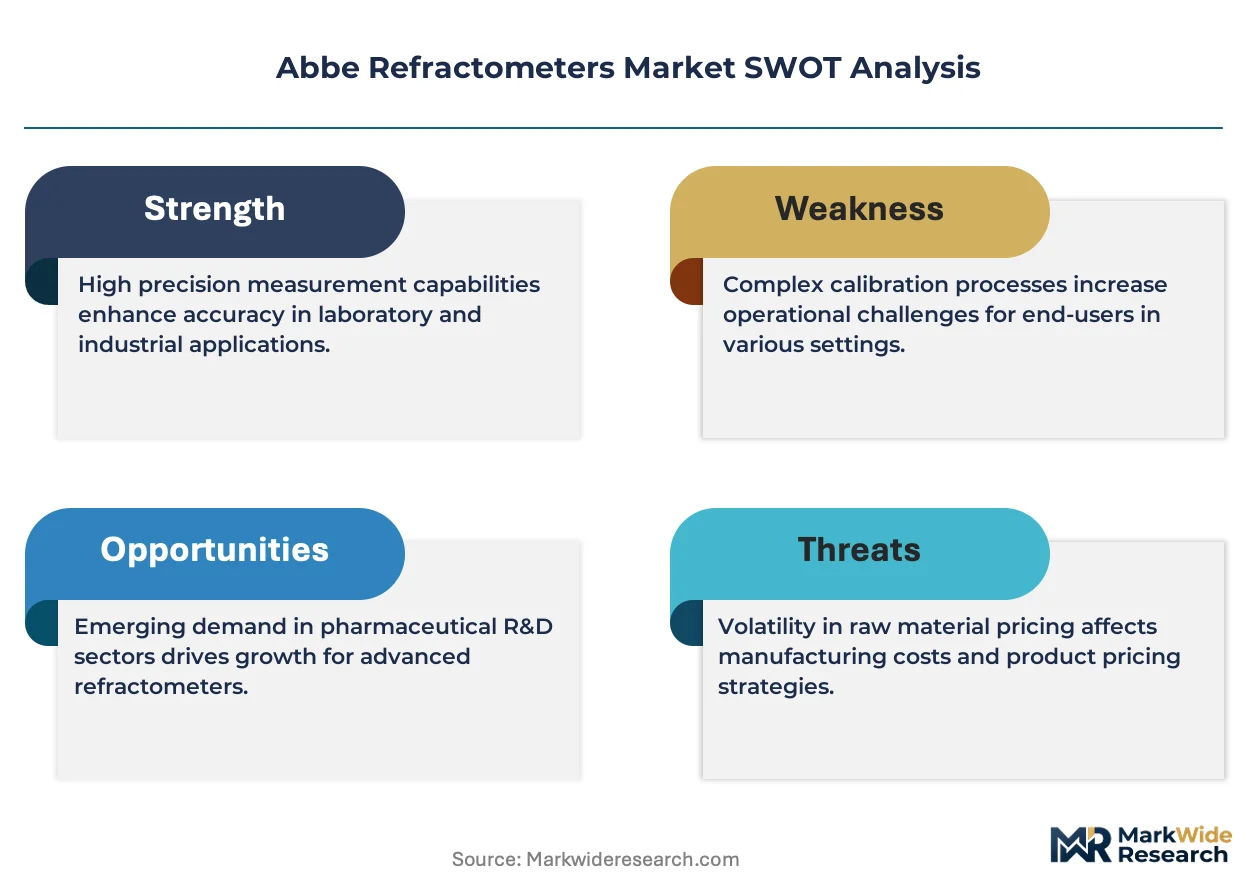
Pharmaceutical laboratories are replacing legacy optical refractometers with thermostatted digital systems to satisfy FDA 21 CFR Part 11 data integrity mandates, compressing replacement cycles and elevating software-connected benchtop units above handheld alternatives in procurement priority.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records and signature requirements force pharmaceutical laboratories to upgrade aging optical units with software-validated digital refractometers, accelerating replacement demand in US drug manufacturing facilities.
- Food safety field testing:Portable handheld designs are penetrating Asian food processing plants for rapid concentration verification at receiving docks, displacing slower laboratory send-out protocols.
- German precision optics clusters:Concentrated prism manufacturing expertise around Jena and Wetzlar sustains component supply for high-precision laboratory instruments serving European metrology networks.
Market Restraints
- Sapphire and optical glass input volatility:Refractive prism materials face price instability from rare earth supply constraints, compressing margins on mid-tier benchtop units.
- Single-source coating suppliers:Anti-reflective prism coatings concentrate among German and Austrian specialty chemical firms, creating vulnerability for manufacturers outside these supply clusters.
- Digital density meters:Oscillating U-tube alternatives capture concentration analysis share in beverage and petrochemical applications where refractive index correlation proves less direct.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO compliance requirements for analytical instrument qualification are creating first-time demand for validated digital refractometers in emerging formulation facilities.
- Bioprocess integration:Inline refractometry converging with single-use bioreactor sensors enables real-time concentration monitoring without sample withdrawal, opening continuous manufacturing applications.
- ISO 17025 laboratory accreditation:Mandatory measurement uncertainty documentation drives service contract attachments and recurring calibration revenue streams.
Industry Challenges
- Metrology technician scarcity:Specialized skills for critical angle calibration and prism maintenance are concentrating among aging workforces in European precision instrument sectors.
- Legacy LIMS integration:Digital refractometer data formats often conflict with established laboratory information management systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abbe Refractometers Market |
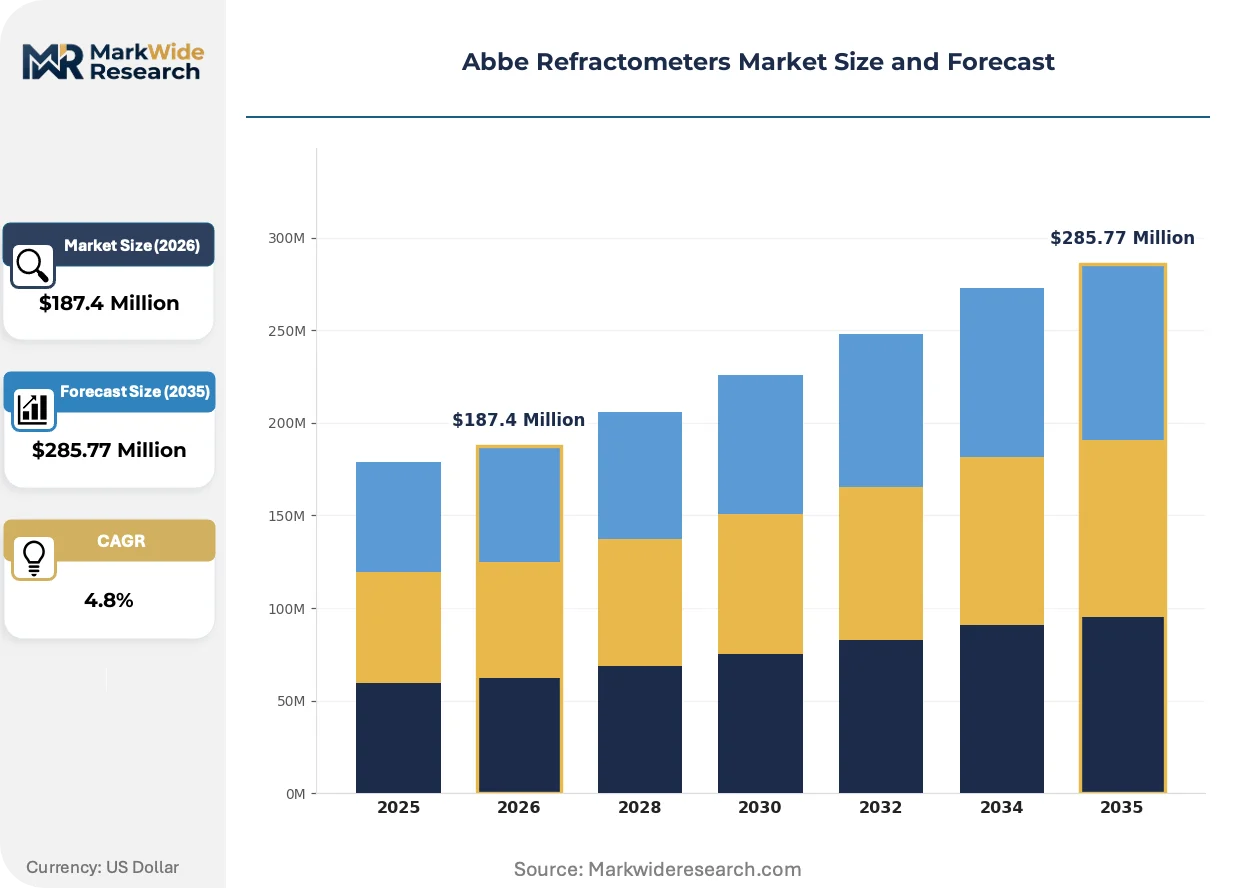
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Benchtop, Digital, Automatic End User: Laboratories, Food Industry, Petrochemical Sector, Pharmaceutical Companies Application: Quality Control, Research & Development, Educational Institutes, Production Monitoring Technology: Optical Measurement, Laser-based, Refractive Index Measurement, Automated Sampling |
| Companies Covered | Anton Paar GmbH, METTLER TOLEDO, Atago Co., Ltd., KRÜSS Optronic GmbH, Reichert Technologies, Bellingham + Stanley, Schmidt + Haensch GmbH & Co., Rudolph Research Analytical, Optika, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abbe Refractometers Market Emerging Trajectories
Refractometer architecture is fragmenting into modular subsystems that separate optical detection, temperature control, and data processing into interchangeable components, enabling laboratories to upgrade capabilities without full instrument replacement.
Thermoelectric Peltier temperature control is modularizing benchtop refractometer design, allowing pharmaceutical quality control departments to swap heating-cooling modules rather than replacing entire instruments when calibration drifts. This modularity compresses capital expenditure cycles while extending installed-base longevity. Service revenue models are pivoting toward component-level subscriptions.
EMA GMP Annex 15 guidelines on computerized systems validation are mandating audit trails and electronic signatures for analytical instruments used in drug release testing. European pharmaceutical manufacturers must document measurement uncertainty traceability chains. Software vendors are embedding automated compliance templates to reduce qualification burden.
Service unbundling is disrupting traditional instrument sales in North American pharmaceutical procurement. Buyers are separating hardware acquisition from validation, training, and calibration contracts, soliciting these elements through competitive RFPs rather than accepting bundled vendor packages. This fragmentation pressures integrated suppliers to defend attachment rates.
Abbe Refractometers Market Segmentation
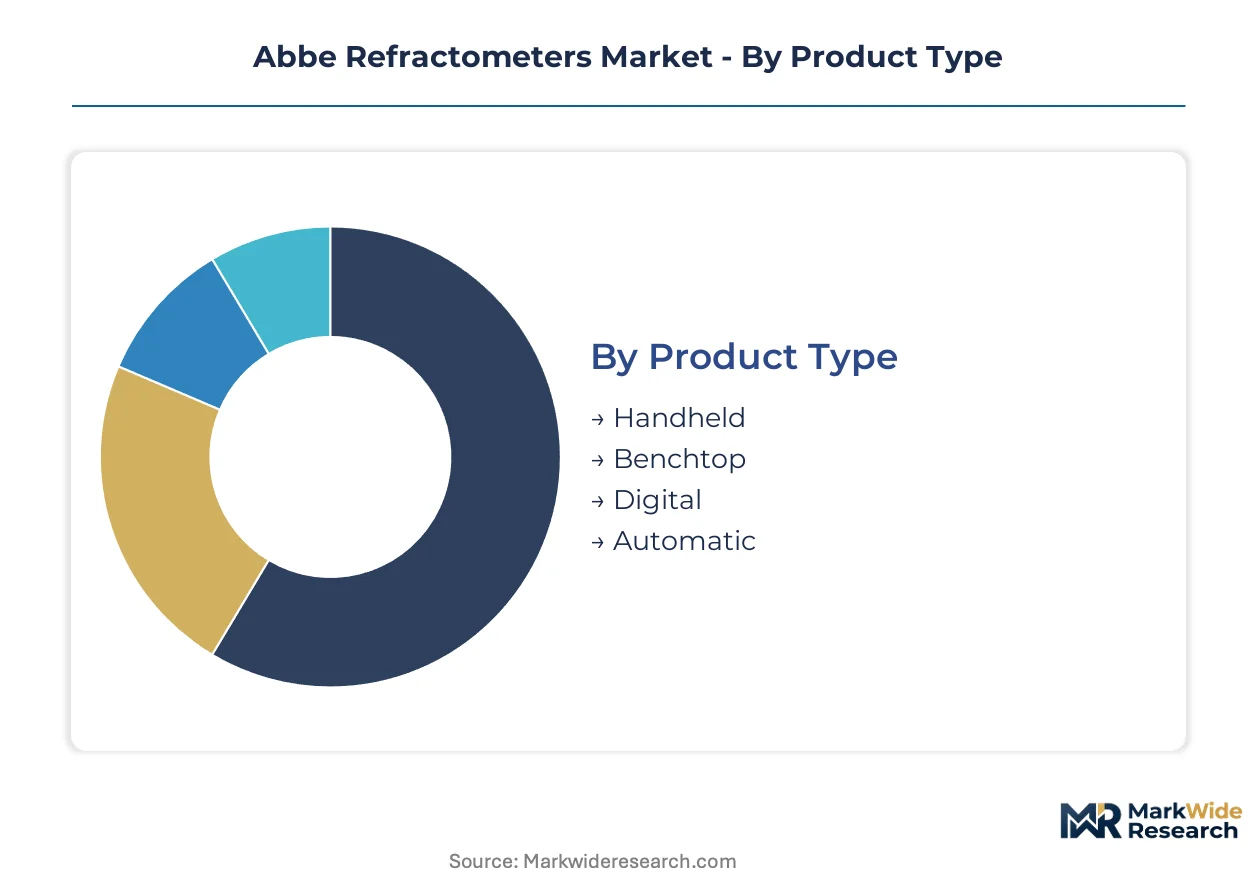
Refractometer purchasing decisions fragment across capital intensity tiers, field deployment requirements, and regulatory compliance burdens. Each segment exhibits distinct procurement cycles, margin structures, and vendor concentration patterns that shape competitive positioning.
Product Type:
Capital intensity varies sharply across this category, with thermostatted benchtop systems demanding the highest upfront instrument investment while handheld units minimize acquisition outlay.
- Handheld:Compact battery-powered units with direct-read displays suit field-deployable concentration checks. Food safety inspectors at Asian processing plants favor these for dockside receiving verification, though precision tops out at three decimal places.
- Benchtop:Laboratory-grade instruments with prism-thermostat integration achieve four-decimal precision for pharmaceutical quality control. German precision optics clusters supply the critical prism subassemblies, creating geographic supply concentration.
- Digital:Software-connected architectures with LCD readouts and data export capabilities dominate replacement demand as laboratories retire analog optical units. FDA 21 CFR Part 11 compliance requirements favor validated digital platforms.
- Automatic:Flow-cell equipped systems with programmable sampling reduce operator intervention in production monitoring environments. Inline configurations for bioprocess applications command premium pricing through reduced sample withdrawal protocols.
Benchtop configurations absorb the bulk of installed capacity; handheld designs are expanding most quickly.
End User:
Customer sophistication and validation burden determine pricing power across this dimension, with regulated pharmaceutical laboratories accepting steeper qualification costs than educational purchasers.
- Laboratories:ISO 17025-accredited testing facilities require traceable calibration chains and measurement uncertainty documentation. Service contract attachment rates run highest in this segment due to mandatory recertification cycles.
- Food Industry:Processors deploy handheld units for rapid °Brix measurement in juice concentration and honey purity verification. Asian markets drive volume through decentralized quality checks at receiving points.
- Petrochemical Sector:Hydrocarbon blend analysis and lubricant characterization demand explosion-proof housing variants. Refractive index correlation with density proves less direct here, exposing the segment to oscillating U-tube meter substitution.
- Pharmaceutical Companies:Drug release testing mandates EMA GMP Annex 15 computerized systems validation. Electronic audit trails and signature capabilities compress vendor shortlists to qualified suppliers with embedded compliance templates.
Pharmaceutical procurement commands the steepest pricing tier; food industry volume is climbing the fastest.
Application:
Throughput requirements and operator skill availability shape instrument specification choices, with automated production monitoring demanding the most integrated subsystem architectures.
- Quality Control:Release testing protocols in pharmaceutical manufacturing require validated methods with documented precision. Thermostatted benchtop units dominate this specification-intensive use case.
- Research & Development:Method development flexibility prioritizes broad refractive index range and multi-sample handling over throughput speed. Academic and corporate R&D labs sustain demand for modular upgrade paths.
- Educational Institutes:Training applications emphasize optical transparency and manual angle-reading to teach critical angle physics. Price sensitivity here favors simpler optical designs over digital connectivity.
- Production Monitoring:Continuous manufacturing integration favors inline refractometry with automated sampling and LIMS connectivity. Bioprocess applications converge refractometry with single-use sensor platforms.
Quality control applications anchor current installed value; production monitoring is gaining share fastest.
Technology:
Measurement modality determines precision ceiling, environmental tolerance, and maintenance burden, with laser-based architectures requiring the most specialized optical alignment expertise.
- Optical Measurement:Conventional prism-telescope arrangements with visual angle reading persist in educational and budget-constrained settings. These legacy configurations face replacement pressure from digital alternatives.
- Laser-based:Interferometric techniques achieve sub-four-decimal precision for metrology-grade reference measurements. German and Austrian specialty coating suppliers concentrate supply for the anti-reflective prism finishes these require.
- Refractive Index Measurement:Critical angle detection remains the dominant technical approach across portable and laboratory platforms. Temperature compensation algorithms differentiate vendor performance in this mature technique.
- Automated Sampling:Flow injection and microfluidic integration reduce operator handling in high-throughput environments. Modular subsystem architectures allow separate upgrade of sampling, detection, and thermal control components.
Refractive index measurement captures the largest installed base; automated sampling shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in German precision optics clusters while pharmaceutical consumption drives demand across North America, Europe, and Asia-Pacific. Refractometer supply chains favor component manufacturing near Jena and Wetzlar, with final assembly distributed to quality control laboratories in drug manufacturing hubs worldwide.
United States
FDA 21 CFR Part 11 compliance mandates reshape procurement toward validated digital systems in pharmaceutical quality control laboratories. The agency's data integrity enforcement accelerates replacement cycles for aging optical instruments. New Jersey and Massachusetts biopharma corridors anchor installed base expansion as CDMOs expand analytical capacity.
Germany
EMA GMP Annex 15 computerized systems validation requirements sustain premium pricing for thermostatted benchtop units in drug release testing. REACH chemical safety obligations constrain prism coating formulations and housing alloy selections. Jena and Wetzlar precision optics clusters supply critical prism subassemblies to European metrology networks.
India
CDSCO analytical instrument qualification requirements create first-time demand for validated digital refractometers in emerging formulation facilities. The country's national pharmaceutical regulator tightens compliance protocols for generic drug exports. Maharashtra and Gujarat pharmaceutical manufacturing zones drive procurement volume for quality control applications.
Japan
PMDA GMP inspections emphasize measurement uncertainty documentation for analytical instruments in drug substance manufacturing. METI industrial standards support domestic precision instrument competitiveness. Osaka and Tokyo pharmaceutical R&D centers sustain demand for research-grade modular systems with upgrade pathways.
China
NMPA pharmaceutical manufacturing quality standards elevate instrument validation requirements for domestic and export-oriented drug producers. GB standards for analytical instruments harmonize with international metrology practices. Yangtze River Delta biopharma clusters expand quality control infrastructure for monoclonal antibody production.
Abbe Refractometers Market Vendor Landscape
Top-tier vendors anchor the premium laboratory segment, while mid-tier specialists and regional fabricators occupy price-sensitive niches. Market structure tilts toward consolidation among precision engineering heritage firms with embedded compliance expertise. Three archetypes dominate: Austrian-German precision engineering houses, integrated analytical instrument conglomerates, and compact handheld specialists. Competitive moves center on modular subsystem architectures and unbundled service contracts that separate hardware from validation and calibration revenue.
Among German and Austrian precision engineering houses, Anton Paar GmbH and Schmidt + Haensch GmbH & Co. exemplify heritage-driven positioning in thermostatted laboratory systems. METTLER TOLEDO represents the integrated conglomerate archetype with bundled balances-and-analytics portfolios. Atago Co., Ltd. anchors the handheld specialist tier with compact field-deployable designs. Each occupies a distinct pricing tier without direct product overlap.
| Leading Market Players |
|---|
| Anton Paar GmbH |
| METTLER TOLEDO |
| Atago Co., Ltd. |
| KRÜSS Optronic GmbH |
| Reichert Technologies |
| Bellingham + Stanley |
| Schmidt + Haensch GmbH & Co. |
| Rudolph Research Analytical |
| Optika |
| Others |
Supply Flow & Price Mechanics
Sapphire and optical glass prism materials traverse from rare earth extraction through German precision optics clusters to three-tier pricing structures across premium, standard, and economy levels, with pharmaceutical quality control laboratories absorbing the steepest markups for validated digital systems.
Pricing Analysis
Margin tightening in mid-tier benchtop units reflects volatile rare earth supply constraints on refractive prism materials. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated digital platforms from optical legacy designs and handheld field units. Price differentiation hinges on certification grade and after-sales service bundling. Educational institutes exhibit highest price sensitivity; pharmaceutical laboratories accept premium positioning for compliance-embedded systems.
Supply Chain Analysis
Domestic-content mandates in Indian pharmaceutical manufacturing zones are reshaping sourcing patterns for validated analytical instruments. Prism subassembly production concentrates in Germany, Austria, and Japan. Supply chains draw from specialty coating chemicals, thermoelectric Peltier modules, and precision-machined housings. Single-source vulnerability concentrates among German and Austrian anti-reflective coating suppliers. Distribution runs through direct laboratory sales channels and analytical instrument distributors serving quality control facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over precision prism manufacturing and embedded calibration service networks determines long-term installed-base revenue capture.
For Market Incumbents: Cement dominance in pharmaceutical quality control by deepening backward integration into precision prism production and expanding captive calibration service networks. Oscillating U-tube density meters threaten refractometry share in beverage applications; defend position through bioprocess inline integration and single-use sensor convergence. For New Entrants and Emerging Players: Small-scale food processors in Southeast Asian markets represent the most penetrable buyer archetype currently underserved by premium European vendors. Compact handheld designs with localized °Brix calibration protocols and price positioning below Atago's established range open channel access. Pursue distributor partnerships with regional food safety inspection agencies rather than direct laboratory sales infrastructure. For Investors and Strategic Acquirers: CDSCO enforcement actions against non-compliant analytical instruments in Indian pharmaceutical exports are the leading indicator that validated digital refractometer demand will accelerate in emerging formulation facilities. Five-to-ten year viability favors precision engineering heritage firms with embedded regulatory compliance expertise. Monitor EMA GMP Annex 15 audit citation rates for computerized systems validation as the inflection signal for replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prism Manufacturing | Captive supply of sapphire and optical glass subassemblies secures margin control against rare earth volatility. |
| Bioprocess Inline Sensor Convergence | Integration with single-use bioreactor platforms opens continuous manufacturing applications beyond batch testing. |
| Calibration Service Network Expansion | ISO 17025-accredited service contracts generate recurring revenue from pharmaceutical installed base. |
| Modular Subsystem Architecture Development | Separable temperature control and detection components extend instrument longevity and compress capital cycles. |
| Regulatory Compliance Template Embedding | FDA 21 CFR Part 11 and EMA GMP Annex 15 pre-validation software reduces customer qualification burden. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with quality control laboratory managers, analytical instrument procurement officers, precision optics manufacturing engineers, and metrology service technicians combined with bottom-up and top-down triangulation. FDA 21 CFR Part 11 guidance documents, EMA GMP Annex 15 inspection reports, and ISO 17025 accreditation databases provided secondary validation. Customs records on prism material imports and analytical instrument trade flows supplemented demand estimation.
Product type, end user, application, and technology dimensions were modeled at granular levels across the projection horizon. Pharmaceutical quality control, food industry, and petrochemical sector end-use segments were cross-referenced with handheld, benchtop, digital, and automatic product configurations. CAGRs were derived from replacement cycle analysis, regulatory compliance-driven upgrade patterns, and emerging market penetration curves. Bioprocess integration trends and modular upgrade pathway adoption informed technology segment trajectories.
Revisions become necessary when rare earth supply disruptions, regulatory enforcement intensity shifts, or substitute technology breakthroughs in density measurement materialize. Forecasts reflect assumptions on compliance timeline adherence and calibration service contract attachment rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Gel Documentation Systems Market
Analytical Instruments
Real-Time Spectrum Analysis Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Atomic Spectroscopy Market
Analytical Instruments
Microfluidic Modulation Spectroscopy Market
Analytical Instruments
Automatic Polarimeter Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Infrared Spectroscopy Devices Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Array Instruments Market
Analytical Instruments
Battery Analyzer Market
Analytical Instruments
Global Electron Microscopes Market
Analytical Instruments
Signaling Analyzer Market
Analytical Instruments
Portable Chromatography Systems Market