
 Telecom Testing Equipment Market | 2026-2036
Telecom Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Testing Equipment Market Outlook
China is fragmenting the traditional telecom testing equipment supply base as domestic manufacturers expand production capacity for 5G base station analyzers and fiber optic test sets. Keysight Technologies leverages its calibration laboratories across Shenzhen and Beijing to sustain premium positioning in vector network analysis. Anritsu Corporation anchors its Asia-Pacific presence through localized production of spectrum analyzers for carrier acceptance testing. Rohde & Schwarz competes by extending its signal generator portfolio into millimeter-wave bands for 6G research programs.
Telecom testing equipment comprises electronic instruments engineered to measure signal integrity, power levels, frequency response, and bit-error rates across copper, fiber, and wireless media, with typical specifications spanning DC to 110 GHz and dynamic ranges exceeding 140 dB. These instruments verify conformance to 3GPP, IEEE, and ITU-T standards before commercial network activation. Optical test equipment commands the densest margin pools as submarine cable deployments and data center interconnects drive demand for coherent optical spectrum analyzers. 5G technology segments are expanding fastest due to massive MIMO beam validation requirements, while Ethernet testing maintains steady replacement cycles amid 800G port rollouts. Fiber optic instrumentation leads in absolute dollar contribution as fiber-to-the-home buildouts persist across developed and emerging markets.
The Federal Communications Commission mandates equipment authorization under Part 15 and Part 27 rules, compelling manufacturers to integrate pre-compliance testing modules that reduce certification cycle times. ETSI in Europe enforces EN 301 908 standards for 5G NR base stations, shaping product development roadmaps for signal quality analyzers sold into EU member states. China's Ministry of Industry and Information Technology imposes GB/T national standards that require domestic certification testing before network equipment deployment. Stakeholders must monitor spectrum reallocation proceedings and Open RAN security mandates as these regulatory vectors will determine which instrument capabilities become table stakes versus differentiators.
Market Dynamics
5G network densification is compressing test cycle timelines as carriers race to activate mid-band spectrum before competitive deadlines, forcing instrument vendors to embed automation layers that slash field calibration overhead.
Growth Catalysts
- Massive MIMO deployment mandates:FCC Part 27 rules require beam validation before commercial 5G activation, pulling demand for multi-port vector network analyzers into carrier capital budgets.
- Fiber-to-the-home acceleration:Municipal broadband programs across Germany, Japan, and the United States are sustaining order flow for optical time-domain reflectometers and coherent spectrum analyzers.
- Open RAN interoperability testing:O-RAN Alliance specifications are forcing multi-vendor validation protocols that expand addressable instrument scope beyond single-supplier environments.
Market Restraints
- Gallium nitride substrate scarcity:Millimeter-wave test set production faces input constraints as defense and telecom sectors compete for limited foundry capacity.
- Calibration laboratory concentration:Premium traceability services cluster in Shenzhen, Munich, and Santa Rosa, creating geographic chokepoints for certification-dependent buyers.
- Legacy Ethernet depreciation cycles:400G port testing equipment retains residual value, delaying replacement demand for 800G-capable platforms in enterprise data centers.
Strategic Opportunities
- India 5G standalone rollout:TRAI spectrum auction rules are opening test equipment procurement windows as Reliance Jio and Bharti Airtel expand mid-band infrastructure.
- Terahertz research instrumentation:6G pre-standardization programs at DARPA and METI are seeding demand for 140 GHz-plus signal generators before commercial volumes materialize.
- Cloud-native test orchestration:Kubernetes-based test automation platforms are displacing bench-centric workflows, enabling subscription revenue models that decouple instrument sales from capital cycles.
Industry Challenges
- RF engineer talent scarcity:Millimeter-wave calibration expertise concentrates among retiring specialists, forcing vendors to embed AI-assisted self-test routines that reduce human dependency.
- Multi-standard certification stacking:Equipment must simultaneously satisfy 3GPP Release 17, IEEE 802.11be, and O-RAN WG4 specifications, extending validation timelines and engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Testing Equipment Market |
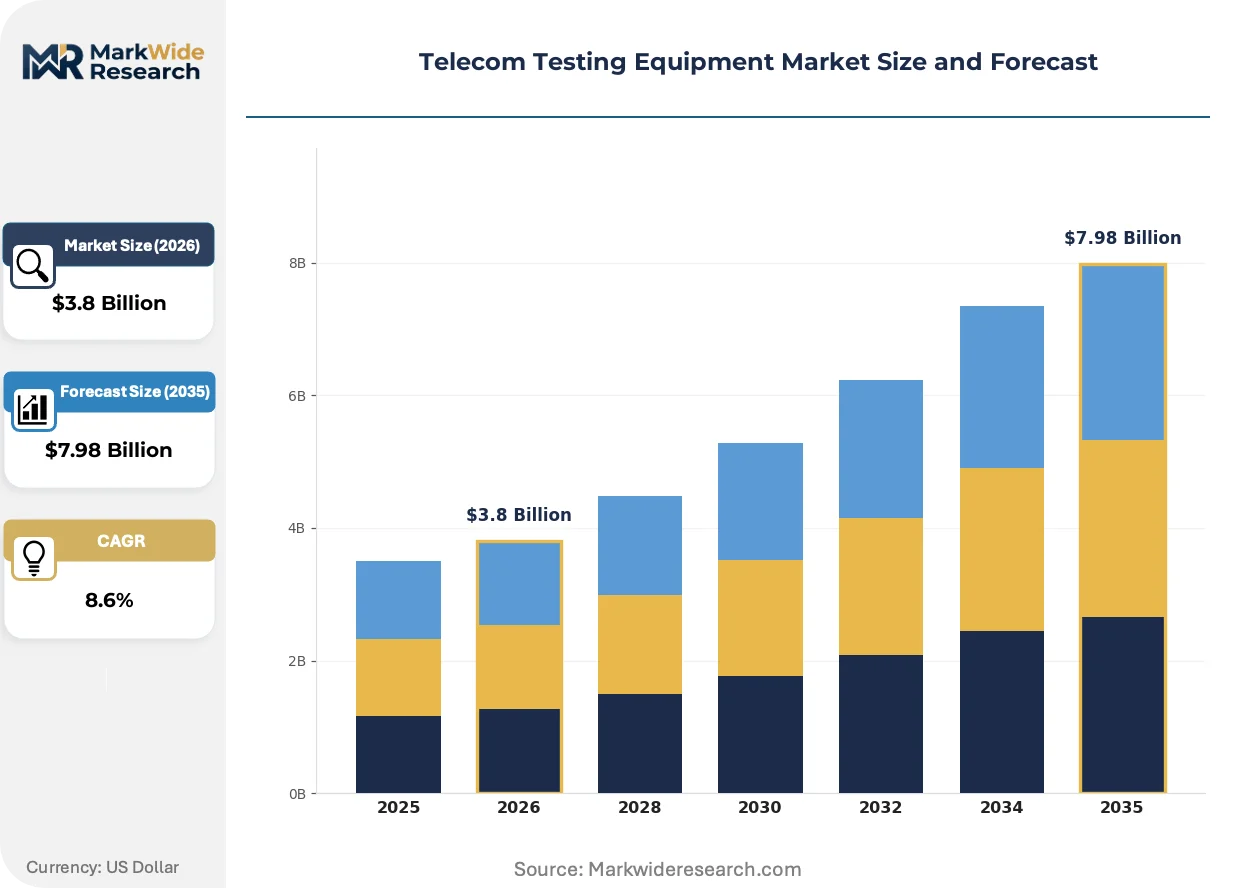
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Analyzers, Signal Generators, Cable Testers, Optical Test Equipment Technology: 5G, LTE, Ethernet, Fiber Optic Application: Installation, Maintenance, Research, Development End User: Telecom Operators, Service Providers, OEMs, Enterprises |
| Companies Covered | Keysight Technologies, Anritsu Corporation, EXFO Inc., Viavi Solutions, Yokogawa Electric Corporation, Spirent Communications, Rohde & Schwarz, Tektronix, Fortive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Testing Equipment Market Strategic Shifts
Test instrumentation is fragmenting into modular, software-defined architectures that displace monolithic hardware platforms, with virtualization layers now handling signal processing that previously demanded dedicated ASICs.
Real-time spectrum analysis is migrating from dedicated hardware engines to FPGA-based software-defined radio platforms. Base station manufacturers are adopting these flexible architectures to compress pre-deployment validation cycles. The shift is enabling instrument vendors to push firmware updates that extend frequency coverage without physical hardware swaps.
ETSI's EN 303 645 cybersecurity standard for consumer IoT devices is cascading into telecom infrastructure requirements, mandating embedded security testing modules in base station analyzers sold into EU member states. Network equipment manufacturers must now demonstrate vulnerability scanning capabilities before carrier acceptance, reshaping product roadmaps for European market entry.
Carrier procurement teams are unbundling after-sales calibration contracts from initial instrument purchases, treating traceability services as separately negotiable spend categories. This behavioral shift pressures vendor margin structures in the United States and Western Europe, where multi-year service attach rates previously subsidized hardware pricing.
Telecom Testing Equipment Market Segmentation
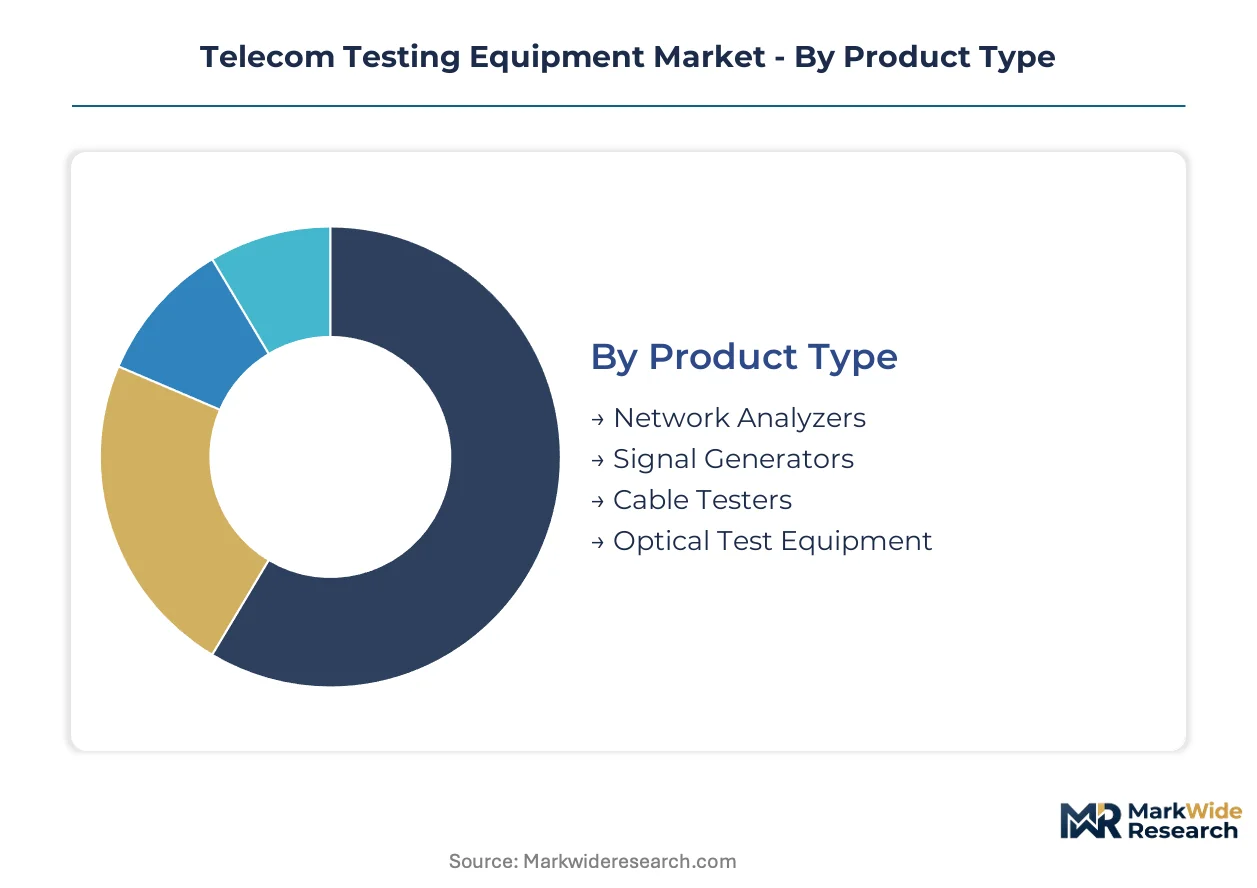
Segmentation in telecom testing equipment reveals divergent margin profiles and service attachment rates across product architectures. Vendors calibrate go-to-market strategies based on calibration intensity, replacement cycles, and customer technical sophistication rather than hardware specifications alone.
Product Type:
After-sales service intensity varies dramatically by instrument complexity, with vector network analyzers demanding annual recalibration contracts while cable testers operate for years without factory intervention.
- Network Analyzers:Multi-port vector network analyzers measure S-parameters across DC to 110 GHz for base station antenna validation. Demand concentrates with 5G massive MIMO deployments in the United States as FCC Part 27 beam-steering mandates intensify pre-commercial testing protocols.
- Signal Generators:These instruments produce precise carrier waveforms for receiver sensitivity testing and interference simulation. Research laboratories in Japan and Germany are pulling demand for millimeter-wave variants ahead of 6G standardization timelines.
- Cable Testers:Handheld units verify coaxial and twisted-pair integrity for field technicians. Enterprise IT departments in commercial real estate drive replacement demand as Category 8 cabling penetrates data center buildouts.
- Optical Test Equipment:Coherent optical spectrum analyzers and OTDRs dominate submarine cable acceptance testing. Fiber-to-the-home programs across Germany and Japan sustain order flow for portable fiber inspection scopes.
By volume, Cable Testers leads. By growth pace, Optical Test Equipment is ahead.
Technology:
Technology segments map directly to capital expenditure cycles among carrier customers, with spectrum auction timing and standards ratification creating step-function demand patterns.
- 5G:Millimeter-wave and mid-band test sets validate beamforming performance and carrier aggregation. Reliance Jio and Bharti Airtel in India are expanding procurement windows as TRAI auction rules enable standalone network rollouts.
- LTE:Legacy 4G test equipment maintains steady replacement demand in emerging markets where network modernization lags advanced economies. Rural coverage obligations in Brazil and Indonesia extend equipment service lifecycles.
- Ethernet:400G and 800G port testing platforms verify physical layer compliance for hyperscale data centers. Cloud providers in Northern Virginia and Frankfurt clusters are delaying 800G upgrades due to residual 400G equipment value.
- Fiber Optic:DWDM and coherent transmission test sets measure optical signal-to-noise ratios across submarine and terrestrial routes. Submarine cable landing stations in Singapore and Marseille anchor demand for chromatic dispersion analyzers.
By installed base, Fiber Optic dominates. By expansion velocity, 5G is climbing the fastest.
Application:
Application segments reflect divergent customer workflows, with field installation teams prioritizing portability while R&D laboratories demand measurement precision at cost tolerance.
- Installation:Ruggedized handheld units with automated pass/fail reporting accelerate technician productivity. Municipal broadband contractors across the United States are standardizing on cloud-connected test platforms that upload results directly to carrier databases.
- Maintenance:Preventive diagnostics and fault isolation instruments minimize network downtime. European incumbent operators are consolidating maintenance tool fleets to reduce training overhead across multinational technician workforces.
- Research:Ultra-high-frequency signal analysis for pre-standardization 6G programs. METI-funded consortia in Japan and DARPA initiatives in the United States are seeding demand for terahertz-capable instrumentation.
- Development:Base station OEMs employ protocol analyzers and conformance test systems during product design cycles. Open RAN disaggregation is fragmenting development test requirements across multiple subsystem vendors.
By revenue contribution, Maintenance leads. By investment intensity, Research is gaining share fastest.
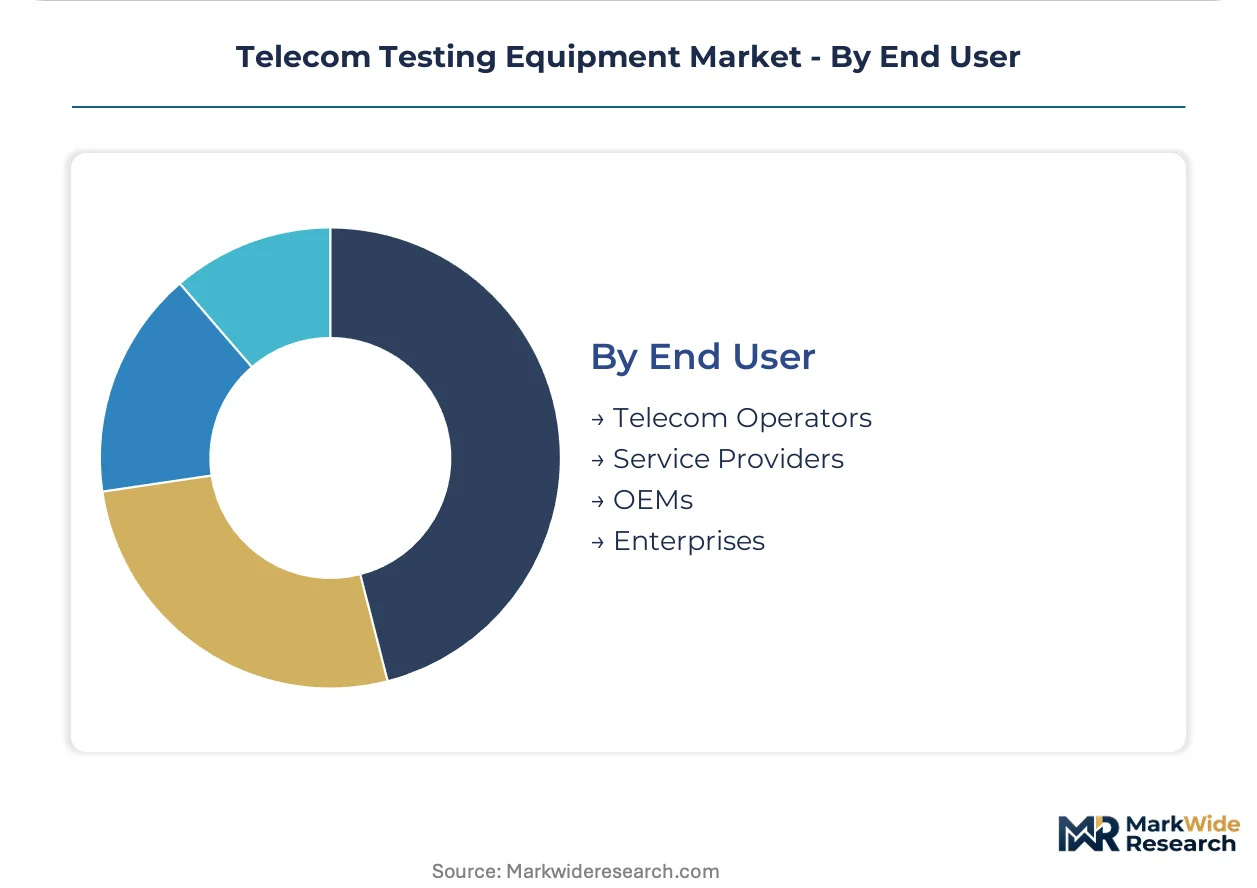
End User:
End user categories exhibit distinct procurement behaviors, with telecom operators bundling multi-year calibration contracts while enterprises negotiate spot purchases.
- Telecom Operators:Tier-1 carriers operate centralized test laboratories with accredited calibration traceability. Verizon and AT&T in the United States are mandating vendor-managed inventory programs for field test equipment.
- Service Providers:Installation and maintenance contractors operate on thin hardware margins with service revenue attachment. Tower companies in India are verticalizing test capabilities to reduce dependency on OEM field support.
- OEMs:Network equipment manufacturers maintain extensive pre-shipment validation facilities. Nokia and Ericsson are consolidating European test operations into shared service centers to optimize capital utilization.
- Enterprises:Corporate IT departments purchase cable certification and LAN test equipment for data center commissioning. Financial services firms in Singapore are upgrading test capabilities to support low-latency trading infrastructure.
By absolute spend, Telecom Operators leads. By procurement flexibility, Enterprises shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test equipment manufacturing concentrates in Germany, Japan, and the United States, where precision instrumentation clusters around automotive-electronics corridors and defense-telecom supply chains. Calibration laboratory networks in Munich, Tokyo, and Santa Rosa anchor traceability services for certification-dependent buyers.
United States
Verizon and AT&T are accelerating mid-band 5G deployments across the Midwest and Southeast, pulling demand for massive MIMO validation systems into carrier capital budgets. FCC Part 27 beam-steering mandates require pre-commercial testing protocols that compress procurement timelines. The Northern Virginia data center cluster sustains replacement demand for 800G Ethernet test platforms amid hyperscale expansion.
Germany
Municipal broadband programs in Bavaria and North Rhine-Westphalia are sustaining order flow for optical time-domain reflectometers and coherent spectrum analyzers. ETSI EN 301 908 standards enforcement shapes product development roadmaps for signal quality analyzers sold into EU member states. The Munich metropolitan area hosts Rohde & Schwarz calibration facilities serving Central European carrier laboratories.
China
Domestic manufacturers are expanding production capacity for 5G base station analyzers and fiber optic test sets, fragmenting traditional supply bases. MIIT GB/T national standards require domestic certification testing before network equipment deployment. Shenzhen and Beijing calibration laboratories sustain premium positioning for imported vector network analysis instruments.
Japan
METI-funded consortia are seeding demand for terahertz-capable instrumentation ahead of 6G standardization timelines. NTT Docomo and KDDI are validating millimeter-wave beamforming performance across Tokyo and Osaka metropolitan corridors. Yokogawa Electric anchors domestic production of spectrum analyzers for carrier acceptance testing.
India
Reliance Jio and Bharti Airtel are expanding mid-band infrastructure procurement following TRAI spectrum auction rules. Tower companies are verticalizing test capabilities to reduce dependency on OEM field support. Mumbai and Delhi-NCR clusters concentrate service provider maintenance operations for 5G standalone rollouts.
Telecom Testing Equipment Market Competitive Environment
Full-stack instrumentation conglomerates and specialized test houses split the market along calibration intensity and frequency coverage vectors. Consolidation around precision measurement IP has produced a tiered structure where premium positioning depends on accredited laboratory networks rather than hardware specifications alone. Three archetypes dominate: vertically integrated precision houses, modular software-defined specialists, and field-portable ruggedization experts. Competitive moves center on strategic partnerships for millimeter-wave IP licensing and geographic expansion of calibration service footprints.
Within the precision-tier, Keysight Technologies, Anritsu Corporation, and Rohde & Schwarz occupy positions defined by their respective Santa Rosa, Kanagawa, and Munich origins. These entities exemplify the vertically integrated archetype through captive calibration infrastructure and sustained R&D intensity. Their geographic clustering reflects historical defense-electronics supply chain development rather than contemporary cost optimization.
| Leading Market Players |
|---|
| Keysight Technologies |
| Anritsu Corporation |
| EXFO Inc. |
| Viavi Solutions |
| Yokogawa Electric Corporation |
| Spirent Communications |
| Rohde & Schwarz |
| Tektronix |
| Fortive |
| Others |
Value Chain & Pricing Dynamics
The Yokohama-Singapore maritime corridor's freight cost volatility shapes margin structures across precision instrument supply chains, compressing landed costs for German and Japanese manufacturers while amplifying price differentiation between calibration-intensive premium tiers and commoditized field-portable units. This logistics dynamic concentrates procurement leverage with carriers operating centralized test laboratories in the United States and Western Europe.
Pricing Analysis
FCC Part 27 equipment authorization rules dictate the pricing tier structure across the Telecom Testing Equipment Market, separating NIST-traceable premium instruments from standard-grade field units lacking accredited calibration chains. Price differentiation hinges on certification grade and after-sales service bundling, with annual recalibration contracts commanding substantial premiums over spot-purchase hardware. Cost compression in the standard tier intensifies as Chinese domestic manufacturers expand 5G base station analyzer production. Enterprise IT departments exhibit highest price sensitivity due to residual 400G Ethernet equipment value, while tier-1 telecom operators prioritize traceability over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for millimeter-wave test set manufacturers, forcing inventory pre-positioning strategies around Shenzhen and Santa Rosa calibration hubs. Production concentrates in Germany, Japan, and the United States, drawing from gallium nitride substrate foundries, precision RF connector suppliers, and FPGA semiconductor vendors. Single-source vulnerability in GaN substrate allocation creates chokepoints as defense and telecom sectors compete for limited wafer capacity. Distribution runs through authorized distributor networks serving carrier procurement teams and direct OEM relationships for base station manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native test orchestration platforms are expanding recurring revenue streams faster than hardware sales, repositioning the Telecom Testing Equipment Market as a service-attach opportunity where subscription-based calibration and firmware-update monetization decouples vendor fortunes from capital expenditure cycles.
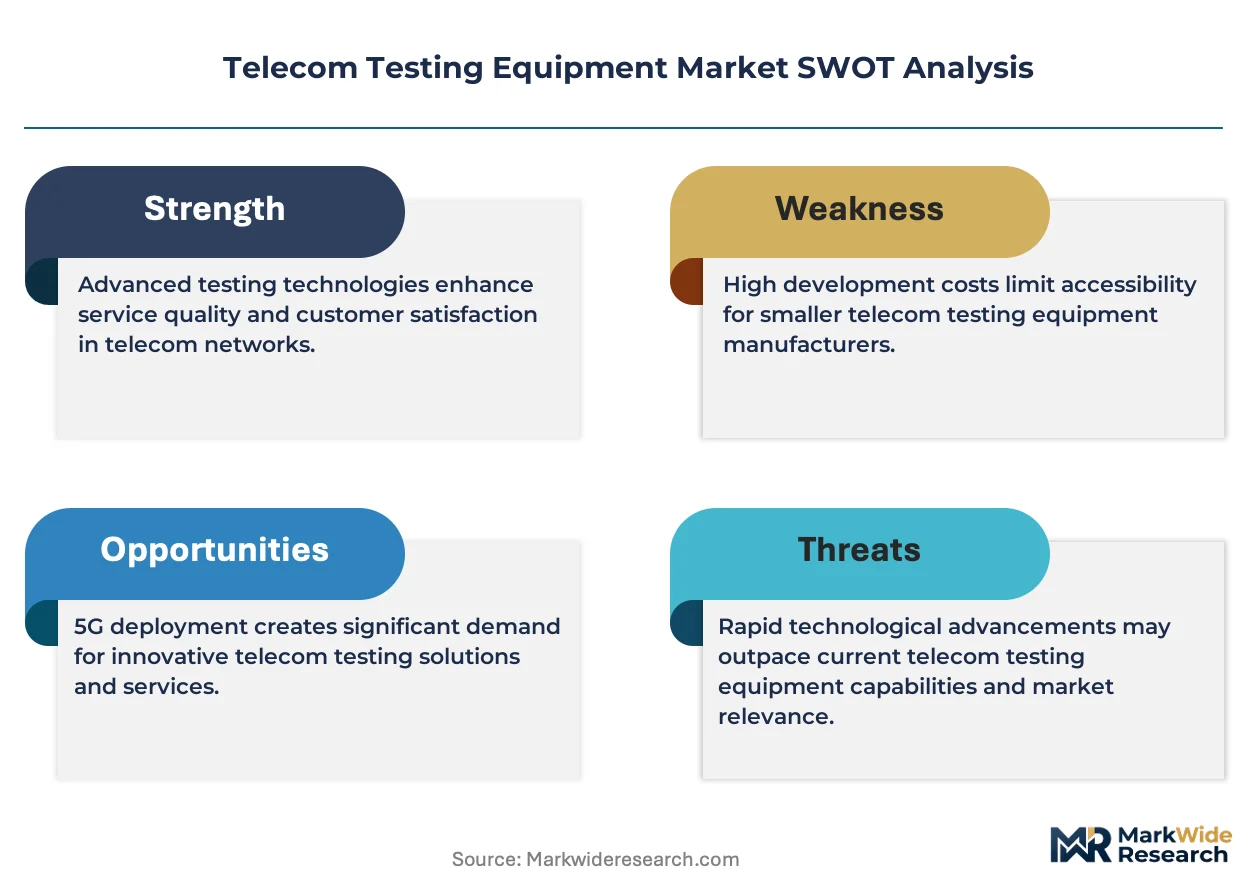
For Market Incumbents: Build calibration laboratory networks as the defensive moat against modular software-defined specialists. Expand captive traceability infrastructure into India and Southeast Asia to preempt emerging entrant laboratory accreditation. Deepen backward integration into millimeter-wave component sourcing to offset GaN substrate scarcity. Prioritize Kubernetes-based automation layer development to capture cloud-native procurement shifts among hyperscale data center operators. For New Entrants and Emerging Players: India's 5G standalone rollout represents the most penetrable geographic entry point, with Reliance Jio and Bharti Airtel procurement windows opening outside incumbent vendor-managed inventory programs. Target municipal broadband contractors in Germany and Japan with portable fiber inspection scopes lacking legacy calibration service overhead. Pursue white-label manufacturing partnerships with Shenzhen-based domestic producers to bypass premium-tier certification requirements. Emphasize spot-purchase pricing flexibility against bundled incumbent contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate test and measurement divisions lacking cloud-native platform investments, particularly European industrial electronics parents with underutilized millimeter-wave IP portfolios. Long-term viability centers on software-defined architecture transitions and recurring revenue attachment rates rather than hardware shipment volumes. Monitor O-RAN Alliance specification maturation as the inflection signal for multi-vendor interoperability testing demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | Accredited traceability infrastructure in Mumbai and Delhi-NCR captures Indian 5G rollout procurement. |
| Cloud-Native Test Orchestration Platform Launch | Kubernetes-based automation decouples revenue from carrier capital cycles at Verizon and AT&T. |
| Millimeter-Wave Signal Generator Portfolio Extension | 140 GHz-plus capabilities address DARPA and METI 6G research program demand ahead of standardization. |
| Backward Integration into GaN Substrate Sourcing | Captive wafer supply secures production continuity amid defense-telecom foundry competition. |
| Open RAN Interoperability Certification Partnership | O-RAN WG4 validation protocols expand addressable scope beyond single-supplier environments. |
Study Parameters
Desk research of FCC equipment authorization databases, ETSI EN standard filings, and carrier capital expenditure disclosures preceded structured interviews with RF test engineering directors, carrier procurement managers, calibration laboratory accreditation officers, and base station OEM validation leads. Primary fieldwork across Santa Rosa, Munich, and Shenzhen manufacturing clusters combined with secondary validation against 3GPP release documentation and O-RAN Alliance specification repositories. Bottom-up instrumentation shipment tracking and top-down carrier capex allocation analysis provided cross-verification.
Forecast assumptions held 5G massive MIMO deployment timelines, Open RAN disaggregation maturity, and fiber-to-the-home program funding commitments as fixed boundary conditions across the analysis window. Segmentation modeling incorporated product type complexity tiers, technology generation cycles, application workflow requirements, and end-user procurement behavior patterns. CAGRs derived from instrument replacement cycle compression rates and service attachment ratio expansion trajectories. Industry-specific inputs included TRAI spectrum auction rule implementations and ETSI EN 303 645 cybersecurity standard adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native platform investments by modular specialists or accelerated GaN substrate capacity additions by defense contractors would shift outcomes. Regulatory reallocation proceedings and Open RAN security mandate timelines constitute primary revision vectors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Sample Rate Converters Market
Test and Measurement
Transformer Testing Equipment Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
Megohmmeters Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Curve Tracer Market
Test and Measurement
Wafer-Level Test and Burn-In [WLTBI] Market
Test and Measurement
Analog Multimeters Market
Test and Measurement
Torsion Tester Market
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market
Test and Measurement
Data Acquisition Equipment Market
Test and Measurement
One-Box Testers Market
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
Flash Point Tester Market