
 Global Spectroscopy Market | 2026-2036
Global Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spectroscopy Market Outlook
Research-grade spectral resolution is collapsing into benchtop and portable form factors once reserved for central laboratories. Agilent Technologies leverages its chromatography-spectroscopy integration to sustain premium positioning in pharmaceutical QA workflows. Bruker Corporation anchors the high-field NMR segment through cryogen-free magnet advances that reduce facility infrastructure costs. Shimadzu Corporation differentiates in Asia-Pacific industrial research with localized service networks and rapid-response technical support.
Spectroscopy encompasses analytical techniques that measure the interaction between electromagnetic radiation and matter to identify molecular composition, structure, and concentration, with instruments typically achieving wavelength precision down to picometer resolution and detection limits in parts-per-billion ranges. Its primary commercial purpose spans quality assurance in drug manufacturing, environmental contaminant screening, and materials characterization for semiconductor fabrication. Mass spectrometry commands the largest revenue pool due to its indispensability in proteomics and metabolomics workflows, while portable and benchtop form factors represent the fastest-expanding demand category as point-of-need testing displaces centralized lab routing. Infrared spectroscopy maintains mature, margin-dense positions in food authenticity verification and polymer identification applications.
FDA method validation requirements and EU MDR instrument qualification standards are elevating compliance costs for manufacturers while creating preference for vendors with embedded regulatory documentation packages. EPA protocols for environmental monitoring and China's NMPA biopharma analytical guidelines are further segmenting demand between certified reference-grade systems and fit-for-purpose industrial units. Stakeholders must weigh capital deployment between high-specification platforms for regulated markets and scalable benchtop configurations serving decentralized testing networks.
Market Dynamics
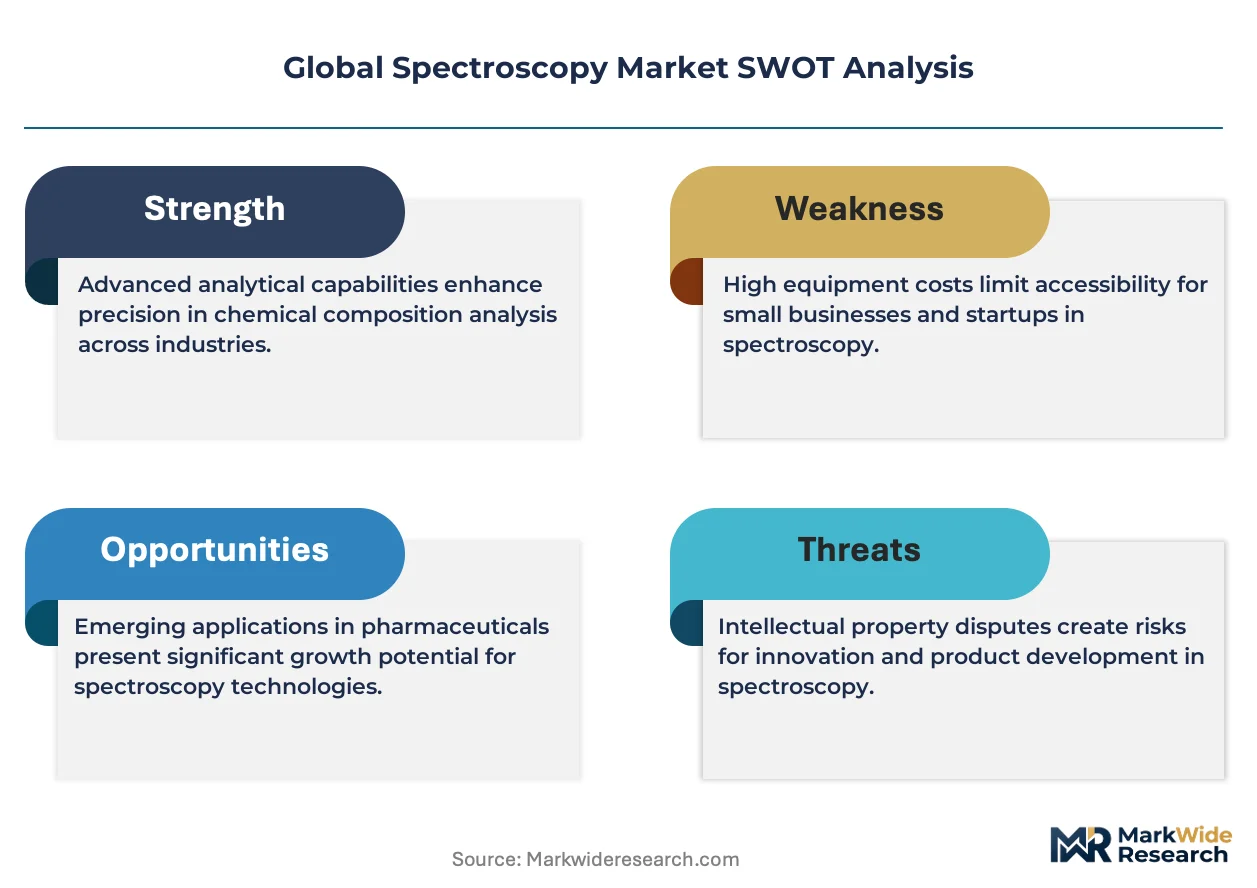
The spectroscopy market is undergoing a structural compression as benchtop and portable instruments displace centralized laboratory infrastructure, driven by pharmaceutical quality control demands and regulatory validation requirements tightening across multiple jurisdictions.
Growth Catalysts
- FDA Method Validation Guidelines:Updated analytical method validation standards are compelling pharmaceutical manufacturers to upgrade spectroscopy systems for impurity detection and quality assurance compliance.
- China's Biopharma Manufacturing Scale-Up:Domestic production capacity expansion is generating concentrated demand for process analytical technology and in-line spectroscopy monitoring systems.
- Cryogen-Free Magnet Advances:High-field NMR systems with reduced facility infrastructure requirements are unlocking adoption in mid-sized research institutions previously priced out of the segment.
Market Restraints
- Helium Supply Concentration:Cryogenic magnet cooling dependencies on concentrated helium sourcing from Qatar and the United States create input cost volatility and supply security risks for high-field NMR manufacturers.
- EU MDR Instrument Qualification:Extended calibration documentation and performance qualification timelines are lengthening sales cycles and elevating pre-purchase compliance costs for European buyers.
- Optical Spectroscopy Substitution:Advanced chromatography-mass spectrometry workflows are capturing applications previously served by UV-Vis and fluorescence techniques in metabolomics research.
Strategic Opportunities
- India's PLI Scheme for Pharma:Production-linked incentive frameworks for active pharmaceutical ingredient manufacturing are creating greenfield demand for process analytical technology and quality control spectroscopy.
- Semiconductor Materials Characterization:Advanced packaging and compound semiconductor fabrication requirements are opening high-margin applications for Raman and X-ray photoelectron spectroscopy in wafer inspection workflows.
- EPA Environmental Monitoring Mandates:Expanded contaminant screening protocols for per- and polyfluoroalkyl substances are driving portable infrared and mass spectrometry procurement for field-deployable testing networks.
Industry Challenges
- Spectroscopist Talent Pipeline:Specialized expertise in spectral interpretation and method development is concentrating in pharmaceutical hubs, creating recruitment bottlenecks for industrial and environmental testing laboratories.
- Legacy LIMS Integration:Laboratory information management system compatibility requirements are complicating deployment of next-generation instruments in established quality control workflows.
- ISO 17025 Accreditation Timelines:Extended certification cycles for testing laboratory competency are delaying revenue recognition for instrument vendors serving contract research organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spectroscopy Market |
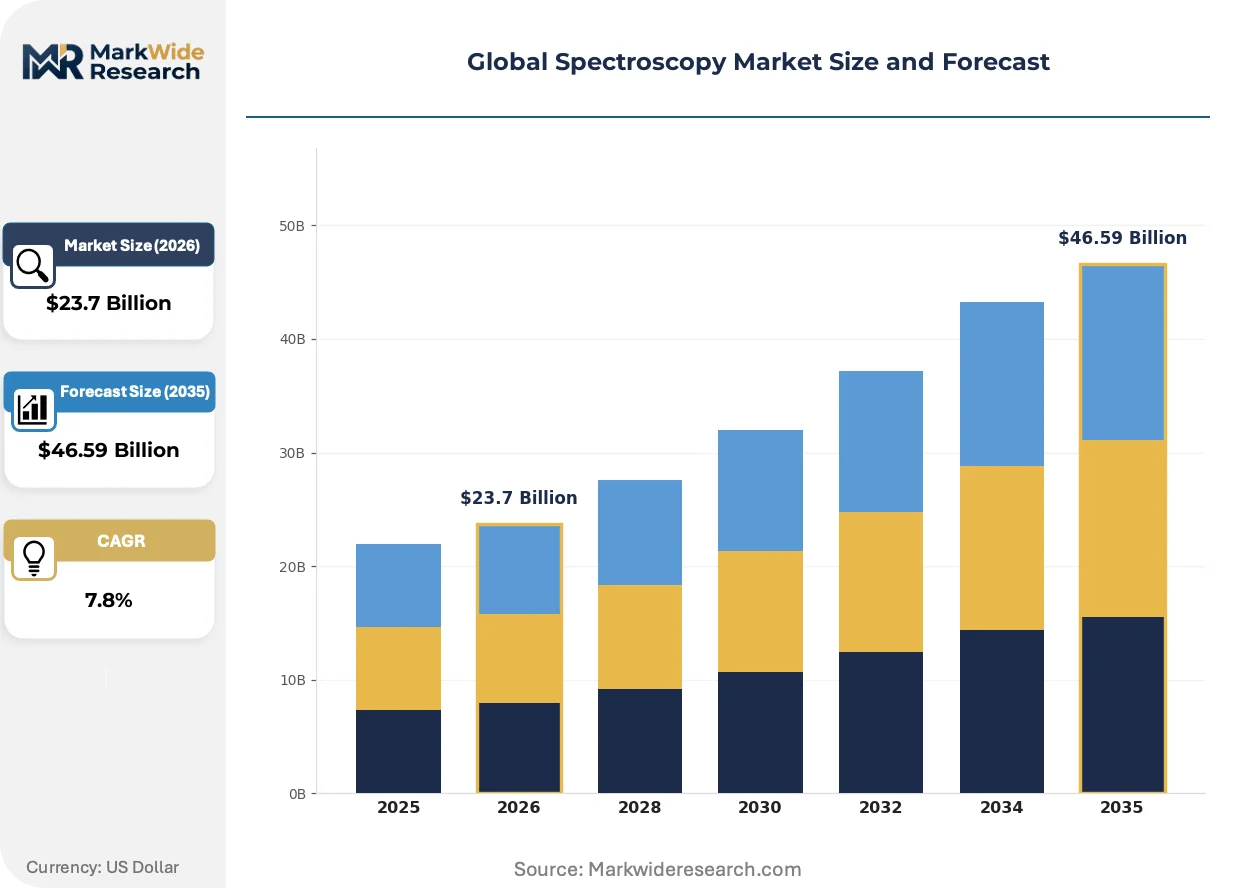
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $46.59 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Mass Spectrometry, Nuclear Magnetic Resonance, Infrared Spectroscopy, Ultraviolet-Visible Spectroscopy Application: Pharmaceuticals, Environmental Testing, Food & Beverage, Biotechnology End User: Academic Research, Clinical Laboratories, Industrial Research, Government Agencies Form: Portable, Benchtop, Hybrid Systems, In-line |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, Bruker Corporation, PerkinElmer, Shimadzu Corporation, Waters Corporation, Danaher Corporation, JEOL Ltd., HORIBA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spectroscopy Market Strategic Shifts
Miniaturization and computational enhancement are converging to relocate analytical capability from central facilities to production floors and field environments, compressing the traditional laboratory services value chain.
Raman spectroscopy with handheld form factors is displacing sample shipment and centralized testing protocols in pharmaceutical raw material verification. Quality control teams at manufacturing sites in Germany and the United States are deploying these units at receiving docks to release inventory within hours rather than days. The structural consequence is a contraction in third-party analytical service contracts and a redistribution of capital expenditure toward point-of-need instrumentation.
REACH substance identification requirements and F-Gas Regulation phase-down schedules are forcing refrigerant-dependent instrument designs toward closed-loop cooling architectures. Manufacturers serving European industrial research markets are accelerating engineering roadmaps to eliminate helium and hydrofluorocarbon dependencies. The segment most affected is high-field NMR, where Bruker and JEOL are prioritizing cryogen-free magnet platforms for EU academic and government laboratory procurement.
Service contract unbundling is fragmenting the traditional instrument vendor revenue model in Asia-Pacific industrial research markets. Buyers in China and Japan are separating hardware procurement from maintenance agreements and software subscriptions, engaging third-party service providers for calibration and repair. This pattern is most visible in food authenticity testing laboratories, where localized technical support networks are displacing manufacturer-direct service organizations.
Global Spectroscopy Market Segmentation
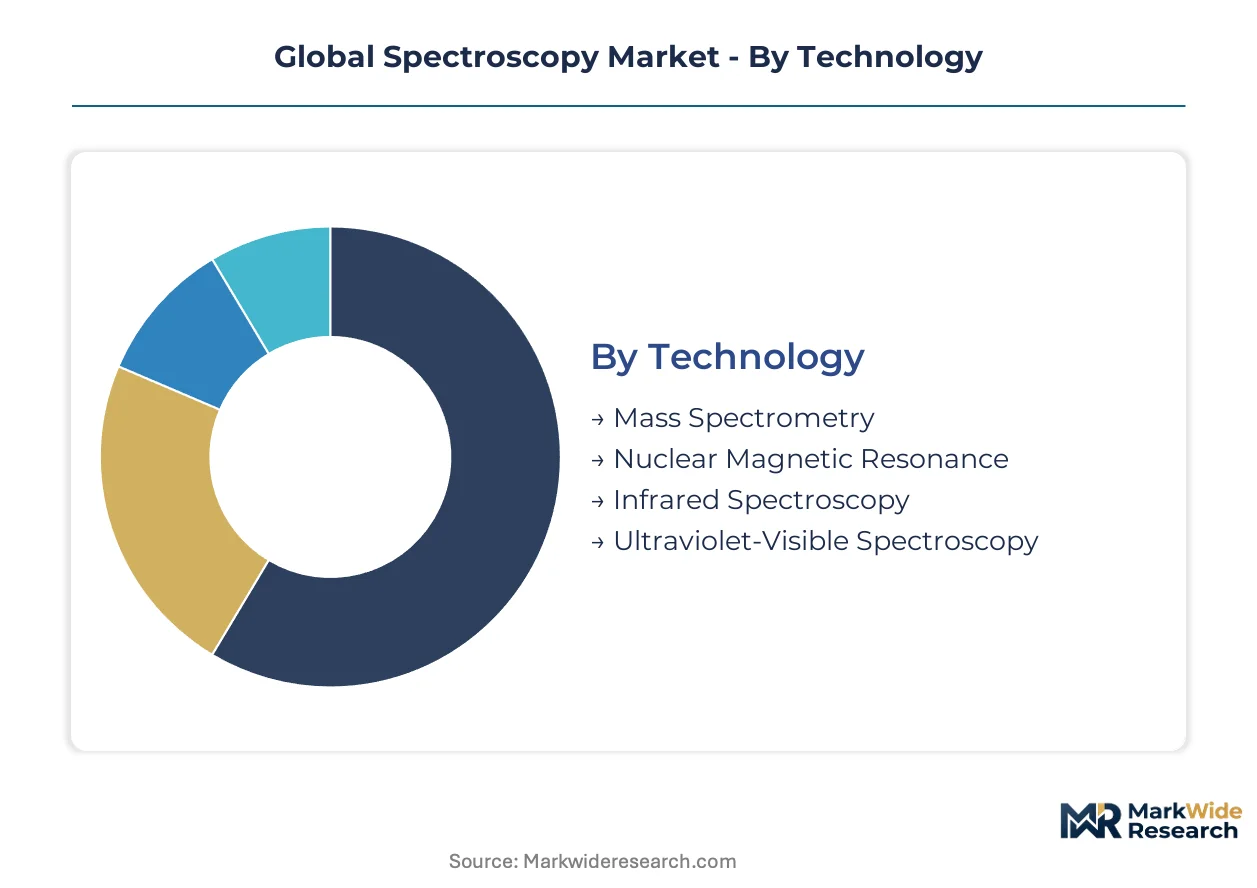
Spectroscopy vendors configure product portfolios around distinct technology-performance tiers, with channel strategy varying sharply between centralized laboratory sales and distributed point-of-need deployment. Understanding how segments map to procurement pathways reveals where margin concentration and volume expansion diverge.
Technology:
Mass spectrometry and NMR systems flow through direct sales channels with embedded service contracts, while optical spectroscopy technologies reach industrial buyers through distribution partners and e-procurement platforms.
- Mass Spectrometry:Ionization and detection systems achieving sub-parts-per-billion sensitivity dominate proteomics and metabolomics workflows. Demand concentrates in pharmaceutical quality control laboratories in Germany and the United States, where FDA method validation requirements compel platform upgrades for impurity detection compliance.
- Nuclear Magnetic Resonance:Cryogen-free magnet architectures are reducing facility infrastructure barriers for high-field systems. Expansion concentrates in mid-sized research institutions in China and Japan previously excluded by helium dependency and facility costs, with cryogen-free platforms unlocking this segment.
- Infrared Spectroscopy:Mature, margin-dense technology serving food authenticity verification and polymer identification through established distribution networks.
- Ultraviolet-Visible Spectroscopy:Cost-effective quantitative analysis for environmental monitoring and pharmaceutical quality assurance, often procured through consolidated laboratory supply contracts.
Mass spectrometry dominates installed base. Cryogen-free NMR is where expansion concentrates.
Application:
Application segments stratify by regulatory intensity, with pharmaceutical and environmental testing commanding premium pricing while food and beverage procurement emphasizes throughput economics.
- Pharmaceuticals:Quality control, impurity profiling, and formulation analysis requiring validated analytical methods. Demand clusters in FDA-regulated manufacturing sites in the United States and EMA-overserved facilities in Germany and Switzerland, with China's NMPA guidelines now driving equivalent compliance investments in domestic biopharma.
- Environmental Testing:Contaminant screening for per- and polyfluoroalkyl substances and persistent organic pollutants. EPA expanded monitoring mandates are accelerating portable infrared and mass spectrometry procurement for field-deployable networks in the United States.
- Food & Beverage:Authenticity verification and adulteration detection, particularly in olive oil and spice supply chains, with European laboratories leading adoption under EFSA oversight.
- Biotechnology:Cell culture monitoring and bioprocess analytical technology, with process analytical technology integration driving in-line spectroscopy demand in single-use manufacturing systems.
Pharmaceuticals anchors revenue concentration. Environmental testing is climbing the fastest as regulatory screening protocols expand.
End User:
End user segments diverge by procurement authority, with academic and government buyers subject to public tender cycles and industrial purchasers negotiating enterprise frameworks.
- Academic Research:Cryogen-free NMR and advanced mass spectrometry for structural biology and materials science. Funding cycles in Germany, Japan, and the United States determine replacement timelines, with EU Horizon programs shaping equipment roadmaps.
- Clinical Laboratories:Diagnostic mass spectrometry for newborn screening and therapeutic drug monitoring, with laboratory-developed test regulations in the United States creating compliance complexity.
- Industrial Research:Applied spectroscopy for polymer development and semiconductor materials characterization, with semiconductor fabrication requirements in Taiwan and South Korea opening high-margin Raman applications.
- Government Agencies:Environmental monitoring and forensic applications, with EPA and EEA procurement standards emphasizing field portability and ruggedized specifications.
Academic research holds the largest installed base. Industrial research is gaining share fastest as semiconductor and advanced materials applications multiply.
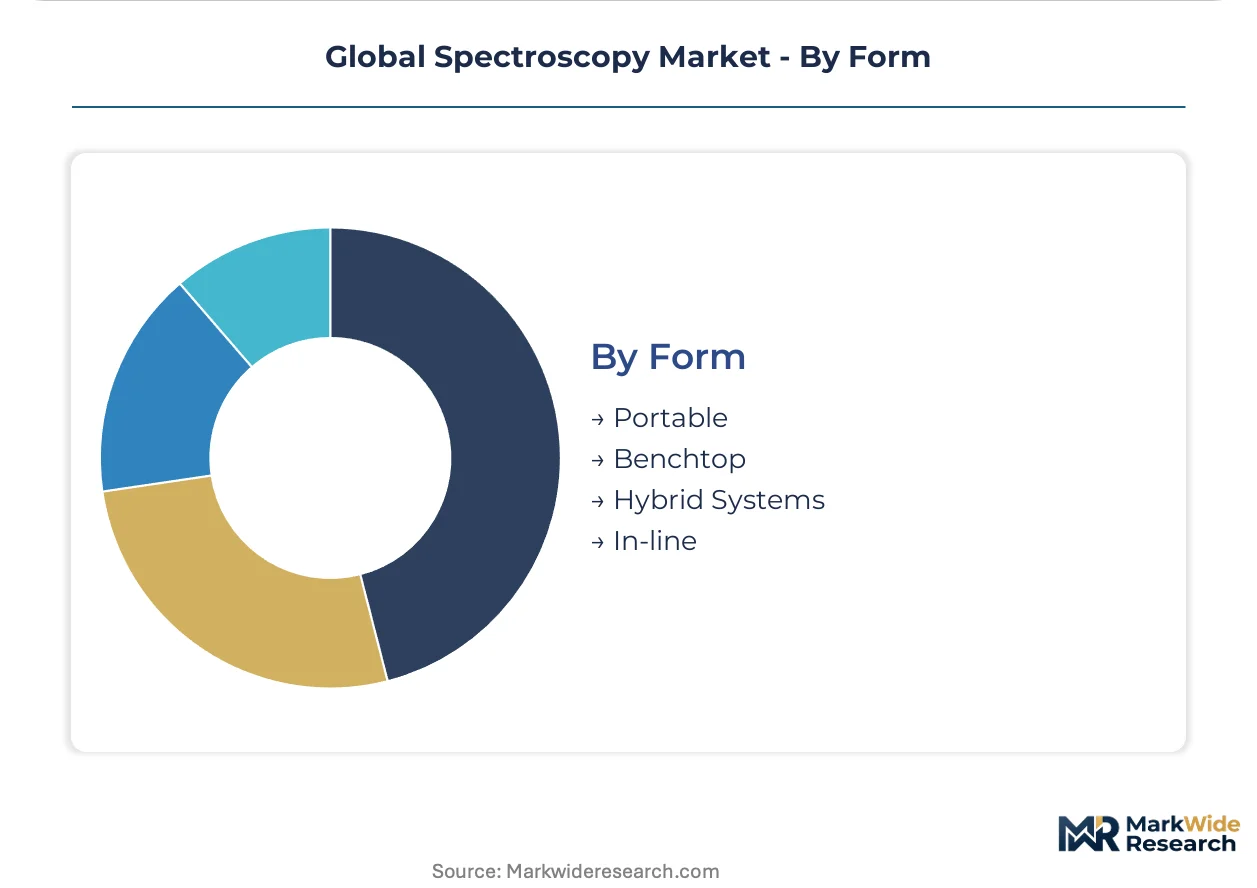
Form:
Form factor selection determines service model economics, with portable and benchtop systems enabling unbundled maintenance contracts and third-party calibration networks.
- Portable:Handheld Raman and infrared units for raw material verification at pharmaceutical receiving docks. Quality control teams in Germany and the United States deploy these for inventory release within hours, compressing third-party analytical service contracts.
- Benchtop:Laboratory-grade performance without facility infrastructure requirements, serving mid-sized institutions and decentralized testing networks in China and India.
- Hybrid Systems:Modular configurations combining multiple spectroscopic techniques, appealing to core facilities serving diverse research programs.
- In-line:Process analytical technology for real-time biopharma manufacturing monitoring, with China's domestic production scale-up generating concentrated demand for continuous verification systems.
Benchtop systems dominate unit shipments. Portable form factors are expanding most quickly as point-of-need testing displaces centralized laboratory routing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium sourcing from Qatar and the United States constrains high-field NMR deployment, while pharmaceutical manufacturing scale-up in China and India redirects procurement toward cryogen-free and benchtop configurations. FDA method validation guidelines and EU MDR instrument qualification standards are segmenting demand between certified reference-grade systems and fit-for-purpose industrial units across major markets.
United States
Pharmaceutical quality control laboratories in New Jersey and Massachusetts are upgrading mass spectrometry platforms for FDA impurity detection compliance. EPA expanded monitoring mandates for per- and polyfluoroalkyl substances are accelerating portable infrared and mass spectrometry procurement for field-deployable testing networks. Boston-Cambridge biotech clusters are driving process analytical technology integration in single-use manufacturing systems.
Germany
BASF and Bayer manufacturing sites in Ludwigshafen and Leverkusen are deploying in-line spectroscopy for real-time process monitoring under REACH substance identification requirements. EMA oversight of pharmaceutical analytical methods is extending calibration documentation timelines for European buyers. Munich-Stuttgart industrial research corridors are prioritizing cryogen-free magnet platforms to eliminate helium dependencies under F-Gas Regulation phase-down schedules.
China
Domestic biopharma manufacturing capacity expansion in Shanghai and Suzhou is generating concentrated demand for process analytical technology and continuous verification systems. NMPA analytical guidelines for biopharma are driving equivalent compliance investments to FDA standards in domestic facilities. Yangtze River Delta pharmaceutical hubs are scaling spectroscopy adoption for quality control and raw material verification.
Japan
Mid-sized research institutions in Tokyo and Osaka are adopting cryogen-free NMR systems previously excluded by helium dependency and facility infrastructure costs. METI funding for materials science research is shaping equipment roadmaps for semiconductor materials characterization. Kyoto-Osaka-Kobe manufacturing belts are opening high-margin applications for Raman spectroscopy in advanced packaging inspection.
India
Production-linked incentive frameworks for active pharmaceutical ingredient manufacturing in Gujarat and Maharashtra are creating greenfield demand for quality control spectroscopy. CDSCO alignment with international method validation standards is compelling upgrade cycles in contract research organizations. Hyderabad-Bengaluru pharmaceutical corridors are deploying handheld Raman units for raw material verification at receiving docks.
Global Spectroscopy Market Competitive Environment
Concentration sits with diversified analytical instrumentation conglomerates and specialized spectroscopy pure-plays. The vendor base spans three tiers: integrated life science platforms with chromatography-spectroscopy bundling, high-field magnetic resonance specialists with cryogen-free engineering capabilities, and regional service-anchored distributors serving industrial research markets. Strategic moves center on regulatory documentation packaging for compliance-heavy pharmaceutical procurement and unbundled service contract structures for Asia-Pacific price-sensitive buyers.
Among diversified analytical instrumentation conglomerates, Agilent Technologies and Thermo Fisher Scientific exemplify platform-integrated positioning that sustains premium capture in pharmaceutical QA workflows. Bruker Corporation anchors the high-field NMR specialist archetype through cryogen-free magnet advances that reduce facility infrastructure barriers for mid-sized institutions. Shimadzu Corporation occupies a position within the Asia-Pacific service-anchored tier, differentiating through localized technical support networks and rapid-response calibration capabilities in industrial research markets.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| Bruker Corporation |
| PerkinElmer |
| Shimadzu Corporation |
| Waters Corporation |
| Danaher Corporation |
| JEOL Ltd. |
| HORIBA |
| Others |
Value Chain & Pricing Dynamics
Long-term helium offtake agreements from Qatar and the United States lock in cryogen-free magnet cost visibility for NMR manufacturers while exposing buyers to supply concentration risk. These contract structures tether pricing predictability to geopolitical stability in concentrated sourcing regions.
Pricing Analysis
FDA method validation guidelines and EU MDR instrument qualification standards dictate the pricing tier structure across pharmaceutical-grade, industrial-research, and fit-for-purpose economy segments. Three-tier pricing structure across premium, standard, and economy levels separates validated reference systems from configurable benchtop units and portable field-deployable instruments. Cost compression in the economy tier is intensifying because buyers in China and India are unbundling service contracts from hardware procurement. Contract research organizations exhibit highest price sensitivity, while FDA-regulated pharmaceutical manufacturers prioritize compliance documentation over unit cost.
Supply Chain Analysis
Qatar and the United States anchor helium extraction for cryogenic magnet cooling, while China and Japan concentrate rare-earth magnet fabrication and precision optical component manufacturing. High-field NMR production draws from concentrated helium sourcing, specialized superconducting wire, and cryostat assembly expertise. Single-source vulnerability runs through Qatar's helium export infrastructure and its exposure to regional supply disruptions. Distribution runs through direct sales channels for mass spectrometry and NMR systems, with optical spectroscopy reaching industrial buyers via regional distribution partners and consolidated laboratory supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-need testing adoption is accelerating penetration beyond centralized laboratory infrastructure, creating early-cycle expansion conditions for portable and benchtop form factors.
For Market Incumbents: Consolidate regulatory documentation capabilities to defend pharmaceutical procurement relationships against emerging chromatography-mass spectrometry substitution threats. Deepen backward integration into cryogen-free magnet engineering to reduce helium dependency exposure. Expand calibration service networks in Asia-Pacific industrial research markets to counter third-party service provider fragmentation.
For New Entrants and Emerging Players: ISO 17025 accreditation fast-tracks open contract research organization procurement channels previously locked behind extended vendor qualification timelines. Target environmental testing laboratories in the United States facing EPA expanded monitoring mandates as the most penetrable segment. Deploy handheld Raman units through rental and lease-to-own structures to bypass capital budget constraints at mid-sized manufacturing sites.
For Investors and Strategic Acquirers: Cryogen-free NMR engineering specialists with established university research relationships represent the priority acquisition archetype for technology and channel access. Long-term viability hinges on portfolio positioning between regulated pharmaceutical compliance markets and scalable industrial point-of-need deployment. Watch for inflection in India's PLI scheme disbursement velocity as a signal for greenfield quality control spectroscopy demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free Magnet Platform Launch | Eliminates helium dependency for EU F-Gas Regulation compliance and mid-sized institution access. |
| Regulatory Documentation Package Expansion | Accelerates FDA and EMA qualification timelines for pharmaceutical quality control procurement. |
| Third-Party Service Network Partnership | Captures unbundled maintenance demand from price-sensitive buyers in China and Japan. |
| Handheld Raman Distribution Agreement | Compresses raw material verification timelines at pharmaceutical receiving docks in Germany and the United States. |
| Process Analytical Technology Integration | Locks in continuous manufacturing monitoring contracts with scaling biopharma producers in Shanghai and Suzhou. |
Study Parameters
A spread of perspectives from spectroscopy product managers, pharmaceutical quality control directors, laboratory procurement officers, and regulatory affairs specialists converged on the working assumptions for demand segmentation and technology substitution patterns. Primary field engagement combined with secondary validation from FDA guidance documents, EMA qualification standards, EPA monitoring protocols, and NMPA analytical guidelines anchored the analytical framework. Bottom-up instrument shipment estimates and top-down market size triangulation cross-checked technology-specific growth trajectories.
Segmentation dimensions modeled include technology type, application vertical, end-user category, and form factor configuration across the projection horizon. CAGRs were derived from weighted technology adoption curves, replacement cycle analysis, and regulatory compliance-driven upgrade elasticity. Cryogen-free NMR penetration rates and portable spectroscopy displacement of centralized testing protocols served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained pharmaceutical manufacturing scale-up in China and helium supply stability from Qatar; material deviation would warrant model refresh. Recalibration cycles align with material shifts in FDA method validation timelines, EU MDR implementation enforcement, and China's domestic biopharma production capacity utilization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Spectrum and Signal Analyzers Market
Analytical Instruments
Boron Analyzer Market
Analytical Instruments
Dissolved Gas Analyzer Market
Analytical Instruments
Global PH Electrochemical Electrodes Market
Analytical Instruments
Trace Oxygen Analyzer Market
Analytical Instruments
Global Gel Documentation Systems Market
Analytical Instruments
Contact Angle Measuring Instrument Market
Analytical Instruments
Dew Point Analyzer Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Gas Analyzer Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Spectroscopy Software Market