
 Portable Chromatography Systems Market | 2026-2036
Portable Chromatography Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Chromatography Systems Market Outlook
Aftermarket service revenue is reshaping competitive economics in portable chromatography, pulling margin pools from hardware sales toward calibration contracts and consumable subscriptions. Agilent Technologies leverages its global service infrastructure to capture recurring revenue across installed bases. Thermo Fisher Scientific anchors its position through deep integration of mass spectrometry detection modules with portable liquid chromatography platforms. Shimadzu Corporation specializes in compact gas chromatography configurations tailored to environmental field monitoring applications.
Portable chromatography systems are self-contained analytical instruments that separate chemical mixtures using mobile and stationary phases, typically operating with detection limits in parts-per-billion range and power draw below 200 watts for true field deployment. Their primary commercial purpose is enabling real-time compositional analysis outside centralized laboratory facilities, reducing sample transit time and degradation risk. Liquid chromatography dominates current revenue owing to its versatility across pharmaceutical and food safety matrices, while gas chromatography segments show faster structural growth driven by petrochemical and environmental enforcement applications. Mass spectrometry detection technology commands premium positioning due to its specificity in complex mixture identification, though UV detection retains volume leadership in routine quality control settings.
EPA Method 8260 and FDA process analytical technology guidelines tighten performance validation requirements for field-deployable instruments, directly shaping product development roadmaps and procurement specifications. REACH compliance in Europe and GB standards enforcement in China add parallel certification burdens that filter lower-specification competitors from commercial consideration. Stakeholders must monitor evolving convergence between portable chromatography data integrity standards and enterprise laboratory information management systems to anticipate integration investment cycles.
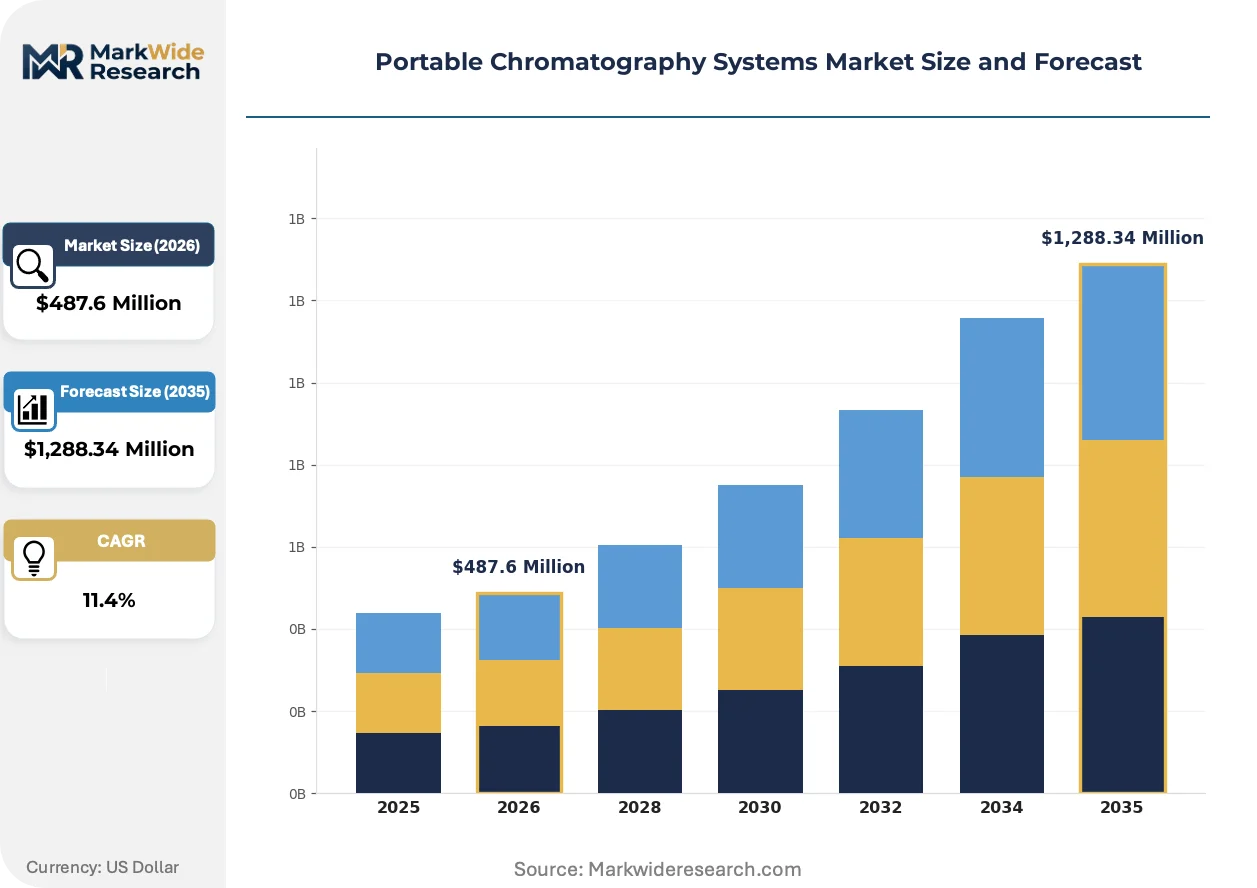
Market Dynamics
Aftermarket service revenue is compressing hardware margins across portable chromatography, forcing manufacturers to restructure around recurring calibration contracts and consumable subscriptions rather than unit sales.
Growth Catalysts
- EPA Method 8260:Volatile organic compound monitoring mandates in the United States are accelerating replacement cycles for field-deployable gas chromatography units in environmental consulting.
- Process analytical technology:FDA guidance on real-time pharmaceutical quality testing is pulling compact liquid chromatography systems into at-line manufacturing configurations.
- Germany's chemical clusters:REACH enforcement intensity around Ludwigshafen and Leverkusen creates premium positioning for portable systems with certified traceability.
Market Restraints
- Helium supply concentration:Gas chromatography dependence on helium carrier gas exposes users to price volatility from Qatar and Algeria export constraints.
- Mass spectrometry cost floor:Detection module miniaturization hits physics limits below $15,000 unit cost, excluding budget-tier buyers from specificity advantages.
- REACH certification friction:ECHA substance database updates force recurring re-registration costs that filter smaller instrument vendors from European tenders.
Strategic Opportunities
- India's pharmaceutical corridors:CDSCO quality mandate expansion in Hyderabad and Ahmedabad creates first-mover positioning for portable systems with Hindi-language interfaces.
- Mass spectrometry-liquid chromatography convergence:Integrated LC-MS platforms for food safety testing command 40% price premiums over UV-detection equivalents in export-certification labs.
- Subscription calibration channels:Remote diagnostics over cellular networks enable predictive maintenance contracts that lock in multi-year consumable revenue streams.
Industry Challenges
- Chromatography method development expertise:Field-deployable systems require operators with compound-specific parameter optimization skills that outpace vocational training pipeline output.
- Laboratory information management integration:Portable units must validate data integrity standards against enterprise LIMS architectures, extending deployment timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Chromatography Systems Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Chromatography, Gas Chromatography, Supercritical Fluid Chromatography, Flash Chromatography End User: Laboratories, Pharmaceuticals, Environmental Testing, Food Safety Technology: UV Detection, Mass Spectrometry, Refractive Index Detection, CAD Application: Quality Control, Research & Development, Chemical Analysis, Drug Testing |
| Companies Covered | Agilent Technologies, Inc., PerkinElmer Inc., INFICON, Axcend, FLIR Systems, Inc., Bio-Rad Laboratories, Thermo Fisher Scientific, Shimadzu Corporation, Phenomenex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Chromatography Systems Market Strategic Shifts
Cloud-native data architectures are displacing local storage in portable chromatography, enabling real-time regulatory submission and remote method transfer between distributed manufacturing sites.
Miniaturized mass spectrometry detection is digitizing compound identification workflows in pharmaceutical field audits. Quality assurance teams at active pharmaceutical ingredient plants are adopting palm-sized MS modules for counterfeit screening. This capability compression is eliminating the gap between laboratory-grade specificity and warehouse-floor throughput.
EU F-Gas Regulation phase-down schedules are forcing refrigerant gas analysis into mobile configurations. Environmental contractors across Belgium and the Netherlands are retrofitting vans with compact gas chromatography for hydrofluorocarbon leak detection. Equipment procurement specifications now mandate battery operation below 150 watts to qualify for green public procurement tenders.
Service unbundling is fragmenting traditional sales relationships in analytical instrumentation. Pharmaceutical buyers in Switzerland and Austria are separating hardware acquisition from multi-vendor calibration contracts. This procurement pattern shift compresses vendor switching costs and rewards modular platform architectures over integrated system lock-in.
Portable Chromatography Systems Market Segmentation
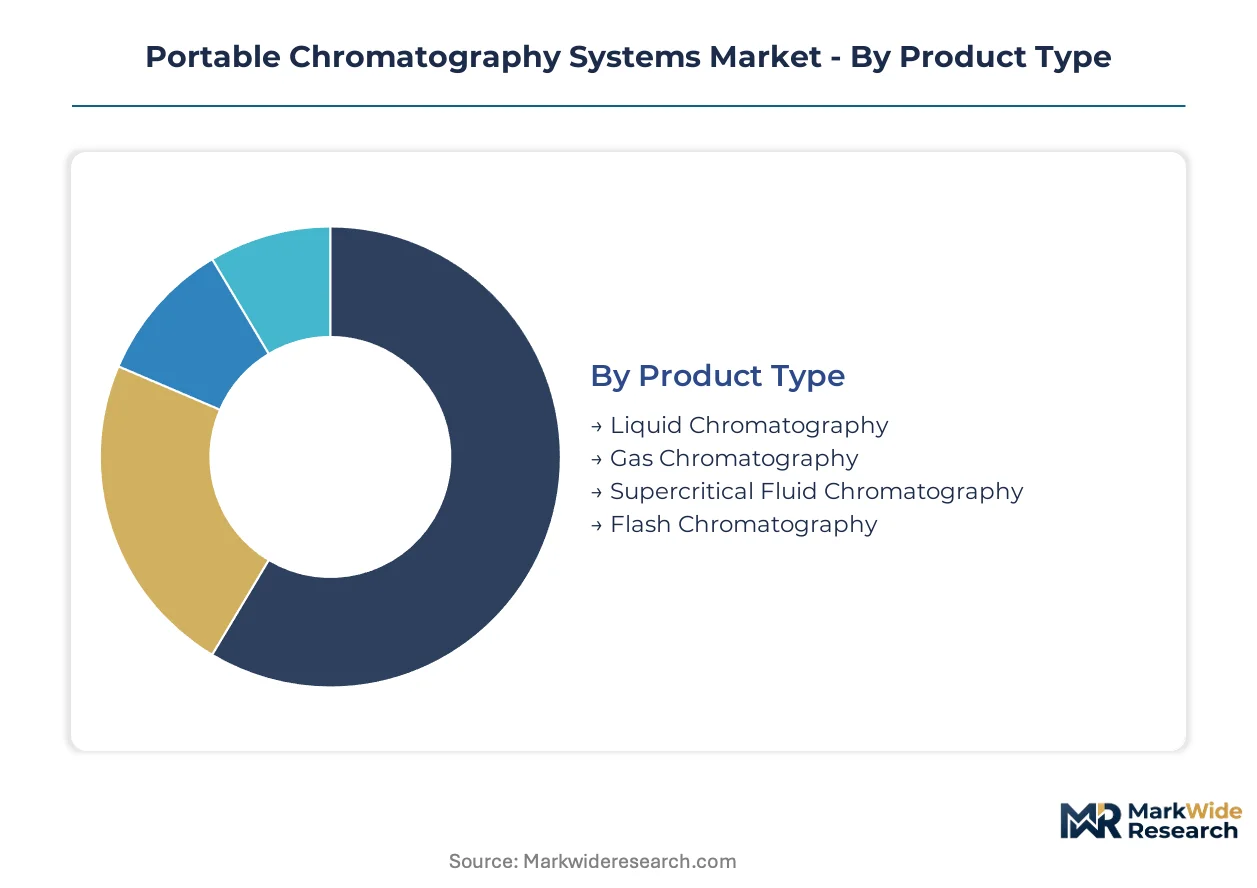
Segmentation in portable chromatography reveals distinct procurement rhythms and margin structures across product architectures, detection technologies, and end-use environments. Understanding these divisions exposes where hardware replacement cycles accelerate versus where installed bases stagnate.
Product Type:
Replacement velocity varies sharply across chromatography modalities, with field-deployable gas units turning over fastest due to carrier gas infrastructure obsolescence, while liquid platforms persist longer in validated pharmaceutical workflows.
- Liquid Chromatography:Compact LC systems separate non-volatile and thermally labile compounds using pressurized solvent delivery, typically achieving resolution below 2.5 µm particle sizes. Pharmaceutical quality control laboratories in Germany concentrate demand here, driven by FDA process analytical technology mandates for at-line release testing.
- Gas Chromatography:These systems analyze volatile organic compounds through heated injection ports and capillary columns, with detection limits reaching parts-per-trillion for environmental applications. Environmental consulting firms across the United States dominate procurement, responding to EPA Method 8260 compliance deadlines for soil and groundwater monitoring.
- Supercritical Fluid Chromatography:SFC platforms employ carbon dioxide as mobile phase for chiral separations in active pharmaceutical ingredient development.
- Flash Chromatography:Low-pressure preparative systems serve synthetic chemistry workflows in academic and contract research settings.
Liquid Chromatography dominates installed base. Gas Chromatography is where expansion concentrates.
End User:
Customer type determines pricing tolerance and service contract attachment rates, with pharmaceutical buyers accepting premium positioning for validation documentation while environmental contractors prioritize capital efficiency.
- Laboratories:Centralized analytical facilities require portable systems for method transfer and satellite location support, typically specifying enterprise LIMS integration and 21 CFR Part 11 compliance documentation. Academic laboratories in Switzerland and Austria are unbundling hardware from calibration contracts, compressing vendor switching costs.
- Pharmaceuticals:Manufacturing quality teams deploy compact systems for at-line potency and purity verification, with detection module specificity directly impacting batch release timelines. CDSCO mandate expansion in Hyderabad and Ahmedabad, India, is accelerating first-mover positioning for systems with localized interface languages.
- Environmental Testing:Field contractors prioritize battery operation below 150 watts to qualify for green public procurement tenders in Belgium and the Netherlands.
- Food Safety:Export certification laboratories command integrated LC-MS platforms for pesticide and veterinary residue screening.
Pharmaceuticals dominates installed base. Environmental Testing is climbing the fastest.
Technology:
Detection modality creates the steepest price stratification in portable chromatography, with mass spectrometry modules commanding substantial premiums over optical alternatives despite miniaturization physics constraints.
- UV Detection:Variable wavelength and diode array configurations serve routine quality control with detection limits in the low nanogram range for chromophore-bearing compounds. Volume leadership concentrates in food safety and pharmaceutical release testing where specificity requirements permit spectroscopic identification.
- Mass Spectrometry:Miniaturized quadrupole and ion trap modules deliver molecular weight confirmation and structural elucidation for complex mixture analysis. Physics limits prevent unit costs below $15,000, excluding budget-tier buyers from specificity advantages in counterfeit pharmaceutical screening.
- Refractive Index Detection:Universal detection for non-chromophoric analytes in polymer and carbohydrate analysis.
- CAD:Charged aerosol detection provides near-universal response for non-volatile compounds in pharmaceutical excipient characterization.
UV Detection dominates installed base. Mass Spectrometry is gaining share fastest.
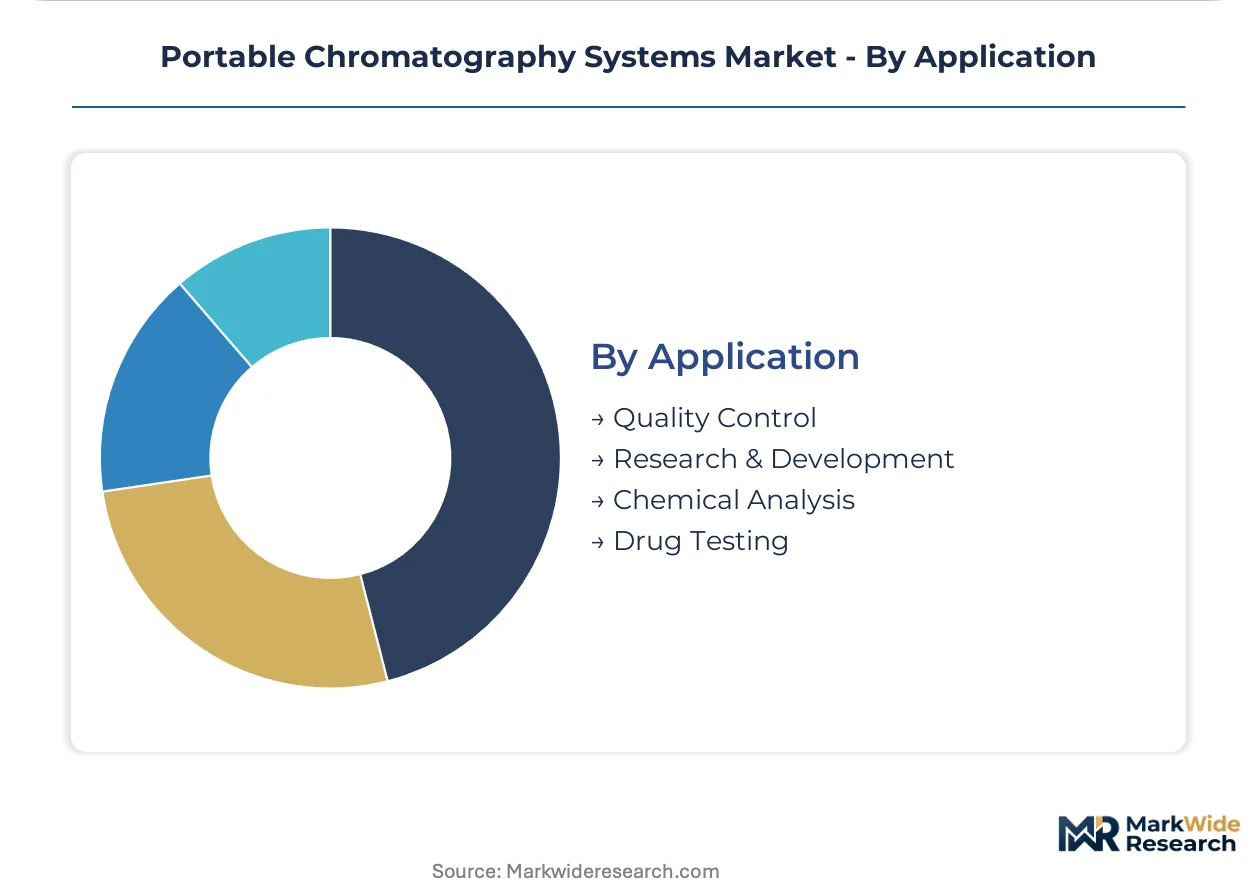
Application:
Use case determines method development investment and operator skill requirements, with research applications tolerating longer optimization cycles than regulated quality control workflows.
- Quality Control:Validated analytical procedures for batch release demand locked method parameters and automated system suitability testing, with data integrity standards extending deployment timelines by 4-6 months for LIMS integration. Pharmaceutical manufacturing sites in Germany's Ludwigshafen and Leverkusen clusters prioritize certified traceability for REACH compliance.
- Research & Development:Method development flexibility and rapid column chemistry switching support synthetic route exploration and formulation characterization. Active pharmaceutical ingredient plants are adopting palm-sized MS modules for counterfeit screening, eliminating throughput gaps between laboratory and warehouse floor.
- Chemical Analysis:Petrochemical field laboratories specify ruggedized enclosures for refinery and pipeline deployment.
- Drug Testing:Forensic and workplace screening applications require chain-of-custody documentation and rapid turnaround.
Quality Control dominates installed base. Research & Development is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portable chromatography system supply concentrates among German precision manufacturers and US analytical instrumentation specialists, with demand fragmentation across pharmaceutical corridors and environmental enforcement zones in multiple jurisdictions.
United States
Environmental consulting firms and pharmaceutical quality teams drive procurement, responding to EPA Method 8260 compliance deadlines for volatile organic compound monitoring. FDA process analytical technology guidelines accelerate at-line instrument deployment in manufacturing facilities. Houston petrochemical clusters and Boston-area biotech corridors concentrate field-deployable gas chromatography adoption.
Germany
Chemical manufacturing clusters around Ludwigshafen and Leverkusen prioritize portable systems with certified traceability for REACH enforcement. ECHA substance database updates force recurring re-registration investments that filter smaller vendors from tenders. Bavarian pharmaceutical manufacturers anchor demand for compact liquid chromatography units with enterprise LIMS integration.
India
CDSCO quality mandate expansion in Hyderabad and Ahmedabad pharmaceutical corridors creates first-mover positioning for systems with Hindi-language interfaces. Active pharmaceutical ingredient plants adopt palm-sized detection modules for counterfeit screening workflows. Gujarat and Maharashtra manufacturing belts concentrate environmental compliance spending among chemical exporters.
China
GB standards enforcement and dual carbon goals drive mobile refrigerant gas analysis procurement across industrial zones. NMPA pharmaceutical quality regulations accelerate at-line testing instrument adoption in active ingredient facilities. Yangtze River Delta chemical clusters and Pearl River Delta electronics manufacturing hubs concentrate demand for battery-operated field systems.
Switzerland
Pharmaceutical buyers in Basel and Zurich unbundle hardware acquisition from multi-vendor calibration contracts, compressing vendor switching costs. Swissmedic validation requirements sustain premium positioning for systems with 21 CFR Part 11 documentation. Academic laboratories in Lausanne and Geneva drive modular platform procurement over integrated system lock-in.
Portable Chromatography Systems Market Competitive Environment
Full-stack analytical instrumentation conglomerates and specialized chromatography component suppliers split the market along integration depth. Tier-one participants leverage global service infrastructures to capture recurring calibration revenue across installed bases. Mid-scale specialists concentrate on compact gas chromatography configurations for environmental field applications. Dominant competitive moves include mass spectrometry detection module integration with portable liquid platforms and remote diagnostics subscription channels over cellular networks.
Within the full-stack instrumentation tier, Agilent Technologies, Inc. and Thermo Fisher Scientific exemplify service-anchored competitive positioning through recurring revenue capture across calibration contracts and consumable subscriptions. Shimadzu Corporation occupies a position among precision manufacturers specializing in environmental monitoring configurations. These three entities represent divergent strategic archetypes: service infrastructure scale, detection technology integration depth, and application-specific compact system design.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| PerkinElmer Inc. |
| INFICON |
| Axcend |
| FLIR Systems, Inc. |
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| Shimadzu Corporation |
| Phenomenex |
| Others |
Value Chain & Pricing Dynamics
Helium supply concentration from Qatar and Algeria export constraints determines both pricing tier spreads and supply chain shape in portable chromatography, compressing margins on gas chromatography units while forcing liquid chromatography platforms toward subscription-based revenue models.
Pricing Analysis
EPA Method 8260 dictates the pricing tier structure across environmental field-deployable units, with certified traceability for REACH compliance commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels separates mass spectrometry-integrated systems from UV-detection equivalents from basic portable configurations. Cost compression in economy-tier gas chromatography is intensifying because helium carrier gas price volatility erodes operating margins. Environmental contractors in Belgium and the Netherlands demonstrate highest price sensitivity, while pharmaceutical quality teams in Germany accept premium positioning for 21 CFR Part 11 validation documentation.
Supply Chain Analysis
Contract manufacturing for precision analytical components concentrates among German precision engineering specialists and Japanese optical component fabricators. Final assembly draws from Germany, United States, and Japan, with detection module miniaturization resting on South Korean semiconductor foundry capacity. Raw material dependencies include fused silica capillary tubing, high-purity solvent chemistries, and rare-earth magnet assemblies for mass spectrometry ion optics. Single-source vulnerability in helium refining infrastructure exposes gas chromatography manufacturers to supply disruption. Distribution runs through direct enterprise sales teams for pharmaceutical accounts and environmental equipment distributors for field contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where EPA Method 8260 and FDA process analytical technology certification requirements create switching costs that lock validated instrument configurations into multi-year replacement cycles.
For Market Incumbents: Pre-empt emerging competitors by deepening backward integration into consumable chemistries and securing exclusive calibration service contracts across installed bases in Germany's Ludwigshafen and Leverkusen chemical clusters. Anchor defensive positioning through predictive maintenance subscriptions over cellular networks that embed remote diagnostics into multi-year agreements. Counter margin pressure from unbundled procurement patterns in Switzerland and Austria by modularizing platform architectures to reduce vendor switching costs. For New Entrants and Emerging Players: Mid-market pharmaceutical manufacturers in Hyderabad and Ahmedabad represent the most penetrable entry point, where CDSCO mandate expansion outpaces established service infrastructure. Target food safety export certification laboratories in India with integrated LC-MS platforms that command price premiums over UV-detection equivalents. Penetrate through Hindi-language interface localization and cellular-enabled remote calibration capabilities that bypass incumbent field service density advantages. For Investors and Strategic Acquirers: EPA Method 8260 compliance deadline acceleration reshapes the acquisition landscape toward environmental field monitoring specialists with established carrier gas infrastructure relationships. Long-term viability favors precision manufacturers with compact gas chromatography expertise and modular platform architectures that accommodate unbundled procurement trends. Target acquisition archetypes include mid-scale specialists with REACH certification track records and cellular diagnostics software stacks. Watch for inflection signals in helium supply contract renegotiation patterns and ECHA substance database update frequency.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Spectrometry Module Integration | Palm-sized detection modules eliminate laboratory-warehouse specificity gaps for pharmaceutical counterfeit screening. |
| Cellular Remote Diagnostics Platform | Predictive maintenance subscriptions over cellular networks lock multi-year consumable revenue streams across distributed manufacturing sites. |
| REACH Certification Investment | Certified traceability documentation filters smaller competitors from European chemical cluster tenders in Germany. |
| Consumable Chemistry Backward Integration | In-house production of high-purity solvents and column chemistries captures margin pools shifting from hardware sales. |
| Hindi Interface Localization | CDSCO mandate expansion in Indian pharmaceutical corridors creates first-mover positioning for localized operator experiences. |
Study Parameters
Operator-level perspectives from pharmaceutical quality control managers, environmental field contractors, analytical instrumentation procurement officers, and aftermarket service directors anchored the qualitative base. Primary interviews combined with secondary validation from EPA enforcement guidance documents, FDA process analytical technology guidance filings, ECHA substance database update records, and customs trade data for analytical instrument imports. Bottom-up installed base modeling and top-down market sizing triangulated volume and value estimates across the analysis window.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning chromatography modality, detection technology, end-use environment, and geographic regulatory cluster. CAGRs derived from replacement cycle velocity analysis, regulatory mandate compliance timelines, and technology diffusion patterns across pharmaceutical manufacturing and environmental enforcement applications. Forecast inputs incorporated helium supply contract pricing trajectories and ECHA registration cost escalation curves.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles and pharmaceutical manufacturing investment patterns would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology miniaturization physics limits. Quarterly review of EPA Method 8260 compliance deadline adjustments and ECHA substance database update frequency is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
Disintegration Analyzer Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
High-Vacuum Gauge Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Portable Gas Analyzer Market
Analytical Instruments
Global Laboratory Electronic Balance Market
Analytical Instruments
Thermoluminescent Dosimeter (TLD) System Market
Analytical Instruments
Analytical Instrumentation for Food Applications Market
Analytical Instruments
Illuminometer Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market