
 AFM Probe Market | 2026-2036
AFM Probe Market Size, Share, and Industry Trends Forecast 2026-2036
AFM Probe Market Analysis
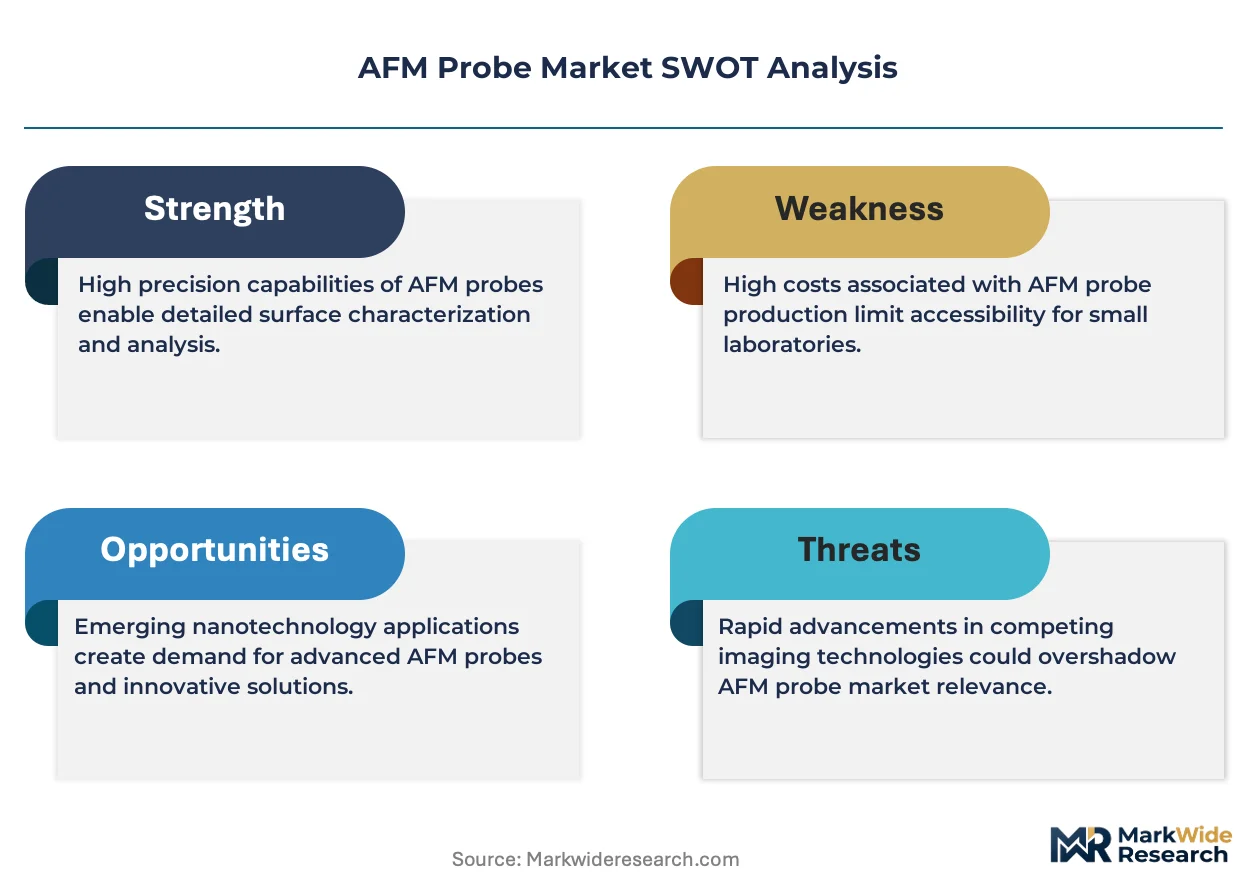
EU REACH substance restrictions on perfluorinated compounds is shifting procurement criteria toward fluorine-free coating chemistries in probe manufacturing. Bruker leverages captive silicon nitride growth facilities to secure supply chain continuity for high-frequency tapping probes. NanoWorld AG anchors European demand through Jena-based fabrication and direct academic channel relationships. Team Nanotec GmbH specializes in custom tip geometries for electrochemical scanning applications, differentiating against standardized catalog offerings.
An AFM probe is a micro-fabricated cantilever with an integrated nanoscale tip, typically manufactured from silicon or silicon nitride through photolithographic and etching processes, designed to raster-scan surfaces with sub-nanometer vertical resolution for topography mapping and force spectroscopy. Tapping probes command premium positioning in semiconductor failure analysis workflows where gentle intermittent contact preserves delicate photoresist layers. Non-contact probes represent the fastest-expanding category in ambient-condition biology labs seeking to image live cell membranes without mechanical deformation. Contact probes retain volume dominance in materials science departments performing routine hardness mapping on thin films and coatings.
FDA oversight of nanotechnology-enabled medical devices and EPA reporting obligations under TSCA Section 8(a) shape material safety documentation burdens for probe suppliers serving U.S. biomedical researchers. ISO 80000-1 dimensional metrology standards and IEC nanotechnology terminology frameworks provide cross-border qualification protocols that reduce customer validation cycles. Stakeholders must monitor evolving dual-use export control classifications affecting tip radius specifications before committing to capacity expansion in precision etching equipment.
Market Dynamics
Sub-7nm semiconductor node validation is concentrating metrology procurement among Taiwan and South Korean foundries, compressing probe replacement cycles and elevating specifications for tip radius uniformity.
Growth Catalysts
- EU REACH fluorine restrictions:Manufacturers are reformulating probe coatings to eliminate perfluorinated compounds, creating certified-supplier advantages for early compliant chemistries.
- Live-cell membrane imaging:Ambient-condition biology laboratories are expanding non-contact probe installations to image cellular structures without mechanical deformation artifacts.
- East Asian fabrication clusters:Foundry capital expenditure on process control equipment continues rising in Taiwan and South Korea, pulling high-frequency tapping probe demand.
Market Restraints
- Silicon nitride supply concentration:Captive growth facilities at select manufacturers create dependency risks for high-frequency probe substrates.
- Dual-use export controls:Evolving classifications on sub-10nm tip radius specifications restrict capacity expansion planning for precision etching equipment vendors.
- Photoresist layer fragility:Semiconductor failure analysis workflows demand intermittent-contact modes that limit probe architecture standardization.
Strategic Opportunities
- Electrochemical scanning applications:Custom tip geometries for corrosion studies and battery interface analysis remain underserved by catalog offerings.
- ISO 80000-1 harmonization:Cross-border dimensional metrology standards reduce customer validation cycles for qualified probe suppliers.
- Biomedical device oversight:FDA nanotechnology-enabled device pathways create documentation service opportunities for probe vendors serving U.S. researchers.
Industry Challenges
- Precision etching technician scarcity:Sub-nanometer tip fabrication requires specialized cleanroom expertise concentrated among legacy equipment operators.
- TSCA Section 8(a) reporting timelines:EPA material safety documentation burdens extend sales cycles for consumable probe lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AFM Probe Market |
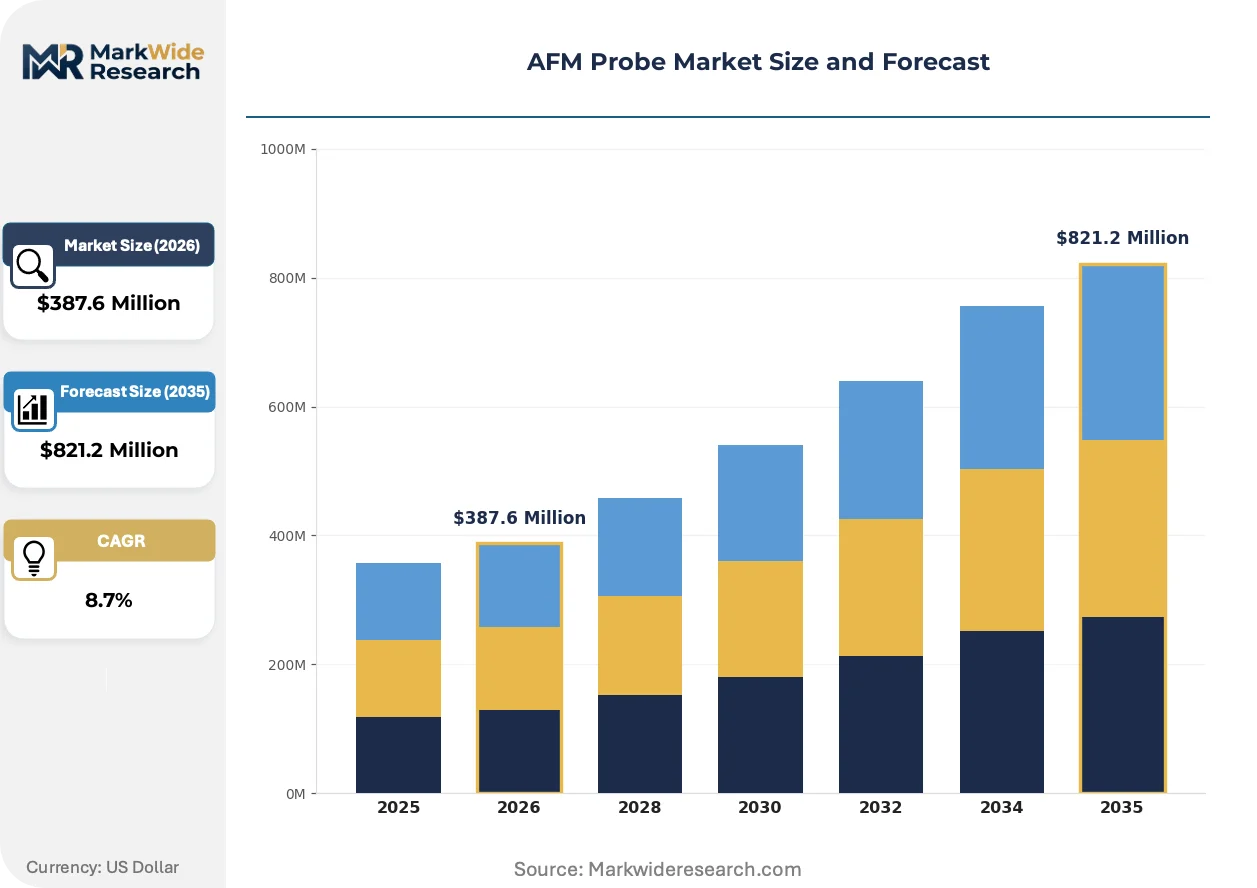
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Probes, Non-Contact Probes, Tapping Probes, Specialized Probes End User: Research Laboratories, Universities, Industrial Firms, Government Agencies Application: Surface Imaging, Mechanical Characterization, Nano-manipulation, Electrical Measurements Technology: Optical Techniques, Magnetic Techniques, Mechanical Techniques, Hybrid Techniques |
| Companies Covered | Asylum Research, Team Nanotec GmbH, NanoWorld AG, MikroMasch, NANOSENSORS, Bruker, AppNano, NaugaNeedles, NT-MDT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AFM Probe Market Emerging Trajectories
Probe manufacturing is converging around fluorine-free coating platforms and captive substrate supply chains as regulatory and supply-side pressures intensify simultaneously.
Carbon nanotube functionalization is unifying tip reinforcement with electrical conductivity enhancement. Semiconductor failure analysis groups are adopting these hybrid probes for concurrent topography and current-mapping workflows. The technology is unifying previously separate mechanical and electrical characterization steps into single-pass inspection protocols.
REACH perfluorinated compound restrictions are forcing coating chemistry transitions across European probe consumption. Manufacturers with Jena-based fabrication and direct academic channel relationships are capturing specification-setting roles. Non-contact probe categories face accelerated reformulation timelines to maintain CE marking eligibility.
Research institutions are consolidating purchases through direct manufacturer relationships rather than distribution intermediaries. Academic channel specialists with on-campus demonstration capabilities are displacing traditional catalog distributors. This pattern concentrates most visibly in German and Swiss materials science departments performing routine thin-film hardness mapping.
AFM Probe Market Segmentation
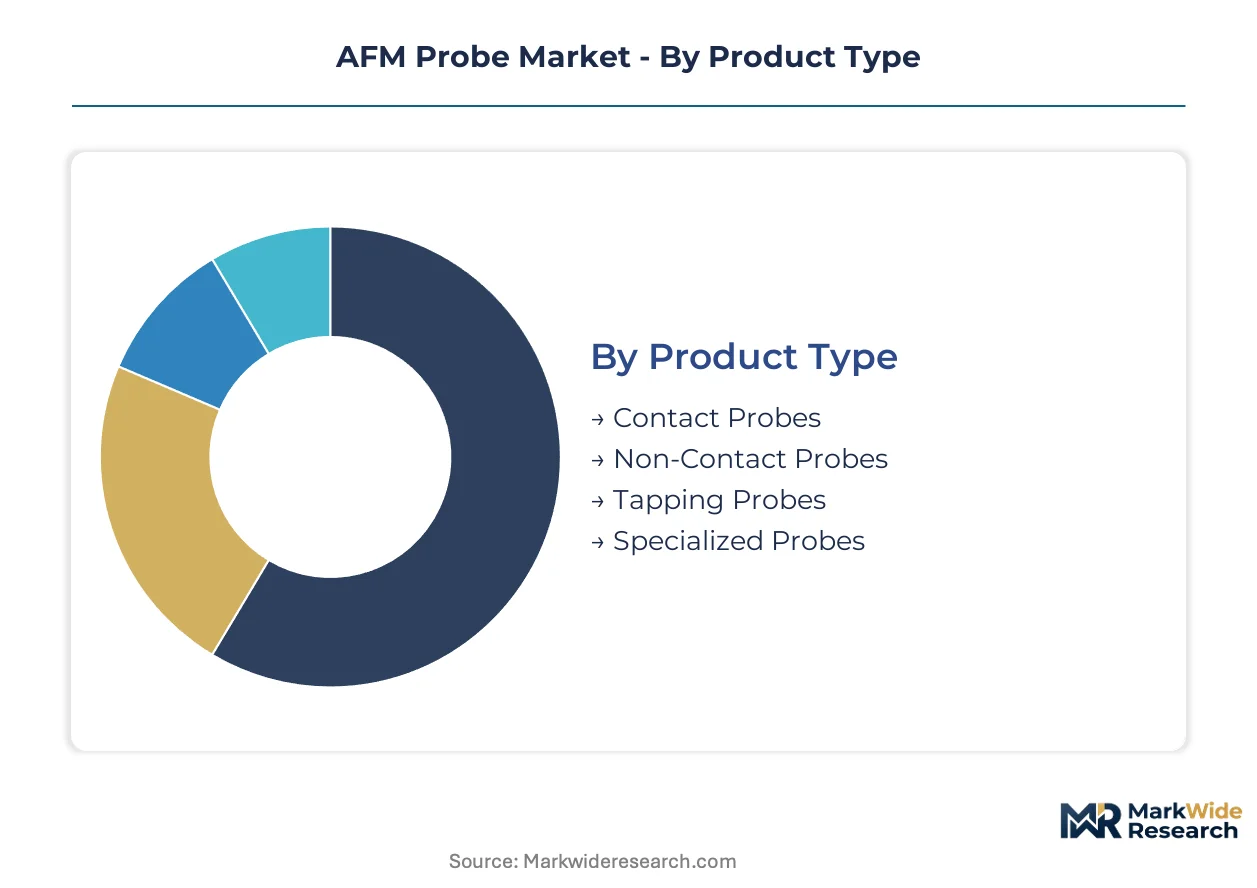
AFM probe procurement patterns diverge sharply by end-use sophistication and capital availability. Research laboratories prioritize tip radius uniformity for reproducible force spectroscopy, while industrial buyers emphasize replacement cycle economics at volume scale.
Product Type:
Capital intensity peaks with tapping probes requiring sub-nanometer tip radius control and proprietary coating chemistries to satisfy EU REACH fluorine restrictions.
- Tapping Probes:These cantilevers oscillate near resonance frequency to enable intermittent surface contact. Semiconductor failure analysis workflows in Taiwan and South Korean foundries specify these for delicate photoresist layer preservation, compressing replacement cycles as sub-7nm node validation intensifies.
- Non-Contact Probes:Operating in attractive force regimes without mechanical surface engagement, these probes serve ambient-condition biology laboratories imaging live cell membranes. Demand concentrates where FDA nanotechnology device oversight shapes documentation requirements for U.S. biomedical researchers.
- Contact Probes:Direct mechanical engagement probes for routine hardness mapping.
- Specialized Probes:Custom geometries for electrochemical and multi-modal applications.
Most installed capacity flows through contact probes for materials science education. Expansion is steepest in tapping probes pulled by East Asian fabrication cluster procurement.
End User:
Volume concentration sits with universities performing routine thin-film characterization, while margin capture favors industrial firms consolidating metrology supplier relationships.
- Industrial Firms:Semiconductor manufacturers and battery interface researchers drive specification-setting for tip uniformity. Taiwan and South Korean foundries anchor procurement for process control equipment, with captive silicon nitride supply chains creating vendor lock-in effects.
- Research Laboratories:National and institutional facilities performing corrosion studies and nano-manipulation. EPA TSCA Section 8(a) reporting obligations extend sales cycles for consumable probe lines serving U.S. facilities.
- Universities:Materials science departments consolidating purchases through direct manufacturer relationships.
- Government Agencies:Standards bodies and defense research facilities with dual-use export control compliance requirements.
Industrial firms command pricing premiums for validated supply continuity. Universities represent the highest-volume procurement channel through academic discount structures.
Application:
Technical complexity escalates from topography mapping through concurrent mechanical-electrical characterization, with hybrid workflows demanding multi-functional tip architectures.
- Surface Imaging:The foundational AFM application requiring precise z-axis piezoelectric control. Biology laboratories in German and Swiss materials science departments specify non-contact modes for live-cell membrane studies without mechanical deformation artifacts.
- Mechanical Characterization:Force spectroscopy and hardness mapping on thin films. ISO 80000-1 dimensional metrology standards reduce customer validation cycles for qualified probe suppliers in this category.
- Nano-manipulation:Tip-based positioning of individual molecules and nanostructures.
- Electrical Measurements:Current-mapping and conductive AFM for battery interface analysis.
Surface imaging dominates installed base by probe count. Electrical measurements are gaining share fastest through carbon nanotube functionalization unifying mechanical and conductive tip properties.
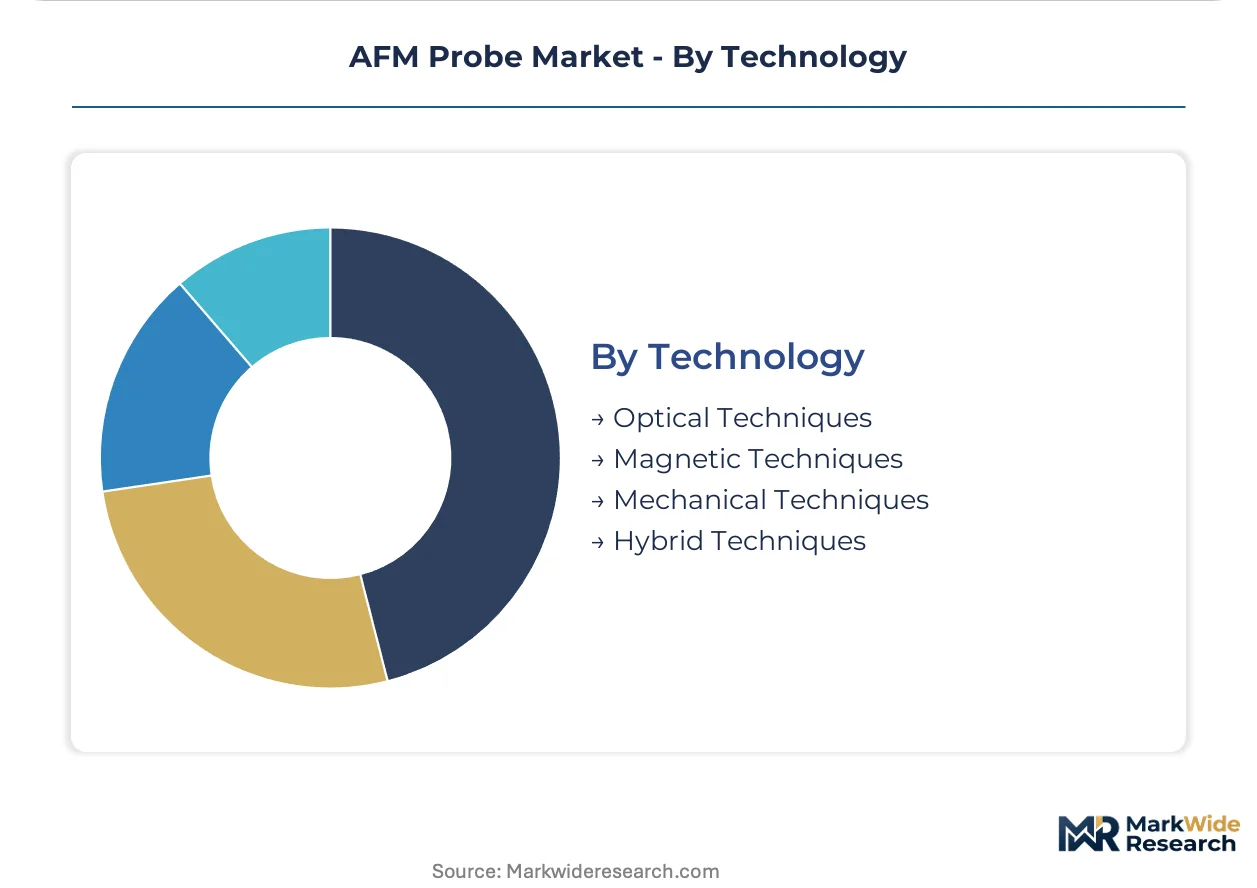
Technology:
Detection modality selection determines cantilever material and optical path requirements, with hybrid architectures commanding manufacturing complexity premiums.
- Mechanical Techniques:Piezoelectric actuation and optical lever detection constitute the dominant architecture. Jena-based fabrication facilities anchor European supply for these standardized cantilever designs.
- Hybrid Techniques:Combining optical, magnetic, and mechanical detection for multi-modal characterization. Semiconductor failure analysis groups adopt these for single-pass inspection protocols integrating topography and current-mapping.
- Optical Techniques:Interferometric detection methods for specialized metrology.
- Magnetic Techniques:MFM and related modes for magnetic domain imaging.
Mechanical techniques carry the broadest installed base. Hybrid techniques show the steepest capability expansion as probe manufacturers integrate electrical conductivity into reinforced tip platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AFM probe manufacturing originated in German precision optics clusters during the 1980s, with Jena-based fabrication facilities establishing early standards for silicon nitride cantilever production. The industry subsequently dispersed to East Asian semiconductor hubs and North American research corridors.
United States
Biomedical researchers at Boston and San Francisco Bay Area institutions drive non-contact probe demand for live-cell membrane studies. FDA oversight of nanotechnology-enabled medical devices shapes material safety documentation requirements for probe suppliers. EPA reporting obligations under TSCA Section 8(a) extend sales cycles for consumable lines serving national laboratory facilities.
Germany
Materials science departments at RWTH Aachen and Karlsruhe Institute of Technology consolidate purchases through direct manufacturer relationships. ECHA REACH perfluorinated compound restrictions force coating chemistry transitions across European probe consumption. Jena-based fabrication anchors continental supply for standardized cantilever designs serving academic channels.
South Korea
Foundry capital expenditure on process control equipment pulls high-frequency tapping probe demand from Samsung and SK hynix facilities. MFDS medical device regulations create parallel compliance pathways for biomedical research probe lines. Suwon and Pyeongtaek fabrication clusters compress replacement cycles as sub-7nm node validation intensifies.
Taiwan
TSMC and United Microelectronics Corporation expand metrology budgets for sub-7nm node inspection, concentrating procurement among local probe distributors. The island's dual-use export control classifications on sub-10nm tip radius specifications restrict capacity expansion planning. Hsinchu Science Park anchors the regional probe consumption cluster.
Japan
Automotive battery interface researchers at Nagoya and Tsukuba facilities specify custom tip geometries for electrochemical scanning applications. METI industrial standards provide cross-border qualification protocols that reduce customer validation cycles. Osaka-based precision equipment vendors supply etching systems to regional probe fabricators.
AFM Probe Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the AFM probe landscape, with captive silicon nitride growth facilities creating vendor lock-in effects at the premium tier. The vendor base stratifies between integrated substrate manufacturers, specialized tip geometry designers, and catalog distributors serving academic channels. Three archetypes dominate: foundry-aligned suppliers with captive material supply, academic channel specialists with on-campus demonstration capabilities, and electrochemical scanning specialists with custom fabrication expertise. Competitive moves concentrate on strategic partnerships with semiconductor equipment vendors and backward integration into coating chemistry formulation.
Among German fabricators, NanoWorld AG exemplifies the academic channel specialist archetype through Jena-based production and direct university relationships. Team Nanotec GmbH occupies a position within the custom geometry tier, serving corrosion and battery interface researchers with non-catalog offerings. Bruker represents the integrated substrate manufacturer archetype, leveraging captive silicon nitride growth facilities to secure supply chain continuity for high-frequency tapping probes.
| Leading Market Players |
|---|
| Asylum Research |
| Team Nanotec GmbH |
| NanoWorld AG |
| MikroMasch |
| NANOSENSORS |
| Bruker |
| AppNano |
| NaugaNeedles |
| NT-MDT |
| Others |
Supply Flow & Price Mechanics
Probe certification tiers for EU REACH fluorine compliance split the market into premium validated supply and commodity catalog offerings, with compliant chemistries commanding 40-60% markups while non-compliant inventory liquidates through academic discount channels. This bifurcation concentrates procurement power among foundry-aligned suppliers with captive coating formulation capabilities, forcing smaller fabricators into distributor dependency or regional niche specialization.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs AFM probe transactions, with premium tiers capturing ISO 80000-1 certification and REACH-compliant coating documentation as price differentiation drivers. Cost compression in standard-grade tapping probes intensifies as Taiwanese foundries consolidate vendor lists and demand volume rebates. Academic buyers exhibit highest price sensitivity, while semiconductor failure analysis groups absorb premium pricing for supply continuity guarantees.
Supply Chain Analysis
Silicon nitride wafer supply rests on German specialty ceramic producers and select Japanese precision material vendors, with secondary sourcing from South Korean chemical conglomerates. Photolithography equipment and sub-nanometer etching systems draw from Dutch and Japanese capital equipment manufacturers. Single-source vulnerability concentrates in sub-10nm tip radius fabrication capability, where legacy cleanroom technician expertise pools among Jena and Osaka-based operators. Distribution runs through direct manufacturer relationships displacing catalog intermediaries in European and North American research corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AFM probe manufacturing rewards geographic arbitrage between REACH-regulated European formulation costs and East Asian foundry procurement scale, with regulatory compliance investments in Germany and Taiwan yielding divergent margin structures.
For Market Incumbents: Anchor supply chain continuity through backward integration into silicon nitride growth facilities, mirroring Bruker's captive substrate model. Defend against emerging electrochemical scanning specialists by locking exclusive tip geometry patents for battery interface analysis. Prioritize certification investment for EU REACH fluorine-free coating platforms to capture specification-setting roles in European academic channels.
For New Entrants and Emerging Players: Electrochemical scanning researchers at automotive battery labs represent an underserved buyer archetype seeking custom tip geometries beyond standardized catalog offerings. Penetrable white space concentrates in corrosion studies and solid-state battery interface characterization, where incumbent response times lag experimental timelines. Go-to-market execution should deploy on-campus demonstration capabilities at German and Swiss materials science departments, displacing traditional distributor relationships through direct technical engagement.
For Investors and Strategic Acquirers: Consolidation pressure builds where captive silicon nitride supply chains create vendor lock-in effects at premium probe tiers, squeezing mid-scale fabricators without substrate control. Long-term viability favors vertically integrated specialists with in-house coating chemistry formulation and precision etching equipment ownership. Acquisition targets should display Jena-based fabrication assets or established direct academic channel relationships. Watch for dual-use export control classification shifts on sub-10nm tip radius specifications as inflection indicators for capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Nitride Substrates | Captive wafer supply secures continuity for high-frequency tapping probes serving TSMC and Samsung validation workflows. |
| REACH-Compliant Coating Chemistry Development | Fluorine-free formulation platforms unlock premium pricing in European academic and industrial procurement channels. |
| Direct Academic Channel Expansion | On-campus demonstration capabilities at RWTH Aachen and Karlsruhe Institute displace traditional catalog distributors. |
| Custom Electrochemical Tip Geometry Fabrication | Non-catalog offerings for battery interface researchers command margin premiums unavailable in standardized probe lines. |
| Dual-Use Export Control Compliance Infrastructure | Sub-10nm tip radius documentation capabilities enable participation in defense-adjacent research facility procurement. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with AFM equipment procurement managers at Taiwan and South Korean foundries, probe manufacturing technical directors, university materials science department heads, and regulatory compliance officers at European nanotechnology suppliers. Secondary validation drew from EPA TSCA Section 8(a) filing databases, ECHA REACH restriction updates, ISO 80000-1 metrology standard revisions, and semiconductor capital expenditure disclosures. Bottom-up probe shipment estimates triangulated against top-down metrology equipment installation data.
Segment-weighting approaches distributed value and volume projections across tapping, non-contact, contact, and specialized probe categories, with further disaggregation by cantilever material, coating chemistry compliance tier, and end-user sophistication level. Modeled dimensions included tip radius specification bands, resonance frequency ranges, and application-specific detection modalities. CAGRs derived from replacement cycle compression rates at sub-7nm semiconductor nodes and ambient-condition biology laboratory expansion trajectories. Forecast inputs incorporated foundry capital expenditure plans and REACH regulatory phase-in timelines.
Underlying measurement precision varies by segment; semiconductor process control applications carry tighter precision than routine materials science education procurement. Forecasts reflect documented assumptions regarding node transition schedules and regulatory enforcement intensity. Probe substrate supply disruptions, dual-use export control reclassifications, and fluorine-free coating formulation delays warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Electrochemistry Meters Market
Analytical Instruments
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market
Analytical Instruments
Digital Moisture Analyzer Market
Analytical Instruments
Trace Chemical Detector Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Atomic Magnetometers Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Air Sampling Equipment Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Battery Analyzer Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market