
 Global Raman Spectroscopy Market | 2026-2036
Global Raman Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Raman Spectroscopy Market Intelligence
Silicon photomultiplier arrays are consolidating as the preferred detector material, displacing traditional charge-coupled devices in next-generation benchtop systems. Thermo Fisher Scientific leverages vertical integration across laser sources and detector modules to sustain margin control. Bruker Corp. anchors its position through specialized ultraviolet Raman configurations for semiconductor defect analysis. HORIBA Ltd. differentiates via deep domain expertise in confocal micro-Raman architectures for materials science laboratories.
Raman spectroscopy measures inelastic light scattering from molecular vibrations, typically employing laser excitation wavelengths from 532 nm to 1064 nm with spectral resolution reaching 1 cm⁻¹; the technique enables non-destructive chemical identification without sample preparation. Portable Raman systems command expanding share in field-deployed pharmaceutical authentication, while micro Raman occupies premium positioning for semiconductor failure analysis. Surface-enhanced Raman spectroscopy represents the fastest-growing technology segment, driven by advances in plasmonic substrate fabrication that amplify weak Raman signals by orders of magnitude.
FDA process analytical technology guidelines and EMA quality-by-design frameworks mandate spectroscopic verification of pharmaceutical raw materials, directly expanding instrument placement in manufacturing suites. EPA methods for environmental contaminant screening and ISO 17025 laboratory accreditation standards further shape procurement specifications and service contract structures. Stakeholders must monitor evolving semiconductor node geometries below 3 nm, where tip-enhanced Raman spectroscopy resolution thresholds determine competitive instrument selection.
Market Dynamics
Portable Raman systems are displacing benchtop configurations in pharmaceutical manufacturing suites as FDA process analytical technology guidelines mandate at-line raw material verification, compressing instrument replacement cycles and reshaping vendor service contract structures.
Growth Catalysts
- EMA Quality-by-Design Frameworks:European pharmaceutical manufacturers must deploy spectroscopic verification systems for raw material identity testing, expanding instrument procurement across Germany, Switzerland, and the Netherlands.
- Plasmonic Substrate Fabrication:Advances in nanostructured metal surfaces amplify weak Raman signals by orders of magnitude, unlocking trace contaminant detection for environmental monitoring agencies.
- Semiconductor Node Compression:Sub-3 nm geometry requirements in Taiwan and South Korea fabs drive demand for tip-enhanced Raman spectroscopy with spatial resolution below 10 nanometers.
Market Restraints
- Laser Source Cost Volatility:Single-frequency solid-state lasers and stabilized diode-pumped systems constitute 35-45% of instrument bill-of-materials, exposing manufacturers to rare-earth element supply fluctuations.
- Detector Supply Concentration:Silicon photomultiplier array production clusters in Japan and Germany create single-source vulnerabilities for next-generation benchtop system vendors.
- Fluorescence Interference Limitations:Biological and polymer samples exhibit strong background emission under visible excitation, restricting Raman applicability in clinical diagnostics without expensive 1064 nm NIR systems.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO's tightening quality standards and expanding API production in Hyderabad and Ahmedabad create first-mover advantages for portable authentication system vendors.
- Battery Material Quality Control:Cathode crystallinity and electrolyte contamination analysis for lithium-ion production lines represents an emerging high-value application segment.
- AI-Assisted Spectral Interpretation:Machine learning algorithms trained on proprietary reference libraries are converging with cloud-connected handheld units, enabling real-time decision support for non-specialist operators.
Industry Challenges
- Spectroscopist Talent Scarcity:Industrial laboratories face recruitment gaps for PhD-level Raman specialists capable of method development for novel material systems.
- ISO 17025 Accreditation Timelines:Contract laboratories require 12-18 month validation cycles for quantitative Raman methods, delaying revenue recognition for instrument vendors.
- Legacy LIMS Integration Complexity:Manufacturing execution systems in regulated industries demand customized data exchange protocols, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Raman Spectroscopy Market |
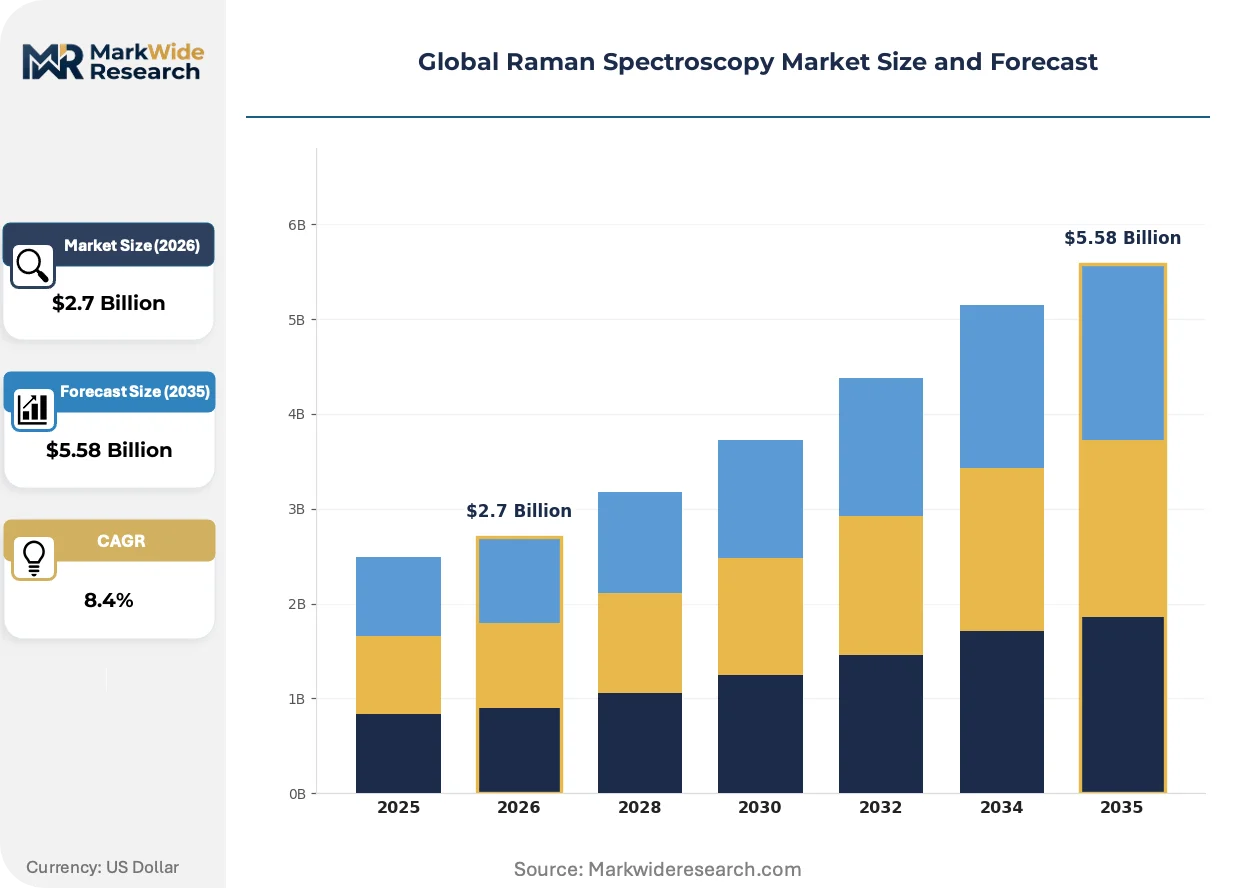
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $5.58 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispersive Raman, Fourier Transform Raman, Micro Raman, Fiber Optic Raman, Portable Raman Technology: Surface-Enhanced Raman Spectroscopy, Resonance Raman Spectroscopy, Tip-Enhanced Raman Spectroscopy, Coherent Anti-Stokes Raman Spectroscopy, Time-Resolved Raman Spectroscopy Application: Chemical Analysis, Pharmaceutical Quality Control, Material Characterization, Forensic Analysis, Environmental Monitoring End User: Academic Institutions, Research Laboratories, Biotechnology Firms, Petrochemicals Companies, Semiconductor Manufacturers |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., Bruker Corp., Mettler Toledo, Renishaw Plc, HORIBA Ltd., PerkinElmer Inc., Anton Paar GmbH, Rigaku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Raman Spectroscopy Market Strategic Shifts & Innovations
Silicon photomultiplier technology is compressing detector form factors while artificial intelligence reshapes spectral interpretation workflows. Regulatory mandates across multiple geographies are synchronizing procurement specifications.
Silicon photomultiplier arrays are integrating into compact handheld architectures, replacing thermoelectrically cooled CCD detectors in portable pharmaceutical authentication systems. Quality control teams at API manufacturing sites in Germany and India are adopting these units for at-line raw material verification. The technology is integrating Raman spectroscopy into warehouse receiving docks previously served by centralized QC laboratories, collapsing testing turnaround from hours to minutes.
REACH authorization requirements for substance identification are compelling European chemical manufacturers to deploy vibrational spectroscopy for supply chain transparency documentation. The regulation mandates analytical verification of SVHC content above 0.1% w/w in articles imported or produced within the EU. Specialty chemical distributors in the Netherlands and Belgium are responding by bundling Raman authentication services with material shipments.
Service unbundling is fragmenting traditional instrument procurement patterns as pharmaceutical manufacturers separate hardware acquisition from method development and validation support. Third-party analytical service providers in the US and Germany are capturing recurring revenue streams previously retained by original equipment vendors. This restructuring concentrates most visibly among mid-sized generic drug manufacturers lacking in-house spectroscopy expertise.
Global Raman Spectroscopy Market Segmentation
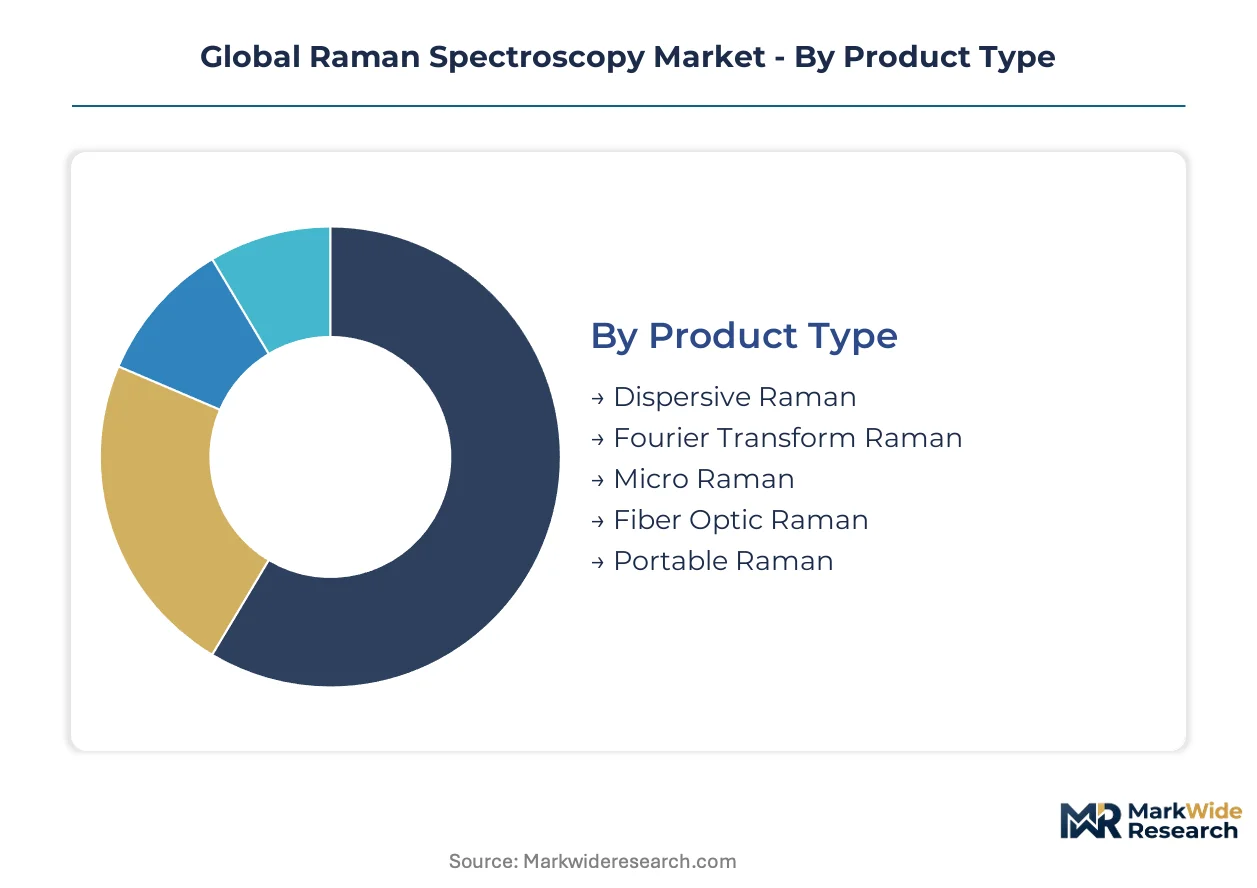
Segmentation in Raman spectroscopy reveals how instrument architectures align with deployment depth—from benchtop laboratory systems to handheld field units. Vendors calibrate feature sets and service models against these distinct operational contexts rather than pursuing one-size-fits-all positioning.
Product Type:
Integration depth separates standalone laboratory platforms from embedded process-line configurations, with hybrid architectures emerging at the boundary.
- Dispersive Raman:Grating-based wavelength separation with silicon photomultiplier or CCD detection dominates pharmaceutical QC laboratories. Thermo Fisher Scientific and HORIBA anchor installed bases in Germany and Switzerland where EMA quality-by-design frameworks mandate at-line deployment.
- Portable Raman:Compact diode laser sources and uncooled detectors enable warehouse dock authentication without climate-controlled infrastructure. Indian API manufacturers in Hyderabad and Ahmedabad are expanding procurement as CDSCO tightens raw material verification requirements.
- Micro Raman:Confocal optical trains deliver sub-micron spatial resolution for semiconductor failure analysis. Taiwan and South Korea fabs below 3 nm node geometries drive specification intensity.
- Fiber Optic Raman:Remote probe configurations separate excitation source from sampling point for hazardous environment monitoring. Petrochemical operators in Rotterdam and Houston deploy these for reactor in-situ analysis.
- Fourier Transform Raman:Interferometer-based detection with 1064 nm excitation eliminates fluorescence interference in polymer and biological matrices. Academic materials science departments maintain legacy procurement despite slower acquisition rates.
Dispersive Raman leads volumes today; Portable Raman is gaining share fastest.
Technology:
Signal enhancement mechanisms determine detection limits and capital intensity, creating tiered access to trace-level applications.
- Surface-Enhanced Raman Spectroscopy:Plasmonic nanostructured substrates amplify Raman signals by 10⁶–10¹⁴ fold, enabling single-molecule detection. Environmental agencies in the Netherlands and Belgium deploy SERS for PFAS trace screening under REACH authorization protocols.
- Tip-Enhanced Raman Spectroscopy:Scanning probe integration achieves sub-10 nm spatial resolution for semiconductor defect mapping at sub-3 nm nodes. Taiwan Semiconductor Manufacturing and Samsung Foundry specify TERS for advanced process development.
- Resonance Raman Spectroscopy:Excitation wavelength matching electronic absorption bands selectively enhances chromophore signals in biological samples. Biotechnology firms in Boston and Basel apply this for protein structural characterization.
- Coherent Anti-Stokes Raman Spectroscopy:Nonlinear four-wave mixing generates blue-shifted signals free from fluorescence background. Combustion research facilities employ CARS for transient species detection in flame environments.
- Time-Resolved Raman Spectroscopy:Pulsed laser gating separates Raman scattering from prompt fluorescence emission. Photochemistry laboratories exploit this for excited-state reaction monitoring.
Surface-Enhanced Raman Spectroscopy commands premium pricing; Tip-Enhanced Raman Spectroscopy shows steepest expansion trajectory.
Application:
Regulatory mandate intensity varies sharply across use cases, with pharmaceutical and environmental compliance creating non-discretionary procurement.
- Pharmaceutical Quality Control:Raw material identity verification and finished product release testing under FDA process analytical technology guidelines. German and Swiss generic manufacturers compress testing turnaround from hours to minutes via portable deployment.
- Environmental Monitoring:Soil, water, and air contaminant screening against EPA methods and ISO 17025 accreditation standards. US environmental laboratories face 12–18 month validation cycles for quantitative Raman methods.
- Material Characterization:Crystallinity, stress, and composition analysis for lithium-ion cathodes and electrolytes. Battery cell producers in Germany and Japan qualify suppliers via Raman-based crystallinity mapping.
- Chemical Analysis:Reaction monitoring and synthetic route verification in specialty chemical manufacturing. REACH SVHC documentation requirements above 0.1% w/w drive analytical verification adoption.
- Forensic Analysis:Explosive, narcotic, and counterfeit material identification for law enforcement. Portable units enable field screening without sample destruction or chain-of-custody complications.
Pharmaceutical Quality Control dominates current procurement; Environmental Monitoring is climbing fastest on regulatory tightening.
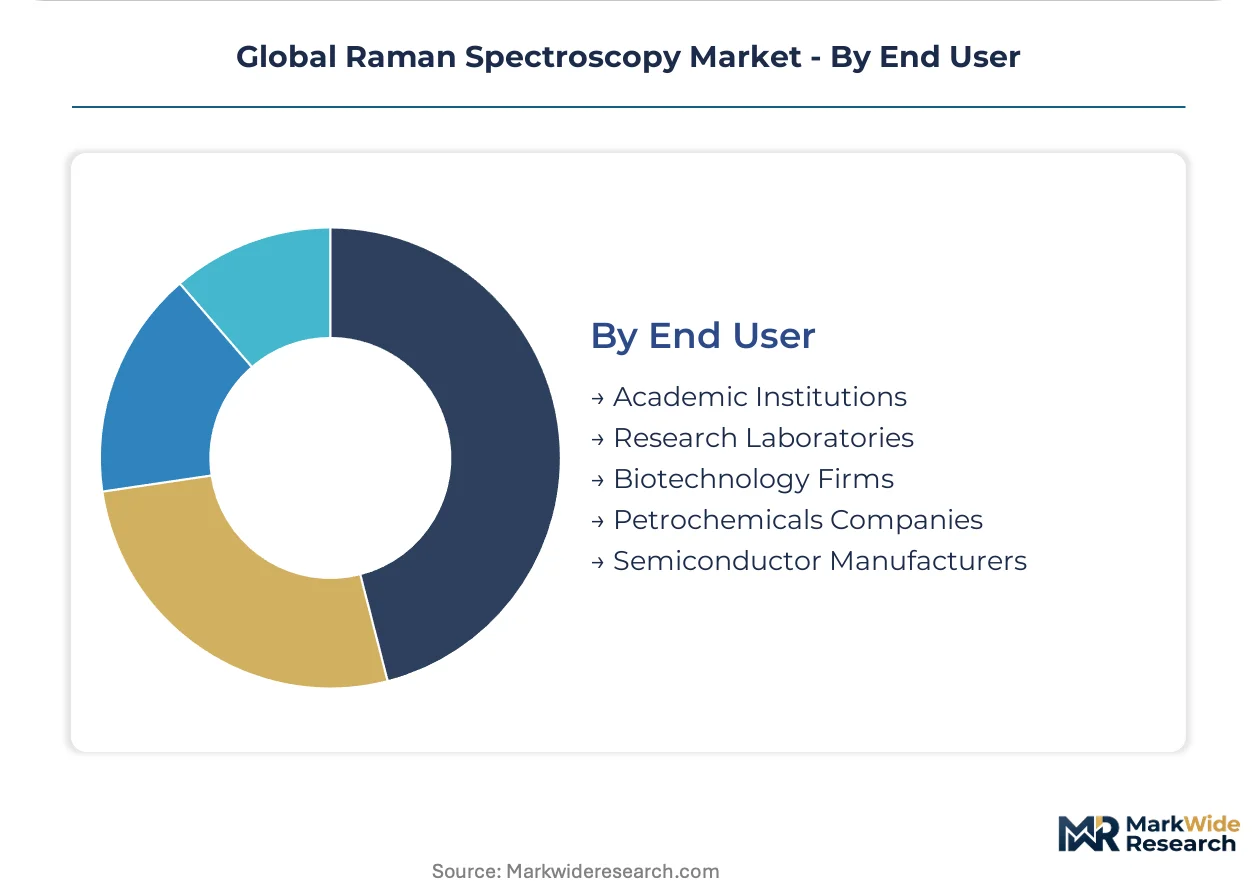
End User:
Capability maturity and capital access separate research-oriented adopters from production-integrated deployers.
- Semiconductor Manufacturers:Sub-3 nm node development and failure analysis demand tip-enhanced and confocal micro-Raman configurations with nanometer spatial resolution. Taiwan and South Korea fabs concentrate advanced instrument procurement.
- Biotechnology Firms:Cell culture media characterization and bioprocess monitoring require 1064 nm excitation systems to suppress fluorescence from complex biological matrices. Basel and Boston clusters anchor demand.
- Research Laboratories:Method development and fundamental spectroscopy studies sustain demand for configurable benchtop platforms with multiple excitation wavelengths. Academic procurement cycles extend 24–36 months.
- Petrochemicals Companies:Refinery process monitoring and catalyst characterization employ fiber optic probes for high-temperature reactor access. Rotterdam and Houston refining complexes maintain centralized analytical facilities.
- Academic Institutions:Undergraduate instruction and interdisciplinary materials research drive entry-level dispersive system placement. Budget constraints favor shared core facility models over individual laboratory instruments.
Semiconductor Manufacturers lead capital deployment; Biotechnology Firms are expanding procurement most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical manufacturing clusters anchor instrument demand as EMA quality-by-design frameworks mandate spectroscopic verification systems. FDA process analytical technology guidelines and CDSCO tightening standards in India compress procurement cycles across three continents.
United States
Environmental monitoring agencies deploy portable Raman units for EPA-method contaminant screening in soil and water matrices. The EPA maintains rigorous accreditation standards that shape laboratory procurement specifications and service contract durations. Boston biotechnology firms anchor demand for 1064 nm excitation systems suppressing fluorescence in complex biological samples.
Germany
Generic drug manufacturers in Baden-Württemberg compress raw material testing turnaround via at-line portable deployment. EMA quality-by-design frameworks mandate spectroscopic identity verification above 0.1% w/w thresholds for pharmaceutical raw materials. Basel-proximate Swiss pharmaceutical clusters indirectly drive cross-border instrument service infrastructure investment.
India
API manufacturers in Hyderabad and Ahmedabad expand portable authentication procurement as CDSCO tightens raw material verification requirements. The country's national pharmaceutical regulator mandates analytical documentation aligning with international good manufacturing practice standards. Gujarat pharmaceutical corridors concentrate first-mover vendor relationships for warehouse dock deployment.
South Korea
Semiconductor fabs below 3 nm node geometries specify tip-enhanced Raman systems achieving sub-10 nanometer spatial resolution. MFDS pharmaceutical quality standards parallel EMA frameworks, expanding dual-use instrument procurement. Seoul capital area manufacturing complexes integrate spectroscopic process analytical technology into continuous manufacturing lines.
Japan
Silicon photomultiplier array production concentrates detector supply for next-generation benchtop systems. METI industrial standards shape instrument calibration protocols exported throughout Asia-Pacific. Tokyo-Yokohama analytical instrument clusters maintain legacy dispersive Raman installed bases alongside emerging portable adoption.
Global Raman Spectroscopy Market Key Industry Players
Global majors compete with regional champions across detector technology and laser source integration. The vendor base stratifies between full-spectrum platform providers and specialized configuration houses. Three archetypes dominate: vertically integrated conglomerates controlling upstream laser and detector supply, domain-specialist firms anchoring premium analytical performance tiers, and regional assembly houses serving price-sensitive emerging markets. Competitive moves concentrate on backward integration into stabilized laser sources and AI-assisted spectral interpretation software licensing.
Within the premium analytical tier, Thermo Fisher Scientific Inc. and HORIBA Ltd. exemplify vertically integrated positioning spanning excitation sources through detector modules. Bruker Corp. occupies a specialized position in ultraviolet configurations for semiconductor defect analysis. Agilent Technologies Inc. and PerkinElmer Inc. represent diversified conglomerate structures leveraging cross-divisional service networks for pharmaceutical customer retention. Anton Paar GmbH anchors European precision instrumentation heritage in density and concentration measurement adjacencies.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Bruker Corp. |
| Mettler Toledo |
| Renishaw Plc |
| HORIBA Ltd. |
| PerkinElmer Inc. |
| Anton Paar GmbH |
| Rigaku Corporation |
| Others |
Cost & Logistics Intelligence
Performance-tier bifurcation between laboratory-grade systems and field-portable units manifests in divergent pricing architectures and supply chain configurations across the Raman spectroscopy market. Premium benchtop configurations with silicon photomultiplier arrays and stabilized laser sources command substantially higher procurement thresholds than uncooled detector handheld units, with the latter sourcing from concentrated Asian electronics manufacturing while the former draws from precision optics clusters in Germany and Japan.
Pricing Analysis
Input-cost pass-through from rare-earth stabilized lasers and precision gratings sustains premium positioning for laboratory systems while portable units face cost compression from commoditized diode sources. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-qualified TERS platforms from pharmaceutical QC workhorses and entry-level educational units. Pricing pressure stems from Indian and Chinese API manufacturers demanding affordable at-line authentication without climate-controlled infrastructure. Generic drug manufacturers in Hyderabad and Ahmedabad exhibit highest price sensitivity; Taiwan semiconductor fabs show least sensitivity given node-shrink imperatives.
Supply Chain Analysis
Silicon photomultiplier array production rests on Japanese and German specialty semiconductor foundries with limited secondary sourcing. Stabilized solid-state laser modules and holographic gratings constitute critical dependencies alongside rare-earth gain media. Single-source vulnerability in detector supply creates procurement risk for next-generation benchtop vendors. Distribution runs through direct OEM sales for semiconductor and pharmaceutical accounts, with third-party analytical service providers capturing mid-sized generic manufacturer demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Raman spectroscopy market functions as a regulatory compounder where FDA process analytical technology guidelines and EMA quality-by-design frameworks create non-discretionary procurement cycles across pharmaceutical manufacturing.
For Market Incumbents: Anticipate displacement pressure from AI-assisted spectral interpretation software bundled with cloud-connected handheld units by deepening captive supply of stabilized laser sources and silicon photomultiplier arrays. Defensive consolidation moves should prioritize backward integration into rare-earth laser gain media and exclusive licensing of proprietary reference libraries for pharmaceutical authentication. Threat emerges from software-first entrants decoupling hardware margins from recurring analytics revenue. For New Entrants and Emerging Players: AI-assisted spectral interpretation algorithms represent the most penetrable wedge for non-specialist operator segments previously served by centralized QC laboratories. White-space targets concentrate in Indian API manufacturing corridors and battery material quality control for lithium-ion cathode crystallinity mapping. Go-to-market positioning should emphasize subscription-based spectral library access reducing upfront capital burden for mid-sized generic manufacturers. For Investors and Strategic Acquirers: Consolidation pressure builds where detector supply concentration and laser source cost volatility squeeze independent instrument vendors lacking upstream integration. Long-term viability favors platforms with recurring revenue from method development and validation services rather than pure hardware plays. Acquisition target archetype: regional service providers with ISO 17025 accreditation infrastructure and established pharmaceutical customer relationships. Signal to watch: CDSCO enforcement intensity in Gujarat pharmaceutical corridors as proxy for emerging market demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Sources | Captive supply of stabilized diode-pumped systems insulates margins from rare-earth price volatility. |
| AI-Assisted Spectral Interpretation Licensing | Machine learning algorithms trained on proprietary pharmaceutical libraries enable real-time decision support for non-specialist operators. |
| ISO 17025 Accreditation Infrastructure | Contract laboratories with validated quantitative methods capture recurring revenue from mid-sized generic manufacturers. |
| Regional Service Provider Acquisition | Established customer relationships in German pharmaceutical clusters accelerate at-line deployment penetration. |
| Plasmonic Substrate Manufacturing Scale-Up | Internal production of SERS nanostructured surfaces unlocks trace contaminant detection for environmental monitoring agencies. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with instrument vendor product managers, pharmaceutical QC directors, semiconductor fab metrology leads, and environmental laboratory accreditation officers alongside secondary validation. Sources included FDA process analytical technology guidance documents, EMA quality-by-design framework publications, EPA method specifications for environmental contaminant screening, and ISO 17025 laboratory accreditation standards. Bottom-up instrument shipment tracking and top-down end-user expenditure analysis provided cross-verification.
Segment-weighting across product type, technology, application, and end-user dimensions anchored the analytical framework over the projection horizon. Dispersive Raman, portable Raman, micro Raman, and fiber optic configurations received distinct growth assumptions based on regulatory mandate intensity and semiconductor node compression trajectories. CAGRs derived from regression analysis against historical instrument procurement cycles and forward-looking regulatory implementation timelines. Industry-specific inputs included CDSCO enforcement patterns in Indian API manufacturing and Taiwan semiconductor fab capital expenditure disclosures.
The model holds under stable regulatory implementation schedules; deviation in FDA inspection intensity or EMA framework revision would shift pharmaceutical procurement timing. Forecasts reflect documented assumptions regarding silicon photomultiplier supply expansion and rare-earth laser source pricing. Semiconductor node transition pace, REACH authorization scope expansion, and AI spectral interpretation accuracy thresholds constitute the small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Flame Ionization Detectors Market
Analytical Instruments
Global TOC Analyzer Market
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
North America Surface Analysis Market
Analytical Instruments
Analytical Ultracentrifuge Systems Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
Kinetic Chromogenic Spectrophotometer Market
Analytical Instruments
EPR (ESR) Spectrometer Market
Analytical Instruments
Europe Surface Analysis Market
Analytical Instruments
Global Atomic Absorption Spectrometer Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Global Ultrapycnometer Market