
 Melt Flow Meter Market | 2026-2036
Melt Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Melt Flow Meter Market Foresight
Metrology technician availability is collapsing across polymer testing labs in North America and Western Europe, forcing equipment buyers toward automated electronic melt flow meters that reduce manual calibration burdens. Dynisco Instruments leverages its capillary rheometry heritage to anchor positions in petrochemical sector accounts. ZwickRoell sustains dominance through backward integration into precision temperature control systems for its mechanical units. Göttfert competes on German engineering credibility in research laboratory channels.
A melt flow meter measures the mass flow rate of a thermoplastic polymer through a standardized capillary die under controlled temperature and load conditions, typically reporting results in grams per ten minutes per ASTM D1238 or ISO 1133 protocols. The instrument serves as the primary quality gate for incoming resin verification, batch release decisions, and supplier qualification in polymer supply chains. Electronic product types command premium positioning where multi-zone temperature uniformity and automatic cutting mechanisms justify higher capital outlays against mechanical alternatives. Quality assurance applications generate the steadiest replacement demand, while research and development spending on capillary rheometry technology is accelerating as custom compounders seek viscosity-shear rate data beyond single-point melt index values.
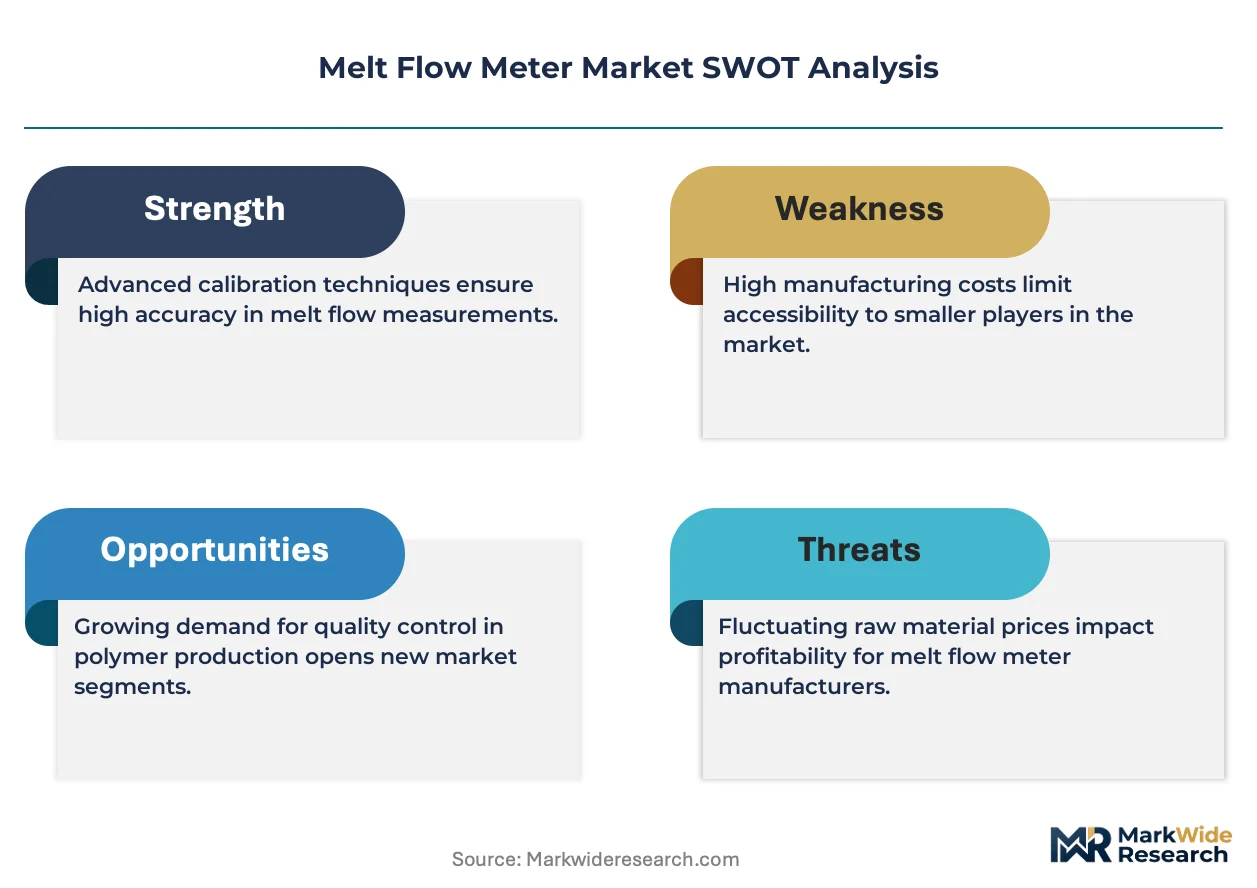
FDA medical device polymer regulations, EPA resin manufacturing emission controls, and China's GB standards for plastic product quality collectively elevate instrument calibration frequency and documentation requirements. ISO 17025 laboratory accreditation mandates across European testing facilities are narrowing vendor qualification lists to suppliers with certified reference material traceability. Stakeholders must weigh capital deployment between portable units for incoming inspection flexibility and fixed systems for production line integration as polymer recycling streams diversify feedstock consistency.
Market Dynamics
ASTM D1238 and ISO 1133 precision mandates are tightening measurement tolerances across polymer testing workflows, compressing acceptable variance windows and forcing equipment replacement cycles in quality assurance laboratories.
Growth Catalysts
- Automotive lightweighting mandates:Germany and Japan are expanding polymer testing requirements for composite structural components, driving melt flow meter deployment in tier-one supplier labs.
- China's GB standards escalation:Plastic product quality regulations in the eastern manufacturing corridor are mandating documented melt index verification for resin imports.
- Capillary rheometry R&D spending:Custom compounders are investing in viscosity-shear rate characterization beyond single-point measurements, pulling demand for advanced electronic units.
Market Restraints
- Metrology technician scarcity:North American and Western European polymer testing labs face collapsing availability of qualified calibration specialists, constraining operational scale.
- Precision temperature control component concentration:Supply of multi-zone heating elements concentrates among German and Japanese thermal subsystem vendors, creating input bottlenecks.
- Mechanical meter substitution resistance:Budget-constrained processors in emerging manufacturing clusters retain legacy manual units despite electronic accuracy advantages.
Strategic Opportunities
- Polymer recycling feedstock diversification:Post-consumer resin streams require incoming inspection flexibility, opening portable melt flow meter demand among compounders.
- ISO 17025 accreditation expansion:European testing facilities are narrowing vendor lists to suppliers with certified reference material traceability, favoring established metrology brands.
- Production line integration:Fixed-system installations for real-time batch release decisions represent underpenetrated deployment in China's petrochemical capacity scaling.
Industry Challenges
- Calibration documentation burden:FDA medical device polymer regulations and EPA resin manufacturing emission controls are elevating instrument qualification timelines.
- Electronic-mechanical integration complexity:Automated cutting mechanisms and multi-zone temperature uniformity require retrofitting legacy lab infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melt Flow Meter Market |
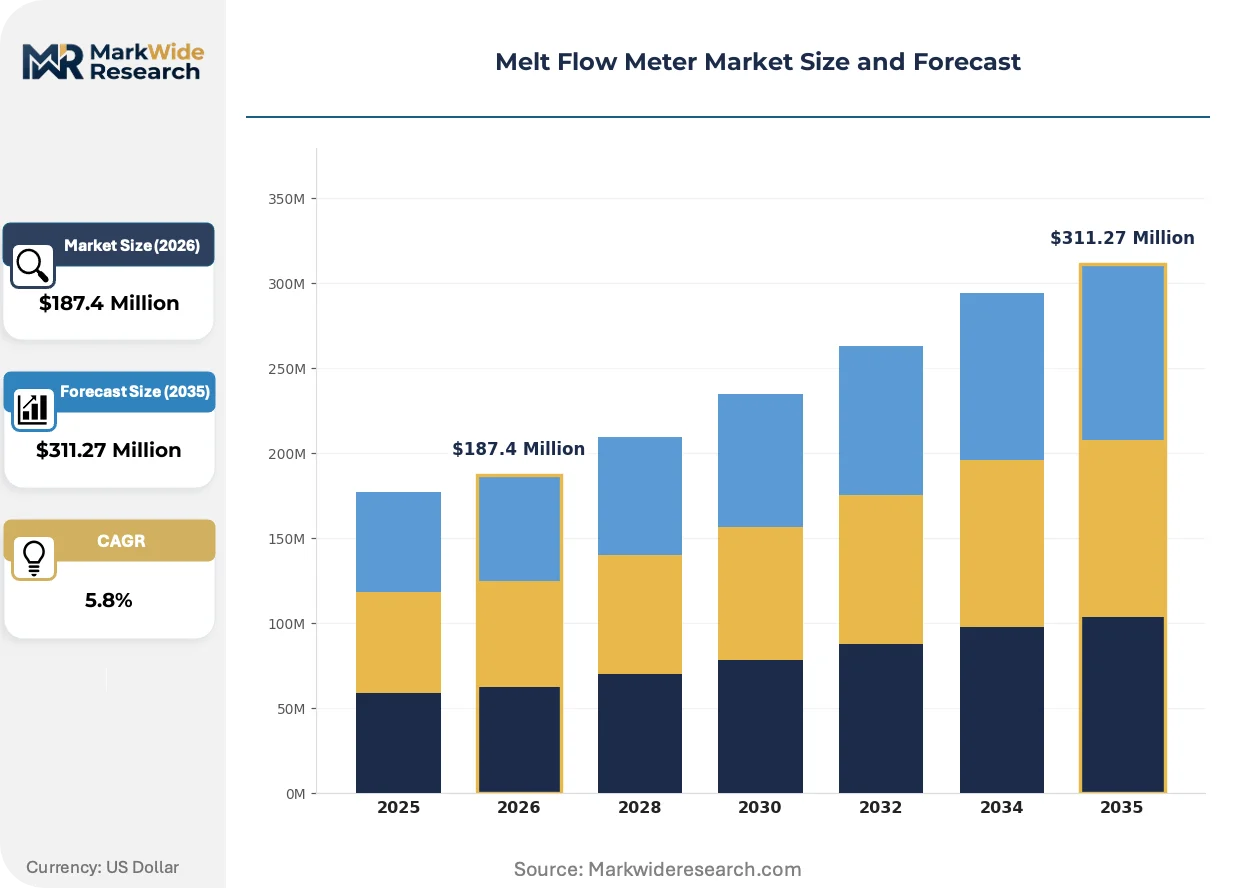
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Mechanical, Portable, Fixed End User: Plastics Industry, Petrochemical Sector, Research Laboratories, Quality Control Application: Polymer Testing, Production Monitoring, Research & Development, Quality Assurance Technology: Capillary, Die, Rheometer, Others |
| Companies Covered | Presto Group, Hanatek Instruments, Qualitest, ZwickRoell, Dynisco Instruments, Instron, Göttfert, Ray-Ran, Tengda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melt Flow Meter Market Shifts & Advancements
Automation architectures and sensor miniaturization are compressing equipment footprints while expanding data capture capabilities, reshaping how polymer testing integrates into production workflows rather than remaining isolated in quality labs.
Portable electronic melt flow meters with integrated load cell weighing and automatic cutting mechanisms are miniaturizing benchtop instrumentation into field-deployable units. Tier-one automotive suppliers in Germany are adopting these compact systems for incoming resin verification at satellite molding facilities. The form factor reduction is enabling distributed testing networks that bypass centralized lab bottlenecks.
REACH substance restrictions and EU Green Deal circularity targets are mandating recycled content thresholds in plastic products. European compounders must verify melt flow properties of post-consumer feedstocks with the same rigor as virgin resins. Research laboratory channels are responding by specifying capillary rheometry systems capable of viscosity profiling across shear rate ranges.
Service contract unbundling is separating hardware acquisition from calibration and certification support. North American polymer processors are purchasing instruments while sourcing ISO 17025 traceability services from third-party metrology providers. The disaggregation is most visible among mid-scale compounders seeking to decouple capital expenditure from recurring compliance costs.
Melt Flow Meter Market Segmentation
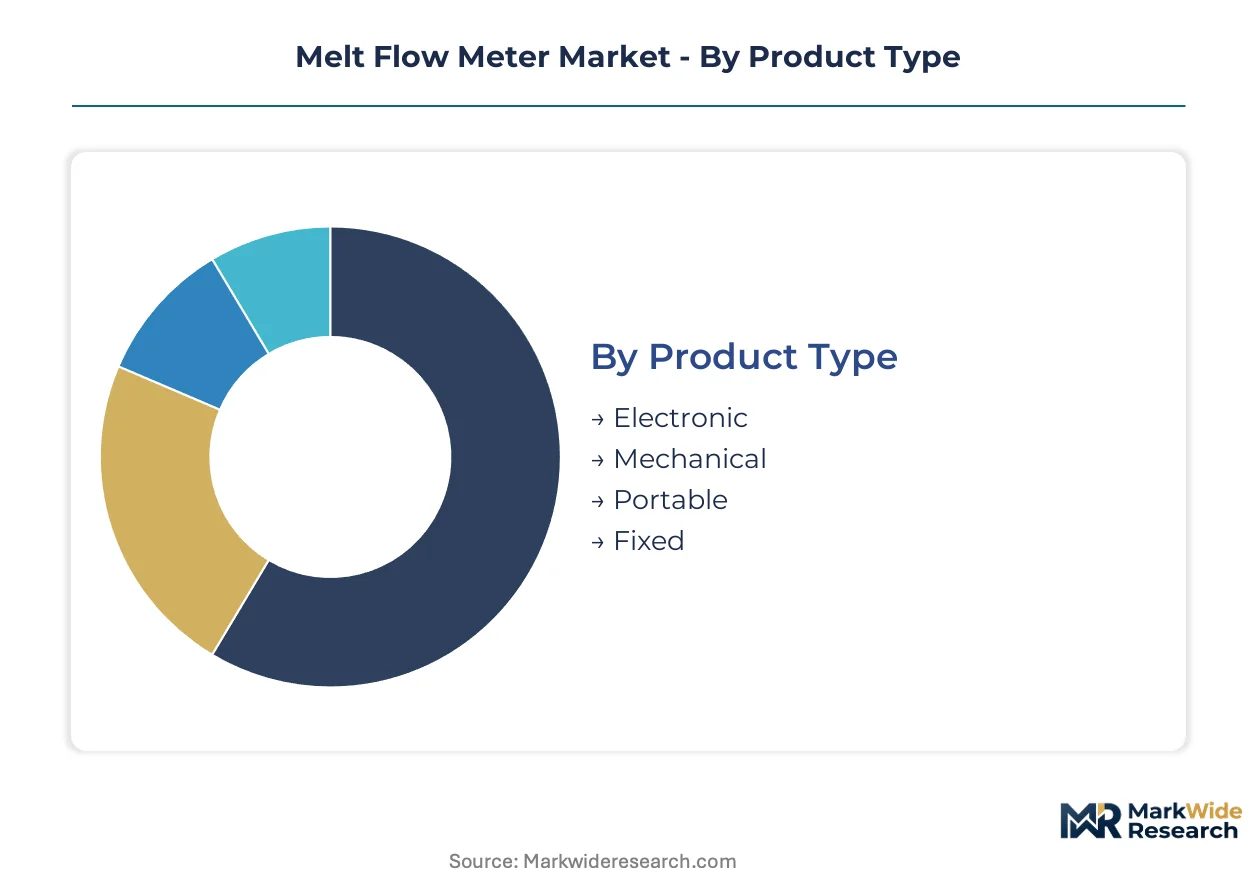
Melt flow meter segmentation reveals how polymer testing requirements fragment across precision tiers, end-use sophistication, and operational deployment models. Equipment buyers face trade-offs between capital efficiency and measurement rigor that vary sharply by segment.
Product Type:
Mechanical units face the most acute substitution pressure as electronic alternatives compress price premiums and automated calibration reduces technician dependency.
- Electronic:Multi-zone temperature control and automatic cutting mechanisms deliver ASTM D1238 and ISO 1133 compliance with minimal operator intervention. Demand concentrates in Germany and Japan where automotive lightweighting programs mandate documented precision for composite structural validation.
- Mechanical:Manual load application and timed cutting rely on operator skill, constraining repeatability in high-throughput environments. Budget-constrained processors in emerging manufacturing clusters retain these units despite accuracy limitations, preserving a residual installed base.
- Portable:Miniaturized load cell architectures enable field-deployable verification of incoming resin streams at satellite molding facilities.
- Fixed:Production line integration supports real-time batch release decisions in China's eastern petrochemical corridor capacity scaling.
Mechanical meters anchor the volume base while portable configurations gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive petrochemical accounts from research laboratories with specialized rheometry requirements.
- Petrochemical Sector:Integrated resin producers require high-throughput verification for batch release documentation. Eastern China manufacturing corridor capacity expansion is pulling fixed-system installations for continuous production monitoring.
- Research Laboratories:Custom compounders demand viscosity-shear rate profiling beyond single-point melt index values. Capillary rheometry R&D spending is accelerating as European facilities respond to REACH substance restrictions and EU Green Deal circularity targets.
- Plastics Industry:Injection molders and extrusion processors prioritize incoming resin verification for supplier qualification.
- Quality Control:Third-party testing facilities face ISO 17025 accreditation mandates that narrow vendor qualification lists.
Plastics industry demand spans the widest price range while research laboratories command the highest specification premiums.
Application:
Volume concentration in quality assurance contrasts with technology evolution in R&D channels.
- Quality Assurance:Steadiest replacement demand stems from FDA medical device polymer regulations and EPA resin manufacturing emission controls elevating calibration frequency. Documentation burdens favor electronic units with automated data logging.
- Research & Development:Custom compounders invest in capillary rheometry systems capable of characterizing post-consumer recycled feedstocks across shear rate ranges. EU circularity targets mandate equivalent verification rigor for virgin and recycled resins.
- Polymer Testing:Incoming resin verification represents the most standardized workflow with established ASTM and ISO protocols.
- Production Monitoring:Real-time batch release decisions require integration with manufacturing execution systems.
Quality assurance generates the most predictable replacement cycles while R&D applications show the steepest technology upgrade intensity.
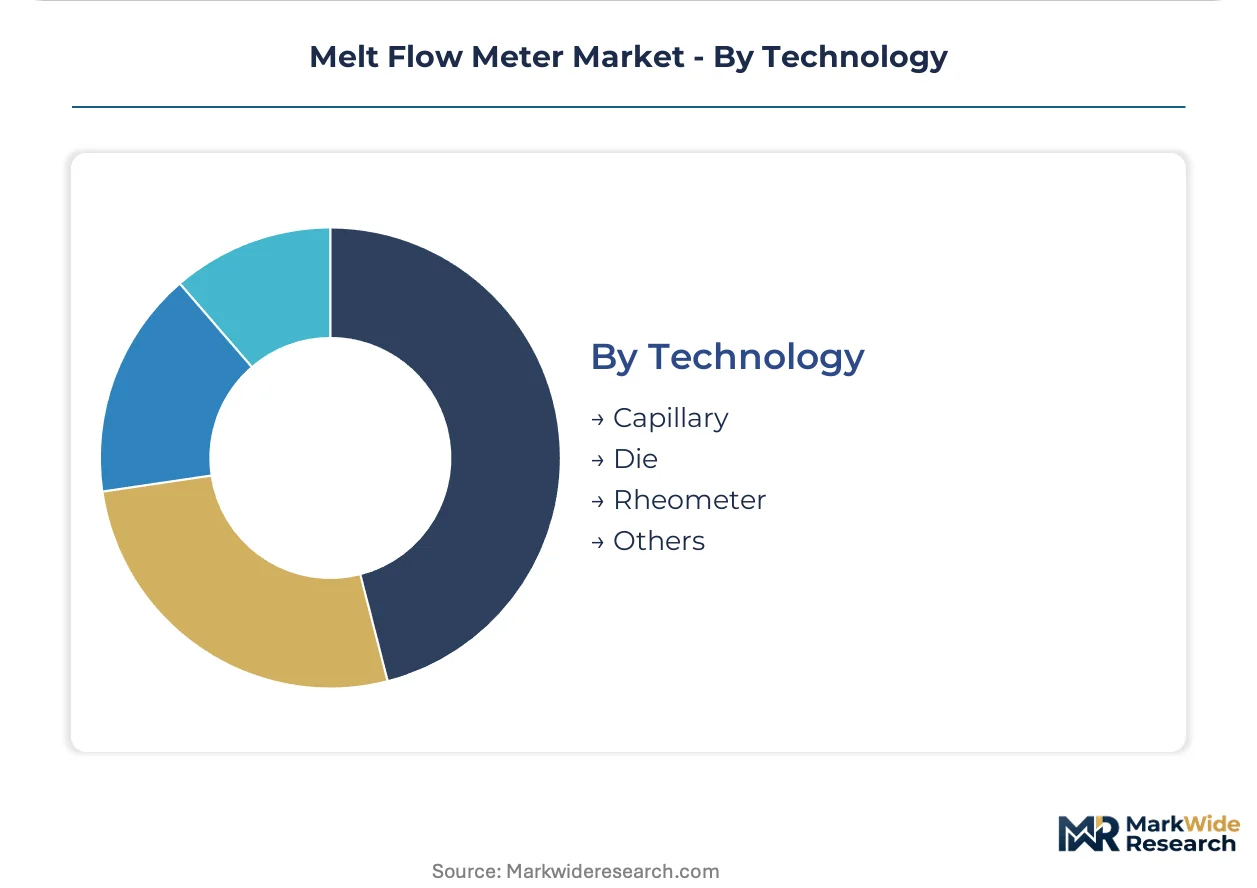
Technology:
Supply concentration in thermal subsystems creates input bottlenecks for precision-dependent architectures.
- Capillary:Standardized die geometry under controlled temperature and load conditions produces melt index values per ASTM D1238 and ISO 1133. German and Japanese thermal subsystem vendors concentrate supply of multi-zone heating elements.
- Rheometer:Extended viscosity-shear rate characterization supports custom compounding beyond single-point measurements. European research channels specify these systems for recycled content verification under circular economy mandates.
- Die:Interchangeable orifice configurations accommodate varying polymer viscosity ranges.
- Others:Emerging sensor architectures and miniaturization approaches compress equipment footprints.
Capillary technology dominates installed base volume while rheometer configurations expand most quickly in premium laboratory channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan favor electronic melt flow meters for automotive lightweighting validation, while China absorbs fixed-system installations for petrochemical scale-up, and the United States prioritizes portable configurations for distributed testing networks.
Germany
Automotive OEMs in Stuttgart and Munich mandate documented melt index precision for composite structural components under KBA certification requirements. REACH substance restrictions and EU Green Deal circularity targets compel recycled content verification. Bavarian research laboratories specify capillary rheometry systems for viscosity-shear rate characterization beyond single-point measurements.
China
Eastern manufacturing corridor petrochemical capacity scaling pulls fixed-system installations for real-time batch release decisions. GB standards for plastic product quality mandate documented melt index verification for resin imports. Yangtze River Delta compounders deploy production-integrated meters as polymer throughput expands.
United States
FDA medical device polymer regulations and EPA resin manufacturing emission controls elevate calibration frequency and documentation burdens. Portable electronic units with automatic cutting mechanisms enable distributed testing networks that bypass centralized lab bottlenecks. Midwest polymer processors favor field-deployable verification for incoming resin streams.
Japan
METI industrial standards and automotive lightweighting programs expand polymer testing requirements for tier-one supplier laboratories. JIS precision mandates compress acceptable measurement variance windows. Nagoya and Osaka industrial clusters deploy electronic units with multi-zone temperature control for minimal operator intervention.
India
BIS polymer quality standards and PLI scheme incentives for petrochemical manufacturing elevate instrument deployment requirements. Maharashtra and Gujarat chemical corridors scale resin production capacity. Mumbai-Pune testing facilities face ISO 17025 accreditation mandates that narrow vendor qualification lists.
Melt Flow Meter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with metrology heritage separating premium positioning from volume-driven alternatives. The upper tier commands positions through backward integration into precision temperature control subsystems and certified reference material traceability. Three archetypes dominate: German engineering-credibility specialists, capillary rheometry heritage players, and Asian scale fabricators. Competitive moves concentrate on service contract unbundling and miniaturization architectures for portable deployment.
Within the heritage-metrology tier, Dynisco Instruments and Göttfert exemplify positioning anchored in decades of capillary rheometry specialization, while ZwickRoell occupies a position representing backward integration into thermal subsystem control. These three entities sit within distinct competitive vectors—Dynisco Instruments exemplifying petrochemical sector anchoring, Göttfert representing research laboratory channel credibility, and ZwickRoell illustrating precision temperature architecture dominance—without their individual strategic actions determining collective market structure.
| Leading Market Players |
|---|
| Presto Group |
| Hanatek Instruments |
| Qualitest |
| ZwickRoell |
| Dynisco Instruments |
| Instron |
| Göttfert |
| Ray-Ran |
| Tengda |
| Others |
Supply & Pricing Matrix
Long-term service contracts with embedded calibration and ISO 17025 traceability provisions lock in multi-year revenue visibility for equipment vendors while insulating buyers from technician scarcity costs. This structure concentrates pricing power among German and Japanese thermal subsystem suppliers whose multi-zone heating elements anchor electronic meter precision.
Pricing Analysis
Project-based hardware sales with unbundled service attachments dominate, though three-tier pricing structure across premium, standard, and economy levels is emerging. Price differentiation hinges on ISO 17025 certification tier and multi-zone temperature uniformity specifications. Cost compression in mechanical meter tiers is intensifying because Asian fabricators scale volume production. Research laboratories show least price sensitivity due to capillary rheometry R&D mandates, while budget-constrained processors in emerging clusters drive economy-tier volume.
Supply Chain Analysis
Port congestion on Hamburg-Shanghai and Yokohama-Long Beach lanes elevates inbound logistics costs for precision thermal subsystems. Multi-zone heating element supply concentrates in Germany and Japan, while load cell architectures source from South Korea and China. Single-source vulnerability in German thermal vendors creates bottleneck risk. Distribution runs through authorized metrology distributors with calibration certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service contract unbundling is expanding recurring-revenue pools faster than hardware sales, with ISO 17025 traceability services commanding premium attach rates. This shift rewards vendors who decouple capital expenditure from compliance cost streams.
For Market Incumbents: Secure backward integration into precision temperature control subsystems to defend against Asian scale fabricators. Anchor petrochemical sector accounts through captive calibration service networks. ISO 17025 accreditation mandates across European testing facilities threaten vendor disqualification for those lacking certified reference material traceability. For New Entrants and Emerging Players: ISO 17025 certification fast-track through third-party metrology partnerships opens laboratory channel access without legacy infrastructure investment. Target portable electronic configurations for polymer recycling compounders facing incoming inspection flexibility requirements. Position on miniaturized load cell architectures as field-deployable verification demand accelerates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with unbundled calibration and certification service layers. Five-to-ten year viability favors entities with thermal subsystem control and established metrology heritage. Monitor capillary rheometry R&D spending intensity at European custom compounders as inflection signal for premium laboratory channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Subsystems | Göttfert and ZwickRoell leverage in-house multi-zone heating element production to control precision architecture supply. |
| Service Contract Unbundling | North American processors decouple hardware acquisition from ISO 17025 traceability services to manage compliance costs. |
| Portable Configuration Miniaturization | Compact load cell architectures enable distributed testing networks bypassing centralized laboratory bottlenecks. |
| Capillary Rheometry R&D Expansion | European compounders invest beyond single-point melt index to verify recycled feedstock viscosity-shear rate profiles. |
| ISO 17025 Accreditation Investment | Third-party testing facilities narrow vendor lists to suppliers with certified reference material traceability. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with polymer testing lab managers, metrology technicians, petrochemical procurement leads, and aftermarket service heads; and secondary validation through ASTM D1238 and ISO 1133 standard documentation, SEC filings of listed instrumentation firms, customs trade data on thermal subsystem imports, and ISO 17025 laboratory accreditation registries. Bottom-up equipment deployment estimates triangulated against top-down resin production capacity figures.
Across the analysis window, forecasts model product type segmentation by precision tier, end user stratification by capital intensity, application splits between quality assurance and R&D channels, and technology differentiation between capillary and rheometer architectures. CAGRs derive from polymer throughput expansion in China's eastern corridor, automotive lightweighting program mandates in Germany and Japan, and technician scarcity-driven automation substitution rates.
Underlying assumptions cover sustained ASTM D1238 and ISO 1133 precision mandate tightening, with deviation risk concentrated in metrology technician availability collapse and thermal subsystem supply bottlenecks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Kinetic Chromogenic Spectrophotometer Market
Analytical Instruments
Battery Analyzer Market
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
Flame Photometer Market
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
Boron Analyzer Market
Analytical Instruments
Flashpoint Analyzer Market
Analytical Instruments
Spectroscopy Software Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Global PH Electrochemical Electrodes Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market
Analytical Instruments
Process Analytical Instrumentation Market
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market