
 Gas Analyzer Market | 2026-2036
Gas Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Analyzer Market Intelligence
The direct sales channel for process instrumentation is fragmenting as OEMs build digital marketplaces and regional service partnerships. Emerson Electric Co. leverages its Plantweb digital ecosystem to anchor long-term service contracts with downstream refiners. Honeywell International Inc. competes through integrated control systems that bundle analyzers with distributed control platforms. ABB Ltd differentiates via laser-based tunable diode analyzer technology for natural gas custody transfer.
A gas analyzer measures the concentration of specific gases within a mixture using detection principles such as nondispersive infrared absorption with resolution down to parts-per-billion levels, enabling real-time process control and regulatory compliance. Fixed-installation analyzers dominate capital expenditure in petrochemical and power generation facilities where continuous stack monitoring is mandatory. Portable units are expanding fastest among environmental contractors performing fugitive emission surveys at refineries and landfill sites. Mass spectrometry technology commands premium positioning in research labs and semiconductor fabrication due to multi-species detection capability and trace-level sensitivity.
The EPA enforces Continuous Emission Monitoring Systems rules under the Clean Air Act that mandate analyzer accuracy and calibration protocols for utilities and chemical producers. The EU Green Deal and F-Gas Regulation are phasing down hydrofluorocarbon use, compelling industrial operators to install leak detection analyzers for fluorinated gas containment. Stakeholders must weigh technology migration paths as electrochemical sensors face displacement by optical methods in applications demanding longer calibration intervals and reduced consumable costs.
Market Dynamics
The migration from electrochemical to optical sensing architectures is compressing calibration cycles and consumable spend, forcing analyzer vendors to restructure service revenue models around predictive maintenance platforms rather than replacement part sales.
Growth Catalysts
- EPA Continuous Emission Monitoring Systems:Stack monitoring mandates for utilities and chemical producers sustain capital deployment in fixed-installation analyzers with certified accuracy protocols.
- EU F-Gas Regulation phase-down:Industrial operators face containment requirements for hydrofluorocarbons, accelerating leak detection analyzer procurement across refrigeration and semiconductor fabrication facilities.
- Natural gas custody transfer:Pipeline operators in Qatar, Norway, and the United States deploy laser-based tunable diode analyzers for BTU measurement precision at fiscal metering points.
Market Restraints
- Optical component supply concentration:German and Japanese laser diode suppliers control critical tunable sources, creating single-source vulnerability for analyzer OEMs.
- Mass spectrometry cost structure:Vacuum pumps and ion detector subsystems from specialized vendors inflate unit economics, limiting penetration outside research and semiconductor verticals.
- Electrochemical sensor obsolescence risk:Existing installed bases face stranded asset exposure as optical methods extend calibration intervals from months to years.
Strategic Opportunities
- India industrial air quality mandates:Central Pollution Control Board enforcement gaps create first-mover positioning for portable analyzer vendors serving environmental contractors.
- Hydrogen economy infrastructure:Purity verification requirements at electrolyzer and fueling station installations open greenfield demand for thermal conductivity and cavity ring-down analyzers.
- Digital marketplace channel:OEM direct platforms with remote diagnostics capability displace traditional distributor networks for standard analyzer configurations.
Industry Challenges
- Spectroscopy engineering talent scarcity:Universities produce insufficient graduates in laser physics and chemometric algorithm development, constraining R&D throughput for next-generation platforms.
- IEC 61508 functional safety certification:Safety instrumented system integration for process analyzers extends validation timelines and engineering overhead.
- Legacy DCS integration complexity:Analyzer data historians must map to proprietary protocols from decades-old distributed control systems in brownfield refineries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Analyzer Market |
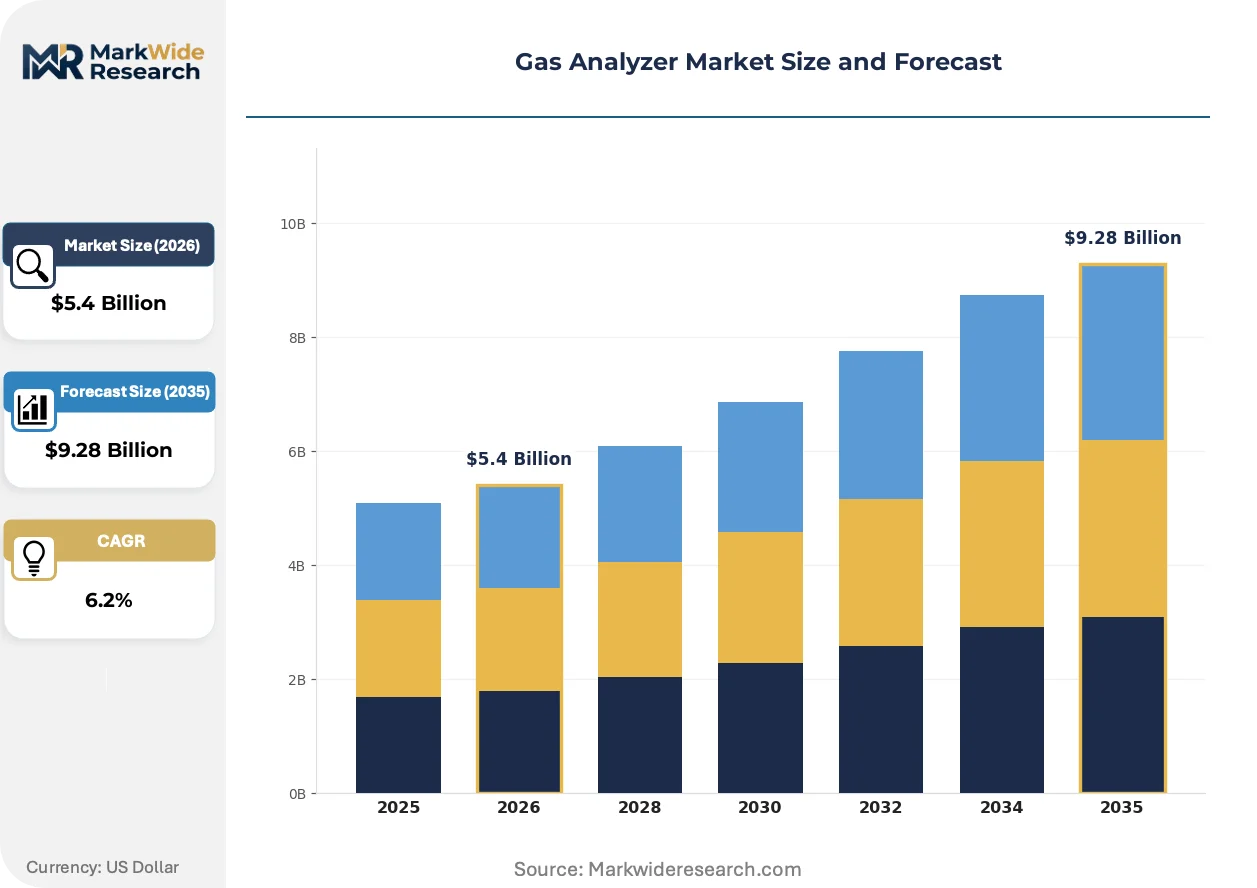
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Benchtop, Online Technology: Infrared, Electrochemical, Optical, Mass Spectrometry End User: Environmental Monitoring, Industrial Sector, Healthcare Facilities, Research Labs Application: Air Quality Testing, Emission Control, Breath Analysis, Combustion Analysis |
| Companies Covered | Emerson Electric Co., Honeywell International Inc., ABB Ltd, Siemens AG, Thermo Fisher Scientific Inc., HORIBA, Ltd, AMETEK, Inc., Mettler-Toledo International Inc., Servomex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Analyzer Market Strategic Shifts & Innovations
Analyzer architectures are converging around solid-state optical engines and edge-computing analytics, compressing the traditional separation between sensing hardware and interpretive software layers.
Tunable diode laser absorption spectroscopy is migrating from natural gas pipeline applications into ammonia and hydrogen purity monitoring for emerging energy transition infrastructure. Chemical producers in the Netherlands and Singapore pilot these platforms for real-time contaminant detection at electrolyzer outlets. The technology is migrating from laboratory bench configurations to field-hardened enclosures with automated zero-span verification.
The EU Green Deal's Industrial Emissions Directive tightens monitoring requirements for volatile organic compounds and methane slip across chemical and waste treatment facilities. Operators must deploy certified analyzers with demonstrated equivalence to reference methods, triggering retrofit cycles in German and Belgian petrochemical corridors. Analyzer vendors respond with pre-certified modular platforms that accelerate site acceptance testing.
Environmental contractors now unbundle analyzer procurement from maintenance contracts, preferring short-term equipment rental with embedded calibration services for episodic emission surveys. This consumption-pattern shift pressures traditional capital-sale margins and favors vendors with regional service depot density. The model is most visible in Texas and California, where third-party leak detection specialists serve oilfield and landfill operators under regulatory inspection schedules.
Gas Analyzer Market Segmentation
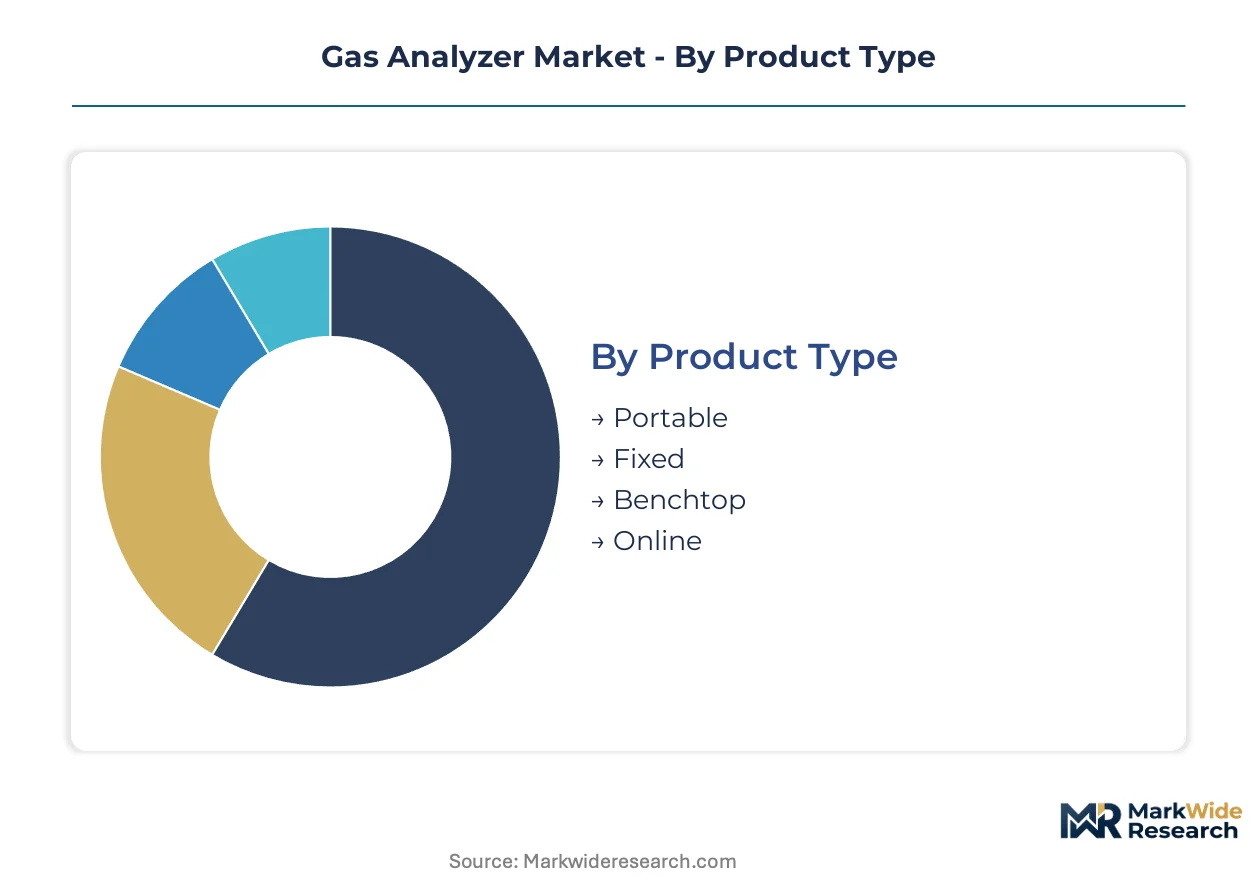
Analyzer segmentation determines service contract structures and calibration revenue streams. Vendors configure aftermarket programs differently across product tiers, with fixed installations demanding continuous technical support while portable units shift toward rental-based service models.
Product Type:
After-sales-service intensity varies sharply across installation permanence, with fixed analyzers locking in decade-long maintenance agreements and portable units operating on episodic calibration schedules.
- Fixed:Permanently installed units integrate with plant distributed control systems for continuous stack monitoring and process loop feedback. Petrochemical complexes in Texas and Rotterdam deploy these for EPA and EU Industrial Emissions Directive compliance, with service contracts typically spanning 10-15 years.
- Portable:Handheld or transportable devices enable fugitive emission surveys and spot-check verification at multiple sites. Environmental contractors across California and Alberta favor these for regulatory inspection schedules, driving rental-model adoption over capital purchase.
- Benchtop:Laboratory-grade instruments with higher precision for sample analysis in centralized facilities.
- Online:Real-time connected analyzers streaming data directly to cloud-based monitoring platforms.
By volume, Portable leads due to contractor fleet expansion. By growth pace, Online is ahead as digital marketplace channels displace traditional distribution.
Technology:
Component cost tiers separate premium optical platforms from legacy electrochemical systems, with laser-based architectures commanding 3-4x unit economics and correspondingly higher margin service attach rates.
- Optical:Tunable diode laser and cavity ring-down spectroscopy platforms deliver parts-per-billion resolution with multi-year calibration intervals. Pipeline operators in Qatar and Norway deploy these for natural gas custody transfer, displacing electrochemical methods in fiscal metering applications.
- Mass Spectrometry:Vacuum-based multi-species detection with trace-level sensitivity for semiconductor fabrication and research laboratories. The subsystem concentration among German and Japanese vacuum pump suppliers constrains OEM margin expansion despite premium positioning.
- Infrared:Nondispersive absorption systems for standard combustion and emission monitoring applications.
- Electrochemical:Sensor-based detection facing obsolescence pressure as optical methods extend maintenance cycles and reduce consumable spend.
By installed base, Electrochemical still dominates. By replacement velocity, Optical is climbing the fastest as calibration interval advantages compound.
End User:
Customer procurement maturity shapes analyzer specification requirements, with industrial operators demanding SIL-certified safety integration and environmental contractors prioritizing fleet standardization.
- Industrial Sector:Petrochemical, power generation, and refining facilities require continuous monitoring for process control and regulatory compliance. German and Belgian chemical corridors are retrofitting under tightened EU Green Deal mandates, triggering certified analyzer procurement with demonstrated reference method equivalence.
- Environmental Monitoring:Regulatory agencies and third-party contractors perform ambient air and stack testing. India's Central Pollution Control Board enforcement gaps create positioning opportunities for portable analyzer vendors serving inspection contractors in Delhi and Mumbai industrial zones.
- Healthcare Facilities:Anesthesia monitoring and respiratory gas analysis in surgical and critical care settings.
- Research Labs:Multi-species detection for academic and government research programs.
By capital deployment, Industrial Sector leads. By expansion trajectory, Environmental Monitoring is gaining share fastest as regulatory inspection outsourcing accelerates.
Application:
Application-specific certification requirements fragment vendor positioning, with emission control demanding regulatory pre-approval and breath analysis following medical device pathways.
- Emission Control:Continuous stack monitoring and leak detection for regulatory compliance. The EPA's Continuous Emission Monitoring Systems rules mandate specific accuracy protocols, while the EU F-Gas Regulation phase-down compels hydrofluorocarbon containment analyzer installation across refrigeration and semiconductor facilities.
- Air Quality Testing:Ambient monitoring and indoor environment assessment for regulatory and occupational health purposes.
- Breath Analysis:Medical diagnostic and metabolic monitoring applications in clinical settings.
- Combustion Analysis:Efficiency optimization and emissions tuning for boilers, furnaces, and engines.
By regulatory pull, Emission Control leads. By technology migration, Air Quality Testing is expanding most quickly as optical platforms enable lower-cost distributed sensor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emission mandates and the EU Green Deal are redrawing procurement geography. Industrial air quality enforcement gaps in emerging economies create positioning windows for portable analyzer vendors.
United States
Stack monitoring requirements under EPA Continuous Emission Monitoring Systems sustain fixed-installation demand across utilities and chemical producers. Texas and Louisiana refineries deploy tunable diode laser systems for fiscal metering and leak detection. Environmental contractors in California operate portable analyzer fleets under state-level fugitive emission inspection schedules.
Germany
The EU Industrial Emissions Directive triggers retrofit cycles in chemical corridors along the Rhine. German operators face tightened volatile organic compound monitoring obligations under Green Deal implementation. The Ruhr industrial cluster and Ludwigshafen chemical complex anchor analyzer procurement for certified reference-method equivalence.
China
Industrial air quality mandates from the Ministry of Ecology and Environment tighten across manufacturing belts. Yangtze River Delta petrochemical facilities install continuous emission monitoring to comply with tightening stack standards. Shanghai and Ningbo port zones drive demand for custody-transfer analyzers at LNG receiving terminals.
India
Central Pollution Control Board enforcement gaps in Delhi and Mumbai industrial zones create first-mover positioning for portable vendors. The country's national environmental regulator is expanding ambient monitoring networks under National Clean Air Programme commitments. Gujarat and Maharashtra manufacturing corridors concentrate demand for contractor-deployed emission survey equipment.
Qatar
Natural gas custody transfer applications dominate analyzer deployment at Ras Laffan and Mesaieed industrial cities. Pipeline operators require laser-based BTU measurement precision for fiscal metering at export terminals. The North Field expansion drives greenfield demand for field-hardened optical platforms with automated verification protocols.
Gas Analyzer Market Key Industry Players
On the supply side, the industry is consolidating around integrated automation conglomerates with captive distribution networks. Three strategic archetypes dominate: diversified industrial technology groups bundling analyzers with control systems; specialized optical instrumentation houses with laser spectroscopy depth; and regional service-intensive operators capturing maintenance contract streams. Competitive moves center on predictive maintenance platform rollouts and digital marketplace channel displacement of traditional distribution.
Among diversified industrial technology groups, Emerson Electric Co., Honeywell International Inc., and ABB Ltd exemplify the control-system-anchored archetype. These entities represent positioning built on long-term service contract capture and integrated safety instrumented system offerings. Their geographic footprint and established plant relationships create defensive moats around replacement cycles. Specialists in laser-based measurement occupy a parallel tier, competing on calibration interval extension and consumable cost reduction rather than bundled platform scale.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Honeywell International Inc. |
| ABB Ltd |
| Siemens AG |
| Thermo Fisher Scientific Inc. |
| HORIBA, Ltd |
| AMETEK, Inc. |
| Mettler-Toledo International Inc. |
| Servomex |
| Others |
Cost & Logistics Intelligence
Shanghai's Yangtze River Delta manufacturing cluster anchors tunable diode laser production for custody-transfer analyzers, concentrating optical engine capacity among a handful of German and Japanese component suppliers. This geographic concentration grants upstream vendors significant leverage over downstream OEM pricing, particularly for field-hardened platforms requiring automated verification protocols.
Pricing Analysis
Certification level (IEC 61508 SIL-grade versus standard industrial) creates the primary spread between premium and mid-market analyzer tiers. Three-tier pricing structure across SIL-certified, CE-marked, and economy-level platforms reflects calibration interval guarantees and safety instrumented system integration depth. Pricing pressure stems from electrochemical sensor obsolescence as optical methods compress maintenance revenue streams. Environmental contractors exhibit highest price sensitivity due to rental-model adoption, while pipeline operators in Qatar and Norway absorb premiums for fiscal metering precision.
Supply Chain Analysis
Export controls on tunable laser diodes under dual-use technology regimes constrain component flows from German and Japanese suppliers to analyzer OEMs. Manufacturing concentrates in Germany, Japan, and the United States for vacuum pump subsystems, ion detectors, and solid-state optical engines. Raw material dependencies span indium phosphide wafers, specialized optical coatings, and high-purity ceramic substrates. Single-source vulnerability for tunable sources creates supply chain risk. Distribution runs through OEM direct digital marketplaces displacing traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spectroscopy engineering talent scarcity constrains R&D throughput for next-generation platforms, with universities producing insufficient graduates in laser physics and chemometric algorithm development. This capability gap separates vendors able to field predictive maintenance platforms from those trapped in replacement part revenue models.
For Market Incumbents: Insulate service contract streams by embedding laser-based analyzers with decade-long calibration interval guarantees into Plantweb-style digital ecosystems. Acquire specialized optical instrumentation houses to capture tunable diode laser absorption spectroscopy depth before emerging players consolidate this tier. Defend against portable analyzer rental-model disruption by building regional service depot density in Texas and California environmental contractor corridors. For New Entrants and Emerging Players: India's Central Pollution Control Board enforcement gaps in Delhi and Mumbai industrial zones offer first-mover positioning for portable analyzer vendors. Target environmental inspection contractors with short-term rental offerings bundled with embedded calibration services. Bypass capital-sale margin compression by unbundling procurement from maintenance through episodic emission survey equipment leasing. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core analytical instrumentation divisions. Long-term viability hinges on optical platform migration velocity and predictive maintenance software attach rates. Watch for IEC 61508 certification backlog as inflection signal—vendors with validated safety instrumented system integration command replacement cycle priority in brownfield petrochemical facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Rollout | Remote diagnostics capability locks in decade-long service contracts with downstream refiners. |
| Laser Spectroscopy Capability Acquisition | Tunable diode laser absorption spectroscopy depth displaces electrochemical methods in fiscal metering. |
| Regional Service Depot Expansion | Density in Texas and California captures environmental contractor rental-model demand. |
| Digital Marketplace Channel Development | OEM direct platforms displace traditional distributor networks for standard analyzer configurations. |
| Electrolyzer Purity Verification Partnership | Thermal conductivity and cavity ring-down analyzer deployment at hydrogen fueling stations opens greenfield demand. |
Research Approach
A standing panel of plant engineers, maintenance directors at petrochemical facilities, OEM procurement teams, and aftermarket service heads provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with analyzer specification committees at German chemical corridors and Texas refineries with trade data from customs records, SEC 10-K instrument division disclosures, and EPA Continuous Emission Monitoring Systems certification databases. Bottom-up unit economics triangulated against top-down capital expenditure tracking across the projection horizon.
Scenario-bracketing anchored the analytical framework, modeling technology migration paths across fixed, portable, benchtop, and online product types alongside optical, mass spectrometry, infrared, and electrochemical technology tiers. End-use segmentation captured industrial sector, environmental monitoring, healthcare facilities, and research labs procurement patterns. CAGRs derived from replacement velocity differentials between electrochemical obsolescence and optical platform adoption, calibrated against EU F-Gas Regulation phase-down enforcement intensity and EPA stack monitoring mandate expansion.
Practitioners should monitor IEC 61508 validation timeline extensions and optical component export control tightening for early signals of forecast deviation. Material shifts in EU Green Deal implementation pace or hydrogen economy infrastructure buildout would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Contact Angle Measuring Instrument Market
Analytical Instruments
Battery Analyzer Market
Analytical Instruments
Trace Oxygen Analyzer Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Electron Microscope Sample Preparation Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
Microfluidic Devices Market
Analytical Instruments
Spatial Mass Spectrometry Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Tunable Diode Laser Analyzer Market