
 Portable Gas Analyzer Market | 2026-2036
Portable Gas Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Gas Analyzer Market Analytics
The price-performance gap between laboratory-grade precision and field-deployable commodity units is hardening across the portable gas analyzer landscape. Honeywell International leverages its distributed sensing architecture to dominate high-reliability industrial safety contracts. ABB sustains technology leadership in laser-based spectroscopy for hydrocarbon measurement. Drägerwerk anchors European market presence through specialized electrochemical portfolios for chemical plant environments.
A portable gas analyzer constitutes a self-contained instrument that detects, identifies, and quantifies gaseous constituents using optical, electrochemical, or ionization principles, typically achieving detection thresholds in the parts-per-million to parts-per-billion range for applications spanning combustion optimization and toxic exposure prevention. The device serves industrial and commercial users requiring real-time, location-flexible air quality or process gas characterization without fixed infrastructure dependency. Infrared analyzers occupy mature margin pools in stack emission verification where regulatory compliance creates stable replacement demand. Laser-based analyzers represent the fastest-growing product category as tunable diode absorption spectroscopy displaces extractive sampling methods in upstream oil and gas leak surveys. Wireless communication technology reshapes competitive dynamics by enabling cloud-connected fleet management and predictive calibration scheduling across distributed instrument populations.
EPA emission standards and OSHA permissible exposure limits directly shape product specification requirements and procurement criteria for U.S. end users, while EU F-Gas Regulation and REACH compliance obligations force redesign of sensor materials and calibration gas compositions for European market access. China's MEE air quality enforcement protocols and GB standard harmonization create parallel certification pathways that fragment go-to-market strategies for multinational suppliers. Stakeholders must monitor evolving methane performance standards and sensor material restriction timelines to align R&D roadmaps with compliance-driven replacement cycles.
Market Dynamics
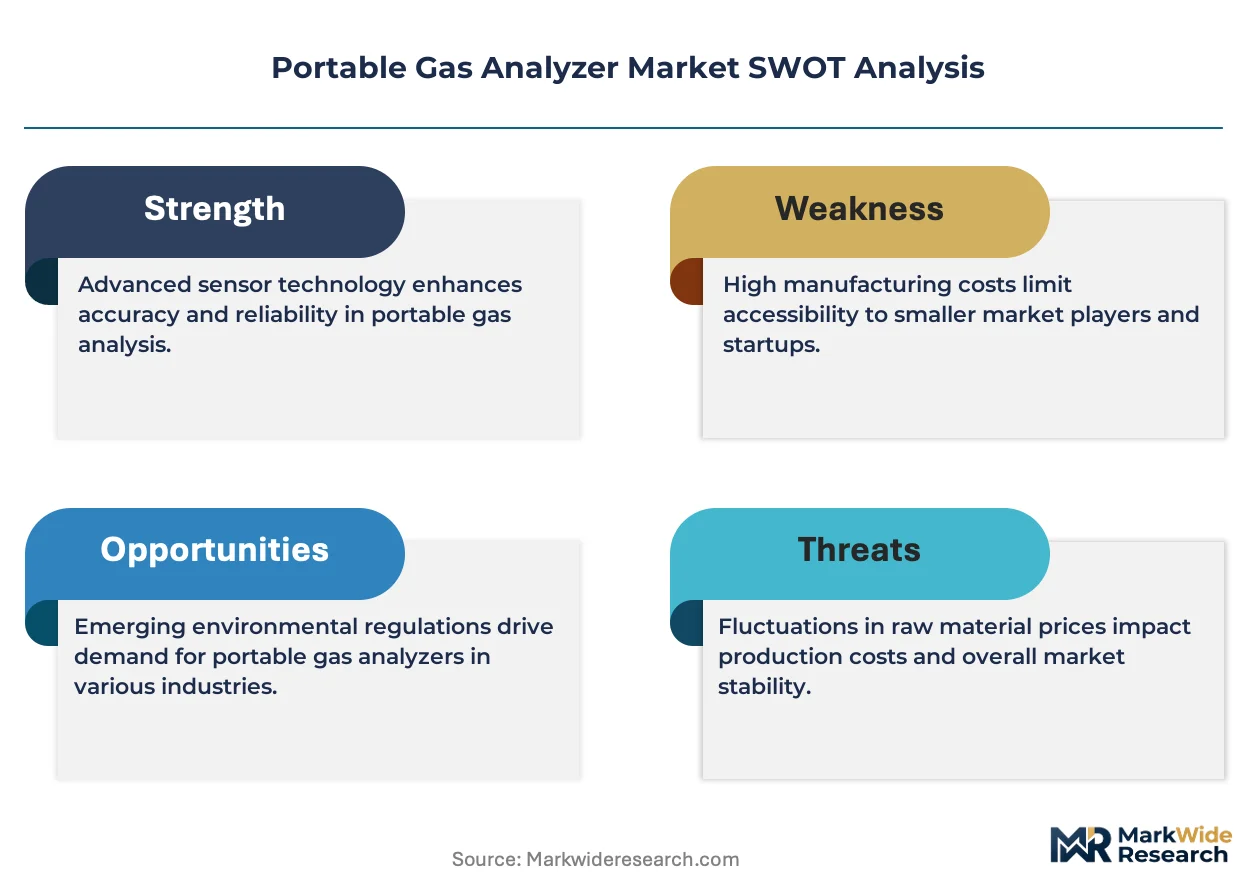
Wireless communication modules and MEMS sensor miniaturization are compressing instrument form factors while expanding deployment flexibility across distributed industrial sites. EPA methane detection mandates and EU F-Gas sensor material restrictions are forcing synchronous hardware redesigns and recertification cycles that favor suppliers with modular platform architectures.
Growth Catalysts
- EPA Quad Oa methane rules:Upstream oil and gas operators must deploy continuous monitoring systems at well pads and compressor stations, accelerating replacement of legacy extractive analyzers with optical instruments.
- Refinery carbon accounting protocols:German and Chinese facilities face Scope 1 emission verification requirements that demand portable validation of fixed-stack CEMS accuracy.
- Tunable diode laser spectroscopy:TDLS miniaturization enables handheld natural gas leak detection with selectivity previously requiring laboratory-grade instrumentation.
Market Restraints
- Helium supply concentration:Mass spectrometer leak detection and carrier gas applications depend on Qatari and U.S. federal helium reserve allocations subject to export quota volatility.
- Electrochemical sensor material restrictions:REACH Annex XVII limits on lead and cadmium compounds force redesign of traditional toxic gas sensors without fully qualified substitutes.
- Calibration gas cylinder logistics:Compressed gas hazmat shipping regulations fragment regional supply chains and inflate total cost of ownership for remote deployments.
Strategic Opportunities
- India's MEE air quality enforcement:Cement and steel plants in Maharashtra and Gujarat require portable stack validation instruments as state pollution control boards tighten inspection protocols.
- Battery thermal runaway detection:Lithium-ion manufacturing and energy storage installations create demand for multi-gas analyzers detecting electrolyte decomposition products.
- 5G-enabled predictive calibration:Cloud-connected instrument fleets allow remote drift monitoring and just-in-time service dispatch, converting capital equipment sales into recurring revenue streams.
Industry Challenges
- Spectroscopy software integration:TDLS and QCL instruments require embedded chemometric models that demand scarce expertise in multivariate calibration algorithm development.
- Dual certification timelines:Simultaneous ATEX/IECEx and SIL 2/3 functional safety approvals extend product launch cycles by 14-18 months for explosion-proof designs.
- Legacy 4-20mA infrastructure:Digital Modbus and wireless HART adoption faces friction from control system architectures predating IIoT protocol standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Gas Analyzer Market |
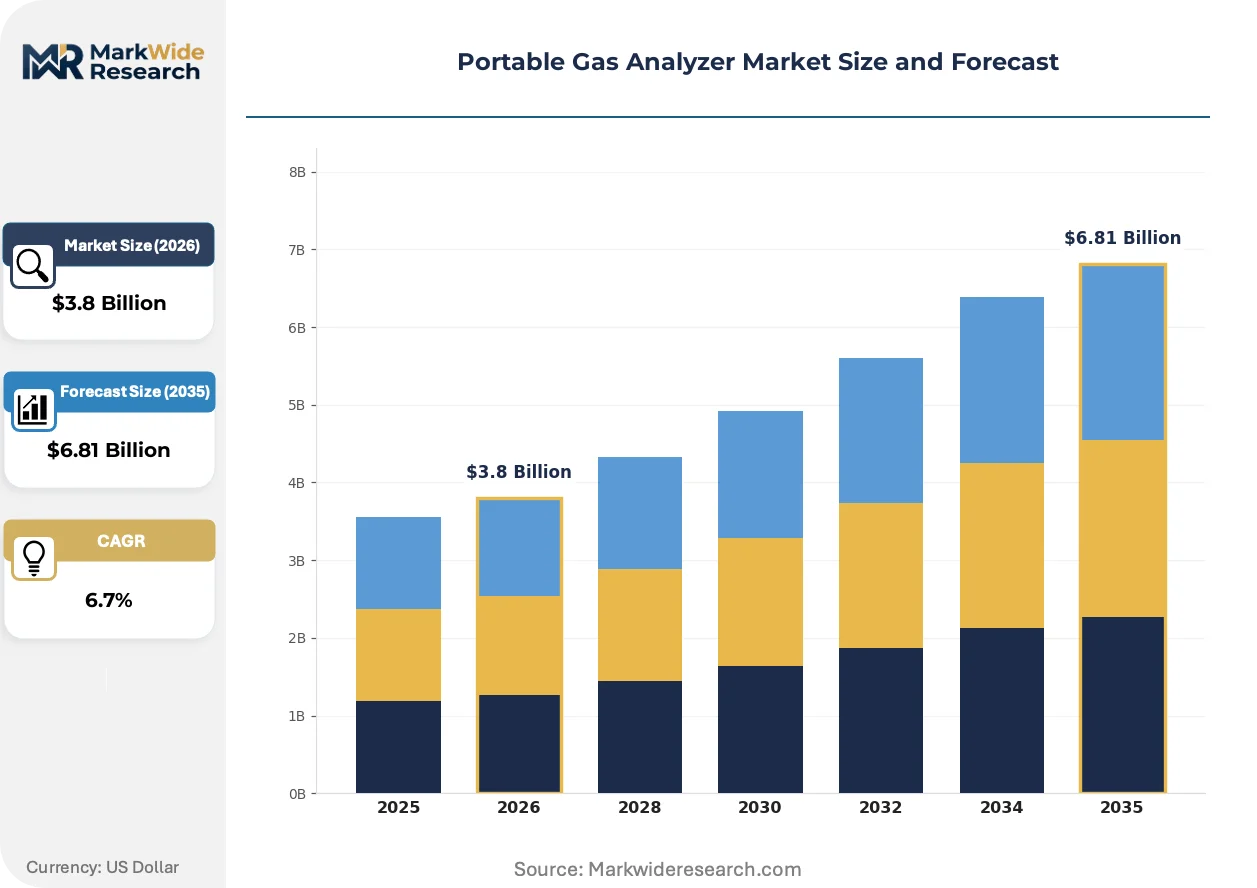
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Analyzers, Electrochemical Analyzers, Photoionization Detectors, Laser-based Analyzers Application: Industrial Safety, Environmental Monitoring, Process Control, Leak Detection End User: Chemical Plants, Oil & Gas Industry, Wastewater Treatment, Laboratories Technology: Optical Sensors, Microelectromechanical Systems, Wireless Communication, Portable Data Logging |
| Companies Covered | Honeywell International, ABB, Emerson Electric, AMETEK, Drägerwerk, MSA Safety, Thermo Fisher Scientific, Teledyne Technologies, Yokogawa Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Gas Analyzer Market Evolving Landscape
Photonic integration and edge computing are collapsing the size-performance tradeoff that historically separated laboratory and field-grade instrumentation. These advances enable new deployment models while regulatory stringency accelerates obsolescence of electrochemical-first architectures.
Photonic integrated circuits are overtaking discrete optical benches in mid-infrared gas analyzers. Packaged waveguide spectrometers now achieve sub-ppm detection limits for hydrocarbon mixtures. Oilfield service contractors in the Permian Basin and North Sea are deploying palm-sized TDLS units for rapid wellhead screening. The technology is overtaking extractive sampling methods by eliminating pump maintenance and response time delays.
EU F-Gas Regulation phase-down schedules are forcing sensor material transitions. Manufacturers must substitute restricted fluorinated compounds in optical windows and detector cooling systems. Electrochemical portfolios face parallel pressure from REACH substance restrictions on mercury-based reference electrodes. European chemical plant operators are prioritizing suppliers with pre-qualified alternative material sets to avoid supply interruption.
Buyer organizations are consolidating instrument fleets under enterprise asset management platforms. Large refinery operators in Texas and Rotterdam now mandate API-compatible data export and cloud dashboard integration as procurement preconditions. Equipment lessors and third-party calibration providers are capturing service revenue previously retained by manufacturer captive networks. This shift concentrates purchasing authority with corporate HSE departments and away from site-level maintenance supervisors.
Portable Gas Analyzer Market Segmentation
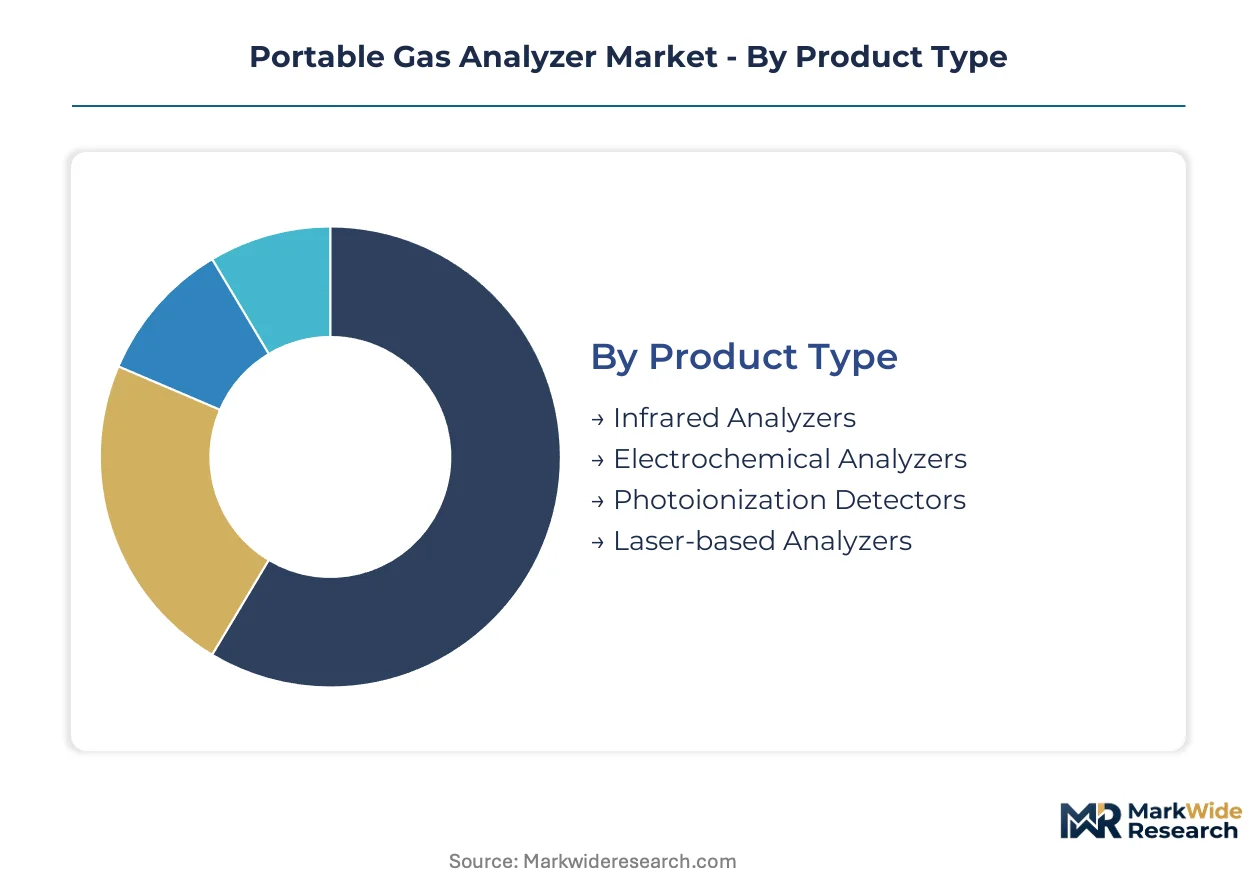
Product architecture choices in portable gas analyzers cascade through procurement specifications, calibration protocols, and total cost-of-ownership calculations. Segment boundaries increasingly blur as MEMS miniaturization and wireless integration enable multi-technology platforms serving overlapping use cases.
Product Type:
Standalone benchtop units dominate laboratory validation workflows, while palm-sized modules embed directly into drone payloads and wearable safety equipment.
- Infrared Analyzers:These instruments exploit the Beer-Lambert absorption principle across the mid-infrared spectrum to quantify hydrocarbon and carbon dioxide concentrations. Stack emission verification teams at German refineries specify NDIR units for EPA and EU F-Gas compliance documentation, driven by regulatory mandates for continuous opacity monitoring.
- Laser-based Analyzers:Tunable diode laser spectroscopy achieves parts-per-billion selectivity for methane and hydrogen sulfide without extractive sampling delays. Permian Basin operators deploy handheld TDLS units for wellhead leak surveys, replacing legacy flame ionization detectors under EPA Quad Oa enforcement timelines.
- Electrochemical Analyzers:Three-electrode amperometric cells measure toxic gases including carbon monoxide and hydrogen sulfide through redox reactions at catalytic surfaces.
- Photoionization Detectors:UV lamp ionization detects volatile organic compounds with 10.6 eV photon energy, serving hazmat response teams requiring broad-spectrum screening capability.
Volume placements concentrate in Infrared Analyzers; the faster expansion belongs to Laser-based Analyzers.
Application:
Cost tiers separate episodic compliance validation from continuous process integration, with premium pricing attaching to SIL-rated safety instrumented systems.
- Industrial Safety:Personal and area monitors detect oxygen deficiency, combustible gas accumulation, and toxic exposure limits in confined space entry protocols. OSHA permissible exposure limit enforcement drives replacement cycles at Texas petrochemical complexes, where multi-gas badges must achieve 90-day calibration stability.
- Leak Detection:Fugitive emission surveys employ optical gas imaging and laser absorption for regulatory compliance and voluntary methane reduction pledges. North Sea platform operators combine handheld analyzers with UAV-mounted sensors to satisfy EU methane performance standards and corporate net-zero commitments.
- Environmental Monitoring:Ambient air quality stations and fence-line monitoring networks track criteria pollutants and hazardous air contaminants.
- Process Control:Real-time gas composition feedback optimizes combustion efficiency and chemical reactor yields in continuous manufacturing.
Procurement volumes cluster in Industrial Safety; Leak Detection is climbing the fastest as methane accountability tightens.
End User:
Customer technical sophistication ranges from certified industrial hygienists to field maintenance crews, shaping interface design and training requirements.
- Oil & Gas Industry:Upstream, midstream, and downstream operations require distinct analyzer specifications from wellhead H2S monitoring to refinery flare gas analysis. Chinese national oil companies accelerate instrument procurement under MEE air quality enforcement protocols and dual carbon policy implementation.
- Chemical Plants:Process analytical technology demands intrinsically safe designs for Zone 1 hazardous area classification, with ATEX/IECEx certification as a non-negotiable entry requirement.
- Wastewater Treatment:Biogas recovery and odor control applications monitor hydrogen sulfide, ammonia, and methane in anaerobic digester operations.
- Laboratories:Research and calibration facilities require traceable reference standards and multi-point linearity verification for regulatory defensibility.
Equipment shipments concentrate in Oil & Gas Industry; Chemical Plants show the steepest expansion trajectory as process intensification demands tighter analytical control.
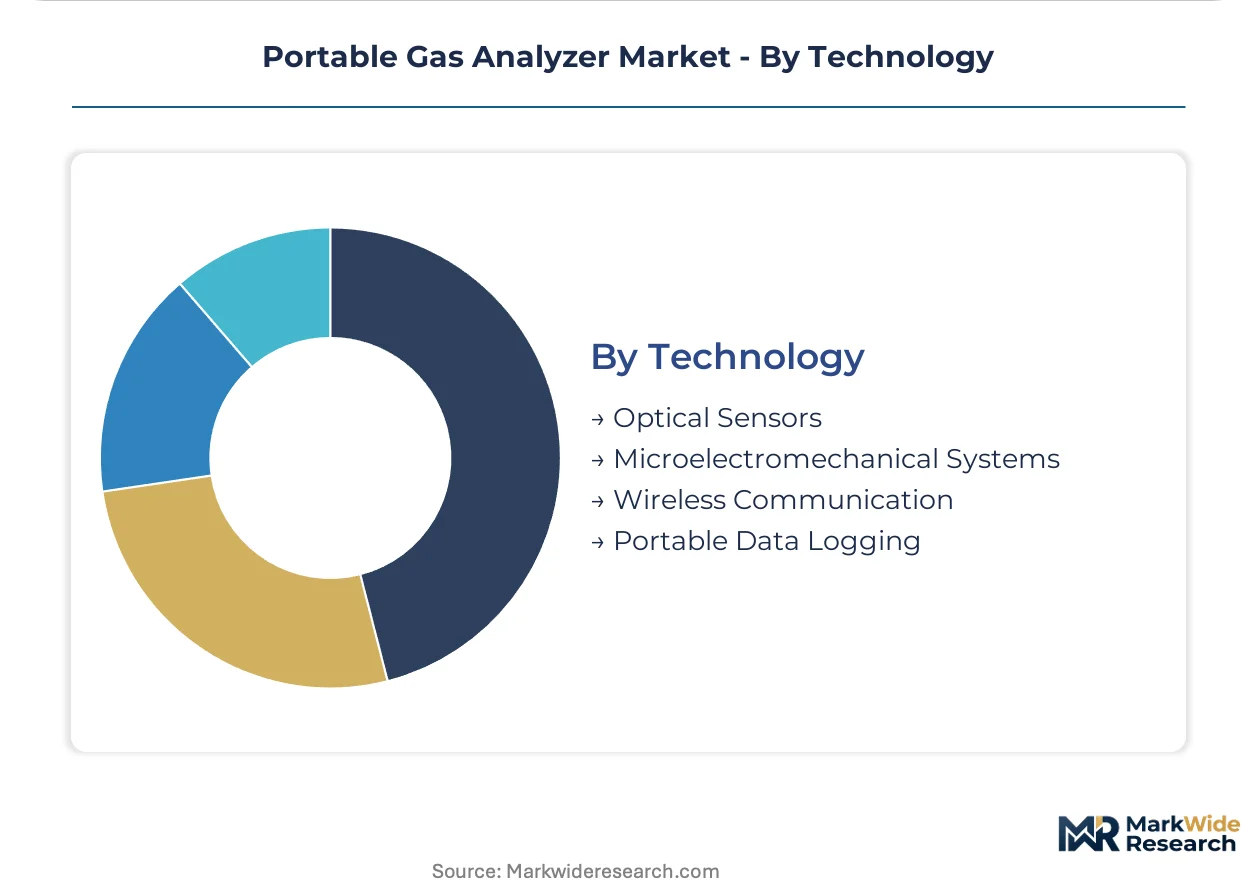
Technology:
Maturity gradients separate proven sensing modalities from emerging architectures still navigating qualification timelines.
- Optical Sensors:Nondispersive infrared and laser absorption platforms deliver species-specific detection without consumable electrolyte degradation. TDLS miniaturization enables smartphone-sized instruments previously requiring vehicle-mounted enclosures, reshaping field deployment economics.
- Wireless Communication:Bluetooth, Wi-Fi, and private 5G connectivity transmit real-time concentration data to centralized safety management systems. Large refinery operators in Rotterdam now mandate cloud dashboard integration as a procurement precondition, consolidating fleet visibility under enterprise asset management platforms.
- Microelectromechanical Systems:Silicon-based gas sensors achieve wafer-scale manufacturing cost structures for high-volume consumer and industrial applications.
- Portable Data Logging:Onboard storage and timestamped event recording support regulatory documentation and incident reconstruction requirements.
Adoption concentrates in Optical Sensors; Wireless Communication is gaining share fastest as IIoT infrastructure penetrates hazardous industrial environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors global procurement intensity for portable gas analyzers, with Texas petrochemical complexes driving instrument replacement cycles under tightened methane detection mandates.
United States
Permian Basin operators deploy handheld tunable diode laser units for wellhead leak surveys under EPA Quad Oa enforcement timelines. OSHA permissible exposure limit compliance drives multi-gas badge procurement at Gulf Coast refineries. Houston-area process analytical teams validate fixed-stack CEMS accuracy using portable optical instruments.
Germany
Ruhr Valley chemical plants prioritize suppliers with pre-qualified alternative sensor materials to avoid REACH Annex XVII supply interruptions. EU F-Gas Regulation phase-down schedules force redesign of optical windows and detector cooling systems. Bavarian refinery operators mandate API-compatible data export and cloud dashboard integration as procurement preconditions.
China
Yangtze River Delta petrochemical complexes accelerate instrument procurement under MEE air quality enforcement protocols and dual carbon policy implementation. GB standard harmonization creates parallel certification pathways that fragment go-to-market strategies. Shandong Province refineries face Scope 1 emission verification requirements demanding portable validation instruments.
India
Maharashtra cement and steel plants require portable stack validation instruments as state pollution control boards tighten inspection protocols. Gujarat chemical corridors demand intrinsically safe designs for Zone 1 hazardous area classification. Delhi-NCR ambient air quality stations track criteria pollutants through fence-line monitoring networks.
Saudi Arabia
Eastern Province gas processing facilities deploy continuous monitoring systems at compressor stations under corporate net-zero commitments. Jubail Industrial City operators combine handheld analyzers with UAV-mounted sensors for fugitive emission surveys. The country's national oil company accelerates optical instrument procurement to replace legacy extractive analyzers.
Portable Gas Analyzer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the portable gas analyzer landscape, with integrated sensing architectures facing pressure from modular platform specialists. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with captive safety instrument portfolios, pure-play analytical instrument specialists, and regional electrochemical sensor manufacturers. Dominant competitive moves include technology licensing agreements for tunable diode laser miniaturization and backward integration into MEMS wafer fabrication.
Within the diversified industrial tier, Honeywell International and ABB exemplify scale-driven platform strategies, while Drägerwerk occupies a position among specialized European safety equipment fabricators. These anchors represent contrasting approaches to regulatory-driven hardware redesigns—modular architectures enabling rapid recertification versus integrated systems optimized for specific hazardous environments.
| Leading Market Players |
|---|
| Honeywell International |
| ABB |
| Emerson Electric |
| AMETEK |
| Drägerwerk |
| MSA Safety |
| Thermo Fisher Scientific |
| Teledyne Technologies |
| Yokogawa Electric |
| Others |
Value Network & Pricing Analysis
Large refinery operators in Texas and Rotterdam now mandate cloud dashboard integration as a procurement precondition, compressing margins for suppliers without modular platform architectures while concentrating purchasing authority with corporate HSE departments.
Pricing Analysis
Value-based pricing anchors on emission reduction outcomes and regulatory compliance uptime rather than hardware unit costs. Three-tier pricing structure across SIL-certified premium, ATEX-standard mid-tier, and economy electrochemical units reflects certification grade and wireless connectivity bundling. Cost compression in economy electrochemical tiers is intensifying because REACH Annex XVII sensor material redesigns force R&D recapture. Chemical plant operators show least price sensitivity due to explosion-proof certification requirements, while small wastewater treatment facilities exhibit highest sensitivity to total cost-of-ownership calculations.
Supply Chain Analysis
China's GB standard harmonization and India's MEE enforcement protocols are reshaping sourcing strategies toward domestic-content-qualified component suppliers. Photonic integrated circuits draw from Taiwanese wafer foundries, German precision optics manufacturers, and Chinese MEMS packaging houses. Helium supply concentration in Qatar and the U.S. federal reserve creates single-source vulnerability for mass spectrometer cooling systems. Distribution runs through manufacturer-direct sales for large refinery fleets and regional calibration service providers for fragmented industrial safety accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Quad Oa methane rules and EU F-Gas Regulation phase-down schedules create a cost-of-compliance barrier that favors incumbent suppliers with pre-qualified alternative material sets and modular recertification capabilities.
For Market Incumbents: Deploy predictive calibration-as-a-service platforms to convert capital equipment sales into recurring revenue streams. Deepen backward integration into MEMS wafer fabrication to secure sensor supply against REACH material restrictions. Anchor defensive positioning through API-compatible data export capabilities that match enterprise asset management platform requirements from large refinery operators. For New Entrants and Emerging Players: Launch via equipment leasing and third-party calibration partnerships to bypass captive manufacturer service networks. Target India's Maharashtra cement and steel corridor where state pollution control board enforcement creates instrument replacement demand without entrenched incumbent relationships. Prioritize battery thermal runaway detection applications in lithium-ion manufacturing as a white-space segment with limited specialized competition. For Investors and Strategic Acquirers: The window for entry favors modular platform specialists with pre-qualified REACH-compliant sensor material portfolios over integrated system architects. Long-term viability rests on suppliers enabling 5G-enabled fleet management and cloud-connected drift monitoring. Watch for EPA methane performance standard revisions as the signal indicating accelerated replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Sensor Miniaturization | TDLS miniaturization enables smartphone-sized instruments for Permian Basin wellhead surveys. |
| Backward Integration into Photonic Components | In-house waveguide spectrometer production reduces dependency on Taiwanese wafer foundry allocations. |
| 5G-Enabled Predictive Calibration | Cloud-connected fleets allow Rotterdam refinery operators to consolidate instrument visibility under single platforms. |
| REACH-Compliant Material Substitution | Pre-qualified alternative sensor materials prevent supply interruption for Ruhr Valley chemical plants. |
| Joint Venture with UAV Platform Providers | Drone-mounted sensor integration captures North Sea platform fugitive emission survey contracts. |
Research Methodology
Independent corroboration across plant engineers at Texas petrochemical complexes, procurement leads at German chemical manufacturers, and aftermarket service heads at calibration providers underwrites the qualitative findings. Primary interviews with maintenance directors, OEM procurement teams, and regulatory affairs specialists at instrument manufacturers combined with secondary validation from EPA enforcement databases, EU F-Gas Regulation implementation reports, and SEC 10-K instrument segment disclosures. Bottom-up shipment estimates triangulate against top-down addressable market calculations.
Comparable-period anchoring to historical replacement cycles under EPA and EU enforcement timelines shaped the projection horizon across the analysis window. Segmentation dimensions modeled include product architecture, application severity tier, end-user industry vertical, and regional regulatory cluster. CAGRs derive from instrument replacement frequency assumptions tied to methane detection mandate phase-in schedules and sensor material restriction compliance deadlines. Forecast inputs incorporate refinery carbon accounting protocol adoption rates and wireless connectivity penetration in hazardous area classifications.
Helium supply quota volatility, REACH Annex XVII substance restriction timeline adjustments, and MEE enforcement intensity variations are the dominant revision risks. Forecasts reflect assumptions regarding regulatory implementation pacing and sensor material qualification timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Life Science and Analytical Instruments Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Global Electron Microscopes Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Gas Analyzer Market
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
Analytical Instrumentation for Food Applications Market
Analytical Instruments
Next Generation Mass Spectrometer Market