
 Air Sampling Equipment Market | 2026-2036
Air Sampling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Air Sampling Equipment Market Analytics
A capital-intensity divergence between integrated sensor manufacturers and assembly-focused distributors is bifurcating competitive dynamics in air sampling equipment. Thermo Fisher Scientific leverages captive electrochemical sensor fabrication to sustain margin depth across compliance testing contracts. SKC competes through specialized pump-based system architectures that anchor its position in industrial manufacturing channels. GASTEC CORPORATION differentiates via compact passive sampling cartridges that dominate Asian workplace safety procurement.
Air sampling equipment comprises instruments designed to capture, concentrate, and quantify airborne contaminants through calibrated flow rates, adsorbent media, or optical detection methods, serving regulatory compliance and occupational health objectives. Active sampling systems with programmable flow control represent the mature revenue base, while continuous monitoring platforms integrating electrochemical and optical sensor arrays capture the fastest expansion as environmental agencies shift from episodic to real-time surveillance. Research laboratories generate concentrated margin pools through low-volume, high-specification procurement of particulate filter configurations.
The EPA enforces NAAQS compliance thresholds that directly determine product sensitivity specifications for domestic manufacturers, while OSHA permissible exposure limits mandate workplace sampling frequencies that sustain replacement demand for pump-based and passive systems. ISO 7708 particulate matter conventions and EU Green Deal industrial emissions frameworks shape transatlantic product certification requirements. Stakeholders must monitor sensor miniaturization trajectories and evolving PFAS air monitoring protocols to align R&D allocation with emerging regulatory test methods.
Market Dynamics
Continuous monitoring platforms are displacing episodic pump-based systems as environmental agencies mandate real-time emissions surveillance, compressing replacement cycles and rewiring procurement specifications across industrial compliance channels.
Growth Catalysts
- EU Green Deal industrial emissions directives:Tightening permissible particulate thresholds in Germany, France, and the Netherlands are forcing manufacturing facilities to upgrade from quarterly manual sampling to automated continuous monitoring systems.
- Pharmaceutical cleanroom expansion:Sterile drug manufacturing facilities in Ireland and Switzerland are procuring multi-point sensor arrays to satisfy FDA and EMA validation requirements for aseptic processing environments.
- PFAS air monitoring protocols:Emerging test methods for per- and polyfluoroalkyl substances in the United States are creating demand for specialized sorbent tube configurations and thermal desorption accessories.
Market Restraints
- Electrochemical sensor supply concentration:Fabrication of high-precision gas sensors concentrates in South Korean and Japanese component houses, exposing assemblers to lead-time volatility and minimum order constraints.
- ISO 17025 calibration infrastructure gaps:Accredited service capacity for flow-rate verification and sensor validation remains thin outside major metropolitan zones, extending equipment commissioning timelines.
- Passive sampling substitution pressure:Compact diffusion tubes for workplace benzene and formaldehyde monitoring offer lower capital burden than active pump systems in cost-sensitive industrial hygiene budgets.
Strategic Opportunities
- India industrial cluster penetration:Pharmaceutical manufacturing parks near Hyderabad and Ahmedabad lack mature continuous monitoring infrastructure, presenting first-mover positioning for compliance-focused system vendors.
- Electrochemical-optical sensor convergence:Hybrid detection architectures combining metal oxide semiconductors with laser scattering are opening specification windows for simultaneous gas and particulate quantification in single enclosures.
- Rental and managed service channels:Project-based environmental consultancies in Australia and Canada are migrating from capital purchase to subscription-based equipment access, shifting margin capture toward service bundling.
Industry Challenges
- Multi-protocol firmware integration:Field technicians must reconcile Modbus, BACnet, and proprietary sensor communication standards when retrofitting continuous monitors into legacy building management architectures.
- EPA Method TO-15 validation timelines:Laboratories seeking accreditation for volatile organic compound analysis by canister sampling face 12-18 month certification queues, delaying contract commencement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Sampling Equipment Market |
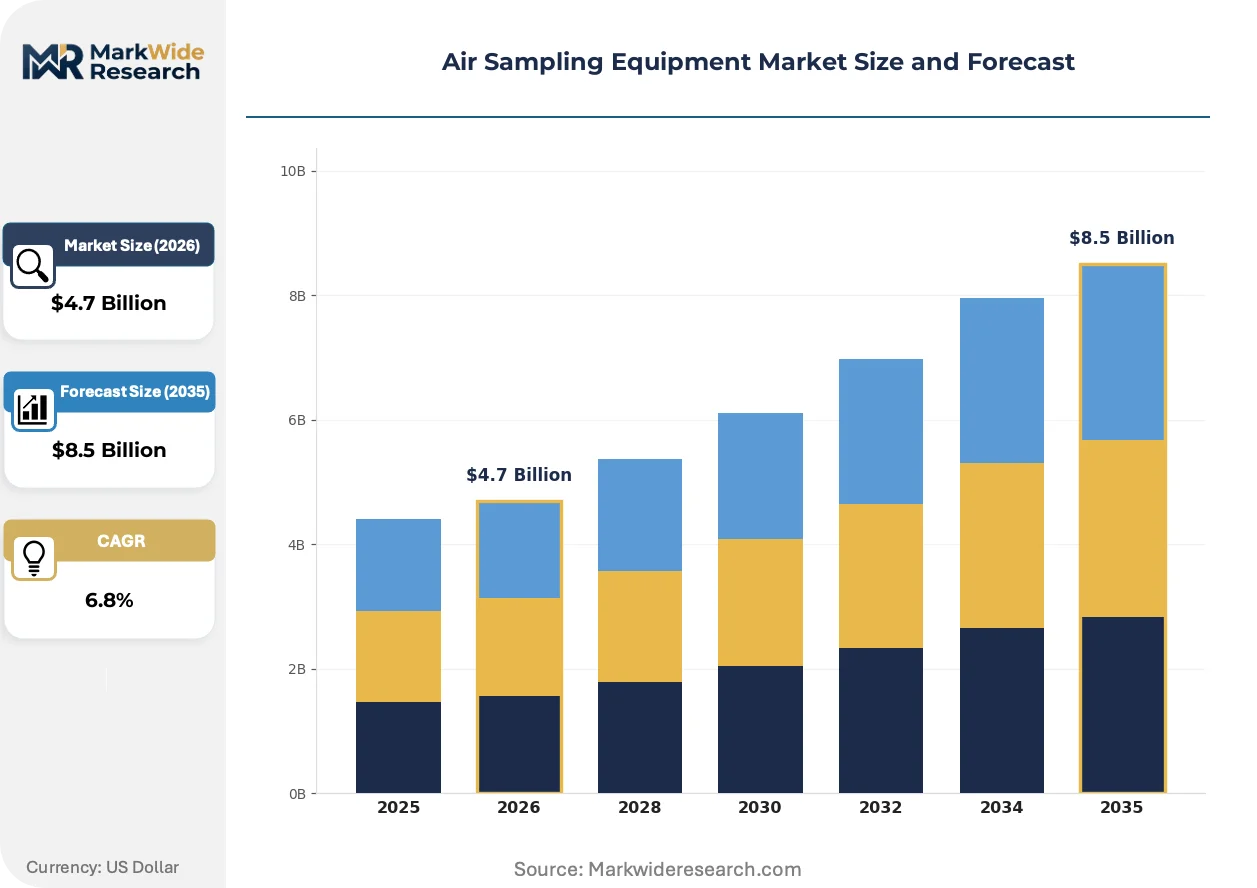
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Sampling, Passive Sampling, Continuous Monitoring, Pump-Based Systems End User: Industrial Manufacturing, Environmental Agencies, Research Laboratories, Educational Institutions Technology: Electrochemical Sensors, Optical Sensors, Solid Adsorbent, Particulate Filters Application: Workplace Safety, Air Quality Monitoring, Research Applications, Compliance Testing |
| Companies Covered | Sensidyne, SKC, SIBATA, GL Sciences, AP BUCK, GASTEC CORPORATION, Zefon, Casella, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Sampling Equipment Market Evolving Landscape
Miniaturization of optical particle counters and solid-state gas sensors is collapsing the form-factor and cost barriers that historically separated laboratory-grade instrumentation from industrial field deployment.
Photoelectric light-scattering arrays with onboard algorithms for particle size discrimination are supplanting filter-based gravimetric methods in ambient air monitoring networks. Municipal environmental agencies in California and Texas are deploying these units at fenceline locations surrounding petrochemical complexes. The shift is compressing data latency from weeks to minutes while eliminating filter handling labor.
REACH authorization requirements for SVHC substance monitoring are extending mandatory air sampling obligations to downstream formulators and polymer processors previously exempt from direct emissions oversight. Chemical manufacturers in Belgium and northern Italy are retrofitting storage and handling areas with fixed-position detectors. Equipment vendors are responding with explosion-proof enclosures rated for ATEX Zone 1 deployment.
Service unbundling is fragmenting traditional system sales into discrete hardware, calibration, and data-analytics contracts. Environmental consulting firms in the United Kingdom are procuring sensors separately from cloud-based dashboard subscriptions. The separation permits software upgrades without capital replacement and is concentrating margin toward recurring data-service revenue streams.
Air Sampling Equipment Market Segmentation
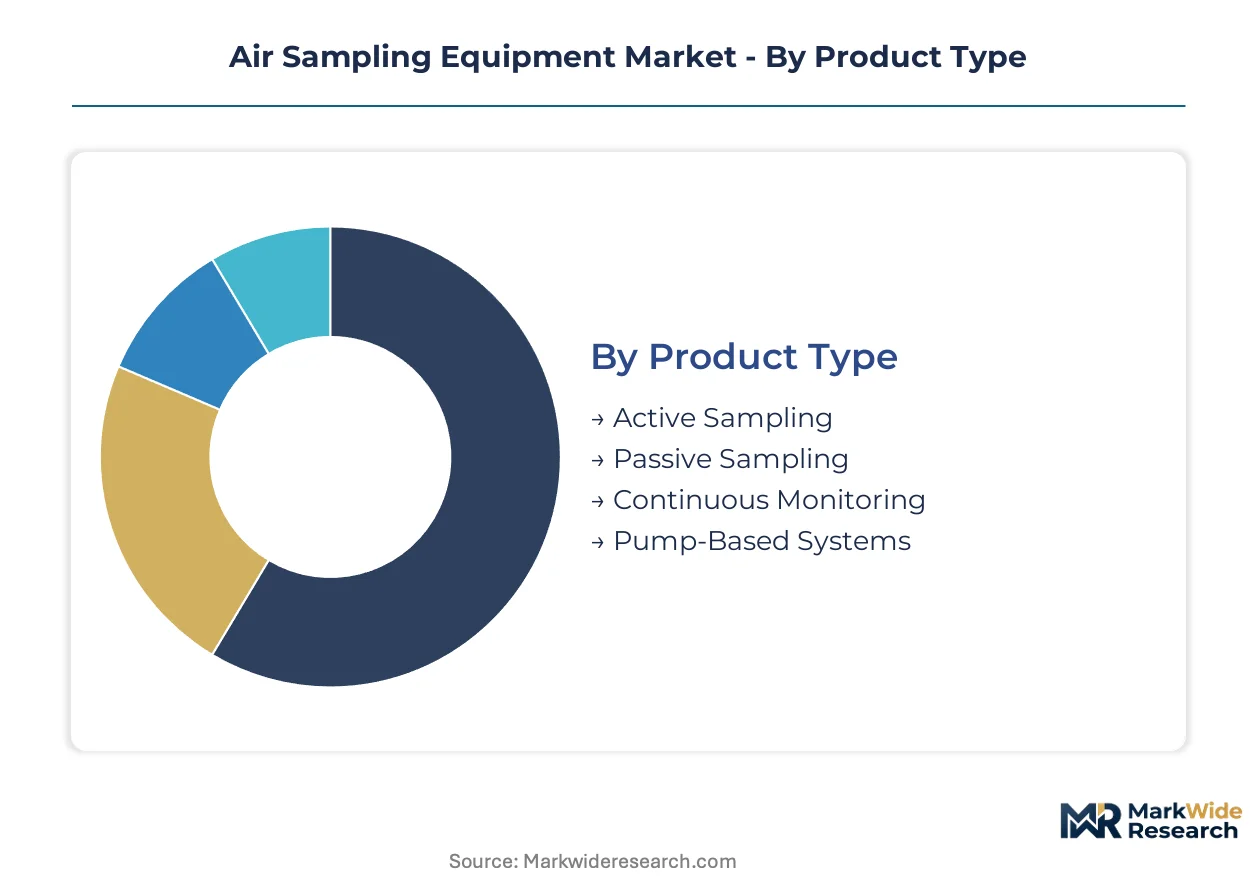
Segmentation in air sampling equipment reveals distinct procurement patterns across regulatory regimes and operational environments. Product architecture, detection technology, and end-use compliance requirements create divergent margin profiles and replacement cycles that vendors must navigate strategically.
Product Type:
Active sampling and continuous monitoring systems anchor domestic procurement in the United States and Germany, while passive sampling cartridges dominate export flows to Asian industrial hygiene markets. Pump-based configurations retain strongholds in episodic compliance testing.
- Active Sampling:Programmable flow-control units draw air through adsorbent media or filters for laboratory analysis. Demand concentrates in EPA regional compliance hubs in California and Texas, where quarterly stack testing mandates sustain replacement cycles for portable pump systems.
- Continuous Monitoring:Fixed-position sensor arrays deliver real-time data streams to environmental management systems. Pharmaceutical cleanroom operators in Germany and Ireland are expanding procurement to satisfy FDA and EMA validation requirements for aseptic processing environments.
- Passive Sampling:Diffusion-based cartridges require no power source and suit cost-sensitive workplace monitoring. Compact GASTEC configurations dominate procurement by Japanese and South Korean manufacturing facilities.
- Pump-Based Systems:Battery-operated portable units serve industrial hygiene contractors conducting personal exposure assessments. SKC specialized architectures anchor position in North American manufacturing channels.
Active sampling commands the established base. The steepest expansion runs through continuous monitoring.
End User:
Environmental agencies drive premium pricing through multi-point network deployments, while industrial manufacturing absorbs volume through distributed facility upgrades. Research laboratories generate concentrated margin pools despite smaller unit volumes.
- Environmental Agencies:Municipal and federal authorities operate ambient monitoring networks requiring NAAQS-compliant sensitivity specifications. California Air Resources Board fenceline deployments around petrochemical complexes are displacing filter-based gravimetric methods with photoelectric light-scattering arrays.
- Industrial Manufacturing:Chemical, pharmaceutical, and electronics producers face tightening EU Green Deal particulate thresholds. Facilities in Belgium and northern Italy are retrofitting storage areas with ATEX Zone 1 rated explosion-proof detectors.
- Research Laboratories:Universities and contract research organizations procure low-volume, high-specification particulate filter configurations. ISO 17025 calibration requirements extend equipment commissioning timelines outside major metropolitan zones.
- Educational Institutions:University environmental science programs acquire training-grade instrumentation for curriculum deployment. Budget constraints favor refurbished pump systems over continuous monitoring platforms.
Industrial manufacturing absorbs the highest unit volumes. Research laboratories capture the strongest margin per transaction.
Technology:
Electrochemical sensor fabrication concentrates in South Korean and Japanese component houses, exposing assemblers to supply volatility. Optical detection methods are gaining share in ambient monitoring applications.
- Electrochemical Sensors:Metal oxide semiconductor architectures quantify gas concentrations through redox reactions. High-precision fabrication concentrates in South Korean and Japanese component houses, exposing assemblers to lead-time volatility.
- Optical Sensors:Laser scattering and photoelectric arrays discriminate particle size in real time. Municipal environmental agencies in Texas are deploying these units at fenceline locations surrounding petrochemical complexes.
- Solid Adsorbent:Activated carbon and Tenax tubes capture volatile organic compounds for thermal desorption analysis. Emerging PFAS air monitoring protocols in the United States are creating demand for specialized sorbent configurations.
- Particulate Filters:Gravimetric methods using pre-weighed membranes remain reference standards for regulatory compliance. Filter handling labor is driving substitution toward optical methods in high-frequency monitoring networks.
Particulate filters anchor regulatory reference methods. Optical sensors are climbing the fastest on deployment expansion.
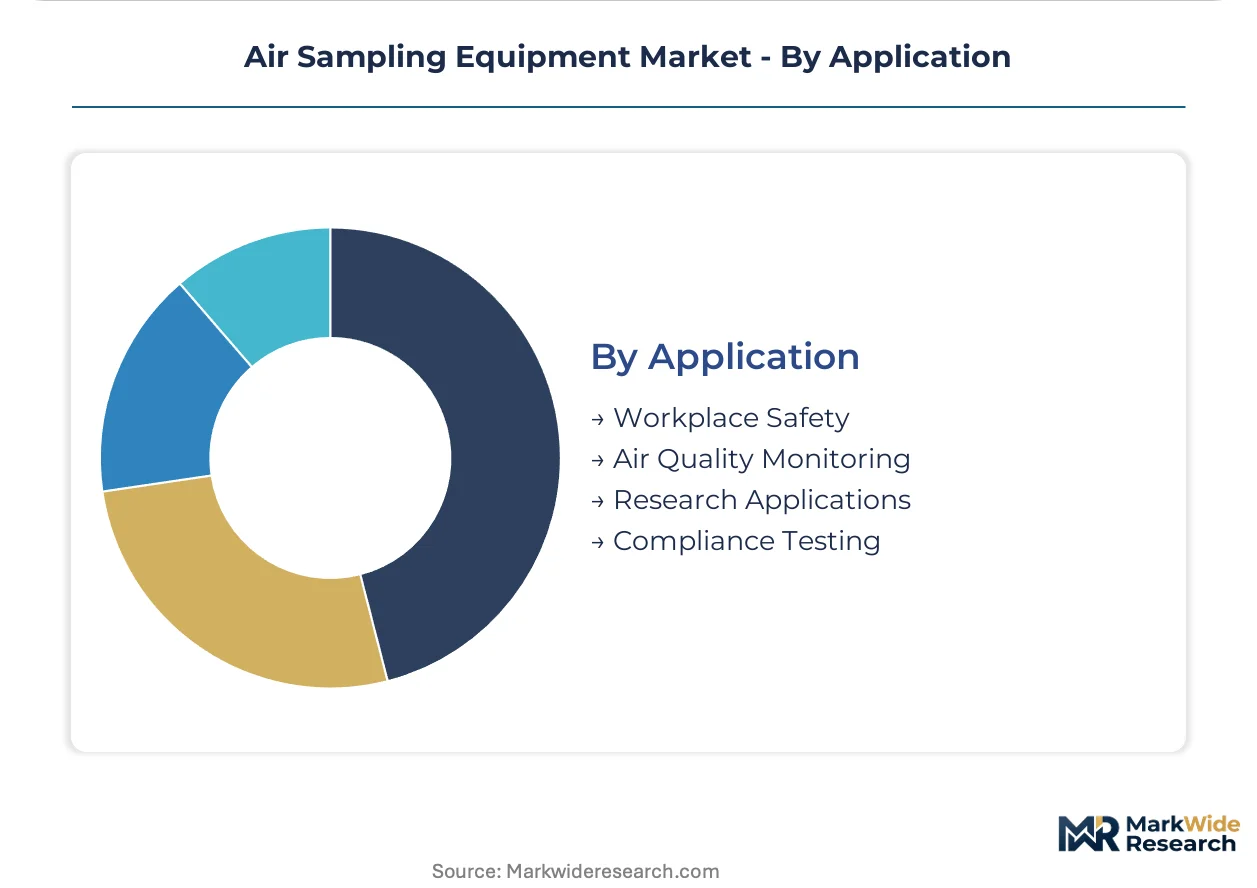
Application:
Workplace safety procurement favors passive and portable active systems, while air quality monitoring shifts toward fixed continuous networks. Compliance testing sustains replacement demand for calibrated pump equipment.
- Workplace Safety:OSHA permissible exposure limits mandate sampling frequencies for benzene, formaldehyde, and respirable particulates. Industrial hygiene budgets in cost-sensitive sectors favor passive diffusion tubes over active pump systems.
- Air Quality Monitoring:Ambient network operators deploy multi-parameter stations at urban and industrial perimeter locations. The shift from episodic to real-time surveillance is compressing data latency from weeks to minutes.
- Research Applications:Atmospheric chemistry and exposure science studies require customizable inlet configurations and speciated analysis capabilities. Low-volume procurement concentrates at National Oceanic and Atmospheric Administration and university atmospheric research centers.
- Compliance Testing:Third-party environmental consultancies conduct mandated emissions testing for industrial permitting. EPA Method TO-15 validation timelines of 12-18 months delay laboratory accreditation for volatile organic compound analysis by canister sampling.
Compliance testing sustains the replacement cycle base. Air quality monitoring is gaining share fastest on regulatory real-time mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss pharmaceutical corridors, while procurement volume gravitates toward EPA regional compliance hubs in California and Texas. This asymmetry shapes divergent product mix strategies across Atlantic markets.
United States
EPA regional compliance hubs in California and Texas drive concentrated demand for NAAQS-aligned continuous monitoring systems. The EPA enforces Method TO-15 validation timelines that extend laboratory accreditation queues to 12-18 months. Fenceline deployments around petrochemical complexes in Houston and Los Angeles are displacing filter-based gravimetric methods with photoelectric light-scattering arrays.
Germany
Pharmaceutical cleanroom operators in Baden-Württemberg and Bavaria are expanding procurement of multi-point sensor arrays for aseptic processing validation. EU Green Deal industrial emissions directives tighten permissible particulate thresholds for manufacturing facilities. The Rhine-Main chemical corridor near Frankfurt is retrofitting storage areas with ATEX Zone 1 rated explosion-proof detectors.
Switzerland
Sterile drug manufacturing facilities in Basel and Zurich procure high-specification particulate filter configurations for FDA and EMA dual validation requirements. Swissmedic oversees medical product manufacturing standards that extend to environmental monitoring protocols. The country's precision instrumentation heritage supports premium-tier continuous monitoring system deployment.
India
Pharmaceutical manufacturing parks near Hyderabad and Ahmedabad lack mature continuous monitoring infrastructure, presenting positioning opportunities for compliance-focused system vendors. The country's national pharmaceutical regulator mandates escalating environmental surveillance for active pharmaceutical ingredient production. Industrial clusters in Gujarat are initiating procurement shifts from manual quarterly sampling toward automated platforms.
Japan
Compact passive sampling cartridges dominate workplace safety procurement by manufacturing facilities in Osaka and Nagoya industrial zones. METI industrial safety guidelines sustain replacement demand for diffusion-based benzene and formaldehyde monitoring. High-precision electrochemical sensor fabrication concentrates in component houses serving domestic and regional assemblers.
Air Sampling Equipment Market Competitive Landscape
Concentration sits with diversified laboratory instrumentation conglomerates and specialized industrial hygiene equipment fabricators. The vendor base stratifies across three tiers: integrated sensor manufacturers sustaining margin depth through captive component production, pump-based system specialists anchoring industrial manufacturing channels, and compact passive sampling providers dominating cost-sensitive Asian procurement. Competitive moves center on sensor miniaturization R&D alignment and managed service channel development for project-based environmental consultancies.
Within the integrated instrumentation tier, Thermo Fisher Scientific exemplifies backward integration into electrochemical sensor fabrication. SKC occupies a position among pump-based system architects serving North American manufacturing compliance channels. GASTEC CORPORATION represents the compact passive sampling archetype with penetration across Japanese and South Korean workplace safety procurement.
| Leading Market Players |
|---|
| Sensidyne |
| SKC |
| SIBATA |
| GL Sciences |
| AP BUCK |
| GASTEC CORPORATION |
| Zefon |
| Casella |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
ISO 17025 calibration requirements gate both supplier qualification and price tiering simultaneously, as laboratories lacking accredited service capacity outside major metropolitan zones face extended commissioning timelines that compress margin capture for mid-tier distributors while amplifying premium capture for integrated manufacturers with captive validation infrastructure.
Pricing Analysis
Configured-to-order pricing for multi-point sensor arrays commands substantial premiums over standard portable pump configurations. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in economy-tier passive sampling cartridges is intensifying because compact diffusion tubes from Asian manufacturers undercut active system capital expenditure. Industrial hygiene contractors in cost-sensitive sectors exhibit highest price sensitivity, while pharmaceutical cleanroom operators in Germany and Switzerland demonstrate lowest sensitivity due to FDA and EMA validation requirements.
Supply Chain Analysis
South Korea and Japan anchor high-precision electrochemical sensor fabrication, with component houses supplying metal oxide semiconductor architectures to global assemblers. Raw material dependencies center on specialized sorbent media, optical-grade laser components, and pre-weighed filter membranes. Single-source vulnerability concentrates in South Korean sensor foundries, exposing procurement timelines to minimum order constraints and lead-time volatility. Distribution runs through specialized industrial hygiene distributors in North America, direct OEM relationships in European pharmaceutical corridors, and compact cartridge exporters serving Asian workplace safety markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous monitoring platforms are displacing legacy pump-based architectures as environmental agencies mandate real-time emissions surveillance, creating a high-growth disruption justified by the EU Green Deal's tightening particulate thresholds and the EPA's shift from episodic to continuous compliance verification.
For Market Incumbents: Shield installed base revenue by accelerating backward integration into electrochemical sensor fabrication to reduce dependency on South Korean and Japanese component houses. Deepen certification investment in ISO 17025 calibration infrastructure to extend service moats against unaccredited distributors. The threat of passive sampling substitution pressure in cost-sensitive industrial hygiene budgets demands channel control through managed service bundling.
For New Entrants and Emerging Players: Anchor in Indian pharmaceutical manufacturing parks near Hyderabad and Ahmedabad, where mature continuous monitoring infrastructure remains underdeveloped and national pharmaceutical regulators mandate escalating environmental surveillance. Target compliance-focused system deployment with rental and subscription-based equipment access models that shift buyer preference from capital purchase. The most penetrable segment lies in project-based environmental consultancies migrating toward service bundling.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrochemical-optical sensor convergence architectures, favoring players with in-house component production over assembly-focused distributors. Long-term viability over the coming decade rests on capturing recurring data-service revenue streams as environmental consulting firms unbundle hardware from cloud-based analytics subscriptions. The acquisition target archetype comprises specialized pump-based system architects with entrenched industrial manufacturing channel positions. Watch sensor miniaturization trajectories and evolving PFAS air monitoring protocols as inflection indicators for R&D allocation alignment.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrochemical-Optical Sensor Convergence | Hybrid detection architectures open specification windows for simultaneous gas and particulate quantification in single enclosures. |
| Managed Service Channel Development | Subscription-based equipment access shifts margin capture toward recurring data-service revenue streams for environmental consultancies. |
| ISO 17025 Calibration Infrastructure Expansion | Accredited service capacity extension compresses commissioning timelines and deepens competitive moats against unqualified distributors. |
| PFAS Air Monitoring Protocol Alignment | Specialized sorbent tube configurations and thermal desorption accessories capture emerging regulatory test method demand. |
| India Industrial Cluster Penetration | First-mover positioning in pharmaceutical manufacturing parks near Hyderabad and Ahmedabad addresses infrastructure maturity gaps. |
Research Methodology
A spread of perspectives from environmental agency procurement officers, pharmaceutical cleanroom validation managers, industrial hygiene contractors, and electrochemical sensor component suppliers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement guidance documents, EU Green Deal industrial emissions directives, ISO 7708 particulate matter conventions, and OSHA permissible exposure limit databases. Bottom-up triangulation across product-type demand curves and top-down reconciliation against regulatory compliance expenditure patterns anchored the quantitative framework.
Segmentation dimensions modeled span product architecture, detection technology, end-user compliance requirements, and application environment across the projection horizon. CAGRs derived from regression analysis of historical procurement cycles and regulatory implementation timelines. Industry-specific forecast inputs incorporated sensor miniaturization trajectories and evolving PFAS air monitoring protocol adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory tightening in particulate thresholds and electrochemical sensor supply concentration; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in EPA regional enforcement priorities and EU Green Deal implementation phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Handheld XRF Analyzers Market
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Dew Point Analyzer Market
Analytical Instruments
Europe Surface Analysis Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Microanalysis Sample Preparation Systems Market
Analytical Instruments
Headspace Gas Analyzers Market
Analytical Instruments
Global Laboratory Electronic Balance Market
Analytical Instruments
Global Fixed Zirconia Oxygen Analyzer Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Gas Analyzer Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Laser Probe Market
Analytical Instruments
Benchtop Ph Meters Market