
 Africa Digital Thermometer Market | 2026-2036
Africa Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Digital Thermometer Market Analytics
African medical device assembly capacity is repositioning toward localized production hubs in Egypt and South Africa. Omron Corporation leverages its distribution partnerships to sustain channel presence across East and West African markets. Microlife Corporation anchors its competitive stance through product specialization in clinical-grade infrared devices. Geratherm Medical AG differentiates via adherence to European CE marking standards that facilitate cross-border trade within African economic communities.
Africa digital thermometers are electronic temperature measurement instruments employing thermistors or infrared sensors to detect body or surface thermal radiation, typically displaying readings within 0.1°C precision on LCD or LED screens for clinical diagnostics and industrial monitoring. Their primary commercial purpose centers on enabling rapid, hygienic temperature screening in healthcare and workplace settings where mercury-based alternatives face phase-out. Infrared thermometers lead product type demand due to non-contact protocols adopted during infectious disease containment campaigns, while smart thermometers with Bluetooth connectivity represent the fastest-growing technology segment as telemedicine platforms expand across the continent. Home healthcare dominates end-user consumption driven by urban middle-class consumers seeking self-monitoring capabilities, whereas hospital procurement channels concentrate margin pools through bulk purchasing agreements and tender-based supply contracts.
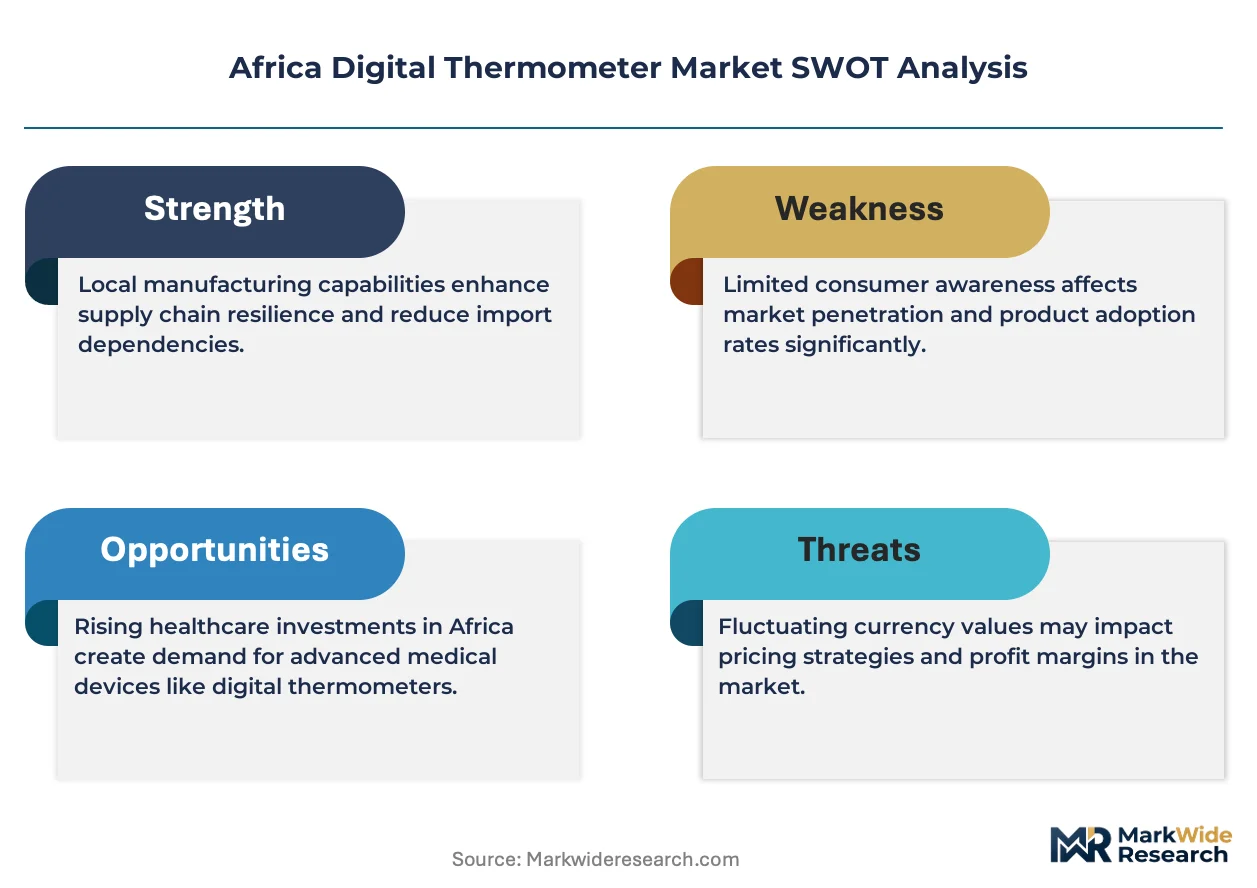
National regulators including South Africa's Health Products Regulatory Authority, Nigeria's National Agency for Food and Drug Administration and Control, and Kenya's Pharmacy and Poisons Board enforce medical device registration requirements that shape import timelines and product labeling standards across the region. WHO prequalification and ISO 13485 certification increasingly function as de facto market access prerequisites for multinational suppliers seeking public sector contracts. Stakeholders must monitor evolving harmonization efforts under the African Medicines Regulatory Harmonization initiative to anticipate streamlined approval pathways and shifting competitive entry barriers.
Market Dynamics
WHO prequalification standards are compressing import timelines for medical devices across African markets, forcing suppliers to restructure certification roadmaps and relocate quality assurance documentation to regional hubs.
Growth Catalysts
- Infrared sensor miniaturization:Non-contact temperature detection protocols adopted during infectious disease containment campaigns are accelerating replacement cycles for mercury-based devices in Nigerian primary care clinics.
- Home healthcare infrastructure:Urban middle-class consumers in Kenya are deploying Bluetooth-enabled thermometers for remote pediatric monitoring, expanding telemedicine platform integration requirements.
- African Medicines Regulatory Harmonization:Streamlined approval pathways under this WHO-backed initiative are reducing registration duplication costs for manufacturers targeting multiple East African Community member states.
Market Restraints
- Lithium battery supply concentration:Dependence on East Asian cell manufacturers creates input cost volatility and extended lead times for portable infrared device production.
- CE marking dependency:European certification requirements function as de facto trade barriers for local African assemblers lacking notified body relationships, limiting regional production scale-up.
- Mercury thermometer residual stock:Existing inventories of banned mercury devices in rural South African clinics delay full digital conversion and compress near-term replacement demand.
Strategic Opportunities
- Ethiopian manufacturing zones:Industrial park incentives and duty-free raw material imports are attracting assembly operations to serve Horn of Africa distribution networks.
- Wearable temperature monitoring:Convergence of flexible printed electronics with low-power Bluetooth Low Energy is enabling continuous fever tracking for post-surgical patients in Ghanaian hospitals.
- Mobile money procurement channels:Integration with M-Pesa and similar platforms is unlocking direct-to-consumer sales in Kenyan and Tanzanian markets previously dependent on pharmacy retail.
Industry Challenges
- ISO 13485 auditor scarcity:Limited availability of qualified medical device quality management certifiers in sub-Saharan Africa extends compliance timelines by 8-14 months for new market entrants.
- Calibration infrastructure gaps:Absence of accredited thermal reference laboratories in West Africa forces manufacturers to ship devices to South Africa or Europe for precision verification, inflating logistics costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Digital Thermometer Market |
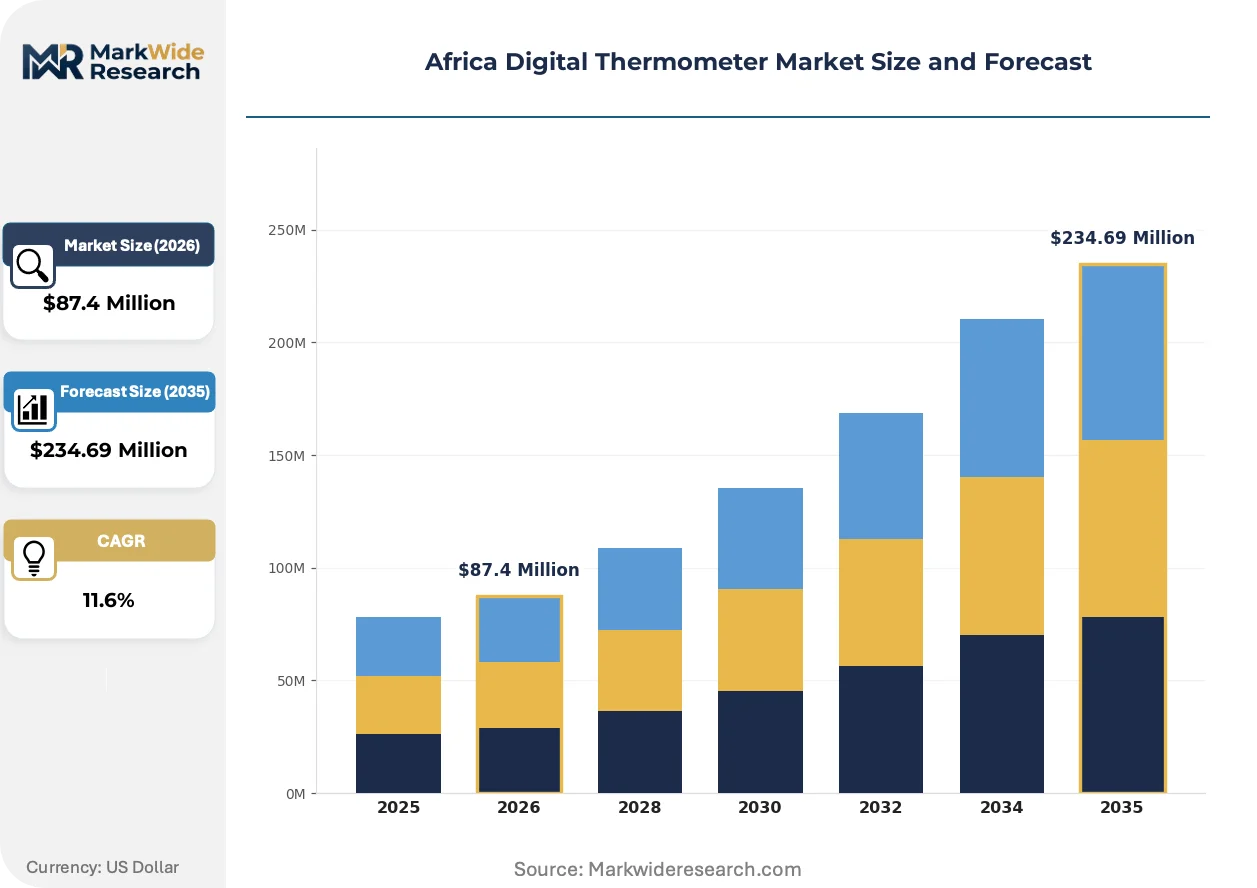
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Thermometers, Clinical Thermometers, Ear Thermometers, Smart Thermometers End User: Hospitals, Clinics, Home Healthcare, Industrial Facilities Distribution Channel: Online Retail, Pharmacies, Medical Supply Stores, Direct Sales Technology: Digital Display, Bluetooth-enabled, Non-contact, Wireless |
| Companies Covered | Omron Corporation, Terumo Corporation, Microlife Corporation, Exergen Corporation, Geratherm Medical AG, Ametek, Inc., A&D Company, Limited, Actherm Inc., American Diagnostic Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Digital Thermometer Market Evolving Landscape
Sensor fusion and connectivity protocols are redefining thermometer functionality beyond single-point measurement, embedding these devices into broader remote patient monitoring ecosystems.
Multispectral infrared arrays are automating fever screening in high-throughput settings such as Johannesburg airport terminals and Lagos port facilities. Transport authorities are deploying these systems at passenger processing checkpoints to reduce manual staffing requirements. The technology is automating temperature triage decisions that previously required trained clinical personnel, compressing labor costs while maintaining detection sensitivity.
South Africa's Health Products Regulatory Authority has mandated Unique Device Identification labeling for all imported Class II medical devices, including digital thermometers. This policy forces manufacturers to reconfigure packaging lines and establish serialization databases before customs clearance. Hospital procurement channels in Gauteng and Western Cape provinces are prioritizing suppliers with pre-registered UDI compliance to avoid tender disqualification.
Direct purchasing by large hospital groups is displacing traditional medical device distributors in Nigerian and Kenyan urban centers. Teaching hospitals in Abuja and Nairobi are establishing centralized procurement offices with technical evaluation capabilities, cutting out intermediary margins. This concentration is most visible in bulk thermometer tenders for national immunization programs, where single-source contracts now dominate volume allocation.
Africa Digital Thermometer Market Segmentation
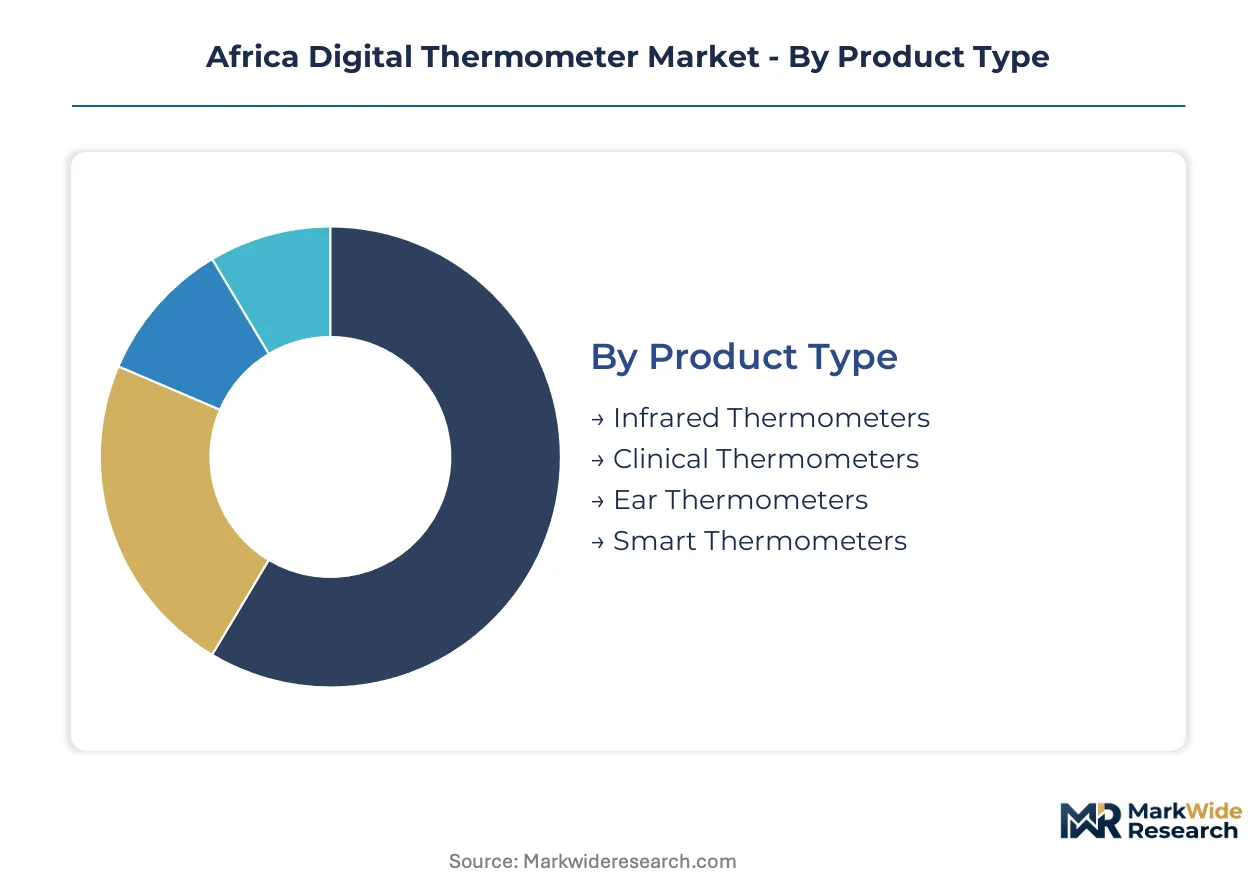
Segmentation reveals how infrared protocols and connectivity standards are fragmenting procurement patterns across African healthcare systems. Each dimension exposes different margin pools, from bulk hospital tenders to mobile money-enabled consumer channels.
Product Type:
Volume concentrates in non-contact devices while premium pricing attaches to connected clinical-grade units.
- Infrared Thermometers:These devices deploy thermopile sensors to detect thermal radiation from skin surfaces without physical contact. Nigerian port authorities and Johannesburg airport terminals deploy these for mass passenger screening during infectious disease containment protocols. Demand concentrates in high-throughput institutional settings where hygiene protocols prohibit contact-based measurement.
- Smart Thermometers:Bluetooth Low Energy connectivity enables seamless data transmission to telemedicine platforms and electronic health records. Kenyan urban middle-class consumers use these for remote pediatric monitoring, integrating with M-Pesa-enabled subscription health services. This segment gains share fastest as home healthcare infrastructure expands.
- Clinical Thermometers:Precision thermistor-based devices designed for oral, rectal, or axillary measurement in clinical settings.
- Ear Thermometers:Tympanic membrane infrared sensors deliver rapid core temperature readings for hospital triage units.
Today's leader: Infrared Thermometers. Tomorrow's challenger: Smart Thermometers.
End User:
Application context determines specification requirements, with industrial monitoring demanding wider temperature ranges than clinical diagnostics.
- Home Healthcare:Self-monitoring applications drive unit volume through retail pharmacy and mobile commerce channels. Urban consumers in Nairobi and Lagos purchase Bluetooth-enabled devices for family fever tracking, bypassing traditional clinic visits for routine temperature assessment. This segment climbs the fastest as telemedicine adoption accelerates.
- Hospitals:Centralized procurement offices in Abuja and Nairobi teaching hospitals negotiate bulk supply agreements with technical evaluation capabilities. These institutions mandate ISO 13485 certification and WHO prequalification for tender eligibility, concentrating margin pools among compliant suppliers.
- Clinics:Primary care facilities across East African Community member states require durable, battery-operated devices for rural deployment.
- Industrial Facilities:Manufacturing and logistics operations in Ethiopian industrial parks use ruggedized thermometers for equipment monitoring and worker health screening.
Hospital procurement commands premium pricing. Home healthcare unlocks volume scale.
Distribution Channel:
Channel selection reflects customer technical sophistication and procurement urgency.
- Direct Sales:Large hospital groups in Nigeria and Kenya establish centralized procurement offices, displacing traditional medical device distributors. Single-source contracts for national immunization programs dominate volume allocation, with technical evaluation teams assessing sensor accuracy and calibration certificates directly.
- Online Retail:E-commerce platforms and mobile money integration enable direct-to-consumer sales previously dependent on pharmacy retail. M-Pesa and similar payment systems unlock Kenyan and Tanzanian markets for manufacturers bypassing traditional distribution markups.
- Pharmacies:Community retail networks remain critical for emergency purchases and rural access where digital infrastructure is limited.
- Medical Supply Stores:Specialized distributors serve small clinics and individual practitioners with technical support and calibration services.
Direct sales capture institutional margin. Online retail reshapes consumer access.
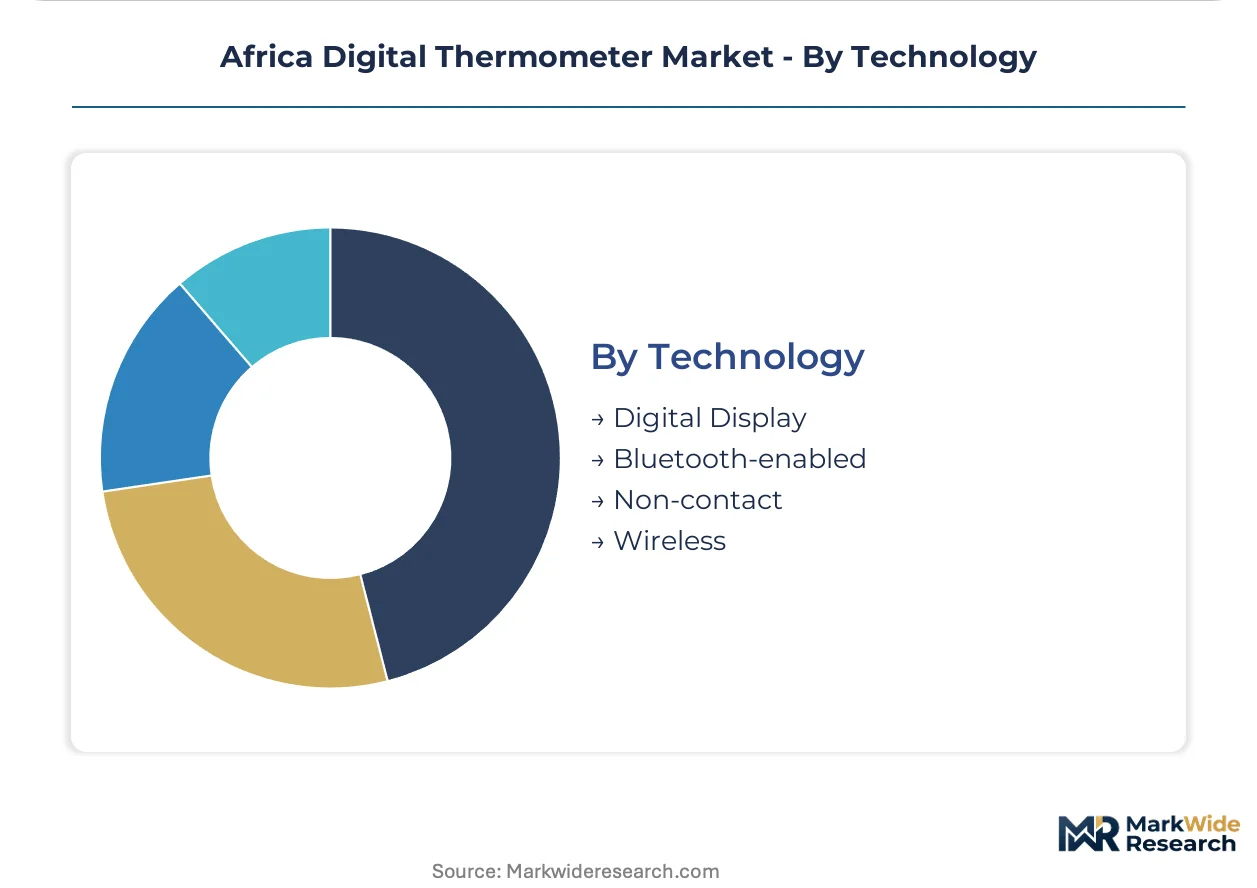
Technology:
Display and connectivity specifications segment pricing tiers and use-case compatibility.
- Bluetooth-enabled:Wireless data transmission protocols integrate with remote patient monitoring platforms and electronic health records. Ghanaian hospitals deploy these for post-surgical fever tracking, enabling continuous monitoring without nursing staff intervention. This technology shows steepest expansion trajectory as healthcare digitization advances.
- Non-contact:Infrared sensing eliminates cross-contamination risk in high-frequency screening environments. Lagos port facilities and Johannesburg transport hubs automate passenger processing with these devices, reducing manual staffing requirements while maintaining detection sensitivity.
- Digital Display:LCD or LED readouts provide immediate visual confirmation for point-of-care diagnostics.
- Wireless:Extended-range connectivity supports centralized monitoring systems in large hospital deployments.
Bluetooth-enabled devices command technology premium. Non-contact protocols dominate institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting assembly capacity toward jurisdictions offering streamlined certification pathways and duty-free raw material access. Manufacturing investment gravitates to countries where WHO prequalification alignment reduces duplicate compliance costs for regional export.
Nigeria
Lagos port authorities deploy multispectral infrared arrays for mass passenger screening, automating fever detection at throughput checkpoints. The National Agency for Food and Drug Administration and Control enforces medical device registration timelines that shape import sequencing. Abuja teaching hospitals concentrate procurement authority for national immunization program tenders.
South Africa
Johannesburg airport terminals integrate non-contact screening infrastructure to reduce manual staffing in transport hubs. The Health Products Regulatory Authority mandates Unique Device Identification labeling for all Class II device imports. Gauteng and Western Cape hospital groups displace traditional distributors through centralized technical evaluation offices.
Kenya
Nairobi's urban middle-class consumers drive Bluetooth-enabled thermometer adoption for remote pediatric monitoring via M-Pesa-integrated telemedicine platforms. The Pharmacy and Poisons Board coordinates with East African Community harmonization initiatives to streamline cross-border registration. Mombasa distribution corridors serve as regional logistics nodes for Horn of Africa markets.
Egypt
Industrial park incentives attract assembly operations targeting duty-free raw material imports for regional device production. The national pharmaceutical regulator aligns medical device oversight with African Medicines Regulatory Harmonization standards. Cairo-Alexandria manufacturing clusters supply North African and Levantine distribution networks.
Ethiopia
Ethiopian industrial zones offer ten-year tax holidays for medical device assemblers serving COMESA export markets. The country's quality infrastructure authority builds ISO 13485 certification capacity to reduce compliance lead times. Addis Ababa-based operations target underserved primary care networks across the Horn of Africa.
Africa Digital Thermometer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue connectivity-enabled specialization and regional assembly partnerships. Market structure fragments across multinational device manufacturers, regional distributors, and local assemblers leveraging industrial zone incentives. Three archetypes dominate: precision sensor specialists, connectivity platform integrators, and cost-optimized regional assemblers. Capacity expansion and certification pre-positioning constitute the dominant competitive moves as WHO prequalification requirements harden.
Within the multinational tier, Omron Corporation and Terumo Corporation exemplify established device manufacturers with distribution depth across East and West African markets. Microlife Corporation occupies a position among precision-focused specialists emphasizing clinical-grade infrared protocols. These entities anchor competitive dynamics through divergent positioning: scale-driven channel presence versus technical specialization in measurement accuracy.
| Leading Market Players |
|---|
| Omron Corporation |
| Terumo Corporation |
| Microlife Corporation |
| Exergen Corporation |
| Geratherm Medical AG |
| Ametek, Inc. |
| A&D Company, Limited |
| Actherm Inc. |
| American Diagnostic Corporation |
| Others |
Value Network & Pricing Analysis
Thermopile sensor and lithium cell costs cascade through three distinct pricing tiers, with East Asian component concentration compressing margins for African assemblers while WHO prequalification requirements sustain premium pricing for certified imports.
Pricing Analysis
Distributor margins of 25-35% separate hospital procurement channels from retail pharmacy markups in Nigerian and Kenyan urban centers. Pricing stratifies across WHO-prequalified, CE-marked, and uncertified economy tiers, with certification grade commanding the steepest premium differential. Cost compression in the economy segment intensifies as Ethiopian industrial zone assemblers scale output for COMESA export markets. Home healthcare consumers in Nairobi and Lagos exhibit highest price sensitivity, while Abuja teaching hospital procurement offices prioritize technical compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from South African hospital groups and Nigerian national immunization programs mandate qualified suppliers in both East Asia and regional African hubs. Component supply draws from Chinese thermopile manufacturers, South Korean lithium cell producers, and Egyptian printed circuit board assemblers. Single-source vulnerability concentrates in infrared sensor modules, where Taiwanese and Japanese suppliers dominate precision manufacturing. Distribution runs through Mombasa and Lagos port corridors, with Johannesburg serving as southern African redistribution node.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa digital thermometer market represents a late-cycle quality story as hospital procurement shifts toward Bluetooth-enabled, UDI-compliant devices that command sustained margin premiums over commodity infrared units.
For Market Incumbents: Deepen backward integration into thermopile sensor sourcing to reduce exposure to East Asian supply concentration and ISO 13485 auditor scarcity. Anchor capacity expansion in Ethiopian industrial zones to capture COMESA duty-free export advantages while pre-positioning for African Medicines Regulatory Harmonization streamlined approvals. For New Entrants and Emerging Players: Capture the wearable temperature monitoring white space in Ghanaian and Kenyan hospital post-surgical wards, where continuous fever tracking demand outpaces incumbent product portfolios. Penetrate via M-Pesa-integrated direct-to-consumer channels that bypass traditional pharmacy distribution markups in East African markets. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 certification timelines stretch 8-14 months and calibration infrastructure gaps force costly South African or European logistics. Target acquisition archetypes include regional assemblers with established Ethiopian or Egyptian industrial zone operations and pre-qualified WHO documentation. Watch for inflection when African Medicines Regulatory Harmonization achieves substantive cross-border registration mutual recognition.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks public sector tender eligibility across Nigerian and Kenyan national immunization programs. |
| East African Community Registration Harmonization | Reduces duplicate compliance costs for manufacturers targeting Kenya, Tanzania, and Uganda simultaneously. |
| Ethiopian Industrial Zone Assembly | Captures ten-year tax holidays and duty-free raw material access for COMESA export manufacturing. |
| Bluetooth Low Energy Platform Integration | Enables M-Pesa subscription health service partnerships in Kenyan home healthcare consumer segments. |
| Unique Device Identification Compliance | Satisfies South African Health Products Regulatory Authority mandates for Gauteng and Western Cape hospital procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts administrators, and medical device regulatory affairs specialists with secondary validation against WHO prequalification databases, East African Community trade statistics, and South African Health Products Regulatory Authority registration filings. Bottom-up unit demand modeling and top-down market size triangulation cross-verified segmentation outputs.
Comparable-period anchoring tied projection assumptions to historical infrared thermometer adoption curves and smart device penetration patterns across the analysis window. Segmentation dimensions modeled include product type, end-user application, distribution channel, and technology connectivity standard, with CAGRs derived from weighted average of demand elasticity coefficients and replacement cycle compression factors. Forecast inputs incorporated telemedicine platform expansion rates and mobile money penetration thresholds.
Underlying measurement precision varies by segment; hospital procurement and home healthcare channels carry tighter precision than industrial facility applications due to more consolidated reporting sources. Forecasts reflect documented assumptions regarding WHO prequalification timeline acceleration and East African Community regulatory harmonization progress. Deviation in lithium cell supply chain disruption or African Medicines Regulatory Harmonization implementation delays would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Array Instruments Market
Analytical Instruments
Energy Dispersive X-Ray Spectrometer Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Industrial X-Ray CT Inspection Systems for Complex Metal Components Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Global Atomic Absorption Spectrometer Market
Analytical Instruments
EPR (ESR) Spectrometer Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Global Mass Spectrometry Market