
 Global Artificial Sweeteners Market | 2026-2036
Global Artificial Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Sweeteners Market Analysis
The artificial sweetener supply base is consolidating around two distinct quality tiers. High-purity stevia extracts and fermentation-derived molecules command formulation partnerships with multinational beverage companies, while commodity-grade aspartame and acesulfame K compete on bulk pricing. Cargill Incorporated leverages its integrated agricultural supply chain to sustain cost advantages in stevia extraction. Tate & Lyle PLC anchors European demand through specialized texturizer-sweetener blends for bakery applications. Ajinomoto Co., Inc. dominates aspartame production through proprietary enzymatic processes that reduce manufacturing waste.
Artificial sweeteners are high-intensity sugar substitutes synthesized or extracted to deliver sweetness at fractions of caloric load, typically requiring stability across pH ranges of 2.0 to 7.0 and thermal thresholds exceeding 80°C for beverage pasteurization. Their primary commercial purpose is enabling food and beverage manufacturers to achieve labeled sugar reduction targets without sacrificing sensory profiles. Sucralose leads in thermal stability applications such as baked goods and confectionery where processing temperatures degrade competing molecules. Stevia extracts represent the fastest-growing product type as clean-label preferences among food manufacturers displace synthetic alternatives in premium positioning. Powder and liquid forms split by application velocity, with liquid concentrates gaining share in fountain beverage systems while powder maintains dominance in dry-mix manufacturing.
The FDA governs artificial sweetener safety through food additive petitions and acceptable daily intake certifications, while EFSA conducts parallel re-evaluations that periodically restrict or expand approved uses across EU member states. China's NMPA and SAMR enforce national food safety standards that increasingly align with CODEX specifications for sweetener purity thresholds. Divergent regulatory timelines between these jurisdictions create compliance complexity for multinational suppliers operating across formulation facilities. Stakeholders must monitor pending EFSA re-evaluations of legacy sweeteners and evolving Chinese GB standard revisions to anticipate reformulation mandates and qualification requirements.
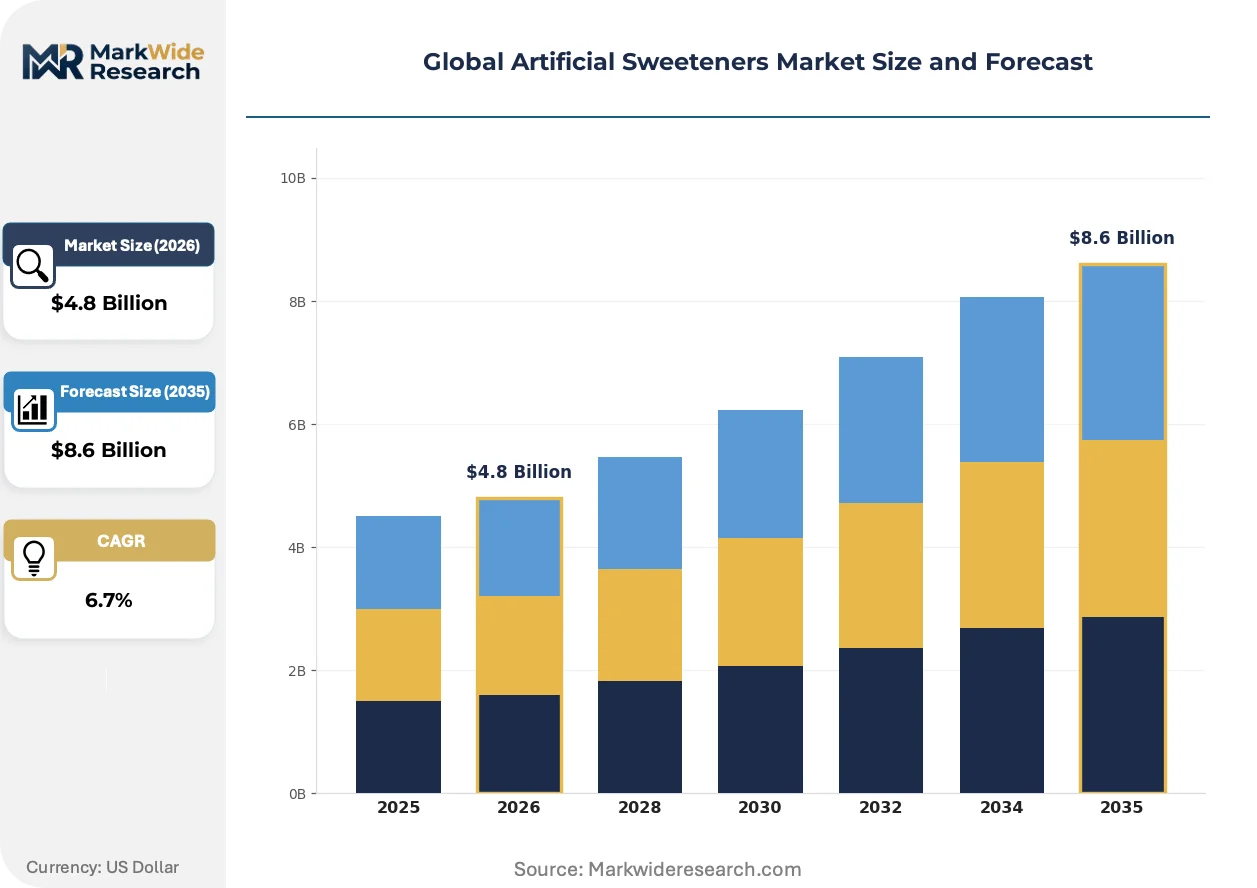
Market Dynamics
Beverage reformulation mandates are compressing formulation cycles as manufacturers race to meet sugar-reduction targets ahead of divergent regulatory deadlines across FDA, EFSA, and NMPA jurisdictions.
Growth Catalysts
- EFSA Re-evaluation Windows:Pending safety reviews of legacy sweeteners are accelerating pre-emptive reformulation by European food manufacturers seeking to avoid supply disruptions.
- China's Low-Calorie Portfolio Expansion:Domestic food producers in Shanghai and Guangdong are scaling stevia procurement to serve health-positioned product lines.
- Fermentation-Derived Molecule Platforms:Bioprocess advances are reducing production costs for rare sugar alcohols, unlocking bakery and confectionery applications previously reserved for synthetic alternatives.
Market Restraints
- Stevia Leaf Input Volatility:Weather-dependent agricultural yields in Paraguay and China create raw material price instability for high-purity extracts.
- Thermal Degradation Limits:Aspartame's instability above 80°C restricts its deployment in ultra-high-temperature processed beverages and baked goods.
- Divergent ADI Thresholds:FDA and EFSA acceptable daily intake disparities for sucralose and acesulfame K force manufacturers to maintain multiple formulation specifications.
Strategic Opportunities
- India's FSSAI Clean-Label Pathway:New food safety standards are creating first-mover advantages for natural sweetener suppliers in Mumbai and Delhi NCR processed food markets.
- Fountain Beverage System Concentrates:Liquid stevia formulations are capturing share in quick-service restaurant dispensing equipment previously dominated by high-fructose corn syrup.
- EU Green Deal Packaging Convergence:Biodegradable sachet requirements are favoring dry-blend sweetener formats that reduce moisture-barrier packaging intensity.
Industry Challenges
- Cross-Jurisdictional Compliance Talent:Shortage of regulatory affairs specialists capable of navigating simultaneous FDA, EFSA, and SAMR petition processes is extending product launch timelines.
- Clean-Label Certification Backlogs:Third-party non-GMO and organic verification queues for stevia supply chains are creating 8-14 month qualification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Sweeteners Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspartame, Sucralose, Acesulfame K, Stevia Form: Powder, Liquid, Granular, Tablet Application: Beverages, Bakery, Dairy Products, Confectionery End User: Food Manufacturers, Beverage Companies, Restaurants, Households |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, Ajinomoto Co., Inc., Roquette Frères, DuPont, JK Sucralose Inc., PureCircle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Sweeteners Market Emerging Trajectories
Biotechnology platforms and regulatory harmonization pressures are restructuring how sweetener molecules reach commercial scale, with implications for cost curves and geographic production allocation.
Enzymatic glycosylation processes are expanding into stevia extract modification, enabling manufacturers to convert bitter-tasting Reb A into cleaner-tasting Reb M and Reb D variants. North American beverage formulators are adopting these ingredients at accelerated rates for zero-sugar carbonated drinks. The technology is expanding into applications previously blocked by sensory limitations, compressing the addressable market for synthetic high-intensity sweeteners.
EFSA's systematic re-evaluation of food additives under the 2008 regulation is tightening purity specifications for legacy sweeteners across EU member states. Manufacturers must now submit updated toxicological dossiers for acesulfame K and aspartame to maintain authorized uses. Bakery and tabletop sweetener segments in Germany and France are responding by accelerating stevia and sucralose substitution programs ahead of potential restriction dates.
Direct procurement relationships between beverage multinationals and fermentation facilities are displacing traditional ingredient distributor intermediaries in sweetener sourcing. Concentrated buyer power in Atlanta, Purchase, and Atlanta headquarters is compressing margins for regional distributors while securing volume commitments for novel molecule suppliers. This pattern is most visible in North American and Western European markets where fountain beverage concentration is highest.
Global Artificial Sweeteners Market Segmentation
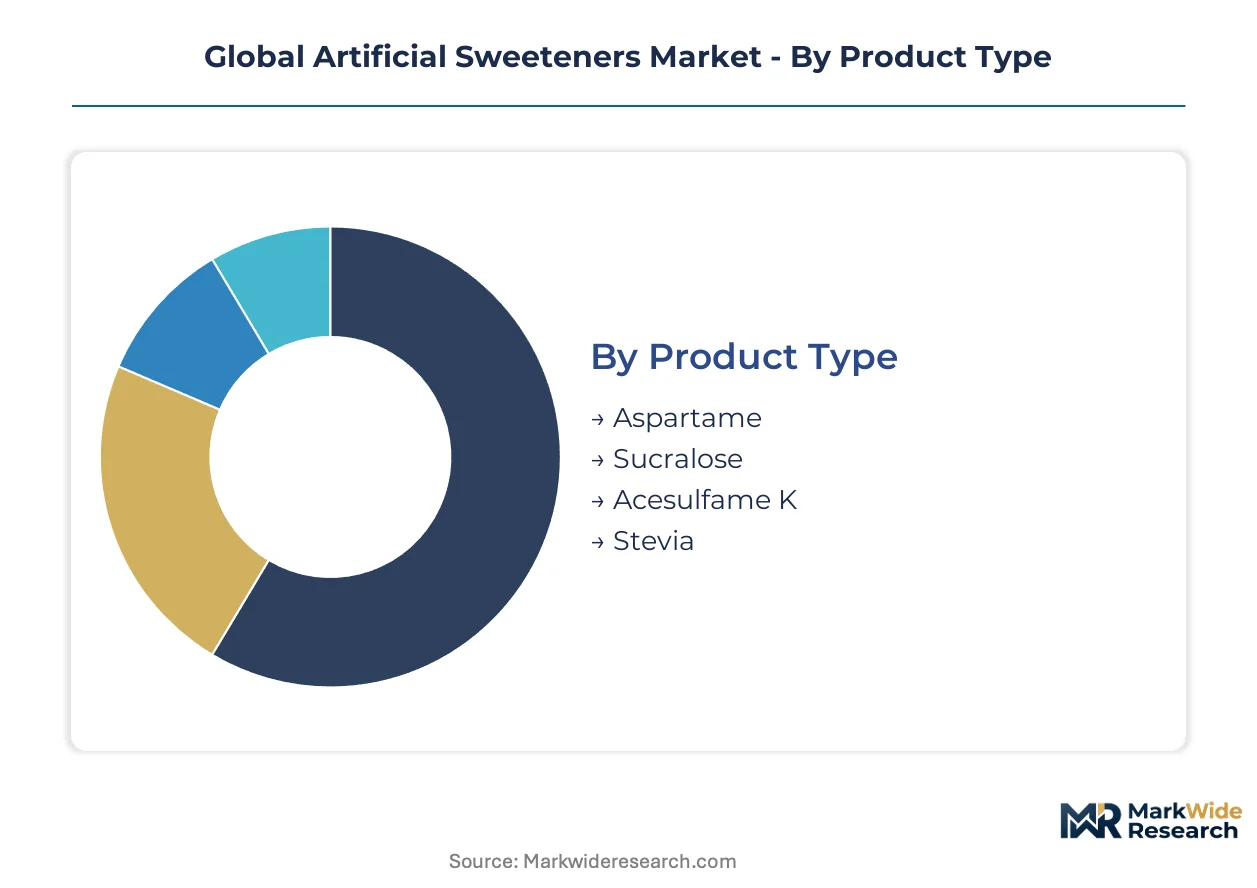
Artificial sweetener procurement patterns diverge sharply across product chemistry, physical form, and end-use specifications. Manufacturers configure supply contracts around thermal stability thresholds, clean-label positioning, and formulation integration complexity.
Product Type:
Buyers in this category sort by thermal tolerance requirements and label positioning rather than sweetness intensity alone.
- Stevia:High-purity glycoside extracts from Stevia rebaudiana leaves deliver zero-calorie sweetness with plant-derived positioning. Demand concentrates in Shanghai and Guangdong beverage facilities as domestic Chinese manufacturers expand health-positioned portfolios to meet clean-label preferences.
- Sucralose:Chlorinated sucrose derivative maintains stability above 150°C, enabling deployment in ultra-high-temperature processed beverages and baked goods where aspartame degrades. European bakery manufacturers in Germany and France are accelerating procurement ahead of EFSA re-evaluation deadlines for legacy synthetic alternatives.
- Aspartame:Methyl ester of dipeptide combining phenylalanine and aspartic acid; requires cold-chain handling and pH below 6.0 to prevent hydrolysis.
- Acesulfame K:Heat-stable oxathiazinone dioxide with rapid sweetness onset; frequently blended with other sweeteners to mask aftertaste profiles.
Volume sits with aspartame; growth tilts toward stevia.
Form:
Physical format selection tracks manufacturing process integration and moisture sensitivity requirements.
- Powder:Spray-dried crystalline formats dominate dry-mix manufacturing for tabletop packets and baking applications. North American quick-service restaurant chains specify powder concentrates for fountain beverage systems requiring extended shelf stability.
- Liquid:Aqueous solutions enable precise dosing in continuous-process beverage lines and reduce dust exposure in manufacturing facilities. Atlanta and Purchase headquarters of multinational beverage corporations are directing procurement toward liquid stevia formulations for zero-sugar carbonated drink portfolios.
- Granular:Free-flowing agglomerated particles blend uniformly with bulk ingredients in industrial bakery operations.
- Tablet:Compressed single-serve formats serve tabletop and foodservice dispensing applications with portion-controlled dosing.
Granular and tablet formats anchor established applications; liquid concentrates are climbing the fastest as fountain system retrofits accelerate.
Application:
End-use segments separate by thermal processing intensity and pH environment constraints.
- Beverages:Carbonated soft drinks, flavored waters, and ready-to-drink teas constitute the largest addressable volume. Reformulation mandates from FDA, EFSA, and China's SAMR are compressing development cycles as manufacturers race to meet divergent sugar-reduction deadlines.
- Bakery:Cookies, cakes, and pastries require heat-stable molecules surviving oven temperatures exceeding 180°C. Sucralose and acesulfame K dominate this segment while stevia extracts gain traction in premium positioning.
- Confectionery:Hard candies and chewing gums depend on thermal stability during cooking and extrusion processes.
- Dairy Products:Yogurts and flavored milk applications favor high-intensity sweeteners compatible with fermentation pH ranges and cold processing.
Beverages command procurement volume; bakery applications show steepest expansion trajectory as EFSA re-evaluations accelerate substitution programs.
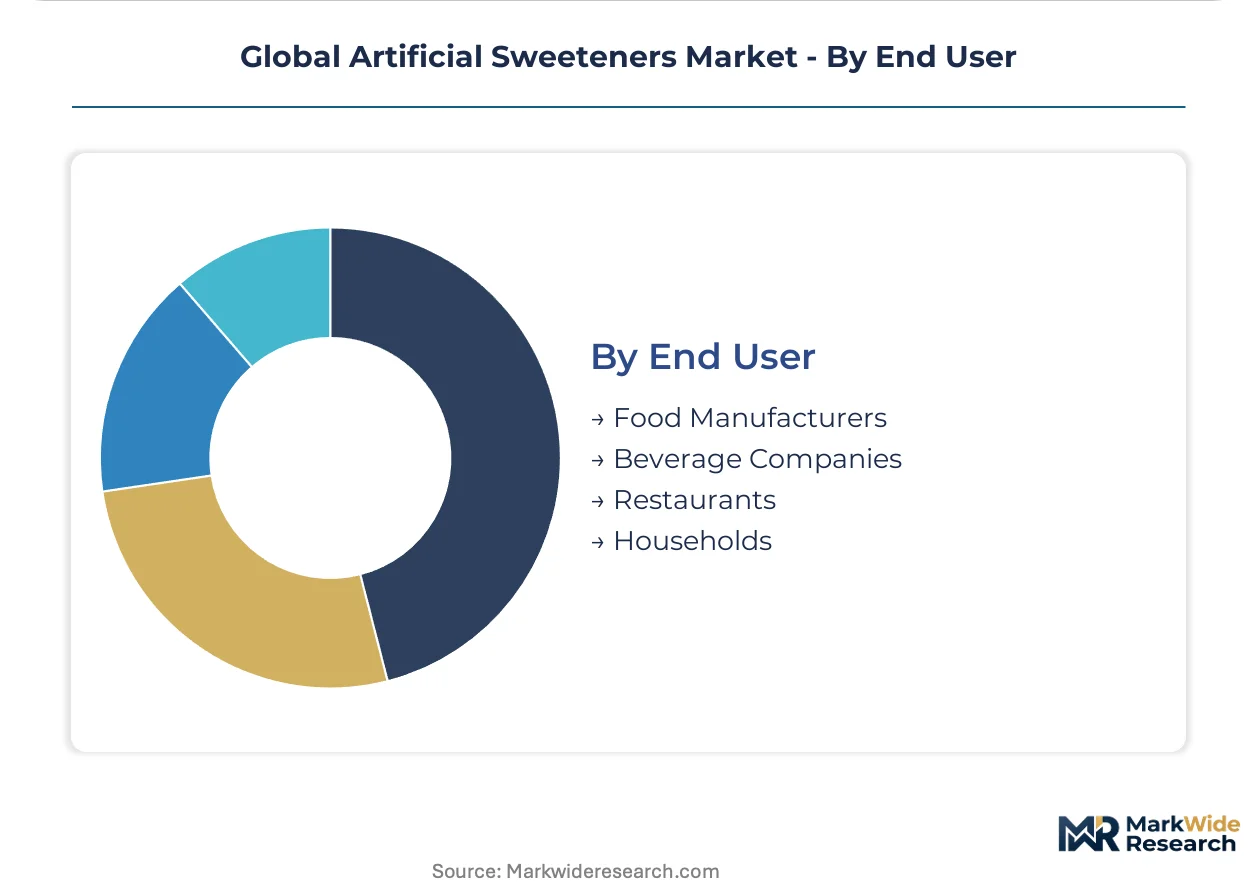
End User:
Customer scale determines contract structure, with direct procurement relationships displacing distributor intermediaries at the largest volume tiers.
- Beverage Companies:Multinational corporations with concentrated headquarters in Atlanta and Purchase negotiate multi-year volume commitments with fermentation facilities and extraction operations. These buyers specify purity thresholds and sustainability certifications that filter supplier qualification.
- Food Manufacturers:Processed food producers in Shanghai, Mumbai, and Delhi NCR configure sweetener blends to achieve labeled sugar reduction targets without reformulation of texture and mouthfeel profiles.
- Restaurants:Quick-service and fast-casual chains specify fountain system concentrates with standardized sweetness delivery across franchise locations.
- Households:Retail tabletop sweetener purchasers respond to clean-label positioning and portion-controlled packaging formats.
Procurement volume concentrates with beverage companies; food manufacturers in emerging markets are gaining share fastest as low-calorie portfolio expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Guangdong beverage facilities are scaling stevia procurement as domestic Chinese manufacturers expand health-positioned portfolios. Reformulation mandates from the FDA, EFSA, and China's SAMR are compressing development cycles across formulation facilities.
United States
Atlanta and Purchase headquarters of multinational beverage corporations direct procurement toward liquid stevia formulations for zero-sugar carbonated drink portfolios. FDA acceptable daily intake certifications govern sweetener safety through food additive petitions. North American quick-service restaurant chains specify powder concentrates for fountain beverage systems requiring extended shelf stability.
China
Domestic food producers in Shanghai and Guangdong are scaling stevia procurement to serve health-positioned product lines. NMPA and SAMR enforce national food safety standards that increasingly align with CODEX specifications for sweetener purity thresholds. Yangtze River Delta extraction facilities are expanding enzymatic glycosylation capacity for Reb M and Reb D variant production.
Germany
Bakery and tabletop sweetener segments are accelerating stevia and sucralose substitution programs ahead of potential EFSA restriction dates. EFSA conducts parallel re-evaluations that periodically restrict or expand approved uses across EU member states. Bavaria and North Rhine-Westphalia processed food manufacturers are reformulating to meet EU Green Deal packaging convergence requirements.
India
Processed food producers in Mumbai and Delhi NCR configure sweetener blends to achieve labeled sugar reduction targets. FSSAI clean-label pathways are creating first-mover advantages for natural sweetener suppliers in emerging processed food markets. Maharashtra and Gujarat food manufacturing corridors are expanding low-calorie portfolio production for domestic and export markets.
Japan
Fermentation-derived molecule platforms are reducing production costs for rare sugar alcohols in bakery and confectionery applications. METI industrial policy supports bioprocess advances for domestic sweetener production. Kanto and Kansai food technology clusters are developing specialized texturizer-sweetener blends for precision formulation.
Global Artificial Sweeteners Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across distinct quality tiers in artificial sweetener supply. High-purity stevia extractors and fermentation-derived molecule platforms command formulation partnerships with multinational beverage companies, while commodity-grade synthetic producers compete on bulk pricing. Three strategic archetypes dominate: integrated agricultural processors with captive leaf supply, specialized enzymatic refiners with proprietary glycosylation technology, and fermentation-based bioprocess operators. Competitive moves concentrate on direct procurement relationship cultivation with beverage headquarters and enzymatic process licensing for taste-profile optimization.
Within the integrated agricultural processor tier, Cargill Incorporated and Archer Daniels Midland Company exemplify supply chain control strategies that sustain cost advantages in stevia extraction. Among specialized enzymatic refiners, Ajinomoto Co., Inc. occupies a position representing proprietary process capabilities, while Tate & Lyle PLC anchors European demand through formulation integration expertise. These three entities represent the dominant competitive archetypes structuring procurement negotiations with concentrated beverage buyers.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Ajinomoto Co., Inc. |
| Roquette Frères |
| DuPont |
| JK Sucralose Inc. |
| PureCircle |
| Others |
Supply Flow & Price Mechanics
Stevia leaf procurement costs in Paraguay and China's Yunnan province cascade through extraction facility economics to determine tier placement for high-purity Reb M and Reb D variants versus commodity-grade Reb A extracts. Fermentation-derived molecules from Kanto bioprocess clusters command formulation premiums based on sensory performance benchmarks rather than input tonnage alone.
Pricing Analysis
Value-based pricing anchors on sweetness equivalence ratios and clean-label certification tiers rather than per-kilogram commodity metrics. Three-tier pricing structure across premium, standard, and economy levels separates enzymatically refined glycoside variants from conventional extracts and synthetic alternatives. Price differentiation hinges on FDA food additive petition status and organic certification completion. Cost compression in commodity-grade aspartame is intensifying because Tate & Lyle and Ajinomoto are expanding enzymatic capacity. Quick-service restaurant procurement teams exhibit highest price sensitivity; multinational beverage headquarters in Atlanta and Purchase show lowest sensitivity due to volume commitment structures.
Supply Chain Analysis
Third-party non-GMO and organic verification queues for stevia supply chains are extending qualification timelines and filtering supplier pools before volume contracts execute. Geographic supply concentration centers on Paraguay, China, and Kenya for leaf inputs, with extraction and refining capacity clustering in Yangtze River Delta and Midwest US processing corridors. Raw material dependencies draw from agricultural stevia leaf, corn-derived dextrose for fermentation substrates, and specialized enzyme stocks for glycosylation modification. Single-source vulnerability runs through Paraguayan leaf supply exposed to El Niño precipitation patterns. Distribution runs through direct procurement relationships with beverage headquarters displacing regional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as Cargill and Archer Daniels Midland pursue captive stevia leaf supply to defend margin position against fermentation-based molecule platforms.
For Market Incumbents: Cement formulation integration partnerships with multinational beverage headquarters in Atlanta and Purchase through multi-year volume commitments with Reb M and Reb D exclusivity clauses. Deepen backward integration into Paraguayan and Yunnan leaf supply through contract farming arrangements that lock in agricultural capacity ahead of competitor expansion. The threat of fermentation-derived rare sugar alcohols from Japanese bioprocess clusters demands defensive patent positioning around enzymatic glycosylation methods. For New Entrants and Emerging Players: Fermentation facility operators in India and Southeast Asia represent the most penetrable channel partner type for breaking into beverage formulation pipelines previously dominated by agricultural extractors. Target white-space opportunities in FSSAI-regulated clean-label pathways for Mumbai and Delhi NCR processed food manufacturers seeking stevia alternatives to synthetic sweeteners. A go-to-market angle emphasizing biodegradable sachet-compatible dry-blend formats aligns with EU Green Deal packaging convergence requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap enzymatic refiners with proprietary Reb D production technology in North American and European geographies where EFSA re-evaluation windows are accelerating substitution demand. Long-term viability across the analysis window rests on securing intellectual property positions in taste-profile optimization rather than commodity extraction scale. The signal to watch is EFSA's timeline for acesulfame K and aspartame restriction decisions, which would trigger reformulation procurement surges.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leaf Supply | Cargill's Paraguayan contract farming secures raw material cost advantages against volatile spot markets. |
| Enzymatic Glycosylation Licensing | Ajinomoto's proprietary Reb M conversion technology unlocks premium beverage formulation partnerships. |
| Direct Procurement Relationship Cultivation | Tate & Lyle's Atlanta headquarters presence captures fountain system concentrate specifications from multinational buyers. |
| Fermentation Platform Scale-Up | Roquette Frères' bioprocess advances reduce rare sugar alcohol production costs for bakery applications. |
| Clean-Label Certification Investment | PureCircle's organic verification completion filters supplier pools for EU and North American clean-label procurement. |
Methodological Framework
Trade data from China Customs, FDA food additive petition filings, and EFSA re-evaluation documentation formed the secondary backbone for volume and pricing calibration. Primary interviews with beverage formulation directors, stevia extraction plant managers, regulatory affairs specialists navigating SAMR and EFSA processes, and quick-service restaurant procurement heads combined with secondary validation to triangulate supply chain dynamics. Bottom-up segmentation modeling across product chemistry, physical form, and end-use specifications integrated with top-down macroeconomic trend analysis.
Historical trendline analysis of stevia leaf spot prices, synthetic sweetener contract volumes, and fermentation facility capex cycles established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including thermal stability tier, clean-label positioning, formulation integration complexity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections incorporating EFSA re-evaluation timing and China's low-calorie portfolio expansion rates. Industry-specific forecast inputs included enzymatic glycosylation capacity buildout schedules and fountain beverage system retrofit penetration curves.
Caveats apply where EFSA restriction decisions, El Niño agricultural disruption, or bioprocess breakthroughs in rare sugar alcohol production could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory timeline adherence and clean-label preference persistence. A model refresh is warranted upon material change in EFSA's acesulfame K and aspartame authorization status or significant fermentation cost curve compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Dry Sweeteners Market
Sweeteners
Tagatose Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Europe Starch Sweetener Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Vanilla Sugar Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
White Sugar Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Glucose Syrup Market
Sweeteners
Fructose Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Trehalose Market
Sweeteners
South America Stevia Market