
 Low-Calorie Sweetener Market | 2026-2036
Low-Calorie Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Sweetener Market Intelligence
Food and beverage buyer concentration is decoupling as multinational bottlers diversify supplier rosters while regional craft beverage makers fragment procurement across specialty ingredient distributors. Tate & Lyle PLC leverages its British research campuses to sustain novel sweetener development for reduced-sugar dairy applications. Cargill, Incorporated anchors North American supply through vertically controlled stevia leaf processing in Brazil and Paraguay. Ajinomoto Co., Inc competes on amino acid-based sweetener purity standards that dominate Japanese and Southeast Asian formulation protocols.
Low-calorie sweeteners are high-intensity sugar substitutes, typically 200–600 times sweeter than sucrose, manufactured through fermentation, enzymatic conversion, or extraction from plant materials to deliver sweetness with minimal caloric contribution. Their primary commercial purpose centers on enabling food and beverage manufacturers to achieve sensory parity in reduced-calorie and sugar-free products without compromising consumer acceptance. Stevia-derived glycosides now lead volume growth across beverage applications where clean-label positioning commands shelf-space premiums, while aspartame retains manufacturing scale advantages in carbonated soft drinks despite ongoing regulatory scrutiny. Sucralose occupies stable margin pools in baked goods and confectionery where thermal stability determines technical suitability.
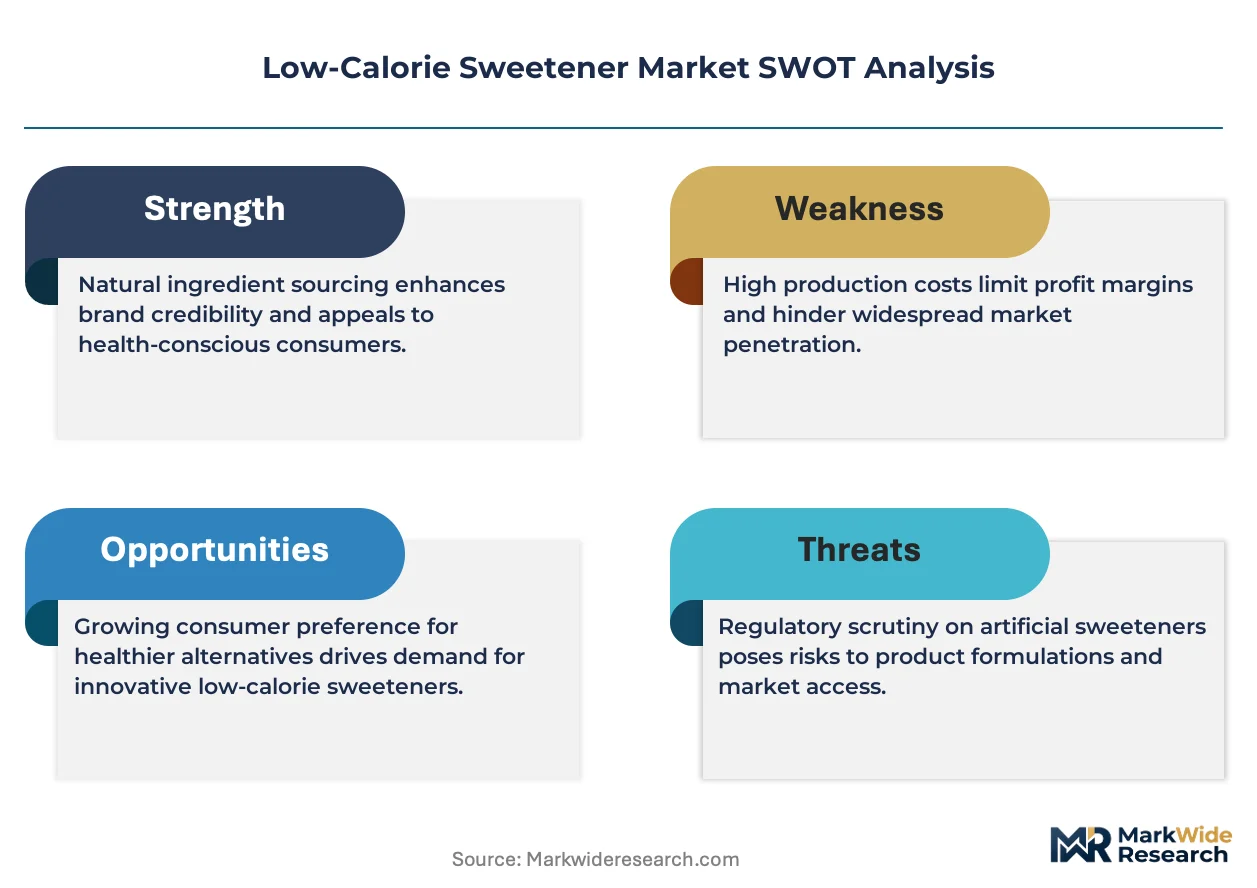
FDA guidance on added sugars disclosure, WHO sugar reduction targets, and EFSA novel food assessments collectively determine which sweetener platforms gain formulation approval and retail access across major economies. The EU's evolving stance on aspartame under EFSA re-evaluation is forcing European manufacturers to accelerate stevia and erythritol substitution timelines. Stakeholders must monitor regulatory divergence between jurisdictions where approval timelines for fermentation-derived sweeteners increasingly determine competitive positioning.
Market Dynamics
Beverage reformulation mandates are compressing procurement cycles as multinational bottlers accelerate sugar reduction timelines ahead of FDA disclosure requirements and WHO intake guidelines. This regulatory convergence is forcing sweetener suppliers to demonstrate clean-label credentials while maintaining cost parity with legacy high-intensity formulations.
Growth Catalysts
- Clean-Label Mandates:FDA updated nutrition labeling requirements pressure beverage manufacturers to disclose added sugars prominently, accelerating stevia and monk fruit adoption in functional drink categories.
- WHO Guidelines:The World Health Organization's sugar reduction targets are reshaping national dietary policies across multiple jurisdictions, expanding addressable demand for high-intensity substitutes in processed foods.
- Fermentation Scale-Up:Bioprocess engineering advances are reducing production costs for rare sugar alcohols, enabling broader formulation access for mid-tier confectionery producers previously locked out of premium sweetener supply chains.
Market Restraints
- Stevia Leaf Concentration:Raw material sourcing clusters in Brazil and Paraguay exposes processors to climate volatility and agricultural commodity cycles that transmit directly to formulation costs.
- Aspartame Scrutiny:EFSA re-evaluation timelines in Europe create formulation uncertainty, forcing manufacturers to maintain dual supply chains for legacy and replacement sweeteners during transition periods.
- Thermal Stability Limitations:Stevia-derived glycosides degrade under high-temperature processing, restricting deployment in baked goods where sucralose retains technical dominance despite clean-label liabilities.
Strategic Opportunities
- Fermentation-Derived Platforms:Precision fermentation of rare glycosides enables cost-competitive production of steviol molecules previously limited to extraction economics, opening premium beverage segments.
- Specialty Dairy Reformulation:Reduced-sugar yogurt and flavored milk categories remain underpenetrated by clean-label sweeteners, presenting first-mover advantages for suppliers with dairy-specific sensory solutions.
- Direct-to-Brand Distribution:E-commerce ingredient platforms are disintermediating traditional distributor networks, allowing specialty sweetener developers to capture margin previously allocated to regional chemical distributors.
Industry Challenges
- Sensory Scientist Scarcity:Formulation expertise bridging food science and consumer preference analytics commands premium compensation, constraining mid-size ingredient houses' R&D throughput.
- Novel Food Approval Timelines:EFSA novel food assessments for fermentation-derived sweeteners extend 18-24 months, delaying revenue recognition for biotech entrants despite technical validation.
- Legacy Equipment Retrofit Costs:Powder handling systems designed for sucrose or aspartame require capital-intensive modification to accommodate hygroscopic sugar alcohols without caking or flow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Sweetener Market |
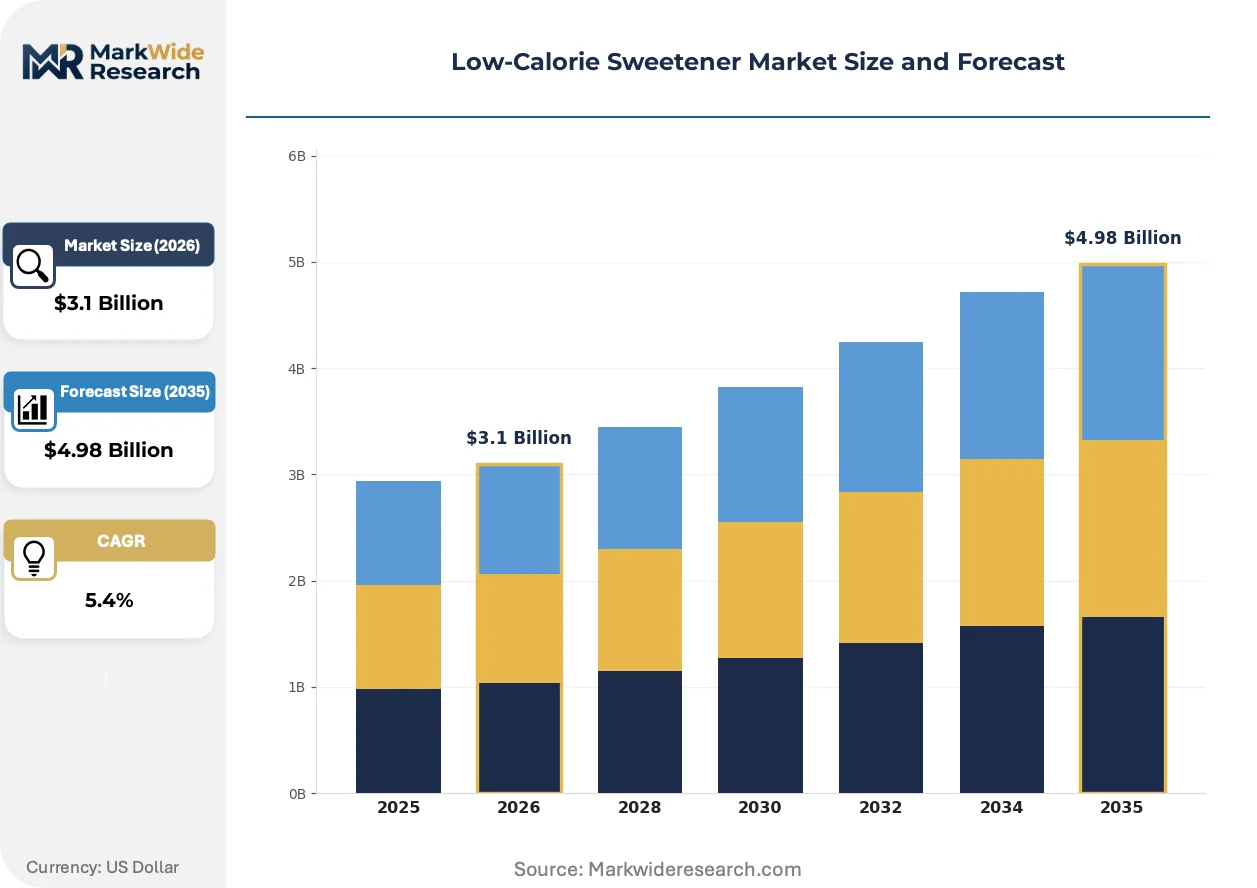
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspartame, Stevia, Sucralose, Erythritol Application: Beverages, Baked Goods, Dairy Products, Confectionery Form: Powder, Liquid, Granular, Tablet Distribution Channel: Online Retail, Supermarkets, Health Stores, Foodservice |
| Companies Covered | Tate & Lyle PLC, Cargill, Incorporated, Archer-Daniels-Midland Company, Ingredion Incorporated, Roquette Freres SA, Ajinomoto Co., Inc, DuPont de Nemours, Inc., Celanese Corporation, NutraSweet Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Sweetener Market Strategic Shifts & Innovations
Bioprocess innovation and regulatory disclosure mandates are converging to reshape competitive positioning across the sweetener value chain. Suppliers must now demonstrate both technical performance and transparent provenance to secure formulation slots in reformulating product portfolios.
Enzymatic glycoside modification is integrating stevia-derived molecules into beverage systems with improved temporal sweetness profiles. Mid-size functional drink brands are adopting these enhanced extracts at accelerated pace to differentiate against mass-market competitors. This enzymatic refinement is compressing the performance gap between natural and synthetic high-intensity options, forcing incumbents to defend position through manufacturing scale rather than sensory superiority.
EFSA novel food assessments are tightening evidentiary requirements for fermentation-derived sweeteners entering European formulation protocols. The industrial consequence is extended approval timelines and elevated regulatory affairs expenditure for biotech entrants. Japanese and Southeast Asian markets are responding faster, with PMDA and national food safety frameworks accepting pilot-scale safety data that EFSA demands at commercial volumes.
Ingredient procurement patterns are fragmenting as craft beverage makers bypass consolidated distributors to source directly from specialty extractors. Regional kombucha and adaptogenic drink producers are establishing captive supplier relationships that lock in exclusive glycoside blends. This channel disintermediation is most visible in California and Colorado, where vertically integrated beverage startups are building formulation teams with direct supplier negotiation capabilities previously reserved for multinational procurement functions.
Low-Calorie Sweetener Market Segmentation
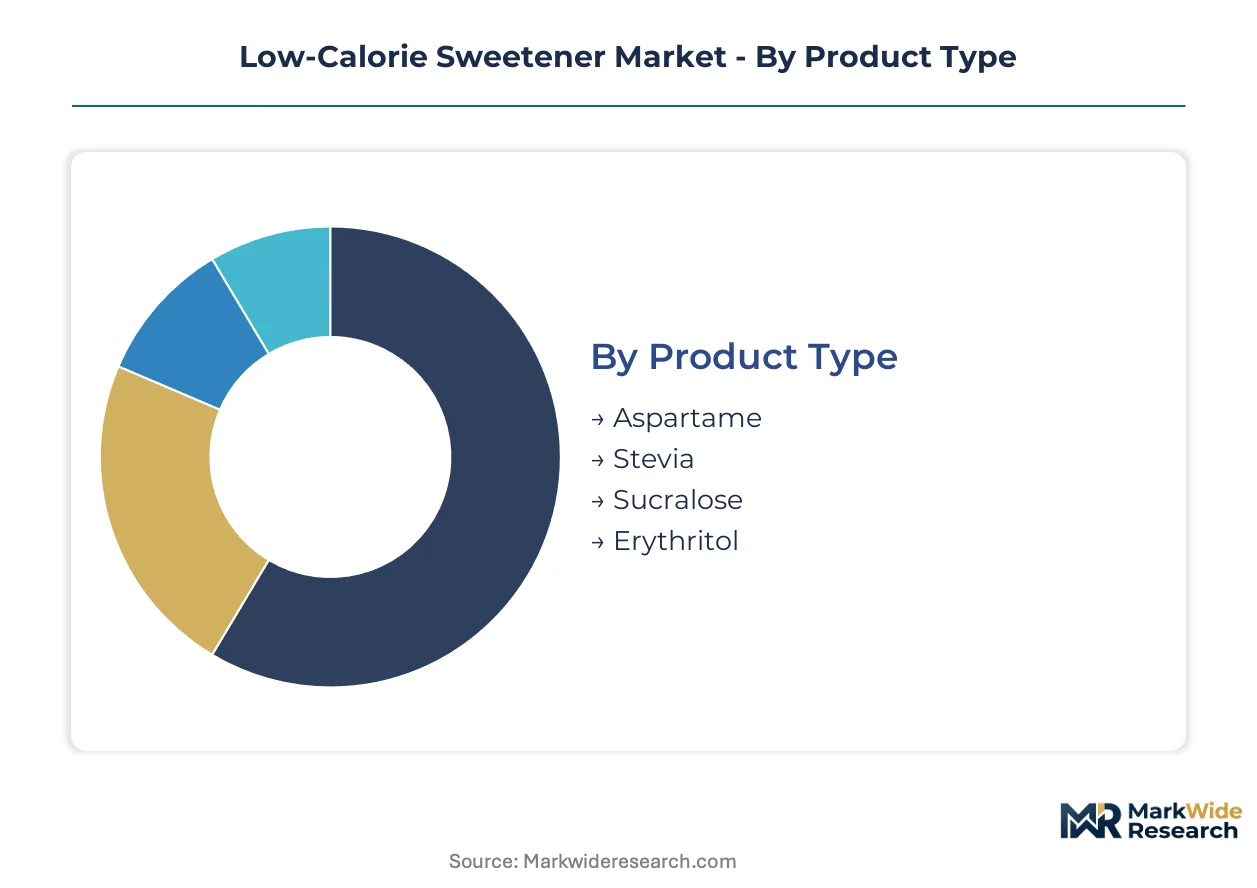
Segmentation reveals how capital deployment, regulatory exposure, and technical requirements fragment procurement strategies across sweetener categories. Manufacturers optimize formulation portfolios by matching intensity profiles, thermal stability, and clean-label positioning to specific end-use constraints.
Product Type:
Capital intensity varies sharply across production platforms, with fermentation and extraction-based processes demanding substantially different fixed-asset footprints than chemical synthesis routes.
- Stevia:Leaf extraction and bioconversion of steviol glycosides requires agricultural sourcing infrastructure plus enzymatic refinement capacity. Demand concentrates in United States functional beverage formulations where FDA disclosure mandates on added sugars accelerate clean-label substitution.
- Aspartame:Chemical synthesis via L-phenylalanine and L-aspartic acid coupling operates at massive scale with mature process economics. Carbonated soft drink manufacturers in legacy markets retain this platform despite EFSA re-evaluation uncertainty forcing dual-supply maintenance.
- Sucralose:Chlorination of sucrose delivers thermal stability unmatched by natural alternatives, securing baked goods and confectionery slots where high-temperature processing degrades competing molecules.
- Erythritol:Fermentation-derived sugar alcohol production scales through yeast-based bioprocesses with crystallization finishing; hygroscopicity challenges require modified powder handling systems versus legacy sweetener infrastructure.
Stevia absorbs the bulk of installed capacity expansion investment; erythritol is expanding most quickly through fermentation scale-up.
Application:
End-use segmentation tracks reformulation urgency, with beverage manufacturers facing the most compressed procurement cycles ahead of regulatory disclosure deadlines.
- Beverages:Liquid and carbonated drink systems demand water-soluble, stable molecules with clean temporal sweetness profiles. United States bottlers dominate procurement volume as FDA added-sugar labeling forces rapid portfolio overhaul.
- Baked Goods:Thermal processing above 150°C eliminates most natural high-intensity options; sucralose and acesulfame potassium retain formulation dominance despite clean-label liabilities in premium positioning.
- Dairy Products:Reduced-sugar yogurt and flavored milk categories present underpenetrated opportunity; protein-sweetener interaction complexity has slowed clean-label adoption versus beverage analogues.
- Confectionery:Hard candy and chocolate applications require precise control over crystallization behavior and mouthfeel; sugar alcohol blends with high-intensity top-notes address bulk replacement challenges.
Beverages command the largest absolute procurement spend; dairy products present the steepest expansion trajectory as clean-label solutions mature.
Form:
Physical format selection determines handling infrastructure requirements, powder flow properties, and dosing precision across manufacturing environments.
- Powder:Spray-dried and crystalline formats dominate high-volume manufacturing; hygroscopicity management requires climate-controlled storage and modified pneumatic conveying systems.
- Liquid:Pre-dissolved concentrates simplify beverage batching operations and enable precise pump-based dosing; preservative systems address microbial stability in aqueous matrices.
- Granular:Agglomerated particles improve flowability and reduce dusting versus fine powders; table-top and small-batch foodservice applications favor this handling convenience.
- Tablet:Compressed single-serve formats target direct-to-consumer channels and foodservice portion control; excipient selection affects dissolution rates in cold versus hot applications.
Powder formats retain the dominant installed processing base; liquid concentrates are gaining share fastest in high-speed beverage manufacturing.
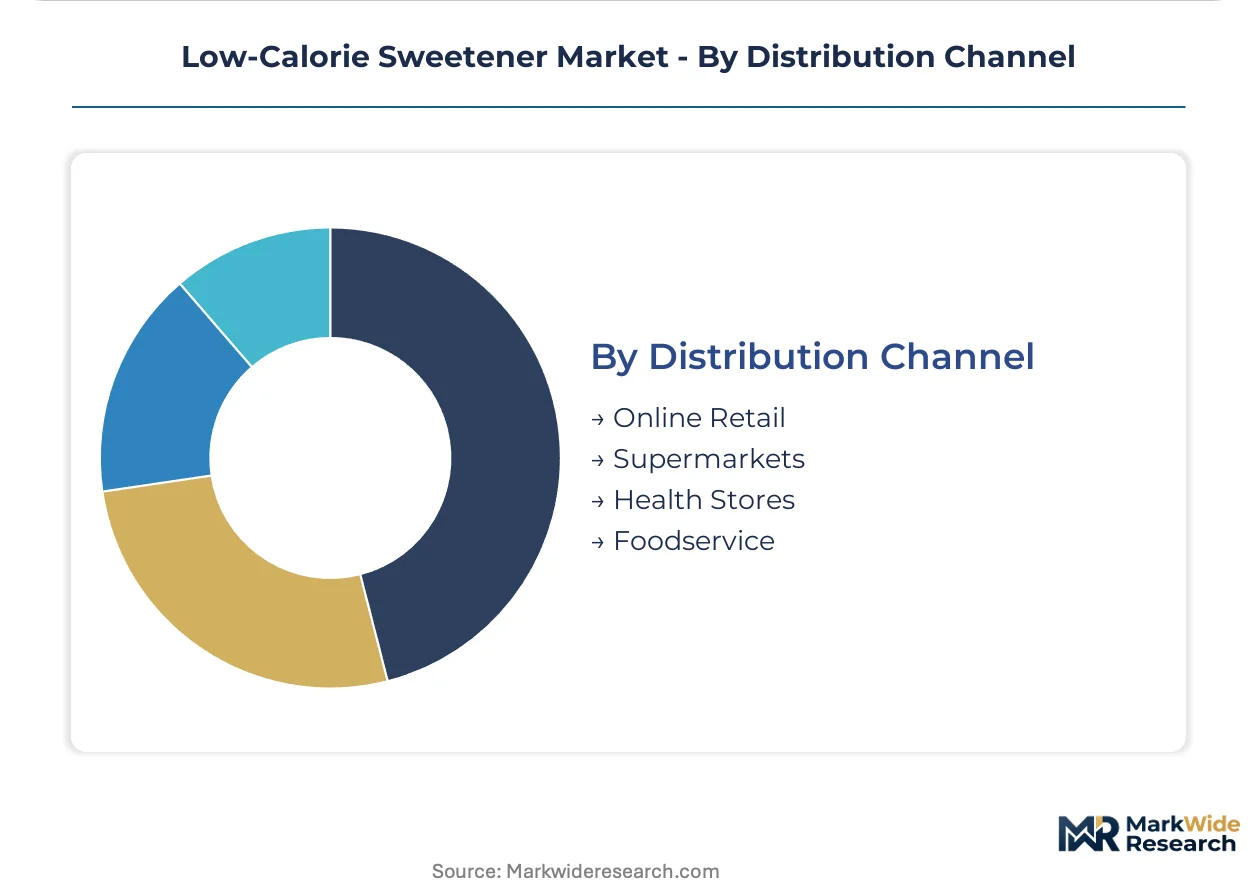
Distribution Channel:
Channel structure reflects customer scale fragmentation, with multinational bottlers and craft producers diverging sharply in procurement pathways.
- Supermarkets:Mass retail shelf placement drives branded ingredient specification; consumer-facing clean-label claims transmit upstream to sweetener selection criteria.
- Foodservice:Institutional and quick-service procurement emphasizes cost stability and supply assurance over sensory optimization; specification lock-ins favor incumbent synthetic platforms.
- Online Retail:Direct-to-consumer ingredient platforms enable specialty sweetener developers to bypass traditional chemical distributors; California and Colorado beverage startups exploit this disintermediation.
- Health Stores:Premium positioning channels demand organic certification and transparent provenance; monk fruit and stevia blends command shelf-space premiums in this segment.
Supermarkets anchor volume throughput; online retail is climbing the fastest as direct supplier relationships fragment traditional distributor concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States beverage bottlers command the largest procurement volumes as FDA added-sugar labeling mandates force rapid portfolio reformulation. Demand concentrates in functional drink categories where stevia and monk fruit blends secure shelf-space premiums.
United States
Carbonated soft drink manufacturers and functional beverage startups drive procurement intensity. FDA updated nutrition labeling requirements pressure disclosure of added sugars, accelerating clean-label sweetener substitution timelines. California and Colorado beverage clusters host vertically integrated startups building direct supplier relationships.
Brazil
Agricultural processors and stevia leaf extractors anchor upstream supply capacity. Climate volatility in Paraná and Mato Grosso do Sul exposes raw material flows to commodity cycle disruption. São Paulo-based processors are expanding enzymatic refinement capacity for export-grade glycosides.
Germany
Reduced-sugar dairy and confectionery applications dominate formulation demand. EFSA novel food assessments for fermentation-derived sweeteners extend approval timelines, delaying biotech entrant market access. North Rhine-Westphalia chemical processors maintain dual supply chains during aspartame re-evaluation uncertainty.
Japan
Amino acid-based sweetener purity standards dominate formulation protocols across beverage and tabletop segments. PMDA regulatory frameworks accept pilot-scale safety data faster than EFSA commercial-volume requirements. Kanto region food manufacturers lead adoption of rare sugar alcohols in premium positioning.
China
Fermentation scale-up for erythritol and rare glycosides concentrates in Shandong and Jiangsu bioprocessing corridors. SAMR food safety standards govern import substitution strategies for high-intensity sweeteners. Pearl River Delta beverage bottlers are retrofitting powder handling systems for hygroscopic sugar alcohols.
Low-Calorie Sweetener Market Key Industry Players
North American producers anchor one tier; European specialists hold formulation expertise advantages in dairy applications. The supplier base exhibits moderate concentration with multinational ingredient houses controlling extraction and fermentation infrastructure while regional distributors fragment downstream access. Two strategic archetypes dominate: vertically integrated agricultural processors with captive leaf supply, and biotech platforms leveraging precision fermentation for rare glycosides. Capacity expansion and direct-to-brand distribution partnerships constitute the primary competitive vectors.
Within the integrated processor tier, Tate & Lyle PLC represents British research-led development archetypes, while Cargill, Incorporated exemplifies North American supply anchoring through South American agricultural control. Ajinomoto Co., Inc occupies a position reflecting Japanese amino acid-based purity standards. These three entities illustrate how geographic origin and production philosophy shape competitive positioning without dictating specific strategic actions.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Cargill, Incorporated |
| Archer-Daniels-Midland Company |
| Ingredion Incorporated |
| Roquette Freres SA |
| Ajinomoto Co., Inc |
| DuPont de Nemours, Inc. |
| Celanese Corporation |
| NutraSweet Company |
| Others |
Cost & Logistics Intelligence
Stevia leaf procurement costs in Paraná and Mato Grosso do Sul transmit directly through three pricing tiers, with enzymatically refined glycosides commanding premiums over standard extracts while commodity-grade aspartame retains economy positioning in carbonated applications.
Pricing Analysis
Volume-scale carbonated soft drink contracts anchor the economy tier through mature aspartame synthesis economics, while premium beverage formulations pay steep markups for rare glycosides certified under FDA disclosure-compliant clean-label protocols. Price differentiation separates certified organic stevia extracts from conventionally processed alternatives, with thermal-stable sucralose occupying a mid-tier technical-performance niche. Pricing pressure stems from fermentation scale-up in Shandong bioprocessing corridors compressing erythritol production costs. Craft beverage startups in California and Colorado exhibit highest price sensitivity, whereas multinational bottlers prioritize supply assurance over unit economics.
Supply Chain Analysis
Agricultural leaf supply rests on Brazilian and Paraguayan stevia cultivation, with enzymatic refinement capacity concentrating in São Paulo processing clusters and Chinese fermentation corridors. Raw material flows draw from steviol glycoside extraction, L-phenylalanine chemical synthesis, and yeast-based erythritol bioconversion. Single-source vulnerability in South American leaf supply exposes processors to climate-induced commodity cycles. Distribution runs through consolidated multinational ingredient houses controlling extraction infrastructure, while regional craft producers fragment procurement through direct specialty extractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where FDA updated nutrition labeling requirements and EFSA novel food assessment timelines erect regulatory moats favoring incumbents with established approval dossiers and captive regulatory affairs capacity.
For Market Incumbents: Deploy backward integration into Brazilian leaf supply to secure glycoside extraction capacity against climate volatility and capture margin from enzymatic refinement scale-up. Accelerate dairy-specific sensory solution development to preempt new entrant penetration in reduced-sugar yogurt and flavored milk categories. Maintain dual aspartame-stevia supply chains during EFSA re-evaluation uncertainty to ensure formulation continuity for European carbonated soft drink contracts. For New Entrants and Emerging Players: Regional craft kombucha and adaptogenic beverage producers represent the most penetrable buyer archetype, with fragmented procurement patterns and direct supplier relationship appetite bypassing traditional distributor concentration. Target underpenetrated reduced-sugar dairy applications where protein-sweetener interaction complexity has slowed clean-label adoption versus beverage analogues. Establish e-commerce ingredient platform presence to disintermediate regional chemical distributors and capture margin previously allocated to middle-tier procurement channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation-platform biotech specialists with pilot-scale rare glycoside production and accelerated PMDA approval pathways in Japanese and Southeast Asian markets. Long-term viability hinges on regulatory approval velocity as competitive moat, with EFSA novel food assessment timelines determining revenue recognition windows. Monitor EFSA aspartame re-evaluation outcomes as inflection indicator for accelerated stevia and erythritol substitution demand across European formulation protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leaf Supply | Cargill's Brazilian and Paraguayan agricultural control secures glycoside extraction capacity against climate volatility. |
| Fermentation Scale-Up for Rare Glycosides | Precision bioprocessing in Shandong corridors enables cost-competitive production of steviol molecules previously limited to extraction economics. |
| Dairy-Specific Sensory Solution Development | Tate & Lyle's British research campuses target underpenetrated reduced-sugar yogurt categories with protein-sweetener interaction expertise. |
| Direct-to-Brand Distribution Partnership | E-commerce ingredient platforms allow specialty developers to bypass regional chemical distributors and capture margin in California beverage clusters. |
| Dual Supply Chain Maintenance | North Rhine-Westphalia processors retain aspartame-stevia flexibility during EFSA re-evaluation uncertainty to ensure European formulation continuity. |
Research Approach
Trade databases, customs records, and SEC 10-K filings formed the secondary backbone, supplemented by FDA novel food approval dossiers and EFSA safety assessment documentation. Primary interviews with beverage formulation scientists, dairy R&D directors, stevia leaf processors, and specialty ingredient procurement managers at multinational bottlers and craft beverage startups validated demand assumptions. Bottom-up volume modeling across stevia, aspartame, sucralose, and erythritol product tiers combined with top-down market sizing through trade flow analysis to establish triangulated baseline estimates.
Historical trendline analysis tracked production capacity expansion, regulatory approval velocity, and end-use substitution patterns across the projection horizon. Segmentation dimensions modeled included product type intensity profiles, beverage-dairy-confectionery-baked goods application constraints, powder-liquid-granular form handling requirements, and supermarket-foodservice-online retail channel structures. CAGRs derived from regression analysis against regulatory disclosure mandate implementation timelines and fermentation cost compression curves, with specific inputs for stevia leaf yield volatility and enzymatic refinement yield improvements.
Revisions become necessary when EFSA novel food assessment timelines extend beyond standard windows, Brazilian climate events disrupt leaf supply, or fermentation platform yields diverge from pilot-scale projections. Forecasts reflect documented assumptions on regulatory convergence speed and bioprocess engineering advancement rates. A small set of named triggers warrants ongoing watch: EFSA aspartame re-evaluation outcomes, SAMR import substitution policy shifts, and PMDA rare sugar alcohol approval velocity in Japanese premium positioning segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sugar-Free Syrups Market
Sweeteners
Organic Palm Sugar Market
Sweeteners
Japan Food Sweetener Market
Sweeteners
Xylitol Market
Sweeteners
Natural Stevia Market
Sweeteners
Dry Molasses Market
Sweeteners
Palm Sugar Market
Sweeteners
Rice Syrup Market
Sweeteners
Sucralose Market
Sweeteners
White Sugar Market
Sweeteners
Sucrose Esters Market
Sweeteners
Tapioca Maltodextrin Market
Sweeteners
Glucose Syrup Market
Sweeteners
Compressible Sugar Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Italy Food Sweetener Market