
 Europe Stevia Market | 2026-2036
Europe Stevia Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Stevia Market Analysis
Stevia pricing is decoupling between premium-certified extracts and commodity-grade blends. Tate & Lyle Plc leverages its European distribution network to sustain premium positioning across beverage accounts. Cargill Inc anchors its supply through backward integration into stevia leaf sourcing. Roquette competes on specialty formulations targeting bakery applications.
Stevia comprises glycoside extracts—primarily rebaudioside A and stevioside—derived from Stevia rebaudiana leaves via water-based extraction and purification to achieve sweetness intensities 200–350 times that of sucrose. The ingredient serves industrial food and beverage manufacturers seeking sugar reduction without synthetic additives. Liquid stevia leads in beverage applications where solubility and dosing precision matter, while stevia powder dominates bakery and dry-mix segments where blending uniformity drives formulation stability. Dietary supplements represent the fastest-growing application as sports nutrition brands reformulate around natural-positioned sweetening systems.
EFSA novel food assessments and EU Food Information to Consumers Regulation shape stevia market access and label claims across member states. REACH compliance for extraction solvents and the EU Green Deal's bio-based manufacturing incentives further filter which suppliers can operate at scale. Stakeholders must monitor how EFSA's pending rebaudioside M evaluations alter competitive positioning between established extract portfolios and next-generation glycoside variants.
Market Dynamics
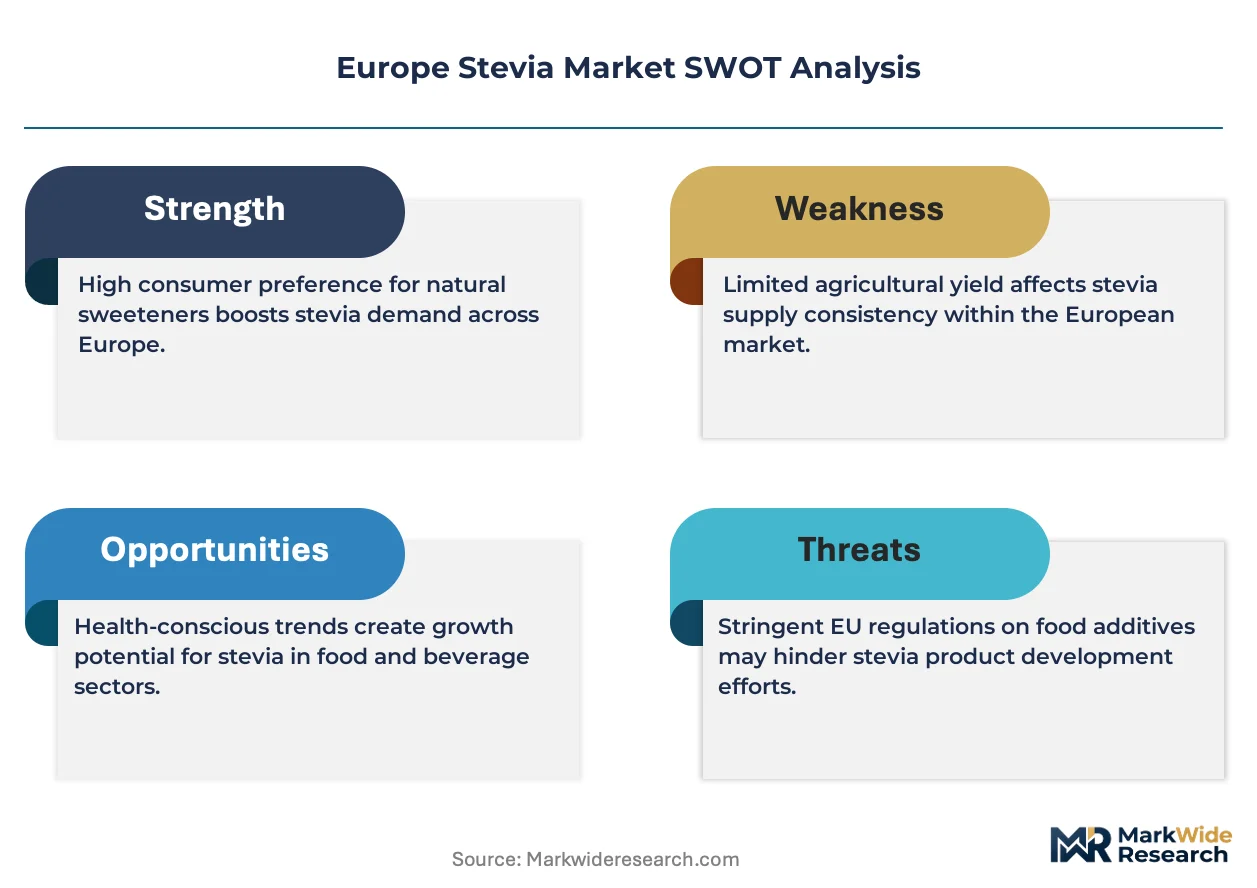
EFSA's pending rebaudioside M evaluations are compressing product development timelines across European formulation labs, forcing manufacturers to accelerate pipeline decisions before novel food pathways crystallize.
Growth Catalysts
- EU Green Deal bio-based manufacturing incentives:Production facilities in Hamburg and Rotterdam are retrofitting extraction lines to qualify for green transition credits, expanding solvent-free purification capacity.
- Beverage reformulation mandates:France's public health nutrition targets are compelling CPG manufacturers to replace synthetic sweeteners with stevia glycosides in carbonated and still drinks.
- Water-based extraction advances:Membrane filtration technologies are reducing residual bitter aftertaste in high-purity rebaudioside A, unlocking broader bakery adoption.
Market Restraints
- Leaf supply geographic concentration:Over 70% of raw stevia leaf sourcing depends on Chinese agricultural processors, exposing European extractors to phytosanitary trade friction.
- EFSA novel food assessment timelines:Pending rebaudioside M approvals are freezing R&D budgets as manufacturers delay commercialization investments until regulatory clarity emerges.
- Natural sweetener substitution pressure:Monk fruit extract and allulose are capturing clean-label positioning in premium beverage segments where stevia held first-mover advantage.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Greenfield stevia formulation facilities in Central Europe offer lower energy costs and proximity to underpenetrated confectionery markets.
- Sports nutrition application white space:Protein powder and pre-workout brands are reformulating around stevia-sweetened systems as synthetic sweetener avoidance hardens into category standard.
- REACH solvent compliance as competitive moat:Early adopters of ethanol-based extraction are securing preferred supplier status with multinational food manufacturers facing supply base rationalization.
Industry Challenges
- Flavor chemist talent scarcity:Formulation expertise bridging stevia glycoside behavior with protein matrix interactions commands premium compensation in Paris and Amsterdam labor markets.
- Extraction equipment capex intensity:Continuous counter-current extraction systems require 8-figure euro investments that strain mid-cap extractors' balance sheets.
- Novel food dossier preparation complexity:EFSA-compliant toxicology and exposure studies for next-generation glycoside variants demand 18-24 month lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Stevia Market |
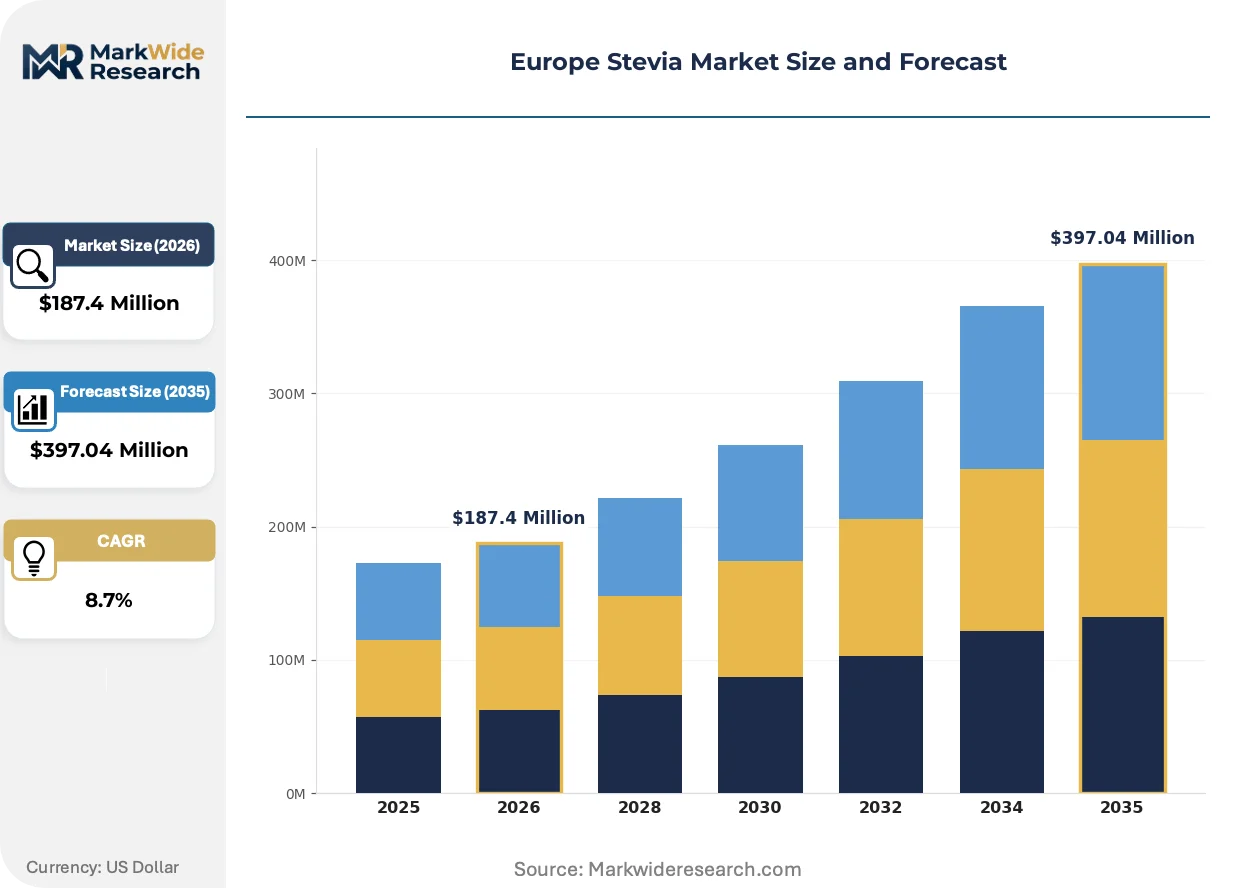
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia Leaf, Liquid Stevia, Stevia Powder, Stevia Blends Application: Beverages, Bakery Products, Dairy Products, Dietary Supplements Form: Granular, Liquid, Powder, Concentrate End User: Food Manufacturers, Beverage Producers, Retail Customers, Health-Conscious Individuals |
| Companies Covered | Tate & Lyle Plc, The Archer Daniels Midland Company, Ingredion Inc, Tereos S A, Roquette, Cargill Inc, GLG Life Tech Corporation, Evolva Holding S.A., PureCircle Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Stevia Market Emerging Trajectories
Rebaudioside M development pipelines are compressing competitive timelines as European extractors race to secure novel food approvals before formulation standards lock in. Three intersecting forces are reshaping how stevia enters finished goods.
Enzymatic glycosylation is expanding into industrial-scale production of rare steviol glycosides previously limited to laboratory yields. Biocatalysis specialists in Denmark and the Netherlands are licensing transglycosylation platforms to major extractors, enabling rebaudioside D and M production at cost parity with conventional rebaudioside A. Sports nutrition and dairy alternative manufacturers are accelerating qualification programs for these enhanced-sweetness variants, compressing the performance gap between natural and synthetic high-intensity sweeteners.
EFSA's evolving guidance on novel food equivalence is forcing extractors to resubmit technical dossiers for enzyme-modified stevia variants. The regulatory friction is delaying product launches by 12-18 months and concentrating investment in jurisdictions with established approval precedents. German and French beverage manufacturers are responding by dual-tracking formulation development—advancing rebaudioside A formulations while maintaining optionality on next-generation glycosides pending regulatory clarity.
Direct procurement relationships between food manufacturers and stevia leaf cooperatives are displacing traditional trader-mediated supply chains. Large CPG accounts in the UK and Germany are signing multi-year offtake agreements with Paraguayan and Kenyan agricultural collectives, securing volume certainty and traceability credentials. This channel compression is most visible in organic-certified stevia segments, where end-to-end chain of custody documentation has become a non-negotiable tender requirement.
Europe Stevia Market Segmentation
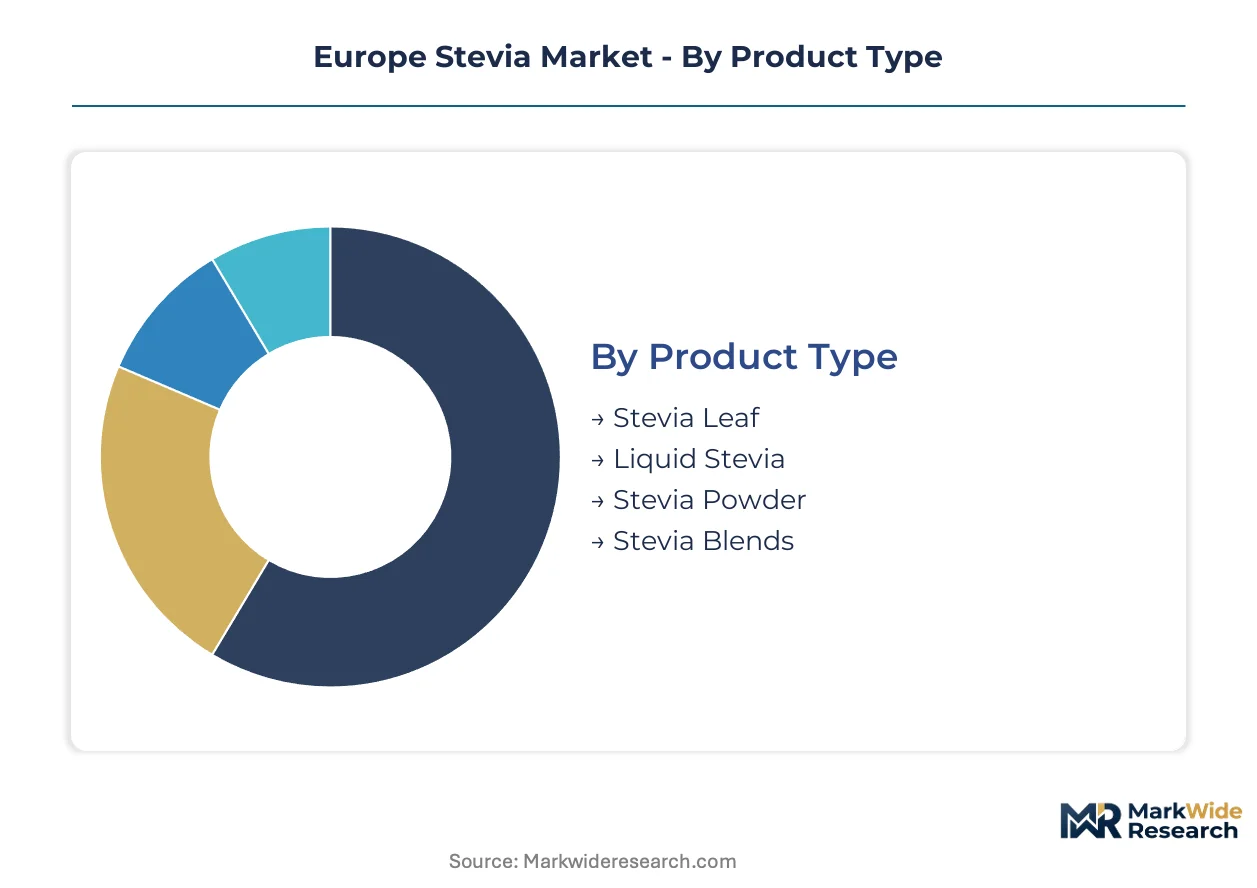
Stevia's industrial utility varies sharply across product formats and end-use specifications, with EFSA novel food pathways and REACH solvent compliance creating divergent commercial barriers. Manufacturers must align extraction investments with the certification burdens each segment demands.
Product Type:
EFSA novel food dossiers impose tiered compliance costs across stevia formats, with purified glycoside extracts facing stricter toxicology requirements than minimally processed leaf products.
- Stevia Leaf:Minimally processed dried leaves containing stevioside and rebaudioside A in native ratios. German herbal tea blenders and French organic retailers source whole-leaf formats to bypass novel food classification, though flavor inconsistency limits industrial scale-up.
- Liquid Stevia:Water or ethanol-based extracts standardized to specific glycoside concentrations. Beverage formulators in Hamburg and Paris specify liquid formats for dosing precision in carbonated drinks, with REACH-compliant ethanol extraction becoming a tender requirement for multinational accounts.
- Stevia Powder:Spray-dried or crystallized glycoside preparations with 200-350x sucrose sweetness intensity. Dry-mix manufacturers across Belgium and the Netherlands favor powder for blending uniformity in bakery premixes.
- Stevia Blends:Co-processed formulations combining stevia glycosides with erythritol, allulose, or soluble fibers to mask bitter aftertaste. Sports nutrition brands in the UK and Germany are accelerating qualification of these engineered sweetness systems.
Stevia powder sits at the top of the volume ranking, with stevia blends climbing the fastest.
Application:
End-use segments separate by formulation complexity, with protein-matrix interactions in dairy and supplements demanding specialized flavor chemistry capabilities.
- Beverages:Carbonated and still drinks represent the deepest reformulation pipeline, with French public health targets compelling CPG manufacturers to replace synthetic sweeteners. Liquid stevia dominates here for solubility and batch-to-batch consistency.
- Bakery Products:Heat-stable glycoside variants are essential for yeast-raised and chemically leavened goods. Membrane filtration advances in German extraction facilities are reducing Maillard reaction off-notes that previously limited bakery adoption.
- Dairy Products:Yogurt and flavored milk applications require stevia systems compatible with acidic pH and protein stability. Dutch dairy alternative startups are driving demand for rebaudioside M variants with cleaner sweetness profiles.
- Dietary Supplements:Protein powders, pre-workout formulations, and gummies are reformulating around natural-positioned sweetening. This application is expanding most quickly as synthetic sweetener avoidance hardens into category standard.
Beverages command the largest share of current demand, with dietary supplements gaining share fastest.
Form:
Physical presentation determines equipment compatibility and dosing economics across European manufacturing footprints.
- Granular:Free-flowing crystals resembling sucrose morphology for direct consumer substitution. Retail channels and small-scale food service accounts in Italy and Spain prefer granular for tabletop use.
- Liquid:Aqueous or hydroalcoholic solutions with defined glycoside titers. Industrial beverage accounts specify liquid for automated dosing systems and reduced dust exposure.
- Powder:Fine-particle preparations for dry blending operations. Bakery and confectionery manufacturers in Poland and the Czech Republic source powder for integration into flour-based matrices.
- Concentrate:High-potency preparations requiring dilution before use. Flavor houses and compound ingredient suppliers in Switzerland and Germany utilize concentrates for downstream formulation flexibility.
Powder maintains volume leadership, with concentrate formats showing steepest expansion trajectory.
End User:
Customer scale and technical capability create distinct procurement patterns, from multinational tender processes to direct-to-consumer subscription models.
- Food Manufacturers:Industrial bakeries, confectioners, and prepared food companies with in-house R&D capabilities. These accounts negotiate multi-year supply agreements with traceability documentation requirements.
- Beverage Producers:Carbonated soft drink, juice, and functional beverage companies with dedicated formulation teams. French and German beverage giants are consolidating supplier bases around REACH-compliant extractors with novel food approval track records.
- Retail Customers:Supermarket private labels and health food chains sourcing finished consumer products. Organic certification and clean-label positioning drive assortment decisions in UK and Scandinavian retail.
- Health-Conscious Individuals:Direct purchasers of tabletop sweeteners and recipe ingredients. E-commerce subscription models are capturing this segment with personalized flavor profiles and delivery scheduling.
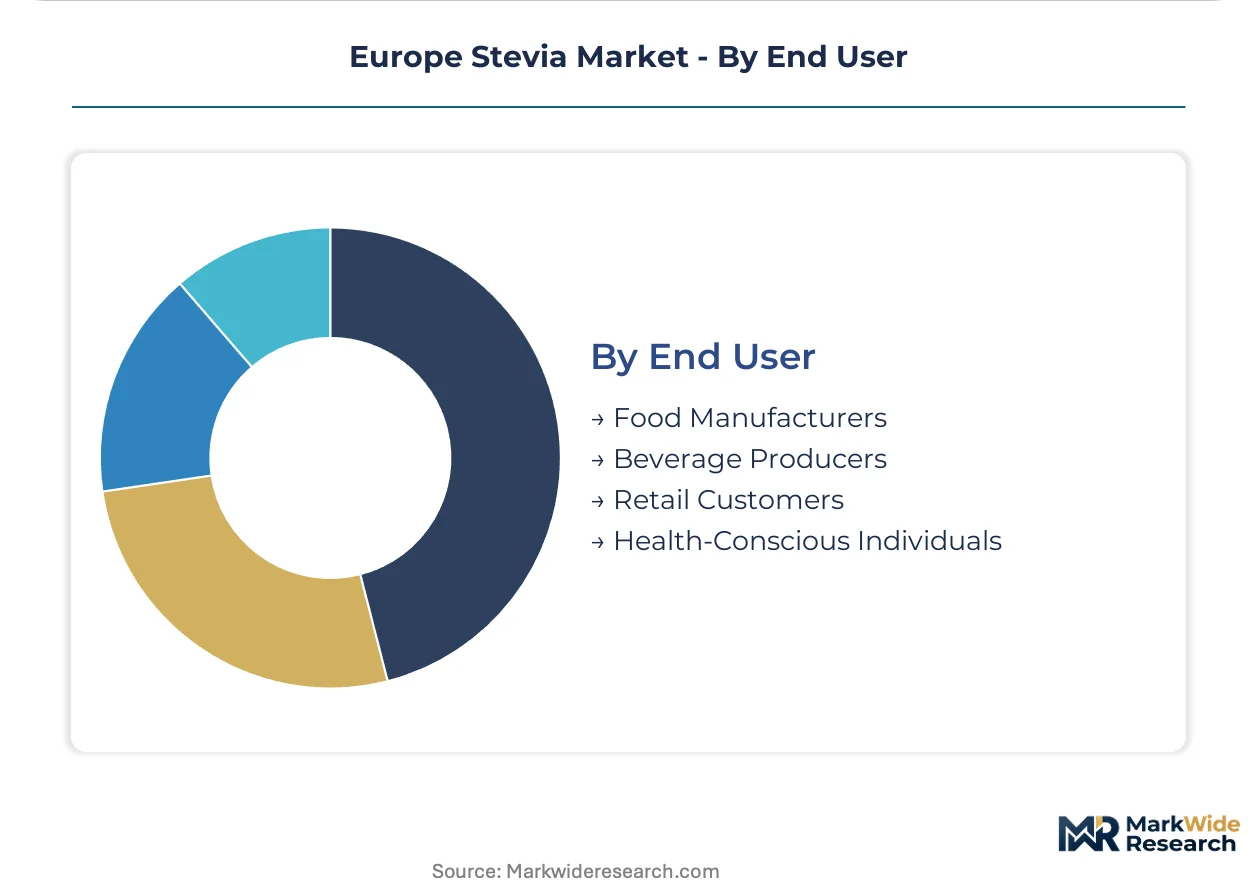
Food manufacturers represent the largest demand block, with health-conscious individuals expanding most rapidly through digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor chemist talent pools in Amsterdam and Paris anchor European stevia formulation capabilities, with extraction expertise clustering around Hamburg and Rotterdam processing hubs.
Germany
Beverage reformulation mandates from Berlin's public health nutrition targets accelerate stevia adoption in carbonated drinks. EFSA novel food guidance shapes approval timelines for next-generation glycoside variants. Hamburg extraction facilities retrofit solvent-free purification lines to qualify for EU Green Deal bio-based manufacturing credits.
France
Paris-based dairy alternative startups drive demand for rebaudioside M variants with cleaner sweetness profiles. France's public health targets compel CPG manufacturers to replace synthetic sweeteners in juice and functional beverages. Île-de-France formulation labs compress product development timelines ahead of pending EFSA evaluations.
United Kingdom
London health food chains and supermarket private labels prioritize organic-certified stevia with end-to-end chain of custody documentation. UK sports nutrition brands reformulate protein powders around natural-positioned sweetening systems. Manchester and Birmingham distribution hubs consolidate procurement from Paraguayan agricultural collectives.
Netherlands
Rotterdam extraction facilities expand membrane filtration capacity to reduce bitter aftertaste in high-purity rebaudioside A. Dutch biocatalysis specialists license transglycosylation platforms for industrial-scale rare glycoside production. Amsterdam flavor houses specialize in protein-matrix interaction formulations for dairy alternatives.
Poland
Greenfield stevia formulation facilities in Warsaw and Kraków offer lower energy costs and proximity to underpenetrated Central European confectionery markets. Polish bakery premix manufacturers favor powder formats for blending uniformity in flour-based matrices. REACH solvent compliance requirements filter supplier qualification for multinational accounts.
Europe Stevia Market Vendor Landscape
Top-tier vendors anchor premium-certified extract supply, while mid-cap specialists compete on specialty formulations and regional distribution reach. The vendor base stratifies across three tiers: multinational ingredient houses with backward integration into leaf sourcing, European extraction specialists with novel food approval track records, and biocatalysis technology licensors. Competitive moves concentrate on capacity expansion in Central European greenfield sites and strategic partnerships securing multi-year offtake agreements with agricultural cooperatives.
Within the multinational tier, Tate & Lyle Plc and Cargill Inc exemplify divergent sourcing strategies—Tate & Lyle leveraging European distribution networks for premium positioning, Cargill anchoring supply through upstream control over stevia leaf procurement. Roquette occupies a specialist position targeting bakery application formulations. Among extraction technology providers, PureCircle Ltd and GLG Life Tech Corporation represent the novel food approval track record archetype, while Evolva Holding S.A. sits within the biocatalysis licensing tier enabling cost parity production of rare glycosides.
| Leading Market Players |
|---|
| Tate & Lyle Plc |
| The Archer Daniels Midland Company |
| Ingredion Inc |
| Tereos S A |
| Roquette |
| Cargill Inc |
| GLG Life Tech Corporation |
| Evolva Holding S.A. |
| PureCircle Ltd |
| Others |
Supply Flow & Price Mechanics
Chinese stevia leaf spot prices cascade through European extraction facilities into three distinct pricing tiers for finished glycoside extracts. EFSA novel food certification status and REACH solvent compliance separate premium-certified supply from commodity-grade alternatives, with beverage manufacturers in Paris and Hamburg paying significant premiums for documented chain-of-custody documentation.
Pricing Analysis
Ingredient-plus-certification bundling dominates transactional structures, with unbundled commodity glycosides trading at substantial discounts to EFSA-approved alternatives. Price differentiation rests on organic certification tier and extraction solvent profile, with ethanol-based purification commanding premiums over conventional methylene chloride processes. Cost compression in standard-grade rebaudioside A intensifies as Chinese agricultural processors expand fermentation-derived capacity. Retail customers and small-scale food service accounts exhibit highest price sensitivity, while multinational beverage producers prioritize supply security over unit economics.
Supply Chain Analysis
REACH-compliant extraction certification gates supplier qualification for European multinational accounts, filtering access to premium formulation contracts. Raw stevia leaf supply draws from Chinese agricultural processors, Paraguayan cooperatives, and emerging Kenyan cultivation zones. Extraction solvents, membrane filtration equipment, and analytical testing services constitute critical input dependencies. Single-source vulnerability concentrates in Chinese leaf supply, where phytosanitary trade friction disrupts just-in-time delivery schedules. Distribution runs through Rotterdam and Hamburg processing hubs into formulation facilities across Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Stevia Market compounds steadily as clean-label sugar reduction mandates harden into regulatory and consumer expectations across member states. Beverage reformulation pipelines in France and Germany provide predictable demand visibility for qualified suppliers.
For Market Incumbents: Deepen backward integration into Paraguayan and Kenyan agricultural cooperatives to secure volume certainty and traceability credentials that multinational accounts now mandate in tender specifications. Expand membrane filtration capacity in Hamburg and Rotterdam facilities to capture EU Green Deal bio-based manufacturing incentives. Monk fruit extract and allulose substitution in premium beverage segments threatens first-mover positioning—accelerate rebaudioside M qualification programs to maintain formulation partnership lock-in. For New Entrants and Emerging Players: Launch via direct-to-sports-nutrition-brand distribution, bypassing consolidated beverage procurement channels where incumbent relationships are entrenched. Poland and Czech Republic greenfield formulation facilities offer lower energy costs and proximity to underpenetrated Central European confectionery markets. White space concentrates in protein powder and pre-workout applications where synthetic sweetener avoidance hardens into category standard—qualify stevia-erythritol blend systems for these matrixes. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap extractors lack capital for continuous counter-current extraction equipment and EFSA novel food dossier preparation. The market supports long-term compounder positioning for suppliers with proven regulatory approval track records and captive agricultural supply. Target acquisition archetype: European extraction specialists with existing EFSA approvals and underutilized capacity in Central European jurisdictions. Signal to monitor: EFSA rebaudioside M approval timeline acceleration, which would trigger immediate capacity rationalization among unprepared competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Cooperatives | Secures leaf supply traceability credentials required by French and German beverage tenders. |
| Membrane Filtration Capacity Expansion | Reduces bitter aftertaste in rebaudioside A, unlocking bakery adoption in Belgian and Dutch markets. |
| EFSA Novel Food Dossier Investment | Establishes regulatory moat against commodity-grade competitors in premium formulation segments. |
| Biocatalysis Platform Licensing | Enables cost parity production of rare glycosides through Danish and Dutch technology partnerships. |
| Central European Greenfield Facilities | Captures lower energy costs and proximity to Polish and Czech confectionery manufacturers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with extraction facility operators, beverage formulation chemists, EFSA regulatory consultants, and procurement leads at multinational food manufacturers with secondary validation. Secondary sources included EFSA novel food register entries, REACH compliance databases, EU customs trade statistics, and Cefic chemical industry reports. Bottom-up volume modeling from individual extraction facility capacities and top-down demand estimation from beverage reformulation pipelines were cross-referenced for triangulation.
Segment-weighting approaches distributed volume and value projections across product type, application, and end-user dimensions, with additional modeling of extraction technology tier and certification status. CAGRs were derived from regression analysis of historical adoption curves and regulatory event impacts, calibrated against EFSA approval timeline scenarios and EU Green Deal incentive uptake assumptions across the analysis window. Industry-specific inputs included leaf yield variability from Chinese agricultural zones and membrane filtration technology diffusion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under phytosanitary trade disruption or accelerated EFSA rebaudioside M approval scenarios. Projections reflect documented assumptions regarding regulatory pathway timelines and agricultural supply stability. A model refresh is warranted upon material change in EFSA novel food guidance or Chinese export certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Turbinado Sugar Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Sugar Beet Juice Extract Market
Sweeteners
Plant-Derived Sweetener Market
Sweeteners
Saccharin Market
Sweeteners
Monk Fruit Sugar Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
Natural Caloric Sweeteners Market
Sweeteners
Xylose Market
Sweeteners
Canada Food Sweetener Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
South America Food Sweetener Market
Sweeteners
Natural Stevia Market
Sweeteners
Invert Sugar Market
Sweeteners
Vietnam Food Sweetener Market
Sweeteners
Corn Syrup Market