
 North America Plant-Derived and Synthetic Sugar Market | 2026-2036
North America Plant-Derived and Synthetic Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plant-Derived and Synthetic Sugar Market Analytics
Stevia extract is hardening its cost position against aspartame in tabletop and beverage applications as enzymatic bioconversion yields improve. Cargill, Incorporated leverages its integrated supply chain from Brazilian leaf sourcing to Nebraska extraction facilities. Ingredion Incorporated anchors its position through deep corn wet milling expertise and modified starch co-production economics. Archer Daniels Midland Company competes on glucose syrup scale, operating multiple refineries across the U.S. Midwest.
Plant-derived and synthetic sugars comprise caloric and non-caloric sweetening agents manufactured through agricultural extraction, enzymatic conversion, or chemical synthesis, with purity grades ranging from liquid syrups to crystalline solids exceeding 99.5% assay. These ingredients function primarily as taste modulators, bulking agents, and preservative enhancers across packaged food, pharmaceutical, and industrial fermentation applications. Sucrose and glucose dominate volume flows through the food and beverages application channel, where margin pools concentrate in high-fructose corn syrup contracts tied to commodity futures. Xylitol crystalline form commands premium positioning in pharmaceutical and oral care adjacencies, while liquid formulations sustain growth in beverage manufacturing for dissolution speed and handling efficiency.
The FDA governs sweetener safety through GRAS determinations and food additive petitions, while Health Canada maintains parallel approval pathways under the Food and Drugs Act that create asynchronous market access timelines. USDA biofuel mandates indirectly tighten corn feedstock availability for glucose and fructose production, elevating input cost volatility for domestic refiners. Stakeholders must monitor FDA guidance on novel sweetener classifications and Health Canada's proposed front-of-package labeling rules, as both frameworks will reshape permissible health claims and reformulation incentives across the North American market.
Market Dynamics
The FDA's added sugars disclosure mandate has triggered systematic reformulation across U.S. beverage manufacturing, compressing procurement timelines and redirecting ingredient sourcing toward enzymatically converted low-calorie alternatives.
Growth Catalysts
- Enzymatic Bioconversion Advances:Improved stevia glycoside yields through microbial fermentation are narrowing cost parity with synthetic alternatives in tabletop and ready-to-drink applications.
- USDA Biofuel Policy:Corn ethanol mandates are tightening glucose feedstock availability, accelerating investment in alternative carbohydrate sources including Brazilian cane and Canadian beet processing.
- Health Canada Front-of-Package Rules:Proposed labeling requirements for high-sugar products are incentivizing preemptive reformulation across Ontario and Quebec food manufacturing corridors.
Market Restraints
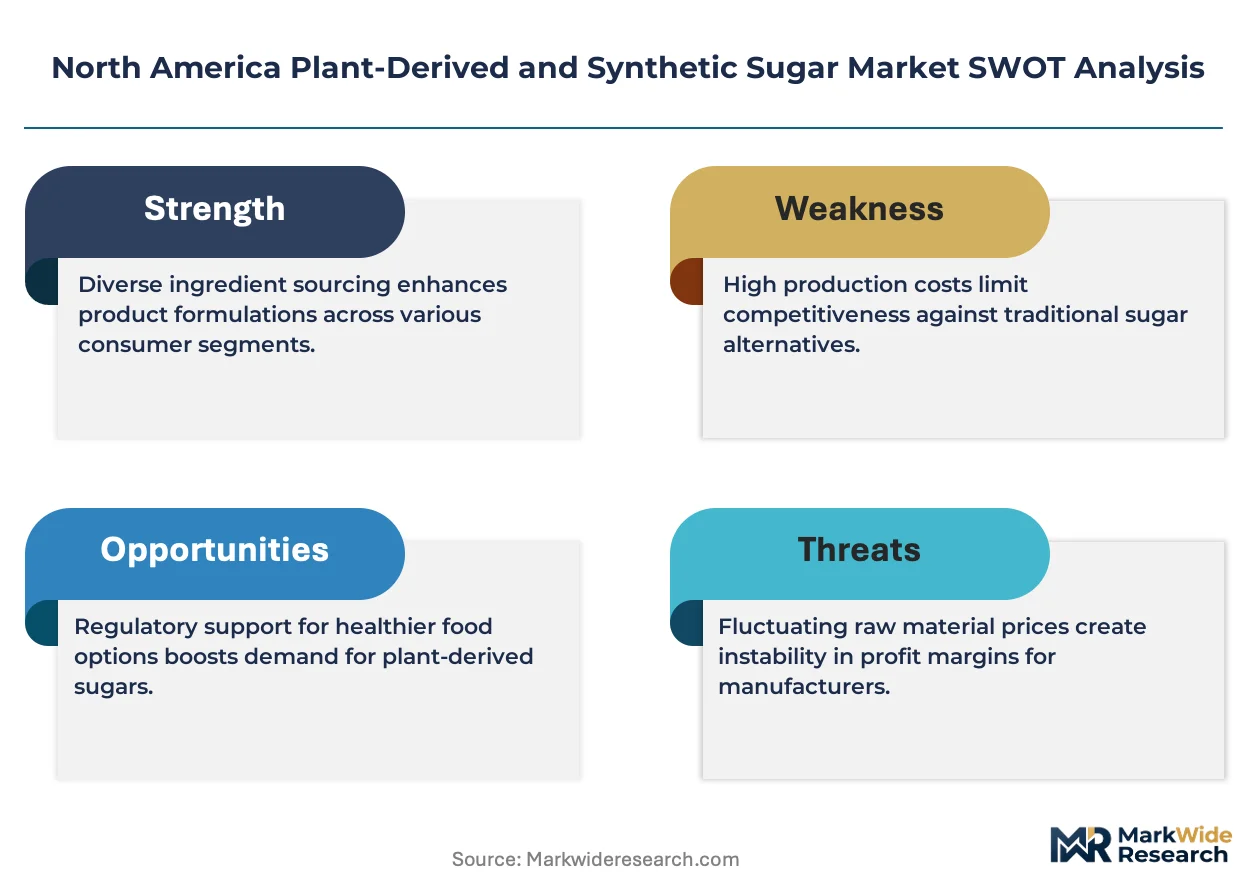
- Corn Price Volatility:Glucose and high-fructose corn syrup production costs fluctuate with commodity futures tied to Midwest harvest conditions and ethanol quota adjustments.
- GRAS Timeline Asymmetry:Novel sweetener approvals through FDA food additive petitions lag Health Canada evaluations, creating staggered commercialization windows between U.S. and Canadian markets.
- Monk Fruit Supply Concentration:Extract sourcing remains geographically concentrated in Guangxi province, exposing North American formulators to Chinese export policy and climate disruption risks.
Strategic Opportunities
- Canadian Prairie Beet Expansion:Alberta and Saskatchewan processing capacity for sucrose and specialty carbohydrates remains underdeveloped relative to corn-dominant U.S. supply chains.
- Pharmaceutical Xylitol Adjacencies:Crystalline polyol demand for chewable tablets and pediatric formulations outpaces current North American refinery output, opening margin expansion paths.
- IRA Clean Manufacturing Credits:Bioprocessing facility investments in Nebraska and Iowa qualify for federal incentives, reducing capital barriers for enzymatic conversion infrastructure.
Industry Challenges
- Fermentation Scale-Up Expertise:Commercial microbial production of rare sugars requires specialized bioprocess engineering talent concentrated in limited Midwest research corridors.
- Dual-Jurisdiction Compliance:Simultaneous FDA GRAS self-affirmation and Health Canada novel food notification create redundant documentation burdens for cross-border product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plant-Derived and Synthetic Sugar Market |
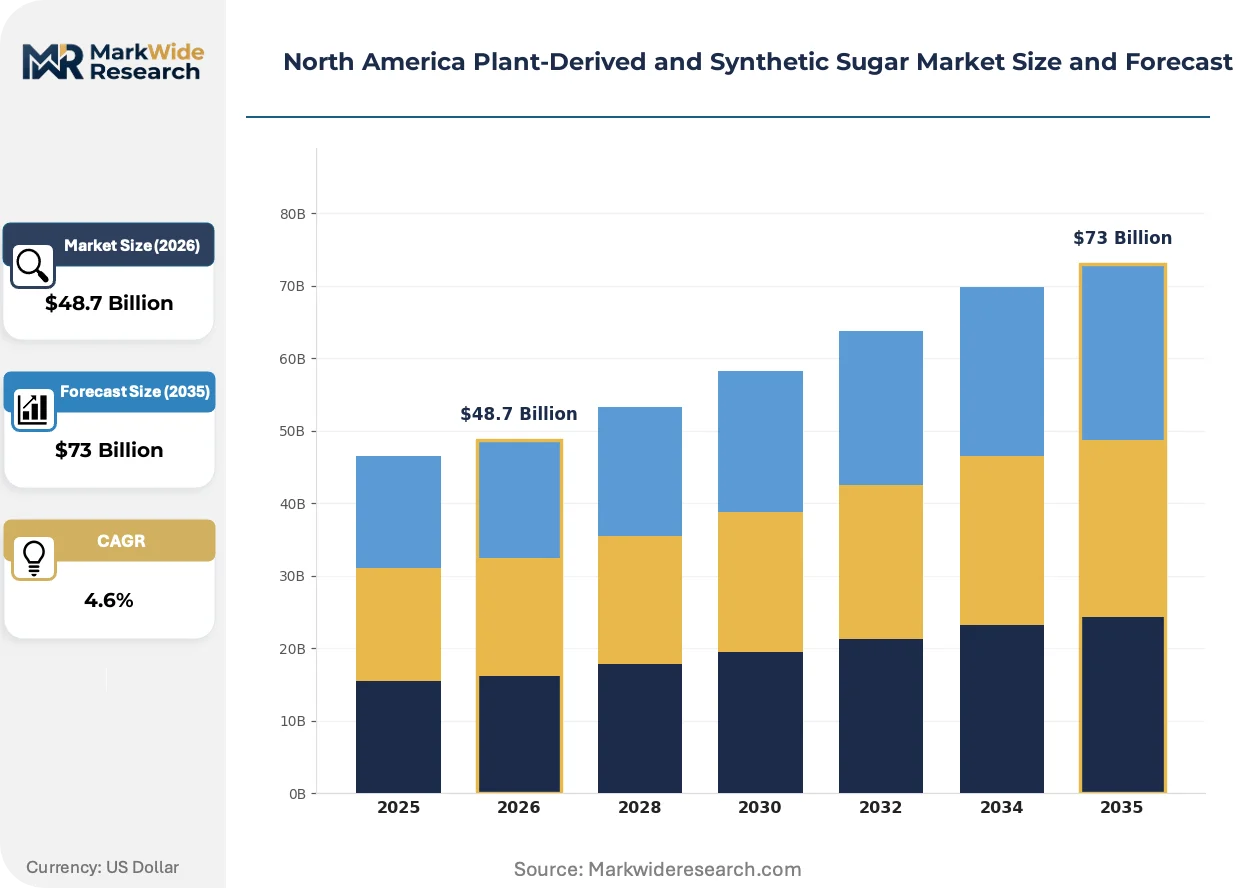
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fructose, Sucrose, Glucose, Xylitol Form: Granulated, Liquid, Powder, Crystal Application: Food & Beverages, Confectionery, Bakery, Pharmaceuticals End User: Food Manufacturers, Retailers, Bakeries, Restaurants |
| Companies Covered | Cargill, Incorporated, Ingredion Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, International Flavors & Fragrances Inc., Roquette Frères, PureCircle, BioNeutra Global Corporation, SweeGen, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plant-Derived and Synthetic Sugar Market Evolving Landscape
Bioconversion technologies and regulatory disclosure requirements are compressing traditional sweetener procurement cycles while elevating enzymatic processing capabilities as a competitive differentiator across North American manufacturing.
Enzymatic stevia glycoside production is consolidating cost structures in natural non-caloric segments. Food and beverage manufacturers in the U.S. Great Lakes corridor are adopting microbially converted Reb M and Reb D at accelerating volumes. This technology is consolidating supplier margins by reducing dependence on leaf extraction yields and Brazilian agricultural cycles.
Health Canada's proposed front-of-package nutrition symbol regulations are forcing reformulation timelines for packaged goods sold in Ontario and Quebec. Manufacturers must reduce added sugars to avoid mandatory warning labels, redirecting R&D expenditure toward bulking agent alternatives. The baked goods and confectionery segments are responding fastest, with contract manufacturers accelerating pilot trials of allulose and erythritol blends.
Beverage procurement patterns are compressing supplier qualification cycles as CPG brands accelerate portfolio renovation. Direct sourcing agreements between sweetener refiners and bottling networks are displacing traditional ingredient distributor intermediaries. This disintermediation is most visible in Texas and California beverage manufacturing clusters, where reformulated zero-sugar launches dominate new product pipelines.
North America Plant-Derived and Synthetic Sugar Market Segmentation
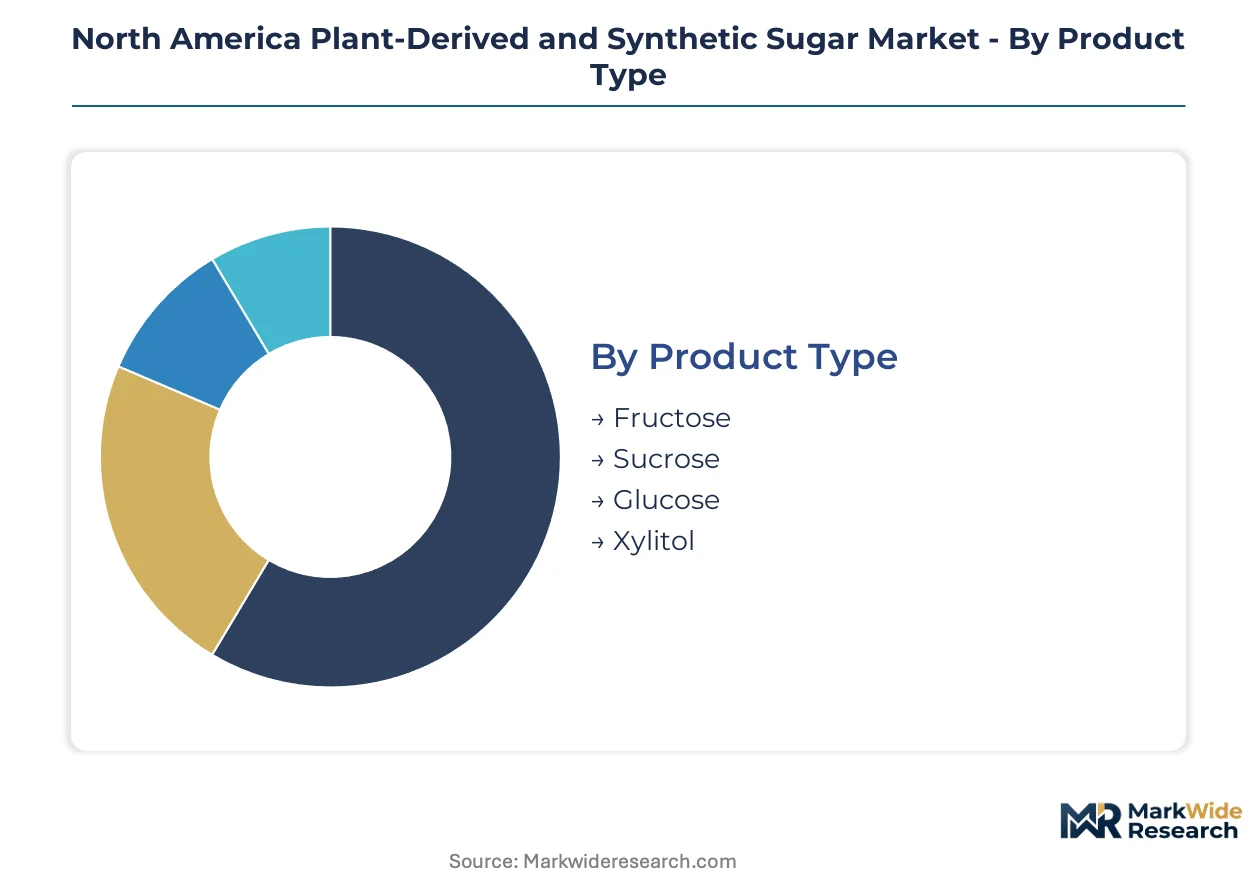
North American sweetener procurement decisions cascade through multiple specification layers, from caloric density and dissolution kinetics to regulatory compliance thresholds. Manufacturers optimize formulations by matching carbohydrate functionality to processing equipment constraints and end-product shelf stability requirements.
Product Type:
Carbohydrate chemistry and enzymatic conversion pathways differentiate cost structures and application suitability across the manufacturing base.
- Fructose:Monosaccharide with 1.7x sucrose sweetness intensity enables reduced-calorie formulations. Demand concentrates in Texas and California beverage manufacturing clusters where high-fructose corn syrup contracts dominate procurement. FDA added sugars disclosure rules are accelerating enzymatic fructose substitution in reformulated portfolios.
- Sucrose:Disaccharide standard for taste modulation and Maillard browning control in thermal processing. Canadian beet-derived sucrose from Alberta and Saskatchewan processing facilities serves Ontario and Quebec food manufacturers seeking supply chain diversification from corn-dependent U.S. sources.
- Glucose:Reducing sugar valued for fermentation feedstock and humectant properties in baked goods. Corn wet milling output from Nebraska and Iowa refineries supplies Great Lakes corridor processors.
- Xylitol:Crystalline polyol with negative heat of solution and dental caries inhibition properties. Pharmaceutical and oral care applications in chewable tablets command premium positioning against commodity sweeteners.
Fructose leads on scale; xylitol leads on momentum.
Form:
Physical state determines handling economics, dissolution kinetics, and equipment compatibility across manufacturing lines.
- Liquid:Syrup concentrates enable metered dosing in automated beverage production and reduce dust exposure in high-volume facilities. Texas bottling networks prefer liquid glucose and fructose for dissolution speed.
- Granulated:Free-flowing crystals suit dry blending operations in bakery and confectionery batch processing. Midwest contract manufacturers stock granulated sucrose for formulation flexibility.
- Powder:Fine particle size accelerates hydration in instant beverage mixes and pharmaceutical sachets. California CPG brands specify powdered allulose for zero-sugar launch pipelines.
- Crystal:High-purity solid forms exceed 99.5% assay for pharmaceutical-grade xylitol and specialized nutrition applications. Crystalline polyol output from North American refineries lags pediatric formulation demand.
Liquid form dominates beverage procurement; powder form is climbing the fastest in instant application segments.
Application:
End-use specifications drive purity grades, documentation requirements, and supplier qualification protocols.
- Food & Beverages:Largest demand channel spanning carbonated drinks, dairy, and prepared foods. FDA Nutrition Facts reformulation deadlines compress procurement cycles for enzymatically converted low-calorie alternatives.
- Confectionery:Hard candy, chocolate, and chewing gum production requires precise control over crystallization kinetics and glass transition temperatures. Health Canada front-of-package warning label proposals are forcing sugar reduction in Ontario and Quebec manufacturing.
- Bakery:Yeast fermentation, crumb structure, and moisture retention depend on reducing sugar availability and dextrose equivalent values. Great Lakes commercial bakeries source glucose syrups from regional corn refiners.
- Pharmaceuticals:Excipient-grade carbohydrates for tablet binding, coating, and pediatric formulations require USP-NF documentation and validated supply chains. Crystalline xylitol shortages constrain North American oral care product launches.
Food & Beverages commands volume concentration; Pharmaceuticals offers the steepest expansion trajectory.
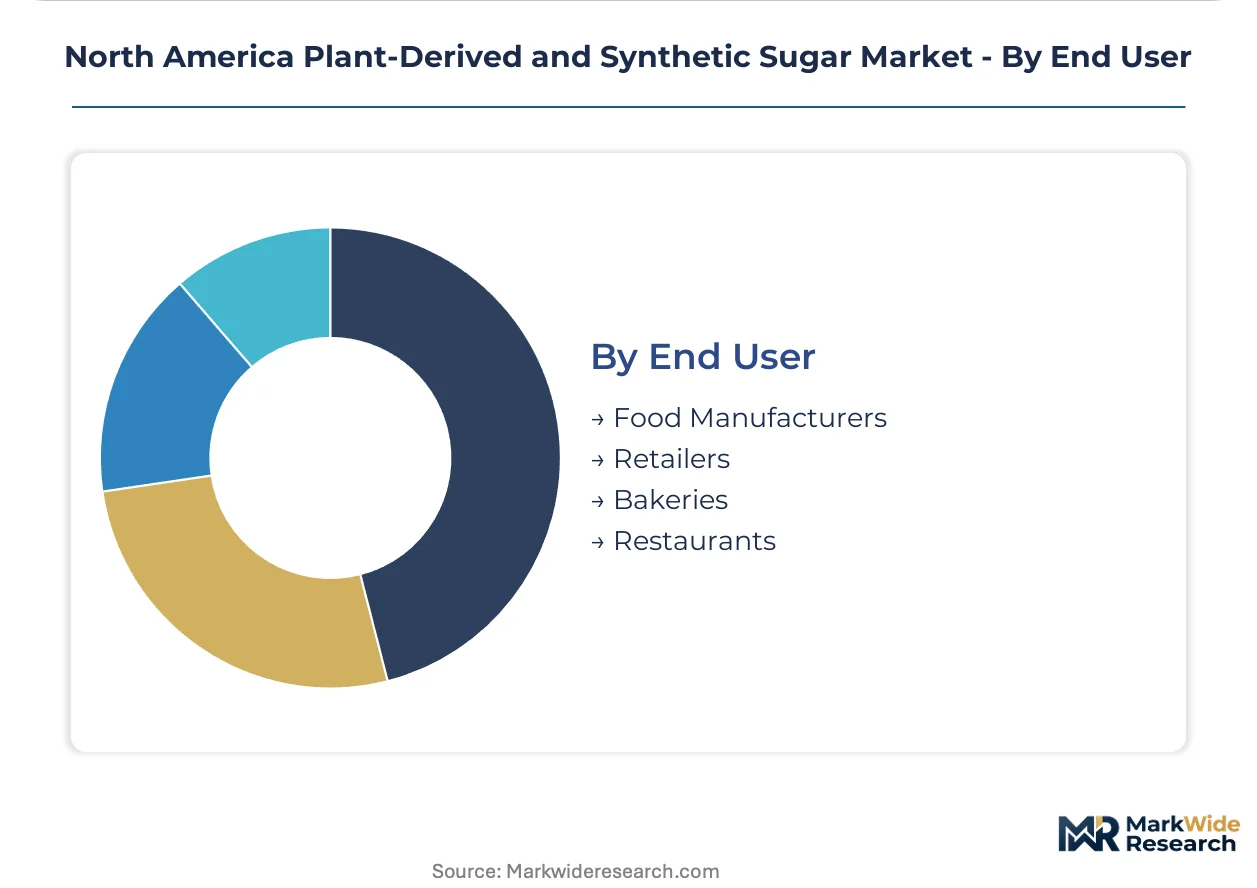
End User:
Customer scale and technical capability determine sourcing relationships, inventory models, and specification stringency.
- Food Manufacturers:Large-scale CPG brands with in-house R&D and direct refiner relationships. Nebraska and Iowa bioprocessing investments target these customers with enzymatic conversion capacity.
- Retailers:Private-label product development teams and ingredient specification groups. Health Canada labeling rules are redirecting retailer procurement toward reformulated low-sugar alternatives.
- Bakeries:Regional commercial operations and artisanal producers with batch-scale purchasing. Great Lakes independent bakeries rely on distributor intermediaries for glucose and sucrose supply.
- Restaurants:Foodservice operators with limited technical staff and standardized menu specifications. Quick-service chains in Texas and California are accelerating zero-sugar beverage rollout timelines.
Food Manufacturers anchor procurement volume; Retailers are gaining share fastest in reformulation-driven sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Great Lakes manufacturing corridor anchors North American sweetener procurement, with corn wet milling clusters supplying glucose and fructose feedstocks to regional food processors. FDA labeling mandates and Health Canada warning symbol proposals are compressing reformulation timelines across both markets.
United States
Beverage manufacturers in Texas and California are accelerating zero-sugar portfolio renovations, driving contract demand for enzymatically converted low-calorie alternatives. The FDA's added sugars disclosure requirement has triggered systematic procurement redirection toward stevia glycosides and allulose. Nebraska and Iowa bioprocessing investments target Great Lakes corridor processors with microbial fermentation capacity.
Canada
Health Canada's proposed front-of-package nutrition symbol regulations are forcing sugar reduction across Ontario and Quebec packaged food manufacturing. Alberta and Saskatchewan beet processing facilities serve eastern Canadian manufacturers seeking supply chain diversification from U.S. corn sources. Toronto-area contract bakeries are accelerating pilot trials of erythritol blends to preempt mandatory warning labels.
Mexico
Beverage bottling networks in Mexico City and Jalisco are reformulating export portfolios to meet U.S. FDA disclosure standards for cross-border product flows. Mexican cane sugar refineries supply both domestic confectionery producers and U.S. border-state manufacturers. Monterrey industrial corridors are expanding glucose syrup storage infrastructure to serve quick-service restaurant supply chains.
North America Plant-Derived and Synthetic Sugar Market Competitive Landscape
Capacity expansion dominates the current landscape as bioprocessing infrastructure investments reshape supplier positioning. The market structures around three tiers: integrated agricultural processors with captive feedstock supply, specialized enzymatic conversion technology providers, and regional distributors with formulation service capabilities. Strategic archetypes include corn wet milling specialists leveraging co-production economics, stevia extractors controlling leaf-to-powder supply chains, and polyol refiners targeting pharmaceutical-grade purity segments. Competitive moves concentrate on backward integration into Brazilian and Chinese agricultural sourcing, plus in-house production of rare sugar bioconversion capacity.
Among integrated agricultural processors, Cargill, Incorporated and Archer Daniels Midland Company exemplify the feedstock-anchored archetype with extensive Midwest refinery networks. Ingredion Incorporated occupies a position within the modified starch and glucose syrup specialist tier, leveraging deep corn wet milling expertise. These three companies represent the dominant supply-side concentration in North American caloric and non-caloric sweetener flows.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| International Flavors & Fragrances Inc. |
| Roquette Frères |
| PureCircle |
| BioNeutra Global Corporation |
| SweeGen |
| Others |
Value Network & Pricing Analysis
Large-scale CPG brands with direct refiner relationships anchor procurement volume concentration, locking in contract-based long-term offtake structures that buffer spot-market volatility for glucose and fructose feedstocks. This buyer archetype's scale dominance compresses margin capture for mid-tier distributors while elevating enzymatic conversion specialists with captive bioprocessing capacity.
Pricing Analysis
Input-cost pass-through from corn futures and Brazilian leaf sourcing governs contract negotiations for caloric and non-caloric sweeteners alike. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade purity levels reflects certification stringency and documentation burden. Cost compression in commodity glucose is intensifying because USDA ethanol mandates tighten feedstock availability. Quick-service restaurant chains exhibit highest price sensitivity due to standardized menu specifications, while pharmaceutical formulators accept premium positioning for USP-NF documented supply.
Supply Chain Analysis
Single-source vulnerability sits with Guangxi province monk fruit extraction and Brazilian stevia leaf harvesting, exposing North American formulators to climate disruption and export policy shifts. Raw material flows draw from U.S. Midwest corn belts, Canadian Prairie beet zones, and Chinese agricultural processing regions. Tariff exposure on Chinese-sourced rare sugars and extract inputs threatens margin stability for natural non-caloric segments. Distribution runs through direct sourcing agreements between refiners and bottling networks, displacing traditional ingredient distributor intermediaries in Texas and California beverage clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on enzymatic bioconversion yield improvements that collapse cost structures for rare glycoside production. Premium-tier positioning in pharmaceutical-grade xylitol and pediatric formulations offers parallel margin capture paths.
For Market Incumbents: To counter microbial fermentation entrants disrupting stevia cost economics, Cargill and ADM should deepen backward integration into Brazilian agricultural sourcing while expanding Nebraska and Iowa bioprocessing capacity. Securing Health Canada novel food notification ahead of FDA GRAS timelines creates first-mover positioning in Ontario and Quebec reformulation cycles. Capacity addition in Alberta and Saskatchewan beet processing addresses supply chain diversification demand from eastern Canadian manufacturers. For New Entrants and Emerging Players: Regional distributors with formulation service capabilities represent the most accessible channel partner type for enzymatic conversion technology providers lacking CPG direct relationships. White-space opportunity concentrates in pharmaceutical-grade crystalline polyol supply, where North American refinery output lags pediatric formulation demand. Canadian Prairie beet processing expansion offers geographic differentiation from corn-dominant U.S. supply chains. Co-development partnerships with Toronto-area contract bakeries navigating Health Canada front-of-package rules provide reformulation-driven entry points. For Investors and Strategic Acquirers: Integrated agricultural processors with captive feedstock supply is the most active acquirer in this space, targeting enzymatic conversion technology providers to consolidate rare sugar bioproduction capabilities. Long-term viability over the coming decade hinges on regulatory alignment between FDA and Health Canada approval pathways. Acquisition target archetype: mid-cap bioprocessing specialists with commercial-scale microbial fermentation expertise and validated rare sugar output. Watch for Health Canada finalizing front-of-package nutrition symbol regulations as inflection indicator for accelerated reformulation capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brazilian Leaf Sourcing | Cargill's Nebraska extraction facilities secure captive stevia glycoside supply against Brazilian agricultural cycle volatility. |
| Enzymatic Conversion Capacity Expansion | Nebraska and Iowa bioprocessing investments target Great Lakes processors with microbial Reb M and Reb D output. |
| Canadian Prairie Beet Processing Buildout | Alberta and Saskatchewan facilities serve Ontario manufacturers seeking supply chain diversification from U.S. corn sources. |
| Pharmaceutical-Grade Xylitol Refinery Investment | Crystalline polyol capacity expansion addresses pediatric formulation shortages constraining North American oral care launches. |
| Direct Sourcing Agreement Displacement of Distributors | Texas and California bottling networks bypass traditional intermediaries to compress procurement cycles for reformulated portfolios. |
Research Methodology
Bottom-up food and beverage manufacturer modeling reconciled against top-down corn wet milling and beet processing capacity tracking forms the analytical core. Primary interviews with CPG procurement directors, corn refinery plant managers, contract bakery R&D leads, and Health Canada regulatory affairs specialists combined with secondary validation from USDA crop reports, FDA GRAS notification databases, Canadian trade statistics, and SEC 10-K filings from listed agricultural processors. Triangulation across these sources ensures supply-side capacity estimates align with downstream demand specifications.
Input-output matrices map carbohydrate feedstock flows through enzymatic conversion pathways to end-use applications across the projection horizon. Segmentation dimensions span product chemistry, physical form, application channel, and end-user scale tier. CAGRs derive from installed capacity expansion schedules, regulatory reformulation deadlines, and substitution elasticity estimates for low-calorie alternatives. Forecast inputs incorporate USDA biofuel mandate adjustments, Brazilian harvest yield variability, and Health Canada labeling rule implementation timelines.
Revisions become necessary when FDA guidance on novel sweetener classifications shifts, Health Canada accelerates front-of-package warning label adoption, or Chinese export policy disrupts monk fruit extract availability. Forecasts reflect documented assumptions on enzymatic yield improvement trajectories and corn-to-ethanol allocation ratios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Crystalline Fructose Market
Sweeteners
Clarified Rice Syrup Market
Sweeteners
South Africa Food Sweetener Market
Sweeteners
Europe Plant-Derived and Synthetic Sugar Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Maltitol Market
Sweeteners
Floral Nectar Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
Europe Starch Sweetener Market
Sweeteners
Africa Stevia Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
Sweet Modulator Market
Sweeteners
South America Stevia Market
Sweeteners
Japan Allulose Market
Sweeteners
Maltol and Ethyl Maltol Market