
 Europe Natural Sweetener Market | 2026-2036
Europe Natural Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Natural Sweetener Market Intelligence
France is tilting toward expanded stevia extraction capacity to serve continental beverage and dairy clients. Roquette Freres leverages its pea-protein and plant-extraction infrastructure to anchor supply security across Western Europe. PureCircle competes through intensive R&D on glycoside purity and taste modulation for stevia formulations. Tate & Lyle PLC specializes in rare-sugar platforms that navigate the gap between natural positioning and functional performance.
Natural sweeteners comprise plant-derived or minimally processed substances that provide sweetness without synthetic chemical synthesis, typically measured by relative sweetness intensity compared to sucrose and characterized by glycemic index profiles ranging from near-zero to moderate values. These ingredients serve industrial food and beverage manufacturers seeking to reduce added sugars while maintaining consumer-acceptable taste profiles and clean-label declarations. Stevia leads volume adoption among product types due to its zero-calorie positioning and regulatory acceptance, while liquid formulations capture premium placement in beverage applications where solubility and dosing precision matter. Maple syrup occupies a narrower but higher-margin niche anchored to North American import supply chains and artisanal positioning in European specialty channels.
EMA food-contact guidelines, EFSA novel-food approvals, and EU Green Deal sustainability thresholds collectively shape which extraction methods and sourcing geographies gain market access across member states. REACH compliance for processing aids and the F-Gas Regulation on extraction solvents further filter production economics for stevia and agave suppliers. Stakeholders must monitor how CSRD disclosure requirements will cascade into supplier sustainability audits and origin-certification demands.
Market Dynamics
EU Green Deal additive restrictions and Farm-to-Fork Strategy mandates are compressing synthetic sweetener shelf space while redirecting procurement budgets toward plant-extraction infrastructure and clean-label certification pathways.
Growth Catalysts
- Clean-label procurement mandates:Major beverage manufacturers across Germany, France, and the Netherlands now require naturally derived sweeteners in reformulation briefs, pulling volume from artificial alternatives.
- REACH compliance as market filter:Registration, Evaluation, Authorisation and Restriction of Chemicals protocols for processing aids and extraction solvents favor suppliers with established European manufacturing footprints over import-dependent competitors.
- Stevia glycoside purity advances:Enzymatic bioconversion methods now yield Reb M and Reb D at commercial scale, eliminating the bitter aftertaste that previously limited high-concentration applications.
Market Restraints
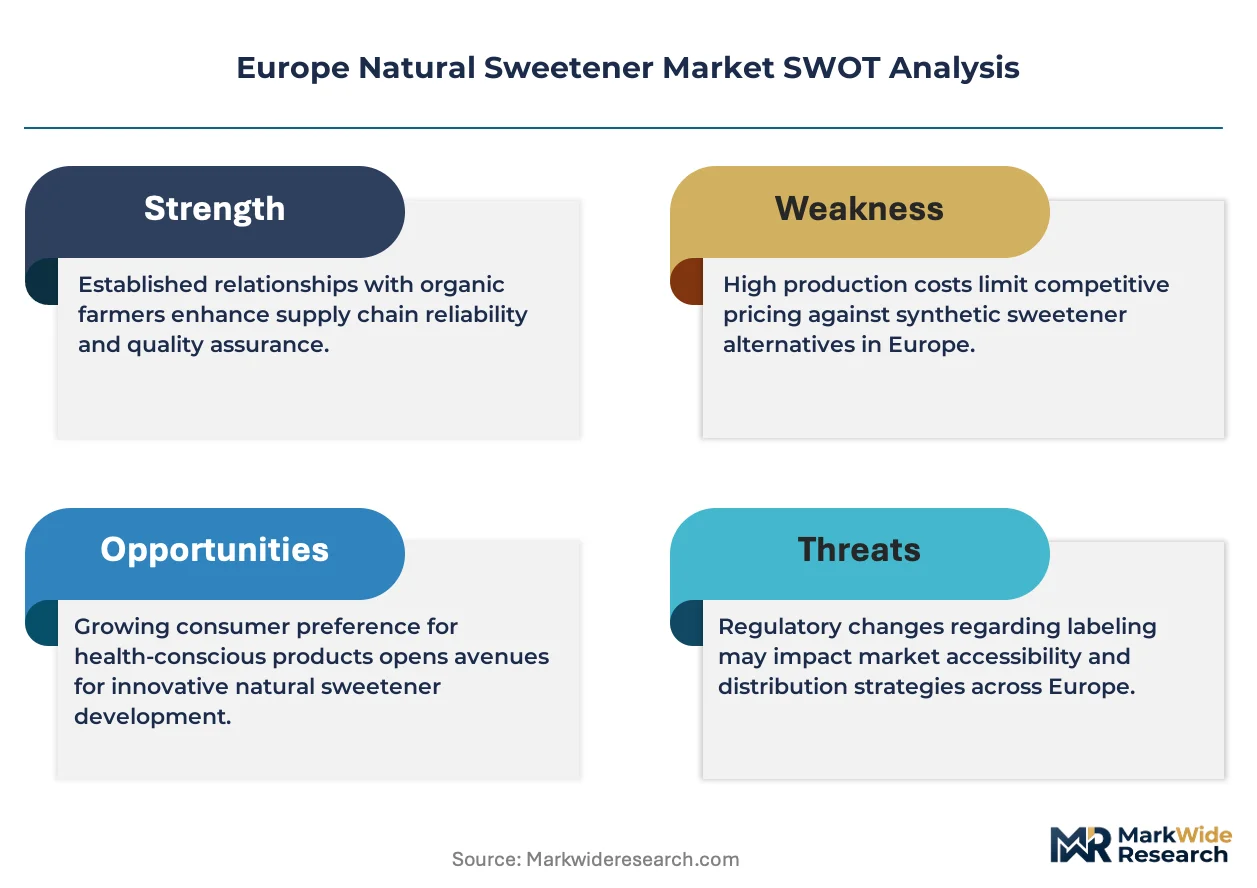
- Agave supply concentration:Over 80 percent of raw agave syrup originates from Mexican highland regions, exposing European formulators to currency volatility and harvest-cycle disruption.
- EFSA novel-food approval timelines:The European Food Safety Authority's 12-to-18-month safety assessment window for new sweetener extracts delays product launch schedules and locks up R&D capital.
- Maple syrup import dependency:North American supply chains for artisan-grade maple syrup face climate-driven yield variability and transatlantic freight cost spikes.
Strategic Opportunities
- Eastern European penetration gap:Poland, Romania, and Bulgaria show sub-15 percent natural sweetener adoption in mass-market beverages versus Western European benchmarks, creating first-mover terrain for regional production facilities.
- CSRD-driven sustainability premiums:Corporate Sustainability Reporting Directive disclosure requirements incentivize food manufacturers to source from suppliers with verified carbon-negative extraction processes and regenerative agriculture certifications.
- Fermentation-convergent biomanufacturing:Precision fermentation platforms for rare sugars such as allulose and tagatose bypass agricultural land constraints while meeting EU GMO labeling exemptions for certain strain categories.
Industry Challenges
- Cross-functional formulation expertise scarcity:Natural sweetener applications require simultaneous mastery of flavor masking, texture engineering, and stability science, a skill combination concentrated among senior technologists at established ingredient houses.
- F-Gas Regulation solvent compliance:The regulation's phasedown of hydrofluorocarbon extraction solvents forces capital-intensive retooling of stevia leaf processing lines, compressing margins for mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Natural Sweetener Market |
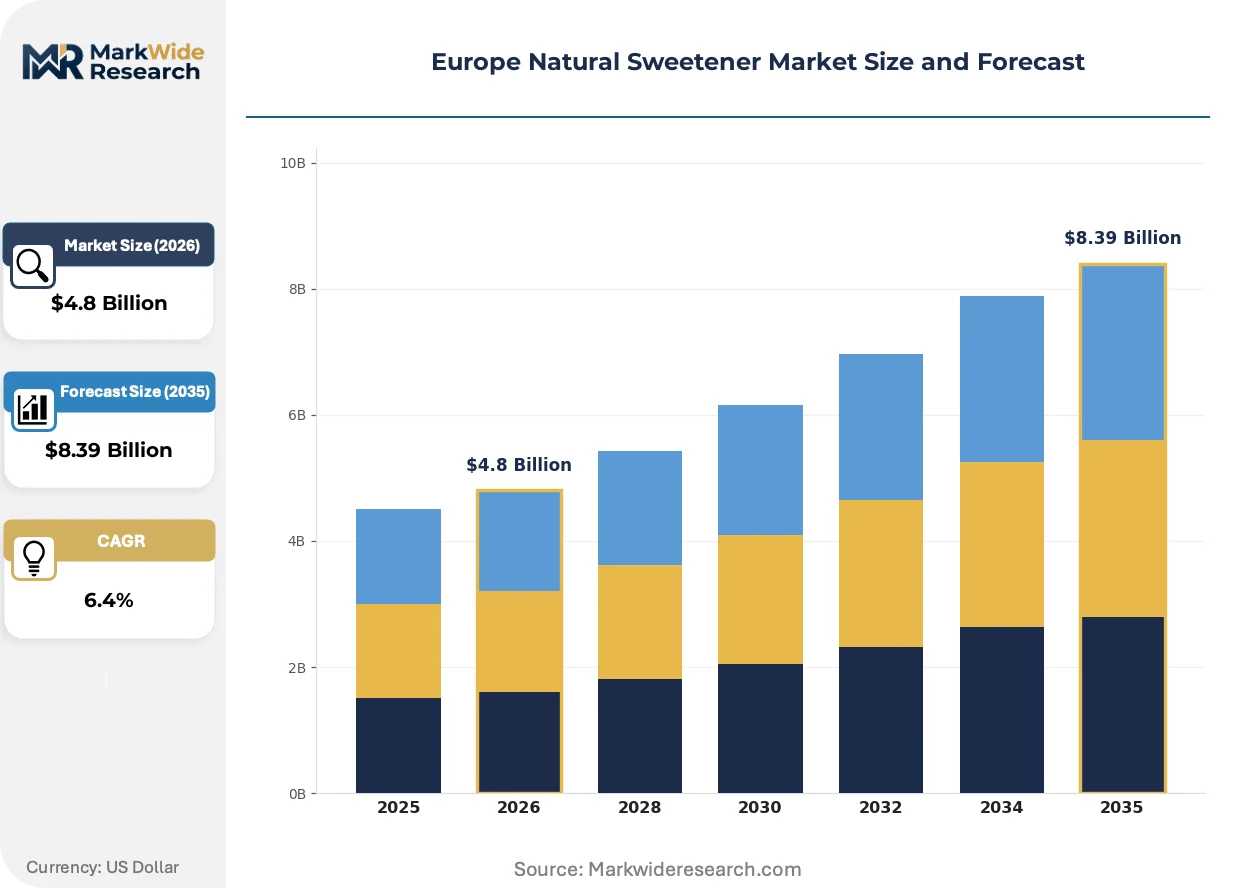
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Agave Nectar, Honey, Maple Syrup Form: Granulated, Liquid, Powdered, Crystals Application: Beverages, Baked Goods, Snacks, Dairy Products Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Roquette Freres, PureCircle, Symrise AG, Tate & Lyle PLC, DuPont de Nemours Inc., Tereos Starch and Sweeteners, HYET Sweet B.V., Cargill Incorporated, Ingredion Incorporated, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Natural Sweetener Market Strategic Shifts & Innovations
Biotechnology-enabled taste modulation and enzymatic conversion platforms are compressing the performance gap between natural and synthetic sweeteners, while regulatory disclosure mandates restructure supplier-buyer contracting terms.
Enzymatic glycoside conversion technology transforms crude stevia extracts into high-purity Reb M through selective glycosyltransferase reactions. Beverage formulators in Germany and France are adopting this at pilot-to-commercial scale within 18-month windows. The process is rendering obsolete traditional solvent-intensive purification methods that carried higher carbon footprints and bitter off-notes.
CSRD scope-three emissions disclosure rules now require large food manufacturers to document supply-chain environmental impacts. The directive forces tier-one sweetener suppliers to deploy blockchain-tracked origin certification and third-party audited carbon accounting. Dairy and plant-based beverage segments face the steepest compliance ramps, driving consolidation toward vertically integrated extraction-to-distribution operators.
Direct sourcing contracts between sweetener extractors and retail private-label divisions are displacing traditional multi-tier distribution networks. Discounters in Germany and supermarket chains in Spain now negotiate volume commitments directly with French and Dutch processing facilities, extracting price transparency and traceability guarantees. This channel compression is most visible in the own-brand beverage category, where reformulation timelines have compressed from 24 months to 8 months.
Europe Natural Sweetener Market Segmentation
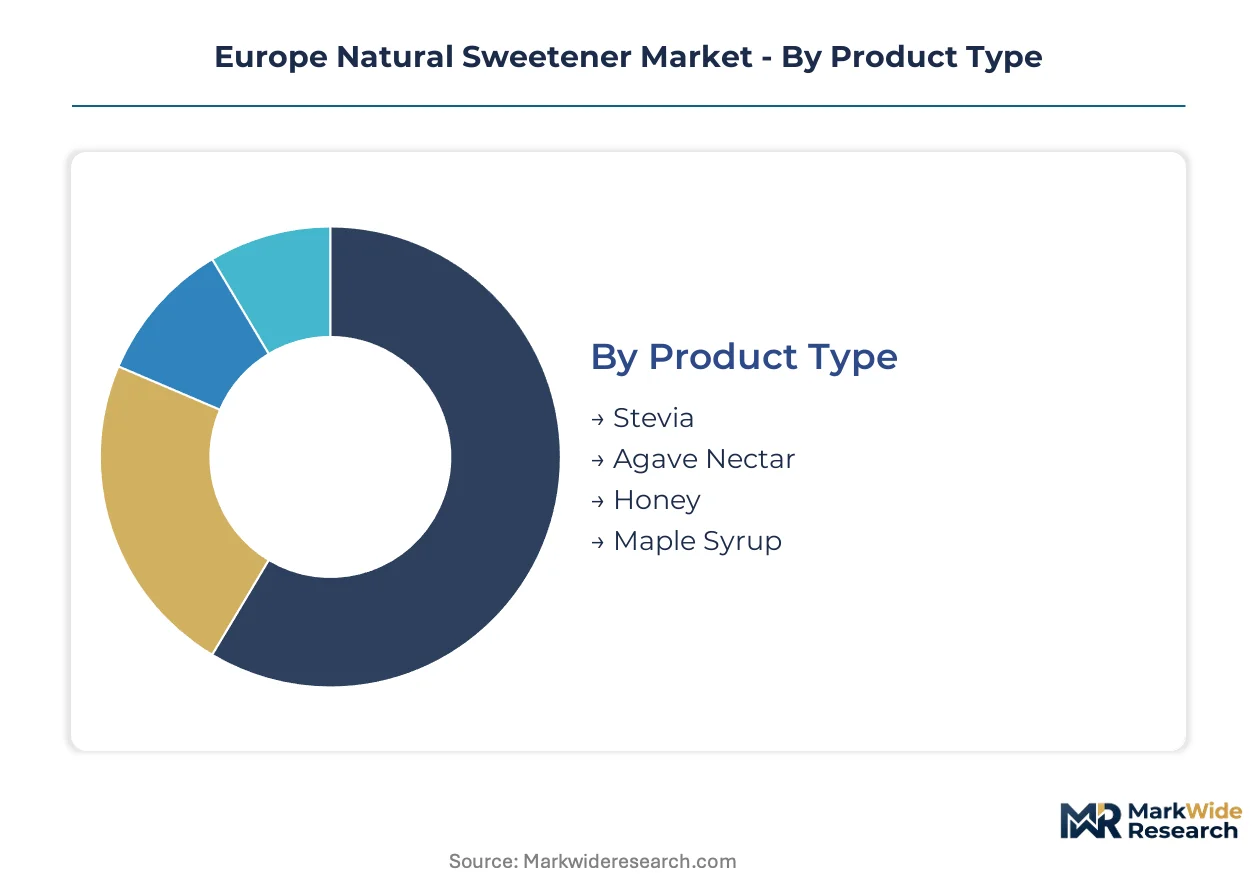
Natural sweetener purchasing patterns diverge sharply across product chemistry, physical state, and end-use application. Manufacturers must align formulation specifications with channel-specific consumer expectations and regulatory constraints governing each segment.
Product Type:
Plant-derived chemistry determines functional performance in sugar reduction and clean-label positioning across European food and beverage manufacturing.
- Stevia:Glycoside-based extracts from Stevia rebaudiana leaves deliver zero-calorie sweetness with glycemic index near zero. German beverage manufacturers are driving volume through enzymatically converted Reb M formulations that eliminate bitter aftertaste in carbonated soft drinks.
- Agave Nectar:Fructose-dominant syrup extracted from Agave tequilana and Agave salmiana varieties provides 1.4x sucrose sweetness with moderate glycemic impact. French dairy processors favor this for yogurt applications where clean-label positioning outweighs cost premiums over high-fructose corn syrup alternatives.
- Honey:Enzymatically processed floral nectar offers complex flavor profiles and antimicrobial properties valued in premium baked goods and functional beverages.
- Maple Syrup:Sucrose-rich sap reduction from Acer saccharum trees commands artisanal positioning in specialty European retail channels despite North American import dependency.
The dominant share belongs to Stevia, while Agave Nectar is closing the gap fastest.
Form:
Physical state dictates manufacturing integration complexity and dosing precision across industrial and consumer applications.
- Liquid:Pre-dissolved concentrates enable precise volumetric dosing in high-speed beverage production lines. Dutch bottling facilities are expanding liquid stevia capacity to serve reformulated zero-sugar programs for retail private-label brands.
- Granulated:Crystalline formats with bulking agents replicate sucrose handling properties for direct substitution in bakery and confectionery operations. Spanish industrial bakeries are adopting granulated blends to maintain processing equipment compatibility during sugar reduction transitions.
- Powdered:Fine-particle extracts maximize surface area for rapid dissolution in instant beverage and dry-mix applications.
- Crystals:Large-format crystalline structures suit tabletop sweetener positioning and controlled-release formulations in functional foods.
Liquid formulations command premium placement in beverage manufacturing, with Granulated formats expanding most quickly in bakery substitution programs.
Application:
End-use categories impose distinct stability, solubility, and flavor-masking requirements that filter viable sweetener selections.
- Beverages:The largest consumption category spanning carbonated drinks, juices, and functional waters where solubility and heat stability determine shelf-life performance. Italian mineral water producers are accelerating stevia adoption under EU Green Deal sugar reduction mandates.
- Baked Goods:Maillard reaction compatibility and moisture retention properties constrain viable options in bread, pastry, and cake applications. German artisan bakeries are testing honey-stevia blends to maintain browning characteristics while reducing added sugars.
- Snacks:Coating and binding applications in cereal bars and dried fruit preparations favor low-hygroscopicity formats to prevent clumping.
- Dairy Products:Fermentation tolerance and protein interaction stability filter selections in yogurt, flavored milk, and ice cream formulations.
Beverages anchor absolute volume demand, though Baked Goods is gaining share fastest as clean-label reformulation penetrates European artisan and industrial bakery segments.
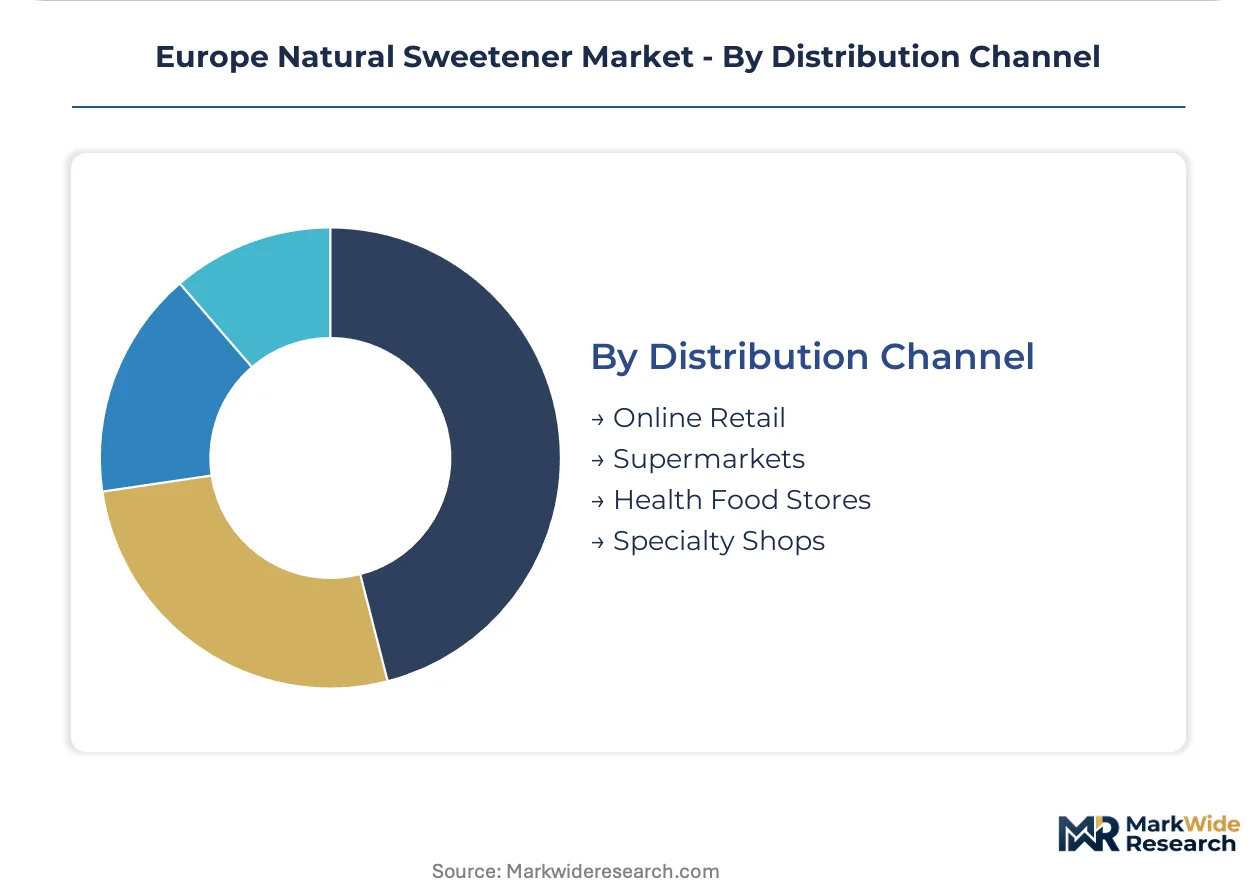
Distribution Channel:
Channel structure determines traceability requirements, pricing transparency, and technical service intensity across customer tiers.
- Supermarkets:High-volume retail chains in Germany and France are consolidating procurement through direct sourcing contracts with extraction facilities, compressing traditional distributor margins. Discounter reformulation timelines now demand 8-month supplier response cycles versus historical 24-month windows.
- Online Retail:E-commerce platforms enable specialty and bulk formats with detailed technical documentation for small-scale food manufacturers and ingredient-conscious consumers.
- Health Food Stores:Specialist retailers emphasize organic certification and origin transparency for premium-positioned natural sweeteners.
- Specialty Shops:Gourmet and ethnic food retailers curate artisanal maple syrup and single-origin honey varieties for connoisseur segments.
Supermarkets control the dominant procurement volume, while Online Retail is expanding most quickly as technical buyers seek direct supplier relationships bypassing traditional distribution tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel-food approval timelines anchor regulatory certainty across the continent, while the EU Green Deal redirects procurement budgets toward plant-extraction infrastructure. National reformulation mandates and clean-label consumer preferences are reshaping competitive positioning in Western and Eastern European markets.
Germany
Beverage manufacturers in Bavaria and North Rhine-Westphalia are accelerating stevia adoption under the national sugar reduction strategy. REACH compliance protocols for extraction solvents favor domestic processing facilities over import-dependent competitors. The Hamburg cluster hosts multiple extraction-to-distribution operators serving discounter private-label reformulation programs with compressed 8-month supplier cycles.
France
Dairy processors in the Île-de-France and Auvergne-Rhône-Alpes regions favor agave nectar for clean-label yogurt positioning. ANSM food-contact guidelines and EMA safety thresholds filter viable extraction methods for continental supply. Roquette Freres leverages its Lestrem facility in Hauts-de-France to anchor pea-protein and plant-extraction infrastructure across Western Europe.
Netherlands
Bottling facilities in the Randstad region are expanding liquid stevia capacity for zero-sugar beverage programs. The F-Gas Regulation's phasedown of hydrofluorocarbon extraction solvents forces capital retooling among mid-scale processors. Eindhoven-based biomanufacturing specialists are piloting precision fermentation platforms for rare sugars that bypass agricultural land constraints.
Spain
Industrial bakeries in Catalonia and Madrid are adopting granulated sweetener blends to maintain equipment compatibility during sugar reduction transitions. EFSA novel-food approval timelines delay product launches for new extract variants. The Valencia cluster concentrates artisanal honey sourcing for premium baked goods and functional beverage applications.
Poland
Mass-market beverage producers in Warsaw and Krakow show sub-15 percent natural sweetener adoption versus Western European benchmarks. EU Green Deal sustainability thresholds are beginning to filter supplier selection for export-oriented manufacturers. The Silesian industrial corridor is attracting first-mover extraction facility investments targeting Eastern European penetration gaps.
Europe Natural Sweetener Market Key Industry Players
Specialist extractors and diversified ingredient houses split the market across distinct capability vectors. Tier-one suppliers with integrated extraction-to-certification infrastructure capture procurement volumes from supermarket direct-sourcing contracts. Three archetypes dominate: vertically integrated plant processors with captive agricultural supply, enzymatic bioconversion technology licensors, and rare-sugar fermentation platform operators. Competitive intensity concentrates on sustainability audit readiness and CSRD-aligned carbon accounting systems.
Within the diversified ingredient house tier, Roquette Freres and Tate & Lyle PLC exemplify contrasting strategic positions. Roquette anchors supply security through its established European manufacturing footprint and plant-extraction infrastructure. Tate & Lyle occupies a position bridging natural positioning claims with functional performance requirements. Among specialist stevia extractors, PureCircle represents the enzymatic glycoside conversion archetype, with purity and taste modulation capabilities filtering into German and French beverage reformulation programs.
| Leading Market Players |
|---|
| Roquette Freres |
| PureCircle |
| Symrise AG |
| Tate & Lyle PLC |
| DuPont de Nemours Inc. |
| Tereos Starch and Sweeteners |
| HYET Sweet B.V. |
| Cargill Incorporated |
| Ingredion Incorporated |
| Others |
Cost & Logistics Intelligence
Agave supply concentration in Mexican highland regions determines both pricing tier spreads and supply chain shape across European natural sweetener procurement. EFSA novel-food approval timelines and F-Gas Regulation compliance costs compress margins for mid-scale processors while rewarding vertically integrated extraction-to-distribution operators with pricing power.
Pricing Analysis
Geographic price spreads between Western and Eastern Europe exceed three-to-one for enzymatically converted Reb M stevia formulations versus conventional extracts. Three-tier pricing structure across premium, standard, and economy levels filters by glycoside purity grade and CSRD-aligned carbon accounting certification. Pricing pressure stems from REACH compliance costs for extraction solvents and enzymatic bioconversion capital requirements. Discounter private-label buyers in Germany exhibit highest price sensitivity, while French dairy processors prioritize clean-label positioning over cost.
Supply Chain Analysis
Extended payment terms from German supermarket chains now stretch 90-120 days, forcing mid-scale extractors toward supply-chain finance facilities. Raw agave syrup draws from Mexico, stevia leaf from China and Paraguay, and maple syrup from Canada and the United States. Single-source vulnerability concentrates in Mexican agave harvest cycles exposed to climate-driven yield variability. Distribution runs through direct sourcing contracts between extraction facilities and retail private-label divisions, displacing traditional multi-tier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional formulation expertise combining flavor masking, texture engineering, and stability science remains concentrated among senior technologists at established ingredient houses, creating capability scarcity that shapes competitive outcomes.
For Market Incumbents: Entrench market position through backward integration into captive stevia leaf supply from regenerative agriculture partnerships and accelerated CSRD-aligned carbon accounting certification. Defend against precision fermentation entrants by expanding enzymatic glycoside conversion capacity in the Hamburg extraction cluster. Prioritize technical service intensity for direct-sourcing supermarket contracts with compressed 8-month reformulation cycles. For New Entrants and Emerging Players: Establish a beachhead in Poland, Romania, and Bulgaria where mass-market beverage natural sweetener adoption sits below 15 percent versus Western European benchmarks. Target the Silesian industrial corridor for first-mover extraction facility investment serving export-oriented manufacturers. Lead with fermentation-convergent biomanufacturing platforms for rare sugars that bypass agricultural land constraints and meet EU GMO labeling exemptions. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated extraction-to-certification operators with established sustainability audit infrastructure. Long-term viability across the projection horizon hinges on CSRD scope-three emissions disclosure readiness and blockchain-tracked origin certification capabilities. Watch EFSA novel-food approval acceleration as the signal for inflection in new extract variant commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Bioconversion Scale-Up | Reb M purity advances eliminate bitter aftertaste in German carbonated beverage reformulations. |
| Regenerative Agriculture Certification | CSRD-driven sustainability premiums reward suppliers with verified carbon-negative extraction processes. |
| Direct Sourcing Contract Expansion | Retail private-label divisions in Spain and Germany compress traditional distributor margins through channel compression. |
| Precision Fermentation Platform Investment | Rare sugar biomanufacturing bypasses Mexican agave supply concentration and agricultural land constraints. |
| Eastern European Production Footprint | Poland and Romania penetration gaps create first-mover terrain for regional extraction facility investments. |
Research Approach
Desk research of EFSA novel-food approval databases, EU Green Deal policy documentation, and REACH compliance registries preceded structured interviews with beverage formulation technologists, dairy procurement directors, extraction facility operations managers, and supermarket category buyers. Primary fieldwork across Germany, France, and the Netherlands validated secondary trade flow data and customs records. Bottom-up volume estimates from individual extraction facility capacities triangulated against top-down procurement budget allocations from major food manufacturers.
Assumptions held fixed include EFSA regulatory timelines, EU Green Deal sustainability threshold trajectories, and enzymatic glycoside conversion technology diffusion rates across the analysis window. Variables tested included Eastern European adoption velocity, precision fermentation platform cost curves, and CSRD disclosure requirement enforcement intensity. Segmentation modeling incorporated product chemistry, physical form, end-use application, and distribution channel dimensions. CAGRs derived from regression analysis of historical procurement volumes against reformulation program announcements and regulatory mandate implementation schedules.
Sensitivities concentrate around EFSA approval acceleration, Mexican agave harvest disruption, and F-Gas Regulation solvent phasedown timelines. Forecasts reflect documented assumptions regarding regulatory trajectory and technology adoption curves. Macroeconomic volatility, regulatory deviation, or breakthrough biomanufacturing scale-up would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Natural Sweeteners Market
Sweeteners
Citrus Molasses Market
Sweeteners
Allulose Powder Market
Sweeteners
Rice Syrup Market
Sweeteners
Asia-Pacific Starch Sweetener Market
Sweeteners
South America Low-Calorie Sweeteners Market
Sweeteners
Agave Nectar Market
Sweeteners
Icing Sugar Market
Sweeteners
Middle East and Africa Plant-Derived and Synthetic Sugar Market
Sweeteners
Molasses Market
Sweeteners
Global Low Intensity Sweeteners Market
Sweeteners
D Psicose Market
Sweeteners
Resistant Maltodextrin Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Italy Food Sweetener Market
Sweeteners
Plant-Derived Sweetener Market