
 Canada Food Sweetener Market | 2026-2036
Canada Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Food Sweetener Market Outlook
Beverage producers is recalibrating procurement priorities toward reduced-sugar formulations across carbonated soft drinks and functional beverages. Cargill Inc. leverages its broad ingredient portfolio to supply erythritol and stevia blends to Canadian bottlers. Tate & Lyle anchors its position through specialized texturant and sweetener systems for dairy alternatives. Rogers Sugar competes in the cane and beet sugar segments while navigating price volatility in domestic sucrose markets.
Food sweeteners comprise caloric and non-caloric substances—sucrose, fructose, maltitol, sucralose, steviol glycosides, and monk fruit extract—formulated to impart sweetness, control water activity, and influence browning and texture in processed foods. High-intensity sweeteners such as stevia and sucralose deliver sweetness multiples hundreds of times greater than sucrose at negligible caloric contribution. Sugars still occupy the largest value share in bakery and confectionery applications, though natural sweeteners represent the fastest-expanding margin pool as clean-label claims harden into category expectations. Sugar alcohols sustain steady volume in sugar-free confectionery and oral care-adjacent food products.
Health Canada enforces front-of-package nutrition symbol regulations that flag products exceeding prescribed sugar thresholds, directly pressuring reformulation across packaged foods. The Canadian Food Inspection Agency monitors sweetener label claims and enforces compositional standards under the Food and Drug Regulations. Health Canada's Novel Food approvals govern new plant-derived sweeteners entering commercial distribution. Stakeholders must monitor pending amendments to added-sugar disclosure rules and pre-emptively validate alternative sweetener performance in sensory and stability trials.
Market Dynamics
Health Canada's front-of-package nutrition symbol regulations are compressing formulation timelines as manufacturers race to reformulate high-sugar products before mandatory compliance deadlines trigger retail delisting risks.
Growth Catalysts
- Clean-label procurement mandates:Major Canadian grocery retailers now require suppliers to meet added-sugar thresholds for shelf placement, accelerating trials of stevia and monk fruit extracts in Ontario and Quebec processing facilities.
- Novel Food approval pathway:Health Canada's streamlined assessments for plant-derived sweeteners are reducing time-to-market for new glycoside variants and rare sugar entrants.
- Beverage reformulation pipelines:Carbonated soft drink and functional beverage producers are expanding R&D budgets to replace sucrose with high-intensity alternatives while maintaining mouthfeel and stability.
Market Restraints
- Input cost volatility:Erythritol and allulose production depends on corn feedstock pricing, exposing Canadian formulators to commodity swings in North American grain markets.
- Supply concentration risk:Steviol glycoside extraction capacity clusters in Chinese processing facilities, creating single-source vulnerability for Canadian clean-label sweetener procurement.
- Technical performance gaps:High-intensity sweeteners exhibit thermal degradation and bitter off-notes in baked applications, limiting substitution rates in artisan and industrial bakery segments.
Strategic Opportunities
- Underpenetrated Prairie provinces:Alberta and Saskatchewan food processing clusters remain reliant on conventional sucrose, creating first-mover advantage for natural sweetener technical service teams.
- Sugar alcohol convergence with fiber claims:Maltitol and isomalt formulations that deliver prebiotic effects align with Health Canada's permitted fiber labeling, opening dual-claim positioning in confectionery.
- Direct-to-manufacturer distribution:Bypassing traditional ingredient distributors through technical sales teams co-located in Toronto and Montreal food corridors reduces formulation support response times.
Industry Challenges
- Sensory science talent scarcity:Formulation chemists with expertise in sweetness modulation and temporal profile matching command premium compensation, constraining mid-tier manufacturer hiring.
- Stability validation timelines:Accelerated shelf-life testing for alternative sweeteners in acidic beverages and frozen desserts extends product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Food Sweetener Market |
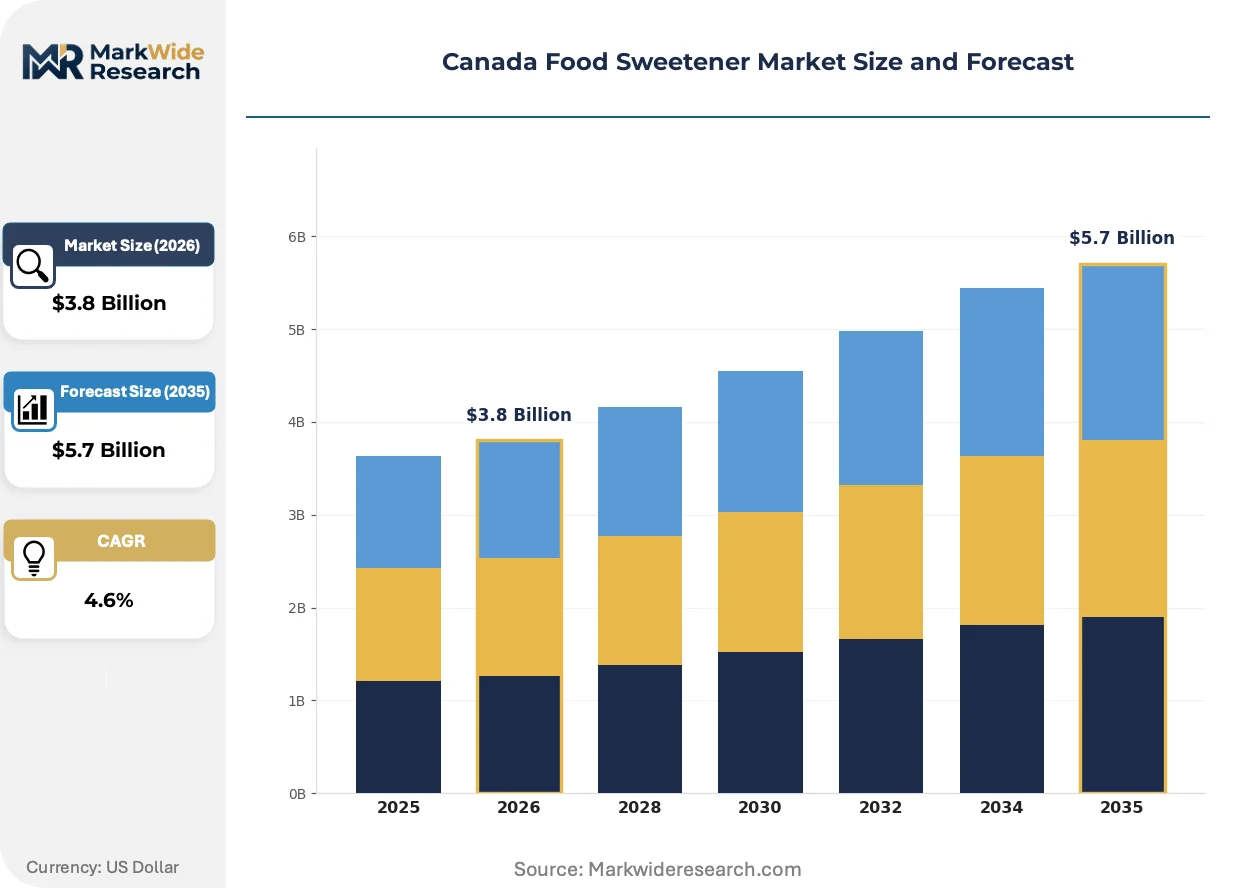
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugars, Sugar Alcohols, High-Intensity Sweeteners, Natural Sweeteners End User: Food Manufacturers, Beverage Producers, Bakeries, Restaurants Application: Confectionery, Beverages, Bakery Products, Dairy Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Tate & Lyle, Cargill Inc., Archer Daniels Midland Company, Lantic Inc., Rogers Sugar, Ingredion, Ajinomoto Co., Inc., International Flavors and Fragrances, GLG Life Tech Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Food Sweetener Market Strategic Shifts
Reformulation chemistry is advancing beyond simple substitution toward synergistic sweetener systems that replicate sucrose's bulk, browning, and freezing-point depression in a single pre-blended platform.
Enzymatic conversion of agricultural sidestreams into rare sugars is electrifying cost structures for allulose and tagatose production. Canadian bioprocessing startups are licensing cell-free enzyme cascades that transform wheat straw and corn stover into functional sweeteners at scale. This biotechnology is compressing the price premium versus cane sugar from 8-12x toward 3-4x, enabling mainstream bakery adoption.
Health Canada's 2022 front-of-package nutrition symbol regulations are forcing label redesigns across 40% of packaged food SKUs. The prescribed black-and-white high-sugar warning symbol is triggering preemptive reformulation in categories from breakfast cereals to flavored yogurts. Ontario-based co-manufacturers report 60% increase in clean-label sweetener technical inquiries since symbol draft guidance released.
Retail buyer consolidation is compressing supplier negotiation leverage as Loblaw, Sobeys, and Metro collectively control 80% of Canadian grocery shelf space. Ingredient procurement teams at these banners now mandate sugar-reduction roadmaps as a condition of category captaincy. Quebec dairy alternative producers report reformulating entire product lines within 18-month windows to retain distribution.
Canada Food Sweetener Market Segmentation
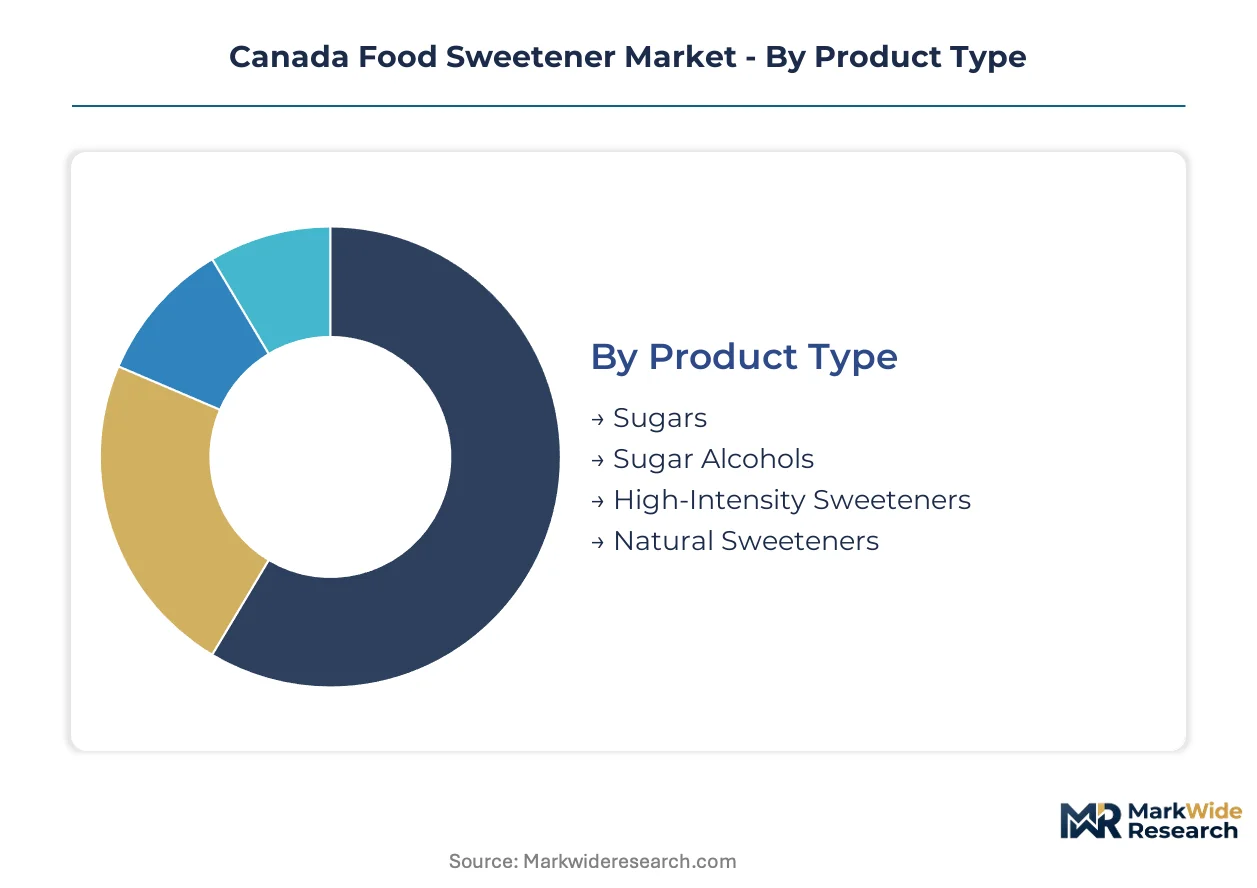
Sweetener procurement in Canada fragments across technical specifications, end-use requirements, and regulatory compliance thresholds. Formulators select ingredients based on Health Canada's Novel Food approvals, front-of-package labelling constraints, and sensory performance in specific applications.
Product Type:
Capital intensity varies sharply across extraction infrastructure, fermentation capacity, and agricultural processing investments.
- Sugars:Cane and beet sucrose production demands extensive agricultural land, milling equipment, and crystallization facilities. Ontario and Quebec refineries anchor domestic supply chains for conventional sweetener procurement in mass-market packaged foods.
- High-Intensity Sweeteners:Synthetic molecules such as sucralose and aspartame require specialized chemical synthesis plants with stringent purity controls. Steviol glycoside extraction from stevia leaves involves solvent-based or water-based processing lines with significant upfront equipment costs.
- Sugar Alcohols:Hydrogenation reactors and crystallization systems for erythritol, maltitol, and xylitol represent moderate capital deployment, typically sourced from corn feedstock processing.
- Natural Sweeteners:Monk fruit extract and allulose production leverages enzymatic conversion or solvent extraction with biotechnology licensing fees adding to facility investments.
Sugars absorb the bulk of installed capacity; natural sweeteners are expanding most quickly.
End User:
Procurement sophistication scales with formulation complexity and regulatory exposure.
- Beverage Producers:Carbonated soft drink and functional beverage manufacturers operate the most advanced reformulation pipelines, integrating high-intensity sweeteners with stability testing for acidic pH environments. Toronto and Montreal bottling clusters drive volume concentration.
- Food Manufacturers:Packaged food producers across breakfast cereals, sauces, and prepared meals balance sugar reduction targets with shelf-life requirements. Front-of-package labelling compliance deadlines accelerate ingredient switching timelines.
- Bakeries:Artisan and industrial bakeries face technical constraints in replacing sucrose's bulk and browning functionality, limiting substitution rates in cakes and pastries.
- Restaurants:Foodservice operators prioritize cost-stable procurement of conventional sugars for menu consistency, with limited clean-label adoption outside premium positioning strategies.
Food manufacturers absorb the bulk of procurement volume; beverage producers are climbing the fastest.
Application:
Functional requirements dictate sweetener selection across thermal processing, pH stability, and texture demands.
- Beverages:Liquid applications prioritize solubility and stability in acidic formulations. Health Canada's front-of-package regulations push carbonated and functional drink producers toward stevia and monk fruit blends.
- Confectionery:Sugar-free candies and chocolates rely on sugar alcohols for bulk and cooling effects, with prebiotic fiber claims opening dual-positioning opportunities.
- Bakery Products:Thermal degradation of high-intensity sweeteners constrains substitution in ovens, preserving sucrose dominance in industrial bread and cake production.
- Dairy:Yogurt and ice cream applications demand freezing-point depression control, where allulose and erythritol replicate sucrose functionality in reduced-sugar formulations.
Beverages absorb the bulk of technical service investment; dairy is gaining share fastest.
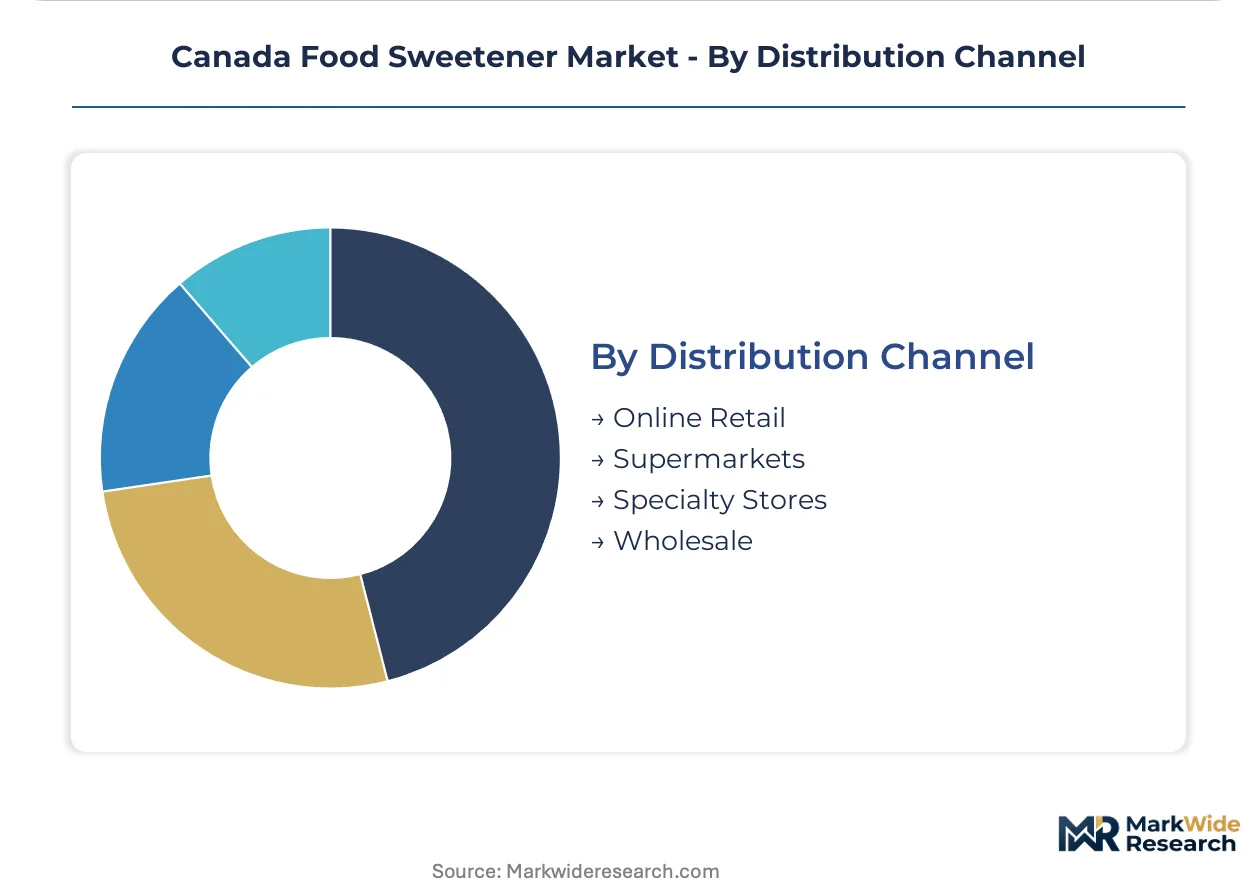
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic proximity to processing clusters.
- Wholesale:Ingredient distributors serving Ontario and Quebec food corridors manage bulk sucrose and specialty sweetener inventories with formulation support teams co-located near major manufacturers.
- Online Retail:E-commerce platforms address small-batch artisan producers and foodservice operators seeking rapid procurement of niche natural sweeteners without minimum order constraints.
- Supermarkets:Retail packaged sweeteners for consumer baking represent a declining channel as commercial procurement shifts toward direct manufacturer relationships.
- Specialty Stores:Health food retailers stock organic and non-GMO certified sweeteners targeting clean-label home bakers in urban centers.
Wholesale absorbs the bulk of volume throughput; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Scientific Research and Experimental Development (SR&ED) tax incentive program concentrates food processing R&D in Ontario and Quebec, accelerating clean-label sweetener trials and reformulation investments across provincial manufacturing clusters.
Ontario
Toronto's food corridor drives procurement volume for high-intensity sweeteners as beverage bottlers and dairy alternative producers expand reformulation pipelines. Health Canada's front-of-package labelling regulations pressure Mississauga and Hamilton manufacturers to reduce added sugars before compliance deadlines. The Golden Horseshoe processing cluster anchors stevia and monk fruit extract demand through specialized technical service teams.
Quebec
Montreal's dairy alternative sector reports accelerated clean-label sweetener adoption to retain distribution under retailer sugar-reduction mandates. The province's food manufacturing base leverages provincial R&D tax credits to validate alternative sweetener performance in stability trials. Laval and Longueuil processing facilities concentrate procurement for erythritol and allulose blends targeting frozen dessert applications.
Alberta
Calgary and Edmonton food processing clusters remain underpenetrated for natural sweeteners, creating technical service opportunities for first-mover suppliers. The province's canola and wheat processing sidestreams feed emerging bioprocessing startups developing enzymatic rare sugar conversion. Health Canada's Novel Food approval pathway reduces regulatory barriers for new plant-derived entrants targeting Prairie bakery and confectionery segments.
British Columbia
Vancouver's functional beverage and natural products sector drives premium positioning for organic certified sweeteners in clean-label formulations. The province's craft food manufacturing base prioritizes non-GMO monk fruit and stevia extracts for differentiation in saturated natural foods retail. Burnaby and Surrey co-manufacturers report rising technical inquiries for sugar alcohol and fiber dual-claim systems.
Canada Food Sweetener Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational ingredient suppliers commanding formulation partnerships while domestic sugar refiners defend conventional sucrose positions. The market structures around three tiers: global ingredient platforms with broad sweetener portfolios, regional specialists in natural extracts, and commodity processors in cane and beet sugar. Strategic moves concentrate on direct technical sales co-location near Toronto and Montreal food corridors, plus biotechnology licensing for rare sugar production scale-up.
Among global ingredient platforms, Tate & Lyle and Cargill Inc. exemplify the integrated texturant-sweetener system archetype, anchoring positions through specialized formulation support. Cargill Inc. occupies a position representing the diversified agricultural processing model, while Rogers Sugar sits within the domestic commodity refining tier. These three entities collectively illustrate the competitive spectrum from specialty high-intensity alternatives through conventional bulk sucrose supply.
| Leading Market Players |
|---|
| Tate & Lyle |
| Cargill Inc. |
| Archer Daniels Midland Company |
| Lantic Inc. |
| Rogers Sugar |
| Ingredion |
| Ajinomoto Co., Inc. |
| International Flavors and Fragrances |
| GLG Life Tech Corp. |
| Others |
Value Chain & Pricing Dynamics
Retailer sugar-reduction mandates from Loblaw, Sobeys, and Metro are compressing supplier margins as formulators absorb reformulation costs to retain shelf access, forcing ingredient distributors to restructure procurement contracts around technical service bundling rather than commodity markups.
Pricing Analysis
Short lead-time premiums for stevia and monk fruit extracts command pricing stratification across premium, standard, and economy tiers as Ontario and Quebec bottlers pay surcharges for rapid formulation support. Price differentiation hinges on certification grade (Health Canada Novel Food approval status) and volume scale, with organic-certified extracts capturing margins above conventional grades. Cost compression in erythritol and allulose is intensifying because corn feedstock volatility feeds through hydrogenation reactor economics. Mid-tier food manufacturers exhibit highest price sensitivity, while functional beverage producers prioritize performance consistency over unit cost.
Supply Chain Analysis
Returns and quality rejection flows for steviol glycoside shipments from Chinese extraction facilities create working capital drag for Canadian distributors managing temperature-sensitive inventory. Geographic supply concentration centers on China for stevia processing, Thailand for monk fruit cultivation, and domestic Ontario-Quebec corridors for corn-derived sugar alcohols. Raw material dependencies include corn feedstock for erythritol, stevia leaf biomass, and wheat straw sidestreams for enzymatic rare sugar conversion. Single-source vulnerability in Chinese glycoside extraction capacity exposes procurement teams to regulatory inspection delays. Distribution runs through Toronto and Montreal-based ingredient distributors with co-located technical service teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around formulation-capable suppliers as Health Canada's front-of-package regulations eliminate commodity-only players unable to deliver sensory-matched sugar reduction.
For Market Incumbents: Anticipate margin compression in bulk sucrose segments by accelerating technical service co-location in Calgary and Edmonton food corridors before regional competitors establish Prairie presence. Defend position through backward integration into enzymatic rare sugar production via licensing agreements with Canadian bioprocessing startups developing wheat straw conversion technology. For New Entrants and Emerging Players: The gap between premium-certified organic stevia and economy-grade conventional extracts offers entry space for mid-tier positioning with dual-label claims. Target Alberta and Saskatchewan bakery clusters still reliant on conventional sucrose, where first-mover technical teams can displace incumbent distributors through direct formulation partnerships. Lead with prebiotic fiber-sweetener dual-claim systems that align with Health Canada's permitted fiber labeling. For Investors and Strategic Acquirers: The window for entry favors vertically integrated ingredient platforms with captive extraction capacity and Health Canada regulatory navigation capabilities. Long-term viability rests on securing Chinese stevia processing relationships or domestic enzymatic conversion scale-up before price premiums compress toward cane sugar parity. Monitor Health Canada Novel Food approval timelines for rare sugar entrants as inflection indicator for biotechnology licensing valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Technical Sales Co-location | Toronto and Montreal teams reduce formulation response times for beverage reformulation pipelines. |
| Enzymatic Rare Sugar Licensing | Canadian bioprocessing startups compress allulose price premiums through wheat straw conversion technology. |
| Health Canada Novel Food Navigation | Regulatory approval expertise accelerates stevia glycoside variant commercialization timelines. |
| Retailer Sugar-Reduction Partnership | Loblaw and Sobeys category captaincy mandates lock in multi-year reformulation roadmaps. |
| Prairie Province Market Development | Alberta and Saskatchewan technical service investment captures underpenetrated bakery procurement. |
Study Parameters
Document review covered Health Canada Novel Food approval databases, Canadian Food Inspection Agency enforcement records, and provincial R&D tax credit disclosures, complemented by interviews with formulation chemists at Ontario beverage bottlers, Quebec dairy alternative producers, Alberta food processing plant managers, and procurement leads at Toronto ingredient distributors. Secondary validation drew from Statistics Canada food manufacturing surveys, Canadian Sugar Institute trade data, and provincial agricultural processing reports. Bottom-up volume estimates from individual facility procurement patterns were cross-referenced against top-down sector aggregates from industry association filings.
Historical volume trajectories were cross-referenced against expert panel inputs from technical directors at sweetener extraction facilities and regulatory affairs specialists familiar with front-of-package compliance timelines. The analytical framework segmented projections by product type (sugars, high-intensity sweeteners, sugar alcohols, natural sweeteners), end user (beverage producers, food manufacturers, bakeries, restaurants), application (beverages, confectionery, bakery, dairy), and distribution channel. CAGRs were derived from slope-consistency checks against input cost elasticity assumptions and reformulation adoption curves. Industry-specific forecast inputs included Health Canada enforcement phase-in schedules and retailer category captaincy renewal cycles.
Inputs from Health Canada regulatory filing databases and provincial R&D tax credit registries were available through the study window; gaps in private-label reformulation timelines and exact stevia extraction capacity utilization introduce uncertainty bands around natural sweetener adoption trajectories. Forecasts reflect assumptions regarding Novel Food approval processing speeds and corn feedstock price stability that regulatory amendments or commodity market shocks could revise. Practitioners should monitor Health Canada added-sugar disclosure rule amendments and Chinese environmental inspection schedules for stevia processing facilities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sanding Sugar Market
Sweeteners
North America High-Intensity Sweeteners Market
Sweeteners
Short-Chain Fructooligosaccharides (Scfos) Market
Sweeteners
Palm Sugar Market
Sweeteners
Maltitol Market
Sweeteners
Asia-Pacific Starch Sweetener Market
Sweeteners
Middle East and Africa Low Calorie Sweeteners Market
Sweeteners
North America Sugar Substitutes Market
Sweeteners
China Food Sweetener Market
Sweeteners
Refined Cane Sugar Market
Sweeteners
Asia Pacific Food Sweetener Market
Sweeteners
Aspartame Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
D Psicose Market
Sweeteners
Dextrates Market
Sweeteners
Europe Stevia Market