
 Vietnam Food Sweetener Market | 2026-2036
Vietnam Food Sweetener Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Food Sweetener Market Analytics
Domestic sugar refineries in the Mekong Delta are realigning capacity toward high-intensity sweetener blends. Cargill leverages its integrated supply chain from regional cane sourcing to finished ingredient distribution. Tate & Lyle sustains technology leadership in enzymatic starch processing for clean-label applications. Vinamilk anchors local procurement through backward integration into domestic stevia cultivation partnerships.
Food sweeteners encompass caloric and non-caloric substances added to confer sweetness, with glycemic index, heat stability, and solubility defining functional selection across industrial formulations. Sucralose maintains thermal stability up to 119°C, enabling its dominance in baked goods and UHT dairy processing where aspartame degrades. Sugar still occupies the largest volume share across beverages and confectionery, though stevia extracts command premium positioning in health-positioned product lines. Powder and granulated forms dominate manufacturing channels, while liquid concentrates gain traction in automated beverage production systems.
Vietnam's Ministry of Health and the Vietnam Food Administration enforce additive standards under the National Technical Regulation on Food Additives, with labeling compliance now mandatory for all imported sweetener batches. BIS-aligned testing protocols for heavy metals and residual solvents shape import clearance timelines and supplier qualification criteria. Stakeholders must monitor evolving draft regulations on sugar reduction targets in processed foods, as these will redirect formulation investments across dairy and bakery segments.
Market Dynamics
Vietnam's Ministry of Health tightened labeling mandates under Circular 24, forcing reformulation investments across beverage and dairy processing corridors while cane refineries pivot capacity toward high-intensity sweetener blends.
Growth Catalysts
- Clean-label enzymatic processing:Tate & Lyle's starch conversion technologies enable reduced-sugar claims in baked goods without sensory compromise, attracting health-positioned brand owners.
- Ho Chi Minh City industrial corridor concentration:Dense clustering of food manufacturers creates localized demand pull for liquid concentrate sweeteners in automated bottling lines.
- Stevia cultivation partnerships:Vinamilk's backward integration into domestic stevia farming secures supply chain control for premium product lines targeting glycemic-conscious consumers.
Market Restraints
- Import clearance friction:BIS-aligned heavy metal and residual solvent testing protocols extend batch qualification timelines for foreign sweetener suppliers.
- Technical degradation limits:Aspartame's thermal instability above 85°C excludes it from UHT dairy and baked goods applications where sucralose dominates.
- Raw material concentration risk:Mekong Delta cane supply volatility exposes domestic refineries to monsoon-driven yield fluctuations.
Strategic Opportunities
- Central Highlands stevia expansion:Underdeveloped cultivation zones in Lam Dong and Dak Lak provinces offer land-cost advantages for contract farming arrangements.
- Sugar reduction mandate anticipation:Draft Ministry of Health targets for processed food reformulation will redirect R&D budgets toward polyol and rare sugar applications.
- Direct-to-manufacturer liquid distribution:Bulk tanker delivery systems bypass traditional distributor markups for high-volume beverage processors.
Industry Challenges
- Food technologist scarcity:Limited domestic expertise in high-intensity sweetener blend optimization slows product development cycles for mid-tier manufacturers.
- Dual certification burden:Simultaneous compliance with Vietnam Food Administration additive standards and importer country requirements fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Food Sweetener Market |
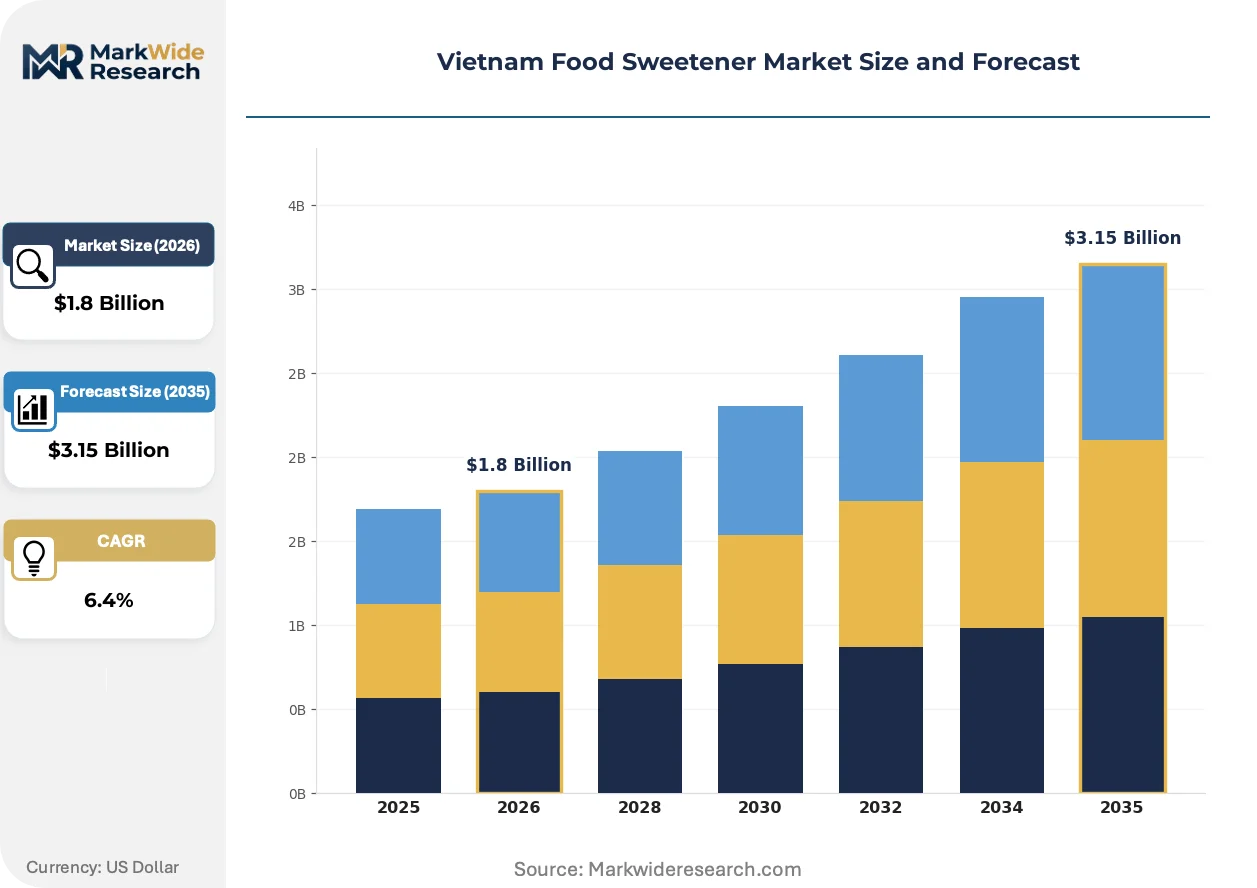
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Sugar, Stevia, Aspartame, Sucralose Application: Beverages, Bakery, Dairy, Confectionery Form: Liquid, Powder, Granulated, Syrup End User: Food Manufacturers, Restaurants, Households, Industrial |
| Companies Covered | Cargill, Tate & Lyle, Ingredion, PureCircle, Kerry Group, Stevia First Corporation, Vinamilk, CJ Foods Vietnam, Asian Blending, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Food Sweetener Market Evolving Landscape
Formulation science and procurement patterns are diverging sharply as thermal stability requirements and clean-label positioning reshape ingredient selection across Vietnam's food processing belt.
Enzymatically produced allulose is overtaking maltitol in reduced-calorie confectionery applications. Domestic chocolate and candy manufacturers are adopting the rare sugar at pilot scale ahead of anticipated sugar reduction mandates. The shift is compressing polyol volume share in premium positioning tiers where cooling aftertaste previously limited formulation flexibility.
Vietnam's Ministry of Health Circular 24 mandates explicit additive disclosure on front-of-pack labels. The regulation forces reformulation toward single-ingredient sweetness solutions that simplify consumer communication. Dairy processors in Binh Duong province are responding by consolidating multi-sweetener blends into stevia-sucralose dual systems.
Beverage manufacturers are consolidating supplier relationships around integrated cane-to-sweetener providers. Long An province processors now specify finished ingredient delivery over raw sugar procurement to reduce in-house refining capital burden. The pattern concentrates procurement authority among technical sales teams with formulation support capabilities rather than commodity traders.
Vietnam Food Sweetener Market Segmentation
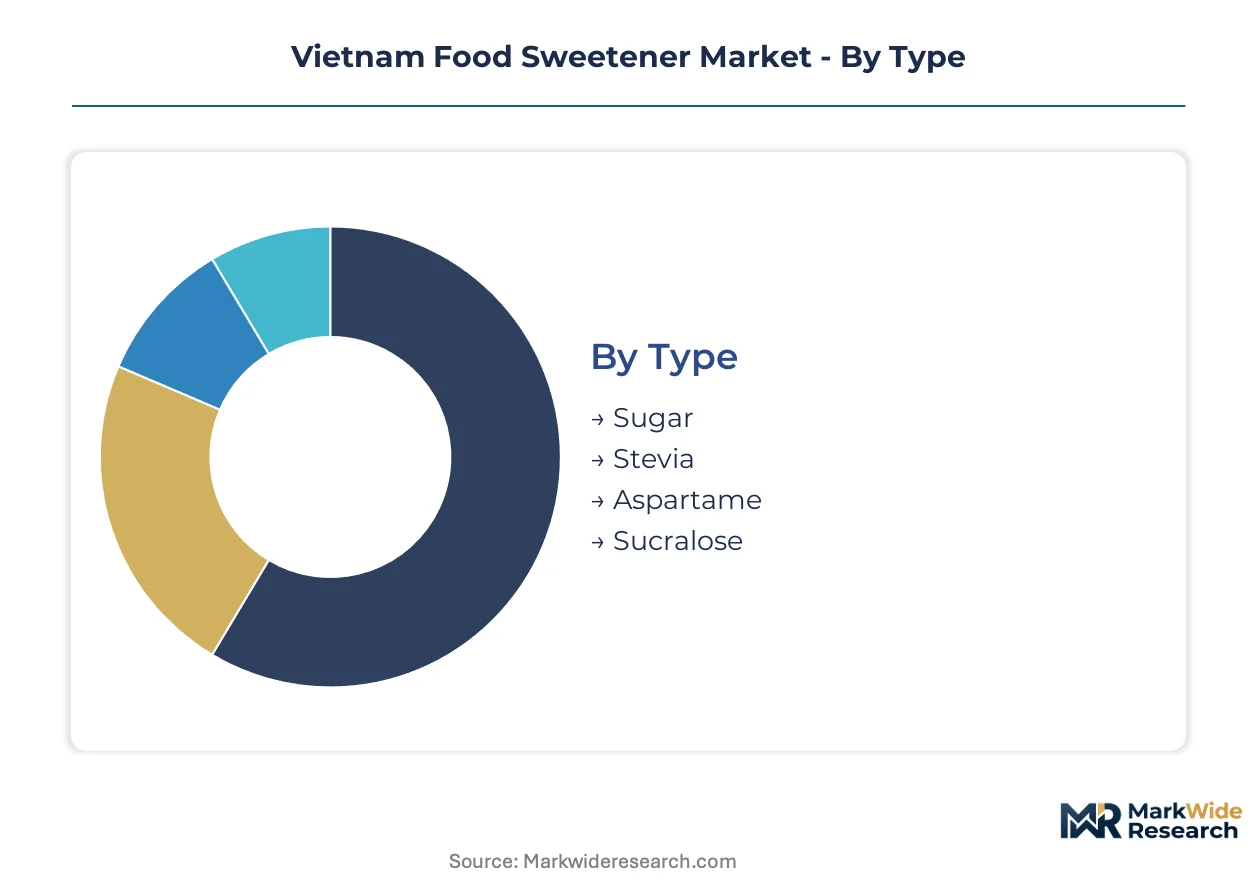
Sweetener selection in Vietnam hinges on thermal stability requirements, glycemic positioning, and automated production compatibility. Procurement patterns diverge sharply between commodity sugar buyers and specialized high-intensity formulators seeking clean-label credentials.
Type:
Cost tier dictates procurement authority, with bulk commodity buyers separating from premium-positioned health brands on formulation complexity.
- Sugar:Refined cane sugar from Mekong Delta mills supplies volume-driven beverage and confectionery channels. Ho Chi Minh City processors specify VHP and RBU grades for carbonated drinks and traditional candies where cost minimization overrides glycemic concerns.
- Stevia:Reb-A and Reb-M glycoside extracts command premium positioning in reduced-sugar dairy and functional beverages. Vinamilk's backward integration into Lam Dong cultivation secures supply chain control for glycemic-conscious product lines targeting urban health segments.
- Aspartame:Methyl ester dipeptide limited to ambient-temperature applications; dominates tabletop and cold-filled beverages where thermal exposure stays below 85°C.
- Sucralose:Chlorinated disaccharide maintains stability through UHT dairy processing and industrial baking; preferred for heat-intensive applications where aspartame degrades.
Sugar leads on scale across Ho Chi Minh City's industrial corridor; stevia leads on momentum as sugar reduction mandates advance through draft Ministry of Health regulations.
Application:
Heat exposure profiles and consumer health positioning split demand across four processing channels with distinct formulation requirements.
- Beverages:Liquid concentrate systems dominate automated bottling lines in Binh Duong and Long An provinces. Sucralose-stevia dual formulations displace single-ingredient solutions under Circular 24 labeling mandates.
- Bakery:Thermal stability above 180°C drives sucralose and maltitol selection in industrial bread and cake production; enzymatic allulose gaining traction in premium reduced-calorie positioning.
- Dairy:UHT milk and yogurt processors specify heat-stable sweeteners; stevia extracts penetrating flavored milk segments targeting parent purchasing for glycemic control.
- Confectionery:Hard candy and chocolate manufacturers balance crystallization control with cooling aftertaste management; rare sugars displacing polyols in premium tiers.
Beverages anchor procurement volume through concentrated manufacturing geography; bakery applications are expanding most quickly as enzymatic processing unlocks clean-label reduced-sugar claims.
Form:
Production automation intensity and inventory handling economics determine physical format selection across the value chain.
- Liquid:Bulk tanker delivery systems bypass distributor markups for high-volume beverage processors; concentrates enable precise dosing in continuous-flow bottling operations.
- Powder:Free-flowing blends dominate dry-mix applications and industrial-scale bakery formulations; hygroscopicity management critical for Mekong Delta humidity conditions.
- Granulated:Tabletop and small-batch food service applications; sugar-alcohol granules for reduced-calorie baking in artisanal segments.
- Syrup:Viscous formats for traditional confectionery and beverage recipes; inverted sugar syrups from domestic refineries supply heritage product manufacturers.
Powder commands the broadest manufacturing penetration; liquid concentrates gain share fastest as Long An and Binh Duong processors consolidate supplier relationships around integrated delivery systems.
End User:
Scale of operation and technical capability separate procurement patterns across four demand channels with divergent specification authority.
- Food Manufacturers:Industrial processors in Ho Chi Minh City's food processing belt drive bulk sweetener demand; formulation teams specify thermal stability and solubility parameters for automated production lines.
- Restaurants:Food service operators prioritize cost-efficient bulk sugar and tabletop alternatives; limited technical staff constrains multi-ingredient blend adoption.
- Households:Retail tabletop packets and consumer-packaged sugars; health-positioned stevia blends penetrating urban supermarket channels.
- Industrial:Ingredient suppliers and toll manufacturers producing intermediate sweetener blends for downstream formulators; BIS-aligned testing protocols shape supplier qualification.
Food manufacturers concentrate procurement authority through scale; industrial end users are climbing the fastest as toll blending and private-label formulation services expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of high-intensity sweeteners migrates toward jurisdictions with lower cost-of-compliance gaps, while Vietnam's tightening additive labeling under Circular 24 accelerates regional sourcing diversification among multinational formulators.
Ho Chi Minh City Industrial Corridor
Beverage processors in Binh Duong and Long An provinces drive concentrated demand for liquid concentrate sweeteners in automated bottling systems. Vietnam Food Administration enforcement of BIS-aligned testing protocols extends import clearance timelines for foreign suppliers. Dense manufacturing clustering here creates localized pull for heat-stable sucralose in UHT dairy applications.
Mekong Delta Cane Belt
Domestic sugar refineries in An Giang and Tien Giang provinces are pivoting capacity toward high-intensity sweetener blends. Monsoon-driven yield volatility exposes processors to raw material concentration risk during flood seasons. Cargill leverages integrated supply chains from regional cane sourcing through finished ingredient distribution to serve downstream formulators.
Central Highlands Stevia Zone
Lam Dong and Dak Lak provinces offer underdeveloped cultivation zones with land-cost advantages for contract farming arrangements. Vinamilk's backward integration into domestic stevia farming secures supply chain control for premium glycemic-conscious product lines. The region's elevation and climate suit Reb-A glycoside extraction for health-positioned dairy applications.
Northern Red River Delta
Hanoi-based food manufacturers rely on imported high-intensity sweeteners given limited local refining capacity. Vietnam Ministry of Health draft sugar reduction targets for processed foods redirect formulation investments across bakery and dairy segments. Industrial processors here face higher logistics costs versus southern competitors due to distance from primary cane supply.
Vietnam Food Sweetener Market Competitive Landscape
American and European multinationals anchor the premium formulation tier; Asian specialists hold contract manufacturing and regional distribution positions. Market structure concentrates procurement authority among integrated cane-to-sweetener providers with technical sales capabilities. Three archetypes dominate: global ingredient conglomerates with enzymatic processing platforms, domestic dairy-led integrators with captive agricultural supply, and toll blenders serving mid-tier manufacturers. Competitive moves center on backward integration into stevia cultivation and direct-to-manufacturer liquid distribution systems bypassing traditional markups.
Among global ingredient conglomerates, Cargill and Tate & Lyle exemplify the integrated supply chain archetype spanning raw material sourcing through finished formulation support. Tate & Lyle occupies a position representing enzymatic starch processing leadership for clean-label applications. Vinamilk anchors the domestic integrator tier through its stevia cultivation partnerships and backward integration into Lam Dong farming operations. These three represent distinct competitive vectors: multinational scale, technology licensing, and captive agricultural supply.
| Leading Market Players |
|---|
| Cargill |
| Tate & Lyle |
| Ingredion |
| PureCircle |
| Kerry Group |
| Stevia First Corporation |
| Vinamilk |
| CJ Foods Vietnam |
| Asian Blending |
| Others |
Value Network & Pricing Analysis
Backward integration into stevia cultivation anchors both supply security and margin protection for Vietnamese dairy processors facing Circular 24 labeling mandates. Cargill's cane-to-sweetener pipeline demonstrates how captive agricultural sourcing compresses procurement costs while insulating against Mekong Delta yield volatility.
Pricing Analysis
Distributor markups on imported high-intensity sweeteners face compression as Long An beverage processors shift toward direct bulk tanker delivery. Pricing stratifies across premium Reb-M stevia extracts, standard Reb-A glycosides, and economy-grade cane sugar based on glycemic positioning and thermal stability certification. Cost pressure intensifies in polyol segments as enzymatic allulose displaces maltitol in reduced-calorie confectionery. Mid-tier bakery manufacturers exhibit highest price sensitivity due to thin formulation budgets and limited technical staff for blend optimization.
Supply Chain Analysis
Refurbishment flows for industrial sweetener blending equipment remain minimal given specialized stainless-steel tank specifications and hygiene requirements. Vietnam draws cane feedstock from domestic Mekong Delta mills and Thai cross-border suppliers, with Reb-A glycoside extraction inputs sourced from Lam Dong cultivation zones. Single-source vulnerability concentrates in stevia leaf supply during Central Highlands monsoon disruption. Distribution runs through Ho Chi Minh City chemical distributors with formulation technical support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's food sweetener market compounds steadily as sugar reduction mandates advance through Ministry of Health regulatory channels. Reformulation investments across dairy and beverage corridors create durable demand for heat-stable, clean-label solutions.
For Market Incumbents: Deepen backward integration into Lam Dong and Dak Lak stevia cultivation to secure supply chain control against emerging contract farming competitors. Expand direct liquid concentrate delivery infrastructure in Binh Duong to capture margin from distributor bypass. Invest enzymatic processing capacity ahead of anticipated rare sugar demand acceleration from draft sugar reduction targets. For New Entrants and Emerging Players: Enter via toll blending services for mid-tier bakery manufacturers lacking in-house food technologist expertise. Target Central Highlands stevia contract farming arrangements with land-cost advantages versus established Mekong Delta cane operations. Lead with formulation support capabilities rather than commodity trading to differentiate from incumbent distributors. For Investors and Strategic Acquirers: Roll-up economics work for regional toll blenders with Vietnam Food Administration certification and established beverage processor relationships because formulation complexity barriers limit new competitor entry. Monitor draft Ministry of Health sugar reduction mandate finalization as inflection signal for polyol and rare sugar investment timing. Prioritize targets with captive stevia supply or enzymatic processing licenses.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stevia Cultivation | Vinamilk's Lam Dong farming partnerships demonstrate supply security for premium glycemic-conscious product lines. |
| Direct-to-Manufacturer Liquid Distribution | Bulk tanker systems in Long An bypass traditional distributor markups for high-volume beverage processors. |
| Enzymatic Allulose Capacity Expansion | Tate & Lyle's starch conversion platforms enable clean-label reduced-sugar claims ahead of mandate implementation. |
| Central Highlands Contract Farming Expansion | Underdeveloped Lam Dong and Dak Lak zones offer land-cost advantages for Reb-A glycoside supply. |
| Integrated Cane-to-Sweetener Supply Chain | Cargill's regional sourcing through finished ingredient distribution compresses procurement costs for downstream formulators. |
Research Methodology
Bottom-up beverage and dairy processor demand modeling reconciled against top-down cane refining and stevia extraction capacity tracking forms the analytical core of this study. Primary interviews with Vietnam Food Administration compliance officers, Ho Chi Minh City procurement directors at industrial food manufacturers, Central Highlands agricultural extension specialists, and enzymatic processing technology suppliers combined with secondary validation from customs import records, Ministry of Health circular filings, and Vietnam Sugar Association production statistics. Triangulation across these sources ensures segment-level accuracy.
Input-output matrices map sweetener type, application heat exposure requirements, and physical form against end-user scale tiers across the projection horizon. Segmentation dimensions include thermal stability certification grade, glycemic positioning tier, automated production compatibility, and regional manufacturing cluster density. CAGRs derive from fitted growth curves calibrated to regulatory milestone timing and downstream formulation investment patterns. Forecast inputs incorporate Mekong Delta cane yield variance and Circular 24 compliance cost pass-through assumptions.
The model holds under stable Ministry of Health regulatory enforcement; deviation in sugar reduction mandate finalization timing or Central Highlands climate disruption severity would shift volume trajectories. Practitioners should monitor draft regulation advancement and monsoon pattern indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Europe Food Sweetener Market
Sweeteners
Polyphenol Sweetener Market
Sweeteners
Isomaltooligosaccharide Market
Sweeteners
Aspartame Market
Sweeteners
Rare Sugar Market
Sweeteners
Dextrates Market
Sweeteners
Maltitol Market
Sweeteners
North America Starch Sweetener Market
Sweeteners
Crystalline Fructose Market
Sweeteners
D-Mannose Market
Sweeteners
Allulose Market
Sweeteners
Xylitol Injection Market
Sweeteners
China Food Sweetener Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Citrus Molasses Market
Sweeteners
Sorbitol Market