
 China Saccharin Market | 2026-2036
China Saccharin Market Size, Share, and Industry Trends Forecast 2026-2036
China Saccharin Market Intelligence
GB 1886.18, the national food additive standard for saccharin and its salts, is redrawing competitive boundaries among Chinese manufacturers. Foodsweet Co., Ltd. leverages its integrated benzoic acid-to-saccharin production chain to control input costs. HENAN KAIFENG PINGMEI SHENMA XINGHUA FINE CHEMICAL CO., LTD. anchors its position through captive supply of ortho-toluenesulfonamide feedstock. Shandong Newnature Biotechnology Co., Ltd. specializes in high-purity sodium saccharin grades that meet pharmaceutical excipient specifications.
Saccharin refers to the synthetic high-intensity sweetener derived from toluene via the Remsen-Fahlberg or Maumee synthesis routes, with a sweetness intensity approximately 300-500 times that of sucrose and zero caloric content. Industrial production centers on sodium saccharin dihydrate crystallization, where purity levels above 99.0% determine eligibility for food-grade versus technical-grade applications. Sodium saccharin dominates volume flows due to its superior solubility profile in beverage formulations, while crystal saccharin retains niche demand in tabletop sweetener compounding. The pharmaceutical applications segment commands premium pricing through excipient-grade certification requirements, whereas food industry procurement operates on contract-volume efficiency metrics.
SAMR enforces food additive labeling and purity standards that directly determine market access for domestic saccharin batches. MEE oversight of chemical manufacturing emissions shapes production site licensing and capacity expansion timelines in Shandong and Henan provinces. GB standards alignment with Codex Alimentarius frameworks determines export eligibility for Chinese saccharin moving into Southeast Asian processed food supply chains. Stakeholders must monitor how SAMR's evolving sweetener maximum usage limits in beverage categories will redirect formulation decisions among downstream buyers.
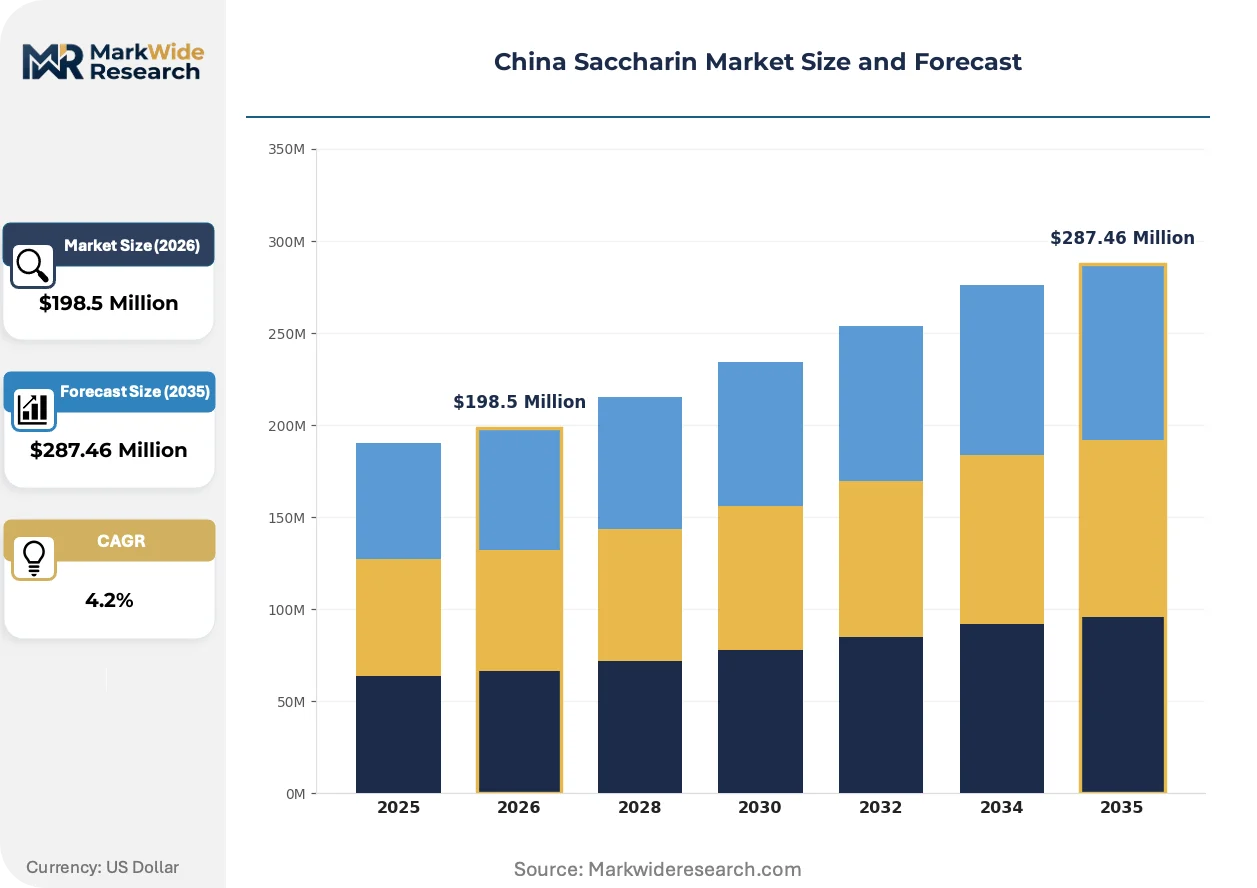
Market Dynamics
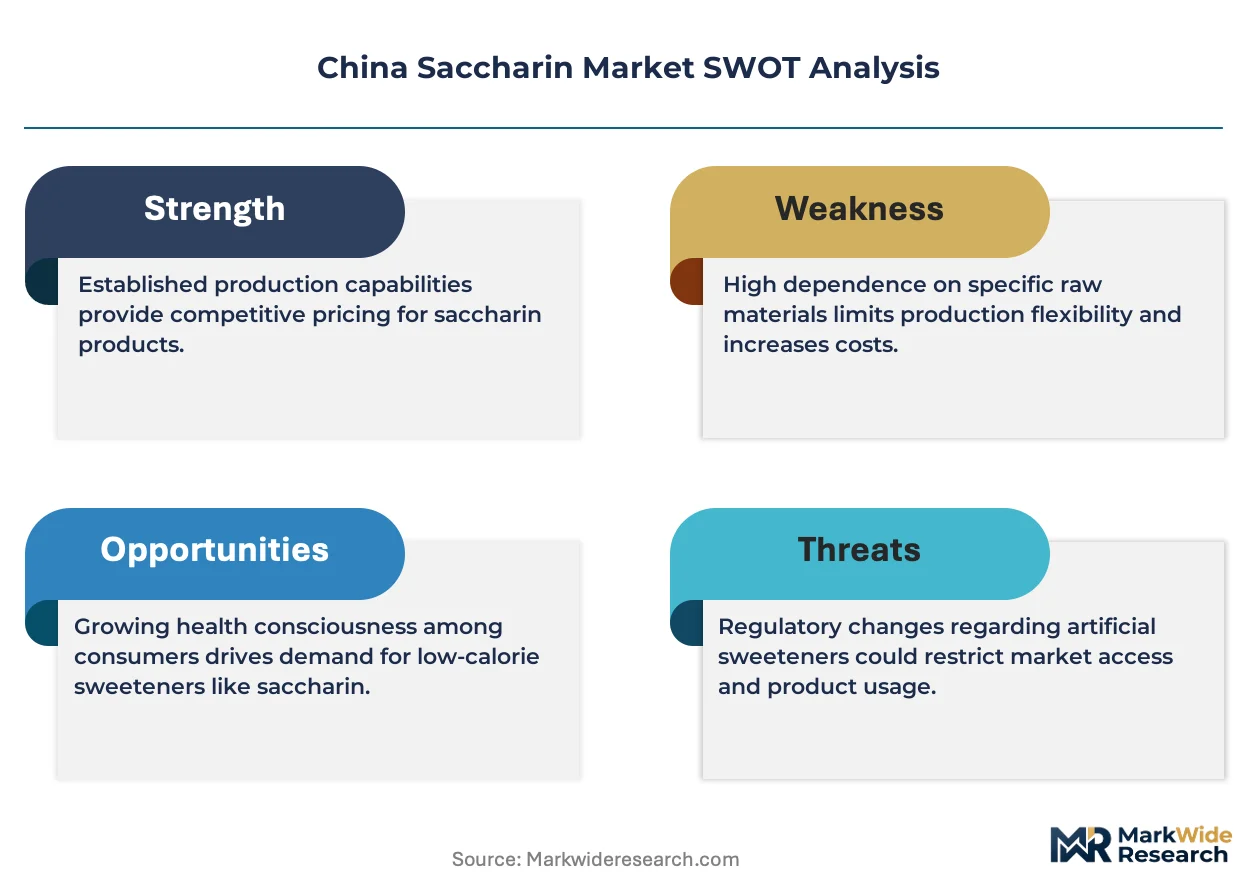
GB 1886.18 purity mandates are compressing margins for unintegrated saccharin producers while concentrating supply authority among Shandong-based refiners with captive feedstock access.
Growth Catalysts
- Low-calorie beverage formulation:Carbonated drink manufacturers in Guangdong and Zhejiang provinces are expanding sodium saccharin procurement volumes. SAMR's maximum usage limits remain permissive relative to Codex Alimentarius ceilings.
- Pharmaceutical excipient certification:Domestic drug manufacturers are qualifying high-purity sodium saccharin grades for tablet disintegrant applications. NMPA's excipient master file requirements favor suppliers with documented impurity profiles.
- Dual carbon policy alignment:MEE emissions permits now favor producers with integrated toluene recovery systems. Shandong facilities with closed-loop solvent handling command preferential licensing timelines.
Market Restraints
- Ortho-toluenesulfonamide supply concentration:Three Henan-based intermediates producers control domestic feedstock availability. Price volatility in this input directly transmits to saccharin dihydrate production economics.
- Stevia and sucralose substitution:Natural-origin high-intensity sweeteners are capturing tabletop and beverage applications where clean-label positioning commands retail premiums.
- GB standard compliance costs:Heavy metal and benzoate impurity testing requirements force capital expenditure on HPLC and atomic absorption equipment.
Strategic Opportunities
- Pharmaceutical-grade export channels:Southeast Asian generic drug manufacturers are qualifying Chinese excipient-grade sodium saccharin for EU-directed shipments. Codex Alimentarius alignment simplifies regulatory dossier preparation.
- Technical-grade industrial sweetening:Electroplating and pesticide formulation sectors in Jiangsu province present volume demand with less stringent purity requirements.
- Biotechnology-derived alternatives:Fermentation-based sweetener platforms are converging with synthetic chemistry expertise among Shandong fine chemical clusters.
Industry Challenges
- Analytical chemistry talent scarcity:GB 1886.18 compliance requires specialized chromatography and spectroscopy expertise that commands premium compensation in Shandong's competitive chemical sector.
- Legacy batch reactor integration:Continuous crystallization technology adoption is blocked by sunk costs in conventional dihydrate production trains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Saccharin Market |
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $287.46 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystal Saccharin, Sodium Saccharin, Liquid Saccharin, Others Application: Food Industry, Beverage Industry, Pharmaceutical Applications, Personal Care Products End User: Food Manufacturers, Beverage Companies, Cosmetic Manufacturers, Dietary Supplements Distribution Channel: Online Retail, Direct Sales, Wholesale Distribution, Supermarkets |
| Companies Covered | Foodsweet Co., Ltd., HENAN KAIFENG PINGMEI SHENMA XINGHUA FINE CHEMICAL CO., LTD., Shaanxi Greenbo Biochem Co.,Ltd, TwoLions (Zhangjiagang) Fine Chemicals Co., Ltd., Shandong Newnature Biotechnology Co., Ltd., Shandong Benyue Biological Technology Co., Ltd., Tianjin Changjie Chemical Co., Ltd., Shanghai Fortune Chemical Co., Ltd., Kaifeng Xinghua Fine Chemical LTD, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Saccharin Market Strategic Shifts & Innovations
Membrane filtration and continuous crystallization systems are redrawing process economics among Shandong refiners. Regulatory stringency and buyer consolidation are simultaneously compressing supplier margins and rewarding scale.
Continuous flow manufacturing is fragmenting traditional batch production dominance in sodium saccharin crystallization. Beverage compounders with annual procurement volumes exceeding 500 metric tons are mandating supplier adoption of in-line purity monitoring. This technology compression is eliminating smaller batch operators unable to amortize automation capex.
SAMR's draft revision to GB 1886.18 proposes tightened limits on ortho-toluenesulfonamide residuals and heavy metal contaminants. Domestic producers with integrated feedstock control are pre-positioning compliance dossiers ahead of implementation. Pharmaceutical excipient applications face the steepest certification burden under the proposed testing protocols.
Direct procurement contracts between saccharin refiners and national beverage brands are displacing layered distribution through regional chemical traders. Carbonated drink manufacturers in Shanghai and Guangzhou are consolidating supplier panels to three qualified sources with dedicated quality agreements. This channel compression is most advanced in premium low-calorie product lines where traceability requirements are strictest.
China Saccharin Market Segmentation
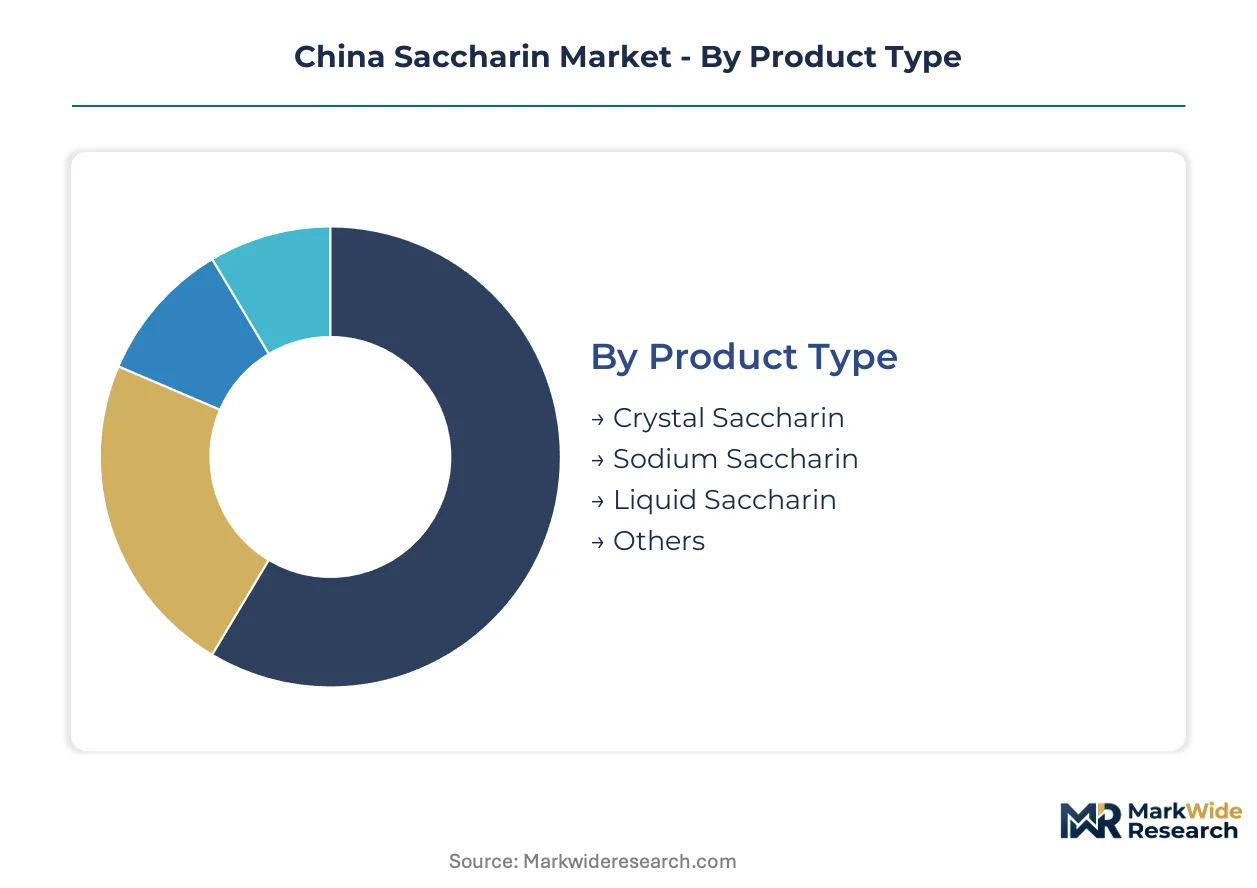
Channel configuration in the China saccharin market varies sharply by product grade and buyer scale. Beverage compounders with annual procurement exceeding 500 metric tons increasingly bypass distributors for direct refiner contracts, while smaller food manufacturers remain dependent on regional wholesale networks.
Product Type:
Crystal saccharin and sodium saccharin move through fundamentally different channel structures, with the former concentrating in tabletop sweetener compounding and the latter dominating industrial beverage formulation.
- Sodium Saccharin:The dihydrate crystalline form delivers superior aqueous solubility for carbonated drink manufacturing. Demand concentrates in Guangdong and Zhejiang province beverage clusters where SAMR maximum usage limits remain permissive relative to Codex Alimentarius ceilings.
- Crystal Saccharin:The free acid form serves tabletop sweetener blending and pharmaceutical excipient applications requiring precise dosing control. Procurement flows through specialized chemical distributors serving compounders in Shanghai and Guangzhou with dedicated quality agreements.
- Liquid Saccharin:Pre-dissolved aqueous solutions target small-scale food manufacturers lacking crystallization handling infrastructure.
- Others:Calcium and potassium salt variants address niche dietary supplement formulations with sodium-restricted positioning.
Sodium saccharin dominates installed base. Crystal saccharin is where expansion concentrates for pharmaceutical excipient certification.
Application:
Application segmentation tracks directly with purity tier requirements, where food-grade and excipient-grade specifications command divergent pricing structures and supplier qualification protocols.
- Beverage Industry:Low-calorie carbonated drink manufacturers in Guangdong and Zhejiang provinces are expanding procurement volumes. National brands are consolidating supplier panels to three qualified sources with documented impurity profiles and in-line purity monitoring systems.
- Pharmaceutical Applications:High-purity sodium saccharin grades serve tablet disintegrant and coating applications under NMPA excipient master file requirements. Southeast Asian generic drug manufacturers are qualifying Chinese suppliers for EU-directed shipments.
- Food Industry:Processed food manufacturers utilize saccharin for baked goods, confectionery, and preserved fruit applications with GB 1886.18 compliance documentation.
- Personal Care Products:Toothpaste and mouthwash formulations incorporate saccharin for sweetness masking of active pharmaceutical ingredients.
Beverage applications anchor volume throughput. Pharmaceutical applications generate the steepest margin expansion trajectory.
End User:
End user scale determines contract structure, with procurement patterns bifurcating between multinational beverage brands with dedicated quality agreements and fragmented regional food processors.
- Beverage Companies:National carbonated drink manufacturers in Shanghai and Guangzhou are mandating supplier adoption of continuous crystallization technology and automated HPLC testing protocols.
- Food Manufacturers:Regional processed food producers in Shandong and Jiangsu provinces rely on wholesale chemical distribution with batch-specific certificates of analysis.
- Cosmetic Manufacturers:Oral care product formulators in Guangdong province source technical-grade saccharin through specialized personal care ingredient distributors.
- Dietary Supplements:Nutraceutical compounders utilize potassium and calcium saccharin variants for sodium-restricted product positioning.
Beverage companies command the most aggressive supplier consolidation. Dietary supplements represent the fastest-climbing demand tier.
Distribution Channel:
Channel structure is compressing as procurement scale thresholds trigger direct refiner relationships, displacing layered distribution through regional chemical traders.
- Direct Sales:Refiner-to-manufacturer contracts dominate procurement for buyers exceeding 500 metric tons annually, with dedicated quality agreements and quarterly price negotiations.
- Wholesale Distribution:Regional chemical traders in Shandong and Henan provinces serve mid-scale food manufacturers with fragmented batch requirements and limited storage infrastructure.
- Online Retail:E-commerce platforms target small tabletop sweetener compounders and research institutions with packaged laboratory-grade quantities.
- Supermarkets:Consumer-facing tabletop sweetener products reach retail shelves through packaged goods distribution networks.
Direct sales channels capture the highest volume flows. Wholesale distribution retains the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao Port container terminal underwrites Shandong Province's dominance in saccharin feedstock logistics, connecting ortho-toluenesulfonamide producers to downstream refineries across the Bohai Economic Rim.
Shandong Province
Beverage manufacturers in Weifang and Zibo are expanding sodium saccharin procurement for low-calorie carbonated drink lines. MEE emissions permits now favor producers with integrated toluene recovery systems operating in the Shandong Peninsula Chemical Industrial Park. The province's fine chemical clusters in Dongying and Binzhou command preferential licensing timelines through closed-loop solvent handling infrastructure.
Henan Province
Three intermediates producers in Kaifeng control domestic ortho-toluenesulfonamide feedstock availability for saccharin dihydrate synthesis. SAMR's draft GB 1886.18 revision is forcing capital expenditure on HPLC testing equipment among unintegrated manufacturers. The Kaifeng fine chemical industrial zone anchors captive supply chains linking coal-chemical toluene derivatives to saccharin salt production.
Guangdong Province
Carbonated drink manufacturers in Guangzhou and Shenzhen are consolidating supplier panels to three qualified sources with documented impurity profiles. The Pearl River Delta's beverage formulation clusters mandate in-line purity monitoring systems for annual procurement exceeding 500 metric tons. SAMR maximum usage limits for saccharin in beverage categories remain permissive relative to Codex Alimentarius ceilings.
Zhejiang Province
Hangzhou and Ningbo food processors are qualifying high-purity sodium saccharin grades for pharmaceutical excipient applications under NMPA master file requirements. The Yangtze River Delta's pharmaceutical manufacturing corridor is driving demand for tablet disintegrant-grade saccharin with certified heavy metal limits. Ningbo Zhoushan Port facilitates export shipments to Southeast Asian generic drug manufacturers.
Jiangsu Province
Electroplating and pesticide formulation sectors in Suzhou and Nanjing present volume demand for technical-grade saccharin with less stringent purity requirements. The province's industrial chemical distribution networks serve mid-scale compounders lacking crystallization handling infrastructure. MEE oversight of chemical manufacturing emissions shapes production site licensing in the Jiangbei New Area chemical parks.
China Saccharin Market Key Industry Players
Listed leaders compete with private specialists across feedstock integration depth, with public chemical conglomerates leveraging balance sheet capacity for emissions compliance upgrades while family-controlled refiners exploit captive ortho-toluenesulfonamide supply. The vendor base organizes into three archetypes: integrated coal-chemical operators with backward reach into toluene derivatives, standalone saccharin refiners dependent on merchant feedstock, and pharmaceutical-grade specialists certifying excipient purity tiers. Dominant competitive moves center on M&A targeting captive feedstock access and strategic partnerships with national beverage brands for direct procurement contracts.
Within the integrated operator tier, Foodsweet Co., Ltd. and HENAN KAIFENG PINGMEI SHENMA XINGHUA FINE CHEMICAL CO., LTD. exemplify divergent approaches to supply chain control. Shandong Newnature Biotechnology Co., Ltd. occupies a position among pharmaceutical-grade specialists targeting NMPA excipient certification requirements.
| Leading Market Players |
|---|
| Foodsweet Co., Ltd. |
| HENAN KAIFENG PINGMEI SHENMA XINGHUA FINE CHEMICAL CO., LTD. |
| Shaanxi Greenbo Biochem Co.,Ltd |
| TwoLions (Zhangjiagang) Fine Chemicals Co., Ltd. |
| Shandong Newnature Biotechnology Co., Ltd. |
| Shandong Benyue Biological Technology Co., Ltd. |
| Tianjin Changjie Chemical Co., Ltd. |
| Shanghai Fortune Chemical Co., Ltd. |
| Kaifeng Xinghua Fine Chemical LTD |
| Others |
Cost & Logistics Intelligence
GB 1886.18 compliance certification gates both supplier qualification and price differentiation across China's saccharin market, with pharmaceutical excipient-grade batches commanding substantial premiums over technical-grade alternatives while SAMR purity mandates compress margins for unintegrated producers.
Pricing Analysis
Volume-discount tiering structures dominate procurement between beverage manufacturers and Shandong refiners, with annual offtake exceeding 500 metric tons triggering dedicated quality agreements and quarterly price negotiations. Three-tier pricing structure across excipient-grade, food-grade, and technical-grade levels reflects certification burden and impurity testing intensity. Cost compression in food-grade tiers is intensifying because MEE emissions compliance upgrades force capital expenditure on HPLC equipment. Regional food manufacturers exhibit the highest price sensitivity, while pharmaceutical compounders prioritize documented impurity profiles over unit economics.
Supply Chain Analysis
Ortho-toluenesulfonamide feedstock concentration in Henan Province's Kaifeng industrial zone creates a chokepoint that constrains national saccharin dihydrate output and amplifies price volatility. Manufacturing draws from toluene derivatives, coal-chemical intermediates, and crystallization solvents sourced domestically. Single-source vulnerability runs through the three Henan-based intermediates producers controlling domestic feedstock availability. Distribution runs through direct refiner-to-manufacturer contracts for large beverage brands, with regional chemical traders serving fragmented mid-scale processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct procurement platform economics are inflecting as national beverage brands consolidate supplier panels to three qualified sources with interoperable quality agreements, replacing layered distribution through regional chemical traders.
For Market Incumbents: Secure captive ortho-toluenesulfonamide supply through backward integration into Henan feedstock producers or long-term offtake agreements with Kaifeng intermediates manufacturers. Defend margin position by accelerating continuous crystallization technology adoption before SAMR's draft GB 1886.18 revision mandates automated HPLC testing protocols that smaller batch operators cannot amortize. For New Entrants and Emerging Players: Anchor in technical-grade industrial sweetening for electroplating and pesticide formulation sectors in Jiangsu Province, where purity requirements remain less stringent and incumbent beverage-grade specialists have limited presence. Target pharmaceutical excipient certification for Southeast Asian generic drug manufacturers qualifying Chinese suppliers for EU-directed shipments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous crystallization technology adoption, favoring acquisition targets with existing automated production trains over greenfield capacity builds. Monitor SAMR's final GB 1886.18 implementation timeline as the signal indicating when compliance-driven consolidation accelerates among unintegrated batch operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive ortho-toluenesulfonamide supply from Henan producers insulates margin volatility from intermediates price swings. |
| Continuous Crystallization Technology Adoption | Automated production trains meet beverage manufacturer mandates for in-line purity monitoring systems. |
| Pharmaceutical Excipient Certification | NMPA master file documentation unlocks premium pricing from domestic drug manufacturers and Southeast Asian exporters. |
| Direct Procurement Platform Development | Bypassing regional chemical traders captures margin from national beverage brands consolidating supplier panels. |
| Dual Carbon Policy Alignment Investment | Integrated toluene recovery systems command preferential MEE emissions permitting timelines in Shandong chemical parks. |
Research Approach
Desk research of SAMR regulatory filings, GB standard documentation, and MEE emissions permit records preceded structured interviews with saccharin refinery plant managers, beverage procurement leads, pharmaceutical excipient qualification specialists, and regional chemical distribution channel partners. Primary fieldwork combined with secondary validation from customs trade data, NMPA master file registrations, and Shandong fine chemical cluster investment disclosures. Bottom-up volume modeling triangulated against top-down value estimates across product grade and application segments.
Variance-decomposition framing separated volume growth drivers from price realization effects across the projection horizon. Segmentation dimensions modeled include product type, application industry, end-user scale tier, and regional production hub. CAGRs were derived through trend extrapolation of historical procurement patterns adjusted for regulatory implementation schedules. Forecast inputs incorporated SAMR draft revision timelines, MEE permitting velocity, and beverage manufacturer supplier consolidation trajectories.
Material uncertainties — SAMR regulatory implementation delays, ortho-toluenesulfonamide feedstock price shocks, and stevia substitution acceleration in clean-label beverage segments — sit outside the modeled envelope. Forecasts reflect assumptions about GB 1886.18 compliance cost pass-through and continuous crystallization technology adoption curves. Revision becomes warranted when stevia or sucralose capture rates in tabletop and beverage applications cross thresholds that redirect formulation decisions among downstream buyers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Asia-Pacific Sugar Substitute Market
Sweeteners
South Korea Allulose Market
Sweeteners
Polyol Sweeteners Market
Sweeteners
Global Stevia Sugar Blends Market
Sweeteners
Asia-Pacific Stevia Market
Sweeteners
Caramelized Sugars Market
Sweeteners
Monk Fruit Sweetener Market
Sweeteners
Dextrose Syrup Market
Sweeteners
Corn Syrup Market
Sweeteners
North America Stevia Market
Sweeteners
Muscovado Sugar Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Brown Rice Syrup Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Sugar Market
Sweeteners
Date Sugar Market