
 Low Calorie Diet Meal Plan Market | 2026-2036
Low Calorie Diet Meal Plan Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Diet Meal Plan Market Analytics
Subscription revenue from personalized low-calorie meal planning is rewriting profit distribution across the food-as-a-service landscape. Nestle SA leverages its frozen meal manufacturing scale to dominate retail shelf space in calorie-controlled categories. Noom anchors its position through behavioral coaching integration with daily meal recommendations. Lifesum AB competes via algorithm-driven macro tracking that personalizes portion sizes across European markets.
Low calorie diet meal plans are structured eating programs delivering nutritionally complete meals or meal guidance at reduced caloric density, typically formulated between 1,200 and 1,800 kilocalories daily with controlled macronutrient ratios and micronutrient fortification. Their primary commercial purpose centers on weight management compliance and metabolic health maintenance for consumers seeking measurable dietary outcomes without independent meal preparation. Ready-to-Eat Meals capture the largest volume share among product types due to workplace convenience demand, while Meal Kits generate the fastest growth through subscription retention mechanics. Health Enthusiasts represent the most mature end-user segment with established purchasing habits, whereas Diabetics offer the highest-margin expansion pool as glycemic-index-specific formulations command premium positioning.
FDA nutrition labeling requirements and USDA dietary guidelines shape product formulation thresholds and serving-size declarations across the United States market. WHO global nutrition targets and emerging EU front-of-pack labeling rules under EFSA influence international formulation standards and export eligibility for meal plan providers. Stakeholders must monitor evolving reimbursement pathways for medically prescribed diet plans and the pace of insurance integration for digital nutrition coaching platforms.
Market Dynamics
Employer-sponsored wellness benefits are compressing procurement cycles for portion-controlled meal subscriptions, converting individual consumer purchases into bulk corporate contracts with multi-year service agreements and integrated health outcome tracking.
Growth Catalysts
- FDA Nutrition Labeling Reforms:Updated serving-size declarations and added-sugar disclosure mandates are forcing reformulation transparency, creating competitive advantage for providers with pre-compliant product architectures.
- Corporate Wellness Procurement:Fortune 500 human resources departments are consolidating vendor relationships for diet plan benefits, generating predictable recurring revenue streams and reducing customer acquisition costs.
- Glycemic-Index Formulation Science:Precision carbohydrate sequencing for diabetic end-users is opening premium pricing tiers previously inaccessible to mass-market meal plan operators.
Market Restraints
- Cold-Chain Logistics Concentration:Frozen ready-to-eat meal distribution depends on third-party refrigerated transport networks concentrated in coastal metropolitan corridors, exposing margin compression from fuel volatility and capacity constraints.
- USDA Organic Certification Barriers:Small-batch meal kit producers face multi-year transition timelines and documentation burdens to access federally subsidized school and hospital procurement channels.
- Fresh Produce Input Volatility:Leafy green and lean protein sourcing contracts reset quarterly, preventing long-term price locking and forcing menu volatility that undermines subscription retention mechanics.
Strategic Opportunities
- Insurance Reimbursement Pathways:Emerging CPT code recognition for medically prescribed diet plans in United States commercial health plans creates direct-to-payer billing models bypassing consumer price sensitivity.
- Algorithmic Personalization Convergence:Integration of continuous glucose monitor data streams with AI-driven meal recommendation engines enables real-time glycemic response optimization for diabetic subscribers.
- European Front-of-Pack Labeling:EFSA-mandated Nutri-Score adoption across France, Germany, and Netherlands is advantaging pre-positioned low-calorie brands with existing A and B grade portfolios.
Industry Challenges
- Registered Dietitian Talent Scarcity:Meal plan providers competing for credentialed nutrition professionals face wage inflation and credential verification bottlenecks that delay service scaling.
- Legacy ERP Integration Friction:Subscription management platforms must reconcile with incumbent food manufacturing inventory systems, creating order-fulfillment latency and data synchronization failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Diet Meal Plan Market |
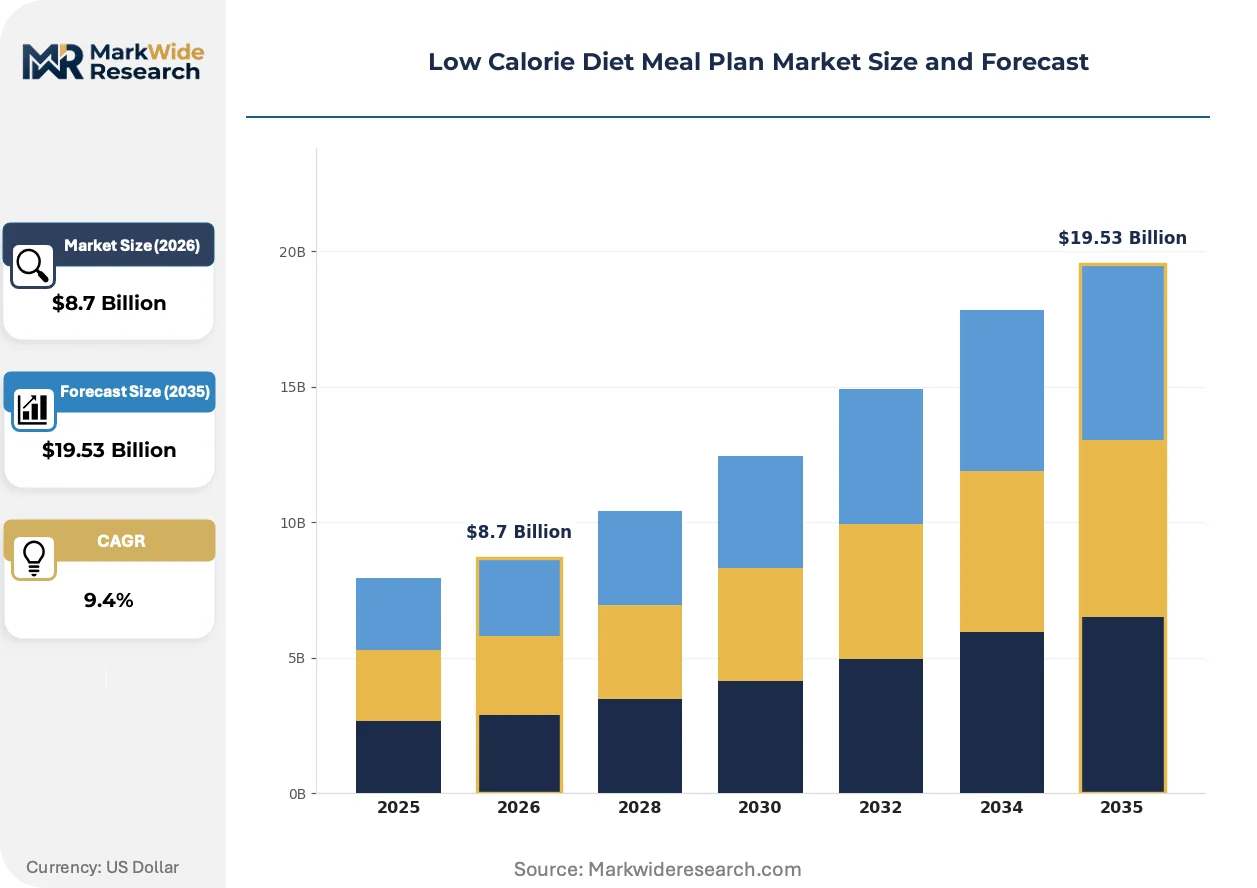
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Snack Bars, Ready-to-Eat Meals, Meal Kits End User: Health Enthusiasts, Weight Watchers, Diabetics, Fitness Professionals Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores Pricing Model: Premium, Mid-Range, Budget, Subscription |
| Companies Covered | Nestle SA, PepsiCo, The Coca-Cola Company, Groupe Danone, Abbott Laboratories, Noom, MyFitnessPal, Lifesum AB, PlateJoy LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Diet Meal Plan Market Evolving Landscape
Digital nutrition coaching platforms are compressing the distance between biometric feedback and meal execution, converting static diet plans into adaptive eating protocols responsive to real-time metabolic data.
AI-driven menu generation engines are virtualizing the traditional dietitian consultation model, replacing scheduled appointments with continuous algorithmic adjustment. Health enthusiasts in United States coastal markets are adopting these platforms fastest, with sixty-day retention rates exceeding conventional meal kit services. This virtualization is collapsing the cost structure of personalized nutrition, forcing incumbent providers to retrain human coaches as escalation specialists rather than primary advisors.
REACH chemical safety regulations in the European Union are tightening food-contact material standards for microwaveable meal trays and packaging films. Manufacturers serving export markets must reformulate polymer compositions or surrender shelf space to compliant competitors. Ready-to-eat frozen meal categories face the steepest compliance costs, accelerating consolidation toward integrated packaging producers with in-house toxicology testing capabilities.
Direct-to-employer distribution is displacing retail and direct-to-consumer channels as the primary growth vector for portion-controlled meal subscriptions. Human resources benefit administrators in United States technology and financial services sectors are consolidating vendor rosters, awarding exclusive multi-year contracts to integrated wellness platforms. This concentration is most visible in California and New York metropolitan labor markets, where talent competition drives aggressive benefit differentiation.
Low Calorie Diet Meal Plan Market Segmentation
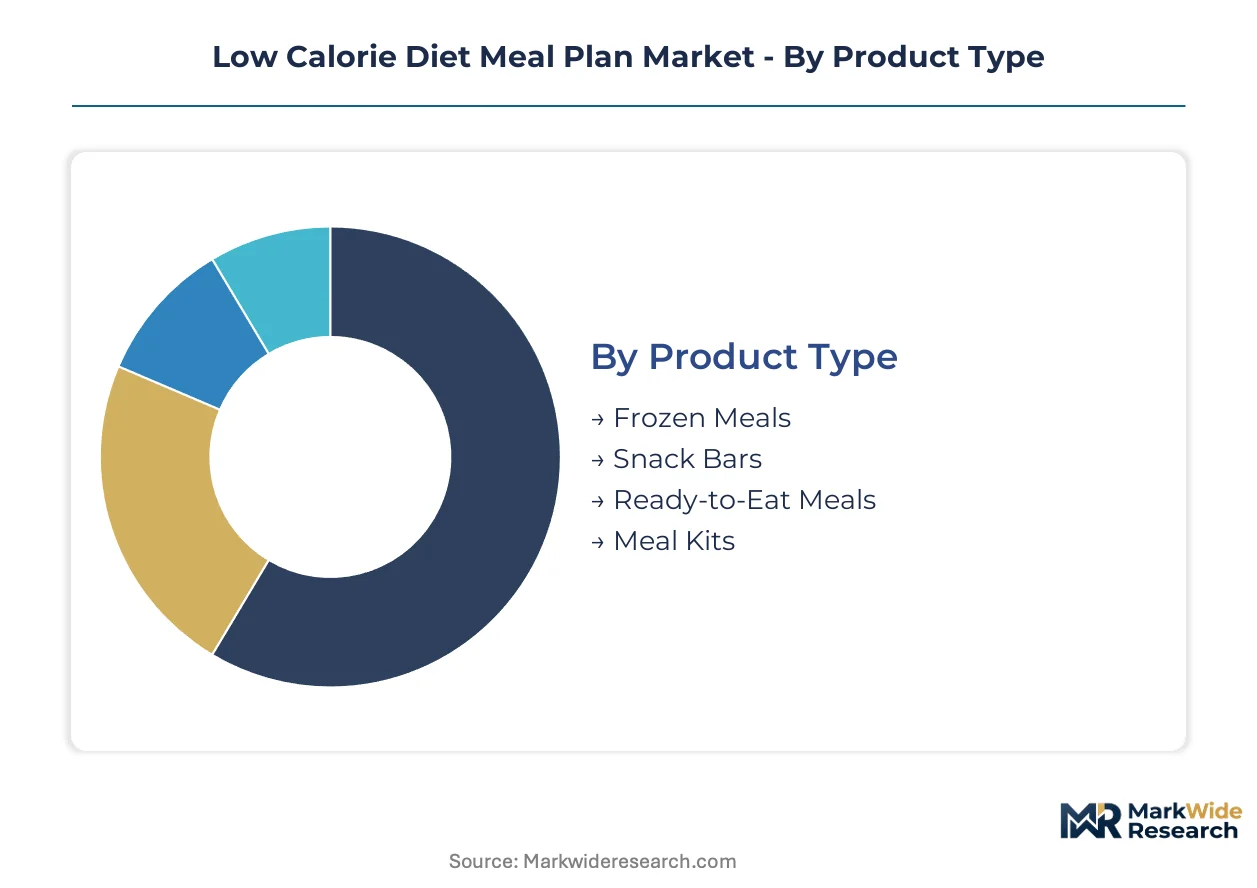
Segmentation in the low calorie diet meal plan market reveals how formulation complexity, distribution economics, and user compliance requirements create distinct competitive arenas. Each dimension exposes different margin structures and customer acquisition costs.
Product Type:
Cost tier differentiation separates manufacturing capital intensity from per-unit margin capture across the four product formats.
- Ready-to-Eat Meals:Shelf-stable or refrigerated complete meals requiring minimal preparation, formulated to precise macronutrient ratios with extended shelf-life packaging. Workplace convenience demand in United States metropolitan corridors drives volume concentration, though cold-chain dependency constrains rural penetration.
- Meal Kits:Pre-portioned ingredients with recipe cards enabling consumer-controlled preparation while maintaining caloric boundaries. Subscription retention mechanics in coastal United States markets generate predictable recurring revenue, offset by fresh produce spoilage rates that compress gross margins.
- Frozen Meals:Blast-chilled complete dishes distributed through retail freezer cases, leveraging existing grocery infrastructure. Nestle SA manufacturing scale dominates retail shelf space allocation.
- Snack Bars:Portion-controlled between-meal products fortified with protein and fiber to manage satiety. Convenience store distribution in Japan and South Korea drives impulse purchase velocity.
Ready-to-Eat Meals holds installed capacity. Meal Kits is rotating up the share rankings.
End User:
Customer type segmentation exposes how medical necessity versus lifestyle preference shapes price elasticity and retention patterns.
- Diabetics:Users requiring glycemic-index-specific formulations with precision carbohydrate sequencing and continuous glucose monitor integration. United States commercial health plans in California and Texas metropolitan areas are piloting direct reimbursement, creating premium pricing tiers inaccessible to lifestyle segments.
- Health Enthusiasts:Established purchasers with consistent replenishment habits and high brand loyalty, typically coastal United States professionals aged 25-45. Algorithmic personalization via Lifesum AB macro tracking sustains engagement, though acquisition costs rise as this segment saturates.
- Weight Watchers:Goal-oriented users seeking measurable outcomes within defined timeframes. Noom behavioral coaching integration addresses compliance dropout.
- Fitness Professionals:Trainers and athletes requiring performance-optimized protein-to-carbohydrate ratios. Corporate wellness procurement in New York and Illinois channels bulk subscription volume.
Health Enthusiasts holds installed capacity. Diabetics is rotating up the share rankings.
Distribution Channel:
Supply concentration determines which customer relationships operators control directly versus ceding to intermediaries.
- Online Retail:Direct-to-consumer platforms with subscription management infrastructure and biometric data integration. United States technology sector employer benefits consolidate vendor relationships here.
- Supermarkets:Traditional brick-and-mortar retail with frozen and refrigerated case placement competing for finite shelf space. Frozen meal slotting fees in Germany and Netherlands favor EFSA Nutri-Score A-grade portfolios.
- Health Food Stores:Specialty retail emphasizing organic certification and clean-label positioning. USDA Organic certification barriers delay small-batch producer access.
- Convenience Stores:Grab-and-go refrigerated placement targeting impulse replenishment. Japanese convenience retail density supports snack bar velocity.
Supermarkets holds installed capacity. Online Retail is rotating up the share rankings.
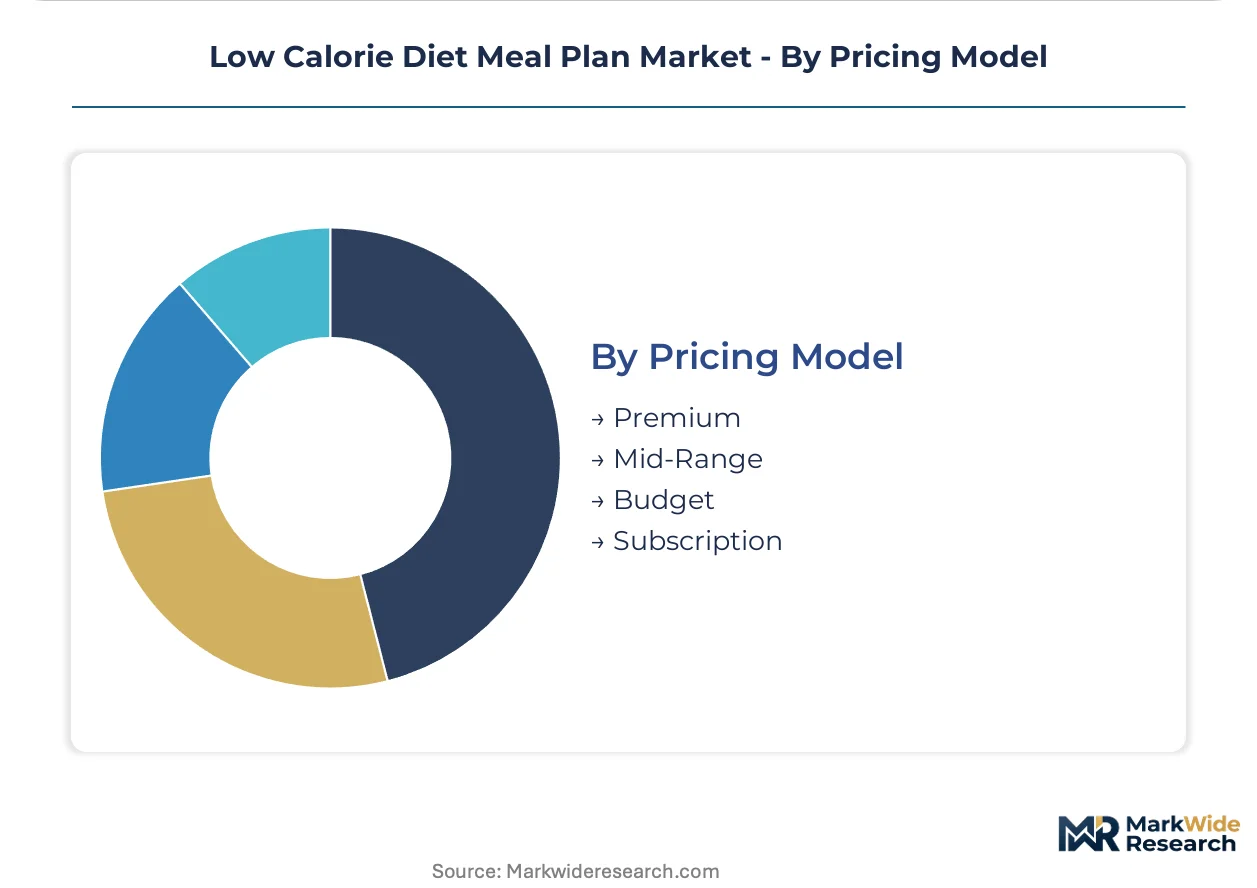
Pricing Model:
Margin structure stratification separates one-time transactions from lifetime value capture through recurring billing mechanics.
- Subscription:Recurring delivery models with portion-controlled weekly or monthly shipments, integrated with digital coaching platforms. Fortune 500 human resources departments in United States financial services are consolidating exclusive multi-year agreements here.
- Premium:Single-purchase positioning emphasizing organic certification, restaurant-quality preparation, or celebrity chef endorsement. Glycemic-index formulation science commands tier-one pricing.
- Mid-Range:Balanced quality-cost positioning targeting mainstream retail consumers. Frozen meal retail shelf space competition concentrates here.
- Budget:Price-sensitive positioning through value-oriented retail channels with simplified formulation and conventional ingredients. Convenience store distribution in emerging markets sustains volume.
Mid-Range holds installed capacity. Subscription is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored wellness benefits in the United States concentrate procurement of portion-controlled meal subscriptions, while European markets prioritize EFSA-aligned front-of-pack labeling and Asian demand clusters around convenience retail density for grab-and-go formats.
United States
Corporate wellness programs at Fortune 500 technology and financial services firms drive bulk subscription procurement with multi-year vendor contracts. FDA nutrition labeling reforms mandate updated serving-size declarations and added-sugar disclosures that reshape formulation transparency requirements. California and New York metropolitan labor markets anchor direct-to-employer distribution growth.
Germany
EFSA-mandated Nutri-Score adoption advantages pre-positioned low-calorie brands with existing A and B grade portfolios in retail freezer cases. REACH chemical safety regulations tighten food-contact material standards for microwaveable meal trays, accelerating consolidation toward integrated packaging producers. The Eindhoven-to-Ruhr corridor hosts reformulation laboratories serving export-compliant frozen meal manufacturing.
Japan
Convenience store retail density supports high-velocity impulse purchase of portion-controlled snack bars and refrigerated ready-to-eat meals. METI guidelines on functional food claims shape product positioning for glycemic-index-specific formulations targeting diabetic consumers. Tokyo and Osaka metropolitan clusters concentrate subscription platform development integrating behavioral coaching with daily meal recommendations.
United Kingdom
Algorithm-driven macro tracking applications sustain engagement among health enthusiast segments with established replenishment habits. Emerging NHS pilot programs for digitally prescribed diet plans create reimbursement pathway exploration for medically indicated meal interventions. London and Southeast England concentrate venture-funded meal kit subscription scaling.
South Korea
MFDS regulations on health functional food labeling govern premium positioning of protein-fortified snack bars in convenience retail channels. Seoul Capital Area employer benefits increasingly incorporate portion-controlled meal subscriptions as talent retention instruments. Daegu-Gyeongbuk industrial zones supply specialized packaging films compliant with escalating food-contact material standards.
Low Calorie Diet Meal Plan Market Competitive Landscape
Capability concentration sits with algorithmic personalization specialists; scale advantage sits with frozen meal manufacturing conglomerates. The competitive structure stratifies into three functional tiers: behavioral coaching platforms integrating daily meal recommendations, legacy food manufacturers leveraging retail shelf space dominance, and digital-native subscription operators optimizing retention mechanics through biometric data integration. Dominant competitive moves include backward integration into cold-chain logistics networks and strategic partnerships with commercial health plans for direct-to-payer billing models.
Within the scale-driven manufacturing tier, Nestle SA exemplifies frozen meal production capacity deployment across retail distribution networks. Noom and Lifesum AB represent divergent personalization archetypes—behavioral coaching integration versus algorithmic macro tracking—each anchoring distinct compliance and engagement methodologies in employer-sponsored and direct-to-consumer channels respectively.
| Leading Market Players |
|---|
| Nestle SA |
| PepsiCo |
| The Coca-Cola Company |
| Groupe Danone |
| Abbott Laboratories |
| Noom |
| MyFitnessPal |
| Lifesum AB |
| PlateJoy LLC |
| Others |
Value Network & Pricing Analysis
The Eindhoven-to-Ruhr corridor's reformulation laboratory concentration anchors European frozen meal manufacturing capacity, translating specialized packaging compliance investments into premium pricing power for Nutri-Score A-grade portfolios while compressing margins for non-compliant producers locked out of German and Dutch retail freezer cases.
Pricing Analysis
Long-term corporate offtake agreements dominate procurement, with Fortune 500 human resources departments locking multi-year subscription contracts that insulate providers from spot-market volatility. Pricing stratifies across premium glycemic-index formulations, standard portion-controlled subscriptions, and budget retail frozen tiers, with certification grade and geographic delivery cost as primary differentiation levers. Cost compression in the budget tier intensifies as fuel volatility in refrigerated transport networks erodes already-thin margins. Corporate wellness buyers exhibit lowest price sensitivity due to integrated health outcome tracking, while individual direct-to-consumer subscribers face highest churn from menu volatility.
Supply Chain Analysis
Contract manufacturing concentration rests with Nestle SA's frozen production facilities, specialized cold-chain logistics providers in California and New York metropolitan corridors, and European integrated packaging producers with in-house REACH toxicology testing. Raw material dependencies draw from quarterly-reset leafy green sourcing contracts, lean protein supply agreements, and EFSA-compliant polymer compositions for microwaveable trays. Single-source vulnerability in third-party refrigerated transport networks concentrated in coastal metropolitan corridors exposes margin compression from capacity constraints. Distribution runs through direct-to-employer platforms, supermarket retail freezer cases, and convenience store grab-and-go placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as employer-sponsored wellness benefits convert individual purchases into bulk corporate procurement, with insurance reimbursement pathway development representing a penetration tailwind still in pilot phase across United States commercial health plans.
For Market Incumbents: Insulate subscription retention mechanics against algorithmic personalization entrants by deepening integration with continuous glucose monitor data streams and securing exclusive multi-year corporate wellness contracts before vendor consolidation completes. Prioritize backward integration into cold-chain logistics networks to reduce third-party transport dependency.
For New Entrants and Emerging Players: Rural United States markets outside coastal metropolitan corridors present underpenetrated white space where cold-chain infrastructure gaps have stalled incumbent expansion. Target diabetic subscriber segments in Texas and California metropolitan areas where commercial health plan reimbursement pilots create premium pricing tiers inaccessible to mass-market operators. Deploy direct-to-employer sales teams before human resources benefit administrators finalize vendor rosters.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithmic personalization specialists with biometric data integration capabilities over legacy frozen meal manufacturing scale. Five-to-ten year viability hinges on insurance reimbursement pathway maturation. The signal to watch is CPT code recognition expansion for medically prescribed diet plans across additional United States commercial health plans.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Employer Distribution Expansion | Fortune 500 benefit administrator consolidation creates exclusive multi-year contract opportunities. |
| Continuous Glucose Monitor Integration | Real-time glycemic response optimization commands premium pricing from diabetic subscribers. |
| EFSA Nutri-Score A-Grade Portfolio Repositioning | Pre-compliant brands capture German and Dutch retail freezer case slotting advantages. |
| Cold-Chain Logistics Backward Integration | In-house refrigerated transport control reduces fuel volatility exposure and capacity constraints. |
| Insurance Reimbursement Pathway Development | Direct-to-payer billing models bypass consumer price sensitivity in medically indicated segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA nutrition labeling filings, EFSA front-of-pack labeling guidance, WHO global nutrition targets, and corporate wellness benefit administrator procurement databases. Primary interviews engaged meal plan provider executives, registered dietitian service directors, cold-chain logistics operations managers, and human resources benefits specialists. Secondary validation drew from USDA dietary guideline publications, SEC 10-K filings of publicly traded food manufacturers, and Nielsen retail audit data. Bottom-up subscriber volume modeling triangulates against top-down market value estimates.
Forecast inputs include product type segmentation across ready-to-eat meals, meal kits, frozen meals, and snack bars; end-user segmentation spanning diabetics, health enthusiasts, weight management subscribers, and fitness professionals; and distribution channel segmentation covering online retail, supermarkets, health food stores, and convenience stores. CAGRs derive from regression analysis of historical subscription growth rates adjusted for employer-sponsored benefit penetration curves. Industry-specific inputs incorporate FDA reformulation compliance timelines and EFSA Nutri-Score adoption trajectories across the analysis window.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by algorithmic personalization specialists or rapid insurance reimbursement pathway expansion by commercial health plans would shift outcomes. Quarterly review of CPT code recognition developments, corporate wellness vendor consolidation announcements, and cold-chain logistics capacity expansion indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Halal Market
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Low Calorie Popsicles Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
Zhacai Market
Specialty Foods
Halal Products Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
North American Jam, Jelly, and Preserve Market