
 Asia-Pacific Space Logistics Market | 2026-2036
Asia-Pacific Space Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Space Logistics Market Analytics
ISO 24300 space systems safety qualification is rotating vendor eligibility across the Asia-Pacific Space Logistics Market. Mitsubishi Heavy Industries leverages its H3 launch vehicle program to sustain domestic Japanese payload capacity. China Aerospace Science and Technology Corporation anchors heavy-lift missions through its Long March family. Indian Space Research Organisation competes on cost-efficient small satellite deployment from Satish Dhawan Space Centre.
Asia-Pacific space logistics encompasses the transportation, orbital transfer, and in-situ servicing of spacecraft, payloads, and consumables using propulsion systems rated for vacuum-specific impulse exceeding 300 seconds and automated rendezvous precision within centimeter-scale tolerances. Satellite deployment services dominate current revenue as constellation operators prioritize ride-share efficiency over dedicated launches. Reusable launch systems represent the fastest-expanding technology segment, with automated cargo vehicles capturing margin pools from government resupply contracts to the International Space Station and planned commercial habitats. Ground support equipment remains mature, with pricing pressured by standardized interfaces.
METI in Japan, MIIT in China, and ISRO's regulatory arm in India enforce national launch licensing and spectrum coordination rules that shape market access timelines and foreign participation limits. REACH-equivalent chemical handling standards in South Korea and Australia's Space Activities Act add compliance layers for propellant logistics and debris mitigation protocols. Stakeholders must monitor how bilateral technology transfer agreements between national space agencies reshape competitive boundaries for private enterprises seeking cross-border launch contracts.
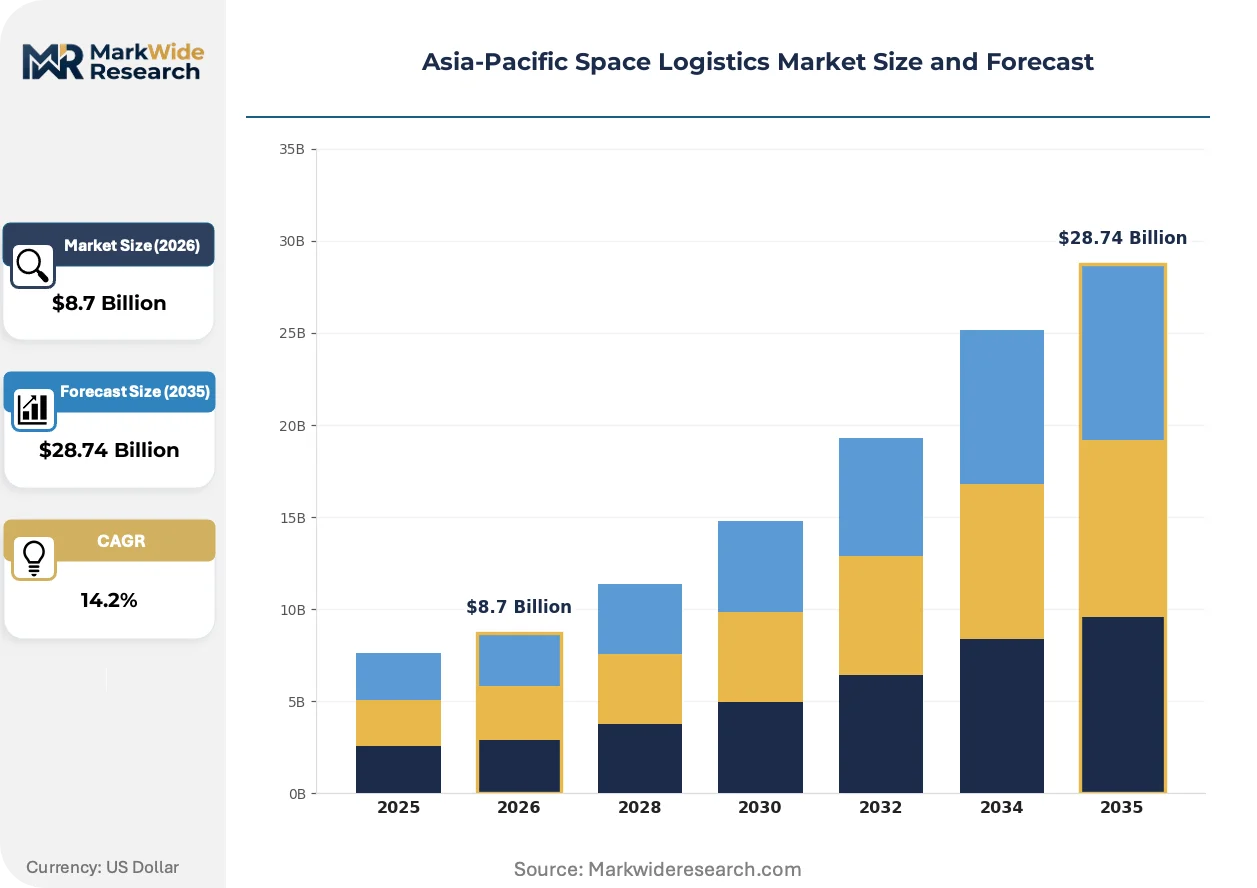
Market Dynamics
Reusable launch systems are compressing unit economics across satellite deployment services, forcing incumbent operators to restructure cost bases while Japan's METI tightens autonomous vehicle qualification protocols that gate market access.
Growth Catalysts
- ISRO SSLV program expansion:India's small satellite launch vehicle creates dedicated capacity for commercial constellation operators seeking ride-share alternatives to heavy-lift missions.
- ISO 24300 safety qualification rotation:The international space systems standard is cycling vendor eligibility, opening procurement windows for qualified Asia-Pacific contractors.
- Orbital transfer service procurement:Satellite communication operators are expanding contracts for in-space mobility, creating pull-through demand for propulsion logistics and rendezvous systems.
Market Restraints
- Propulsion system input concentration:Vacuum-rated engines exceeding 300-second specific impulse rely on limited domestic supply chains in China and Japan.
- METI autonomous cargo friction:Japan's tightening safety protocols extend qualification timelines for orbital transfer vehicles and resupply systems.
- Ground support equipment commoditization:Standardized interface requirements eliminate pricing power for legacy port infrastructure providers.
Strategic Opportunities
- Private pad infrastructure near Sriharikota:India's commercial launch sector is concentrating demand around ISRO's Satish Dhawan Space Centre, opening private ground facility investment.
- In-situ servicing convergence:Automated rendezvous systems and robotic manipulation tools are merging to enable satellite life extension and debris removal contracts.
- Commercial habitat resupply channels:Planned private space stations create new cargo logistics demand outside government ISS contracts.
Industry Challenges
- Centimeter-scale rendezvous precision gap:Automated proximity operations require specialized guidance, navigation, and control talent scarce across the region.
- Dual-use technology licensing complexity:Propulsion and autonomous systems fall under export control frameworks that fragment cross-border contracting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Space Logistics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Satellite Deployment, Cargo Resupply, Spacecraft Maintenance, Orbital Transfer End User: Government Agencies, Private Enterprises, Research Institutions, Commercial Operators Technology: Reusable Launch Systems, Automated Cargo Vehicles, Orbital Docking Mechanisms, Ground Support Equipment Application: Satellite Communication, Earth Observation, Scientific Research, Space Exploration |
| Companies Covered | Mitsubishi Heavy Industries, China Aerospace Science and Technology Corporation, Indian Space Research Organisation, Japan Aerospace Exploration Agency, Lockheed Martin, Space Exploration Technologies, Thales Alenia Space, RUAG Space, Arianespace, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Space Logistics Market Evolving Landscape
Electrification of orbital transfer vehicles and modular payload adapters are restructuring how constellation operators contract launch services across the Asia-Pacific region.
Electric propulsion for orbital maneuvering is fragmenting the traditional chemical propulsion supplier base. Small satellite operators in India and Japan are adopting Hall-effect thrusters and gridded ion engines for station-keeping and orbit-raising. The technology is fragmenting procurement patterns by enabling rideshare to lower orbits followed by autonomous spiral-out, compressing demand for direct-injection heavy launches.
METI's revised safety protocols for autonomous cargo vehicles are extending pre-qualification testing requirements. Japanese orbital transfer vehicle developers must now demonstrate fault-tolerant rendezvous under simulated communication blackout conditions. The policy most affects commercial resupply contractors targeting the ISS and planned commercial habitats, forcing design architecture changes.
Constellation operators are unbundling launch procurement from orbital placement services. Satellite communication providers now contract separately for rideshare to parking orbits and subsequent orbital transfer, fragmenting the traditional integrated launch service model. This pattern is most visible among operators deploying medium Earth orbit constellations from Indian and Chinese launch facilities.
Asia-Pacific Space Logistics Market Segmentation
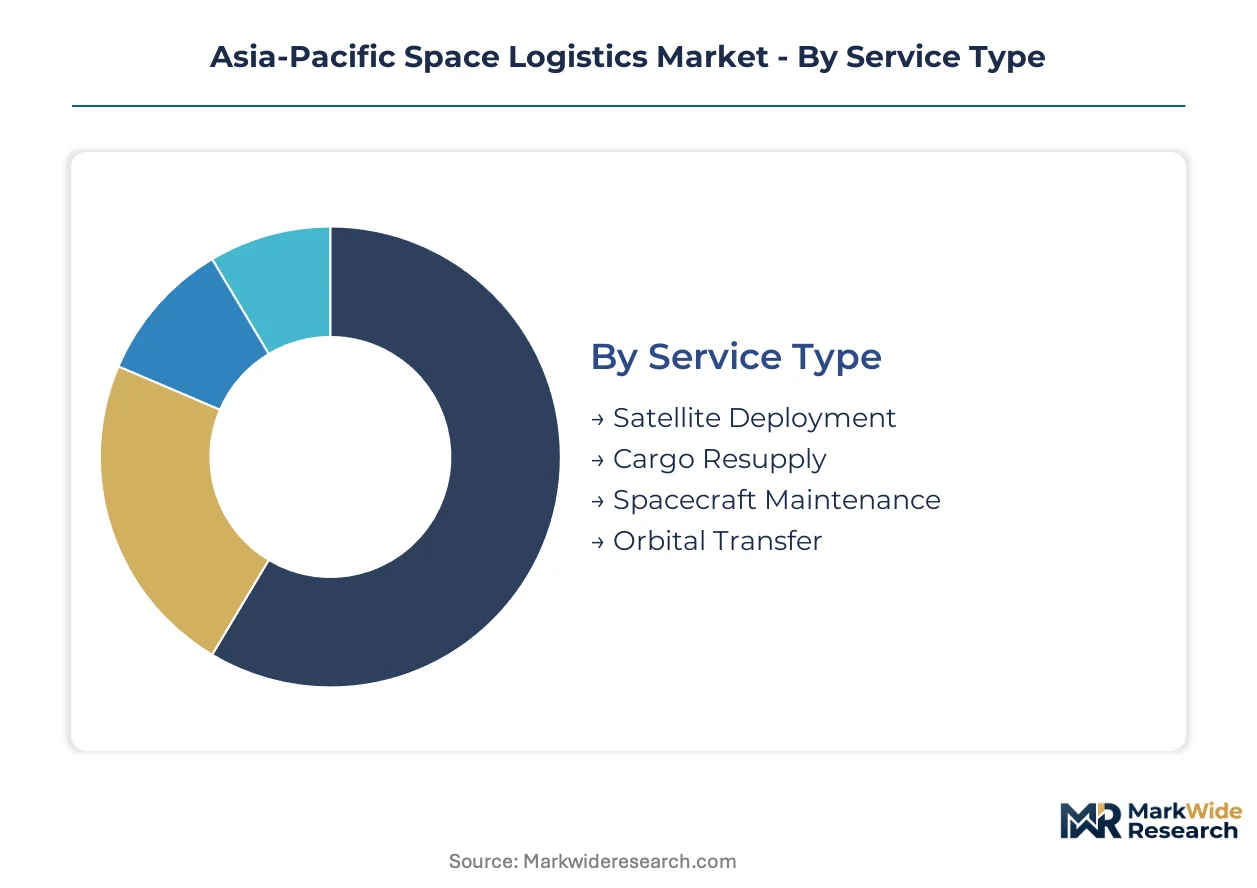
Segmentation reveals how service substitution and technology displacement are redrawing competitive boundaries across Asia-Pacific space logistics. Understanding where reusable systems displace expendable launch and where orbital transfer unbundles traditional deployment exposes margin migration paths for operators and investors.
Service Type:
Substitution pressure concentrates heaviest where orbital transfer services fragment the legacy integrated launch model, forcing satellite deployment providers to defend position through rideshare efficiency gains.
- Satellite Deployment:Heavy-lift and small-lift missions delivering payloads to initial parking orbits, with ISRO's SSLV program capturing constellation operator demand through dedicated small satellite capacity. India's Satish Dhawan Space Centre anchors procurement for commercial operators seeking alternatives to crowded heavy-lift manifests.
- Orbital Transfer:In-space mobility services using electric or chemical propulsion to reposition satellites from deployment orbits to final operational stations. Hall-effect thrusters from Japanese suppliers are displacing traditional chemical spiral-out maneuvers among medium Earth orbit constellation builders.
- Cargo Resupply:Automated vehicle missions delivering consumables, equipment, and crew supplies to orbital habitats. METI's revised fault-tolerant rendezvous requirements extend qualification timelines for contractors targeting ISS and planned commercial stations.
- Spacecraft Maintenance:On-orbit servicing including refueling, component replacement, and life extension through robotic manipulation. Centimeter-scale precision requirements limit viable contractor pools across the region.
Satellite deployment retains volume leadership; orbital transfer holds the steepest expansion curve.
End User:
Cost tier stratification separates government-funded missions with extended qualification timelines from commercial operators prioritizing speed-to-orbit over redundancy margins.
- Government Agencies:National space programs including ISRO, JAXA, and CASC procuring launch services under multi-year budget cycles with stringent safety documentation. Contracts emphasize reliability metrics over unit cost minimization.
- Commercial Operators:Constellation builders and satellite communication providers unbundling launch from orbital placement to optimize capital deployment. These entities drive demand for rideshare efficiency and autonomous transfer vehicle compatibility.
- Private Enterprises:Emerging space stations and in-space manufacturing ventures creating cargo resupply demand outside traditional government channels. Planned habitats in low Earth orbit require dedicated logistics infrastructure.
- Research Institutions:Universities and scientific consortia accessing space through piggyback payload arrangements and dedicated small satellite missions. ISRO's commercial arm facilitates academic access through standardized interface protocols.
Commercial operators are gaining share fastest; government agencies maintain procurement value concentration.
Technology:
Application maturity diverges sharply between flight-proven reusable launch and nascent automated cargo systems facing extended regulatory qualification.
- Reusable Launch Systems:First-stage recovery and rapid refurbishment architectures compressing per-kilogram launch economics. China's Long March program and Japan's H3 vehicle demonstrate technical viability while Indian private developers advance methane-oxygen reusable concepts.
- Automated Cargo Vehicles:Unmanned resupply craft with autonomous rendezvous and berthing capabilities. METI's simulated communication blackout testing requirements force architectural changes for Japanese developers targeting ISS replacement markets.
- Orbital Docking Mechanisms:Standardized mechanical and data interfaces enabling spacecraft coupling for refueling, cargo transfer, and module assembly. ISO 24300 qualification cycles rotate vendor eligibility across Asia-Pacific contractor pools.
- Ground Support Equipment:Launch pad infrastructure, payload processing facilities, and tracking networks with standardized interfaces eliminating pricing power for legacy providers. Private pad development near Sriharikota concentrates investment demand.
Ground support equipment dominates installed base; reusable launch systems show the steepest adoption trajectory.
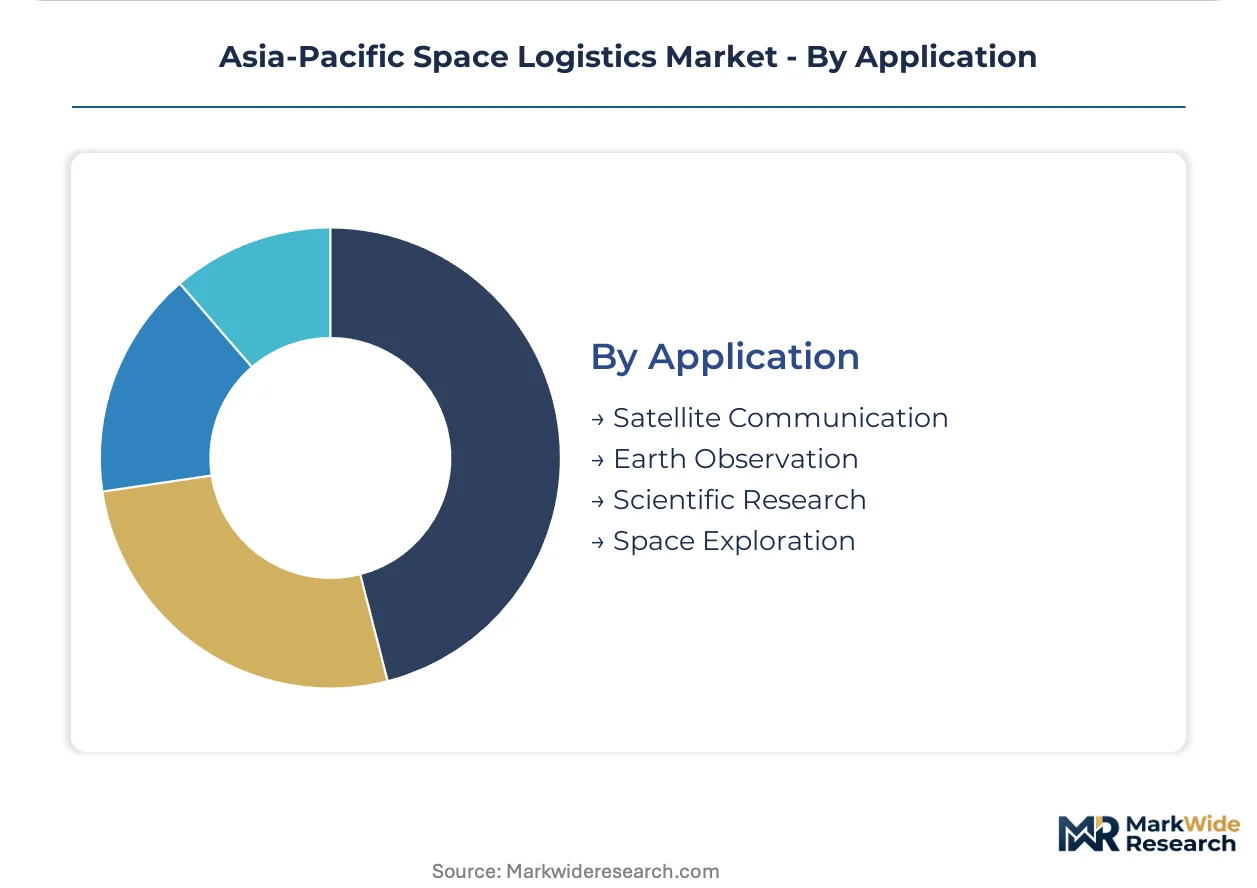
Application:
Volume concentration in established satellite communication contrasts with emerging demand from Earth observation constellations requiring more frequent revisit capabilities.
- Satellite Communication:Geostationary and non-geostationary broadband constellations driving rideshare procurement to parking orbits. Operators increasingly separate launch contracting from orbital transfer service acquisition.
- Earth Observation:Remote sensing constellations demanding sun-synchronous and polar orbits with specific local time constraints. Small satellite operators in India leverage SSLV dedicated capacity for precision injection.
- Scientific Research:Astronomy, heliophysics, and microgravity experiments requiring specific orbital parameters and pointing stability. JAXA and ISRO coordinate multi-payload missions to optimize launch utilization.
- Space Exploration:Lunar and deep-space missions with unique trajectory and velocity requirements. China's heavy-lift Long March vehicles anchor regional capability for translunar injection.
Satellite communication commands current volume; Earth observation exhibits the sharpest demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI safety protocols and India's SSLV commercialization program are redrawing procurement boundaries across Asia-Pacific space logistics, with national regulators tightening qualification windows while private pad infrastructure concentrates investment near established launch complexes.
Japan
Fault-tolerant rendezvous requirements for autonomous cargo vehicles are extending pre-qualification timelines for commercial resupply contractors. METI mandates simulated communication blackout testing for orbital transfer vehicles targeting the ISS and planned commercial habitats. Mitsubishi Heavy Industries anchors domestic payload capacity through its H3 launch vehicle program at Tanegashima Space Center.
China
Heavy-lift Long March missions anchor regional capability for translunar injection and geostationary deployment. MIIT enforces national launch licensing and spectrum coordination rules that shape foreign participation limits and technology transfer boundaries. China Aerospace Science and Technology Corporation concentrates heavy-lift mission execution from Jiuquan and Xichang launch complexes.
India
ISRO's SSLV program creates dedicated small satellite capacity for commercial constellation operators seeking ride-share alternatives to crowded heavy-lift manifests. The commercial arm of ISRO facilitates standardized interface protocols for academic and private payload access. Private pad infrastructure investment is concentrating near Satish Dhawan Space Centre at Sriharikota.
South Korea
Nuri rocket development and KSLV-II program expansion are building indigenous launch capability for small and medium payloads. REACH-equivalent chemical handling standards add compliance layers for propellant logistics and debris mitigation protocols. Korea Aerospace Research Institute coordinates launch operations from Naro Space Center in Goheung.
Australia
Commercial launch site development at Whitsunday and Equatorial Launch Australia facilities is attracting Asia-Pacific payload operators seeking equatorial access. The Space Activities Act establishes licensing frameworks for launch and re-entry operations with debris mitigation requirements. Southern Launch operates test facilities near Port Lincoln and the Whitsunday Islands.
Asia-Pacific Space Logistics Market Competitive Landscape
Listed leaders compete with private specialists across qualification timelines and launch capacity allocation. The market structure tiers between established aerospace conglomerates with flight-proven vehicle families and emerging private developers advancing reusable methane-oxygen concepts. Three archetypes dominate: state-affiliated heavy-lift operators, commercial small-lift specialists, and orbital transfer service providers. Competitive moves center on private pad infrastructure investment and electric propulsion technology licensing for in-space mobility.
Within the state-affiliated tier, Mitsubishi Heavy Industries and China Aerospace Science and Technology Corporation exemplify integrated aerospace-industrial positioning. Indian Space Research Organisation occupies a hybrid position bridging government mission execution with commercial capacity allocation. These three entities represent the dominant launch service archetypes across the Asia-Pacific region.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| China Aerospace Science and Technology Corporation |
| Indian Space Research Organisation |
| Japan Aerospace Exploration Agency |
| Lockheed Martin |
| Space Exploration Technologies |
| Thales Alenia Space |
| RUAG Space |
| Arianespace |
| Others |
Value Network & Pricing Analysis
Electric propulsion substitution for chemical orbital maneuvering systems is redrawing procurement geography across the Asia-Pacific Space Logistics Market, compressing demand for direct-injection heavy launches while fragmenting supplier bases between Japanese Hall-effect thruster manufacturers and legacy chemical propulsion houses in China and India.
Pricing Analysis
Certification level under ISO 24300 space systems safety standards creates the primary spread between premium-tier orbital transfer vehicle contractors and unqualified aspirants. The dominant pricing structure runs contract-based long-term offtake for government resupply missions, with commercial operators negotiating project-based spot contracts for rideshare capacity. Price differentiation stems from METI fault-tolerant rendezvous qualification status and volume scale commitments from constellation operators. Margins are tightening due to ground support equipment commoditization eliminating pricing power for legacy port infrastructure providers. Commercial operators exhibit highest price sensitivity, prioritizing speed-to-orbit over redundancy margins, while government agencies accept premium pricing for extended qualification timelines and reliability documentation.
Supply Chain Analysis
Strait of Malacca transit corridors for xenon and krypton propellant feedstock underpin orbital transfer vehicle production economics across the region. Geographic supply concentrates in Japan for precision guidance components, China for heavy-lift vehicle structures, and India for small satellite platform integration. Raw material dependencies center on high-purity noble gases, vacuum-rated alloys exceeding 300-second specific impulse ratings, and fault-tolerant avionics modules. Supply chain risk rests on single-source vulnerability for Hall-effect thruster magnetic core materials subject to export licensing. Distribution runs through national space agency procurement channels with bilateral technology transfer agreements gating cross-border contractor eligibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Centimeter-scale rendezvous precision talent scarcity constrains viable contractor pools across the Asia-Pacific Space Logistics Market, with automated proximity operations expertise concentrated among a handful of Japanese and Chinese developers. This capability gap shapes competitive boundaries for orbital transfer and in-situ servicing segments.
For Market Incumbents: Secure fault-tolerant rendezvous qualification under METI's revised autonomous cargo protocols before competitors complete extended testing cycles. Anchor capacity allocation through backward integration into private pad infrastructure near Sriharikota, where ISRO's SSLV commercialization concentrates demand. Lock in multi-year propellant supply agreements with South Korean REACH-equivalent compliant handlers to preempt chemical logistics bottlenecks. Defend margin position against electric propulsion substitution by bundling heavy-lift deployment with orbital transfer service packages. For New Entrants and Emerging Players: ISO 24300 safety qualification fast-tracks open procurement windows for electric propulsion subsystem contractors targeting medium Earth orbit constellation builders. White-space concentration sits with in-situ servicing robotics for satellite life extension, where centimeter-scale precision requirements limit incumbent saturation. India's commercial launch sector around Satish Dhawan Space Centre offers the most penetrable geography given private pad infrastructure investment demand. Go-to-market leverage rests on modular payload adapter compatibility with ISRO's standardized interface protocols. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed orbital transfer vehicle developers holding METI pre-qualification status but requiring growth capital for commercial habitat resupply channel buildout. Long-term viability frames around automated rendezvous system licensing revenue streams recurring across constellation operator procurement cycles. Acquisition target archetype: electric propulsion subsystem specialists with Hall-effect thruster flight heritage and gridded ion engine development pipelines. Signal to watch: bilateral technology transfer agreement announcements between national space agencies that reshape cross-border launch contracting boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 24300 Safety Qualification Investment | Rotates vendor eligibility across Japanese, Chinese, and Indian procurement pools. |
| Private Pad Infrastructure Development | Captures demand concentration near ISRO's Satish Dhawan Space Centre at Sriharikota. |
| Electric Propulsion Technology Licensing | Enables rideshare-to-parking-orbit business model fragmentation of integrated launch services. |
| Fault-Tolerant Rendezvous System Development | Meets METI simulated communication blackout testing requirements for ISS and commercial habitat contractors. |
| Cross-Border Launch Contracting Partnership | Navigates dual-use technology export controls fragmenting regional propulsion system trade. |
Research Methodology
Cross-validation between launch service procurement databases and national space agency budget disclosures anchors the qualitative findings in this study. Primary interviews with constellation operator procurement leads, orbital transfer vehicle program managers, METI regulatory affairs officers, and ISRO commercial arm executives combined with secondary validation from JAXA mission manifests, MIIT launch licensing records, and Satish Dhawan Space Centre payload processing logs. Bottom-up triangulation across service type segmentation and top-down verification against regional launch capacity announcements established demand quantification boundaries.
Sensitivity analysis around electric propulsion adoption curves and reusable launch system refurbishment rates informs the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, end user archetype, propulsion technology, and application with cross-cutting geographic regulatory cluster overlays. CAGRs derived from capacity utilization trajectories at Tanegashima, Jiuquan, Xichang, and Sriharikota facilities against constellation operator deployment schedules. Forecast inputs incorporated METI qualification timeline extensions and ISRO SSLV commercialization ramp assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained government resupply contract flows and commercial habitat development timelines; material deviation in autonomous rendezvous regulatory stringency or bilateral technology transfer agreement scope would warrant model refresh. Practitioners should keep alternative scenarios live as electric propulsion substitution rates and private pad infrastructure investment commitments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Europe Space Logistics Market
Space
Deep Space Robotics Market
Space
Space Wheel Market
Space
Rocket Launchpad Market
Space
Near Space Robotics Market
Space
Private Space Travel Market
Space
Europe Space Electronics Market
Space
Space Sensors Market
Space
India Aviation, Defense, and Space Market
Space
Space Frame Market
Space
Deep Space Exploration Market
Space
Space Propulsion Systems Market
Space
Africa Space Electronics Market
Space
Italy Space Electronics Market
Space
Space Colonization Market
Space
Space Ground Station Equipment Market