
 Private Space Travel Market | 2026-2036
Private Space Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Private Space Travel Market Insights
Asset-light leasing of launch capacity is rewriting competitive entry barriers for private space travel ventures. SpaceX leverages vertical integration across reusable boosters and crew capsules to sustain cost leadership on orbital missions. Blue Origin anchors its position through in-house propulsion manufacturing and suborbital tourism operations from its West Texas facility. Virgin Galactic competes via air-launch architecture that reduces ground infrastructure requirements for spaceplane operations.
Private space travel encompasses commercial human transportation beyond Earth's atmosphere using vehicles rated for atmospheric exit and controlled re-entry, typically operating at altitudes above 100 kilometers with thermal protection systems, pressurized crew compartments, and automated or piloted flight control architectures. The primary purpose is to generate revenue from passenger transport, research hosting, and experiential services outside national space agency programs. Suborbital flights currently occupy the largest share of near-term revenue as shorter mission profiles match current vehicle capabilities and tourist risk tolerance. Orbital flights represent the fastest-growing service category as Crew Dragon and forthcoming commercial stations extend multi-day mission availability. Reusable launch vehicles concentrate capital investment and margin capture among operators achieving rapid turnaround cycles.
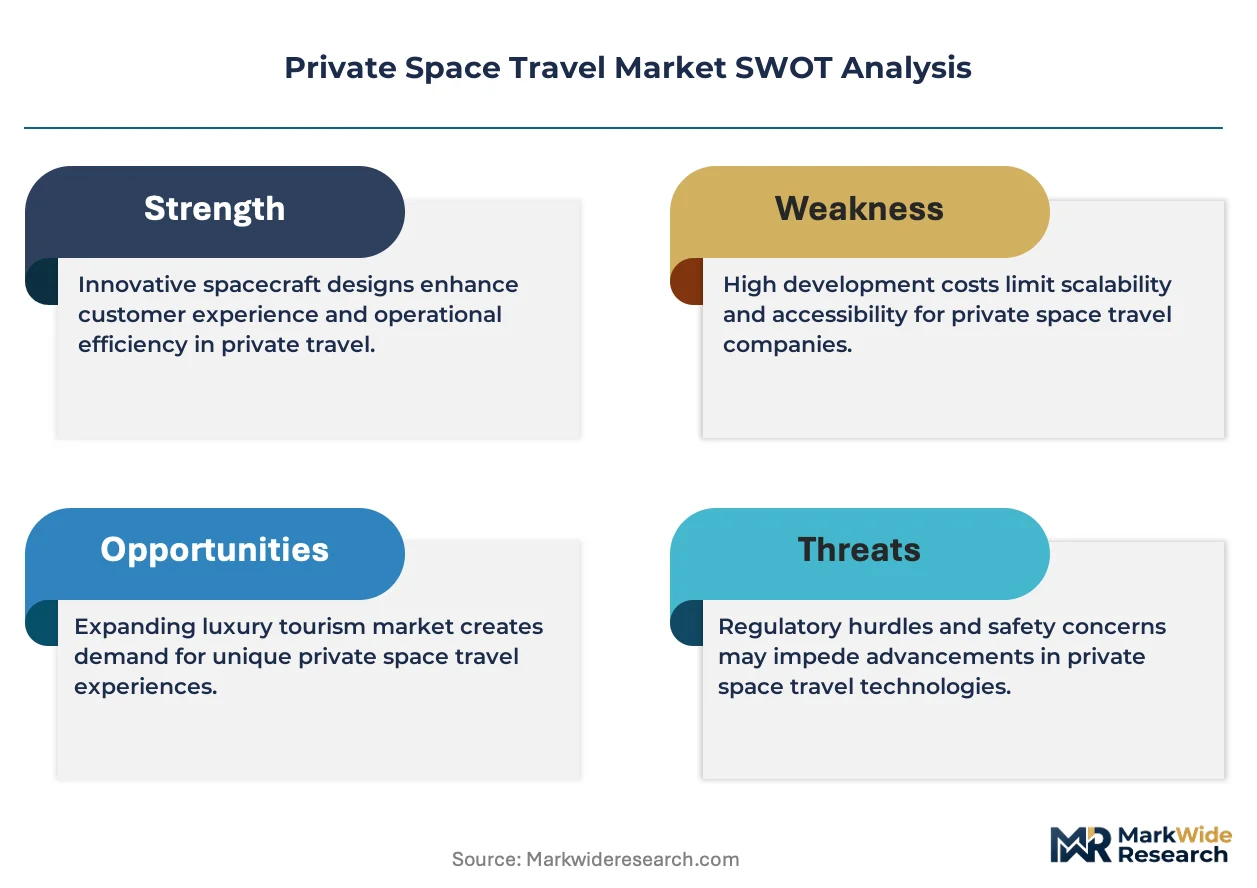
FAA Office of Commercial Space Transportation licensing governs U.S. launch and re-entry operations, creating compliance costs that favor scaled operators over emerging entrants. NASA's Commercial Crew and Commercial LEO Destination programs channel government demand through certified contractors, shaping procurement concentration. ISO 24113 space debris mitigation standards influence vehicle design requirements across jurisdictions. Stakeholders must monitor how FAA streamlining of passenger safety regulations affects market access timelines versus operational liability exposure.
Market Dynamics
Reusable launch vehicle economics is compressing per-seat costs and redistributing margin capture toward operators achieving rapid turnaround cycles, fundamentally altering competitive entry barriers for orbital and suborbital services.
Growth Catalysts
- FAA Streamlined Licensing:The FAA Office of Commercial Space Transportation is accelerating launch authorization timelines for certified operators, reducing pre-mission regulatory overhead and enabling higher flight cadence from US spaceports.
- Ultra-High-Net-Worth Tourism Demand:Luxury experiential travel segments are allocating discretionary capital toward orbital stays and suborbital weightlessness experiences, creating sustained booking pipelines for commercial crew missions.
- Reusable Thermal Protection Systems:Advances in ceramic matrix composites and ablative shielding are extending vehicle reuse cycles, lowering refurbishment costs between flights and improving unit economics for high-frequency operators.
Market Restraints
- Liquid Oxygen and Kerosene Price Volatility:Propellant input costs fluctuate with hydrocarbon commodity markets, exposing operators to margin compression during energy price spikes despite fixed ticket pricing.
- Launch Site Concentration Risk:US East Coast and Gulf Coast spaceports handle the majority of crewed commercial missions, creating weather-related scheduling bottlenecks and geographic vulnerability to coastal disruption events.
- Human-Rating Certification Barriers:FAA Part 460 safety standards impose multi-year validation requirements for new vehicle architectures, extending development timelines and capital lockup periods for emerging entrants.
Strategic Opportunities
- UAE and Saudi Arabia Spaceport Development:Gulf sovereign wealth vehicles are funding equatorial launch facilities with favorable orbital mechanics, attracting operators seeking reduced delta-v requirements for geostationary transfer missions.
- Research Hosting Contracts:Microgravity manufacturing and pharmaceutical crystallization applications are creating B2B revenue streams beyond tourism, diversifying customer bases toward institutional and corporate research sponsors.
- NASA Commercial LEO Destination Program:Federal procurement for commercial space station modules is channeling development funding toward habitat constructors, creating anchor tenancy agreements for sustained orbital presence.
Industry Challenges
- Aerospace Medicine Specialist Scarcity:Flight surgeon and space medicine physician training programs produce limited annual graduates, constraining crew health monitoring capabilities as flight rates accelerate.
- Vehicle-to-Vehicle Docking Standardization Delays:Incompatible rendezvous and docking interfaces between commercial capsules and prospective station modules are forcing costly custom adapter development.
- Passenger Liability Insurance Capacity:Underwriter appetite for high-limit space tourism coverage remains constrained, elevating self-insurance requirements and balance sheet exposure for operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Space Travel Market |
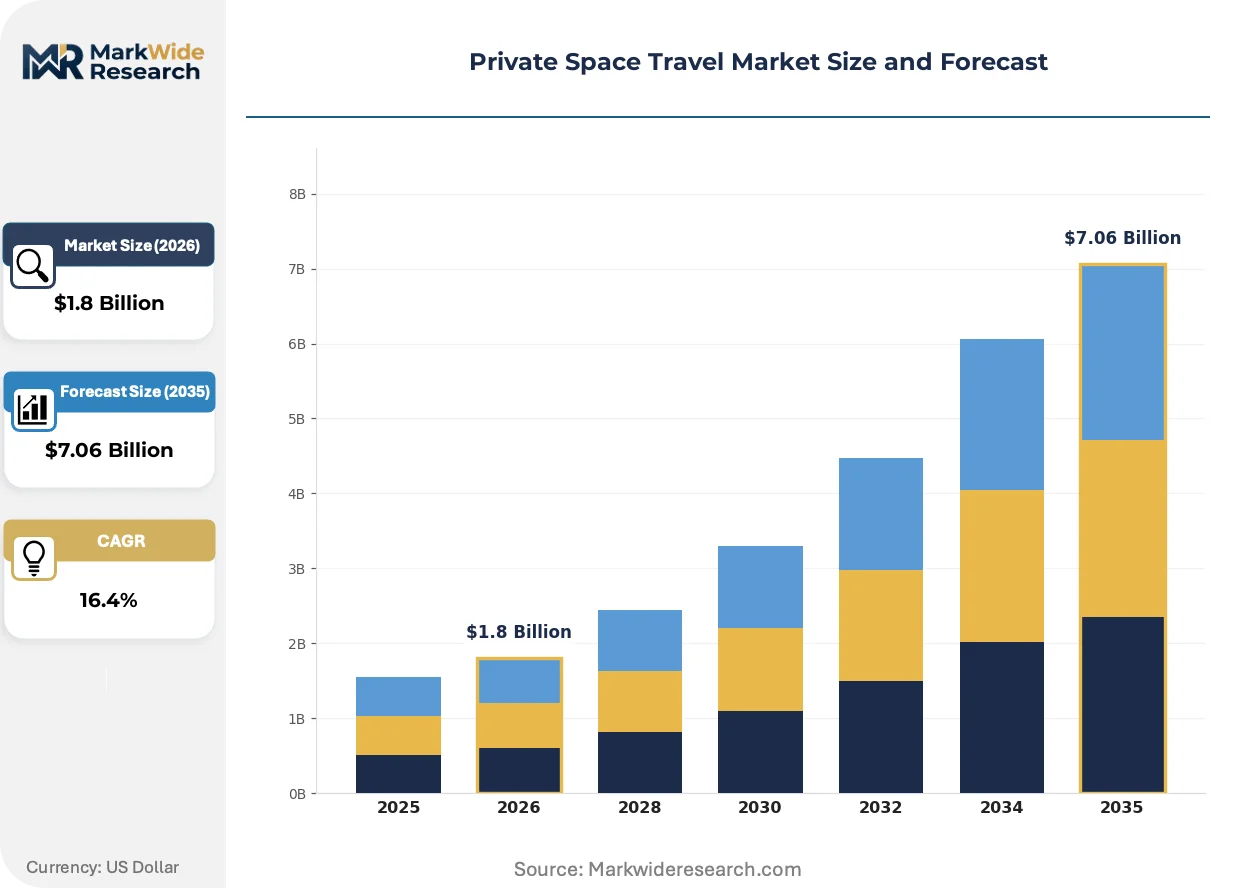
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Orbital Flights, Suborbital Flights, Lunar Missions, Space Tourism, Cargo Delivery Customer Type: Luxury Tourists, Research Institutions, Commercial Enterprises, Government Contractors Technology: Reusable Launch Vehicles, Crew Capsules, Space Habitats, Propulsion Systems, Life Support Systems Mission Duration: Short Duration, Extended Missions, Multi-week Expeditions, Long-term Stays |
| Companies Covered | Virgin Galactic, SpaceX, Blue Origin, Axiom Space, Boeing, Airbus Group SE, Bigelow Aerospace, Orion Span, Space Perspective, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Space Travel Market Trends and Innovations
Propulsion architecture evolution and regulatory adaptation are converging to reshape how commercial human spaceflight services are designed, certified, and consumed across orbital and suborbital categories.
Methane-oxygen full-flow staged combustion engines are collapsing the cost-per-kilogram-to-orbit metric that has governed launch economics since the expendable era. Operators adopting this propulsion architecture are securing payload contracts previously reserved for government missions. The structural consequence is collapsing price floors across the crewed launch services market, forcing legacy hydrogen-oxygen providers into accelerated engine redevelopment programs.
The FAA is finalizing streamlined passenger safety regulations under updated Part 460 frameworks, reducing prescriptive design requirements in favor of performance-based certification. This shift transfers more risk assessment responsibility to operators while accelerating vehicle approval timelines. Suborbital tourism providers with established flight histories are capturing first-mover advantage under the relaxed standards, while orbital entrants face extended validation periods for life-support redundancy demonstrations.
Buyer contracting patterns are fragmenting from single-mission ticket purchases toward multi-flight loyalty structures and research subscription models. Corporate research departments and wealthy individuals are negotiating block bookings with price protection clauses, displacing spot-market transactions. This behavioral shift is most pronounced in US and European markets where repeat passenger programs and institutional research pipelines have achieved critical mass.
Private Space Travel Market Segmentation
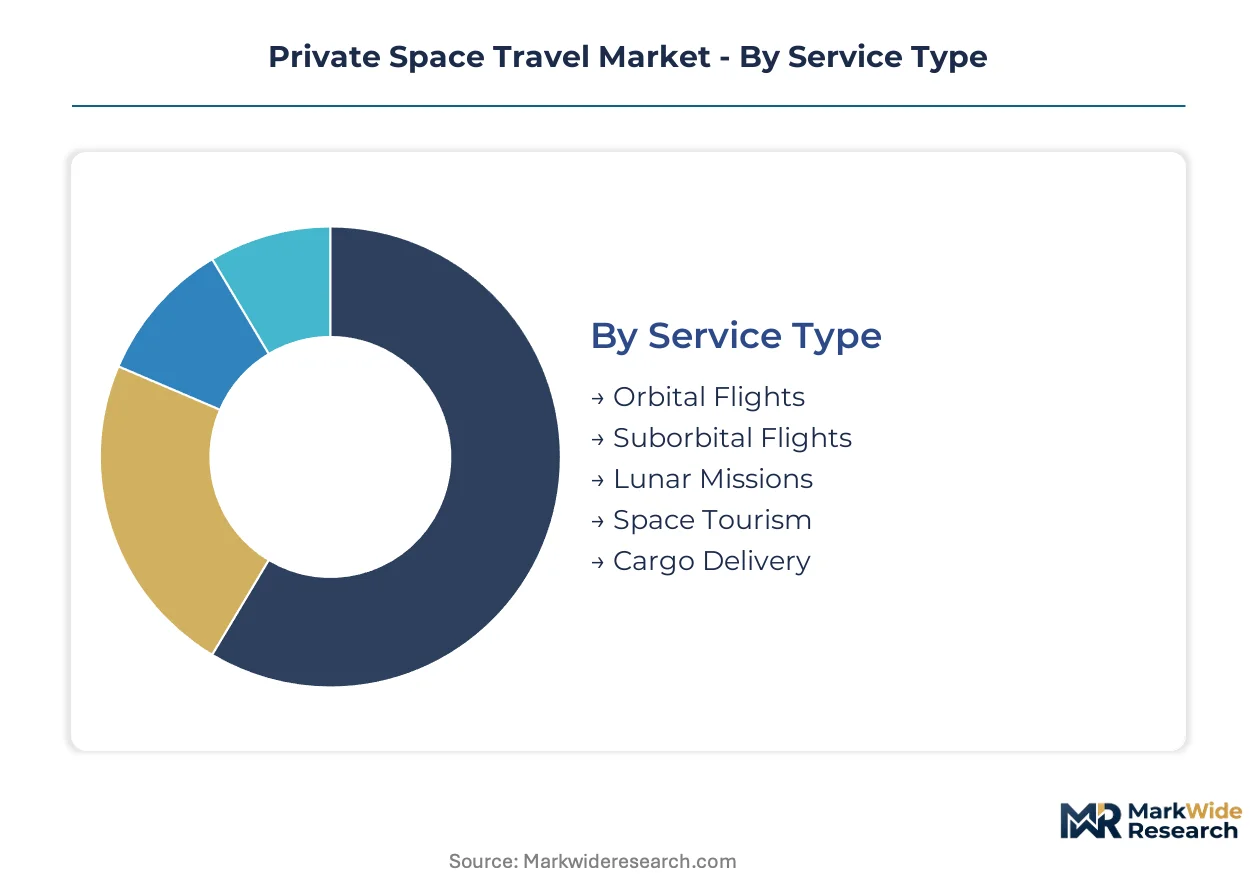
Segmentation in private space travel separates mission economics from customer willingness to pay. Operators configure vehicle architectures and pricing tiers around service intensity, institutional versus leisure demand, and technical certification requirements.
Service Type:
Mature suborbital tourism operations coexist with emerging orbital and cislunar capabilities, creating a capability gradient that segments price points and customer risk profiles.
- Orbital Flights:Multi-day missions above 400 kilometers altitude using Crew Dragon or comparable capsules with pressurized habitats and automated docking. NASA Commercial Crew contracts and private station anchor tenancy concentrate demand in the United States, constrained by limited vehicle availability and human-rating certification timelines.
- Suborbital Flights:Brief weightlessness experiences to 100+ kilometers using rocket-powered spaceplanes or vertical launch systems with glide or parachute recovery. Virgin Galactic and Blue Origin operations in New Mexico and West Texas anchor near-term revenue, though per-seat margins compress as flight cadence scales.
- Lunar Missions:Cislunar trajectories and surface landing expeditions using Starship or Artemis-derived architectures. No commercial operations yet certified; demand concentrates among ultra-high-net-worth individuals and sovereign flag-carrier programs.
- Space Tourism:Experiential packages combining training, launch, and recovery with hospitality elements. Bookings cluster in the United States and United Arab Emirates where spaceport infrastructure and luxury travel ecosystems intersect.
- Cargo Delivery:Unpressurized and pressurized payload transport to orbit or surface destinations. Research institutions and satellite operators in the United States and Europe drive contract volume for dedicated and rideshare missions.
Suborbital Flights retains volume leadership; Orbital Flights holds the steepest expansion curve.
Customer Type:
Cost tier stratification separates individual discretionary spend from institutional procurement cycles and federal program funding.
- Luxury Tourists:Ultra-high-net-worth individuals purchasing experiential missions for personal consumption. United States and Gulf State residency concentrates booking pipelines, with price sensitivity lowest among first-time flyers seeking status differentiation.
- Research Institutions:Universities and national laboratories procuring microgravity access for physical and biological science. European and Japanese academic consortia are expanding contract volume as Crew Dragon availability extends beyond NASA requirements.
- Commercial Enterprises:Pharmaceutical, materials, and satellite companies purchasing repeat-access programs. In-space manufacturing trials for fiber optics and protein crystallization are attracting venture-backed startups in the United States.
- Government Contractors:Prime and subcontractors delivering crew transport or station modules under federal procurement. NASA Commercial LEO Destination awards are channeling development funding toward selected habitat constructors.
Government Contractors anchor current revenue concentration; Commercial Enterprises are climbing the fastest as manufacturing applications mature.
Technology:
Supply concentration in propulsion and thermal protection creates bottleneck dependencies that segment operator margin structures.
- Reusable Launch Vehicles:First-stage recovery systems using propulsive landing or aerial capture. SpaceX booster reuse in Texas and Florida is compressing per-kilogram costs and forcing competitor engine redevelopment programs.
- Crew Capsules:Pressurized vehicles with launch abort systems and water or ground landing capability. Boeing Starliner and Crew Dragon certification by FAA Office of Commercial Space Transportation governs US market access.
- Space Habitats:Modular pressurized volumes for orbital or surface habitation. NASA Commercial LEO Destination funding is accelerating Axiom Space and Orbital Reef development timelines.
- Propulsion Systems:Engines ranging from pressure-fed kerolox to full-flow staged combustion methalox architectures. Blue Origin BE-4 and SpaceX Raptor production rates constrain vehicle delivery schedules.
- Life Support Systems:Environmental control, carbon dioxide removal, and water recycling for crewed missions. Closed-loop system reliability requirements extend certification timelines for emerging habitat providers.
Reusable Launch Vehicles dominate capital deployment; Life Support Systems face the steepest certification backlog as commercial station timelines accelerate.
Mission Duration:
Volume distribution inversely correlates with mission length, as extended stays multiply life support mass and orbital mechanics complexity.
- Short Duration:Suborbital or brief orbital missions under 48 hours. Virgin Galactic and Blue Origin flight profiles match current tourist risk tolerance and training commitment thresholds.
- Extended Missions:Three to fourteen day orbital stays using docked capsules or temporary habitats. Axiom Space private astronaut missions to the International Space Station established this category's commercial viability.
- Multi-week Expeditions:Twenty to ninety day stays requiring dedicated habitat modules and resupply logistics. Commercial station operators are targeting this duration for research manufacturing campaigns.
- Long-term Stays:Six month or longer rotations analogous to ISS crew assignments. No commercial equivalent yet operational; NASA astronaut selection criteria currently govern this duration category.
Short Duration captures current transaction volume; Extended Missions are gaining share fastest as private station availability expands beyond government partnership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth individuals in the United States currently dominate booking pipelines for orbital and suborbital experiences, though sovereign wealth programs in the Gulf States and research consortia in Western Europe are diversifying demand geography.
United States
Luxury tourists and NASA procurement anchor demand concentration. The FAA Office of Commercial Space Transportation governs launch licensing and human-rating certification under Part 460 standards. Cape Canaveral and Houston host the densest operator clusters, with SpaceX and Blue Origin maintaining facilities across Texas and Florida.
United Arab Emirates
Sovereign flag-carrier programs and luxury hospitality integration drive emerging demand. The UAE Space Agency coordinates regulatory frameworks with the country's national aviation regulator. Dubai and Abu Dhabi are developing spaceport-adjacent tourism infrastructure to capture premium experiential travel spend.
Germany
Research institutions and industrial manufacturing trials sustain institutional demand. ESA procurement standards and national space legislation govern payload qualification and crew safety. Bavaria and North Rhine-Westphalia concentrate aerospace engineering capabilities, with Munich hosting satellite and propulsion development clusters.
Japan
Academic microgravity research and corporate materials science programs expand contract volume. METI oversees commercial space activity coordination with JAXA technical standards. The Kanto region around Tokyo anchors space-related manufacturing, while Nagoya hosts precision engineering suppliers for thermal protection systems.
United Kingdom
Satellite operators and emerging suborbital tourism ventures drive commercial interest. The UK Space Agency licenses launch activities under the Space Industry Act 2018. Scotland's Sutherland and Shetland spaceports are advancing vertical launch capabilities for small-lift and future human-rated missions.
Private Space Travel Market Competitive Landscape
Channel-controlling players compete with product-specialist players across vertically integrated launch systems and modular habitat architectures. The market structure concentrates among three to five operators achieving rapid reusability turnaround, with long-tail entrants facing capital barriers and certification delays. Two strategic archetypes dominate: full-stack operators capturing margin across boosters, capsules, and destinations; and subsystem specialists supplying propulsion, life support, or station modules to prime contractors. Competitive moves center on rapid reusability achievement and anchor tenancy agreements for commercial station modules.
Within the full-stack operator tier, SpaceX and Blue Origin exemplify channel control through captive launch and crew transport capabilities. SpaceX occupies a position representing rapid reusability economics, while Blue Origin anchors suborbital tourism operations with in-house propulsion manufacturing. Axiom Space sits within the habitat-specialist archetype, securing NASA Commercial LEO Destination funding to develop modular station capacity.
| Leading Market Players |
|---|
| Virgin Galactic |
| SpaceX |
| Blue Origin |
| Axiom Space |
| Boeing |
| Airbus Group SE |
| Bigelow Aerospace |
| Orion Span |
| Space Perspective |
| Others |
Pricing and Supply Chain Analysis
Texas and Florida spaceport clusters concentrate reusable booster refurbishment capacity, giving SpaceX pricing power over orbital crew missions that competitors cannot match without comparable turnaround velocity.
Pricing Analysis
Cost-plus contracts with NASA Commercial Crew carry fixed-margin indexation to propellant and labor inputs, insulating operators from commodity spikes while capping upside. Three-tier pricing structure across orbital, suborbital, and training-only experiences separates ultra-high-net-worth tourists from research institutions and government contractors. Cost compression in suborbital tourism is intensifying because Virgin Galactic and Blue Origin are scaling flight cadence against fixed infrastructure. Research institutions exhibit highest price sensitivity due to grant-funded procurement cycles, while first-time luxury tourists show lowest sensitivity.
Supply Chain Analysis
Contract manufacturing for crew capsules concentrates at SpaceX Hawthorne facilities and Boeing Starliner production lines in Florida and Alabama. Propulsion systems draw from Blue Origin Kent, Washington and SpaceX McGregor, Texas test sites, with ceramic matrix composites for thermal protection sourced from domestic specialty suppliers. Single-source vulnerability runs through Raptor and BE-4 engine production, where limited qualified alternative suppliers constrain vehicle delivery schedules. Distribution runs through direct operator sales teams and luxury travel concierge networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping private space travel as docking standardization and commercial station interoperability create ecosystem lock-in effects around dominant capsule architectures.
For Market Incumbents: Build regulatory moats through accelerated FAA Part 460 certification for next-generation vehicles before streamlined rules sunset. Incumbents should secure anchor tenancy agreements with Axiom Space and Orbital Reef developers to preempt habitat capacity allocation. Vertical integration into life support systems manufacturing reduces exposure to aerospace medicine specialist scarcity.
For New Entrants and Emerging Players: Gulf State sovereign wealth spaceport development offers underpenetrated launch capacity with favorable orbital mechanics and reduced delta-v requirements. New entrants should target research hosting contracts for microgravity manufacturing, where pharmaceutical and materials science sponsors seek repeat-access programs beyond tourism volatility. A go-to-market angle through corporate R&D departments bypasses consumer marketing costs.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because orbital and cislunar logistics networks will exhibit natural monopoly characteristics as scale economies consolidate. Acquisition targets should display captive launch capacity or certified habitat modules with NASA Commercial LEO Destination funding. The signal to watch is FAA streamlining of passenger safety regulations, which would accelerate vehicle approval timelines and compress capital lockup periods.
| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Booster Rapid Turnaround | SpaceX Texas and Florida facilities compress per-seat costs below hydrogen-oxygen competitors. |
| Commercial Station Anchor Tenancy | Axiom Space and Orbital Reef agreements create sustained orbital presence beyond ISS partnership models. |
| Suborbital Tourism Scale-Up | Virgin Galactic New Mexico operations match tourist risk tolerance with brief weightlessness experiences. |
| Methane-Oxygen Propulsion Transition | Full-flow staged combustion engines collapse cost-per-kilogram metrics governing launch economics. |
| Research Hosting Contract Diversification | Microgravity manufacturing trials attract pharmaceutical and fiber optics venture-backed startups. |
Research Methodology
Initial hypotheses were tested against primary input from commercial spaceflight operators, FAA regulatory affairs specialists, aerospace medicine physicians, and luxury travel concierge directors and refined through secondary validation against FAA Office of Commercial Space Transportation licensing databases, NASA Commercial Crew contract disclosures, and ISO 24113 space debris mitigation standards. Bottom-up triangulation across operator flight manifests and top-down reconciliation against sovereign wealth spaceport investment disclosures anchored market sizing.
Demand-supply-balance modeling across the analysis window segmented by service type, customer archetype, and mission duration with orbital mechanics constraints informing capacity utilization assumptions. CAGRs were derived from flight rate projections and per-seat cost compression curves, with propellant price volatility and human-rating certification timelines as sensitivity inputs.
Practitioners should monitor FAA Part 460 regulatory revisions and commercial station construction delays for early signals of forecast deviation. Cross-checking against NASA budget appropriation trajectories and Gulf State sovereign wealth deployment rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Radar Market
Space
Space Debris Monitoring and Removal Market
Space
Space on Board Computing Platform Market
Space
Asia-Pacific Space Logistics Market
Space
Space Designing Market
Space
Space Sensors Market
Space
Space-Based Smart Sensors Market
Space
Space Tourism Market
Space
LAMEA Space As a Service Market
Space
Spacesuit Market
Space
Space Burial Service Market
Space
UK Space Propulsion System Market
Space
Europe Space Electronics Market
Space
Asia-Pacific Space Electronics Market
Space
Space Traffic Management Market
Space
Space-Based Solar Power Market