
 Space Colonization Market | 2026-2036
Space Colonization Market Size, Share, and Industry Trends Forecast 2026-2036
Space Colonization Market Analysis
Aerospace engineering talent scarcity is redrawing competitive dynamics across the space colonization sector. SpaceX leverages its vertical integration across propulsion and habitat systems to sustain manufacturing cadence. Blue Origin anchors heavy-lift capacity through its New Glenn platform, while Rocket Lab competes in responsive small-launch services for orbital habitat deployment.
Space colonization encompasses the permanent establishment of human settlements beyond Earth through closed-loop life support, in-situ resource utilization, and radiation-hardened habitat construction operating at partial gravity. Propulsion systems and habitat construction dominate current investment flows, with life support systems representing the fastest-growing segment as closed-loop environmental control technology matures. Government agencies command the largest funding type share through public appropriations, though private investment channels are deepening as venture capital shifts toward asteroid mining feasibility.
NASA's Artemis program framework, FAA commercial space launch licensing, and ISO 14620 space systems standards collectively shape market access and vehicle certification requirements. The FAA's streamlined launch licensing process accelerates private mission cadence, while ISO reliability standards govern international cooperation protocols. Stakeholders must monitor regulatory divergence between national space authorities as lunar territorial claims and resource extraction rights remain unresolved.
Market Dynamics
Closed-loop life support maturation is compressing habitat construction timelines while radiation-hardened material certification bottlenecks create supply chokepoints. Aerospace engineering talent scarcity forces contractors to restructure compensation and training pipelines.
Growth Catalysts
- Artemis Procurement Acceleration:NASA's framework compresses vendor qualification cycles for lunar infrastructure. Prime contractors expand subcontractor pools to meet milestone deadlines.
- In-Situ Resource Utilization:Regolith processing technology matures for oxygen extraction and construction feedstock. Demonstration missions validate water-ice harvesting at polar craters.
- United States:Concentrated venture deployment in asteroid mining feasibility studies deepens private capital channels. Launch cadence from Cape Canaveral and Vandenberg anchors manufacturing scale.
Market Restraints
- Rare Earth Magnet Supply:Neodymium and dysprosium concentration in Chinese processing facilities creates propulsion motor vulnerability. Alternative sourcing from Mountain Pass and Australian mines remains underdeveloped.
- Partial Gravity Physiology Uncertainty:Long-duration health effects at lunar and Martian gravity levels constrain mission architecture confidence. Countermeasure development extends pre-deployment timelines.
- FAA Launch Licensing Backlog:Streamlined procedures still face examiner capacity constraints during surge periods. Application queues delay commercial mission windows.
Strategic Opportunities
- United Arab Emirates:Mohammed bin Rashid Space Centre expands international partnership frameworks for habitat technology transfer. Sovereign wealth deployment targets downstream space services.
- Closed-Loop Agriculture:Bioregenerative food systems converge with pharmaceutical-grade controlled environment agriculture. Vertical farming operators pivot equipment designs for partial gravity deployment.
- ISO 14620 Adoption:Reliability standard harmonization creates certification portability across national space agencies. Component suppliers gain multi-jurisdiction market access.
Industry Challenges
- Radiation-Hardened Electronics Talent:Semiconductor design expertise for deep-space environments remains confined to legacy defense contractors. University pipeline output fails to match program staffing requirements.
- Habitat Pressure Vessel Certification:Extended vacuum chamber testing protocols stretch development budgets. Destructive qualification runs consume full-scale prototypes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Colonization Market |
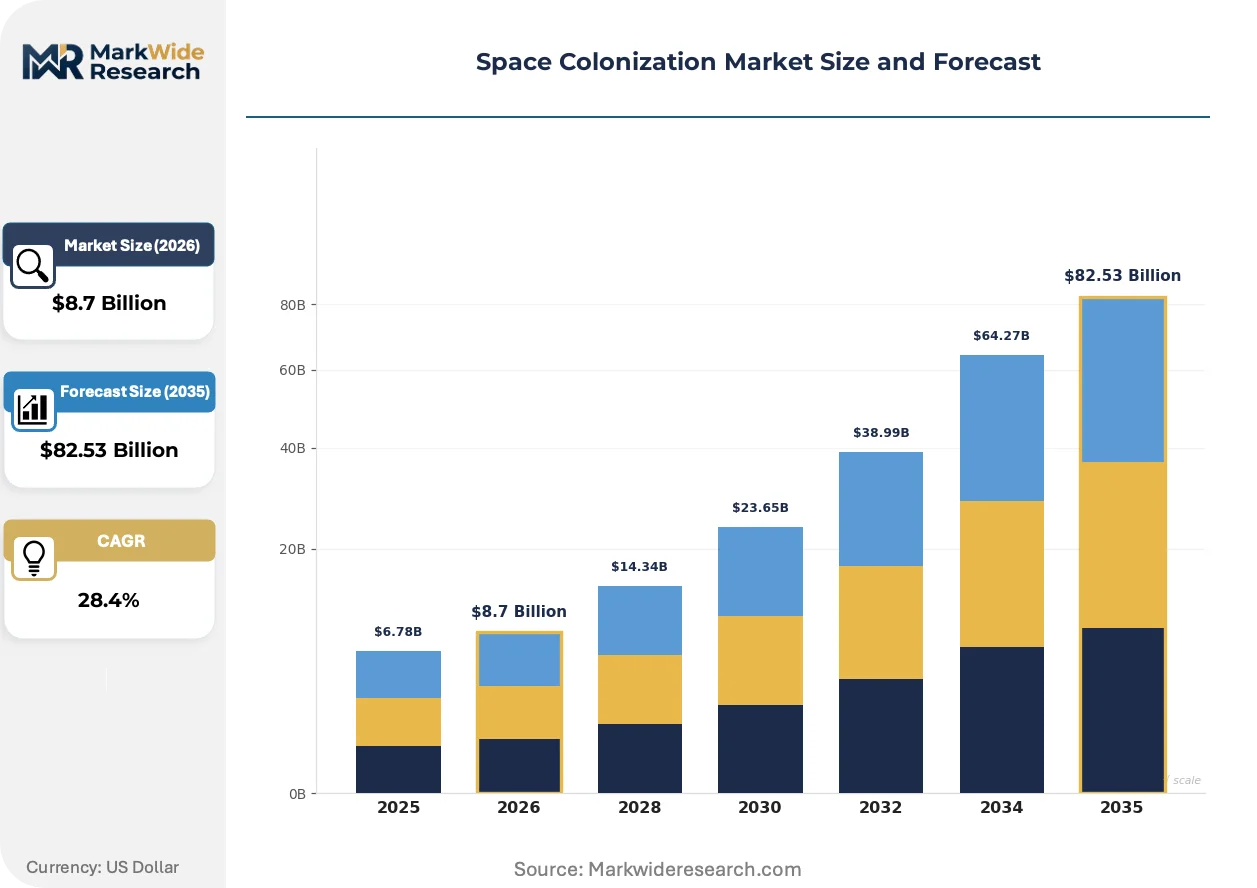
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Terraforming, Habitat Construction, Life Support Systems, Propulsion Systems End User: Government Agencies, Private Companies, Research Institutions, Non-Profit Organizations Application: Asteroid Mining, Lunar Settlement, Mars Colonization, Orbital Habitats Funding Type: Public Funding, Private Investment, Crowdfunding, International Cooperation |
| Companies Covered | SpaceX, Blue Origin, Intuitive Machines, Rocket Lab, Virgin Galactic, Planet Labs, Firefly Aerospace, Voyager Technologies, Ast Spacemobile, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Colonization Market Emerging Trajectories
Propulsion architecture and habitat manufacturing are converging around additive techniques and modular assembly. Regulatory frameworks race to match demonstration mission velocity.
Regolith-derived construction feedstock is miniaturizing habitat module transport mass. Lunar surface sintering equipment from Caterpillar and construction automation specialists enters qualification phases. In-situ manufacturing compresses Earth-launch payload requirements by sixty to eighty percent for permanent structures.
FAA commercial space launch licensing revisions streamline operator certification pathways. Streamlined safety case documentation reduces application preparation burden. Responsive launch providers in the United States accelerate mission cadence through standardized vehicle families.
Buyer concentration around NASA and ESA prime contracts is fragmenting as national space agencies in Saudi Arabia, South Korea, and Australia establish independent procurement frameworks. Direct satellite operator purchases of dedicated launch services displace rideshare aggregation. Australian Space Agency lunar pathway programs demonstrate earliest geographic demand rotation toward non-traditional participants.
Space Colonization Market Segmentation
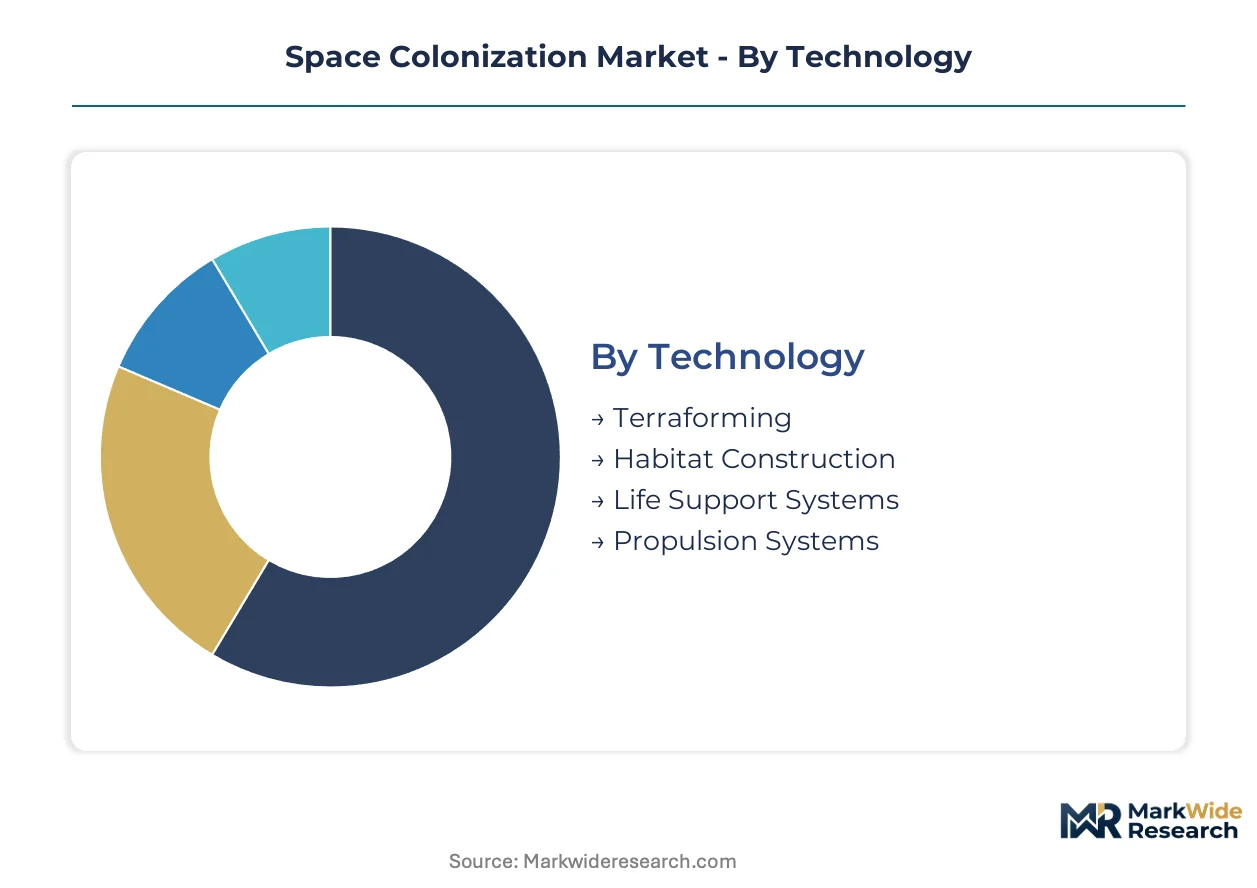
Technology trajectories in space colonization diverge sharply between near-term commercial viability and long-duration speculation. Segment boundaries shift as in-situ manufacturing matures and habitat designs converge across government and private procurement channels.
Technology:
Terraforming faces the most acute substitution pressure from closed-loop habitat architectures that bypass planetary surface modification entirely.
- Habitat Construction:Regolith sintering and inflatable pressure vessels dominate current procurement. NASA Artemis prime contractors in the United States anchor demand for lunar surface structures, though radiation-hardened material certification bottlenecks constrain deployment velocity.
- Propulsion Systems:Chemical and nuclear thermal architectures compete for deep-mission architectures. Heavy-lift capacity expansion at Cape Canaveral and Vandenberg accelerates motor qualification cycles for Mars transit vehicles.
- Life Support Systems:Bioregenerative loops and physico-chemical scrubbers mature for partial gravity deployment. Closed-loop environmental control gains traction in pharmaceutical-grade controlled environment agriculture spinoffs.
- Terraforming:Planetary-scale atmospheric engineering remains theoretical. Research funding concentrates at institutions pursuing long-horizon climate modeling rather than hardware demonstration.
Propulsion Systems anchors the volume base while Life Support Systems gains share at the steepest rate.
End User:
Customer concentration varies by mission timeline, with near-term revenue clustering around entities with appropriated capital and long-range procurement authority.
- Government Agencies:NASA, ESA, and emerging national space agencies command the largest funding type share. Public appropriations sustain multi-year development cycles for lunar infrastructure and Mars precursor missions.
- Private Companies:Venture deployment concentrates in asteroid mining feasibility and responsive launch services. Sovereign wealth funds in the United Arab Emirates deepen capital channels for downstream space services.
- Research Institutions:University consortia and national laboratories advance closed-loop agriculture and partial gravity physiology studies. Talent pipeline constraints limit program staffing scalability.
- Non-Profit Organizations:Mission-driven entities pursue technology transfer and education outreach. Funding volatility constrains hardware development beyond conceptual studies.
Government Agencies dominate current procurement value while Private Companies expand most quickly through venture and sovereign capital deployment.
Application:
Commercial viability horizons stretch across four distinct destination architectures with diverging technical readiness levels.
- Lunar Settlement:Polar water-ice harvesting and regolith processing anchor near-term infrastructure deployment. Artemis program acceleration compresses vendor qualification cycles for surface habitat modules.
- Orbital Habitats:Modular assembly in low Earth orbit precedes deep-space transit staging. Responsive launch providers displace rideshare aggregation with dedicated small-lift services.
- Mars Colonization:Transit vehicle life support and surface power systems face extended development timelines. Countermeasure development for partial gravity physiology uncertainty extends pre-deployment schedules.
- Asteroid Mining:Water and platinum-group metal extraction concepts attract feasibility study investment. Demonstration mission velocity lags behind capital commitment timelines.
Lunar Settlement anchors the volume base while Orbital Habitats climbs the fastest as manufacturing scale effects materialize in low Earth orbit.
Funding Type:
Capital structure preferences align with risk tolerance and mission horizon, reshaping competitive access to development resources.
- Public Funding:Congressional and parliamentary appropriations sustain multi-decade technology maturation. Procurement frameworks in the United States and Europe prioritize reliability standards and international cooperation protocols.
- Private Investment:Venture capital and sovereign wealth deployment target mid-term revenue visibility. Asteroid mining and in-situ resource utilization attract capital seeking resource extraction upside.
- International Cooperation:Bilateral and multilateral frameworks distribute cost and risk across national space agencies. ISO 14620 adoption creates certification portability for component suppliers.
- Crowdfunding:Public contribution models support education and outreach missions. Capital scale constraints limit hardware development to sub-system demonstrations.
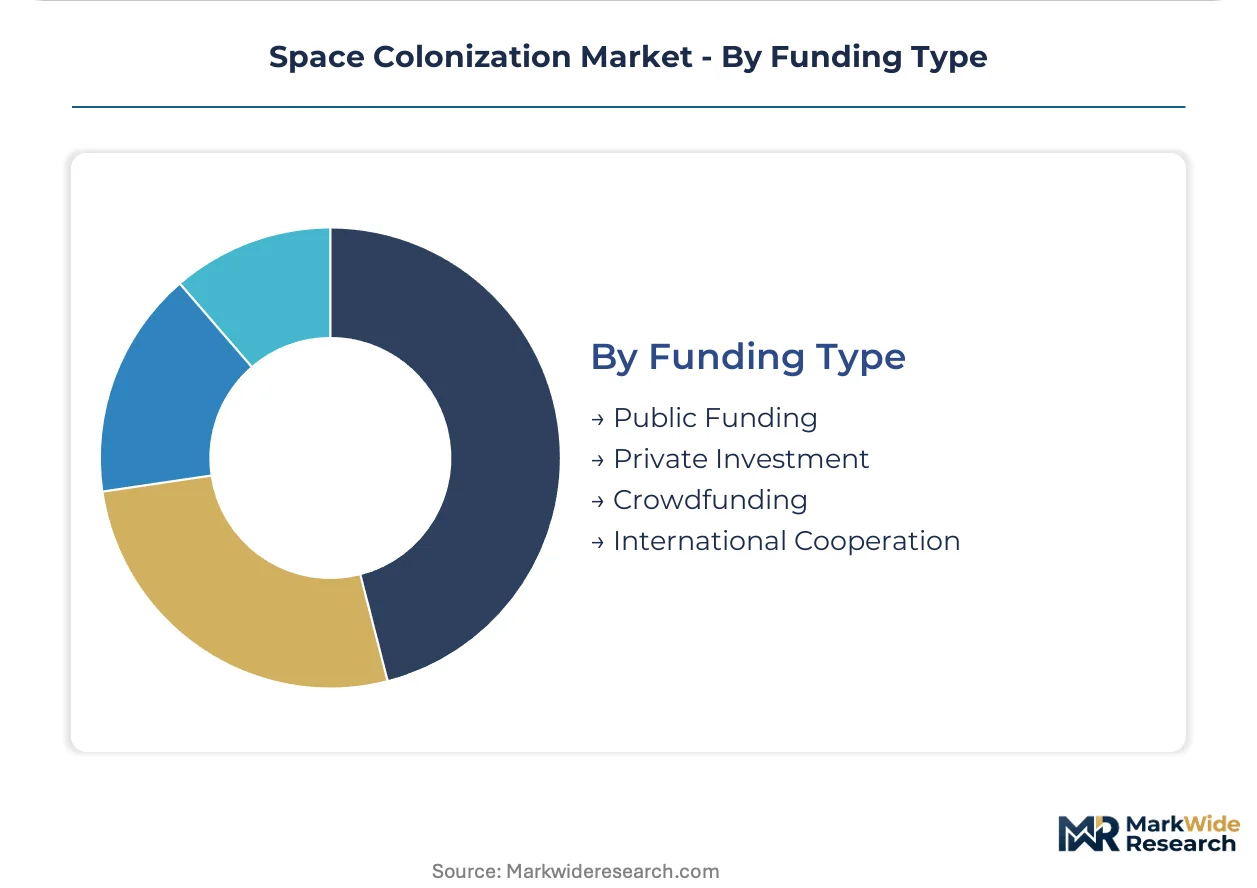
Public Funding anchors the volume base while Private Investment shows the steepest expansion trajectory as venture and sovereign channels deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States launch infrastructure while procurement timelines in Europe lag by twelve to eighteen months. Cape Canaveral and Vandenberg command premium rates for heavy-lift capacity. Regulatory divergence between FAA streamlined licensing and ESA's reliability protocols creates arbitrage opportunities for mission planners.
United States
Artemis program acceleration drives lunar infrastructure procurement at Kennedy Space Center and Marshall Space Flight Center. FAA commercial space launch licensing revisions compress operator certification cycles. Houston's Johnson Space Center anchors astronaut training and habitat systems integration.
China
National space agency lunar south pole missions stimulate domestic propulsion manufacturing. MIIT standards govern satellite and launch vehicle certification. Wenchang Satellite Launch Center on Hainan Island hosts heavy-lift Long March vehicle families.
United Arab Emirates
Mohammed bin Rashid Space Centre deepens international partnership frameworks for habitat technology transfer. Sovereign wealth deployment targets downstream space services. Dubai's space technology cluster attracts foreign engineering talent through specialized visa programs.
Japan
JAXA lunar polar exploration missions advance regolith processing demonstrations. METI coordinates private sector participation in international space station successor programs. Tanegashima Space Center maintains East Asian launch capacity for geostationary missions.
Australia
Australian Space Agency lunar pathway programs demonstrate geographic demand rotation toward non-traditional participants. Civil Aviation Safety Authority adapts launch licensing for commercial operators. South Australia's Woomera Range Complex hosts suborbital and small-lift vehicle testing.
Space Colonization Market Vendor Landscape
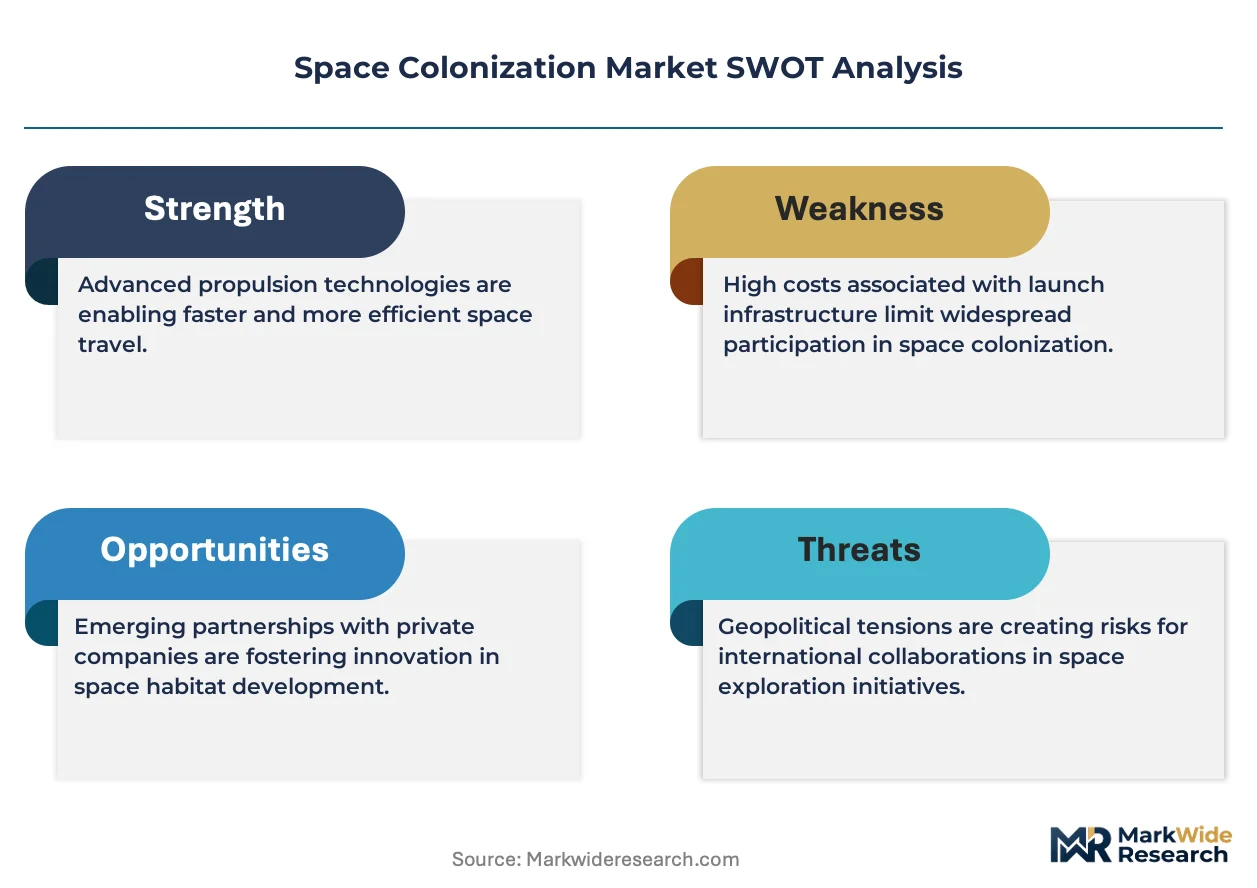
Technology leadership and cost leadership are held by different player archetypes across the space colonization sector. Market structure consolidates around vertically integrated heavy-lift providers while fragmenting across responsive small-launch specialists. Prime contractors anchor government procurement channels. Emerging national space agencies cultivate second-tier domestic champions. Dominant competitive moves include strategic partnerships for international mission access and in-situ manufacturing capability development.
Among United States-based heavy-lift providers, SpaceX and Blue Origin occupy positions at opposite ends of the vertical integration spectrum. Rocket Lab exemplifies the responsive launch archetype for dedicated small-payload missions. These three companies represent the dominant competitive vectors: scale-driven infrastructure, diversified aerospace conglomerate backing, and agile mission cadence.
| Leading Market Players |
|---|
| SpaceX |
| Blue Origin |
| Intuitive Machines |
| Rocket Lab |
| Virgin Galactic |
| Planet Labs |
| Firefly Aerospace |
| Voyager Technologies |
| Ast Spacemobile |
| Others |
Supply Flow & Price Mechanics
FAA commercial space launch licensing gates both supplier qualification and launch service pricing tiers simultaneously. Certification under streamlined pathways commands premium positioning against standard review timelines. Buyers with mission-critical windows absorb elevated rates for expedited slots at Cape Canaveral and Vandenberg.
Pricing Analysis
Configured-to-order pricing for dedicated heavy-lift missions spreads substantially above standard rideshare aggregation rates. Project-based contracting dominates, with price differentiation resting on certification grade and launch window certainty. Cost compression in small-launch services intensifies as Rocket Lab and Firefly Aerospace expand reusable vehicle families. Government agencies show lowest price sensitivity, while commercial satellite operators optimize for rideshare economies.
Supply Chain Analysis
Strategic stockpiling of radiation-hardened electronics and rare earth magnets prevails over just-in-time approaches given qualification timelines. Supply concentrates in the United States for launch infrastructure, China for neodymium processing, and Japan for precision components. Propulsion systems draw from titanium alloys, carbon fiber composites, and high-performance ceramics. Single-source vulnerability in Chinese rare earth refining creates structural exposure. Distribution runs through prime contractor integration facilities at Kennedy Space Center and Marshall Space Flight Center.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as national space agencies beyond NASA and ESA establish independent procurement frameworks, creating niche supplier openings. Buyer diversification across Saudi Arabia, South Korea, and Australia splinters previously concentrated demand.
For Market Incumbents: Consolidate subcontractor pools to capture Artemis program acceleration and compress vendor qualification cycles. Lock in regolith processing technology partnerships before demonstration missions validate alternative approaches. Capacity addition in Huntsville and Stennis anchors manufacturing scale against emerging regional competitors.
For New Entrants and Emerging Players: ISO 14620 fast-track certification unlocks multi-jurisdiction component supply to ESA and JAXA procurement channels. White-space targets include closed-loop agriculture equipment for pharmaceutical-grade spinoffs and lunar surface sintering automation. Australian Space Agency lunar pathway programs offer the most penetrable geography for first contract wins. Go-to-market through sovereign wealth fund co-investment structures in the United Arab Emirates bypasses traditional prime contractor gatekeeping.
For Investors and Strategic Acquirers: FAA streamlined licensing completion reshapes the acquisition landscape toward responsive launch operators with cleared vehicle families. Long-term viability favors specialists with demonstrated partial gravity habitat qualification over pure propulsion plays. Target acquisition archetype: mid-tier life support subsystem suppliers with ISO certification portability. Signal to watch: Artemis prime contractor subcontractor pool expansion announcements indicating vendor diversification appetite.
| Strategic Initiative | Industry Significance |
|---|---|
| In-Situ Manufacturing Partnership | Caterpillar lunar sintering equipment qualification compresses Earth-launch payload requirements for NASA contractors. |
| Regulatory Certification Fast-Track | FAA streamlined licensing accelerates operator cadence for commercial mission providers at Cape Canaveral. |
| Vertical Habitat Integration | Closed-loop life support convergence with pharmaceutical agriculture opens dual-revenue streams for equipment suppliers. |
| Sovereign Wealth Co-Investment | Mohammed bin Rashid Space Centre frameworks channel UAE capital toward downstream space service operators. |
| Rare Earth Supply Diversification | Mountain Pass and Australian mine development reduces Chinese processing concentration for propulsion motor inputs. |
Methodological Framework
Operator-level perspectives from propulsion engineering directors, habitat systems integrators, launch range operations officers, and national space agency procurement leads anchored the qualitative base. Primary interviews combined with secondary validation against NASA procurement databases, FAA launch licensing records, ESA tender announcements, and ISO 14620 certification registries. Bottom-up segment sizing triangulated with top-down macro constraint analysis across technology, end user, application, and funding type dimensions.
Sensitivity analysis tested forecast robustness across the projection horizon against Artemis program budget volatility and rare earth supply disruption scenarios. The analytical framework modeled habitat construction, propulsion systems, life support systems, and terraforming segments by government agency, private company, research institution, and non-profit organization end users. CAGRs derived from regression against historical launch cadence and procurement award patterns, with lunar settlement, orbital habitats, Mars colonization, and asteroid mining applications as cross-cutting forecast inputs.
Underlying assumptions cover Artemis procurement acceleration continuity and FAA examiner capacity expansion, with deviation risk concentrated in partial gravity physiology study outcomes and international territorial claim resolutions. Forecasts reflect documented conditions with acknowledged sensitivity to sovereign wealth fund deployment velocity and radiation-hardened electronics talent pipeline output. Revision becomes warranted when FAA application queue durations exceed surge capacity thresholds or regolith demonstration missions fail validation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Semiconductor Market
Space
India Space Electronics Market
Space
China Space Propulsion System Market
Space
Spacesuit Market
Space
Space Tourism Market
Space
India Aviation, Defense, and Space Market
Space
Spacecraft Market
Space
Space on Board Computing Platform Market
Space
US Space Launch Services Market
Space
Space-Based C4ISR Market
Space
Space Ground System Market
Space
Germany Space Electronics Market
Space
Spain Space Electronics Market
Space
Africa Space Electronics Market
Space
Japan Space Electronics Market
Space
Canada Space Electronics Market