
 North America Food Hydrocolloids Market | 2026-2036
North America Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Hydrocolloids Market Analytics
The FDA's updated food additive review framework is hardening clean-label requirements across the North American food industry. Cargill leverages its integrated supply chain to secure consistent guar gum and pectin volumes for major food manufacturers. CP Kelco anchors its position through specialized fermentation capabilities for xanthan gum production. Kerry Group differentiates via customized hydrocolloid blends tailored to dairy alternative textures.
Food hydrocolloids comprise high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to form viscous solutions or gels, with typical usage levels ranging from 0.1% to 2.0% by weight depending on the desired rheological profile. These functional ingredients primarily control water mobility, stabilize emulsions, and build texture in processed foods across temperature and pH extremes. Pectin and xanthan gum command premium positioning within the product type landscape due to their plant-derived credentials and versatile thickening profiles. The beverages application segment shows structural momentum as manufacturers reformulate with reduced sugar and enhanced mouthfeel. Powder form dominates current manufacturing workflows for its extended shelf stability and ease of dry blending in large-scale food production.
The FDA and USDA jointly govern hydrocolloid safety assessments and labeling standards across the United States, while Health Canada and PMRA administer parallel frameworks for Canadian market access. The FDA's Generally Recognized as Safe notification process directly shapes ingredient innovation timelines and reformulation strategies for suppliers. Stakeholders must monitor evolving clean-label certification thresholds and state-level ingredient disclosure mandates to maintain formulation compliance and commercial positioning.
Market Dynamics
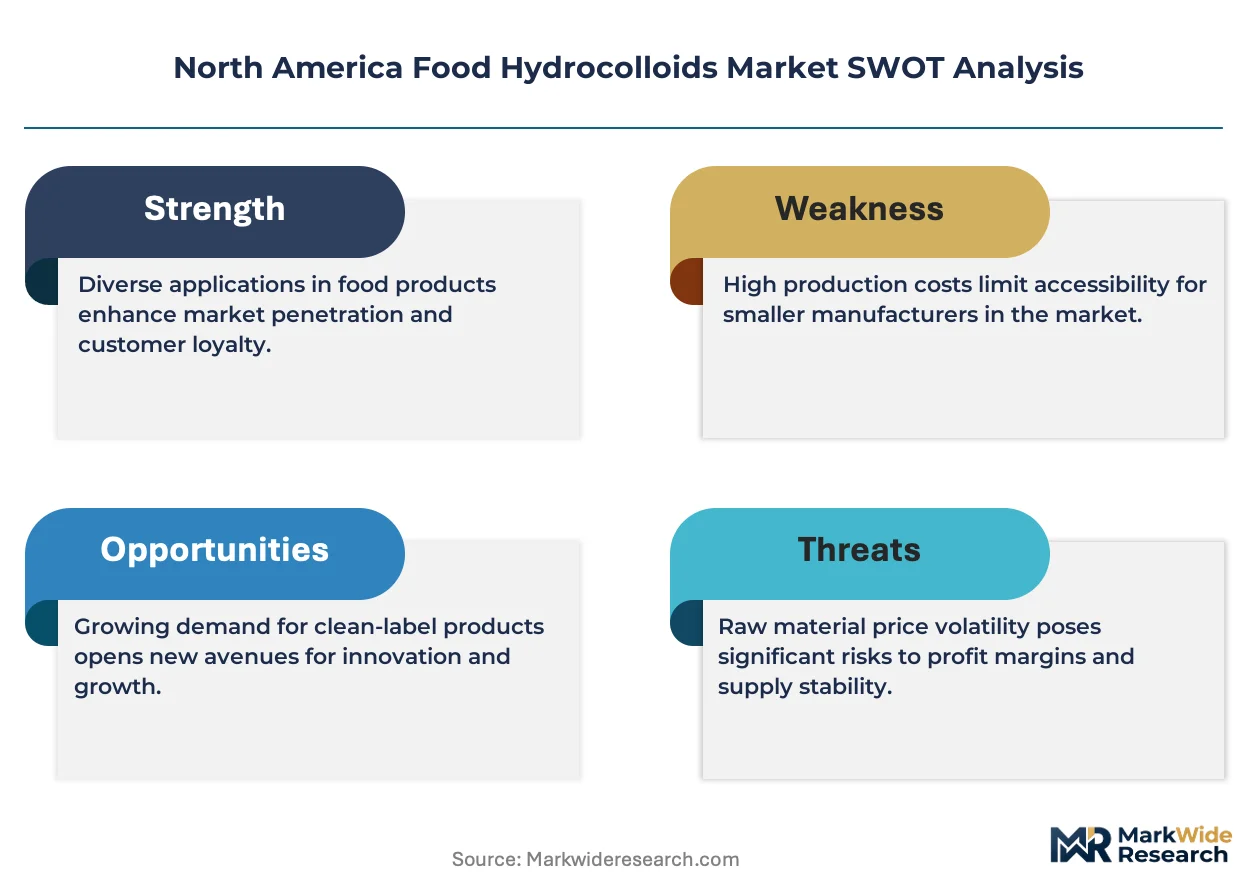
The FDA's updated food additive review framework is compressing innovation timelines while amplifying clean-label compliance costs across North American hydrocolloid procurement.
Growth Catalysts
- Plant-based dairy alternatives:Oat, almond, and pea protein beverages require hydrocolloid stabilization systems to replicate traditional dairy mouthfeel and prevent phase separation during shelf storage.
- California's clean-label manufacturing corridor:Concentrated food production in the San Joaquin Valley and Bay Area generates clustered demand for certified-organic pectin and locust bean gum with full supply chain traceability.
- Fermentation-derived xanthan gum:Advanced bioprocessing platforms are expanding domestic production capacity, reducing import dependency on Asian supply sources for this critical texturizing agent.
Market Restraints
- Guar gum price volatility:Weather-dependent harvests in India and Pakistan create input cost instability that propagates through North American thickener formulations and margin structures.
- Single-source fermentation capacity:Xanthan gum production concentrates among specialized biotech facilities, creating supply vulnerability when equipment downtime or contamination events occur.
- FDA notification backlog:Extended Generally Recognized as Safe review queues delay novel hydrocolloid launches and reformulation approvals by 18-24 months.
Strategic Opportunities
- Mexico's processed food expansion:Underpenetrated hydrocolloid usage in Latin American-owned manufacturing facilities near the US border offers volume growth as NAFTA-aligned supply chains deepen.
- Cell-cultured meat texturization:Scaffold and matrix applications for alternative proteins represent an emerging demand vertical requiring custom gelation profiles and thermal stability.
- USDA BioPreferred program:Federal procurement preferences for biobased ingredients create certification-driven channel access for domestically produced fermentation hydrocolloids.
Industry Challenges
- Clean-label certification complexity:Multiple overlapping standards from Non-GMO Project, USDA Organic, and retailer-specific programs fragment compliance requirements and audit costs.
- Bioprocess engineering talent scarcity:Specialized fermentation scale-up expertise remains concentrated among legacy xanthan gum producers, constraining new facility staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Hydrocolloids Market |
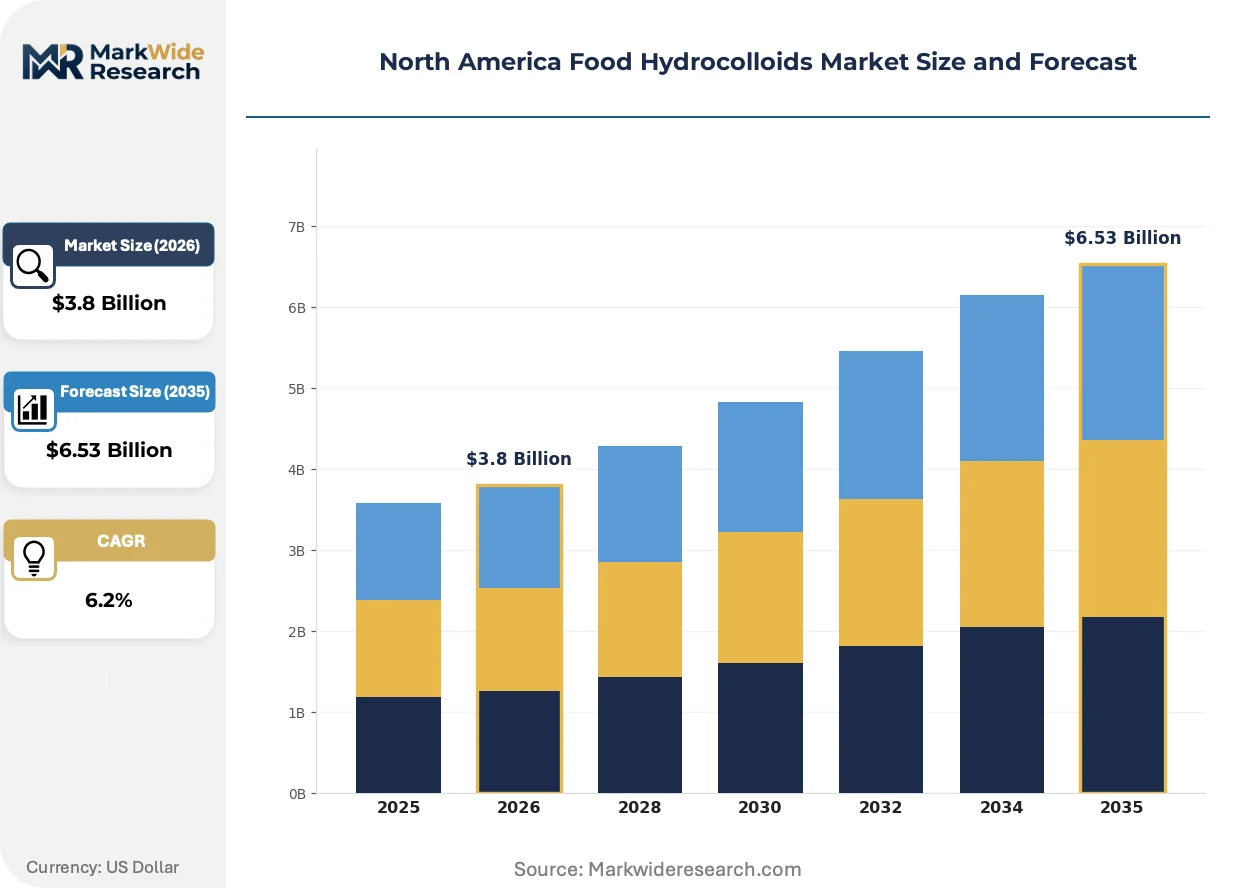
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Pectin, Xanthan Gum, Guar Gum Application: Dairy Products, Bakery, Sauces, Beverages Form: Powder, Liquid, Granule, Paste End User: Food Manufacturers, Retailers, Food Service, Private Label |
| Companies Covered | Cargill, CP Kelco, Kerry Group, Ingredion Incorporated, Archer Daniels Midland Company, DuPont de Nemours Inc., Ashland Global Holdings Inc., Tate & Lyle PLC, Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Hydrocolloids Market Evolving Landscape
Clean-label formulation pressures are forcing simultaneous innovation across extraction methods, fermentation platforms, and finished-product certification architectures.
Precision fermentation for hydrocolloid production is consolidating competitive positioning among suppliers with captive biotech infrastructure. Mid-sized food manufacturers are adopting these domestically produced alternatives to reduce supply chain risk and simplify origin documentation. The technology is consolidating procurement patterns toward vertically integrated fermentation specialists with in-house strain development capabilities.
Health Canada's updated Food and Drug Regulations for novel food ingredients are tightening pre-market notification requirements for enzymatically modified hydrocolloids. Canadian manufacturers face extended approval timelines that compress product launch windows and increase regulatory consulting expenditures. The protein-fortified beverage segment is responding by reverting to established pectin and carrageenan grades with grandfathered regulatory status.
Beverage brand procurement teams are consolidating supplier relationships from multi-source spot buying toward strategic partnerships with full-service hydrocolloid blenders. Large-scale co-manufacturers in Texas and Illinois are displacing fragmented distributor networks with direct technical service agreements. This concentration is most visible in the carbonated soft drink reformulation segment, where reduced-sugar launches require customized viscosity modulation.
North America Food Hydrocolloids Market Segmentation
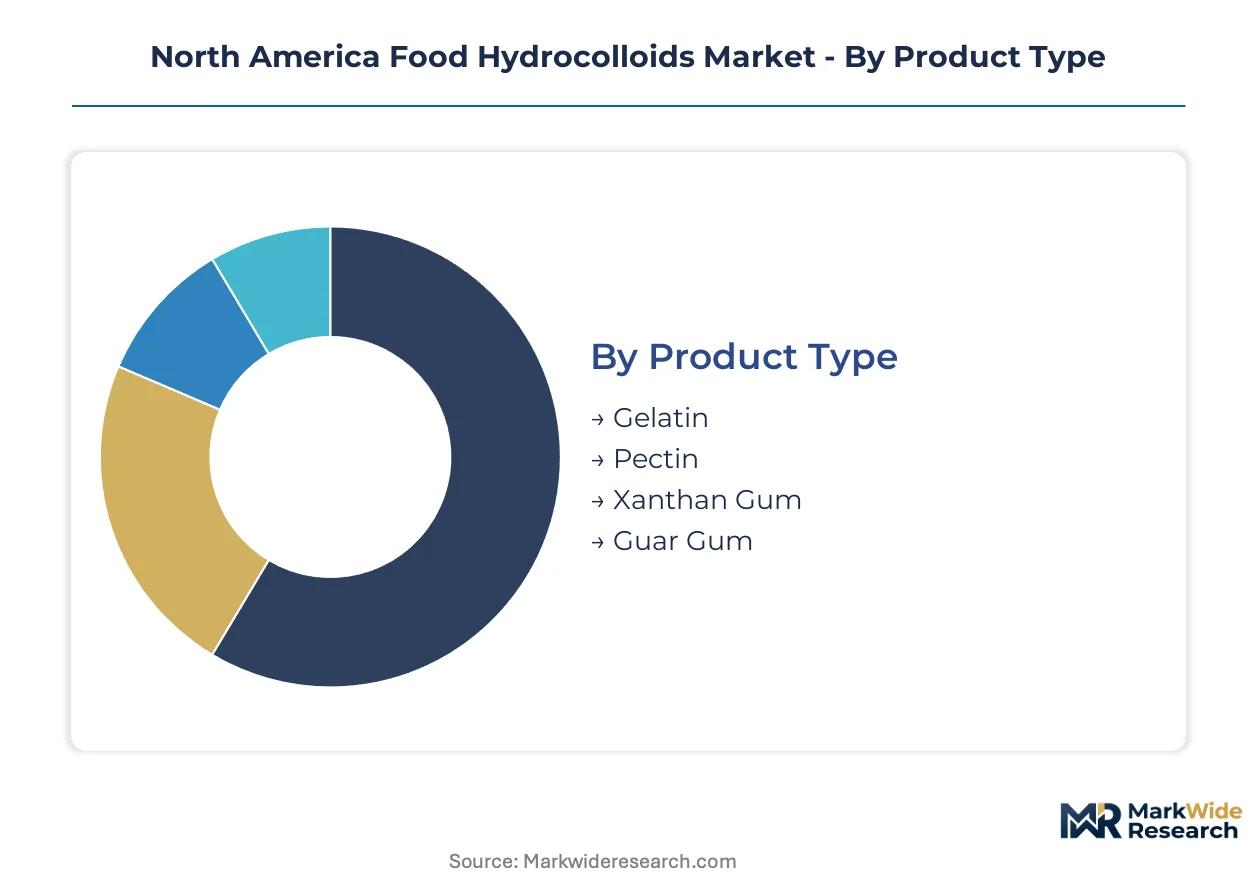
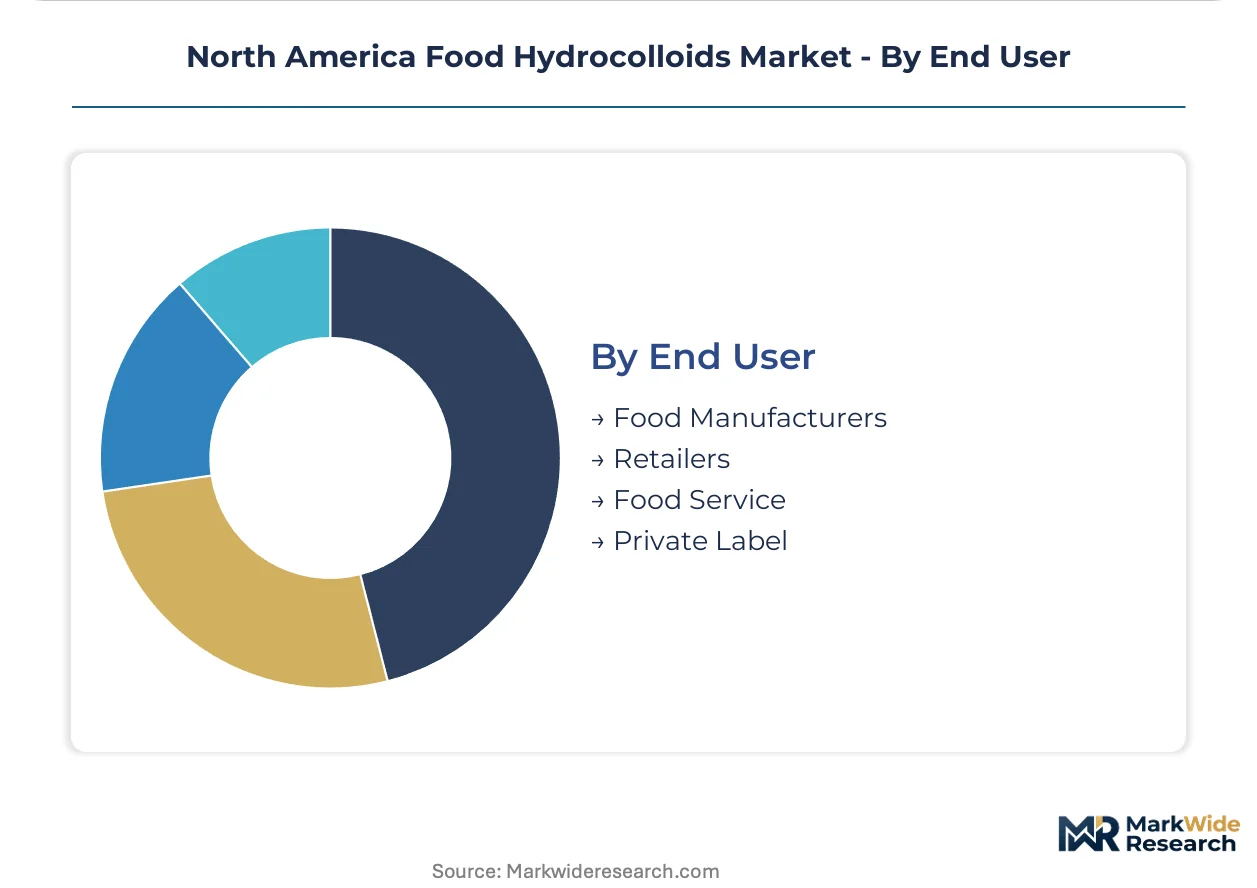
North American food hydrocolloids procurement fragments across four structural dimensions. Product type determines supply chain configuration and regulatory pathway. Application and end-user specifications dictate formulation complexity and service intensity requirements.
Product Type:
Manufacturers upgrade stabilization systems as clean-label mandates displace legacy ingredients across reformulation cycles.
- Pectin:Citrus and apple-derived polysaccharide with amidated and high-ester variants for calcium-set or acid-stable gelation. Demand concentrates in California's organic juice processors seeking Non-GMO Project verification for reduced-sugar beverages.
- Xanthan Gum:Fermentation-produced exopolysaccharide with pseudoplastic rheology and salt-tolerant viscosity. CP Kelco's specialized bioreactors in San Diego County supply Texas-based beverage co-manufacturers reformulating carbonated soft drinks.
- Gelatin:Collagen hydrolysate from porcine and bovine sources with Bloom strength gradations for confectionery and dairy applications. FDA's updated food additive review framework extends approval timelines for novel gelatin blends.
- Guar Gum:Galactomannan from cluster bean endosperm with cold-water solubility and synergistic viscosity enhancement with xanthan. Weather-dependent harvests in India and Pakistan propagate price instability through North American thickener formulations.
Pectin sits at the top of the volume ranking, with xanthan gum climbing the fastest as fermentation capacity expands domestically.
Application:
Cost tier separation emerges between commodity-scale dairy applications and premium-positioned beverage texturization demanding technical service intensity.
- Beverages:Hydrocolloid systems modulate mouthfeel in reduced-sugar formulations and stabilize protein-fortified alternatives. San Joaquin Valley juice processors drive concentrated demand for certified-organic pectin with full supply chain traceability.
- Dairy Products:Gelation and emulsion stabilization in yogurt, ice cream, and processed cheese applications. Plant-based dairy alternatives in California and Texas require hydrocolloid systems to replicate traditional dairy texture and prevent phase separation.
- Bakery:Moisture retention and crumb structure modification in gluten-free and extended-shelf-life formulations. FDA's Generally Recognized as Safe notification backlog delays novel hydrocolloid launches for clean-label bread applications.
- Sauces:Viscosity building and freeze-thaw stability in pourable and spoonable dressing categories. Kerry Group supplies customized hydrocolloid blends to Illinois-based co-manufacturers producing private-label condiments.
Dairy products command the largest absolute volume, though beverages gain share fastest as sugar reduction mandates accelerate reformulation activity.
Form:
Manufacturing workflow compatibility and shelf stability requirements segment procurement by physical presentation format.
- Powder:Spray-dried or milled particulate with extended shelf stability and dry-blending compatibility. Dominates current North American manufacturing workflows for large-scale food production across Texas and Illinois facilities.
- Liquid:Pre-hydrated suspensions eliminating dust exposure and hydration time in high-throughput beverage lines. Cargill leverages integrated supply chain to secure consistent liquid pectin volumes for major juice manufacturers.
- Granule:Agglomerated particles with reduced dusting and improved dispersibility compared to fine powders. Health Canada's updated Food and Drug Regulations for novel food ingredients tighten pre-market requirements for enzymatically modified granule grades.
- Paste:High-solids preparations for immediate incorporation into wet-processed applications. Limited adoption outside specialized confectionery and dairy processing equipment configurations.
Powder form maintains volume leadership, while liquid preparations expand most quickly in beverage sector automation upgrades.
End User:
Customer type determines service model intensity from commodity distribution to collaborative formulation development.
- Food Manufacturers:Branded and private-label processors requiring technical service support for reformulation and scale-up. Procurement teams consolidate from multi-source spot buying toward strategic partnerships with full-service hydrocolloid blenders.
- Food Service:Institutional and commercial kitchen operators sourcing pre-blended stabilizer systems for consistency. Underpenetrated hydrocolloid usage in Mexico's Latin American-owned manufacturing facilities near the US border offers expansion potential.
- Retailers:Private-label program managers specifying ingredient grades for supplier qualification. Clean-label certification complexity from Non-GMO Project, USDA Organic, and retailer-specific programs fragments compliance requirements.
- Private Label:Contract manufacturers producing store-brand products across multiple retail banners. USDA BioPreferred program creates certification-driven channel access for domestically produced fermentation hydrocolloids.
Food manufacturers represent the dominant volume segment, with food service climbing fastest as institutional procurement professionalizes ingredient specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food hydrocolloid manufacturing first scaled in the Midwestern United States during the mid-20th century, when corn wet-milling infrastructure spawned fermentation-based texturizer production. Today the industry concentrates in three national markets with distinct regulatory and supply chain profiles.
United States
California's San Joaquin Valley and Bay Area generate clustered demand for certified-organic pectin with full supply chain traceability. The FDA's updated Generally Recognized as Safe notification process extends approval timelines for novel hydrocolloid launches by 18-24 months. Texas and Illinois host large-scale beverage co-manufacturers consolidating procurement toward direct technical service agreements with full-service hydrocolloid blenders.
Canada
Health Canada's updated Food and Drug Regulations for novel food ingredients tighten pre-market notification requirements for enzymatically modified hydrocolloids. Canadian protein-fortified beverage manufacturers respond by reverting to established pectin and carrageenan grades with grandfathered regulatory status. Ontario and Quebec processors face extended approval timelines that compress product launch windows and increase regulatory consulting expenditures.
Mexico
Latin American-owned manufacturing facilities near the US border show underpenetrated hydrocolloid usage, offering volume growth as NAFTA-aligned supply chains deepen. The country's federal consumer protection agency coordinates with US FDA on cross-border ingredient safety protocols. Nuevo León and Baja California house expanding processed food operations upgrading stabilization systems for export-oriented production.
North America Food Hydrocolloids Market Competitive Landscape
Capital-heavy fermentation specialists compete with asset-light formulation designers across the North American hydrocolloid supply base. The market structure shows moderate consolidation, with three to five integrated suppliers commanding premium positioning in fermentation-derived xanthan gum while numerous regional blenders serve commodity dairy and bakery applications. Strategic archetypes include captive biotech infrastructure operators, integrated agricultural processors with seed-to-hydrocolloid control, and specialized blenders offering customized texture systems. Dominant competitive moves center on backward integration into fermentation capacity and strategic partnerships with beverage co-manufacturers seeking reformulation support.
Among integrated agricultural processors, Cargill leverages its supply chain architecture to secure consistent guar gum and pectin volumes for major food manufacturers. CP Kelco anchors the fermentation-specialist tier through its San Diego County bioreactor operations supplying Texas-based beverage reformulators. Kerry Group occupies a position within the customized-blender segment, differentiating via tailored hydrocolloid systems for dairy alternative textures.
| Leading Market Players |
|---|
| Cargill |
| CP Kelco |
| Kerry Group |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| DuPont de Nemours Inc. |
| Ashland Global Holdings Inc. |
| Tate & Lyle PLC |
| Koninklijke DSM N.V. |
| Others |
Value Network & Pricing Analysis
Guar gum harvest volatility in India and Pakistan propagates through North American hydrocolloid pricing tiers, compressing margins for standard-grade thickeners while fermentation-derived xanthan commands premium positioning among California's clean-label beverage manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified-organic pectin from conventional food-grade hydrocolloids and commodity guar derivatives. Price differentiation rests on Non-GMO Project verification and USDA Organic certification, with California juice processors absorbing 15-20% premiums for full traceability documentation. Cost compression in standard-grade guar gum is intensifying because weather-dependent South Asian harvests destabilize input costs. Small-scale bakery manufacturers show highest price sensitivity, while beverage co-manufacturers prioritize technical service over per-kilogram economics.
Supply Chain Analysis
Direct technical service agreements between fermentation specialists and Texas-based beverage co-manufacturers displace fragmented distributor networks for high-volume reformulation projects. Raw material sourcing draws from Indian guar seed cultivation, Chinese xanthan fermentation capacity, and domestic citrus peel pectin extraction in Florida and California. Single-source fermentation vulnerability concentrates supply risk when bioreactor contamination or equipment downtime occurs. Distribution runs through integrated agricultural processors with captive seed-to-hydrocolloid control, bypassing spot-market intermediaries for strategic accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American food hydrocolloids constitute a late-cycle quality story as beverage manufacturers trade up to certified-organic pectin and precision-fermentation xanthan amid sugar-reduction mandates and clean-label procurement standards.
For Market Incumbents: Extend fermentation capacity in San Diego County and Nuevo León to capture NAFTA-aligned supply chain consolidation. Deepen backward integration into guar seed processing through partnerships with Rajasthan agricultural cooperatives, reducing exposure to Indian monsoon volatility. Defend margin position by embedding technical service teams within California clean-label manufacturing corridors. For New Entrants and Emerging Players: Mexico's Latin American-owned manufacturing facilities near the US border represent the most penetrable demand pocket, with underdeveloped hydrocolloid specifications in processed meat and condiment applications. Target Illinois private-label sauce co-manufacturers with customized stabilizer blends offering freeze-thaw stability guarantees. Establish channel access through USDA BioPreferred program certification for domestically produced fermentation hydrocolloids. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized fermentation scale-up expertise remains concentrated among legacy xanthan gum producers with captive biotech infrastructure. Long-term viability favors vertically integrated specialists with in-house strain development capabilities and direct technical service relationships with beverage reformulators. Monitor FDA Generally Recognized as Safe notification queue lengths as an inflection indicator for novel hydrocolloid launch velocity and incumbent pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Domestic xanthan gum production reduces import dependency on Asian supply sources. |
| Backward Integration into Guar Seed Processing | Captive agricultural supply insulates margin structures from South Asian weather volatility. |
| Clean-Label Certification Investment | Non-GMO Project and USDA Organic credentials unlock California beverage manufacturer procurement. |
| Technical Service Partnership Model | Embedded formulation support differentiates commodity hydrocolloid supply through value-added collaboration. |
| NAFTA-Aligned Supply Chain Development | Mexico manufacturing footprint captures processed food expansion in Nuevo León and Baja California. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining interviews with hydrocolloid procurement managers at beverage co-manufacturers, fermentation facility operations directors, regulatory affairs specialists navigating FDA notification queues, and agricultural commodity traders tracking guar seed harvests. Secondary validation draws from FDA Generally Recognized as Safe filings, Health Canada novel food ingredient submissions, USDA organic certification databases, and customs trade records for hydrocolloid imports. Bottom-up volume modeling triangulates against top-down market sizing across product type, application, and end-user segments.
Rate-of-change decomposition separates volume growth from price/mix effects across the projection horizon. Segmentation dimensions modeled include product type (pectin, xanthan gum, gelatin, guar gum), application (beverages, dairy, bakery, sauces), form (powder, liquid, granule, paste), and end-user category (food manufacturers, food service, retailers, private label). CAGRs derive from historical trajectory analysis adjusted for regulatory timeline impacts and supply chain restructuring events. Industry-specific forecast inputs incorporate FDA notification backlog duration estimates and fermentation capacity expansion announcements.
Underlying measurement precision varies by segment; powder-form hydrocolloids and established pectin grades carry tighter precision than novel enzymatically modified variants awaiting regulatory clearance. Forecasts reflect assumptions regarding FDA review velocity, South Asian agricultural output stability, and beverage reformulation commitment durability. Periodic stress-testing of base assumptions is recommended given regulatory backlog volatility and climate-dependent raw material availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Texture Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Fractionated Fatty Acid Market
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
Europe and MEA Food Phosphate Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
India Food Hydrocolloids Market