
 France Food Hydrocolloids Market | 2026-2036
France Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
France Food Hydrocolloids Market Foresight
Plant-based dairy alternatives is shifting hydrocolloid demand profiles across French food manufacturing. Cargill Inc leverages its European starch and texturant network to supply clean-label pectin solutions for yogurt alternatives. Rousselot anchors the gelatin segment through its specialized collagen extraction capabilities serving premium confectionery and pharmaceutical adjacent food grades. DuPont competes with microbial fermentation-derived xanthan gum positioned for gluten-free bakery applications.
Food hydrocolloids encompass polysaccharide and protein biopolymers that hydrate in aqueous systems to modify viscosity, gelation, and water-binding properties, with molecular weights typically ranging from ten thousand to several million Daltons depending on extraction source and processing severity. Gelatin maintains volume leadership in French meat and confectionery applications due to its unique thermoreversible melt profile and mouthfeel characteristics, while pectin captures accelerated growth from reduced-sugar jam and dairy spread formulations where low-methoxyl grades enable calcium-set gelling without sucrose dependence. Carrageenan occupies stable demand in processed dairy desserts despite ongoing EFSA re-evaluation of refined grades in infant nutrition contexts.
ANSES conducts hazard assessments on food additive petitions including novel hydrocolloid sources, while DGCCRF enforces labeling compliance on origin declarations and additive function categories. The EU Green Deal's Farm to Fork strategy pressures ingredient suppliers to document sustainable sourcing credentials for seaweed-derived alginates and carrageenans. Stakeholders must monitor EFSA scientific opinions on refined carrageenan safety thresholds and adapt formulation portfolios accordingly.
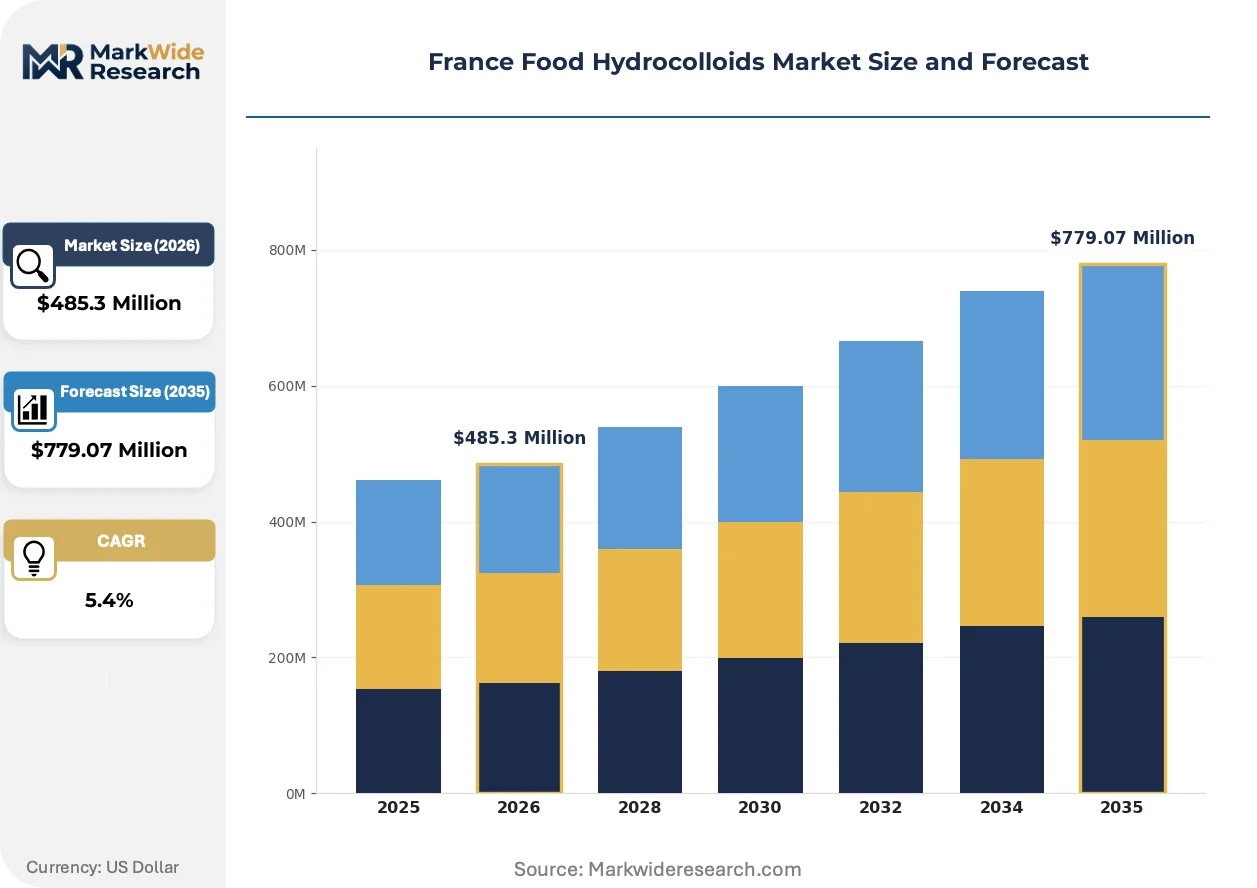
Market Dynamics
Clean-label reformulation mandates from ANSES and DGCCRF are compressing synthetic additive portfolios while pulling natural hydrocolloid volumes upward across French dairy and confectionery manufacturing.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Sustainability documentation requirements for seaweed-derived alginates and carrageenans are rewarding suppliers with certified traceability systems.
- Plant-based dairy alternatives:Yogurt and spread manufacturers are reformulating with low-methoxyl pectin to replicate mouthfeel without gelatin dependence.
- Paris-Ile-de-France cluster concentration:Food manufacturing density around the capital creates localized demand pull for just-in-time hydrocolloid supply.
Market Restraints
- Seaweed supply volatility:Carrageenan and alginate raw material costs fluctuate with Chilean and Indonesian harvest cycles and ocean temperature shifts.
- EFSA refined carrageenan re-evaluation:Pending scientific opinions on infant nutrition safety thresholds are freezing formulation decisions in sensitive applications.
- Gelatin substitution pressure:Religious dietary restrictions and vegan positioning are displacing porcine and bovine collagen derivatives in confectionery.
Strategic Opportunities
- Lyonnaise ingredient processing hub expansion:Secondary logistics nodes outside Paris offer lower operational costs for hydrocolloid blending and distribution.
- Reduced-sugar jam formulations:Calcium-set pectin gelling enables clean-label spreads without sucrose dependence, capturing reformulation budgets.
- Microbial fermentation xanthan:Non-allergen positioning for gluten-free bakery creates differentiation against cereal-derived hydrocolloids.
Industry Challenges
- ANSES hazard assessment timelines:Novel hydrocolloid source approvals face extended toxicological review periods that delay product launches.
- Clean-label certification complexity:Multiple overlapping standards for natural origin claims require redundant documentation across customer audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Food Hydrocolloids Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $779.07 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Pectin, Carrageenan, Xanthan Gum, Guar Gum, Alginate Application: Dairy & Frozen Desserts, Bakery Products, Meat & Poultry, Beverages, Confectionery, Sauces & Dressings End User: Food Manufacturers, Beverage Producers, Confectionery Makers, Catering Services, Foodservice Providers Distribution Channel: Direct Sales, Distributors, Retailers, E-commerce Platforms, Wholesale Suppliers |
| Companies Covered | CP Kelco U.S. Inc, Darling Ingredients Inc, Cargill Inc, DuPont, Ashland, Ingredion Incorporated, Rousselot, Archer Daniels Midland Company, Koninklijke DSM N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Food Hydrocolloids Market Shifts & Advancements
Formulation transparency requirements and precision texture engineering are converging to reshape hydrocolloid specification practices across French food manufacturing.
Enzymatic modification of pectin molecular weight is automating the production of tailored gelling profiles for individual dairy applications. Mid-sized yogurt manufacturers are adopting these precision-grade ingredients to reduce batch-to-batch variability. The technology is automating quality control steps that previously required manual viscosity adjustment during production.
ANSES and DGCCRF are tightening origin declaration requirements for food additives including hydrocolloid function categories on labels. Manufacturers must now document extraction sources and processing locations through the supply chain. Dairy spread and dessert segments are responding by consolidating supplier bases to reduce traceability complexity.
Direct procurement relationships between food manufacturers and hydrocolloid processors are displacing traditional distributor intermediaries in the Paris-Ile-de-France cluster. Large dairy groups are negotiating volume contracts with Rousselot and Cargill's European starch networks for pectin and gelatin supply. This channel compression is most visible in premium confectionery and pharmaceutical-adjacent food grades where batch consistency commands priority.
France Food Hydrocolloids Market Segmentation
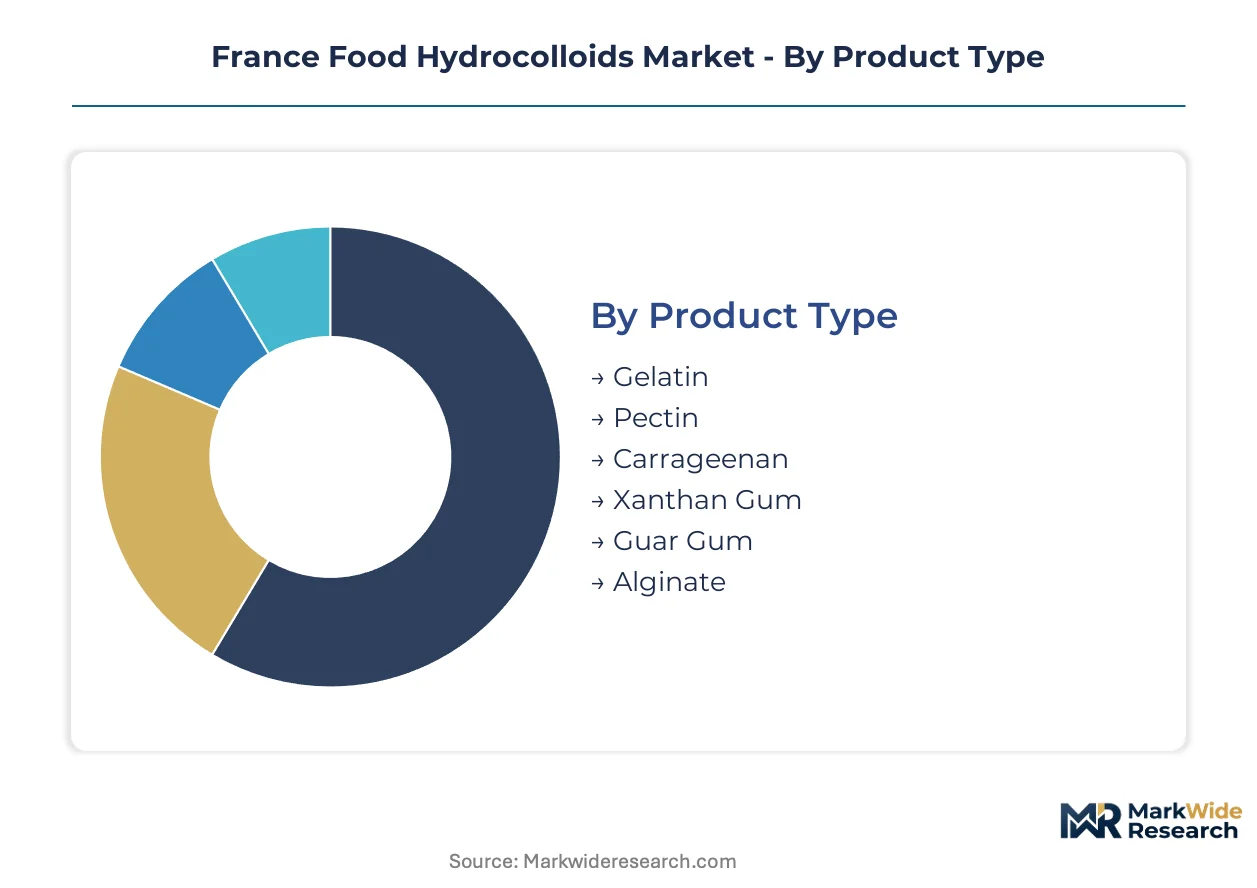
Segmentation in the France Food Hydrocolloids Market reveals how functional properties align with specific manufacturing requirements across dairy, confectionery, and processed food sectors. Specification differences between gelling agents, thickeners, and stabilizers dictate procurement patterns among Paris-Ile-de-France food clusters and Lyon-based processors.
Product Type:
Molecular architecture and extraction source determine hydration kinetics, gel strength, and thermal stability specifications across French formulation laboratories.
- Gelatin:Thermoreversible collagen-derived protein with unique melt-in-mouth profile. Parisian meat processors and premium confectionery houses in the Ile-de-France cluster specify porcine and bovine grades for pâté en croûte and pharmaceutical-adjacent food applications where ANSES traceability requirements apply.
- Pectin:Galacturonic acid polysaccharide from citrus peel and apple pomace extraction. Low-methoxyl grades enable calcium-set gelling in reduced-sugar dairy spreads from Normandy manufacturers responding to DGCCRF clean-label mandates without sucrose dependence.
- Carrageenan:Sulfated galactan from red seaweed harvesting.
- Xanthan Gum:Microbial fermentation exopolysaccharide with pseudoplastic rheology.
- Guar Gum:Galactomannan seed endosperm powder for viscosity building.
- Alginate:Brown seaweed-derived block copolymer for controlled gelation.
Gelatin leads on scale; pectin leads on momentum.
Application:
End-use processing conditions—thermal treatment, pH ranges, and shear rates—filter compatible hydrocolloid categories through formulation compatibility matrices.
- Dairy & Frozen Desserts:Carrageenan-protein complexes stabilize casein micelles in UHT cream and flan desserts. Brittany dairy cooperatives specify kappa-grade carrageenan for thermally processed puddings where EFSA refined-grade evaluations remain pending.
- Bakery Products:Xanthan gum replicates gluten network functionality in free-from bread formulations. Artisan bakers in Lyon and Bordeaux source fermentation-derived grades for celiac-safe croissants and brioche alternatives.
- Meat & Poultry:Gelatin and carrageenan bind moisture in emulsified products.
- Beverages:Pectin and xanthan suspend pulp and stabilize flavor emulsions.
- Confectionery:Gelatin sets gummy textures; pectin enables vegan alternatives.
- Sauces & Dressings:Xanthan and guar gums prevent phase separation.
Dairy & Frozen Desserts leads on scale; Bakery Products leads on momentum.
End User:
Procurement sophistication and volume scale differentiate specification practices across the French food manufacturing value chain.
- Food Manufacturers:Industrial-scale dairy and meat processors with in-house R&D laboratories. Danone and Bel Group facilities around Paris negotiate direct contracts with Rousselot and Cargill for gelatin and pectin specifications tailored to individual production lines.
- Beverage Producers:Juice and soft drink bottlers requiring suspension stability. Languedoc-Roussillon fruit processors specify high-ester pectin for cloud stability in citrus nectars subject to ANSES additive labeling.
- Confectionery Makers:Premium chocolate and candy houses specifying texture profiles.
- Catering Services:Institutional kitchens sourcing pre-hydrated hydrocolloid blends.
- Foodservice Providers:Restaurant chains and centralized kitchens.
Food Manufacturers leads on scale; Beverage Producers leads on momentum.
Distribution Channel:
Logistics configuration and technical service intensity shape channel selection for hydrocolloid procurement in French territory.
- Direct Sales:Volume contracts between hydrocolloid processors and large dairy groups. Rousselot's direct relationships with Paris-Ile-de-France manufacturers bypass distributor margins for pharmaceutical-grade gelatin batches requiring certificate-of-analysis documentation.
- Distributors:Regional ingredient specialists with blending capabilities. Lyon-based intermediaries service mid-sized saucisson and pâté producers in the Rhône-Alpes region with multi-hydrocolloid inventory and technical formulation support.
- Retailers:Cash-and-carry outlets for small-batch artisan producers.
- E-commerce Platforms:Digital procurement for specialty and organic-certified grades.
- Wholesale Suppliers:Bulk handlers of standard-grade guar and xanthan.
Direct Sales leads on scale; E-commerce Platforms leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping hydrocolloid sourcing patterns as French manufacturers weigh compliance costs against proximity advantages. ANSES hazard assessment timelines and DGCCRF labeling mandates create friction that some processors offset through cross-border formulation strategies. The analysis examines five European markets where production concentration and regulatory divergence intersect.
Germany
Bavarian dairy cooperatives and North Rhine-Westphalia meat processors drive gelatin and carrageenan consumption for sausage binding and dessert stabilization. BfR toxicological evaluations run parallel to ANSES assessments, creating dual-track approval pathways for novel hydrocolloid sources. Cologne-based ingredient distributors service mid-sized manufacturers with blended hydrocolloid systems for clean-label reformulation.
Netherlands
Amsterdam-Rotterdam port infrastructure enables cost-efficient import of Chilean seaweed-derived carrageenan and Indonesian alginate for re-export to French processors. NVWA enforcement of EU additive regulations matches DGCCRF stringency on origin declarations. Wageningen University research clusters accelerate enzymatic pectin modification for precision dairy applications.
Spain
Catalonian citrus processing generates apple pomace and peel feedstock for low-methoxyl pectin extraction serving reduced-sugar jam manufacturers. AESAN labeling requirements align with French ANSES standards on additive function disclosure. Valencia-based hydrocolloid blenders supply Andalusian dairy dessert factories with carrageenan-protein stabilization systems.
Italy
Emilia-Romagna parmesan and gelato producers specify pharmaceutical-grade gelatin from Rousselot's European network for texture-critical applications. ISS risk assessments on refined carrageenan inform formulation decisions parallel to EFSA evaluations. Milan ingredient traders consolidate pectin and xanthan inventories for cross-Alpine supply to Lyon processing hubs.
Belgium
Flemish chocolate and confectionery houses source thermoreversible gelatin for premium praline textures and gummy candy applications. FAVV additive oversight mirrors DGCCRF enforcement on clean-label certification complexity. Antwerp chemical distributors maintain strategic stocks of guar and xanthan for just-in-time delivery to Paris-Ile-de-France manufacturing clusters.
France Food Hydrocolloids Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals commanding direct sales channels to large dairy groups while regional blenders service formulation-intensive mid-tiers. The vendor base concentrates around three archetypes: seaweed extractors with coastal processing assets, fermentation-derived biopolymer specialists, and animal collagen processors with pharmaceutical-adjacent certification. Competitive moves center on backward integration into raw material supply and precision-grade portfolio expansion targeting reduced-sugar and plant-based application segments.
Among US-based multinationals, Cargill Inc and CP Kelco U.S. Inc exemplify the integrated archetype with European starch and texturant networks supplying clean-label pectin solutions. DuPont occupies a position within microbial fermentation specialists leveraging non-allergen positioning for gluten-free bakery applications. Rousselot represents the animal-derived collagen segment through specialized extraction capabilities serving premium confectionery grades. These three anchors illustrate how geographic origin and processing specialization stratify competitive positioning across French formulation laboratories.
| Leading Market Players |
|---|
| CP Kelco U.S. Inc |
| Darling Ingredients Inc |
| Cargill Inc |
| DuPont |
| Ashland |
| Ingredion Incorporated |
| Rousselot |
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between pharmaceutical-adjacent gelatin and commodity pectin concentrates pricing power among ANSES-traceable suppliers while compressing margins for undifferentiated hydrocolloid traders. This tier divergence manifests in direct sales channels commanding certificate-of-analysis premiums for Rousselot's collagen derivatives, whereas standard-grade carrageenan flows through distributor intermediaries absorbing seaweed harvest volatility.
Pricing Analysis
Distributor margin layers in the Paris-Ile-de-France cluster absorb 12-18 point spreads between processor gate prices and end-user contract rates. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade gelatin batches from industrial pectin and commodity guar powder. Pricing pressure stems from Chilean seaweed supply instability elevating carrageenan raw material costs. Mid-sized Lyon processors exhibit highest price sensitivity, negotiating volume rebates against just-in-time delivery premiums.
Supply Chain Analysis
Freight cost differentials between Rotterdam port entry and overland trucking to Lyon processing hubs favor Dutch re-export consolidation over direct Indonesian alginate shipments. Raw material supply concentrates in Chile, Indonesia, and Brazil for seaweed extracts, with citrus peel feedstock drawing from Spanish and Italian processing. Single-source vulnerability runs through the Chilean carrageenan harvest cycle exposed to El Niño temperature shifts. Distribution runs through direct sales for large dairy groups and regional distributors for mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's hydrocolloid market functions as a geographic-arbitrage play where ANSES hazard assessment timelines exceed BfR approval speeds in Germany, creating formulation migration incentives for novel ingredient launches.
For Market Incumbents: Cement backward integration into citrus peel and apple pomace supply through Spanish and Italian orchard contracts to secure low-methoxyl pectin feedstock against Normandy dairy spread reformulation demand. Lock in pharmaceutical-grade gelatin capacity through ANSES-certified traceability systems before EFSA refined carrageenan opinions displace infant nutrition applications. Channel control through direct sales relationships with Danone and Bel Group facilities protects margin position against distributor compression.
For New Entrants and Emerging Players: The premium-economy price gap in microbial fermentation xanthan creates entry space for gluten-free bakery specialists positioning non-allergen alternatives against cereal-derived hydrocolloids. Target Lyon-based artisan bakers and Bordeaux croissant manufacturers with technical formulation support and smaller batch flexibility. A go-to-market angle emphasizing enzymatic precision-grade pectin with automated viscosity control addresses mid-sized yogurt manufacturer pain points.
For Investors and Strategic Acquirers: Consolidation pressure builds where clean-label certification complexity requires redundant documentation systems that scale inefficiently across fragmented regional blenders. The five-to-ten year viability window favors acquisition targets with captive seaweed processing assets in Indonesia or Chile and established ANSES compliance protocols. Watch EFSA refined carrageenan safety threshold rulings as the signal for portfolio reallocation between seaweed-derived and fermentation-derived hydrocolloid exposures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Harvesting | Captive supply of Chilean and Indonesian carrageenan raw material insulates against ocean temperature volatility. |
| Enzymatic Pectin Modification Capacity | Precision-grade production automation reduces batch-to-batch variability for Normandy dairy spread manufacturers. |
| ANSES Traceability Certification Investment | Pharmaceutical-grade gelatin batches command direct sales premiums from Paris-Ile-de-France meat processors. |
| Lyonnaise Distribution Hub Expansion | Secondary logistics nodes lower operational costs for hydrocolloid blending outside capital-region congestion. |
| Microbial Fermentation Xanthan Scale-Up | Non-allergen positioning captures gluten-free bakery demand from Lyon and Bordeaux artisan producers. |
Research Methodology
Bottom-up dairy and confectionery application modeling reconciled against top-down seaweed and starch derivative supply tracking forms the analytical core of this study. Primary interviews with hydrocolloid procurement managers at Danone and Bel Group, technical R&D directors at Lyon-based ingredient blenders, distribution channel partners in the Paris-Ile-de-France cluster, and ANSES regulatory affairs specialists combined with secondary validation from EU customs trade data, EFSA scientific opinion filings, DGCCRF enforcement bulletins, and SEC 10-K disclosures from listed multinationals. Triangulation between demand-side volume specifications and supply-side production capacity ensures forecast coherence.
Input-output matrices map hydrocolloid grade tier against end-use application intensity across dairy desserts, reduced-sugar spreads, gluten-free bakery, and premium confectionery segments. Segmentation dimensions include molecular architecture category, extraction source origin, certification grade tier, and regional manufacturing hub concentration. CAGRs derive from weighted average of application growth rates and substitution elasticity coefficients between hydrocolloid categories. Forecast inputs incorporate EFSA regulatory timeline scenarios and EU Green Deal Farm to Fork sustainability documentation requirements.
The model assumes a particular technology adoption path; alternative pathways for enzymatic pectin modification automation would alter the outlook if mid-sized manufacturers accelerate precision-grade ingredient adoption beyond baseline assumptions. Forecasts reflect documented assumptions about ANSES approval timelines and seaweed harvest stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Modified Starch Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
India Food Hydrocolloids Market
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Food Premix Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
Germany Food Hydrocolloids Market