
 Canada Food Hydrocolloids Market | 2026-2036
Canada Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Food Hydrocolloids Market Outlook
Clean-label hydrocolloid extraction and fermentation-based bioprocessing is reshaping how Canadian food manufacturers source texturizing ingredients. Cargill Incorporated leverages its North American agricultural supply chain to secure consistent raw material flows for hydrocolloid derivatives. Kerry Group plc differentiates through integrated taste and nutrition platforms that combine hydrocolloid functionality with flavor systems. CP Kelco anchors its position with specialty gellan and xanthan production tailored to precision fermentation needs.
Food hydrocolloids are high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to form viscous solutions or gels, typically functioning at concentrations between 0.1% and 2.0% by weight to control texture, stability, and water retention in processed foods. Xanthan gum dominates industrial volumes due to its shear-thinning rheology and compatibility across pH ranges, while gellan gum captures premium positioning in plant-based dairy alternatives where brittle gel textures matter. Carrageenan retains substantial share in conventional dairy applications despite ongoing clean-label substitution pressures.
Health Canada enforces food additive approvals under Division 16 of the Food and Drug Regulations, requiring pre-market safety assessments that directly determine which hydrocolloid grades achieve commercial eligibility. The Canadian Food Inspection Agency monitors label claims and ingredient declarations, pushing manufacturers toward transparent sourcing documentation. The Safe Food for Canadians Regulations impose preventive control requirements on imported hydrocolloid supplies, elevating compliance costs for non-domestic suppliers. Stakeholders must track evolving positions on carrageenan and modified cellulose within Health Canada's cyclical priority substance reviews.
Market Dynamics
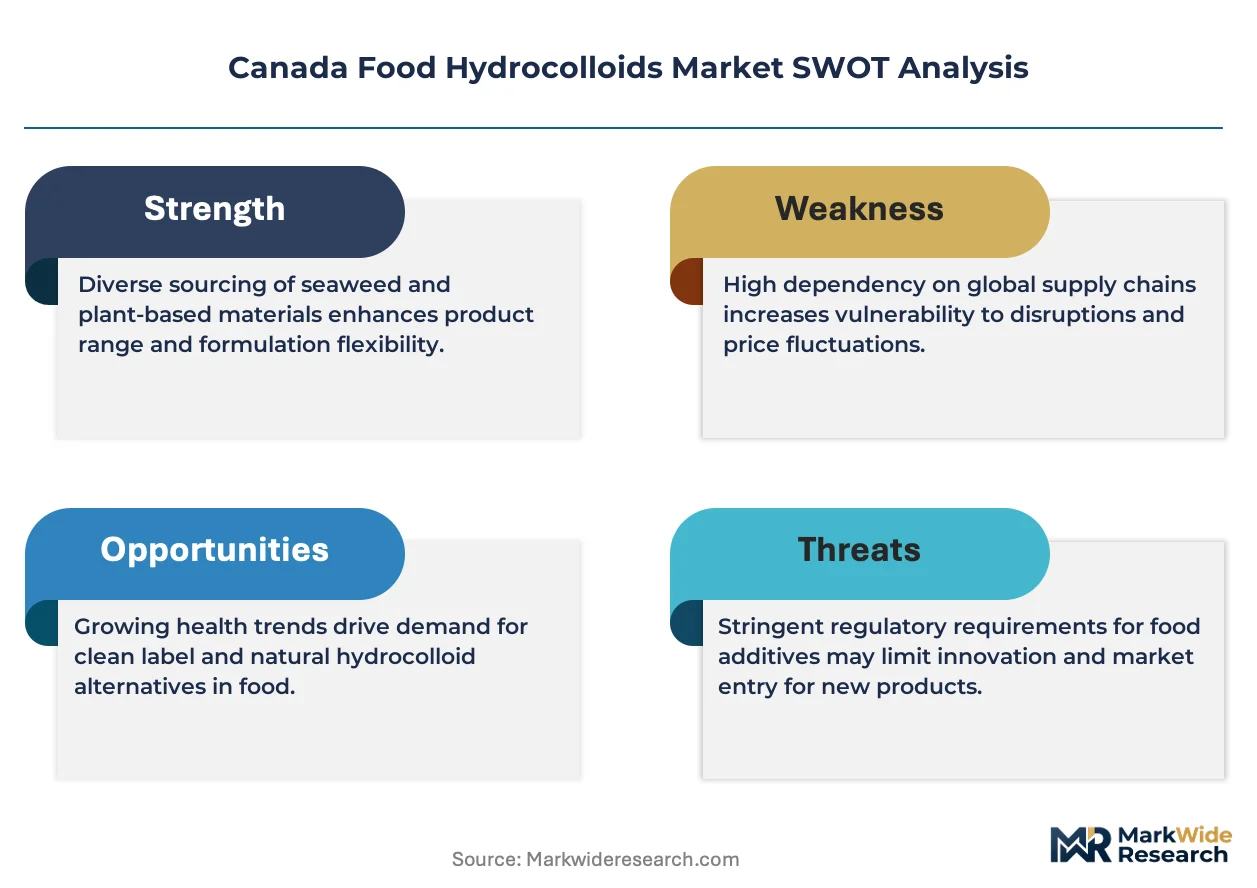
Clean-label extraction technologies and fermentation-based bioprocessing are compressing supply chains while Health Canada's Division 16 safety assessments filter which hydrocolloid grades achieve commercial eligibility. This dual pressure—technological substitution on the supply side and regulatory gatekeeping on the compliance side—determines competitive positioning.
Growth Catalysts
- Precision fermentation platforms:Canadian biotechnology firms deploy cell-culture systems to produce gellan and xanthan variants with consistent molecular weights, bypassing agricultural weather volatility.
- Ontario's food manufacturing corridor:Dense clustering of dairy processors around Toronto and Hamilton generates concentrated demand for texturizing and stabilizing hydrocolloids.
- Safe Food for Canadians Regulations:Preventive control mandates on imports elevate compliance costs for foreign suppliers, creating protected domestic market space.
Market Restraints
- Guar gum price volatility:Dependence on Indian and Pakistani monsoon-dependent harvests creates input cost instability for Canadian formulators.
- Carrageenan substitution pressure:Clean-label reformulation campaigns in plant-based dairy alternatives displace traditional seaweed-derived thickeners.
- Health Canada priority substance reviews:Cyclical re-evaluations of modified cellulose grades introduce regulatory uncertainty and reformulation risk.
Strategic Opportunities
- Alberta pulse protein integration:Pea and lentil fractionation byproducts offer regional feedstock for novel hydrocolloid development.
- Quebec precision fermentation scale-up:Provincial biomanufacturing incentives support domestic gellan gum production for fermentation media applications.
- Direct-to-processor digital platforms:E-procurement channels bypass traditional distributor markups for mid-size Ontario dairy cooperatives.
Industry Challenges
- Fermentation scale-up expertise:Shortage of bioprocess engineers with food-grade GMP experience constrains domestic production expansion.
- Dual certification timelines:Simultaneous Health Canada food additive approval and Canadian Food Inspection Agency facility registration extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Food Hydrocolloids Market |
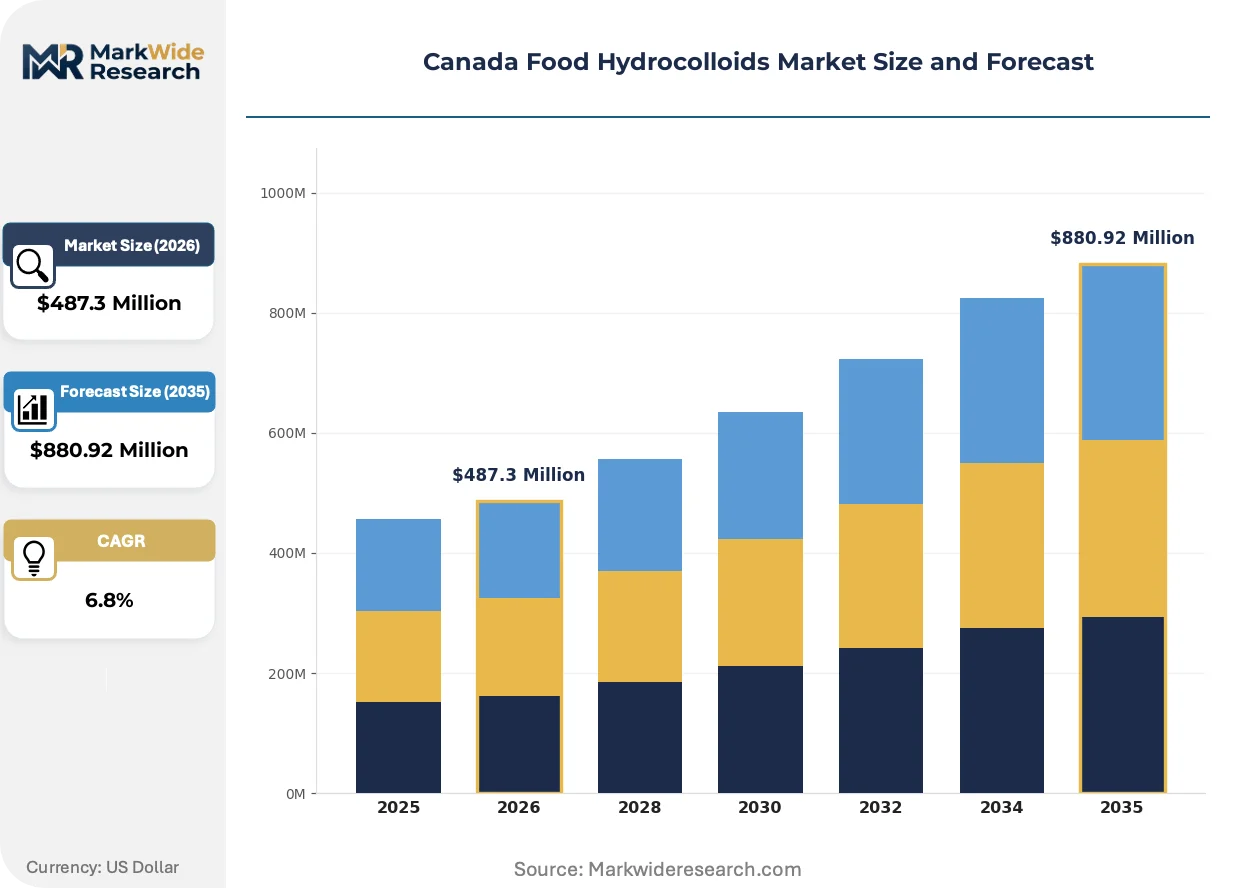
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gellan Gum, Agar, Xanthan Gum, Carrageenan Application: Dairy Products, Bakery, Beverages, Sauces Form: Powder, Liquid, Sheet, Gel End User: Food Manufacturers, Restaurants, Retailers, Bakeries |
| Companies Covered | Cargill Incorporated, DuPont de Nemours, Inc., Ingredion Incorporated, CP Kelco, Koninklijke DSM N.V., Tate & Lyle PLC, Archer Daniels Midland Company, Kerry Group plc, Ashland Global Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Food Hydrocolloids Market Strategic Shifts
Bioprocessing advances and regulatory transparency mandates are reconfiguring how Canadian manufacturers source, formulate, and document hydrocolloid ingredients. Three developments define this transformation.
Enzymatic hydrocolloid modification is rendering obsolete traditional chemical derivatization for texture control. Canadian plant-based dairy processors adopt enzymatically treated starches and pectins to achieve clean-label gelation without E-number declarations. This shift compresses the addressable market for chemically modified cellulose derivatives.
Health Canada's cyclical priority substance reviews are tightening documentation requirements for carrageenan and modified cellulose grades. The Canadian Food Inspection Agency now demands transparent supply chain mapping for imported seaweed extracts. Dairy alternative manufacturers respond by accelerating reformulation toward fermentation-derived gellan systems.
Consolidated procurement by Ontario's dairy processor cooperatives is compressing supplier margins while demanding technical service integration. Mid-size hydrocolloid distributors lose share to direct manufacturer relationships with major Toronto-area plants. This concentration is most visible in the Greek yogurt and plant-based beverage segments.
Canada Food Hydrocolloids Market Segmentation
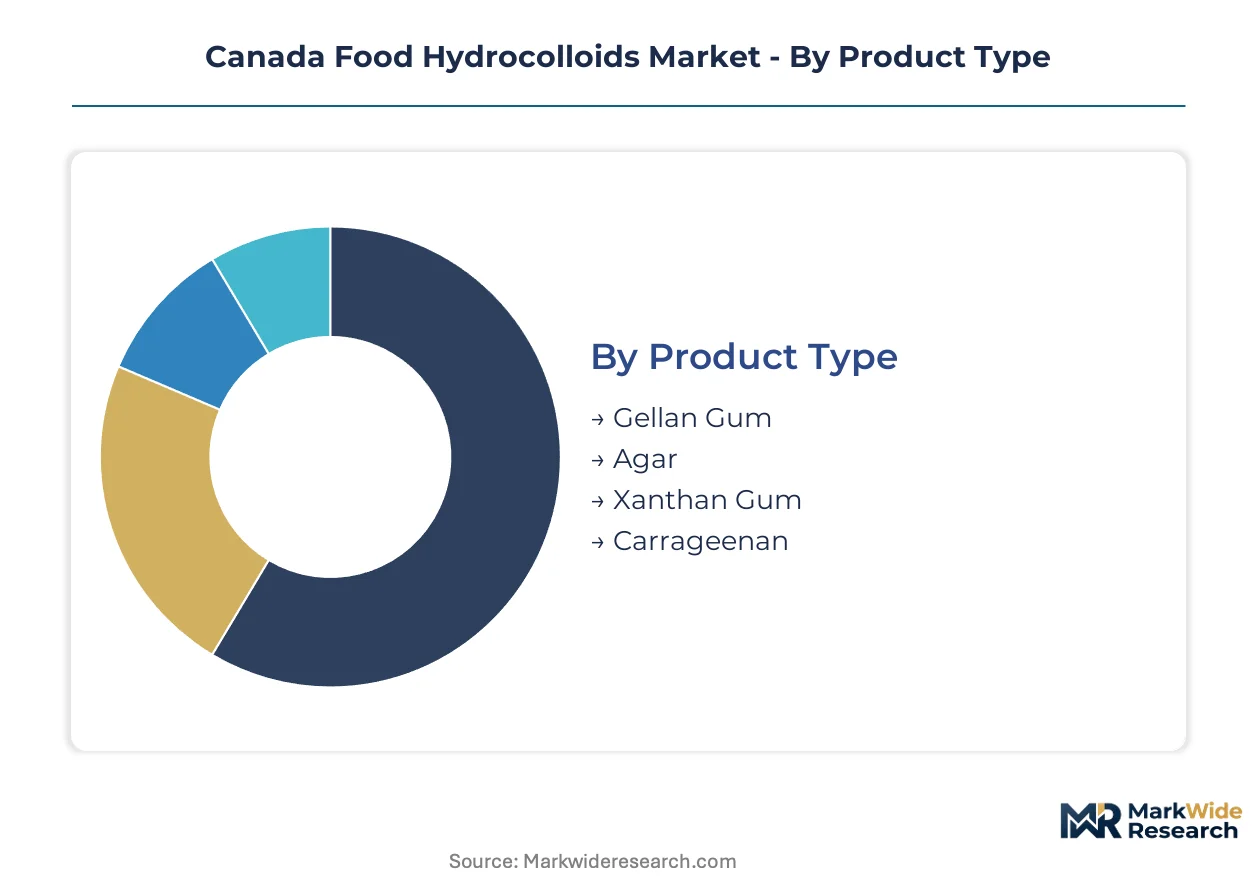
Canadian food hydrocolloid procurement varies sharply by functional requirement and end-use specification. Segmentation reveals how texture engineering demands diverge across dairy processing, plant-based formulation, and foodservice channels.
Product Type:
Industrial formulators select hydrocolloids based on rheological performance across shear conditions, pH stability, and clean-label positioning.
- Xanthan Gum:An extracellular polysaccharide produced by Xanthomonas campestris fermentation exhibiting pronounced shear-thinning behavior and salt tolerance. Ontario's Greek yogurt processors specify high-viscosity grades for suspension stability in high-protein matrices. Health Canada's Division 16 listing under food additives ensures broad formulation eligibility.
- Gellan Gum:A linear anionic heteropolysaccharide synthesized via Sphingomonas elodea fermentation, available in high-acyl and low-acyl variants for brittle or elastic gel textures. Quebec's precision fermentation facilities target domestic production to supply plant-based dairy alternatives seeking transparent supply chains. The clean-label profile accelerates displacement of chemically modified starches.
- Carrageenan:Sulfated galactans extracted from red seaweed (Chondrus crispus, Eucheuma species) delivering strong protein reactivity for dairy stabilization. Health Canada's priority substance reviews introduce reformulation uncertainty for conventional ice cream applications.
- Agar:A gelling polysaccharide from Gelidium and Gracilaria seaweeds with high gel strength and thermoreversible properties. Specialty confectionery and bakery applications in Vancouver and Montreal specify agar for vegan gelation requirements.
Established volume favors xanthan gum; emerging adoption favors gellan gum.
Application:
Cost tier stratification separates commodity dairy applications from premium plant-based innovation budgets.
- Dairy Products:Yogurt, ice cream, and processed cheese formulations leverage hydrocolloids for water binding, syneresis control, and mouthfeel engineering. The concentration of processors around Toronto and Hamilton generates concentrated demand for carrageenan and modified cellulose systems.
- Beverages:Plant-based milk alternatives and functional drinks require suspension stability and emulsion integrity. Gellan gum captures share in oat and pea protein beverages where visual clarity and clean labels command formulation priority.
- Bakery:Hydrocolloids extend shelf life through moisture retention and retard staling in industrial bread and cake production. Guar gum and xanthan blends dominate gluten-free formulations where structure replacement is critical.
- Sauces:Salad dressings, condiments, and prepared sauces utilize xanthan for pour control and freeze-thaw stability. Mid-size Ontario co-packers specify standardized viscosity grades for consistent processing line performance.
Margin compression concentrates in dairy; premium pricing persists in beverages.
Form:
Supply chain configuration determines availability and handling economics across Canadian distribution networks.
- Powder:Spray-dried or drum-dried hydrocolloid concentrates dominate industrial procurement due to extended shelf stability and freight efficiency. Bulk rail and truck deliveries service major Toronto-area dairy plants with pneumatic conveying systems.
- Liquid:Pre-hydrated suspensions reduce dust exposure and accelerate batch processing for mid-size manufacturers lacking high-shear dispersion equipment. Higher water content elevates transportation costs from US and European suppliers.
- Sheet:Agar and gelatin sheet formats serve artisan bakery and restaurant segments requiring precise portion control. Limited Canadian domestic production necessitates import reliance on Japanese and Korean suppliers.
- Gel:Pre-formed hydrocolloid gels target foodservice and ready-meal applications where immediate functionality eliminates hydration time. Quebec's prepared food manufacturers specify gel formats for sauce bases and dessert components.
Volume scale favors powder; operational convenience favors liquid.
End User:
Customer type dictates technical service intensity and procurement channel structure.
- Food Manufacturers:Large-scale processors in Ontario's manufacturing corridor negotiate direct supply agreements with hydrocolloid producers. Technical collaboration on formulation optimization replaces transactional distributor relationships.
- Restaurants:Commercial kitchens and chain operators source through broadline distributors with limited technical support. Molecular gastronomy applications in Toronto and Vancouver restaurants drive specialty gellan and agar demand.
- Retailers:Private-label food brands and ingredient retailers package hydrocolloids for home bakers and small commercial users. E-commerce penetration accelerates in specialty and allergen-free segments.
- Bakeries:Independent and franchise bakery operations require consistent hydration performance across variable water quality conditions. Regional distributor networks service this fragmented channel with standardized product grades.
Procurement consolidation favors food manufacturers; service fragmentation characterizes restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's food hydrocolloids trade runs a structural deficit in specialty fermentation-derived grades while maintaining surplus positions in commodity xanthan and guar blends. Import dependence concentrates in gellan gum and premium seaweed extracts sourced from Asian and European suppliers.
Ontario
Toronto and Hamilton anchor North America's densest dairy processing corridor, driving concentrated demand for carrageenan and modified cellulose stabilizers. Health Canada's Division 16 food additive approvals filter which hydrocolloid grades achieve commercial eligibility for yogurt and ice cream formulations. The Golden Horseshoe manufacturing zone hosts direct supply agreements between major processors and hydrocolloid distributors.
Quebec
Provincial biomanufacturing incentives support precision fermentation scale-up for domestic gellan gum production targeting plant-based dairy alternatives. The country's national food regulator maintains cyclical priority substance reviews that introduce reformulation uncertainty for conventional thickeners. Montreal's food technology cluster attracts fermentation startups seeking alternative protein texturizing solutions.
Alberta
Pulse protein fractionation byproducts from pea and lentil processing offer regional feedstock potential for novel hydrocolloid development. The Safe Food for Canadians Regulations impose preventive control requirements on imported specialty grades, elevating compliance costs for foreign suppliers. Calgary's ingredient distribution hubs service Prairie food manufacturers with bulk powder logistics.
British Columbia
Vancouver's plant-based food innovation ecosystem drives specialty agar and gellan demand for vegan confectionery and bakery applications. The Canadian Food Inspection Agency monitors label claims and ingredient declarations, pushing manufacturers toward transparent sourcing documentation. Regional seafood processors experiment with seaweed-derived hydrocolloid extraction from coastal biomass.
Canada Food Hydrocolloids Market Competitive Environment
On the supply side, the industry is bifurcated between agricultural commodity traders and fermentation technology specialists. Tier-one integrated ingredient conglomerates negotiate direct supply agreements with Ontario dairy processors, bypassing traditional distribution channels. Three archetypes dominate: North American agricultural supply chain operators, European taste-and-nutrition integrators, and precision fermentation pure-plays. Competitive positioning hinges on backward integration into raw material sourcing and technical service bundling with formulation support.
Within the integrated conglomerate tier, Cargill Incorporated and Archer Daniels Midland Company represent agricultural supply chain anchoring, securing consistent raw material flows through North American commodity networks. Kerry Group plc occupies a position combining hydrocolloid functionality with flavor system integration. CP Kelco exemplifies the fermentation specialist archetype, with gellan and xanthan production capabilities tailored to precision fermentation media requirements. These three entities illustrate how competitive positioning stratifies across supply chain control, technical integration depth, and bioprocessing specialization.
| Leading Market Players |
|---|
| Cargill Incorporated |
| DuPont de Nemours, Inc. |
| Ingredion Incorporated |
| CP Kelco |
| Koninklijke DSM N.V. |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Kerry Group plc |
| Ashland Global Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
The Great Lakes-St. Lawrence Seaway corridor's freight cost dynamics compress margins for imported fermentation-derived grades while amplifying price differentiation between domestic precision fermentation output and Asian-sourced seaweed extracts. Supply concentration in Ontario's dairy processing corridor grants volume buyers leverage over distributors, forcing tiered pricing structures that separate long-term contract tiers from spot procurement premiums.
Pricing Analysis
Extraction-technology pricing gaps separate enzymatically modified hydrocolloids commanding formulation premiums from chemically derivatized grades facing commoditization pressure. Three-tier pricing structure across premium fermentation-derived, standard agricultural-extracted, and economy commodity-blend levels stratifies the Canadian market. Price differentiation rests on Health Canada Division 16 certification status and clean-label positioning for plant-based dairy alternatives. Cost compression in standard carrageenan and modified cellulose tiers is intensifying because Ontario dairy cooperatives consolidate procurement volumes. Mid-size Ontario co-packers exhibit highest price sensitivity due to limited formulation budgets, while precision fermentation startups show lowest sensitivity for gellan gum sourcing.
Supply Chain Analysis
Contract manufacturing concentration among Quebec precision fermentation facilities and Ontario toll-processing plants determines domestic specialty grade availability. Geographic supply concentration centers on China for xanthan gum fermentation capacity, India and Pakistan for guar gum agricultural output, and Indonesia and the Philippines for carrageenan seaweed extraction. Raw material dependencies draw from North American corn and soybean feedstocks for fermentation substrates, Asian red seaweed biomass for carrageenan, and Indian subcontinent guar bean harvests. Single-source vulnerability in Indian monsoon-dependent guar gum harvests exposes Canadian formulators to input cost spikes. Distribution runs through Toronto-area ingredient distributors serving the Golden Horseshoe manufacturing zone with bulk pneumatic delivery systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's food hydrocolloids sector approaches a platform-economics inflection where precision fermentation infrastructure interoperability will determine which suppliers capture formulation relationships with consolidated dairy processors.
For Market Incumbents: Pre-empt displacement by enzymatic modification technologies through backward integration into Quebec fermentation capacity and exclusive supply agreements with Ontario dairy cooperatives. Lock in Health Canada Division 16 certification pipelines ahead of priority substance reviews on modified cellulose grades. Channel control through direct technical service teams at Toronto-area plants replaces distributor relationships as the defensive priority. For New Entrants and Emerging Players: Alberta pulse protein fractionation byproducts represent the most penetrable entry point for novel hydrocolloid development leveraging regional agricultural waste streams. Quebec precision fermentation scale-up incentives offer subsidized capacity access for domestic gellan gum production targeting plant-based dairy alternatives. Direct-to-processor digital procurement platforms bypass traditional distributor markups for mid-size Ontario dairy cooperatives lacking technical formulation support. For Investors and Strategic Acquirers: Fermentation technology specialists with Health Canada-approved food additive portfolios and existing Ontario customer relationships represent the highest-conviction acquisition archetype for exposure to clean-label substitution trends. Long-term viability across the analysis window hinges on regulatory navigation capabilities and bioprocess engineering talent retention. Watch for Health Canada priority substance review announcements on carrageenan and modified cellulose as inflection indicators for reformulation-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Quebec provincial incentives support domestic gellan gum production for plant-based dairy alternatives. |
| Backward Integration into Feedstocks | Alberta pulse protein byproducts offer regional raw material security for novel hydrocolloid development. |
| Direct-to-Processor Digital Platform | E-procurement channels bypass distributor markups for mid-size Ontario dairy cooperatives. |
| Health Canada Certification Investment | Division 16 pre-market approval accelerates commercial eligibility for fermentation-derived grades. |
| Technical Service Integration | On-site formulation support locks in supply agreements with Toronto-area Greek yogurt processors. |
Study Parameters
A spread of perspectives from hydrocolloid procurement managers at Ontario dairy processors, Quebec fermentation facility operators, Alberta pulse protein fractionation engineers, and Health Canada regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with formulation chemists at major food manufacturers combined with secondary validation from Canadian Food Inspection Agency enforcement bulletins, Health Canada Division 16 food additive listings, and Agriculture and Agri-Food Canada trade statistics. Bottom-up volume estimates from individual processor consumption patterns triangulated against top-down market sizing from customs import data and industry association membership records.
Demand-supply balance framing anchored the forecast framework across the analysis window, modeling consumption growth against domestic fermentation capacity expansion and import substitution potential. Segmentation dimensions included hydrocolloid product type, application category, form factor, and end-user procurement channel. CAGRs derived from fitted growth curves applied to base-year consumption estimates, adjusted for regulatory approval timelines and technology substitution rates. Industry-specific inputs incorporated Health Canada priority substance review schedules and Quebec provincial biomanufacturing incentive program uptake.
Macroeconomic conditions sit as an overlay; deviation in Canadian dollar exchange rates against Asian currencies, Prairie agricultural commodity prices, and ocean freight indices would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability, fermentation scale-up success rates, and clean-label substitution velocity. Quarterly review of Health Canada additive approval announcements, Ontario dairy processor procurement consolidation activity, and Quebec fermentation facility commissioning timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Mexico Food Hydrocolloids Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Polyunsaturated Fatty Acids Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Argentina Food Hydrocolloids Market
Food Components and Additives
Food Texture Market