
 USA Food Premix Market | 2026-2036
USA Food Premix Market Size, Share, and Industry Trends Forecast 2026-2036
USA Food Premix Market Analytics
Domestic premix manufacturing is restructuring around specialized nutrient complexes as large-scale producers adapt to tighter label claim verification. Cargill Incorporated leverages its grain origination network to secure feedstock for vitamin precursors. DSM sustains R&D intensity in lipid-soluble nutrient stabilization. Balchem Corporation anchors western production with chelated mineral capacity.
Food premix denotes industrially blended concentrates of vitamins, minerals, amino acids, or enzymes formulated to precise potency specifications for downstream fortification. Manufacturers typically employ tumble blending or fluid bed agglomeration to achieve homogeneity coefficients below five percent, ensuring uniform micronutrient distribution in finished foods. The vitamins segment leads volume due to mandatory flour fortification programs, while sports nutrition applications within functional foods represent the fastest-expanding margin pool. Dairy end-use commands premium positioning through probiotic-vitamin combinations.
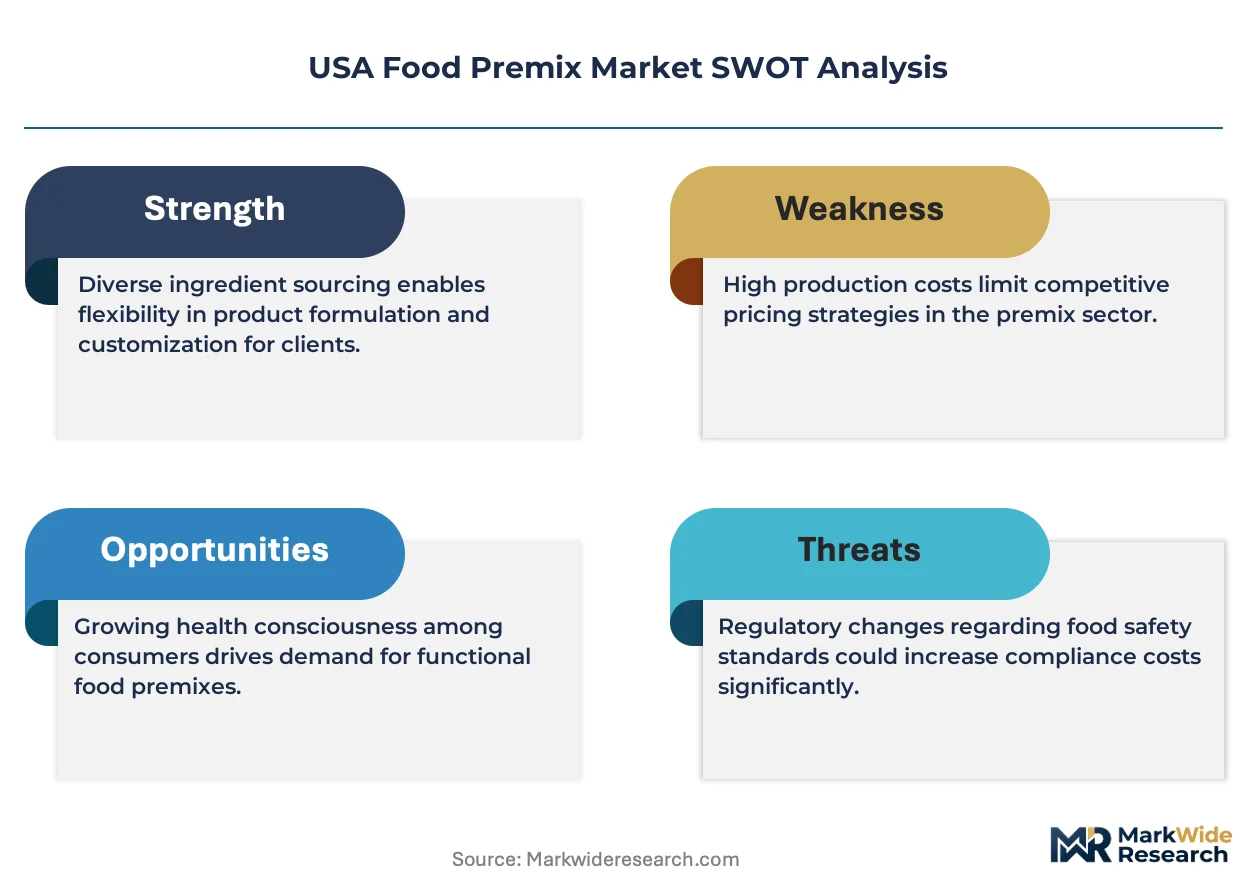
FDA nutrition labeling rules, USDA organic certification standards, and FSMA preventive controls collectively govern premix composition, supplier verification, and facility sanitation requirements. These frameworks elevate compliance costs but simultaneously consolidate demand toward certified producers with documented supply chain controls. Stakeholders must monitor emerging micronutrient reference daily intake revisions and their cascading effects on formulation thresholds.
Market Dynamics
Domestic premix manufacturing is restructuring around specialized nutrient complexes as large-scale producers adapt to tighter label claim verification. FDA's updated Nutrition Facts labeling requirements are reshaping fortification specifications nationwide.
Growth Catalysts
- Flour fortification mandates:Mandatory vitamin enrichment programs in wheat and maize processing sustain baseline volume demand across bread, pasta, and cereal manufacturers.
- Sports nutrition expansion:Fitness-focused consumers are driving premix adoption in protein powders, energy bars, and recovery beverages with targeted amino acid profiles.
- California functional food corridor:Concentrated manufacturing clusters in the San Joaquin Valley accelerate formulation innovation and shorten development cycles for fortified dairy and plant-based alternatives.
Market Restraints
- Vitamin precursor feedstock volatility:Corn and soybean derivative prices fluctuate with commodity cycles, compressing margins for lipid-soluble vitamin production.
- Single-source mineral dependencies:Chelated zinc and selenium concentrates rely heavily on Utah and Nevada mining operations, creating geographic concentration risk.
- FSMA preventive control burdens:Extensive documentation requirements for supplier verification and facility sanitation elevate compliance costs disproportionately for mid-scale blenders.
Strategic Opportunities
- Texas dairy processing expansion:Underpenetrated fortification in yogurt and kefir production offers white space for probiotic-vitamin combination premixes.
- USDA organic certification tailwind:Premium positioning for certified organic premixes aligns with natural channel growth and clean-label consumer preferences.
- Precision fermentation convergence:Biosynthetic vitamin production methods are converging with traditional chemical synthesis to reshape cost structures for B-complex nutrients.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in lipid-soluble nutrient stabilization and chelation chemistry remains concentrated among aging technical workforces in Midwest manufacturing hubs.
- Legacy ERP integration friction:Batch record systems for FSMA traceability requirements conflict with existing inventory management platforms, forcing costly middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Food Premix Market |
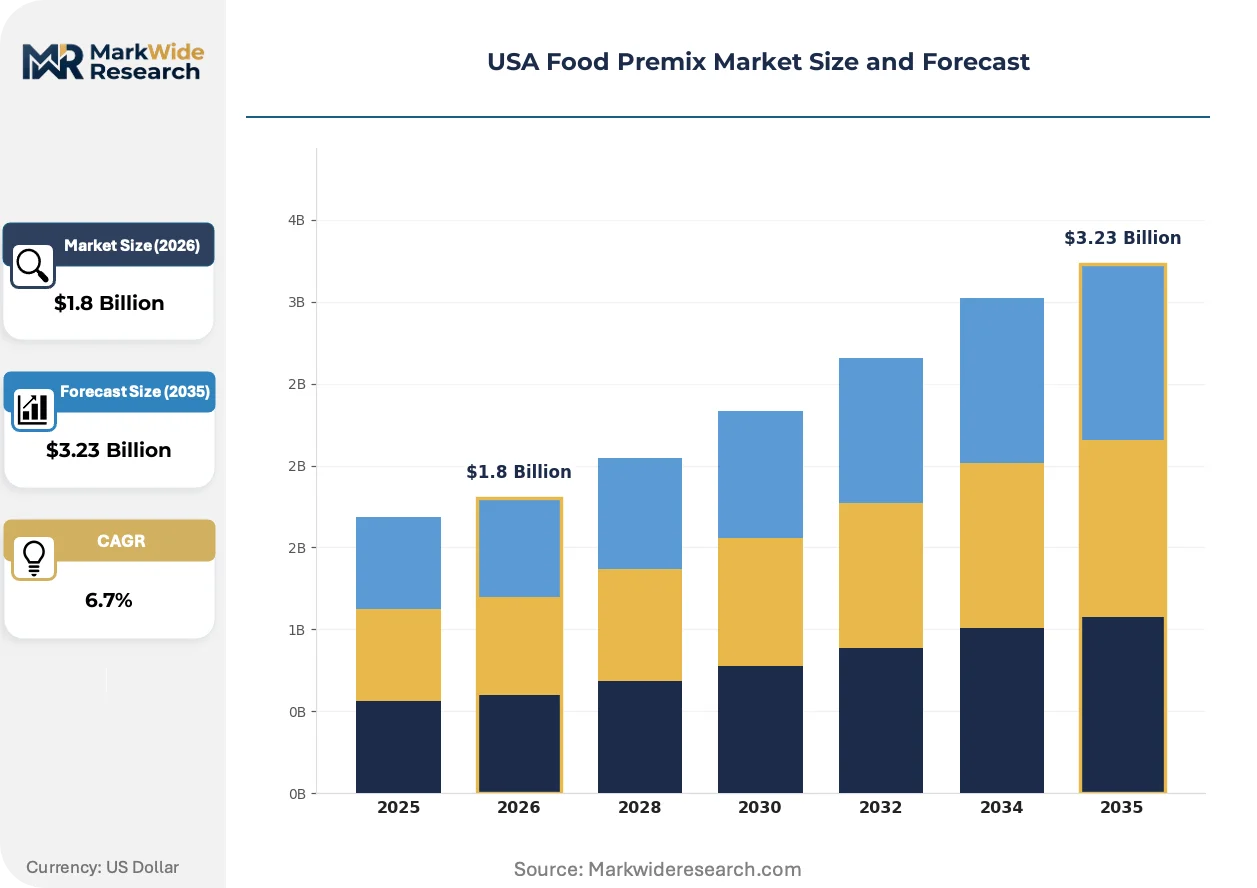
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Enzymes End User: Bakery, Beverages, Confectionery, Dairy Application: Nutritional Supplements, Functional Foods, Sports Nutrition, Baked Goods Distribution Channel: Online Retail, Supermarkets, Health Stores, Distributors |
| Companies Covered | BASF SE, Glanbia plc, Cargill Incorporated, SternVitamin GmbH & Co. KG, Prinova Group LLC, Archer Daniels Midland Company, Corbion N.V., Balchem Corporation, DSM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Food Premix Market Evolving Landscape
Active reshaping in the USA food premix sector centers on manufacturing technology upgrades, evolving federal compliance frameworks, and shifting procurement patterns among contract manufacturers. These forces are compressing development timelines while elevating technical barriers to entry.
Microencapsulation technology is consolidating control over nutrient bioavailability and shelf stability. Dairy processors and beverage manufacturers are adopting fluid-bed coating systems at accelerated rates to protect heat-sensitive vitamins during pasteurization. This consolidation is compressing the supplier base toward blenders with in-house particle engineering capabilities.
FDA's updated Nutrition Facts labeling rules are mandating revised daily value percentages for vitamin D and potassium. Premix formulators must recalculate potency specifications and adjust master batch records to maintain label claim accuracy. Sports nutrition and functional food segments are responding fastest, with California and Colorado manufacturers leading reformulation cycles.
Direct sourcing from certified premix specialists is displacing traditional distributor intermediaries among mid-scale bakery and snack producers. Contract manufacturers are consolidating supplier lists to reduce audit burdens under FSMA preventive controls. This pattern is most visible in the Pacific Northwest, where co-manufacturing networks prioritize documented supply chain controls over price competition.
USA Food Premix Market Segmentation
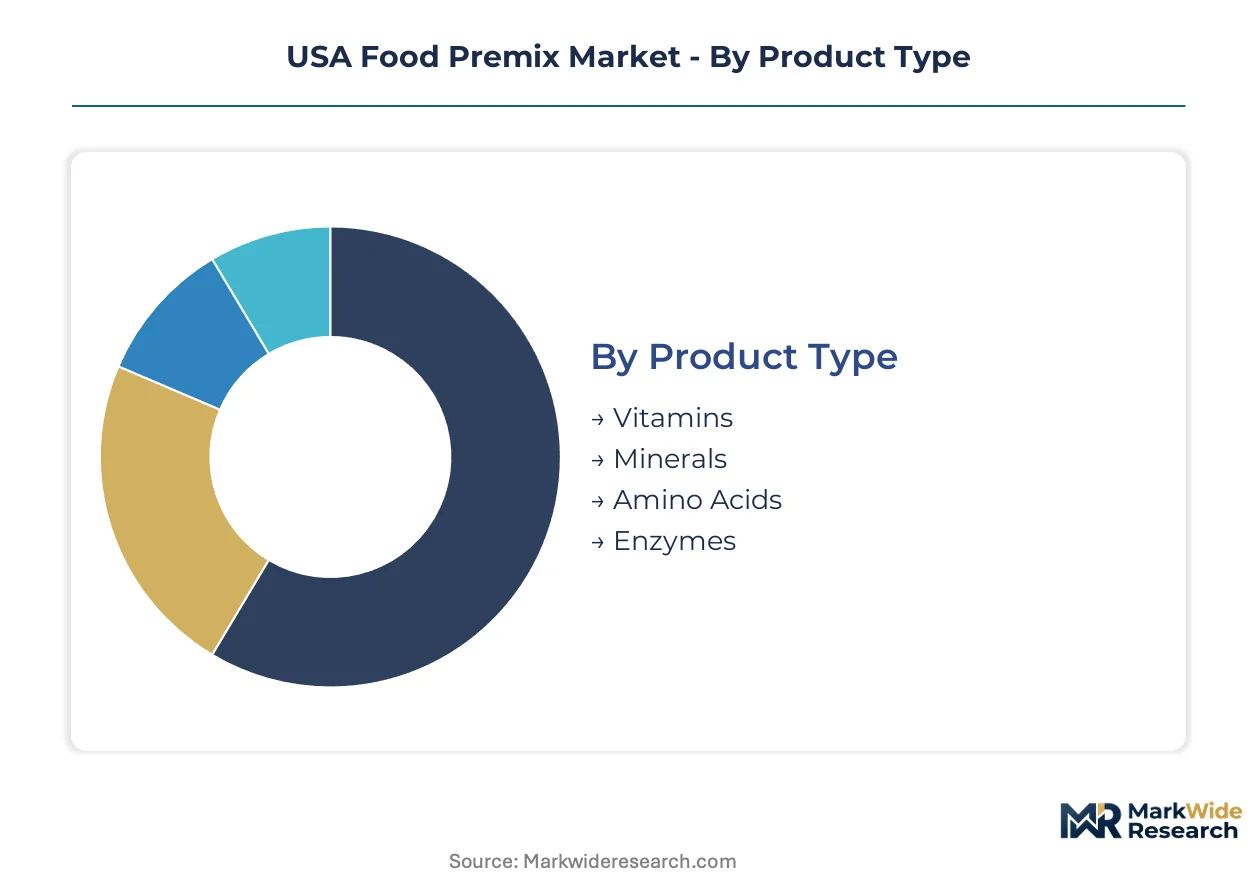
Food premix segmentation reveals distinct capital requirements and margin profiles across nutrient categories. Manufacturers configure production lines around specific blending technologies, creating natural specialization barriers that shape competitive positioning.
Product Type:
Vitamins demand the heaviest upfront investment due to precursor synthesis infrastructure and stabilization R&D. Fluid-bed agglomeration systems for lipid-soluble forms require seven-figure capital commitments before commercial scale.
- Vitamins:Concentrates of fat-soluble (A, D, E, K) and water-soluble (B-complex, C) compounds formulated to precise IU specifications. Mandatory flour fortification programs in Kansas and North Dakota wheat processing sustain baseline volume, though vitamin D potency recalculations under revised FDA labeling rules are forcing master batch record updates.
- Minerals:Chelated and inorganic forms including zinc, selenium, iron, and calcium with defined bioavailability coefficients. Utah and Nevada mining operations supply concentrated feedstock, creating geographic concentration risk that elevates procurement hedging costs for Midwest blenders.
- Amino Acids:Branched-chain and essential amino profiles targeting sports nutrition and clinical nutrition applications. Precision fermentation methods are converging with traditional extraction to reshape cost structures for leucine and isoleucine production.
- Enzymes:Protease, amylase, and lipase concentrates for digestive health and processing aid applications. Thermostability requirements limit supplier base to specialists with in-house strain development capabilities.
Vitamins absorb the bulk of installed capacity; sports nutrition applications within amino acids are expanding most quickly.
End User:
Customer scale and formulation complexity create tiered service requirements, with dairy commanding premium technical support while bakery prioritizes price efficiency.
- Bakery:Bread, pasta, and cereal manufacturers purchasing vitamin-mineral premixes for mandatory enrichment compliance. FSMA preventive control documentation burdens hit mid-scale regional bakeries hardest, consolidating demand toward certified suppliers.
- Beverages:Juice, dairy alternatives, and functional drink producers requiring heat-stable microencapsulated nutrients. California's San Joaquin Valley manufacturing corridor accelerates formulation innovation for fortified plant-based alternatives.
- Confectionery:Chocolate and candy producers fortifying with B-vitamins and minerals for permissible health claims. Masking off-notes from iron and zinc compounds demands specialized flavor integration expertise concentrated among coastal formulators.
- Dairy:Yogurt, kefir, and milk processors combining probiotics with fat-soluble vitamins. Texas processing expansion offers white space for probiotic-vitamin combination premixes in underpenetrated production facilities.
Bakery commands the largest absolute volume; dairy carries the steepest expansion trajectory.
Application:
Regulatory scrutiny intensity varies sharply across use cases, with nutritional supplements facing the tightest label claim verification while baked goods operate under established GRAS frameworks.
- Nutritional Supplements:Capsule, tablet, and powder premixes for direct consumption with potency tolerances below five percent. FDA cGMP inspections for dietary supplement manufacturers elevate compliance costs disproportionately for small-batch blenders.
- Functional Foods:Fortified everyday foods with structure-function claims requiring substantiation dossiers. Clean-label consumer preferences in natural channel retail are driving USDA organic certification demand among California and Colorado manufacturers.
- Sports Nutrition:Protein powders, energy bars, and recovery beverages with targeted amino acid and electrolyte profiles. Fitness-focused consumers in metropolitan markets are accelerating reformulation cycles for novel delivery formats.
- Baked Goods:Enriched flour and premix concentrates for bread, muffin, and cereal production. Mandatory enrichment programs sustain predictable baseline demand with limited margin expansion opportunity.
Sports nutrition is climbing the fastest; baked goods provide the revenue floor.
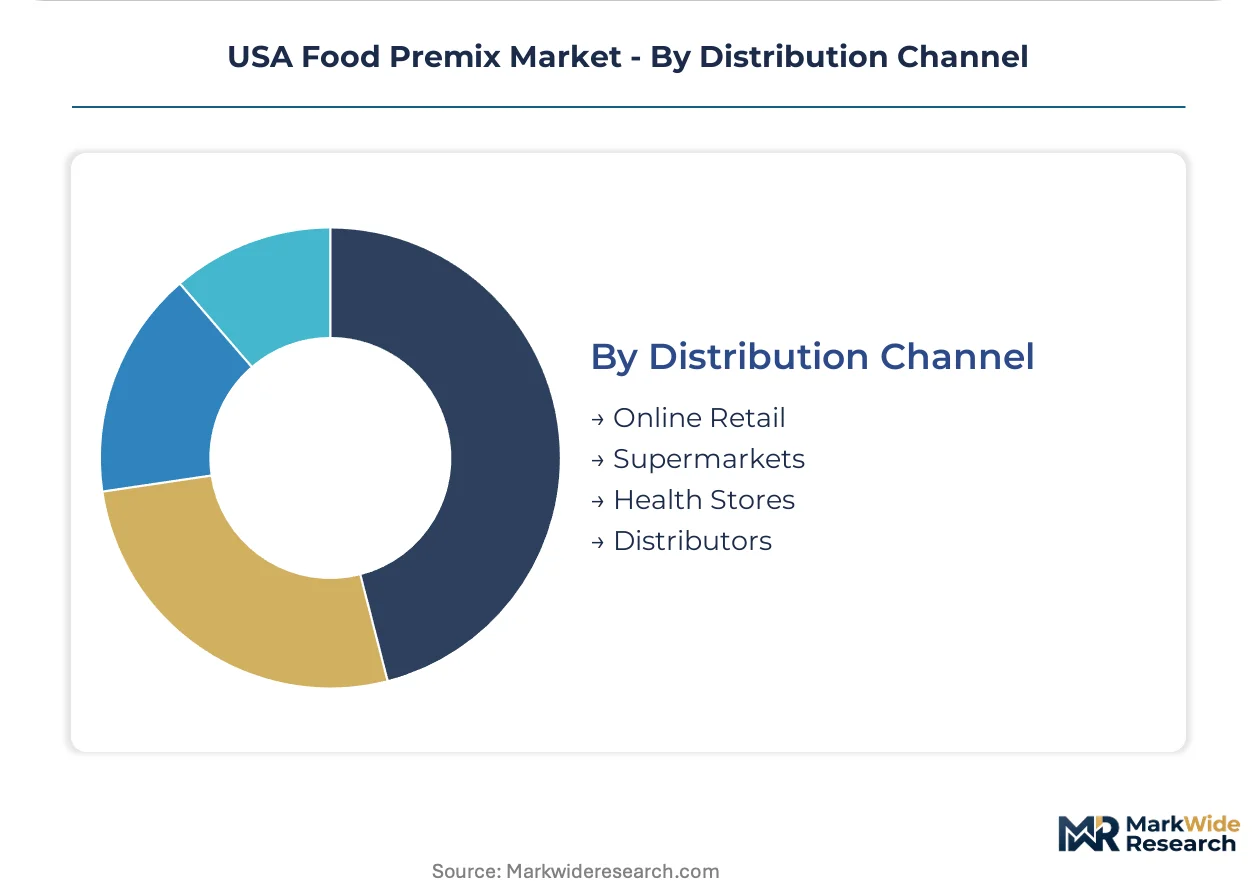
Distribution Channel:
Channel selection reflects customer scale and audit burden tolerance, with direct sourcing displacing intermediaries among FSMA-conscious buyers.
- Online Retail:E-commerce platforms serving small-scale food entrepreneurs and specialty producers. Rapid SKU proliferation strains inventory management systems for premix blenders serving fragmented demand.
- Supermarkets:Mass-market retail chains with private-label fortified food programs. Volume commitments justify dedicated production runs but compress margins through procurement leverage.
- Health Stores:Natural channel retailers prioritizing certified organic and non-GMO verified premixes. Premium positioning aligns with clean-label consumer preferences in coastal metropolitan markets.
- Distributors:Traditional intermediaries facing displacement as contract manufacturers consolidate supplier lists. FSMA preventive control documentation requirements favor direct relationships with certified premix specialists.
Supermarkets and distributors still handle the majority of volume; online retail is gaining share fastest among emerging brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utah and Nevada mining operations supply concentrated mineral feedstock that anchors western premix production capacity. California's San Joaquin Valley functional food corridor concentrates formulation innovation. Texas dairy processing expansion creates new demand pockets for probiotic-vitamin combinations.
California
San Joaquin Valley manufacturing clusters accelerate fortified plant-based beverage development. FDA updated Nutrition Facts labeling requirements drive reformulation cycles among Los Angeles and San Francisco area producers. Clean-label consumer preferences concentrate organic premix demand in coastal metropolitan markets.
Texas
Underpenetrated yogurt and kefir production facilities create white space for probiotic-vitamin combination premixes. USDA organic certification tailwind aligns with natural channel growth in Dallas-Fort Worth and Austin metro areas. Houston-area dairy processors are expanding fortification programs for functional milk alternatives.
Midwest
Kansas and North Dakota wheat processing sustains baseline vitamin premix volume through mandatory flour enrichment programs. Specialized expertise in lipid-soluble nutrient stabilization remains concentrated among aging technical workforces in Illinois and Ohio manufacturing hubs. Legacy ERP integration friction forces costly middleware deployments for FSMA traceability compliance.
Mountain West
Utah and Nevada mining operations supply chelated zinc and selenium concentrates with defined bioavailability coefficients. Geographic concentration risk elevates procurement hedging costs for regional blenders. Denver-area formulators are developing microencapsulation capabilities for heat-sensitive vitamin protection.
Pacific Northwest
Co-manufacturing networks prioritize documented supply chain controls over price competition under FSMA preventive controls. Direct sourcing from certified premix specialists displaces traditional distributor intermediaries among Portland and Seattle area contract manufacturers. Rapid SKU proliferation strains inventory management systems serving fragmented specialty food demand.
USA Food Premix Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation and biosynthetic nutrient pathways. The vendor base clusters around three operational models: grain-origination networks securing vitamin precursor feedstock, in-house particle engineering capabilities for microencapsulation, and chelated mineral specialization with captive mining relationships. Strategic consolidation centers on M&A activity targeting R&D-intensive formulators and capacity expansion in underpenetrated dairy regions.
Within the integrated nutrition science tier, DSM and BASF SE exemplify global research-intensive positioning with lipid-soluble stabilization expertise. Cargill Incorporated anchors the agribusiness-integrated archetype, leveraging origination infrastructure for feedstock security. Balchem Corporation occupies the western production specialist position with chelated mineral capacity concentrated near Utah and Nevada mining operations.
| Leading Market Players |
|---|
| BASF SE |
| Glanbia plc |
| Cargill Incorporated |
| SternVitamin GmbH & Co. KG |
| Prinova Group LLC |
| Archer Daniels Midland Company |
| Corbion N.V. |
| Balchem Corporation |
| DSM |
| Others |
Value Network & Pricing Analysis
Captive mineral sourcing from Utah and Nevada mining operations anchors both supply security and pricing power for western premix manufacturers, while FDA label claim verification requirements bundle technical warranty costs into master batch pricing. This integration pattern concentrates margin protection among blenders with documented supply chain controls, leaving mid-scale competitors exposed to feedstock volatility and compliance cost inflation.
Pricing Analysis
Technical warranty bundling separates certified premix suppliers from unverified competitors, with FSMA documentation and potency guarantee coverage included in premium tier pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in economy-tier vitamin premixes is intensifying because corn and soybean derivative feedstock prices fluctuate with commodity cycles. Mid-scale regional bakeries exhibit the highest price sensitivity due to thin margins, while dairy processors prioritize technical support over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Utah and Nevada mining operations for chelated zinc and selenium concentrates, creating geographic concentration risk that elevates procurement hedging costs. Domestic premix manufacturing draws from Chinese vitamin precursor synthesis, Brazilian amino acid fermentation feedstock, and domestic grain origination networks. Tariff exposure on imported vitamin intermediates threatens margin stability for non-integrated blenders. Distribution runs through direct sourcing relationships with certified specialists, displacing traditional distributor intermediaries among FSMA-conscious contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around qualified formulation chemists and certified production capacity prop pricing power for incumbent blenders, creating a supply-constrained market structure that favors producers with documented FSMA controls.
For Market Incumbents: Deploy backward integration into vitamin precursor feedstock to secure margin protection against commodity volatility. Acquire microencapsulation capabilities in-house to capture premium positioning for heat-sensitive nutrient applications. Precision fermentation entrants threaten traditional B-complex cost structures; defend through captive R&D in biosynthetic nutrient stabilization.
For New Entrants and Emerging Players: Launch via direct sourcing partnerships with Texas dairy processors seeking probiotic-vitamin combination premixes. Target underpenetrated yogurt and kefir production facilities in Dallas-Fort Worth and Houston metro areas. USDA organic certification offers the most penetrable positioning angle for natural channel growth.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by agribusiness-integrated nutrition platforms seeking western mineral capacity. Long-term viability hinges on R&D-intensive formulators with lipid-soluble stabilization expertise and documented FSMA compliance infrastructure. Watch for precision fermentation cost parity announcements as the inflection signal for traditional synthesis margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Precursor Feedstock | Cargill leverages grain origination networks to secure supply security against commodity volatility. |
| Microencapsulation Capability Acquisition | Balchem anchors western production with in-house particle engineering for heat-sensitive nutrient protection. |
| USDA Organic Certification Investment | Clean-label positioning aligns with natural channel growth in California and Colorado metropolitan markets. |
| Precision Fermentation R&D Partnership | Biosynthetic vitamin production methods reshape cost structures for B-complex nutrients. |
| Texas Dairy Processing Expansion | Underpenetrated yogurt and kefir facilities create white space for probiotic-vitamin combination premixes. |
Research Methodology
Multi-period observation of FDA label claim verification requirements, FSMA compliance cost trajectories, and mineral feedstock price volatility anchored the trend analysis, supplemented by interviews with premix formulation chemists, dairy processing procurement directors, bakery operations managers, and FSMA compliance officers. Secondary validation drew from FDA cGMP inspection databases, USDA organic certification records, SEC filings of publicly traded nutrition companies, and customs trade data on vitamin precursor imports. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile volume estimates.
Input-output matrices mapped nutrient category production capacity against end-use demand segments across the projection horizon. Segmentation dimensions modeled include product type, end user industry, application use case, and distribution channel structure. CAGRs were derived through regression analysis of historical volume trends and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated flour fortification mandate compliance rates and sports nutrition SKU proliferation patterns.
Feedstock commodity price shocks, FDA micronutrient reference daily intake revisions, and precision fermentation cost breakthroughs are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented supply chain control premiums and certification cost structures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Horseradish Peroxidase Market
Food Components and Additives
Polydextrose Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial and Antioxidants Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial Coating Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Food Premix Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Clean Label Pectin Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Food Grade Activated Carbon Market