
 Asia-Pacific Food Anti Caking Agents Market | 2026-2036
Asia-Pacific Food Anti Caking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Anti Caking Agents Market Outlook
Bakeries and restaurant chains are unwinding decades of reliance on bulk commodity suppliers. Evonik Industries AG leverages its synthetic silica expertise to serve premium baking mix producers across East Asia. Kao Corporation anchors supply relationships with Japanese dairy processors seeking magnesium carbonate with documented particle size consistency. Brenntag AG competes through its regional distribution network, controlling inventory points in Australia and Thailand to reduce lead times for mid-tier food manufacturers.
Food anti-caking agents are powdered or granular substances, typically composed of silicates, carbonates, or bicarbonates with specified particle diameters below 50 microns, that adsorb moisture or physically separate crystalline structures to maintain free-flowing properties in dry food matrices. Their primary commercial purpose is to preserve processing efficiency, dosing accuracy, and shelf stability in packaged foods prone to caking under humidity exposure. Calcium silicate dominates product type demand due to its dual functionality as both anti-caking aid and calcium fortifier in baking mixes and seasoning blends. Sodium bicarbonate segments show structural momentum in sauce applications where pH buffering accompanies flow control, while talc faces margin compression as reformulation trends accelerate in dairy products across the region.
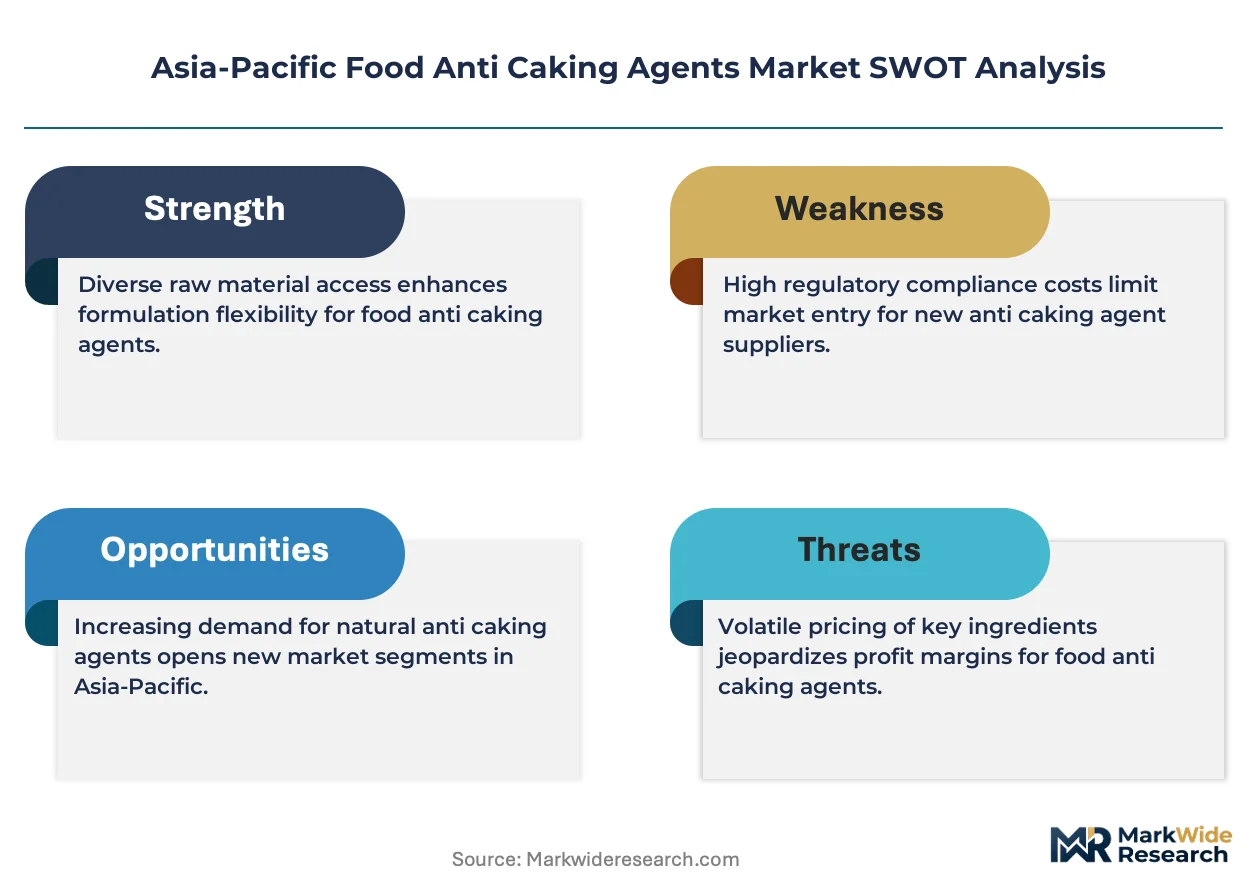
FSSAI purity mandates in India, MEE environmental discharge rules affecting silicate producers in China, and Japan's Food Sanitation Law administered by the Ministry of Health shape formulation choices and import clearance protocols across the region. Regulatory divergence between jurisdictions forces suppliers to maintain multiple certificate portfolios, elevating compliance costs for smaller distributors. Stakeholders must monitor how China's GB standards evolution and India's BIS certification expansion for food additives will reshape supplier qualification timelines and regional sourcing patterns.
Market Dynamics
Reformulation pressure from India's FSSAI purity mandates and China's MEE discharge rules is forcing suppliers to rebuild certificate portfolios across multiple jurisdictions, elevating compliance costs and reshaping competitive positioning among regional distributors.
Growth Catalysts
- Processed dairy corridor expansion:China's dairy processors are accelerating adoption of magnesium carbonate and calcium silicate systems to replace talc-based formulations in infant formula and UHT milk powders.
- FSSAI regulatory tightening:India's food-grade silicate purity standards are compelling domestic seasoning manufacturers to upgrade anti-caking specifications, creating certified-supplier premiums.
- Synthetic silica functionalization:Premium baking mix producers across East Asia are specifying sub-20-micron particle distributions for moisture control in high-humidity distribution environments.
Market Restraints
- Input cost volatility:Sodium bicarbonate feedstock prices fluctuate with soda ash mining output from China's Inner Mongolia production belt.
- Supply concentration risk:Synthetic silica manufacturing clusters along China's Yangtze River face recurrent MEE environmental audits disrupting regional availability.
- Technical limitation:Magnesium carbonate exhibits hygroscopic instability above 75% relative humidity, restricting deployment in Southeast Asian coastal seasoning facilities.
Strategic Opportunities
- Vietnam's underpenetrated processed food sector:Local sauce and seasoning manufacturers lack technical partnerships for anti-caking specification development.
- Regulatory tailwind from Japan's Food Sanitation Law:Ministry of Health documentation requirements for particle size consistency are creating preference for suppliers with JIS-traceable quality systems.
- E-commerce channel emergence:Direct procurement platforms are compressing distributor margins and enabling mid-tier Australian food manufacturers to source specialized silicate grades.
Industry Challenges
- Certification timeline compression:BIS expansion for food additives in India is extending supplier qualification periods by 8-12 months for new market entrants.
- Legacy equipment incompatibility:Talc-reliant dairy processing lines require retrofitting for carbonate-based flow agents, demanding capital allocation from processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Anti Caking Agents Market |
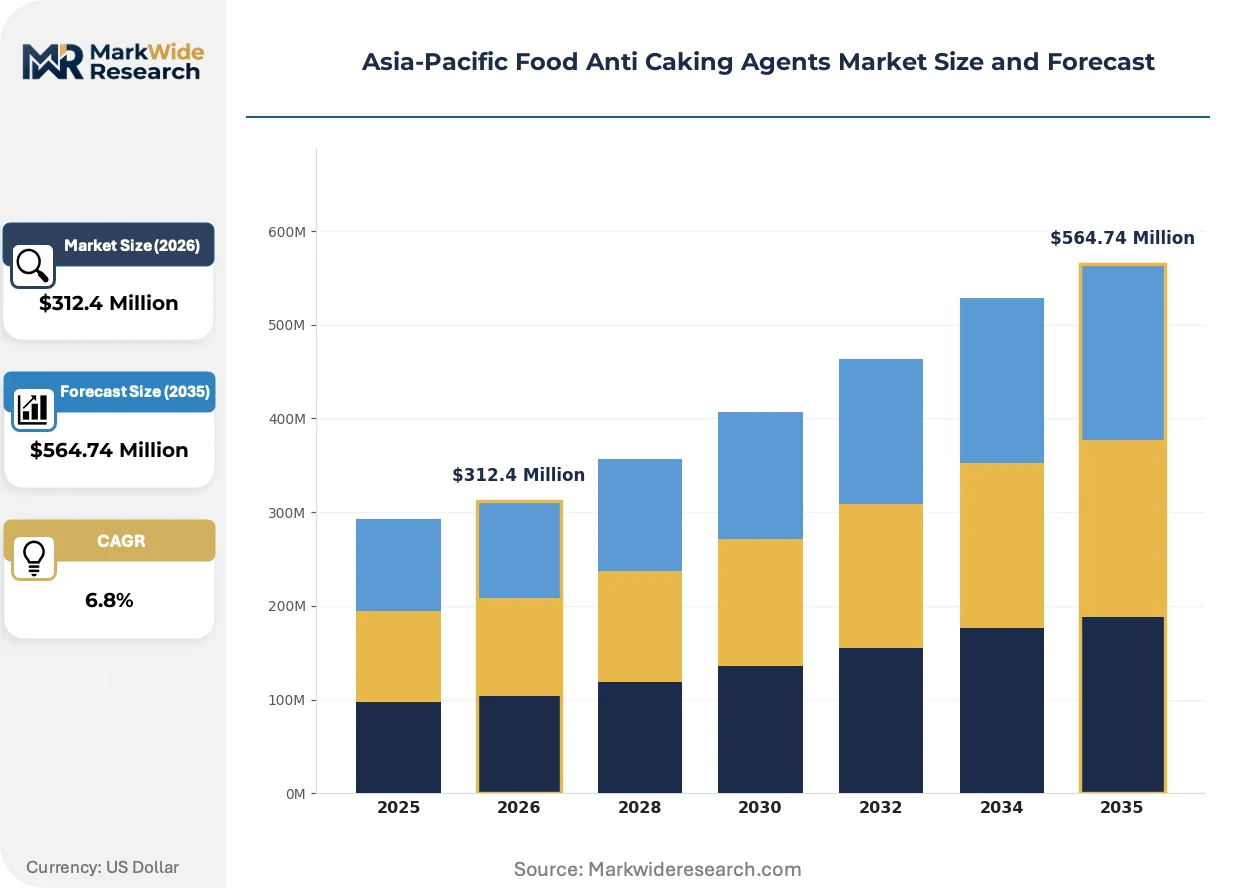
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Silicate, Magnesium Carbonate, Sodium Bicarbonate, Talc Application: Dairy Products, Sauces, Seasonings, Baking Mixes End User: Food Manufacturers, Bakeries, Restaurants, Retail Chains Distribution Channel: Online Retail, Wholesalers, Direct Sales, Specialty Stores |
| Companies Covered | Evonik Industries AG, PPG Industries, Inc., Brenntag AG, Univar Solutions Inc., Solvay SA, Cabot Corporation, Huber Engineered Materials, Kao Corporation, Kemin Industries, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Anti Caking Agents Market Strategic Shifts
Active reformulation across dairy and seasoning verticals is splitting the market between premium synthetic systems and commodity mineral grades, with regulatory documentation becoming the primary differentiation mechanism.
Sub-micron synthetic silica functionalization is bifurcating the premium segment from commodity talc and carbonate suppliers. Japanese dairy processors are specifying documented particle size distributions below 15 microns for infant formula applications. This technical escalation is compressing margins for undifferentiated mineral-grade suppliers while rewarding synthetic specialists with captive precipitation expertise.
FSSAI's 2023 purity mandate for food-grade silicates is forcing Indian seasoning manufacturers to discard legacy talc-dominant formulations. Domestic suppliers without BIS certification face import clearance delays at Mumbai and Chennai ports. Powdered seasoning producers in Maharashtra and Gujarat are accelerating supplier audits to pre-qualify certificate portfolios ahead of enforcement expansion.
Direct procurement through specialized chemical platforms is displacing traditional distributor relationships among mid-tier Australian and Thai food manufacturers. Brenntag's regional inventory points face margin pressure as buyers source magnesium carbonate directly from Japanese producers with documented consistency. This channel shift is most visible in Australia's baking mix sector, where formulators prioritize specification transparency over distributor technical service.
Asia-Pacific Food Anti Caking Agents Market Segmentation
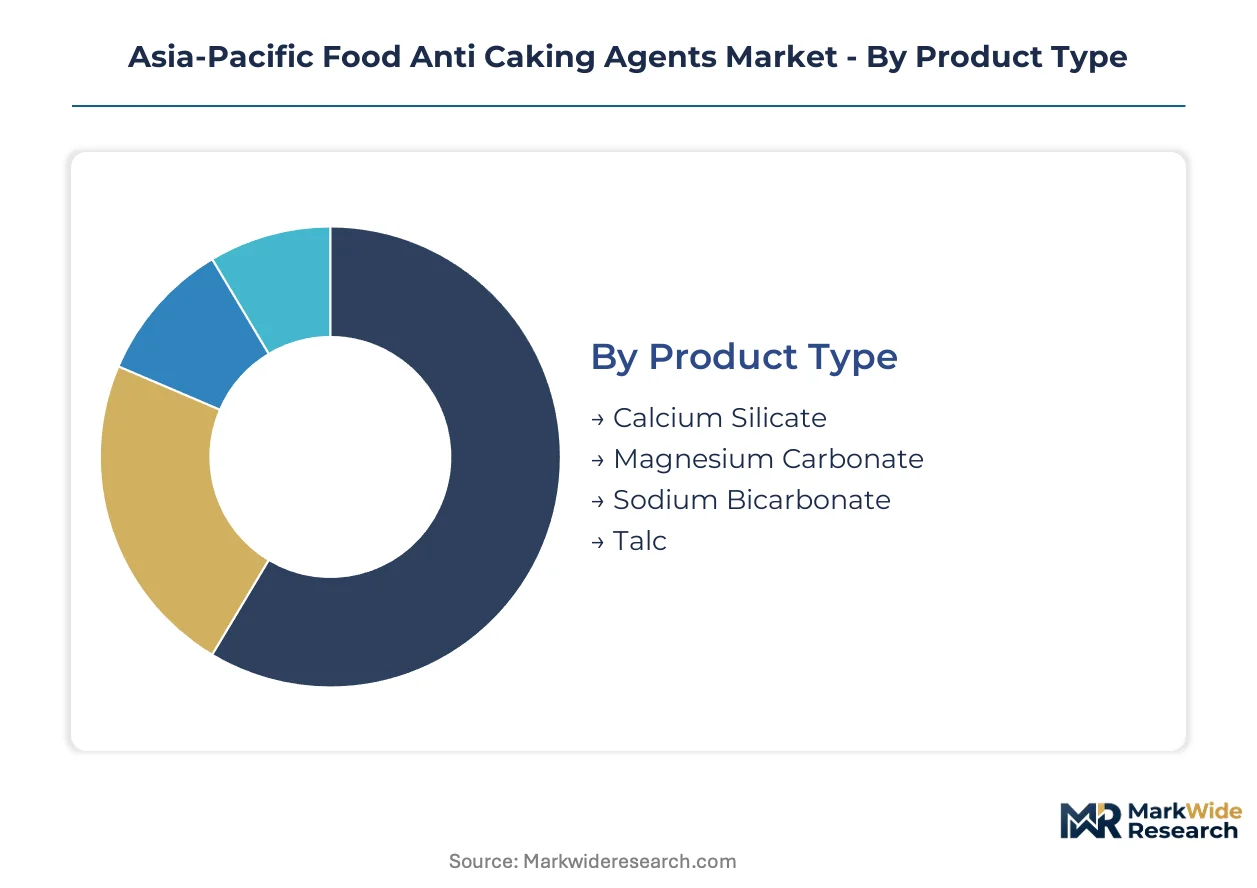
Anti-caking agent selection in Asia-Pacific hinges on reformulation pressures from India's FSSAI mandates and China's MEE discharge rules. Segmentation reveals where substitute threats concentrate and which functional specifications command premium positioning across dairy, seasoning, and baking applications.
Product Type:
Substitution pressure intensifies around talc-based systems as dairy processors abandon legacy formulations for carbonate and silicate alternatives with documented purity certificates.
- Calcium Silicate:Synthetic precipitated silicate with dual functionality as anti-caking aid and calcium fortifier. China's processed dairy corridor and Indian baking mix manufacturers specify this grade for moisture adsorption below 50% relative humidity. FSSAI purity mandates elevate certified-supplier premiums for food-grade specifications.
- Magnesium Carbonate:Light and heavy carbonate variants with documented particle size consistency below 20 microns. Japanese dairy processors anchor procurement relationships around JIS-traceable quality systems for infant formula applications. Hygroscopic instability above 75% relative humidity restricts deployment in Southeast Asian coastal facilities.
- Sodium Bicarbonate:Bicarbonate systems combining pH buffering with flow control in sauce applications. Feedstock prices fluctuate with soda ash output from China's Inner Mongolia production belt.
- Talc:Natural mineral facing margin compression from accelerated reformulation trends across regional dairy products. Legacy processing lines require capital retrofitting for carbonate compatibility.
Calcium silicate anchors the volume base while magnesium carbonate gains share at the steepest rate.
Application:
Cost tier stratification separates premium infant formula specifications from commodity seasoning grades, with regulatory documentation requirements widening the gap.
- Dairy Products:Infant formula and UHT milk powder applications demanding sub-15-micron particle distributions with full certificate traceability. China's dairy processors drive specification escalation as talc replacement accelerates.
- Seasonings:Powdered spice and condiment blends requiring humidity resistance in high-moisture distribution environments. Maharashtra and Gujarat manufacturers pre-qualify supplier portfolios ahead of FSSAI enforcement expansion.
- Sauces:Dry sauce mixes where sodium bicarbonate provides simultaneous pH buffering and anti-caking functionality. Vietnam's underpenetrated processed food sector lacks technical partnerships for specification development.
- Baking Mixes:Premium East Asian producers specify sub-20-micron synthetic silica for moisture control in high-humidity channels. Direct procurement platforms compress distributor margins in Australia's baking sector.
Dairy products command the highest specification premiums while seasonings deliver the broadest volume base across the region.
End User:
Customer type determines procurement sophistication, with large food manufacturers maintaining multi-certificate portfolios while smaller bakeries rely on distributor technical service.
- Food Manufacturers:Integrated processors with in-house formulation capabilities and direct supplier relationships. Seasoning and dairy specialists in India and China maintain dedicated quality audit teams.
- Bakeries:Mid-tier producers unwinding bulk commodity reliance in favor of premium baking mix specifications with documented particle consistency.
- Restaurants:Chain operators standardizing ingredient flow properties across centralized procurement systems. Specification transparency outweighs distributor relationships for larger operators.
- Retail Chains:Private-label food producers sourcing through direct procurement platforms, bypassing traditional wholesale channels.
Food manufacturers dominate certified-grade procurement while retail chains are expanding most quickly through platform-based sourcing.
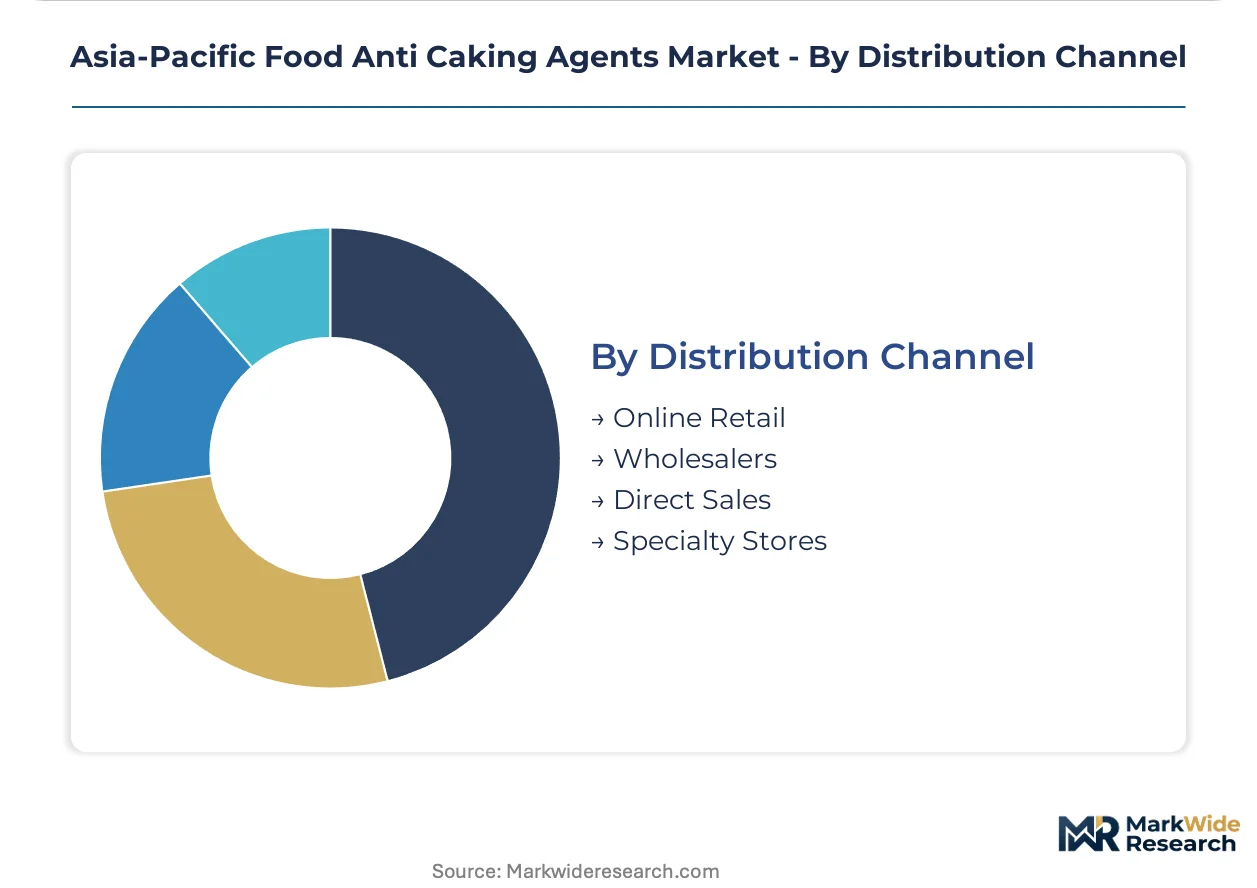
Distribution Channel:
Supply concentration along China's Yangtze River clusters shapes channel selection, with environmental audit disruptions favoring inventory-heavy distributor relationships for risk-averse buyers.
- Direct Sales:Large-volume dairy and seasoning processors contracting directly with Japanese magnesium carbonate producers or synthetic silica specialists. Brenntag's regional inventory points face displacement as specification transparency becomes paramount.
- Wholesalers:Traditional channel controlling stock points in Australia and Thailand for mid-tier manufacturers prioritizing lead time reduction over certificate depth.
- Online Retail:Emerging platform channel compressing margins and enabling mid-tier Australian formulators to source specialized silicate grades with full documentation.
- Specialty Stores:Niche channel serving small bakeries and artisan producers requiring technical consultation alongside product supply.
Wholesalers retain the broadest geographic coverage while direct sales climbs the fastest as large processors consolidate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in food additive logistics, while Singapore's Jurong Port anchors transshipment for Southeast Asian seasoning supply chains.
China
Processed dairy corridors in Heilongjiang and Inner Mongolia drive magnesium carbonate procurement for infant formula applications. MEE environmental discharge rules along the Yangtze River synthetic silica clusters disrupt regional availability and force inventory pre-positioning. Qingdao and Tianjin ports handle the bulk of carbonate imports for baking mix manufacturers.
India
Maharashtra and Gujarat seasoning manufacturers pre-qualify supplier portfolios ahead of FSSAI enforcement expansion on food-grade silicate purity. Mumbai and Chennai ports experience import clearance delays for uncertified anti-caking shipments. The dairy processing belt in Punjab and Haryana upgrades to talc-free formulations.
Japan
Kanto region dairy processors specify sub-15-micron particle distributions for infant formula under Ministry of Health documentation requirements. JIS-traceable quality systems create preference barriers for uncertified imports. Osaka-based formulators anchor procurement relationships with documented consistency suppliers.
Australia
Mid-tier baking mix producers in Victoria and New South Wales bypass traditional distributors through direct procurement platforms. Melbourne and Sydney warehouses compress lead times for carbonate grades. The sector unwinds bulk commodity reliance in favor of specification transparency.
Vietnam
Saigon Port handles growing volumes of sauce and seasoning anti-caking imports for Ho Chi Minh City processors. Local manufacturers lack technical partnerships for specification development. The underpenetrated processed food sector presents partnership opportunities for documented-grade suppliers.
Asia-Pacific Food Anti Caking Agents Market Competitive Environment
Concentration sits with synthetic silica specialists and regional distributors maintaining multi-jurisdiction certificate portfolios. The vendor base spans German chemical conglomerates, Japanese diversified industrials, and commodity mineral traders. Two strategic archetypes dominate: precipitation-technology owners serving premium dairy specifications, and inventory-heavy distributors optimizing for lead-time-sensitive mid-tier manufacturers. Competitive moves center on M&A for certificate portfolio expansion and strategic partnerships with port-adjacent warehousing operators.
Among Germany-based chemical specialists, Evonik Industries AG exemplifies the synthetic silica archetype with precipitation expertise. Japanese diversified industrial Kao Corporation anchors the documented-consistency tier for dairy applications. Brenntag AG represents the regional distribution archetype controlling inventory points across Australia and Thailand.
| Leading Market Players |
|---|
| Evonik Industries AG |
| PPG Industries, Inc. |
| Brenntag AG |
| Univar Solutions Inc. |
| Solvay SA |
| Cabot Corporation |
| Huber Engineered Materials |
| Kao Corporation |
| Kemin Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
FSSAI purity mandates in India gate both supplier qualification timelines and price differentiation tiers, compressing margins for uncertified mineral-grade traders while elevating certified synthetic silica premiums across the Asia-Pacific food anti-caking landscape.
Pricing Analysis
Volume-discount tiering structures separate premium synthetic silica specifications from commodity carbonate and talc grades. Price differentiation rests on JIS-traceable certification tiers for Japanese dairy applications and FSSAI-compliant documentation for Indian seasoning processors. Cost compression in the economy mineral tier is intensifying because direct procurement platforms displace distributor markups. Mid-tier Australian baking manufacturers exhibit highest price sensitivity, while infant formula processors in China show least sensitivity to certification-grade premiums.
Supply Chain Analysis
China and Japan anchor synthetic silica and magnesium carbonate production respectively for Asia-Pacific food anti-caking supply. Raw material dependencies draw from soda ash mining in Inner Mongolia, precipitated silicate feedstocks along the Yangtze River, and documented-purity carbonate from Osaka-based chemical complexes. Single-source vulnerability concentrates around MEE environmental audit disruptions affecting Yangtze River silicate clusters. Distribution runs through port-adjacent warehousing at Shanghai, Singapore Jurong, and Melbourne with inventory pre-positioning for lead-time-sensitive dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where multi-jurisdiction certificate portfolios create switching costs that lock in incumbent positioning across the Asia-Pacific food anti-caking landscape.
For Market Incumbents: Consolidate certificate portfolio depth across FSSAI, JIS, and GB standard tiers to preempt new entrant qualification timelines. Acquire port-adjacent warehousing capacity in Vietnam and Australia to defend against direct procurement platform displacement. Capacity addition in Southeast Asian coastal zones addresses magnesium carbonate hygroscopic instability risks for seasoning manufacturers.
For New Entrants and Emerging Players: Differentiate on sub-15-micron particle specification capabilities for infant formula applications where documented consistency commands structural premiums. Vietnam's underpenetrated sauce and seasoning sector offers the most penetrable geography for technical partnership entry. A go-to-market angle anchored to BIS certification pre-qualification services for Maharashtra and Gujarat manufacturers bypasses incumbent distributor relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic silica precipitation capacity as MEE discharge rules force environmental compliance investments. Long-term viability favors precipitation-technology owners with captive R&D over commodity mineral traders facing margin compression. Acquisition target archetypes include Japanese magnesium carbonate specialists with JIS-traceable systems and regional distributors controlling Australia-Thailand inventory nodes. The signal to watch is FSSAI enforcement expansion timelines affecting import clearance velocity at Mumbai and Chennai ports.
| Strategic Initiative | Industry Significance |
|---|---|
| Certificate Portfolio Expansion | FSSAI-JIS-GB multi-jurisdiction coverage locks in supplier qualification timelines for Indian and Japanese dairy processors. |
| Port-Adjacent Warehousing Investment | Singapore Jurong and Melbourne inventory nodes reduce lead times for carbonate-grade procurement by Australian mid-tier manufacturers. |
| Sub-Micron Particle Functionalization | Synthetic silica precipitation expertise below 15 microns captures infant formula specification premiums in China's Heilongjiang dairy corridor. |
| Direct Procurement Platform Partnership | E-commerce channel integration displaces Brenntag-style distributor margins among Victoria and New South Wales baking mix producers. |
| Technical Specification Development Service | Partnership models for Vietnam's Ho Chi Minh City sauce manufacturers address underpenetrated processed food sector gaps. |
Study Parameters
The analysis maps synthetic silica, magnesium carbonate, sodium bicarbonate, and talc sub-sectors, each validated through formulation chemists at dairy processors, procurement leads at seasoning manufacturers, distribution channel partners, and regulatory affairs specialists at import clearance agencies. Primary interview insights triangulate against customs trade data, FSSAI notification filings, BIS certification registries, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume builds from application-grade consumption estimates cross-check against top-down market sizing from regional production cluster analysis.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type, application vertical, end-user procurement sophistication, and distribution channel structure dimensions. CAGRs derive from segment-level growth rate synthesis applied to base-year consumption estimates. Forecast inputs incorporate MEE environmental audit frequency assumptions and FSSAI enforcement expansion timelines affecting supplier qualification periods.
Decision-makers should treat outputs as directional under stable regulatory enforcement and environmental compliance assumptions; material deviation in MEE audit intensity or BIS certification expansion velocity would warrant model refresh. Recalibration cycles align with material shifts in purity mandate enforcement schedules and synthetic silica cluster environmental clearance protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Modified Wheat Starch Market
Food Components and Additives
Asia-Pacific Food Hydrocolloids Market
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
Calcium Glycerophosphate Market
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Europe Food Preservatives Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Food Texture Market
Food Components and Additives
Canada Food Hydrocolloids Market