
 Generator (Up to 20 Kva) Market | 2026-2036
Generator (Up to 20 Kva) Market Size, Share, and Industry Trends Forecast 2026-2036
Generator (Up to 20 Kva) Market Foresight
Multi-source procurement for engine blocks and alternator assemblies is hardening across the supply base. Cummins leverages its captive engine foundry network to insulate margin pools from commodity volatility. Kohler anchors its position through deep channel control in North American residential standby segments. Kirloskar competes on manufacturing scale across India's tier-two and tier-three distribution nodes.
A generator up to 20 kVA is a compact internal combustion or inverter-based power conversion unit rated at twenty kilovolt-amperes or below, typically incorporating a prime mover, alternator, voltage regulator, and acoustic enclosure to deliver single-phase or three-phase electrical output for localized load centers. These units bridge grid instability or absence across commercial construction, telecom infrastructure, and residential backup applications. Diesel portable units retain volume leadership in emerging-market construction, while inverter technology captures expanding share among recreational users and premium residential buyers seeking harmonic distortion below five percent. Gas standby systems represent the fastest-expanding margin pool as methane infrastructure penetration deepens in suburban North America and parts of Europe.
EPA Tier 4 Final and CARB certification requirements in the United States, EU Stage V and F-Gas Regulation in Europe, and BIS emission norms under India's CEA directives collectively elevate engineering barriers and compliance costs for sub-20 kVA diesel products. These frameworks compress product lifecycles and force portfolio rebalancing toward gas, bi-fuel, and battery-hybrid architectures. Stakeholders must monitor regulatory phase-in calendars and pre-position alternative-fuel certification pipelines before diesel-dominant revenue streams face accelerated obsolescence.
Market Dynamics
Emissions compliance deadlines are compressing diesel generator product lifecycles and forcing portfolio rebalancing toward gas and battery-hybrid architectures across all major supply bases.
Growth Catalysts
- Telecom infrastructure electrification:Tower operators across India and Southeast Asia are expanding backup power procurement as grid reliability fluctuates and uptime requirements tighten.
- EU Stage V emissions standards:These frameworks redirect R&D spending toward bi-fuel and gas architectures, creating certified product differentiation for early movers.
- Distributed commercial construction:Secondary cities in India concentrate demand where small business electrification outpaces centralized infrastructure buildout.
Market Restraints
- Copper and steel price volatility:Alternator winding costs and enclosure fabrication inputs swing with commodity markets, squeezing margin pools on fixed-price contracts.
- Engine block supply concentration:Foundry capacity clusters in China and India expose procurement to regional logistics disruptions and tariff exposure.
- EPA Tier 4 Final certification costs:Diesel after-treatment engineering elevates unit economics and narrows the addressable market for sub-10 kVA products.
Strategic Opportunities
- Methane infrastructure penetration:Suburban North America and parts of Europe enable gas standby systems to capture expanding margin pools as pipeline coverage deepens.
- Inverter technology convergence:Recreational vehicle manufacturers and premium residential buyers seek harmonic distortion below five percent, creating premium positioning.
- India's tier-three distribution nodes:Manufacturing scale advantages concentrate procurement decisions where channel control remains underdeveloped.
Industry Challenges
- Emissions calibration engineering talent:Scarce expertise in after-treatment system integration delays product certification timelines and stretches development cycles.
- Dual-fuel control system integration:Software complexity for seamless diesel-gas switching creates warranty exposure and field service training burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generator (Up to 20 Kva) Market |
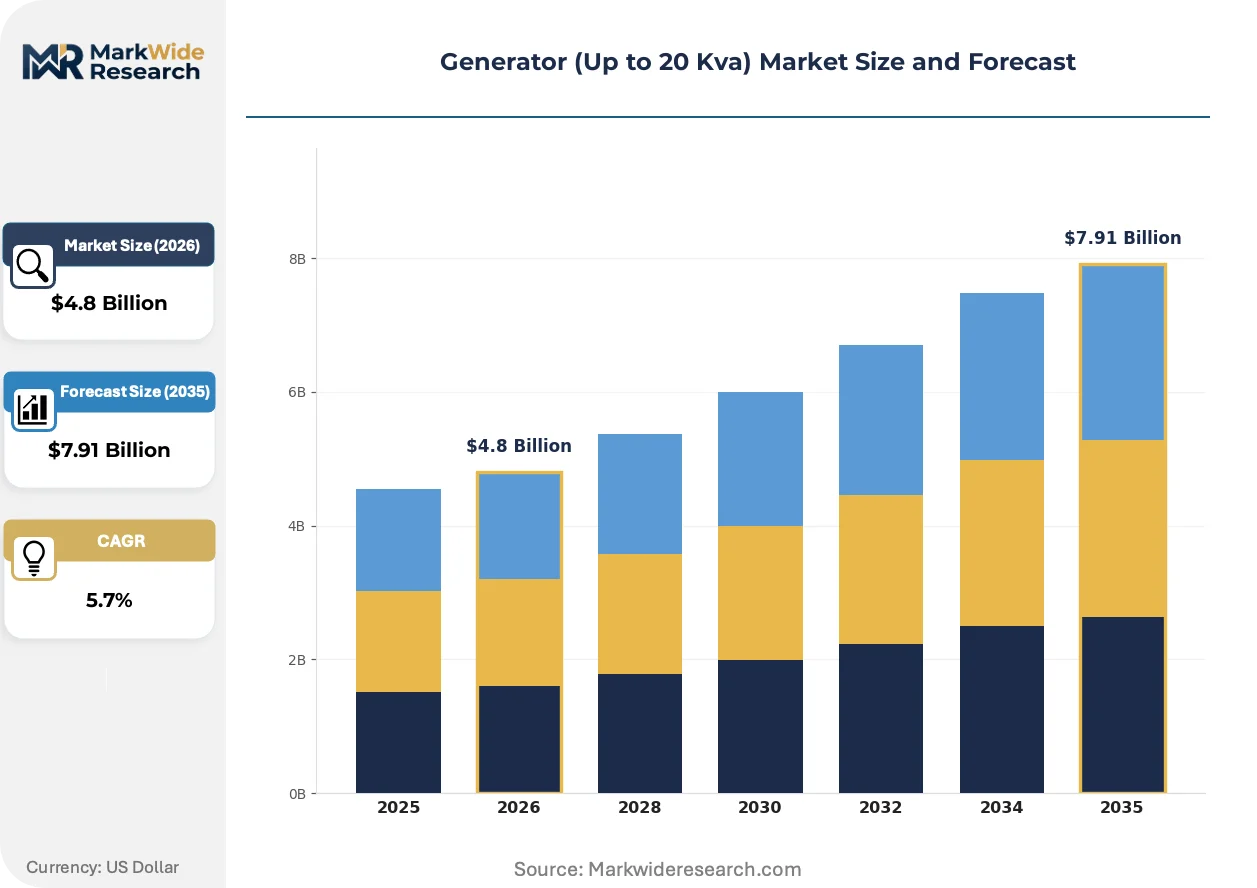
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Inverter, Diesel, Gas, Bi-Fuel Technology: Brushless, Synchronous, Asynchronous, Digital Control, AVR System Application: Residential Backup, Construction Sites, Remote Worksites, Events, Telecommunications End User: Small Businesses, Mobile Operators, Agricultural Operations, Emergency Services, Recreational Users |
| Companies Covered | Cummins, Caterpillar, Kohler, Generac Power Systems, Kirloskar, Doosan, Honda, Weichai, Atlas Copco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generator (Up to 20 Kva) Market Shifts & Advancements
Power conversion architectures are bifurcating between conventional internal combustion platforms and electronically controlled inverter systems, with regulatory pressure accelerating the shift toward cleaner prime movers.
Bi-fuel control systems are integrating diesel and natural gas combustion management through single-ECU architectures that optimize fuel switching based on load profiles and methane availability. Commercial standby buyers in suburban North America are specifying these configurations to hedge fuel price volatility. The technology is integrating emissions compliance with operational flexibility, compressing the pure-diesel product lifecycle.
EPA Tier 4 Final and CARB certification requirements in the United States are elevating engineering barriers for sub-20 kVA diesel products and forcing portfolio rebalancing. Manufacturers face compressed development timelines to secure approvals before phase-in deadlines. The construction rental segment is responding by accelerating gas and battery-hybrid pilot programs.
Telecom tower operators are consolidating procurement decisions at regional headquarters rather than site-level purchasing, concentrating vendor relationships and squeezing distributor margins. Equipment lessors and direct manufacturer channels are displacing traditional dealer networks for large fleet orders. This concentration is most visible across India and Southeast Asia where tower portfolios exceed ten thousand units.
Generator (Up to 20 Kva) Market Segmentation
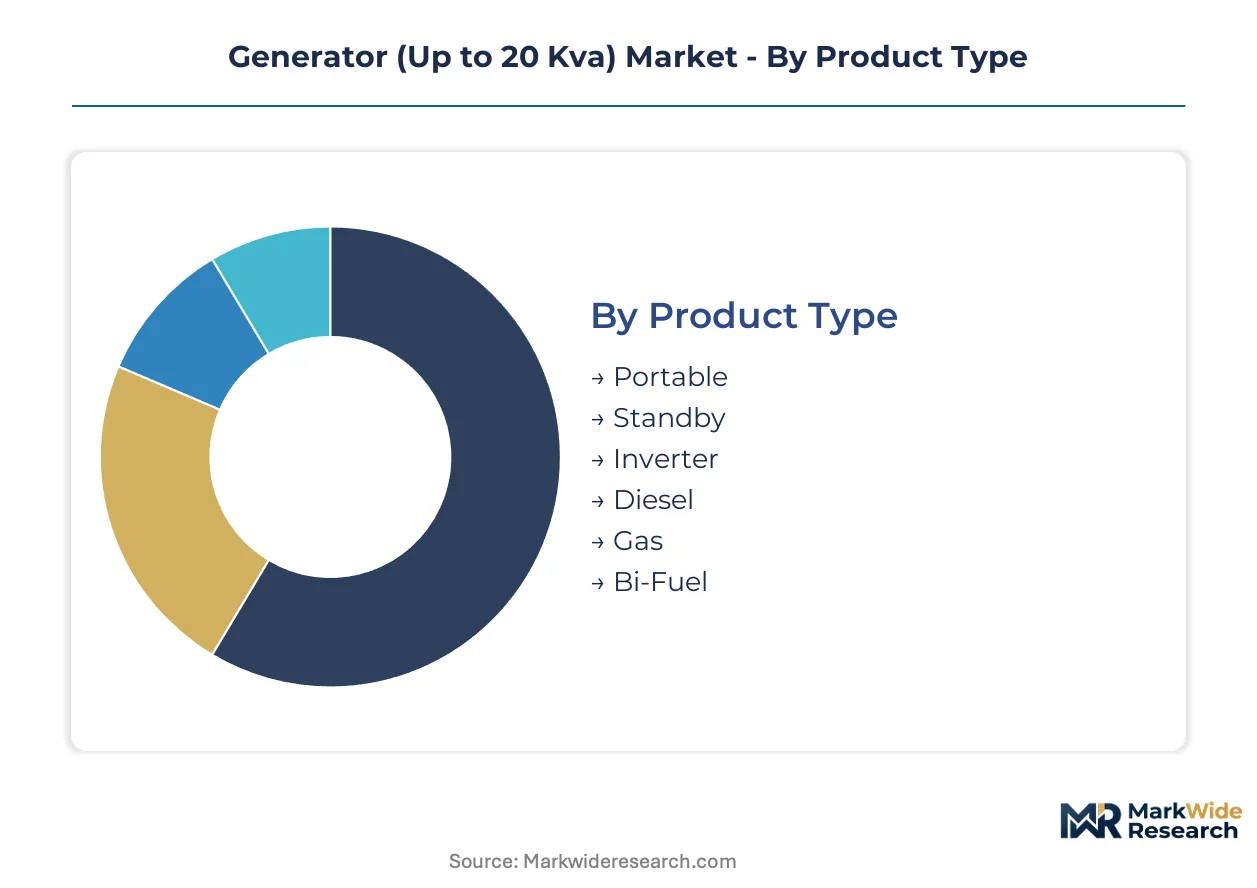
Segmentation in the sub-20 kVA generator market maps directly to divergent power quality requirements and regulatory exposure across end-use environments. Buyers sort themselves by runtime needs, harmonic sensitivity, and fuel infrastructure availability rather than kilovolt-ampere ratings alone.
Product Type:
Customization intensity varies sharply across this category, from mass-produced portable units to site-engineered bi-fuel installations requiring fuel train integration.
- Diesel:Compression-ignition engines with mechanical or electronic fuel injection dominate construction rental fleets and telecom backup in grid-unreliable regions. India's tower operators specify these for 72-hour autonomous runtime where methane infrastructure is absent. Demand concentrates in secondary cities across Maharashtra and Uttar Pradesh as small business electrification outpaces distribution utility buildout.
- Gas:Spark-ignited natural gas or propane systems leverage suburban pipeline penetration in the United States and parts of Europe. Residential standby buyers in Texas, Florida, and suburban Germany specify these for lower emissions profiles and fuel cost predictability. EPA and EU Stage V compliance burdens are compressing diesel alternatives and redirecting procurement toward certified gas architectures.
- Portable:Compact wheeled or carry-frame units with recoil or electric start target construction crews and event operators requiring mobility over runtime.
- Standby:Fixed automatic transfer switch integration serves residential and commercial buyers seeking seamless grid failure response.
- Inverter:Electronically controlled power conversion delivers sub-5% total harmonic distortion for sensitive electronics and recreational vehicle applications.
- Bi-Fuel:Diesel-gas combustion management through single-ECU architectures enables fuel switching based on methane availability and price arbitrage.
Leading the category by volume: Diesel. Growing fastest: Gas.
Technology:
Cost tier separation distinguishes premium electronically controlled systems from commodity electromechanical platforms serving price-sensitive procurement.
- Digital Control:Microprocessor-based engine governors and alternator voltage regulation enable remote monitoring, load-dependent throttle modulation, and predictive maintenance alerts. Telecom tower operators in India and Southeast Asia specify these for centralized fleet management across dispersed sites. The technology commands premium positioning where uptime guarantees drive vendor selection.
- AVR System:Automatic voltage regulation through analog or digital sensing circuits maintains ±1% output stability for construction equipment and sensitive electronics. Demand clusters in North American residential standby and European commercial applications where grid voltage fluctuation tolerance is narrow. Regulatory pressure on emissions compliance is accelerating integration with bi-fuel control architectures.
- Brushless:Self-exciting alternator designs eliminate slip rings and reduce maintenance intervals for continuous-duty applications.
- Synchronous:Fixed-speed operation at utility frequency suits stable load profiles with minimal harmonic distortion requirements.
- Asynchronous:Induction generator designs offer cost advantages for short-duration intermittent duty cycles.
Highest margin capture: Digital Control. Steepest expansion trajectory: AVR System integration with bi-fuel platforms.
Application:
Customer type determines whether procurement prioritizes purchase price, total cost of ownership, or operational flexibility under emissions constraints.
- Telecommunications:Tower infrastructure backup demands 99.99% uptime with autonomous runtime spanning grid failures of 48-72 hours. Operators across India, Indonesia, and the Philippines consolidate procurement at regional headquarters, squeezing distributor margins and favoring direct manufacturer relationships. BIS emission norms under India's CEA directives are forcing portfolio rebalancing toward gas and battery-hybrid pilots.
- Construction Sites:Rental fleet operators specify diesel portables for mobility and fuel logistics simplicity in emerging markets. India's secondary cities concentrate demand where distributed commercial construction outpaces centralized infrastructure. EPA Tier 4 Final certification costs are narrowing the addressable market for sub-10 kVA diesel products and accelerating gas pilot programs.
- Residential Backup:Homeowners in suburban North America and storm-exposed US coastal states specify automatic standby systems with methane or propane fuel.
- Remote Worksites:Mining exploration and oilfield services require skid-mounted or containerized solutions with extended fuel autonomy.
- Events:Temporary power for outdoor entertainment and exhibitions prioritizes rapid deployment and acoustic enclosure compliance.
Dominant by revenue: Telecommunications. Gaining share fastest: Residential Backup as methane infrastructure deepens.
End User:
Volume scale separates fragmented small business procurement from concentrated mobile operator fleet decisions.
- Mobile Operators:Telecom tower companies and wireless carriers aggregate sub-20 kVA generator demand across tens of thousands of sites. Reliance Jio, Indus Towers, and regional Southeast Asian operators specify standardized platforms for maintenance interoperability and spare parts pooling. Procurement concentration is displacing traditional dealer networks in favor of direct manufacturer channels and equipment lessors.
- Small Businesses:Retail, hospitality, and light manufacturing operators in India's tier-two and tier-three cities purchase through distributor networks with limited technical specification capability. Kirloskar and regional assemblers compete on manufacturing scale and channel penetration where brand recognition remains underdeveloped. Price sensitivity dominates over emissions certification or remote monitoring features.
- Agricultural Operations:Irrigation pump backup and cold chain protection drive seasonal demand with intermittent duty cycles.
- Emergency Services:Hospitals, fire stations, and disaster response teams mandate automatic start capability with regulatory compliance documentation.
- Recreational Users:RV owners and outdoor enthusiasts prioritize inverter technology for harmonic distortion below 5% and acoustic discretion.
Controlling procurement volume: Mobile Operators. Expanding most quickly: Small Businesses as India's secondary cities electrify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper winding production clusters in Jiangsu and Zhejiang provinces anchor Asian supply chains for alternator assemblies. Steel foundry capacity concentrates in Shandong and Hebei, feeding enclosure fabrication across the region. These material localities shape procurement geography for generator manufacturers worldwide.
United States
Suburban methane infrastructure expansion drives residential standby demand across Texas, Florida, and storm-exposed coastal states. EPA Tier 4 Final and CARB certification requirements elevate engineering barriers for diesel products below 10 kVA. Manufacturing and distribution concentrate in Wisconsin and the upper Midwest, where established power equipment fabricators maintain regional headquarters.
India
Telecom tower electrification and distributed commercial construction concentrate procurement in Maharashtra, Uttar Pradesh, and Karnataka. BIS emission norms under CEA directives force portfolio rebalancing toward gas and battery-hybrid pilots. Tier-two and tier-three distribution nodes in Gujarat and Tamil Nadu concentrate manufacturing scale advantages for domestic assemblers.
Germany
EU Stage V emissions standards and F-Gas Regulation redirect R&D spending toward certified gas architectures and bi-fuel systems. Industrial standby demand clusters in Baden-Württemberg and North Rhine-Westphalia, where manufacturing automation requires harmonic-sensitive power quality. Bavaria anchors precision engineering capabilities for digital control integration.
China
Engine block foundry capacity in Shandong and Hebei provinces supplies domestic and export markets for sub-20 kVA diesel platforms. GB standards and dual carbon goals under MEE direction compress pure-diesel product lifecycles. Yangtze River Delta manufacturing clusters in Jiangsu and Zhejiang dominate alternator winding and electronic control module production.
Brazil
Agricultural irrigation backup and cold chain electrification drive seasonal demand across São Paulo, Minas Gerais, and Rio Grande do Sul. ANVISA and national environmental regulator frameworks elevate compliance costs for imported diesel after-treatment systems. Equipment rental fleets in the Southeast region concentrate construction-phase procurement for distributed commercial projects.
Generator (Up to 20 Kva) Market Competitive Landscape
Capacity expansion dominates the current landscape as foundry and alternator winding investments harden supply positions. The vendor base stratifies across three tiers: integrated engine-alternator manufacturers with captive foundry networks, regional assemblers scaling through distributor channel control, and specialized inverter technology developers. M&A activity concentrates on digital control and remote monitoring capabilities. Geographic expansion into India's tier-three nodes represents the second dominant competitive vector.
Among integrated power equipment manufacturers, Cummins, Kohler, and Kirloskar occupy distinct archetype positions. Cummins exemplifies the vertically integrated model with captive engine production insulating margin exposure. Kohler represents premium-tier channel control through deep North American residential standby penetration. Kirloskar anchors manufacturing scale advantages across India's secondary city distribution networks. These three companies illustrate the strategic divergence between technology-led certification positioning and cost-led geographic expansion.
| Leading Market Players |
|---|
| Cummins |
| Caterpillar |
| Kohler |
| Generac Power Systems |
| Kirloskar |
| Doosan |
| Honda |
| Weichai |
| Atlas Copco |
| Others |
Supply & Pricing Matrix
Copper price indices on the London Metal Exchange cascade through alternator winding costs into three distinct procurement tiers for sub-20 kVA equipment. Steel benchmark volatility from Chinese futures markets feeds enclosure fabrication expenses, compressing margin pools for fixed-price contract holders and forcing portfolio rebalancing toward gas architectures with lower material intensity.
Pricing Analysis
Warranty bundling separates premium digital-control systems with predictive maintenance alerts from unbundled economy portables carrying limited coverage. Three-tier pricing structure across premium, standard, and economy levels reflects EPA Tier 4 Final certification costs and remote monitoring capability. Pricing pressure stems from copper and steel commodity swings squeezing fixed-contract margins. Small businesses in India's tier-three cities exhibit highest price sensitivity, while telecom tower operators prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Engine block supply rests on foundry capacity clusters in Shandong and Hebei provinces, with alternator winding production anchored in Jiangsu and Zhejiang. Copper magnet wire, laminated steel cores, and electronic control modules constitute critical input dependencies. Single-source vulnerability concentrates in Chinese foundry networks exposed to regional logistics disruptions and tariff exposure. Distribution runs through direct manufacturer channels displacing traditional dealer networks for large fleet orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around emissions compliance capabilities, with EPA Tier 4 Final and EU Stage V deadlines forcing weaker diesel-dependent assemblers toward exit or acquisition.
For Market Incumbents: Deepen captive engine foundry integration to insulate margin pools from commodity volatility and foundry supply disruption. Accelerate bi-fuel certification pipelines before pure-diesel revenue streams face accelerated obsolescence under tightening BIS emission norms. Prioritize digital control R&D to capture premium positioning where telecom operators consolidate procurement.
For New Entrants and Emerging Players: Direct-to-tower-operator digital channels offer white-space entry around India's tier-three distribution nodes where channel control remains underdeveloped. Target gas standby configurations in suburban North America as methane infrastructure penetration deepens. Lead with inverter technology convergence for recreational vehicle manufacturers seeking harmonic distortion below five percent.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional assemblers with manufacturing scale advantages in India's secondary cities but lacking emissions certification capabilities. Long-term viability hinges on gas and battery-hybrid architecture transitions over the next decade. Monitor EPA and EU regulatory phase-in calendars as inflection indicators for diesel asset obsolescence acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Bi-Fuel Certification Investment | Single-ECU diesel-gas architectures capture expanding margin pools as methane infrastructure penetrates suburban North America. |
| Backward Integration into Foundry Capacity | Captive engine block production insulates margin exposure from Shandong and Hebei supply concentration risks. |
| Digital Control Platform Development | Microprocessor-based governors enable remote fleet management for telecom tower operators consolidating procurement decisions. |
| Channel Expansion into Tier-Three Nodes | Direct manufacturer relationships displace traditional dealer networks where India's small business electrification concentrates demand. |
| Battery-Hybrid Pilot Programs | Construction rental fleets accelerate gas and battery-hybrid adoption as EPA Tier 4 Final costs narrow diesel addressable markets. |
Research Methodology
Trade flow databases, customs records, and SEC 10-K filings formed the secondary backbone, cross-referenced with primary interviews involving maintenance directors at telecom tower operators, procurement leads at construction rental fleets, plant engineers at foundry facilities, and aftermarket service heads at regional distributors. Bottom-up unit shipment tallies by product type and technology tier were triangulated against top-down value estimates derived from reported revenue disclosures and import-export parity analysis.
Bottom-up modeling tracked diesel, gas, portable, standby, inverter, and bi-fuel product categories across digital control, AVR system, brushless, synchronous, and asynchronous technology tiers. Top-down validation referenced telecommunications, construction sites, residential backup, remote worksites, and events applications segmented by mobile operators, small businesses, agricultural operations, emergency services, and recreational users. CAGRs were derived from regression analysis of historical shipment trajectories against regulatory phase-in calendars and infrastructure buildout timelines.
The model holds under steady emissions compliance enforcement and commodity price regime stability; deviation in regulatory acceleration or foundry supply disruption would shift volume trajectories. A small set of named triggers—EPA Tier 4 Final deadline adjustments, EU Stage V enforcement intensity, and Chinese foundry capacity utilization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Generator Sales Market
Generators
Asia-Pacific Portable Generator Market
Generators
South America Diesel Generator Market
Generators
Asia-Pacific Generator Sets Market
Generators
Dual-Fuel Generator Market
Generators
Halogenerator Market
Generators
Construction Generator Sets Market
Generators
Saudi Arabia Diesel Generator Market
Generators
US Generator Sales Market
Generators
Gas Generator Market
Generators
North America Gas Generator Market
Generators
South Africa Diesel Generator Market
Generators
South America Gas Generator Market
Generators
United States Portable Generator Market
Generators
Power Generator for Military Market
Generators
Turbo Generator Market