
 Dual-Fuel Generator Market | 2026-2036
Dual-Fuel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Dual-Fuel Generator Market Foresight
Asian manufacturing clusters is pivoting toward dual-fuel assembly lines to serve North American and European demand for flexible backup power. Cummins leverages its integrated engine-generator architecture to dominate the industrial standby segment. Caterpillar sustains its position through captive distribution networks and field service density in mining and oilfield applications. Kohler Co. anchors the premium residential market with propane-natural gas flexibility and automatic transfer switch integration.
A dual-fuel generator employs a combustion engine engineered to operate on two distinct fuel sources, typically diesel paired with natural gas or propane, with electronic fuel blending systems that modulate the diesel-to-gas ratio across load conditions to optimize emissions and fuel cost. These units serve critical commercial and industrial functions where fuel supply redundancy prevents operational shutdown during primary fuel disruptions or grid failure. The standby deployment category leads value generation due to mandatory backup requirements in healthcare, data center, and telecommunications infrastructure codes. Portable units represent the fastest-growing product type as construction contractors and emergency response agencies prioritize mobility combined with fuel flexibility. The industrial segment commands the deepest margin pools owing to custom engineering, extended service contracts, and integration with facility control systems.
EPA Tier 4 Final regulations and CARB certification frameworks in the United States mandate particulate matter and nitrogen oxide limits that dual-fuel systems must satisfy through optimized combustion calibration or after-treatment integration. The EU F-Gas Regulation and CE marking requirements shape market access for imported equipment across European member states by enforcing emission disclosure and refrigerant containment standards in packaged generator sets. Stakeholders must monitor evolving grid interconnection standards and carbon intensity reporting rules that will determine which fuel blending ratios and control architectures qualify for clean energy procurement preferences.
Market Dynamics
EPA Tier 4 Final emission standards and CARB certification requirements are compressing diesel-only product lifecycles while elevating dual-fuel architectures to default specification in commercial standby procurement across the United States.
Growth Catalysts
- Healthcare infrastructure codes:Joint Commission accreditation standards mandate backup power redundancy for acute care facilities, forcing hospital operators toward dual-fuel systems that eliminate single-point fuel failure risks.
- Grid instability concentration:ERCOT reliability challenges in Texas, PSPS events in California, and hurricane exposure in Florida create concentrated demand pockets where fuel flexibility commands premium positioning.
- Data center Tier III/IV certification:Uptime Institute requirements for continuous operation during utility disruption accelerate adoption of generators capable of automatic fuel source switching without load interruption.
Market Restraints
- After-treatment cost inflation:Diesel particulate filters and selective catalytic reduction systems required for EPA compliance add material cost burden that compresses margin pools on sub-500kW units.
- Natural gas infrastructure gaps:Rural commercial sites and remote industrial installations lack pipeline connectivity, constraining addressable market for gas-dependent dual-fuel configurations.
- Propane supply seasonality:Agricultural demand spikes during planting and harvest seasons create regional price volatility that undermines fuel cost predictability for propane-primary operators.
Strategic Opportunities
- Microgrid integration:Solar-plus-storage hybridization with dual-fuel backup creates island-capable systems for military installations and critical infrastructure operators seeking energy independence.
- Carbon intensity reporting:Corporate sustainability frameworks that track Scope 1 emissions create procurement preference for natural gas blending ratios that reduce diesel consumption during test cycles.
- Portable rental fleet conversion:Construction equipment lessors are replacing single-fuel mobile units with dual-fuel models to serve contractors facing varying fuel availability across dispersed job sites.
Industry Challenges
- Combustion calibration expertise:Electronic fuel ratio modulation requires specialized technicians trained in both diesel engine management and gas carburetion systems, creating hiring bottlenecks for service networks.
- Legacy control system interoperability:Facility building management systems using Modbus or BACnet protocols demand custom gateway development for seamless generator integration, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual-Fuel Generator Market |
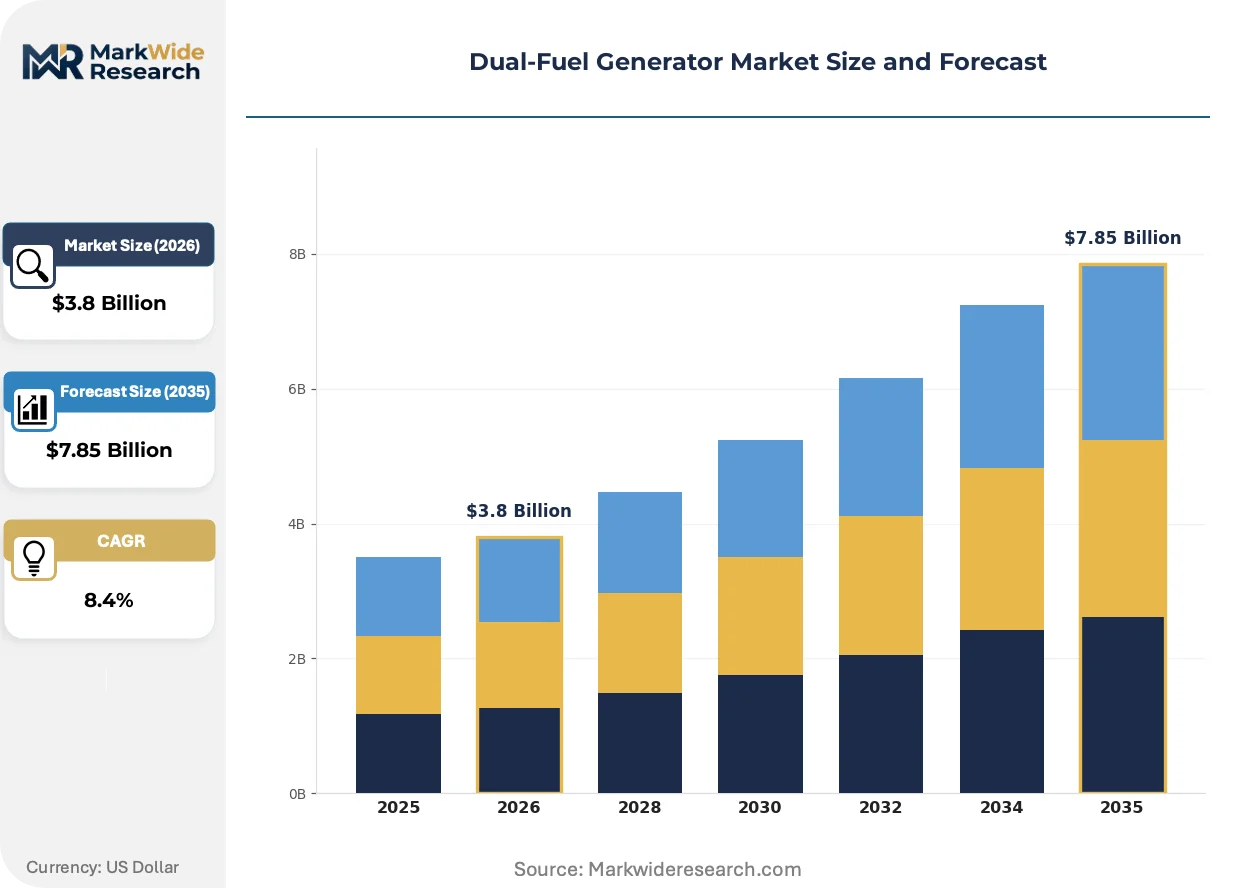
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Industrial, Residential Fuel Type: Gasoline, Diesel, Propane, Natural Gas End User: Construction, Agriculture, Emergency Services, Marine Deployment: Onshore, Offshore, Remote Sites, Utility Backup |
| Companies Covered | Caterpillar, Cummins, Generac Power Systems, Kohler Co., Champion Power Equipment, DuroMax Power Equipment, Westinghouse Electric Corporation, Honda Motor Co., Ltd., Briggs & Stratton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual-Fuel Generator Market Shifts & Advancements
Digital fuel blending algorithms and predictive load management are compressing the performance gap between dedicated diesel and dual-fuel architectures in high-variability applications.
Adaptive injection mapping is rewriting combustion efficiency benchmarks. Electronic control modules now modulate diesel pilot injection timing across 5-95% gas substitution ratios based on real-time exhaust oxygen feedback. Data center operators in Virginia and Illinois are specifying these systems for N+1 redundancy configurations. The technology is rewriting procurement specifications by eliminating the historical 15% derate penalty that constrained dual-fuel adoption in prime power applications.
CARB certification pathways for mobile agricultural equipment are tightening particulate matter testing protocols. Manufacturers must now demonstrate compliance across transient load cycles that simulate actual field operation rather than steady-state laboratory conditions. Portable generator lines targeting California construction markets face redesign imperatives that favor dual-fuel architectures with lower baseline PM emissions.
Service contract unbundling is fragmenting traditional vendor-customer relationships. End-users in the telecommunications sector are separating preventive maintenance from emergency response coverage, awarding these components to specialized regional providers rather than factory-authorized distributors. This pattern is most pronounced in Texas and Florida where storm seasonality creates surge demand that strains captive service networks.
Dual-Fuel Generator Market Segmentation
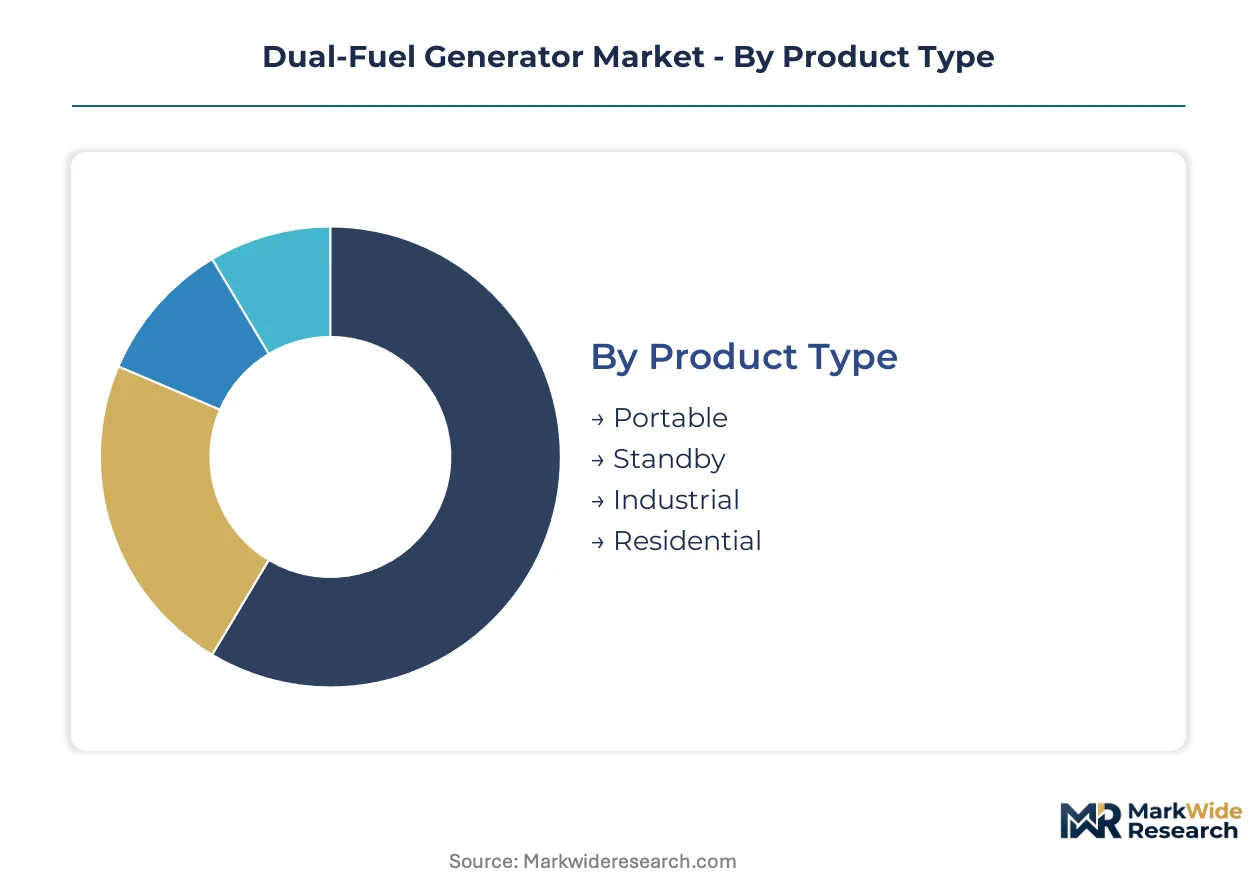
Dual-fuel generator procurement patterns diverge sharply across deployment contexts, with standby installations commanding premium engineering while portable units drive volume expansion. Equipment specification varies by fuel access infrastructure, emission zone classification, and load profile predictability.
Product Type:
Replacement cycles accelerate where EPA Tier 4 Final compliance deadlines force early retirement of diesel-only legacy fleets.
- Standby:Fixed installations engineered for automatic load transfer during grid failure, sized 50kW to 2MW. Hospital operators in Texas and California specify these for Joint Commission accreditation, with propane-natural gas flexibility eliminating single-point fuel failure.
- Portable:Mobile units mounted on trailers or skids for construction and emergency response. Rental fleet operators in Florida are converting single-fuel inventories to dual-fuel configurations to serve contractors facing dispersed job site fuel availability.
- Industrial:Custom-engineered prime power systems with extended service contracts and facility control integration. Mining and oilfield applications in remote locations specify these for 24/7 operation with diesel backup when pipeline gas is interrupted.
- Residential:Smaller units below 50kW with automatic transfer switch integration. Premium suburban markets in hurricane-exposed coastal counties favor propane flexibility when natural gas service fails during storm recovery.
Volume placements concentrate in Standby; the faster expansion belongs to Portable.
Fuel Type:
Cost tier differentiation separates pipeline-connected urban sites from remote locations dependent on delivered fuels.
- Natural Gas:Primary fuel for commercial standby systems with pipeline access, offering lower carbon intensity per kWh than diesel-only operation. Data center operators in Virginia and Illinois specify high gas-substitution ratios for Scope 1 emissions reporting.
- Diesel:Pilot fuel and backup energy source providing combustion ignition and full-load capability during gas supply interruption. Remote industrial sites without pipeline connectivity maintain diesel-primary configurations despite after-treatment cost inflation.
- Propane:Delivered fuel stored on-site for facilities lacking natural gas infrastructure. Agricultural operations in the Midwest face seasonal price volatility during planting and harvest demand spikes.
- Gasoline:Limited to small portable units below 10kW where fuel availability trumps efficiency considerations. Emergency services stockpile gasoline-compatible units for disaster response where supply chain disruption is probable.
Procurement volume clusters around Natural Gas configurations; Propane is climbing the fastest as rural commercial addressable market expands.
End User:
Application-specific duty cycles determine fuel blending ratio optimization and maintenance interval specification.
- Construction:Intermittent high-load operation at dispersed sites with unpredictable fuel access. Contractors in California facing CARB mobile equipment regulations are specifying dual-fuel portable units to meet transient load cycle testing protocols.
- Emergency Services:Critical load requirements with zero-tolerance for fuel supply interruption. Fire departments and medical response agencies prioritize automatic fuel source switching without operator intervention.
- Agriculture:Seasonal operation aligned with irrigation and processing schedules. Dairy and poultry operations in Texas install standby units to maintain ventilation and refrigeration during grid instability events.
- Marine:Vessel propulsion and auxiliary power with MARPOL emission zone compliance requirements. Harbor craft operators in Florida and Louisiana specify dual-fuel architectures for port entry permissions in regulated zones.
Equipment shipments concentrate in Construction; Emergency Services represents the steepest expansion trajectory as disaster preparedness funding increases.
Deployment:
Geographic isolation and grid reliability variance create distinct specification requirements across installation contexts.
- Utility Backup:Grid-connected commercial and industrial facilities requiring seamless transition during outage. ERCOT reliability challenges in Texas accelerate procurement for manufacturing and healthcare facilities.
- Remote Sites:Off-grid installations lacking utility infrastructure, common in mining and oilfield extraction. These locations demand diesel-primary configurations with gas blending where LNG or CNG delivery is economically viable.
- Onshore:Land-based installations with standard foundation and ventilation requirements. Data center campuses in Illinois and Virginia specify N+1 redundancy with dual-fuel generators as default.
- Offshore:Platform and vessel applications with space constraints and salt exposure specifications. Gulf of Mexico operators require marine-grade enclosures and enhanced corrosion protection.
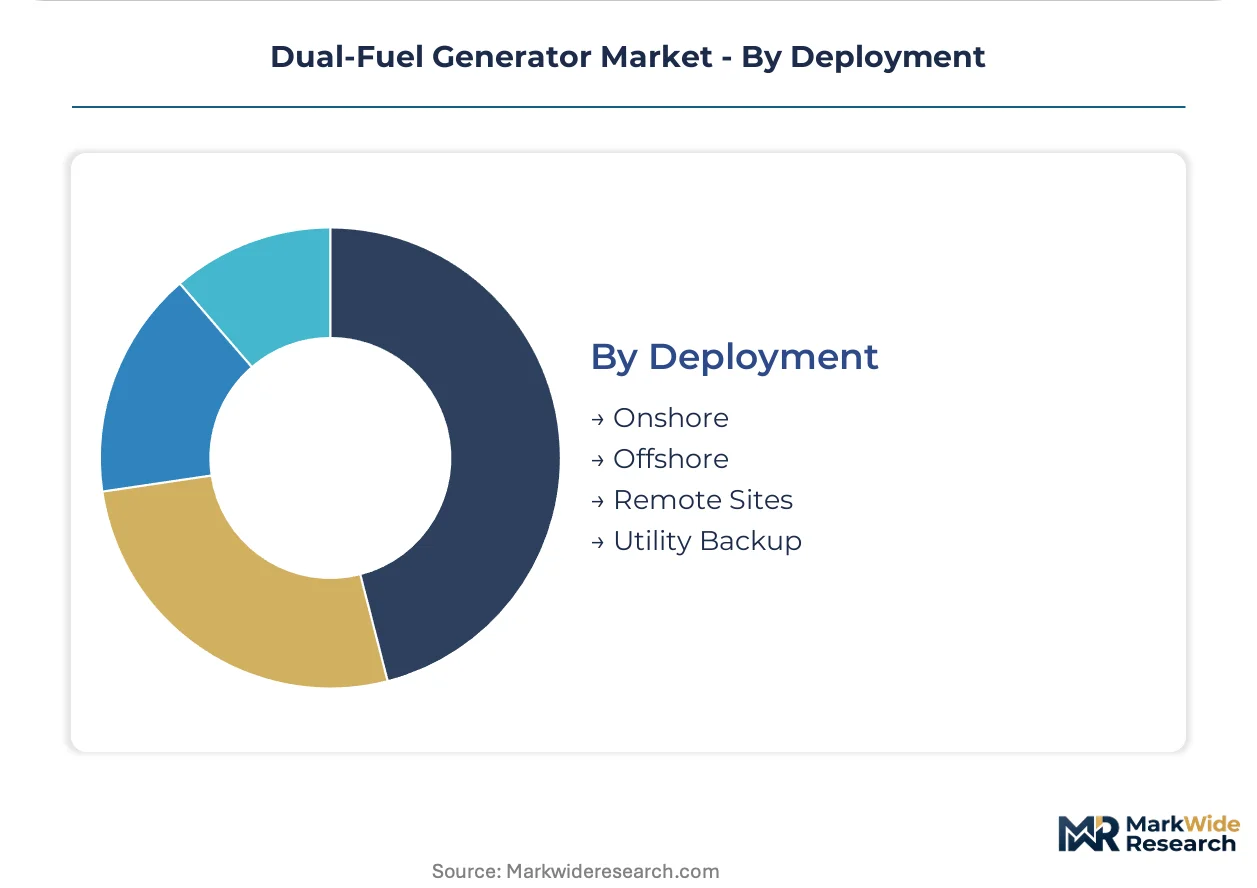
Deployment activity centers on Utility Backup; Remote Sites are gaining share fastest as distributed energy investment extends to isolated industrial operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural gas pipeline networks anchor demand geography for dual-fuel generator deployment, with grid reliability variance and emission zone classification determining specification intensity across markets.
United States
Texas ERCOT reliability challenges and California PSPS events concentrate commercial standby procurement. EPA Tier 4 Final standards and CARB certification frameworks mandate particulate matter limits that favor dual-fuel architectures over diesel-only legacy fleets. Data center campuses in Virginia and Illinois specify N+1 redundancy configurations with automatic fuel source switching.
Germany
Industrial manufacturing clusters and chemical processing facilities drive prime power demand with carbon intensity reporting requirements. EU F-Gas Regulation and CE marking standards enforce emission disclosure for packaged generator sets. The Ruhr industrial corridor and Bavarian manufacturing belt anchor deployment for combined heat and power applications.
China
Data center construction in the Yangtze River Delta and Pearl River Delta accelerates backup power procurement. MIIT energy efficiency standards and GB emission classifications shape product design for domestic manufacturers. Shanghai and Shenzhen municipal governments enforce building code provisions for critical infrastructure redundancy.
Japan
Semiconductor fabrication facilities and pharmaceutical manufacturing plants require zero-interruption power continuity. METI industrial safety regulations and JIS standards govern standby system certification. The Kansai region around Osaka and the Chubu industrial zone near Nagoya concentrate high-reliability installations.
India
Telecommunications infrastructure expansion and healthcare facility accreditation drive standby generator adoption. CEA grid connectivity standards and BIS certification requirements apply to imported and domestically manufactured equipment. Maharashtra and Karnataka state industrial corridors anchor manufacturing cluster deployment for export-oriented units.
Dual-Fuel Generator Market Competitive Landscape
Global majors compete with regional champions across technology integration and service network density. The vendor base separates into three tiers: integrated engine-generator architects with captive distribution, specialized component suppliers licensing combustion control systems, and regional assemblers serving price-sensitive portable segments. Two dominant competitive moves define current positioning: M&A activity targeting electronic fuel blending software capabilities, and geographic expansion of field service networks into storm-exposed coastal counties.
Within the integrated-system tier, Caterpillar and Cummins exemplify divergent strategic positioning. Caterpillar occupies a position anchored in mining and oilfield applications through field service density in remote extraction zones. Cummins represents the industrial standby vector with engine-generator architecture optimized for healthcare and data center specifications. Generac Power Systems sits within the residential and light commercial segment, exemplifying automatic transfer switch integration and propane flexibility for suburban backup power markets.
| Leading Market Players |
|---|
| Caterpillar |
| Cummins |
| Generac Power Systems |
| Kohler Co. |
| Champion Power Equipment |
| DuroMax Power Equipment |
| Westinghouse Electric Corporation |
| Honda Motor Co., Ltd. |
| Briggs & Stratton |
| Others |
Supply & Pricing Matrix
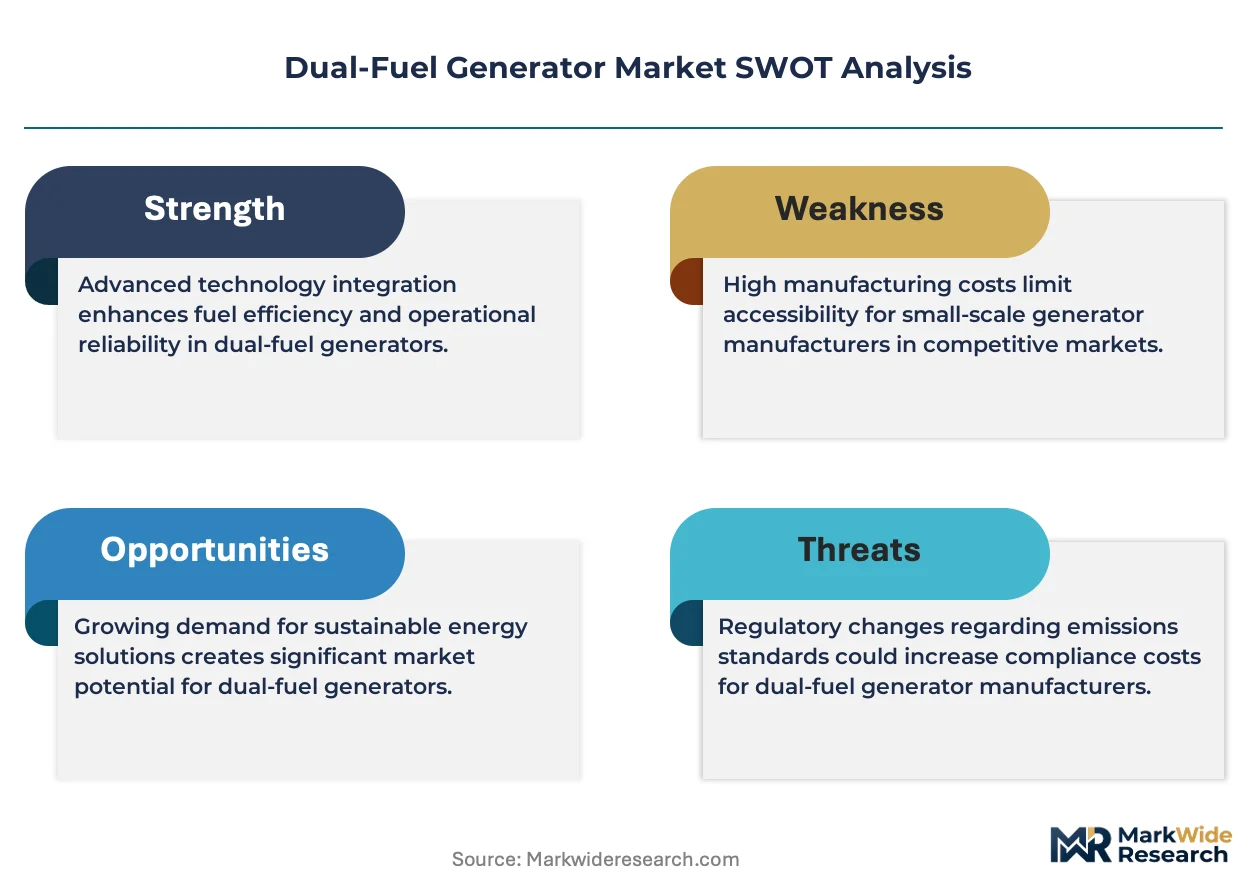
Adaptive injection mapping and electronic fuel ratio modulation are compressing manufacturing cost differentials between dedicated diesel and dual-fuel architectures while concentrating production expertise among Tier 1 engine houses with captive combustion calibration capabilities. EPA Tier 4 Final after-treatment requirements and CARB certification complexity are simultaneously elevating engineering cost floors and squeezing margin pools for sub-500kW product lines.
Pricing Analysis
Warranty and preventive maintenance unbundling is fragmenting traditional vendor-customer relationships across the telecommunications and data center segments. Three-tier pricing structure across premium, standard, and economy levels separates factory-authorized service networks from regional independent providers, with certification grade and geographic delivery cost as primary differentiation drivers. Price erosion runs through the portable rental fleet segment as construction equipment lessors convert inventories at volume. Healthcare operators demonstrate lowest price sensitivity due to Joint Commission accreditation mandates, while agricultural buyers face acute sensitivity during propane supply seasonality.
Supply Chain Analysis
Domestic-content mandates under the Inflation Reduction Act and Buy American provisions are reshaping component sourcing for federally funded infrastructure projects. Manufacturing concentration centers on the United States, China, and Germany, with electronic control modules and selective catalytic reduction systems as critical imported inputs. Supply chain risk hinges on single-source vulnerability for specialized gas carburetion components. Distribution runs through captive dealer networks for industrial standby systems and independent rental channels for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual-fuel generator procurement functions as a cost-of-compliance story where EPA Tier 4 Final and CARB certification frameworks erect barrier-to-entry moats that protect incumbents with established after-treatment integration capabilities.
For Market Incumbents: Hedge diesel-primary exposure by accelerating electronic fuel blending software acquisitions and expanding field service density in ERCOT-served Texas counties where grid instability concentrates demand. Defend against specialized component suppliers licensing combustion control systems by deepening backward integration into electronic control module production. For New Entrants and Emerging Players: CARB certification pathways for mobile agricultural equipment in California open a window for portable dual-fuel architectures designed to transient load cycle testing protocols. Target construction contractors facing dispersed job site fuel availability with rental fleet conversion programs. Pursue go-to-market partnerships with regional equipment lessors rather than competing against captive distribution networks. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated engine-generator architects seeking electronic fuel blending capabilities. Long-term viability favors targets with demonstrated CARB certification execution and established service contracts in healthcare or data center verticals. Watch EPA enforcement patterns around diesel-only legacy fleet retirement timelines as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electronic Fuel Blending Software Acquisition | Cummins and Caterpillar are consolidating combustion control expertise through targeted technology purchases. |
| Field Service Network Expansion | Storm-exposed coastal counties in Florida and Texas demand emergency response coverage that strains captive networks. |
| CARB Certification Investment | California construction markets require transient load cycle compliance that favors redesigned dual-fuel architectures. |
| Microgrid Integration Partnership | Military installations seek island-capable solar-plus-storage hybridization with dual-fuel backup systems. |
| Portable Rental Fleet Conversion | Construction equipment lessors replace single-fuel inventories to serve contractors facing variable fuel access. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combined with EPA enforcement databases, CARB certification registries, EIA power reliability statistics, and Joint Commission accreditation records. Bottom-up equipment shipment tracking and top-down market sizing triangulated volume estimates across product categories.
Data-stream reconciliation applied a structured analytical framework across the projection horizon. Segmentation dimensions modeled include product type, fuel configuration, end-use application, deployment context, and regional regulatory cluster. CAGRs derived from replacement cycle analysis, compliance deadline scheduling, and infrastructure investment patterns. Grid reliability variance in ERCOT and PSPS event frequency in California served as location-specific demand inputs.
Caveats apply where EPA enforcement intensity, natural gas pipeline expansion timelines, or carbon intensity reporting rule evolution could materially shift the outlook. Forecasts reflect assumptions around regulatory compliance cost pass-through and substitution elasticity between dual-fuel and diesel-only architectures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Europe Diesel Generator Market
Generators
North America Gasoline Gensets Market
Generators
Digital Inverter Generator Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
South America and Africa Diesel Generator Market
Generators
Europe Gas Turbine Market
Generators
Middle East Portable Generator Market
Generators
Gas Generator Market
Generators
Generator [Up to 100 Kva] Market
Generators
South America Portable Generator Market
Generators
China Gas Generator Market
Generators
Turbo Generator Market
Generators
Emergency Power Generators Sales Market
Generators
Gulf Cooperation Council (GCC) Diesel Generator Market
Generators
Asia Pacific Electric Generators Market
Generators
Residential Generators Market