
 Southeast Asia Battery Market | 2026-2036
Southeast Asia Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Battery Market Analytics
Project finance tied to integrated nickel-to-cell complexes is narrowing the field of viable competitors in Southeast Asia. CATL leverages its Indonesian smelter partnerships to anchor cathode supply chains across the archipelago. Samsung SDI competes through specialized cylindrical cell production targeting premium automotive programs in Thailand. Gotion High-tech sustains cost positioning via direct lithium extraction agreements with Vietnamese mineral developers.
Southeast Asia batteries are electrochemical energy storage devices comprising anode, cathode, electrolyte, and separator assemblies, typically delivering voltages from 1.2V to 800V depending on series configuration and chemistry, designed to convert stored chemical energy into electrical power for motive, stationary, or portable applications. Lithium-ion chemistry dominates value creation due to superior energy density and cycle life, while lead-acid retains share in commercial backup power where capital constraints outweigh performance requirements. Electric vehicle application demand outpaces other segments as Thai and Indonesian OEM assembly capacity expands, and solid-state technology R&D concentrates in South Korean and Japanese parent labs with pilot transfer planned for regional subsidiaries.
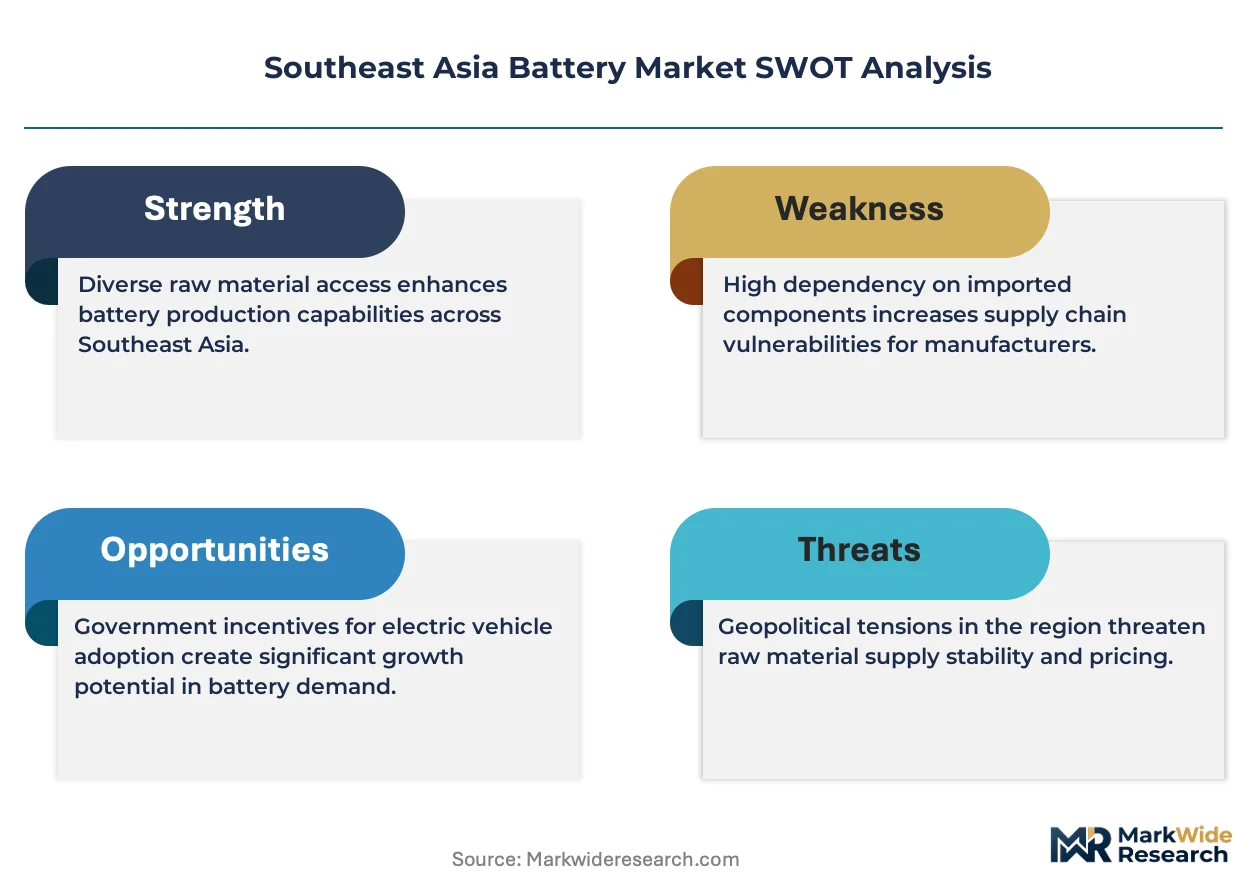
Indonesia's Ministry of Industry enforces local content thresholds for EV incentives, while Thailand's Board of Investment structures tax holidays contingent on domestic cell assembly, and Vietnam's Ministry of Natural Resources and Environment imposes waste battery recovery mandates that reshape aftermarket economics. EMA-equivalent ASEAN harmonization discussions remain stalled, perpetuating fragmented certification burdens. Stakeholders must track which national regulator moves first on unified safety standards to preempt compliance cost escalation.
Market Dynamics
Indonesia's nickel processing corridors and Vietnam's cathode material plants are concentrating regional cell manufacturing investment, forcing fleet operators and project developers to co-locate with upstream refining assets to secure incentive-compliant supply chains.
Growth Catalysts
- Local Content Thresholds:Indonesia's Ministry of Industry enforces domestic assembly requirements for EV tax incentives, compelling pack integrators to establish in-country production facilities.
- Thai Assembly Expansion:Board of Investment tax holidays contingent on domestic cell assembly are pulling cathode active material producers into Eastern Economic Corridor industrial zones.
- Lithium Extraction Partnerships:Direct offtake agreements with Vietnamese mineral developers are securing feedstock for mid-tier cell producers outside Chinese supply orbits.
Market Restraints
- Nickel Price Volatility:London Metal Exchange nickel contract swings disrupt project finance calculations for Indonesian integrated smelter-to-cell complexes.
- Single-Source Cathode Dependence:NCM precursor supply concentrates in Chinese-owned Indonesian facilities, creating concentration risk for non-Chinese pack assemblers.
- Technical Limitation:Solid-state electrolyte manufacturing remains confined to South Korean and Japanese parent labs, delaying regional pilot transfer timelines.
Strategic Opportunities
- Philippines Grid Storage:Islanded archipelago geography creates natural demand for battery-plus-solar microgrids underserved by mainland Asian suppliers.
- Battery Passport Mandates:EU Battery Regulation upstream traceability requirements are opening compliance service niches for Southeast Asian certification bodies.
- Second-Life EV Packs:Thai and Indonesian commercial and industrial power backup applications are absorbing retired automotive modules before formal recycling infrastructure matures.
Industry Challenges
- Electrochemical Engineering Talent:Regional universities produce insufficient cell design and manufacturing process engineers, forcing producers to import South Korean and Japanese technical staff.
- EMA-Equivalent Harmonization Delays:Stalled ASEAN safety standard unification perpetuates fragmented certification burdens, extending product launch timelines across member states.
- Legacy Lead-Acid Infrastructure:Commercial backup power incumbents resist lithium-ion migration due to stranded distributor inventory and technician retraining costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Battery Market |
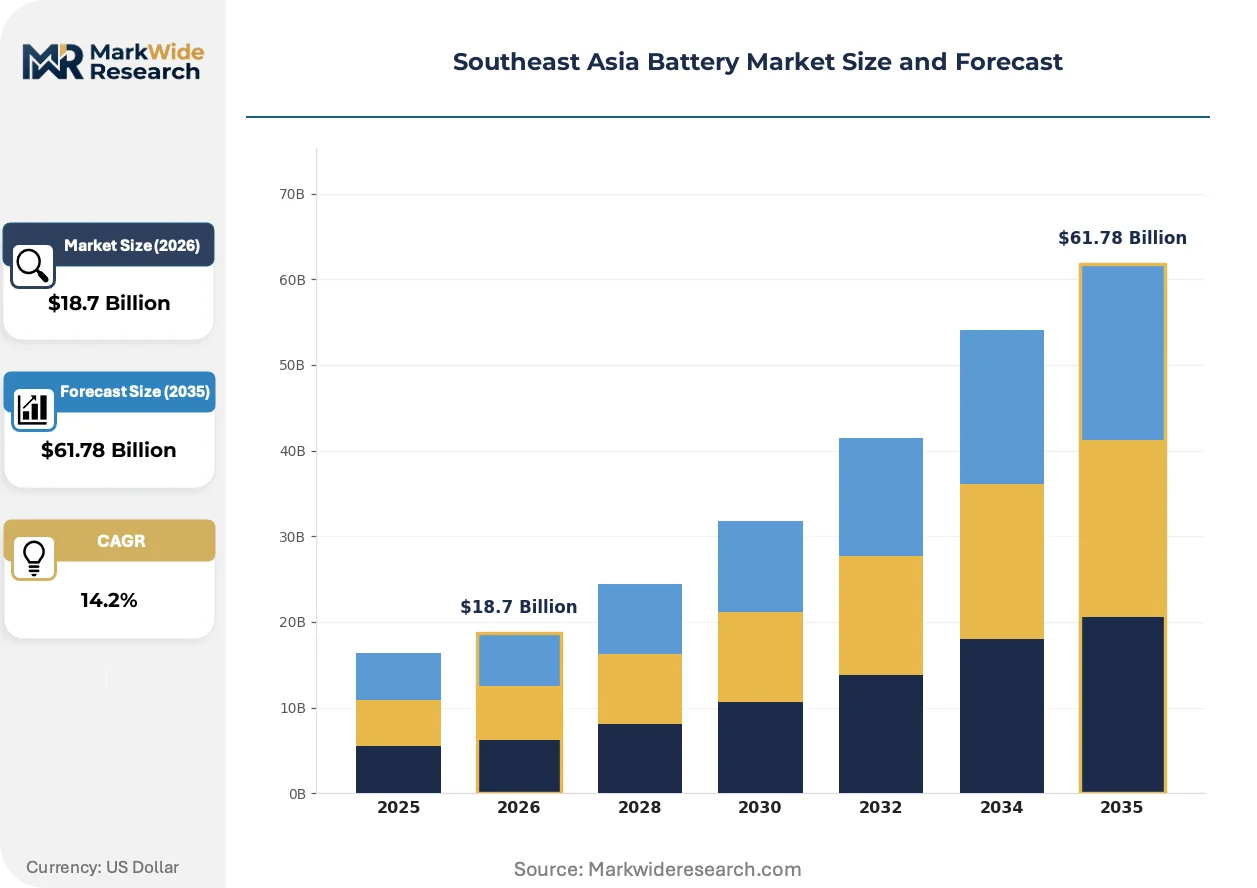
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Flow Batteries Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Use End User: Residential, Commercial, Automotive, Utilities Technology: Solid State, Hybrid, Fuel Cell, Others |
| Companies Covered | BYD, GS Yuasa, CATL, REPT Battero, Gotion High-tech, LG Energy Solution, Panasonic Holdings, Clarios, Samsung SDI, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Battery Market Evolving Landscape
Solid-state and semi-solid electrolyte research is accelerating competitive positioning shifts, while regulatory fragmentation and procurement model evolution are rewriting how cell producers access Southeast Asian offtake.
Semi-solid lithium-metal cells are hybridizing conventional liquid electrolyte manufacturing with gel-polymer separators to bridge energy density gaps. Thai premium automotive programs are piloting these packs for luxury EV platforms requiring extended range without solid-state production scale. The technology is hybridizing cost-performance tradeoffs between incumbent NCM cylindrical formats and next-generation solid-state architectures.
Indonesia's Ministry of Industry local content thresholds are tightening eligibility for national EV incentive schemes, forcing cathode precursor producers to co-locate smelting and refining operations with cell assembly plants. Battery-grade nickel sulfate and MHP conversion facilities must now demonstrate domestic value-add percentages to qualify downstream pack integrators for tax holidays. Thai and Vietnamese OEM assembly subsidiaries are responding by restructuring procurement contracts to exclude Chinese-traded intermediate materials.
Fleet operators in Thailand and Indonesia are consolidating lithium-ion pack procurement through multi-year supply agreements with integrated nickel-to-cell producers, displacing spot-market purchasing through trading houses. This concentration is compressing distributor margins and forcing independent pack assemblers to specialize in aftermarket retrofit applications. The shift is most visible in Bangkok and Jakarta commercial EV deployment programs where total cost of ownership guarantees now dominate supplier selection criteria.
Southeast Asia Battery Market Segmentation
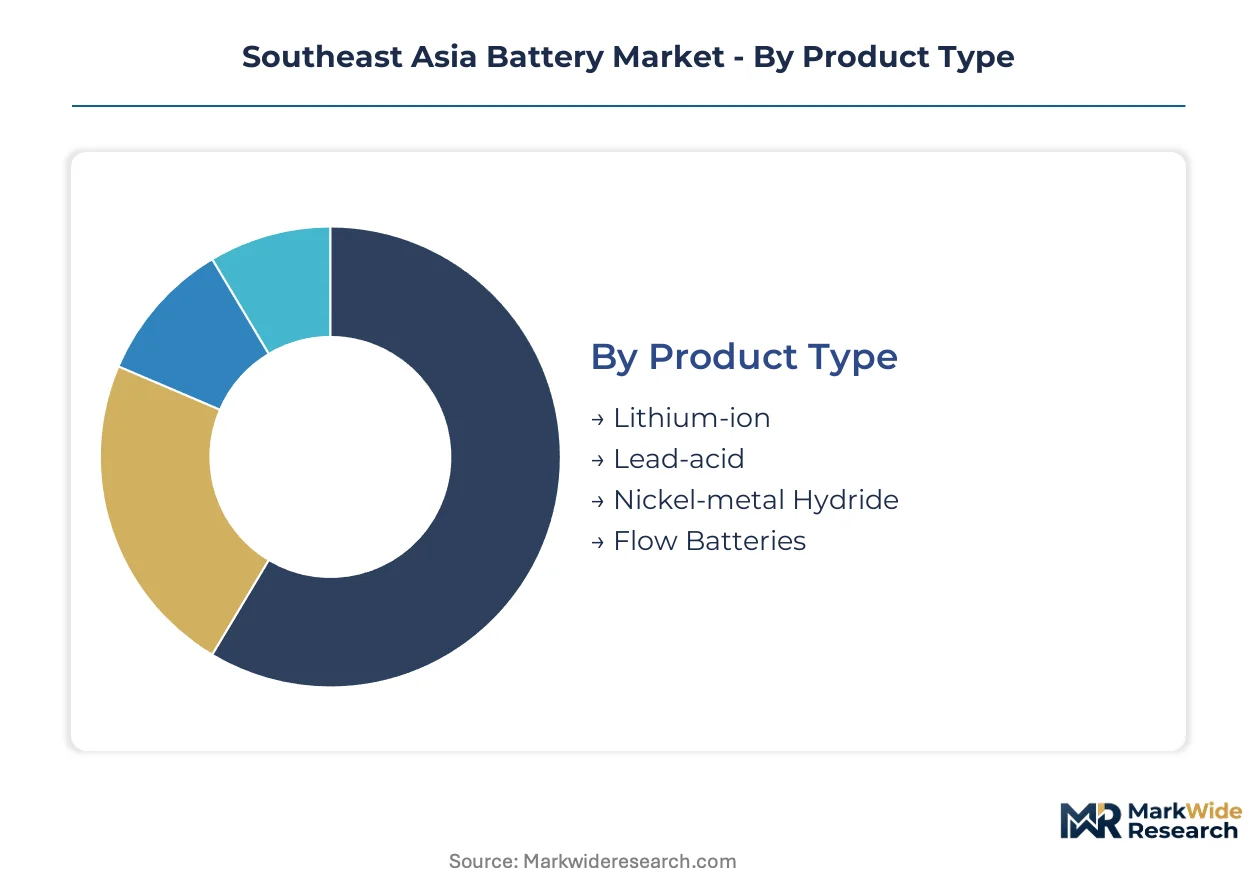
Battery procurement patterns across Southeast Asia diverge sharply by chemistry cost structure and application voltage requirements. Fleet operators, grid developers, and consumer OEMs each impose distinct performance specifications that reshape manufacturing priorities.
Product Type:
Cost tier positioning determines which chemistries capture volume versus margin in regional assembly plants.
- Lithium-ion:NCM and LFP cathode formulations deliver 150-300 Wh/kg energy density for electric vehicle traction and grid-scale storage. Thai and Indonesian OEM assembly lines are absorbing cylindrical and prismatic formats as local content rules harden.
- Lead-acid:Flooded and AGM variants provide 30-50 Wh/kg at one-fifth the lithium cost for commercial backup power. Vietnamese and Philippine distributor networks still move significant volume where capital constraints dominate procurement decisions.
- Nickel-metal Hydride:Mature hybrid vehicle auxiliary systems and low-temperature industrial applications in northern Vietnam and highland Thailand retain niche demand.
- Flow Batteries:Vanadium redox systems offer 4-8 hour discharge duration for islanded microgrids across the Philippine archipelago.
Lithium-ion holds installed capacity. Flow batteries are rotating up the share rankings.
Application:
End-use voltage and duty cycle requirements split manufacturing investment across motive, stationary, and portable demand pools.
- Electric Vehicles:400V-800V pack architectures dominate procurement from Thai and Indonesian fleet operators scaling under Board of Investment incentive windows. Battery management system integration and thermal runaway containment are non-negotiable specifications.
- Renewable Energy Storage:Containerized lithium-ion and emerging flow battery deployments absorb retired solar PV generation across Java and Luzon grids. Duration requirements above 4 hours favor non-lithium chemistries.
- Consumer Electronics:Cylindrical 18650 and 21700 formats power smartphones, laptops, and power tools through Vietnamese contract manufacturers serving regional distribution.
- Industrial Use:Forklift motive power and telecom backup systems in Malaysian and Singaporean logistics hubs specify lead-acid for cost or lithium-ion for cycle life.
Electric vehicles command capital allocation. Renewable energy storage is climbing the fastest.
End User:
Customer procurement scale and technical sophistication determine whether vendors sell cells, modules, or fully integrated systems.
- Automotive:Thai and Indonesian OEM subsidiaries negotiate multi-year pack supply agreements with nickel-to-cell integrated producers, displacing spot-market purchasing through trading houses.
- Utilities:State-owned PLN in Indonesia and EGAT in Thailand tender grid-scale storage with 15-20 year performance guarantees, favoring bankable suppliers with balance sheet depth.
- Commercial:Bangkok and Jakarta commercial and industrial power backup applications absorb second-life EV modules before formal recycling infrastructure matures.
- Residential:Solar-plus-storage adopters in suburban Malaysian and Vietnamese markets specify 5-15 kWh wall-mounted units through installer channels.
Automotive anchors procurement volume. Commercial is gaining share fastest.
Technology:
Manufacturing maturity and electrolyte architecture separate commercially available systems from pilot-stage platforms.
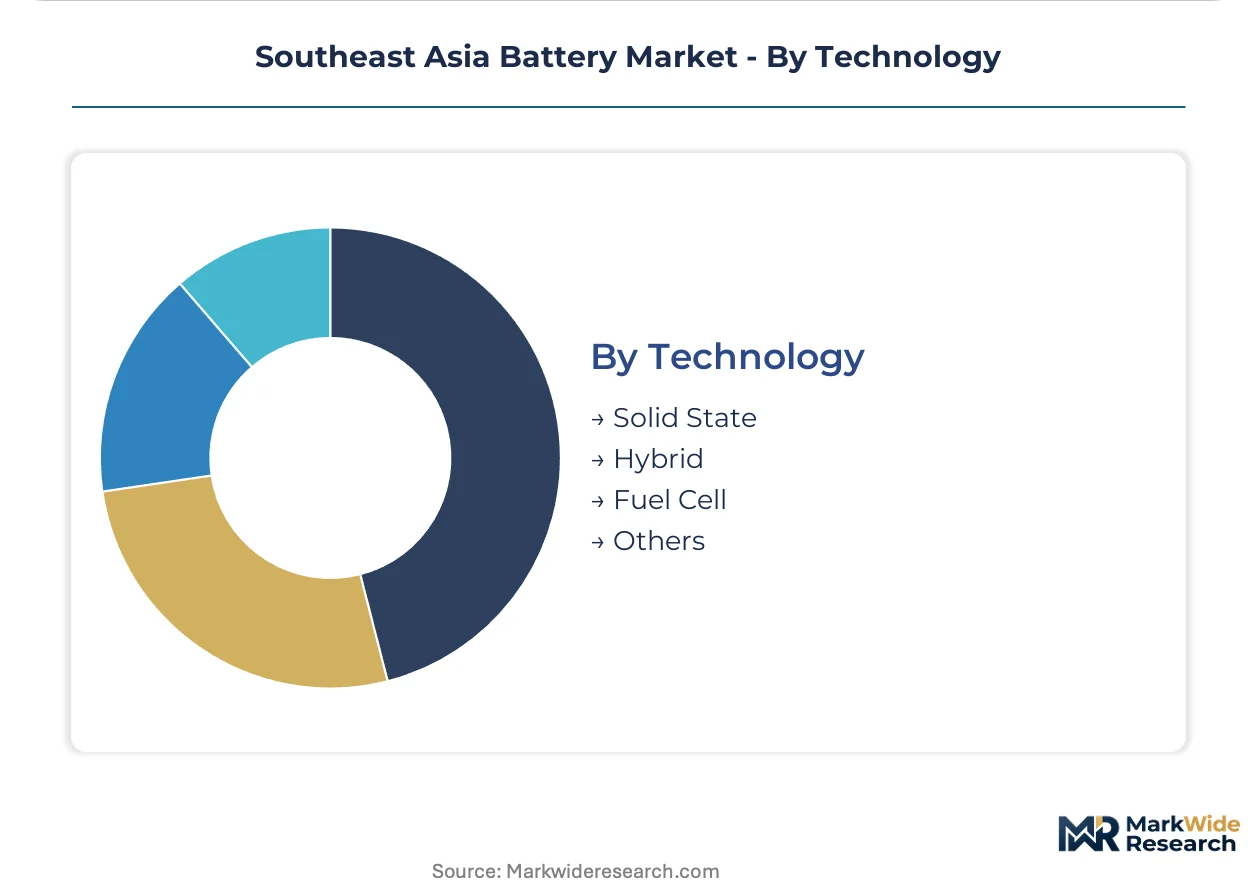
- Solid State:Sulfide and oxide electrolyte research remains concentrated in South Korean and Japanese parent laboratories, with regional pilot transfer timelines delayed by electrochemical engineering talent scarcity.
- Hybrid:Semi-solid lithium-metal cells with gel-polymer separators bridge energy density gaps for Thai premium automotive programs requiring extended range without solid-state production scale.
- Fuel Cell:Proton exchange membrane systems for heavy-duty trucking corridors between Bangkok and Laem Chabang port retain development interest despite hydrogen infrastructure gaps.
- Others:Sodium-ion and aluminum-air chemistries occupy research portfolios but lack regional manufacturing investment.
Hybrid holds near-term deployment potential. Solid state represents the steepest expansion trajectory once pilot transfer completes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Ministry of Industry local content thresholds and Thailand's Board of Investment tax holidays are pulling cathode active material producers and pack integrators into ASEAN industrial zones at accelerating rates.
Indonesia
Nickel processing corridors in Sulawesi and Maluku are concentrating integrated smelter-to-cell complexes as EV fleet operators scale procurement under domestic assembly requirements. The Ministry of Industry enforces value-add percentages for battery-grade nickel sulfate and MHP conversion facilities to qualify downstream integrators for tax incentives. Morowali Industrial Park anchors the archipelago's cathode precursor supply chain with Chinese and Korean smelter partnerships.
Thailand
Eastern Economic Corridor zones in Chonburi and Rayong absorb cylindrical and prismatic cell production as Board of Investment tax holidays contingent on domestic assembly pull in cathode material producers. Samsung SDI operates specialized production targeting premium automotive programs requiring extended range specifications. Bangkok commercial EV deployment programs now prioritize total cost of ownership guarantees over spot-market purchasing through trading houses.
Vietnam
Cathode material plants in Thai Nguyen and Vinh Phuc provinces concentrate regional precursor production as direct lithium extraction agreements with local mineral developers secure feedstock outside Chinese supply orbits. The Ministry of Natural Resources and Environment imposes waste battery recovery mandates that reshape aftermarket economics for second-life pack applications. Haiphong port infrastructure supports export-oriented contract manufacturing serving regional distribution networks.
Philippines
Islanded archipelago geography across Luzon, Visayas, and Mindanao creates natural demand for battery-plus-solar microgrids underserved by mainland Asian suppliers. State-owned utility tenders favor 4-8 hour duration vanadium redox flow systems for grid stabilization in off-grid municipalities. Batangas and Cebu industrial zones host emerging pack assembly capacity targeting commercial and industrial power backup before formal recycling infrastructure matures.
Singapore
Advanced manufacturing R&D hubs and regional headquarters functions concentrate decision-making for multinational cell producers operating across ASEAN production networks. The city-state's logistics and finance infrastructure enables procurement contract restructuring for Thai and Vietnamese OEM subsidiaries excluding Chinese-traded intermediate materials. Jurong Island chemical processing capabilities support electrolyte and separator material refinement for regional cell assembly plants.
Southeast Asia Battery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions in Southeast Asia. Integrated nickel-to-cell producers anchor procurement relationships with fleet operators through multi-year supply agreements, displacing independent pack assemblers into aftermarket retrofit specialization. Three archetypes dominate: upstream-integrated Chinese producers with Indonesian smelter partnerships, Korean-Japanese specialists in cylindrical premium formats, and mid-tier regional players leveraging Vietnamese mineral offtake. Competitive moves concentrate on backward integration into nickel refining and strategic partnerships with national OEM assembly subsidiaries.
Among Chinese-integrated producers, CATL and BYD occupy positions defined by upstream smelter control and domestic incentive compliance. Korean specialists LG Energy Solution and Samsung SDI exemplify premium-tier positioning through cylindrical cell expertise targeting automotive programs. Gotion High-tech represents mid-tier cost positioning secured via direct lithium extraction partnerships with Vietnamese developers, sitting outside dominant Chinese supply orbits while serving regional pack integrators.
| Leading Market Players |
|---|
| BYD |
| GS Yuasa |
| CATL |
| REPT Battero |
| Gotion High-tech |
| LG Energy Solution |
| Panasonic Holdings |
| Clarios |
| Samsung SDI |
| Others |
Value Network & Pricing Analysis
Indonesian nickel processing corridors in Sulawesi and Maluku concentrate cathode precursor supply, anchoring margin pools in integrated smelter-to-cell complexes while compressing distributor margins for independent pack assemblers. Battery-grade nickel sulfate and MHP conversion facilities must demonstrate domestic value-add percentages to qualify downstream integrators for tax incentives, forcing procurement contract restructuring that excludes Chinese-traded intermediate materials.
Pricing Analysis
Certification level against ASEAN safety standards and local content compliance thresholds creates the primary spread between premium and economy tier cell pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal runaway containment specifications and battery management system integration depth. Cost compression in standard-tier cylindrical formats is intensifying because Thai fleet operators now prioritize total cost of ownership guarantees over spot-market purchasing. Commercial backup power buyers in Vietnam and the Philippines remain most price-sensitive where lead-acid incumbents resist lithium-ion migration.
Supply Chain Analysis
Tariff exposure between Indonesian nickel smelters and Thai pack assembly plants dominates supply chain risk calculations for integrated producers. Raw material dependencies draw from Indonesian nickel laterite, Australian spodumene concentrate, and Vietnamese lithium brine developments. Single-source cathode precursor concentration in Chinese-owned Indonesian facilities creates vulnerability for non-Chinese pack assemblers seeking incentive-compliant supply chains. Distribution runs through Eastern Economic Corridor logistics hubs and Haiphong port infrastructure serving regional OEM subsidiaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery lifecycle services including second-life pack repurposing and waste recovery mandates are expanding faster than cell manufacturing hardware, creating recurring revenue layers that reshape competitive economics. Service-attach models around thermal management system maintenance and battery management software updates now generate margin pools independent of commodity cell pricing.
For Market Incumbents: Pre-empt margin erosion from mid-tier Vietnamese mineral offtake competitors by securing exclusive direct lithium extraction partnerships before feedstock agreements harden. Anchor backward integration into nickel refining corridors through joint venture structures with Indonesian Ministry of Industry-licensed smelter operators. Invest in electrochemical engineering talent pipelines with Thai and Vietnamese technical universities to reduce dependence on imported South Korean and Japanese staff.
For New Entrants and Emerging Players: Pursue Philippine islanded microgrid deployments where vanadium redox flow battery demand outpaces mainland Asian supplier capacity. Target commercial and industrial power backup applications in Batangas and Cebu industrial zones before formal recycling infrastructure matures. Lead with battery-plus-solar integrated system offerings rather than standalone cell sales to bypass established distributor networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state electrolyte pilot transfer programs as South Korean and Japanese parent labs delay regional subsidiary deployment. Long-term viability in the five-to-ten year window favors acquisition targets with captive nickel sulfate supply and existing OEM pack supply agreements rather than trading house-dependent assemblers. Monitor ASEAN safety standard harmonization progress as the signal to watch for compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Refining | Captive battery-grade nickel sulfate supply secures Indonesian EV incentive compliance for downstream integrators. |
| Direct Lithium Extraction Partnership | Vietnamese mineral offtake agreements bypass Chinese supply orbit concentration for mid-tier cell producers. |
| Second-Life Pack Repurposing Infrastructure | Thai and Indonesian commercial backup applications absorb retired automotive modules before recycling maturity. |
| Solid-State Electrolyte Pilot Transfer | South Korean and Japanese parent lab technology bridges energy density gaps for premium automotive programs. |
| ASEAN Safety Standard Harmonization Lobbying | Preemptive compliance positioning reduces fragmented certification burdens across member state markets. |
Research Methodology
Initial hypotheses were tested against primary input from cell manufacturing process engineers, EV fleet procurement managers, nickel smelter operations directors, and ASEAN regulatory affairs specialists and refined through secondary validation. Primary fieldwork combined structured interviews with plant managers at Indonesian integrated complexes and Thai Eastern Economic Corridor facilities with channel partner discussions across Vietnamese distributor networks. Secondary sources included customs and trade flow databases, Indonesia Ministry of Industry local content filings, Thailand Board of Investment tax holiday disclosures, and ASEAN standardization committee documentation. Bottom-up cell production capacity estimates were triangulated against top-down EV deployment projections.
Demand-supply balance modeling across the analysis window integrated electric vehicle traction pack procurement, grid-scale storage tender awards, and commercial backup power replacement cycles. Segmentation dimensions covered chemistry formulation, voltage architecture, end-use application, and national regulatory cluster. CAGRs were derived from installed capacity buildout trajectories and fleet operator procurement pipeline visibility. Industry-specific forecast inputs incorporated nickel LME price volatility scenarios and solid-state technology transfer timeline assumptions from parent laboratory disclosures.
Macroeconomic conditions sit as an overlay; deviation in nickel commodity price swings, EV incentive policy continuity, or ASEAN harmonization progress would shift the trajectory. Forecasts reflect documented assumptions around local content threshold enforcement and cathode precursor supply concentration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Zinc Ion Batteries Market
Batteries
France Rechargeable Battery Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Portable Battery Market
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
Battery Voltage Recorder Market
Batteries
Battery Anode Materials Market
Batteries
Middle-East Battery Market
Batteries
Battery Terminal Brushes Market
Batteries
United States SLI Battery Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
South America Rechargeable Battery Market
Batteries
Micro Battery Market
Batteries
Semi-Solid Flow Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
Grid-Scale Battery Market