
 Middle East Portable Generator Market | 2026-2036
Middle East Portable Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Portable Generator Market Foresight
Copper winding is consolidating market share over aluminum in portable generator stator assemblies across the Middle East, improving thermal efficiency and extending service intervals in desert climates. Honda Middle East leverages its regional distribution network to sustain premium positioning in residential and light commercial segments. Cummins Inc anchors the heavy-duty diesel category through its dealer presence in Saudi Arabia and the UAE. Atlas Copco AB competes in the rental channel with modular power solutions designed for construction site mobility.
A portable generator is an internal combustion or photovoltaic engine-alternator set mounted on a wheeled or skid frame, typically producing alternating current between 1 kW and 50 kW for locations without grid access. Diesel generators dominate the Middle East product mix due to fuel availability and load-bearing requirements at remote oilfield installations and construction camps. The 5 to 10 kW power rating band captures the fastest growth as small contractors and outdoor event operators upgrade from sub-2 kW units. Emergency services represent a concentrated margin pool where municipalities and hospital networks prioritize reliability certifications over unit cost.
SFDA emissions protocols in Saudi Arabia and UAE federal energy efficiency standards are tightening particulate limits for non-road mobile machinery, compelling manufacturers to redesign exhaust systems or risk market exclusion. BIS-equivalent conformity assessment procedures in Qatar and Kuwait add testing layers that favor suppliers with established regional certification capabilities. Stakeholders must monitor how Gulf standardization bodies harmonize carbon monoxide safety thresholds with European F-Gas Regulation approaches, as this alignment will determine which product architectures achieve multi-country approval without redundant engineering cycles.
Market Dynamics
SFDA emissions protocols and UAE federal energy efficiency standards are compressing product development cycles across the Middle East portable generator market, forcing manufacturers to redesign exhaust architectures or surrender access to the Gulf's largest procurement pools.
Growth Catalysts
- Infrastructure buildouts:Construction sites across Saudi Arabia and the UAE are expanding generator procurement as megaproject pipelines accelerate, creating sustained demand for mobile power assets in desert conditions.
- SFDA emissions mandates:Saudi Arabia's tightening particulate limits for non-road mobile machinery are compelling fleet operators to upgrade aging diesel units, generating replacement volume.
- Hybrid architectures:Battery-diesel hybrid systems are penetrating oilfield services and remote camp operations, extending service intervals and reducing fuel logistics burdens in isolated installations.
Market Restraints
- Copper price volatility:Stator winding costs fluctuate with copper commodity markets, pressuring margins on premium thermal-efficiency models designed for Gulf desert climates.
- Testing concentration:BIS-equivalent conformity assessment procedures in Qatar and Kuwait favor suppliers with established regional certification capabilities, creating barriers for new entrants lacking local laboratory relationships.
- Grid extension:Utility infrastructure investments in Saudi Arabia's urban corridors are reducing backup power dependency for some commercial segments.
Strategic Opportunities
- Oman underpenetration:Muscat's industrial zone expansion and port modernization are outpacing local generator supply capacity, creating first-mover advantages for distributors establishing service networks.
- Rental channel digitization:Construction contractors in the UAE are migrating to app-based equipment rental platforms, opening direct-to-site distribution bypassing traditional dealer networks.
- Carbon monoxide harmonization:Gulf standardization bodies are aligning safety thresholds with European F-Gas Regulation approaches, enabling single-engineering-cycle multi-country approval for prepared manufacturers.
Industry Challenges
- Certification timeline compression:SFDA and MOHAP approval windows are narrowing as regulatory staff volumes lag application growth, delaying product launches.
- After-sales network gaps:Remote oilfield installations require technician deployment across vast desert distances, straining service cost structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Portable Generator Market |
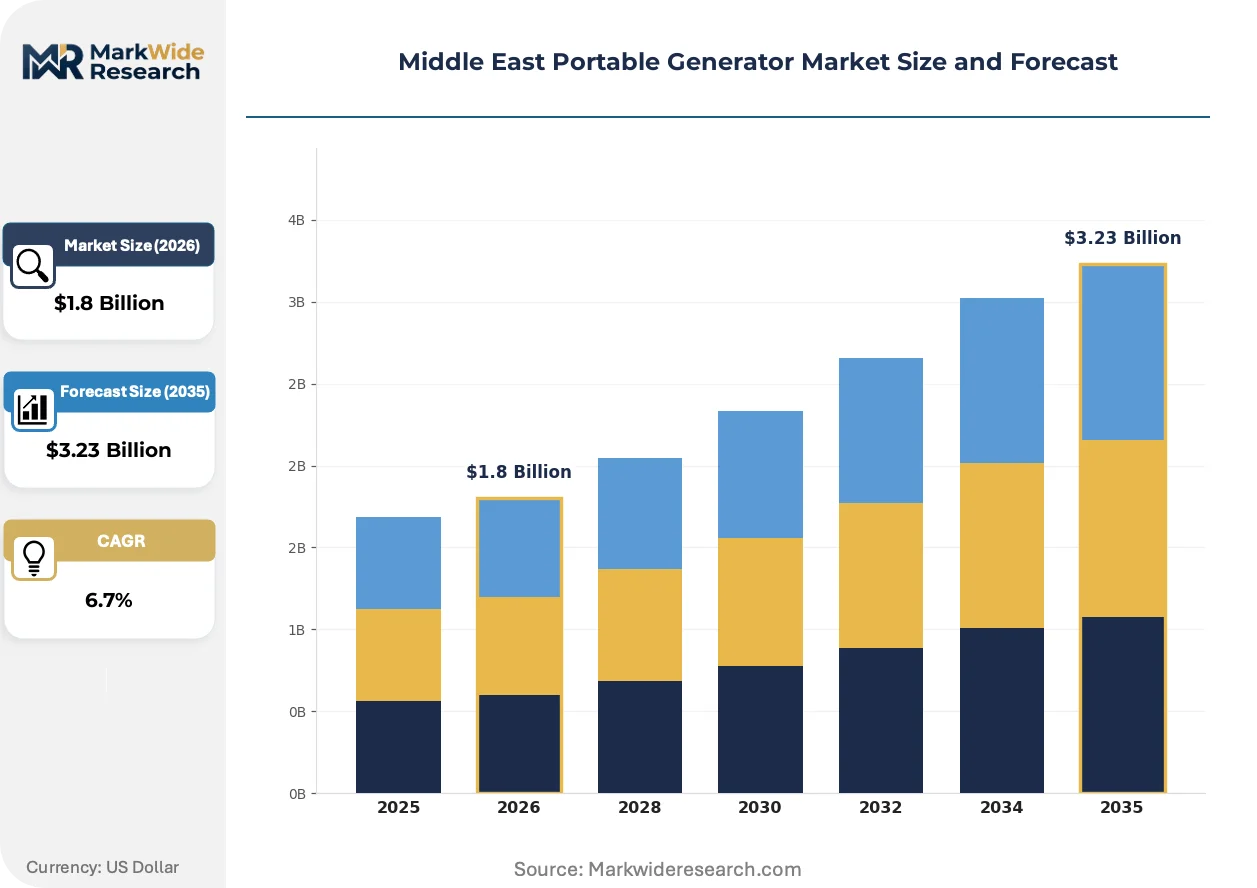
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Generators, Diesel Generators, Solar Generators, Hybrid Generators End User: Residential Users, Construction Sites, Outdoor Events, Emergency Services Power Rating: Below 2 kW, 2 to 5 kW, 5 to 10 kW, Above 10 kW Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Yamaha Motor Co Ltd, Atlas Copco AB, Doosan Portable Power, Caterpillar Inc, Generac Holdings Inc, Ultra Power Generators, Cummins Inc, Honda Middle East, Briggs & Stratton Corporation, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Portable Generator Market Shifts & Advancements
Portable generator architectures across the Middle East are pivoting toward thermal efficiency and emissions compliance as desert operating conditions and regulatory thresholds tighten simultaneously.
Copper winding is expanding into stator assemblies across premium product tiers, displacing aluminum in units rated above 5 kW. Saudi Arabian oilfield contractors and UAE event rental fleets are specifying copper-wound models exclusively for 4,000-hour service interval targets. This metallurgical shift is expanding into mid-range commercial offerings as procurement specifications harden around thermal performance guarantees.
SFDA emissions protocols are forcing exhaust system redesigns across the Saudi Arabian market, with particulate matter limits now matching EU Stage V equivalence for non-road mobile machinery. Diesel generator manufacturers must integrate diesel oxidation catalysts or face market exclusion from government and healthcare tenders. The 10 to 50 kW rental fleet segment is absorbing the steepest compliance costs as operators refresh units ahead of enforcement deadlines.
Event economy operators in Dubai are compressing rental procurement cycles from annual contracts to project-based sourcing, unbundling after-sales service from equipment rates. Outdoor production companies now source generators through specialized event logistics platforms rather than construction equipment dealers. This behavioral shift is most visible in Abu Dhabi's entertainment and exhibition verticals, where mobility and rapid deployment trump long-term service relationships.
Middle East Portable Generator Market Segmentation
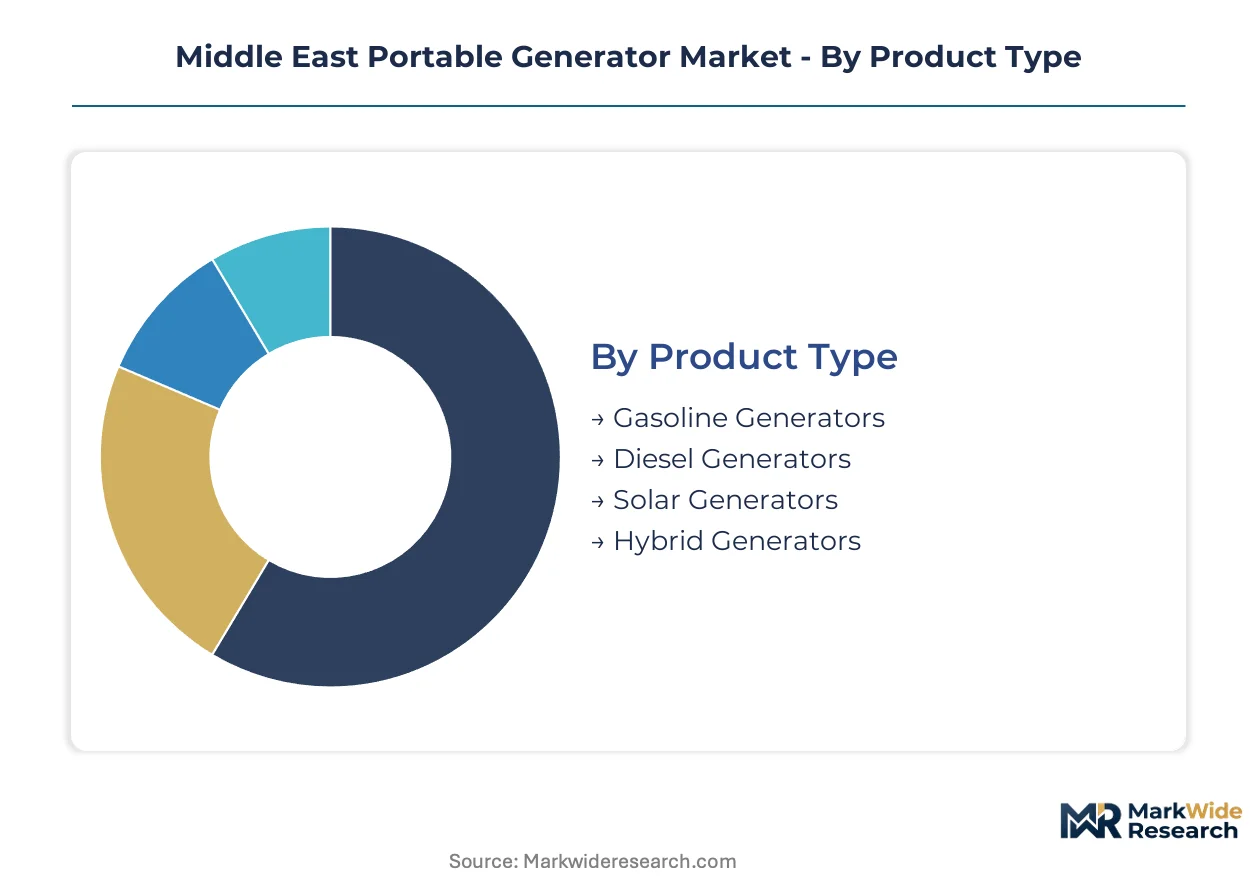
Portable generator procurement in the Middle East fragments across fuel technologies, deployment contexts, and power thresholds. Buyers prioritize thermal resilience in desert climates and emissions compliance under tightening SFDA and UAE federal mandates.
Product Type:
Fuel selection dictates maintenance intervals, logistics burden, and regulatory compliance costs for operators across Saudi Arabia and the UAE.
- Diesel Generators:Compression-ignition engines deliver sustained load-bearing capacity above 10 kW for remote oilfield installations and construction camps. Saudi Aramco contractors specify diesel units exclusively for 4,000-hour service intervals in Rub' al Khali desert operations. Volume sits with diesel; growth tilts toward hybrid architectures.
- Hybrid Generators:Battery-diesel systems integrate lithium-ion storage with combustion backup, extending service intervals and reducing fuel convoy frequency in isolated installations. UAE event rental fleets are piloting hybrid units for Dubai outdoor productions where noise restrictions and runtime flexibility outweigh capital premiums.
- Gasoline Generators:Spark-ignition units dominate sub-5 kW residential and light commercial segments across Gulf Cooperation Council states.
- Solar Generators:Photovoltaic-battery systems serve off-grid telecommunications and remote monitoring stations in Omani interior regions.
Procurement specifications harden around thermal performance guarantees and particulate emissions thresholds.
End User:
Application context determines reliability certification requirements and procurement channel preferences across the Gulf.
- Construction Sites:Mobile power assets face dust ingestion, vibration, and 24-hour duty cycles on Saudi megaproject sites. Contractors prioritize copper-wound stators and heavy-duty skids for generator transport across unpaved desert access roads.
- Emergency Services:Hospital networks and municipal civil defense units mandate redundant starting systems and automatic transfer switches. SFDA reliability certifications override unit cost considerations for Saudi healthcare infrastructure backup power.
- Residential Users:Homeowners in UAE villa communities and Saudi urban corridors purchase sub-5 kW units for air conditioning backup during grid instability.
- Outdoor Events:Dubai entertainment producers source through specialized logistics platforms rather than traditional equipment dealers, compressing rental cycles to project-based terms.
Margin concentration clusters where certification barriers exclude commodity suppliers; volume concentrates in construction rental fleets.
Power Rating:
Output threshold shapes fuel system architecture, transportability, and end-use addressability across Middle East deployment contexts.
- 5 to 10 kW:Single-phase and light three-phase output captures small contractor upgrades and outdoor event operator expansion from sub-2 kW inventories. Abu Dhabi oilfield services firms specify this band for camp auxiliary power where load diversity precludes larger fixed installations.
- Above 10 kW:Heavy-duty skidded units serve construction batch plants, drilling mud pump power, and desalination backup across Saudi Arabia's Red Sea coast projects.
- Below 2 kW:Compact inverter generators address residential lighting and small appliance loads in UAE apartment sectors.
- 2 to 5 kW:Mid-range portable units bridge residential and light commercial applications with wheeled frame mobility.
Technology substitution accelerates in the 5 to 10 kW band as hybrid architectures penetrate established diesel strongholds.
Distribution Channel:
Channel selection reflects buyer sophistication, service requirements, and procurement urgency across Middle East market segments.
- Wholesale Distributors:Regional inventory aggregation in Jebel Ali Free Zone and Dammam industrial corridors enables rapid fulfillment for Saudi construction contractors facing project timeline compression. Distributors carry certified stock pre-approved for SFDA and MOHAP registration.
- Online Retailers:E-commerce platforms penetrate residential and small contractor segments in UAE and Saudi urban markets where specification familiarity reduces pre-purchase technical consultation needs.
- Specialty Stores:Physical showrooms serve first-time buyers requiring hands-on comparison of noise levels and physical dimensions.
- Direct Sales:Manufacturer representatives engage oilfield services and hospital network procurement teams for customized specifications and service contract bundling.
Channel power concentrates with distributors holding regional certification capabilities and spare parts inventory depth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portable generator procurement concentrates in Gulf Cooperation Council states where infrastructure buildouts and desert operating conditions sustain premium equipment demand. Saudi Arabia and the UAE absorb the majority of regional volume, while Oman and Qatar present expansion vectors for distributors establishing service networks.
Saudi Arabia
Saudi Aramco contractors drive diesel generator procurement for Rub' al Khali desert operations requiring 4,000-hour service intervals. SFDA emissions protocols are tightening particulate limits for non-road mobile machinery, forcing exhaust system redesigns ahead of enforcement deadlines. Riyadh and the Eastern Province cluster megaproject sites where copper-wound stators dominate procurement specifications for thermal resilience.
United Arab Emirates
Dubai's event economy sustains continuous rental orders for mobile generation assets where rapid deployment trumps long-term service relationships. UAE federal energy efficiency standards are compressing product development cycles for manufacturers seeking market access. Abu Dhabi's oilfield services sector anchors heavy-duty diesel procurement, with contractors specifying hybrid architectures for isolated camp operations.
Oman
Muscat's industrial zone expansion and port modernization are outpacing local generator supply capacity, creating first-mover advantages for establishing distributor networks. The country's national energy regulator is evaluating emissions alignment with GCC standardization frameworks. Sohar and Duqm port developments concentrate demand for construction-grade mobile power assets in coastal industrial corridors.
Qatar
BIS-equivalent conformity assessment procedures favor suppliers with established regional certification capabilities and local laboratory relationships. Lusail City development and North Field expansion projects sustain procurement of skidded units above 10 kW for batch plant and auxiliary power applications. Doha's healthcare infrastructure mandates SFDA-equivalent reliability certifications for hospital backup power systems.
Kuwait
Construction camp operators in the northern oilfields specify diesel generators exclusively for load-bearing capacity above 10 kW in isolated installations. The country's national standards body maintains testing layers that add compliance complexity for new market entrants. Al Ahmadi and Mina Al Ahmadi industrial zones concentrate demand for heavy-duty mobile power in petrochemical and refining operations.
Middle East Portable Generator Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium residential and light commercial categories consolidating around established names while rental and heavy-duty categories accommodate regional fabricators. The vendor base organizes into three strategic archetypes: integrated engine-alternator manufacturers with captive distribution, modular power specialists targeting construction mobility, and regional assemblers serving price-sensitive contractor segments. Competitive moves concentrate on certification pre-positioning ahead of SFDA enforcement deadlines and spare parts inventory depth for desert service coverage.
Within the integrated manufacturer tier, Honda Middle East and Cummins Inc exemplify contrasting approaches to Gulf market positioning. Atlas Copco AB occupies a position in the rental channel archetype, with modular power solutions designed for construction site mobility. Yamaha Motor Co Ltd represents the residential-specialist vector, leveraging brand recognition in sub-5 kW inverter segments across UAE villa communities. These anchors illustrate how geographic origin and company structure map to segment concentration in Middle East portable generator procurement.
| Leading Market Players |
|---|
| Yamaha Motor Co Ltd |
| Atlas Copco AB |
| Doosan Portable Power |
| Caterpillar Inc |
| Generac Holdings Inc |
| Ultra Power Generators |
| Cummins Inc |
| Honda Middle East |
| Briggs & Stratton Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap distributors across Jebel Ali and Dammam industrial corridors anchor supply consolidation in the Middle East portable generator market, translating inventory depth into pricing discipline against fragmented contractor procurement. Their control over certified stock pre-approved for SFDA and MOHAP registration creates tiered margin structures where certification capability commands premium positioning.
Pricing Analysis
Volume concentrates in diesel units below 10 kW where construction contractors prioritize fleet standardization over unit economics, while margins cluster in hybrid architectures and copper-wound premium tiers where thermal performance guarantees differentiate pricing. Certification grade and after-sales service bundling drive price differentiation across Saudi Aramco tenders and Dubai event rental contracts. Pricing pressure stems from copper commodity volatility pressuring stator winding costs in desert-optimized models. Small contractors exhibit highest price sensitivity, whereas hospital networks and oilfield services prioritize reliability certifications over unit cost.
Supply Chain Analysis
Freight costs from China, South Korea, and Japan dominate landed cost structures for engine-alternator sets arriving at Jebel Ali Free Zone, with container rate volatility compressing distributor margins on heavy-duty skidded units. Manufacturing draws from Chinese casting foundries for engine blocks, Japanese alternator specialists for copper-wound assemblies, and South Korean battery cell suppliers for hybrid architectures. Single-source vulnerability concentrates in diesel oxidation catalyst supply for SFDA compliance. Distribution runs through wholesale distributors holding regional certification capabilities and spare parts inventory for desert service coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East portable generator market sits in a technology-transition phase as battery-diesel hybrid architectures displace pure combustion units in oilfield services and event rental applications. This substitution reconfigures procurement specifications, service interval expectations, and capital deployment patterns across Gulf Cooperation Council states.
For Market Incumbents: Extend copper-wound stator advantages into mid-range commercial tiers before aluminum-wound regional assemblers achieve cost parity. Deepen backward integration into alternator winding capacity in Saudi Arabia's Eastern Province to defend against Korean and Chinese component suppliers. Prioritize SFDA pre-certification investments ahead of enforcement deadline compression. For New Entrants and Emerging Players: Wholesale distributors with established MOHAP laboratory relationships represent the most viable channel partners for bypassing certification barriers in Qatar and Kuwait. Target Oman's underpenetrated industrial zones around Sohar and Duqm where port modernization outpaces local supply capacity. Lead with hybrid unit pilots for UAE event rental platforms seeking noise-compliant, rapid-deployment assets. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional assemblers with dormant SFDA certification files and existing Jebel Ali inventory positions during copper price correction phases. Long-term viability hinges on hybrid technology transition execution capability rather than pure diesel scale. Watch for GCC standardization body alignment with European F-Gas Regulation approaches as inflection signal for single-engineering-cycle multi-country approval economics.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Pre-Certification Investment | Exhaust system redesigns ahead of particulate limit enforcement secure Saudi Aramco tender access. |
| Hybrid Architecture Pilot Programs | Battery-diesel trials with Dubai event logistics platforms validate noise-compliant runtime flexibility. |
| Copper Winding Capacity Expansion | In-house alternator production in Eastern Province reduces exposure to commodity price volatility. |
| Oman Distributor Network Establishment | First-mover service coverage around Sohar and Duqm port developments captures industrial zone demand. |
| After-Sales Service Unbundling | Project-based rental terms for Abu Dhabi entertainment verticals match compressed procurement cycles. |
Research Methodology
Document review covered SFDA regulatory filings, UAE federal energy efficiency standards, GCC customs trade data, and oilfield services procurement databases, complemented by interviews with maintenance directors at Saudi construction contractors, rental fleet managers in Dubai, biomedical engineers at Doha hospital networks, and aftermarket service heads at Jebel Ali distributors. Primary fieldwork with equipment procurement officers and regulatory affairs specialists cross-referenced against secondary validation from national standards body publications and EPC contractor project disclosures. Bottom-up unit shipment analysis triangulated with top-down market sizing across fuel technology, power rating, and end-use segments.
Historical shipment patterns from national customs databases cross-referenced against panel input from distributor inventory managers and OEM regional representatives anchored the analytical framework. Segmentation modeling spanned fuel technology architecture, power output tier, deployment context, and certification requirement intensity across the projection horizon. CAGRs derived from regression analysis against infrastructure investment pipelines and regulatory enforcement timelines. Industry-specific forecast inputs included Saudi megaproject award trajectories and SFDA approval window compression rates.
Caveats apply where copper commodity volatility, GCC regulatory harmonization delays, or grid extension acceleration in Saudi urban corridors could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Europe Gas Turbine Market
Generators
East Africa Diesel Generator Market
Generators
Heat Recovery System Generator Market
Generators
Power Generator Rental Market
Generators
India Diesel Generator Market
Generators
Gas Generator Sets Market
Generators
Europe Portable Generator Market
Generators
North America Portable Generators Market
Generators
Europe Turbo Generator Market
Generators
Africa Diesel Generator Market
Generators
Natural Gas Generator Market
Generators
Railway Generators Market
Generators
Gasoline Generator Market
Generators
Construction Portable Generators Market
Generators
Reciprocating Power Generating Engine Market
Generators
Industrial Generator Market