
 Australia Transportation Infrastructure Construction Market | 2026-2036
Australia Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Transportation Infrastructure Construction Market Outlook
The Australian transportation infrastructure construction sector is pivoting between premium engineered solutions and commodity-grade delivery models. CPB Contractors leverages its integrated project delivery capability to dominate complex rail and road packages across eastern states. John Holland Group anchors its position through specialized tunnelling and bridge competencies that sustain higher-margin execution. Lendlease differentiates via development-aligned infrastructure that controls end-to-end precinct outcomes.
Australia transportation infrastructure construction encompasses the planning, design, fabrication, and assembly of civil assets including roadways, bridges, railways, and airports, typically employing reinforced concrete with specified compressive strengths exceeding 40 MPa, structural steel grades complying with AS/NZS 3678, and hot-mix asphalt with polymer-modified binders for heavy-duty pavements, all serving to enable safe, efficient movement of passengers and freight across metropolitan and regional networks. Roads and railways command the largest capital allocation pools, with rail exhibiting faster growth due to Inland Rail and suburban metro expansions, while concrete maintains volume leadership though composites are gaining share in bridge deck rehabilitation where reduced dead load delivers structural advantage. Government funding dominates procurement channels, yet public-private partnerships are expanding as state treasuries seek risk transfer for mega-projects exceeding two billion dollars in capital value.
Infrastructure Australia sets national priority benchmarks that shape federal funding allocation, while state-based planning regulators enforce environmental impact thresholds that extend project timelines but elevate asset resilience standards. The Australian Building Codes Board and state work safety authorities mandate construction-phase protocols that filter market access toward contractors with certified quality systems. Stakeholders must monitor how evolving Commonwealth infrastructure pipeline commitments interact with state debt capacity and workforce availability to calibrate bidding strategies and resource deployment.
Market Dynamics
Federal Infrastructure Investment Program commitments are compressing project delivery timelines across Australian states, forcing contractors to absorb front-loaded capital deployment risks while state treasuries transfer operational liability to private consortia.
Growth Catalysts
- Inland Rail Corridor:The Melbourne-to-Brisbane freight rail project is unlocking regional connectivity upgrades that cascade into feeder road and bridge contracts across Queensland and Victoria.
- Green Building Council of Australia rating mandates:Low-carbon concrete specifications are creating differentiated procurement tiers that reward certified sustainable material suppliers with preferred supplier status.
- Polymer-modified asphalt specifications:State road authorities in New South Wales are mandating higher-performance pavement binders that extend asset life cycles and justify premium construction bids.
Market Restraints
- Structural steel import dependency:AS/NZS 3678 compliant plate supply concentrates among limited Australian mills, exposing project budgets to domestic capacity constraints.
- Specialized tunnelling labour scarcity:Certified tunnel boring machine operators and shotcrete technicians command wage premiums that inflate underground package costs beyond initial estimates.
- Environmental impact assessment thresholds:State-based planning regulators enforce extended approval timelines that compress construction windows and escalate carrying costs for mobilized equipment fleets.
Strategic Opportunities
- Western Sydney Airport precinct:The aerotropolis development is generating integrated road-rail-bridge packages that favor contractors with multi-discipline execution capabilities.
- Recycled aggregate mandates:Infrastructure Australia priority frameworks are embedding circular material specifications that create first-mover advantages for demolition-to-construction supply chain integrators.
- Digital engineering twins:Convergence of BIM platforms with IoT sensor networks is enabling predictive asset management contracts that extend contractor revenue streams into operational phases.
Industry Challenges
- Geotechnical survey capacity:Specialist drilling crews and laboratory testing facilities face backlogs that delay foundation design finalization and push procurement timelines.
- Cross-jurisdiction certification:Interstate project portfolios require duplicate safety system accreditations that fragment quality management resources and inflate administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Transportation Infrastructure Construction Market |
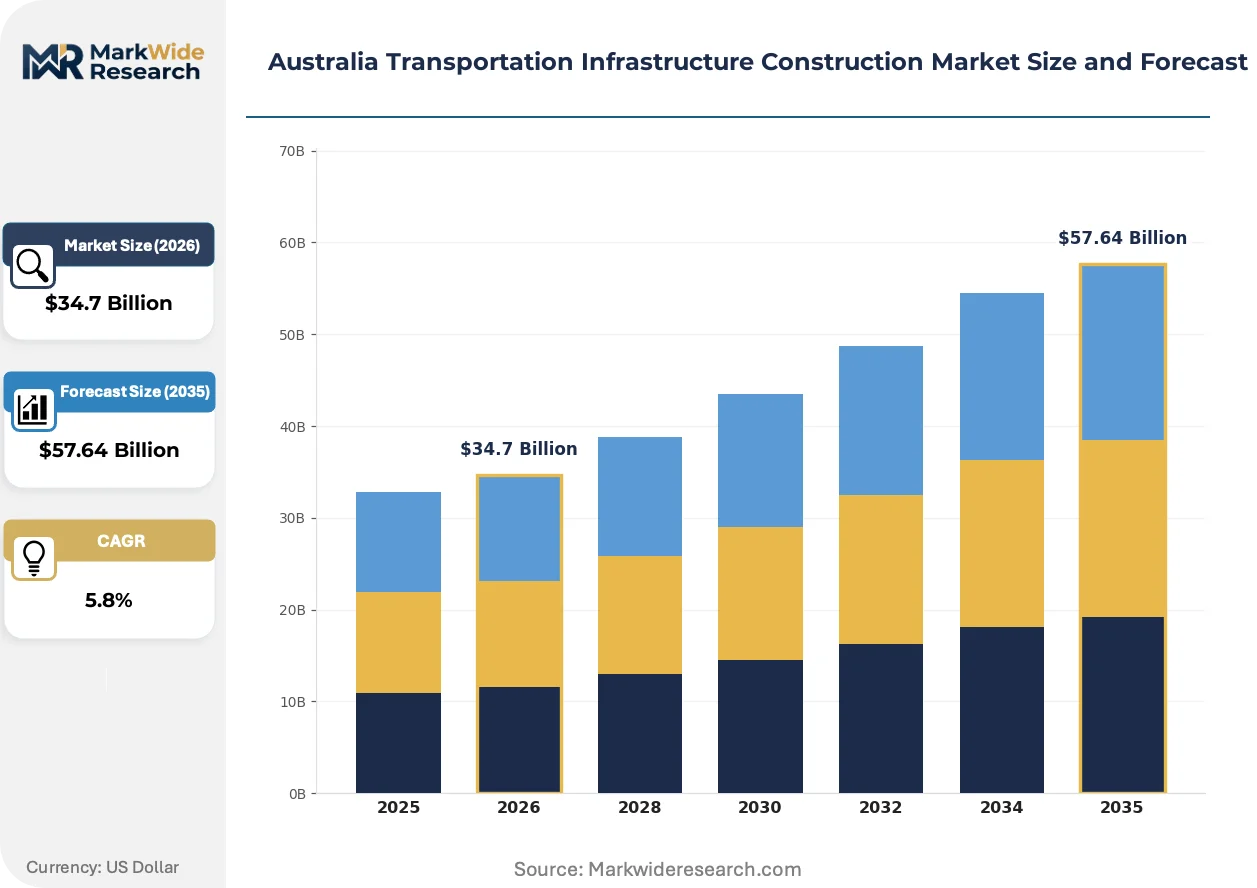
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $57.64 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roads, Bridges, Railways, Airports Material Type: Concrete, Steel, Asphalt, Composites Funding Source: Government, Private Sector, Public-Private Partnerships, International Aid Construction Stage: Planning, Design, Execution, Maintenance |
| Companies Covered | CPB Contractors, John Holland Group, Lendlease, Hutchinson Builders, Fulton Hogan, ADCO Constructions, BMD Constructions, Acciona Construction Australia, Downer Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Transportation Infrastructure Construction Market Strategic Shifts
Digital fabrication methods and material science advances are compressing traditional construction phases while regulatory pressure on embodied carbon forces specification changes across structural packages.
Ultra-high performance concrete (UHPC) with compressive strengths exceeding 150 MPa is rewriting bridge deck and joint repair methodologies. State road authorities in Victoria are specifying UHPC overlays for corrosion-damaged structures, enabling thinner cross-sections that reduce dead load and extend span capabilities without superstructure replacement.
Infrastructure Australia priority benchmarks now embed climate resilience criteria that elevate asset design standards. Contractors must demonstrate adaptive capacity against flood and fire risk scenarios to secure federal co-funding, shifting engineering focus from minimum compliance to performance-under-stress validation.
Public-private partnership models are displacing traditional design-bid-build procurement for mega-projects exceeding two billion dollars in capital value. State treasuries in New South Wales and Queensland are transferring demand risk to consortia, requiring contractors to price traffic revenue uncertainty into long-term maintenance obligations.
Australia Transportation Infrastructure Construction Market Segmentation
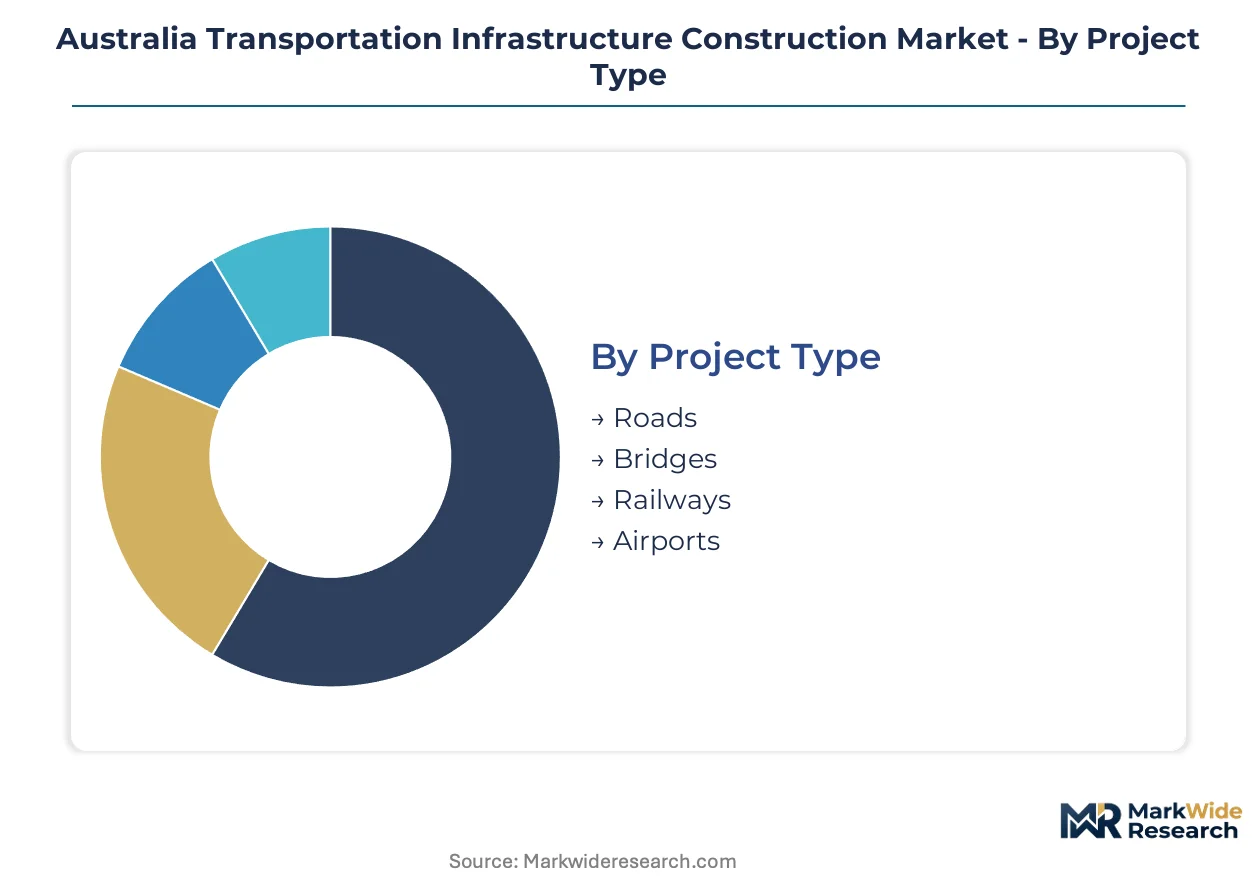
Segmentation in Australian transportation infrastructure construction reveals how procurement channels, material specifications, and project phases allocate risk and margin across the value chain. Contractors calibrate capability investments against these dimensions to secure recurring revenue streams in a government-dominated funding environment.
Project Type:
Rail corridors demand integrated multi-discipline execution, while road and bridge packages often fragment into specialized subcontracts.
- Roads:Hot-mix asphalt with polymer-modified binders dominates heavy-duty pavement specifications across New South Wales and Victoria. State road authorities in Queensland are accelerating urban corridor upgrades linking Brisbane satellite cities, compressing delivery timelines and favoring contractors with in-house surfacing fleets.
- Railways:Suburban metro expansions in Sydney and Melbourne require tunnel boring machine deployment and elevated viaduct construction with reinforced concrete superstructures exceeding 50 MPa. The Inland Rail corridor is cascading feeder road and bridge contracts across regional Queensland and Victoria.
- Bridges:Ultra-high performance concrete overlays are specified for corrosion-damaged structures, enabling thinner cross-sections that reduce dead load. Composites gain share in deck rehabilitation where reduced mass delivers structural advantage.
- Airports:Western Sydney Airport aerotropolis development is generating integrated road-rail-bridge packages requiring multi-discipline coordination.
Volume placements concentrate in Roads; the faster expansion belongs to Railways.
Material Type:
Cost tier stratification separates commodity-grade bulk materials from certified sustainable alternatives that command procurement preference.
- Concrete:Low-carbon formulations with supplementary cementitious materials are achieving preferred supplier status under Green Building Council of Australia rating mandates. Infrastructure Australia priority frameworks are embedding circular material specifications that reward demolition-to-construction supply chain integrators.
- Steel:AS/NZS 3678 compliant structural plate concentrates among limited domestic mills, exposing project budgets to capacity constraints. Bridge fabrication and rail infrastructure command the highest grade specifications.
- Asphalt:Polymer-modified binders are mandated by New South Wales road authorities, extending asset life cycles and justifying premium construction bids.
- Composites:Fiber-reinforced polymers are displacing conventional materials in bridge deck rehabilitation and corrosion-prone coastal infrastructure.
Concrete maintains volume leadership; composites are climbing the fastest as regulatory pressure on embodied carbon intensifies.
Funding Source:
Risk allocation patterns vary sharply between direct government procurement and long-term concession structures.
- Government:Federal Infrastructure Investment Program commitments are compressing project delivery timelines across Australian states. Direct procurement dominates roads and regional rail, with state treasuries retaining demand risk.
- Public-Private Partnerships:Mega-projects exceeding two billion dollars in capital value are transferring operational liability to private consortia. New South Wales and Queensland state treasuries are pricing traffic revenue uncertainty into long-term maintenance obligations.
- Private Sector:Western Sydney Airport precinct development and mining corridor infrastructure attract direct private capital with shorter payback horizons.
- International Aid:Limited application in Australian domestic infrastructure; primarily relevant to Pacific regional connectivity projects under Commonwealth development frameworks.
Government channels dominate current placements; public-private partnerships are gaining share fastest as state debt capacity faces constraints.
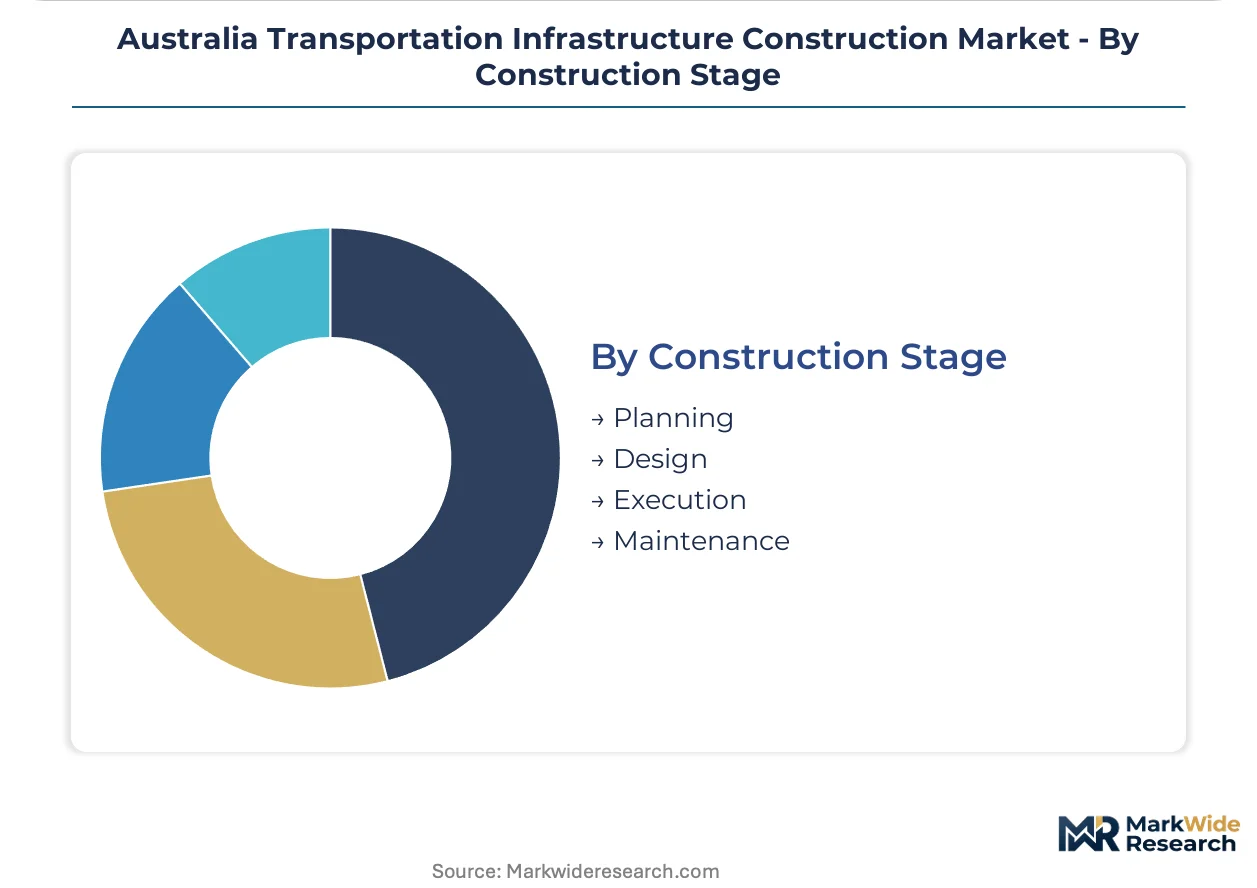
Construction Stage:
Margin profiles steepen toward execution and maintenance phases where specialized capabilities filter market access.
- Planning:Geotechnical survey capacity constraints are delaying foundation design finalization. Specialist drilling crews and laboratory testing facilities face backlogs that push procurement timelines.
- Design:Digital engineering twins and BIM platforms are enabling predictive asset management contracts that extend contractor revenue streams. Climate resilience criteria now require adaptive capacity demonstration against flood and fire risk scenarios.
- Execution:Front-loaded capital deployment risks are forcing contractors to absorb mobilization costs while state treasuries compress construction windows. Certified tunnel boring machine operators and shotcrete technicians command wage premiums that inflate underground package costs.
- Maintenance:Outcome-based contracts with long-term performance obligations are emerging under public-private partnership structures.
Execution captures the largest capital allocation; maintenance is expanding most quickly as asset portfolios mature and availability-based contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney anchors Australian transportation infrastructure construction, with the Western Sydney Airport aerotropolis and metro rail extensions concentrating capital deployment in New South Wales. State governments across Australia's eastern seaboard are compressing project delivery timelines under Infrastructure Australia priority frameworks.
New South Wales
Suburban metro expansions and Western Sydney Airport feeder corridors dominate procurement pipelines. The state's road authority mandates polymer-modified asphalt specifications that extend pavement life cycles. Sydney's orbital motorway upgrades and Parramatta light rail extensions concentrate contractor mobilization in the Greater Sydney basin.
Victoria
Melbourne's suburban rail loop and level crossing removal programs absorb the bulk of state infrastructure budgets. Infrastructure Victoria planning frameworks enforce climate resilience criteria in asset design standards. The Geelong-Ballarat corridor and Melbourne Airport rail link anchor regional connectivity investments.
Queensland
Brisbane's Cross River Rail and Inland Rail feeder contracts cascade into regional bridge and road packages. The state's Department of Transport and Main Roads prioritizes flood-resilient design standards for tropical corridor assets. Southeast Queensland's urban corridor upgrades linking Brisbane satellite cities accelerate surfacing fleet deployment.
Western Australia
Mining corridor infrastructure and Perth's Metronet extensions sustain contractor workloads outside the eastern states concentration. Main Roads Western Australia specifications emphasize heavy-duty pavement designs for remote haulage routes. The Kwinana industrial strip and Pilbara resource corridors anchor non-residential transport investment.
South Australia
Adelaide's North-South Corridor completion and hydrogen export precinct road-rail interfaces concentrate state capital allocation. The Department for Infrastructure and Transport embeds recycled aggregate mandates in metropolitan project specifications. The Port Adelaide industrial zone and northern suburbs growth corridors structure procurement geography.
Australia Transportation Infrastructure Construction Market Competitive Environment
Capital-heavy producers compete with asset-light designers across Australia's transportation infrastructure construction sector. The market structures around tiered capability portfolios, with integrated multi-discipline contractors commanding premium positioning on complex rail and airport packages. Three archetypes dominate: full-service infrastructure developers controlling end-to-end precinct outcomes, specialized civil contractors anchoring tunnel and bridge competencies, and regional surfacing specialists capturing recurring road maintenance volumes. Competitive moves concentrate on public-private partnership consortium formation and sustainable material certification to secure preferred supplier status under Green Building Council of Australia frameworks.
Among integrated delivery specialists, CPB Contractors and John Holland Group exemplify the multi-discipline execution archetype that dominates mega-project procurement. Lendlease occupies a position bridging infrastructure construction with development-aligned precinct control. These three entities anchor the competitive structure through their capacity to bid integrated road-rail-bridge packages under compressed state government timelines.
| Leading Market Players |
|---|
| CPB Contractors |
| John Holland Group |
| Lendlease |
| Hutchinson Builders |
| Fulton Hogan |
| ADCO Constructions |
| BMD Constructions |
| Acciona Construction Australia |
| Downer Group |
| Others |
Value Chain & Pricing Dynamics
Federal Infrastructure Investment Program procurement concentrates demand among tier-one contractors, locking in project-based pricing with outcome-linked performance guarantees. State treasuries transfer operational liability to private consortia, compressing margins for execution-phase bidders while rewarding certified sustainable material suppliers with preferred status.
Pricing Analysis
Outcome-based pricing anchors mega-project procurement, with public-private partnership consortia pricing long-term maintenance obligations against traffic revenue uncertainty. Price differentiation hinges on Green Building Council of Australia certification tiers and in-house tunnelling capability depth. Cost compression in commodity-grade concrete supply is intensifying because state authorities are mandating low-carbon formulations. Regional surfacing specialists exhibit highest price sensitivity; integrated multi-discipline contractors command premium positioning.
Supply Chain Analysis
Direct-to-state-authority channels handle hyperscale infrastructure demand, with project bundling favoring contractors with captive quarry and asphalt plant networks. Domestic steel supply draws from limited AS/NZS 3678 compliant mills in Australia, exposing budgets to capacity constraints. Raw material flows hinge on polymer-modified bitumen imports, supplementary cementitious materials, and fiber-reinforced polymer composites. Single-source vulnerability concentrates in certified tunnel boring machine operator labor pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
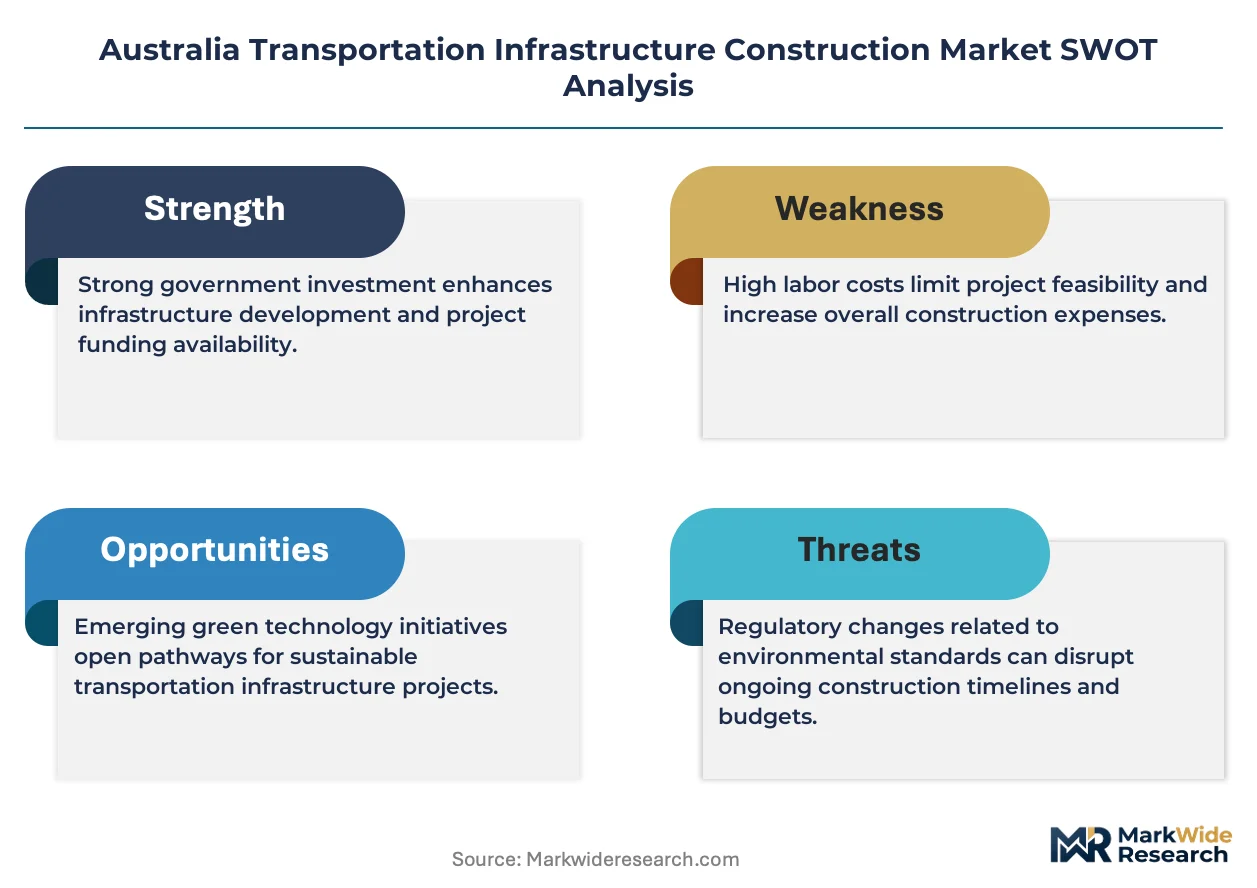
Infrastructure Australia priority frameworks have erected a cost-of-compliance moat around the Australian transportation infrastructure construction sector, with Green Building Council of Australia rating mandates filtering market access toward certified quality systems.
For Market Incumbents: Extend predictive asset management service lines to capture operational-phase revenue streams under public-private partnership structures. Deepen backward integration into recycled aggregate supply chains to secure first-mover advantage under circular material mandates. Counter specialized tunnelling labour scarcity by anchoring workforce development partnerships with technical training institutes. For New Entrants and Emerging Players: Enter via Western Sydney Airport aerotropolis feeder contracts where multi-discipline coordination requirements are loosening incumbent lock-in. Target Queensland regional bridge packages cascading from Inland Rail connectivity upgrades. Lead with digital engineering twin capabilities to differentiate on predictive maintenance offerings. For Investors and Strategic Acquirers: The window for entry favors demolition-to-construction supply chain integrators with certified sustainable material processing assets. Long-term viability hinges on exposure to maintenance-phase outcome contracts as asset portfolios mature. Monitor state debt capacity against Infrastructure Australia pipeline commitments as the inflection signal for procurement volume shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Green Material Certification Investment | Green Building Council of Australia ratings unlock preferred supplier status in federal co-funded projects. |
| Predictive Asset Management Platform Launch | BIM-IoT convergence extends contractor revenue into operational phases under availability-based contracts. |
| Recycled Aggregate Supply Chain Integration | Circular material specifications in Infrastructure Australia frameworks create defensible input cost positions. |
| Tunnelling Workforce Development Partnership | Certified operator pipelines address labour scarcity inflating underground package bids. |
| Multi-Discipline Consortium Formation | Integrated road-rail-bridge execution capabilities secure Western Sydney Airport precinct awards. |
Study Parameters
Document review covered Infrastructure Australia priority framework publications, state treasury budget papers, and Green Building Council of Australia technical standards, complemented by interviews with project directors at tier-one contractors, procurement leads at state road authorities, tunnelling engineering specialists, and sustainable materials certification auditors. Secondary validation drew from Australian Bureau of Statistics construction activity data, state government infrastructure pipeline disclosures, and AS/NZS standards documentation. Bottom-up project aggregation was cross-checked against top-down federal funding allocation analysis.
Market value and volume outputs were generated through segmentation-level modeling across project type, material specification, funding source, and construction phase dimensions over the projection horizon. CAGRs were derived from trend extrapolation of historical capital deployment patterns adjusted for announced pipeline commitments. Forecast inputs incorporated workforce availability constraints, state debt capacity trajectories, and embodied carbon regulatory trajectory assumptions.
Revisions become necessary when Infrastructure Australia priority framework recalibrations, state treasury debt ceiling adjustments, or geotechnical survey capacity bottlenecks materialize beyond base-case assumptions. Forecasts reflect documented assumptions regarding federal funding continuity and material certification pathway adoption rates. Periodic stress-testing of base assumptions against actual project award timelines and contractor margin compression indicators is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
Concrete Canvas Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Aerial Cable Car Equipment Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Utility System Construction Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Global Manhole Covers Market