
 Middle East & Africa Infrastructure Construction Market | 2026-2036
Middle East & Africa Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East & Africa Infrastructure Construction Market Insights
Lifecycle maintenance contracting is decoupling capital expenditure from operational delivery across transport and energy assets. Bechtel leverages its integrated EPC model to anchor large-scale project execution in Saudi Arabia's giga-project pipeline. Orascom Construction competes through its deep civil engineering heritage across Egypt and broader North Africa.
Middle East and Africa infrastructure construction encompasses the planning, engineering, and assembly of transport, energy, water, and social assets using reinforced concrete, structural steel, and composite materials designed to withstand seismic and arid-zone stressors. Its primary purpose is to enable economic connectivity and urban densification across economies with substantial infrastructure deficits. Concrete remains the dominant material type due to localized cement production capacity and thermal performance requirements, while modular construction technology gains traction where labor mobility constraints persist. Government end users command the largest project pipeline, though private sector participation deepens where regulatory frameworks permit build-operate-transfer structures.
Saudi Arabia's National Project Management Organization, the UAE's Estidama program, and South Africa's National Regulator for Compulsory Specifications collectively shape material standards, environmental compliance thresholds, and contractor qualification requirements across the region. These frameworks elevate entry barriers for foreign firms while accelerating local content obligations and sustainability certification adoption. Stakeholders must monitor how procurement rule changes around local partnership requirements and carbon disclosure standards reshape competitive access to the next wave of mega-project awards.
Market Dynamics
Lifecycle maintenance contracting is decoupling capital expenditure from operational delivery across transport and energy assets, forcing contractors to restructure balance sheets and service capabilities around long-term performance guarantees rather than milestone-based construction payments.
Growth Catalysts
- Saudi Arabia's giga-project pipeline:Transport corridors absorb rising capital as Riyadh accelerates delivery timelines for NEOM and Red Sea developments, concentrating demand for heavy civil engineering capacity.
- UAE Estidama certification:Green building mandates redirect material procurement toward lower-carbon concrete and steel specifications, creating premium tier demand for certified suppliers.
- Modular construction technology:Labor mobility constraints across Gulf Cooperation Council states accelerate prefabrication adoption where on-site workforce availability remains restricted.
Market Restraints
- Localized cement production concentration:Supply vulnerability persists where single-source clinker capacity dominates national markets, exposing projects to input cost volatility during energy price spikes.
- Foreign contractor entry barriers:Saudi Arabia's National Project Management Organization and South Africa's National Regulator for Compulsory Specifications elevate qualification thresholds that delay market access for non-established firms.
- Arid-zone material degradation:Thermal stressors and saline groundwater accelerate reinforced concrete deterioration, compressing maintenance cycles and inflating lifecycle cost assumptions.
Strategic Opportunities
- Nigeria's Lagos-Ibadan corridor:West Africa's expressway renewal concentrates demand for heavy civil engineering capacity where regional contractor scarcity creates first-mover positioning.
- Build-operate-transfer regulatory frameworks:Deepening private sector participation in UAE and Saudi Arabia permits long-term revenue streams beyond construction completion.
- Digital twin convergence with seismic monitoring:Real-time structural health monitoring is integrating with predictive maintenance platforms to extend asset service life across earthquake-prone North African zones.
Industry Challenges
- Local content obligation compliance:Workforce nationalization quotas in Saudi Arabia and UAE strain project staffing timelines where skilled domestic labor pools remain shallow.
- Carbon disclosure certification timelines:Estidama and emerging Saudi sustainability frameworks demand documentation systems that most regional contractors have not yet operationalized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East & Africa Infrastructure Construction Market |
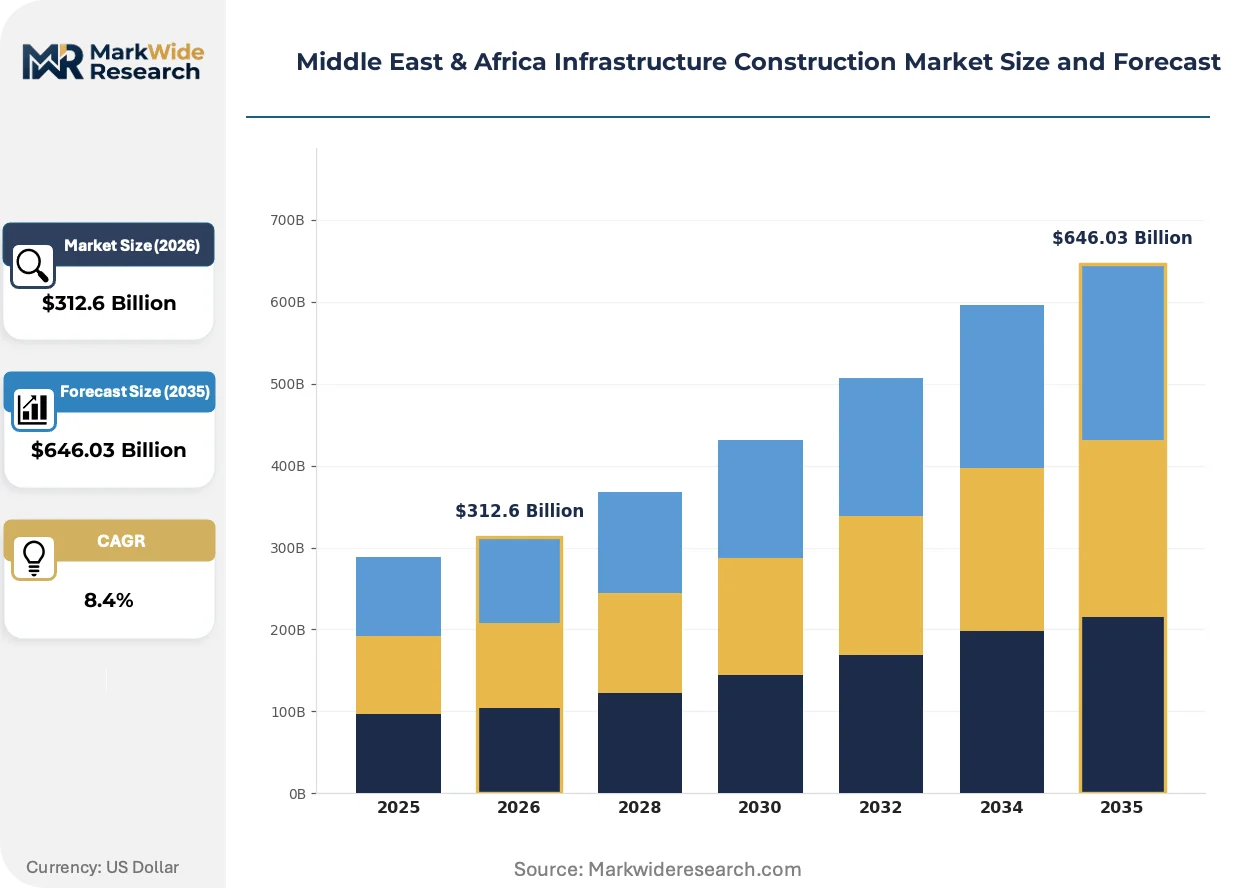
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $646.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: Residential, Commercial, Industrial, Institutional Material Type: Concrete, Steel, Wood, Composite Technology: Modular Construction, BIM, Prefabrication, Smart Building End User: Government, Private Sector, NGOs, Developers |
| Companies Covered | KEO International Consultants, Bechtel, Parsons International, Tiger Group, WorleyParsons, Saudi Binladin Group, Orascom Construction, Arabtec Construction LLC, China State Construction Engineering Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East & Africa Infrastructure Construction Market Trends and Innovations
Digital fabrication and material traceability systems are compressing traditional procurement cycles while elevating compliance documentation burdens across Middle East and Africa project portfolios.
Building Information Modeling (BIM) is integrating clash detection, quantity surveying, and progress monitoring into unified platforms that reduce rework rates on complex giga-project sites. Saudi Arabia's National Project Management Organization mandates BIM Level 2 compliance for public contracts above defined thresholds, accelerating adoption among tier-one contractors. The structural consequence is compressing design-to-construction handover timelines while demanding upstream capability investments from engineering consultancies.
South Africa's National Regulator for Compulsory Specifications enforces SABS-approved material standards that restrict imported steel and cement specifications on public infrastructure. The industrial consequence is redirecting procurement toward domestic mill capacity and certified regional suppliers. Water and transport segments face the steepest compliance costs, with contractors maintaining dual inventory pools to satisfy specification divergence between South African and Gulf Cooperation Council markets.
Long-term service agreements are displacing discrete construction contracts across energy and water assets, with operators bundling decades of maintenance into initial procurement decisions. Saudi Aramco and UAE utility off-takers now structure tenders around availability-based payments rather than capital expenditure milestones. This pattern is most visible in desalination and power generation verticals where operational technology expertise determines contractor selection as heavily as civil construction capability.
Middle East & Africa Infrastructure Construction Market Segmentation
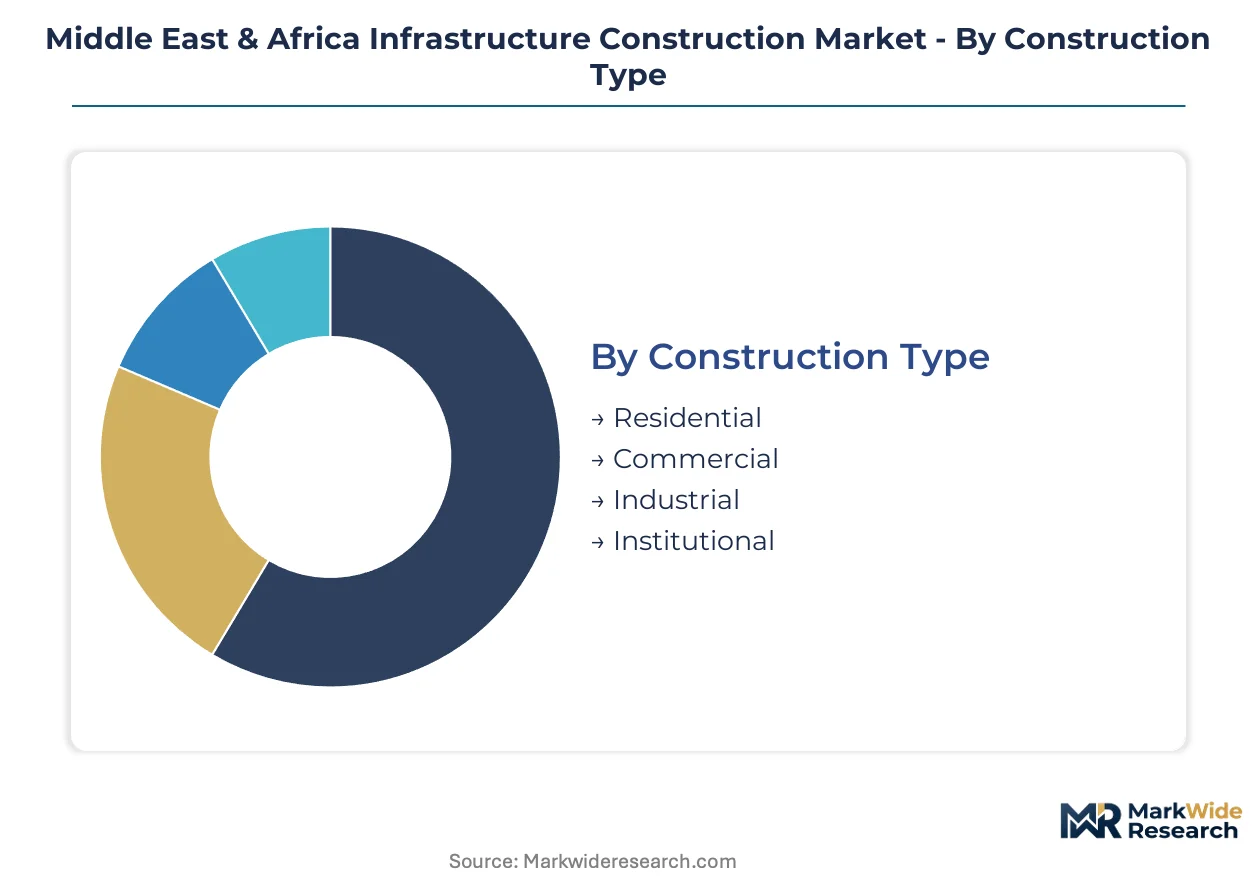
Segmentation in Middle East and Africa infrastructure construction reveals how procurement rules, material specifications, and delivery models diverge across asset classes. Contractors must align capabilities with distinct technical and commercial requirements rather than pursuing undifferentiated market entry.
Construction Type:
Buyers in this category differ by asset lifecycle length and maintenance obligation intensity.
- Residential:Giga-project housing clusters in Saudi Arabia demand rapid-scale delivery with standardized unit repetition. NEOM and Red Sea developments concentrate demand for volume builders capable of modular assembly at desert sites.
- Commercial:UAE office and retail assets face Estidama certification mandates that elevate glazing, HVAC, and envelope specifications. Premium rental rates in Dubai and Abu Dhabi justify higher upfront capital for energy performance compliance.
- Industrial:Logistics hubs and manufacturing zones require heavy foundation engineering for equipment loading.
- Institutional:Healthcare and education assets carry extended warranty terms and operational handover requirements.
Volume sits with Residential; growth tilts toward Commercial.
Material Type:
Cost tiers separate segments by thermal performance needs and supply chain localization.
- Concrete:Dominates transport and water infrastructure due to localized clinker capacity in Egypt, Saudi Arabia, and UAE. Arid-zone thermal stressors drive demand for sulfate-resistant and low-heat hydration formulations on coastal and desert sites.
- Steel:Structural framing for high-rise commercial towers and long-span bridges concentrates procurement around SABS-certified mills in South Africa and GCC re-rolling capacity. Import restrictions elevate domestic premium over landed cost.
- Wood:Limited to interior finishes and temporary works where fire codes permit.
- Composite:Fiber-reinforced polymers gain traction in corrosion-exposed environments like desalination plants and coastal bridges.
Concrete commands current spend; composites are climbing the fastest on specialized applications.
Technology:
Maturity gaps separate early adopters from compliance-driven implementers across contractor tiers.
- Modular Construction:Labor mobility constraints across GCC states accelerate offsite fabrication for repetitive residential and hospitality units. Saudi Arabia's National Project Management Organization mandates modular ratios on select giga-project packages.
- BIM:Saudi Arabia mandates Level 2 compliance for public contracts above defined thresholds, compressing design-to-construction handovers. Engineering consultancies in UAE and Qatar maintain dual certification for Gulf and African market access.
- Prefabrication:MEP rack and facade unit pre-assembly reduces on-site workforce exposure to extreme heat conditions.
- Smart Building:Integrated building management systems concentrate in UAE commercial towers seeking LEED and Estidama Platinum ratings.
BIM anchors regulatory compliance; modular methods gain share fastest where labor supply tightens.
End User:
Contracting risk allocation distinguishes government procurement from private sector deal structures.
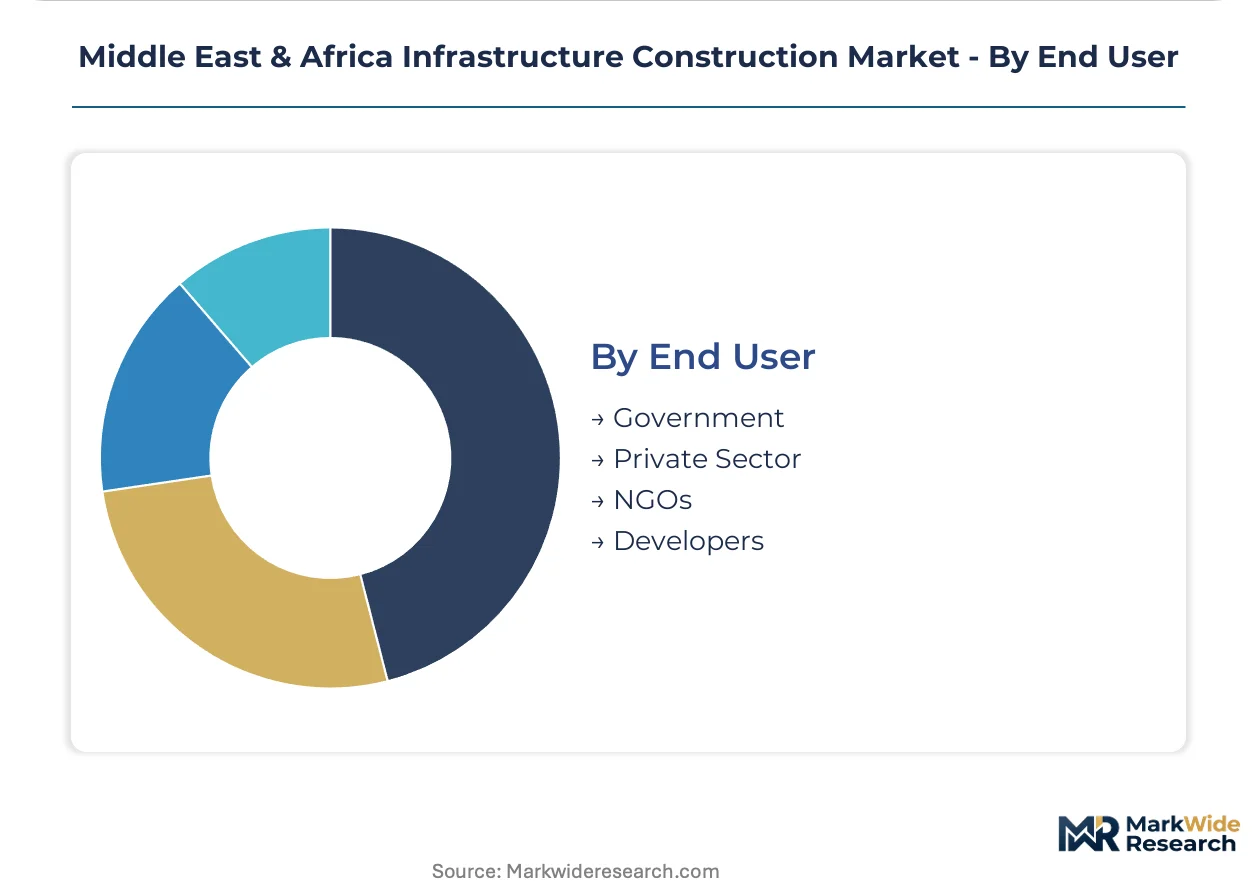
- Government:Commands the largest project pipeline through transport, water, and social infrastructure budgets. Saudi Arabia's National Project Management Organization and South Africa's National Regulator for Compulsory Specifications impose qualification thresholds that filter contractor pools.
- Private Sector:Deepening participation through build-operate-transfer frameworks in UAE and Saudi Arabia energy assets. Long-term availability payments replace milestone-based construction contracts in desalination and power generation.
- NGOs:Concentrate on rural water and health infrastructure with grant-financed delivery models.
- Developers:Mixed-use masterplanning in Dubai, Riyadh, and Lagos drives integrated design-build procurement.
Government contracts dominate awarded value; private sector structures are expanding most quickly on operational technology bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's giga-project corridor concentrates the region's heaviest civil engineering activity, with NEOM and Red Sea developments absorbing capital at unprecedented scale. Transport spine construction and modular residential delivery dominate contractor deployment across the Arabian Peninsula.
Saudi Arabia
NEOM and Red Sea Project transport corridors absorb rising capital as Riyadh accelerates delivery timelines. The National Project Management Organization imposes qualification thresholds and BIM Level 2 mandates that filter contractor pools. Jeddah's logistics hub expansion concentrates demand for heavy foundation engineering and modular assembly capacity.
United Arab Emirates
Commercial tower construction and Estidama-certified mixed-use developments drive material procurement toward lower-carbon concrete and steel specifications. The Estidama program mandates environmental performance thresholds that elevate glazing and envelope standards. Dubai's premium office market justifies higher upfront capital for energy compliance, while Abu Dhabi's masterplanned districts integrate smart building management systems.
South Africa
Water infrastructure renewal and transport backbone maintenance concentrate demand for SABS-certified material compliance. The National Regulator for Compulsory Specifications enforces domestic steel and cement standards that redirect procurement toward local mill capacity. Gauteng's logistics corridor and KwaZulu-Natal's port expansion absorb heavy civil engineering resources amid fiscal constraints.
Egypt
New administrative capital construction and Suez Canal economic zone development sustain demand for integrated design-build delivery. The country's national project authority streamlines contractor qualification for mega-project access. Cairo's eastern desert corridor and Alexandria's port modernization concentrate cement-intensive activity where localized clinker capacity provides cost advantage.
Nigeria
Lagos-Ibadan expressway renewal and port modernization concentrate West Africa's demand for heavy civil engineering capacity. Federal infrastructure budgets and multilateral financing shape project pipelines where regional contractor scarcity creates positioning opportunities. Lagos state's transport spine and Lekki Free Trade Zone absorb foundation engineering and modular construction deployment.
Middle East & Africa Infrastructure Construction Market Competitive Landscape
Capital-heavy integrated EPC contractors compete with asset-light specialist engineering consultancies for project origination and execution control. The vendor base stratifies across tier-one global firms with balance sheet capacity for performance guarantees, regional champions with civil engineering heritage and local partnership networks, and state-linked entities capturing domestic mega-project awards. Strategic moves center on forming consortia to satisfy local content obligations and acquiring modular fabrication capabilities to address labor mobility constraints.
Within the integrated EPC tier, Bechtel and Orascom Construction exemplify contrasting geographic anchoring strategies. Bechtel occupies a position tied to Saudi Arabia's giga-project pipeline through its established National Project Management Organization relationships. Orascom Construction sits within the North African specialist archetype, leveraging deep civil engineering heritage across Egypt and broader regional markets. Parsons International represents the engineering consultancy vector, positioned for design-to-construction handover compression where BIM mandates elevate technical compliance burdens.
| Leading Market Players |
|---|
| KEO International Consultants |
| Bechtel |
| Parsons International |
| Tiger Group |
| WorleyParsons |
| Saudi Binladin Group |
| Orascom Construction |
| Arabtec Construction LLC |
| China State Construction Engineering Corporation |
| Others |
Pricing and Supply Chain Analysis
Skilled civil engineering labor concentration in Egypt and Turkey generates cost differentials that widen pricing-tier spreads across integrated EPC contracts, with Gulf-based projects commanding premiums over North African bids due to workforce mobility premiums and certification compliance burdens.
Pricing Analysis
Availability-based payment structures anchor value-based pricing for desalination and power generation assets, where contractors guarantee operational uptime rather than construction milestones. Pricing stratifies across Estidama Platinum-certified, standard-compliant, and uncertified tiers based on material traceability and carbon disclosure documentation. Cost compression in standard-tier concrete supply is intensifying because single-source clinker capacity exposes projects to energy price volatility. Government end users exhibit highest price sensitivity due to fiscal constraint pressures, while private utility off-takers prioritize lifecycle performance over upfront capital minimization.
Supply Chain Analysis
Regional distribution centers in Jeddah, Dubai, and Cairo orchestrate hub-and-spoke material flows to giga-project sites across the Arabian Peninsula and North Africa. Cement and clinker supply concentrates in Saudi Arabia, Egypt, and UAE, while structural steel procurement draws from SABS-certified South African mills and GCC re-rolling capacity. Reinforced concrete supply rests on imported admixture and domestic clinker dependencies. Single-source vulnerability in national cement markets creates exposure to input cost spikes during energy price cycles. Distribution runs through contractor-controlled on-site batching plants for major transport and water infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over modular fabrication capacity and certified material supply chains determines bid competitiveness on giga-project tenders.
For Market Incumbents: To counter emerging modular construction specialists from Asia-Pacific, anchor market position through backward integration into precast concrete manufacturing and BIM-compliant engineering consultancy acquisitions. Deepen Estidama certification capabilities to capture premium-tier procurement mandates in UAE commercial developments. Prioritize long-term service agreement structuring to displace discrete construction contracts in Saudi energy and water assets.
For New Entrants and Emerging Players: Estidama program expansion in UAE opens a window for green material suppliers specializing in lower-carbon concrete formulations and certified steel procurement. Target Nigeria's Lagos-Ibadan corridor where regional contractor scarcity and multilateral financing concentration create first-mover positioning. Enter through design-build partnerships with established local firms to satisfy National Project Management Organization qualification thresholds without full balance sheet deployment.
For Investors and Strategic Acquirers: The window for entry favors mid-cap civil engineering specialists with modular fabrication assets and established local partnership networks. Acquisition targets should demonstrate compliance capability with Saudi Arabia's BIM Level 2 mandates and UAE carbon disclosure frameworks. Monitor National Project Management Organization procurement rule changes around local content obligations as the primary inflection signal for competitive access shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fabrication Capacity Buildout | Addresses GCC labor mobility constraints while accelerating giga-project delivery timelines for NEOM and Red Sea developments. |
| BIM Level 2 Compliance Investment | Satisfies Saudi Arabia's National Project Management Organization mandates that filter contractor pools on public contracts. |
| Estidama Certification Acquisition | Captures premium-tier demand in UAE commercial towers where environmental performance thresholds elevate material specifications. |
| Local Partnership Consortium Formation | Navigates workforce nationalization quotas and local content obligations across Saudi Arabia and UAE procurement frameworks. |
| Long-Term Service Agreement Structuring | Aligns with Saudi Aramco and UAE utility off-taker shifts toward availability-based payments across desalination assets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with EPC contract directors, project finance officers at multilateral development banks, procurement leads at Saudi Arabia's National Project Management Organization, and engineering consultancy principals. Secondary sources included National Regulator for Compulsory Specifications documentation, Estidama program technical guidelines, and cement industry production statistics. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling enabled triangulation across data streams.
Data-stream reconciliation across construction type, material specification, technology adoption, and end-user segments generated volume and value outputs over the projection horizon. Segmentation dimensions encompassed residential, commercial, industrial, and institutional construction types alongside concrete, steel, and composite material categories. CAGRs were derived from weighted project award trajectories and capital expenditure commitment patterns across the analysis window. Forecast inputs incorporated BIM mandate compliance timelines and modular construction adoption curves.
Caveats apply where regulatory revisions to local content obligations or carbon disclosure certification timelines could materially shift the outlook for contractor competitive positioning. Forecasts reflect documented assumptions around giga-project delivery schedules and multilateral financing availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
North America Modular Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
Japan Commercial Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
France Prefab Homes Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
Thailand Construction Market
Building Construction
US Prefabricated Buildings Market
Building Construction
Construction Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
Vietnam Construction Market