
 Rebar Tier Market | 2026-2036
Rebar Tier Market Size, Share, and Industry Trends Forecast 2026-2036
Rebar Tier Market Analytics
Maintenance and calibration service contracts for automated rebar tying equipment is shifting from aftermarket add-on to bundled core offering, reshaping how contractors evaluate total cost of ownership. Makita Corporation leverages its power tool service network to sustain recurring revenue streams across job sites. Max Co., Ltd. anchors its position through pneumatic tool specialization in Japanese commercial construction. Wacker Neuson SE competes by extending equipment lifecycle support for European infrastructure contractors.
Rebar tier equipment mechanically fastens steel reinforcement bars using wire-fed tying guns, battery-powered tools, or pneumatic systems operating at 0.5–1.2 second cycle speeds per tie to secure concrete structural frameworks. The technology eliminates manual hand-tying, reducing repetitive strain injuries while improving consistency in high-rise and bridge applications. Deformed rebar commands the largest product type position due to its superior concrete bond strength in load-bearing walls and foundations. High strength material grade segments are gaining share as seismic design codes tighten across Pacific Rim construction markets. Infrastructure end users generate the most consistent equipment replacement cycles compared to volatile residential project timelines.
OSHA workplace ergonomics enforcement in the United States and MEE construction noise and dust regulations in China are mandating reduced manual handling exposure, directly expanding addressable demand for powered tying solutions. ISO 9001 quality certification and CE marking requirements in Europe filter import competition while elevating product liability standards for battery-powered job site equipment. Stakeholders must weigh regional certification burdens against localized manufacturing partnerships when prioritizing market entry sequencing.
Market Dynamics
OSHA ergonomics enforcement and China's MEE construction dust mandates are systematically eliminating manual rebar tying from commercial job sites, forcing contractors to absorb powered equipment capital costs or exit bidding pools entirely.
Growth Catalysts
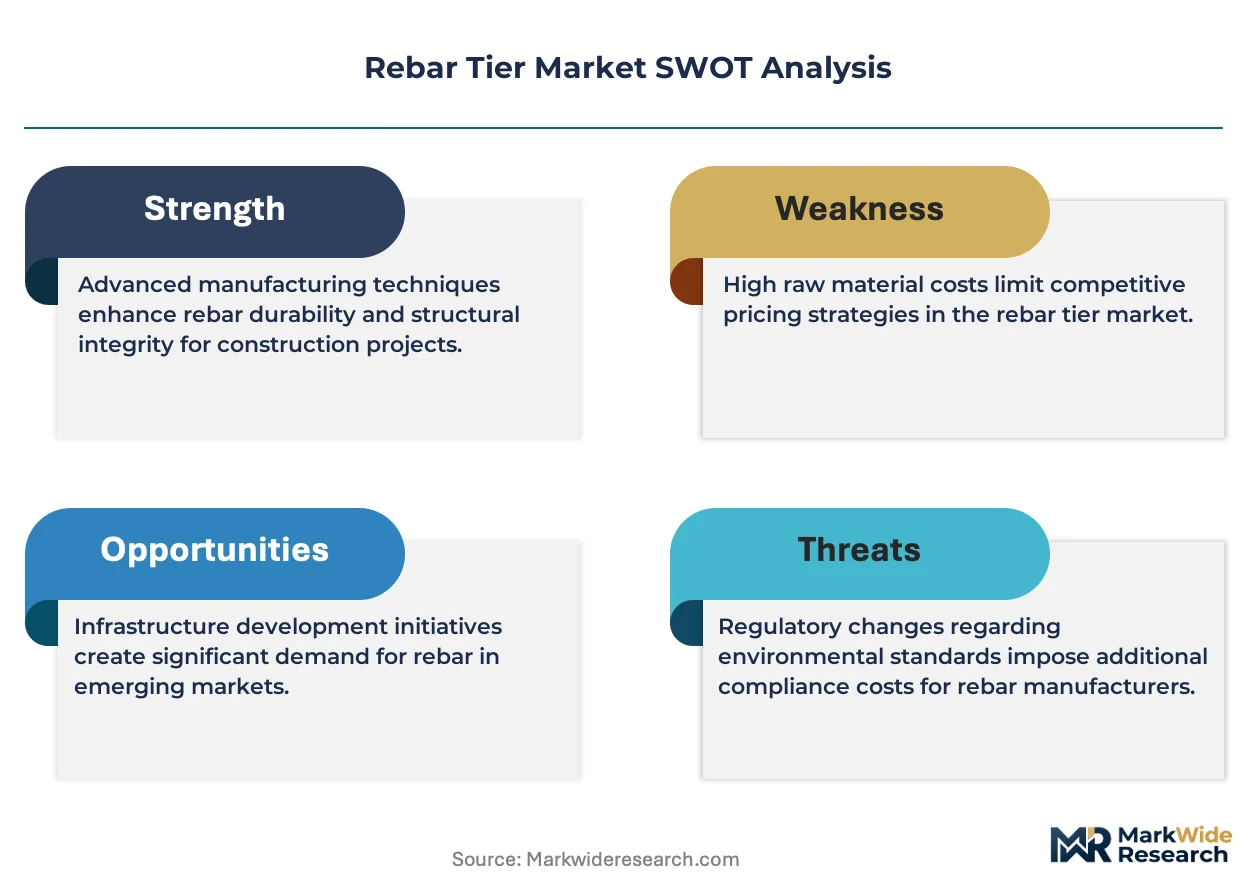
- OSHA Workplace Ergonomics Directives:US commercial contractors face citation exposure for repetitive strain injuries in high-rise steel framing, accelerating battery-powered tier adoption across unionized job sites.
- Deformed Rebar Specification Dominance:Seismic design codes in Pacific Rim markets specify high-bond reinforcement grades that demand consistent mechanical tying torque manual workers cannot reliably deliver.
- Infrastructure Budget Expansion:Bridge and highway appropriations in China, India, and the United States create sustained equipment replacement cycles independent of residential construction volatility.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Tier manufacturers depend on Chinese cell suppliers for cordless tool power packs, exposing production schedules to export control disruptions and raw material price swings.
- Pneumatic System Infrastructure Requirements:Compressed air compressor deployment on remote bridge and tunnel sites adds capital burden that battery alternatives circumvent, fragmenting technology choice by project geography.
- Manual Tying Labor Cost Arbitrage:Informal construction labor markets in South Asia and Southeast Asia sustain wage rates below powered equipment payback thresholds, capping addressable market penetration.
Strategic Opportunities
- India Infrastructure Pipeline:National highway and metro rail expansion creates first-time mechanized tier demand among domestic contractors lacking legacy pneumatic infrastructure.
- Service Contract Bundling:Maintenance and calibration subscriptions shift from aftermarket add-on to core equipment value proposition, locking recurring revenue and raising switching costs.
- Battery-Pneumatic Hybrid Platforms:Dual-power tool architectures bridge job site air supply gaps while preserving pneumatic speed advantages for high-volume foundation work.
Industry Challenges
- CE Marking Certification Timelines:European battery-powered job site equipment faces extended conformity assessment periods that delay product launches and compress selling seasons.
- Wire Feed Mechanism Calibration:Field technicians require specialized training to maintain consistent tie tension across varying rebar diameters and corrosion conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rebar Tier Market |
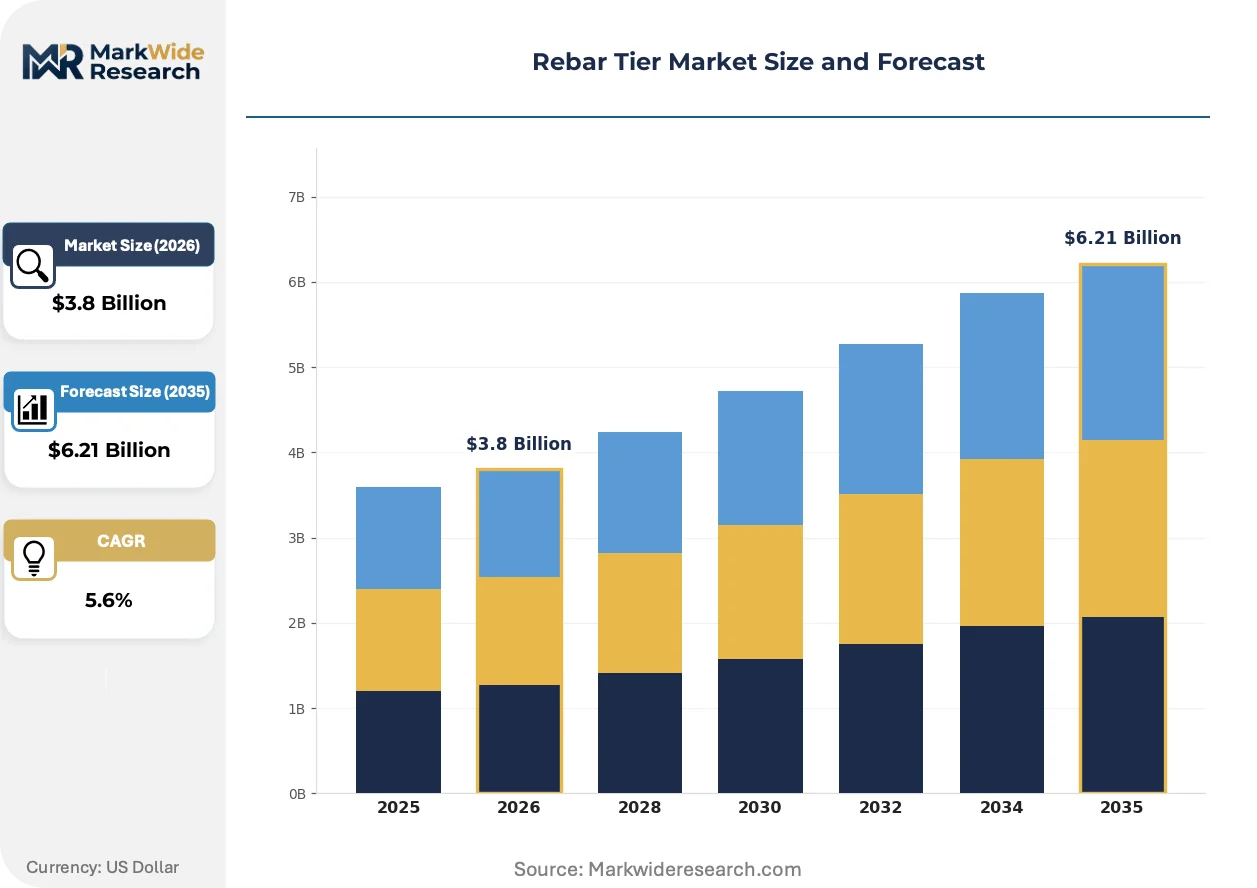
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Rebar, Deformed Rebar, Epoxy-Coated Rebar, Galvanized Rebar End User: Construction, Infrastructure, Residential, Commercial Distribution Channel: Direct Sales, Distributors, Retailers, E-commerce Material Grade: High Strength, Low Alloy, Mild Steel, Others |
| Companies Covered | BN Products-USA, LLC, Rapid Tool Australia Ltd., Max Co., Ltd., Benner-Nawman Inc., Pexgun, Makita Corporation, Wacker Neuson SE, Xyltron, DeWalt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rebar Tier Market Evolving Landscape
Battery chemistry advances and ergonomic design refinements are collapsing the performance gap between cordless and pneumatic tying systems, redrawing competitive boundaries across commercial construction segments.
Brushless motor controllers paired with high-density lithium-polymer cells is decentralizing job site power infrastructure for rebar tying operations. Mid-rise concrete contractors in Texas and Florida are deploying battery tiers exclusively, eliminating compressor rental logistics and noise complaints from urban neighbors. This shift compresses project mobilization timelines and expands bidding eligibility for contractors lacking capital for pneumatic system investments.
China's MEE construction noise and dust regulations mandate reduced manual handling exposure in commercial building envelopes. The policy forces state-owned contractors to document powered equipment deployment in environmental impact filings. High-rise residential towers in Shanghai and Shenzhen now specify mechanical tying in bid documents, filtering subcontractor pools to equipment-capable firms.
Equipment-as-a-service contracts are displacing outright purchase for mid-tier contractors managing project portfolio volatility. German and Austrian infrastructure specialists lease tying systems with bundled maintenance, converting capital expenditure to operational line items. This model concentrates most visible in European public-private partnership bridge contracts where equipment utilization spans multiple subcontractors.
Rebar Tier Market Segmentation
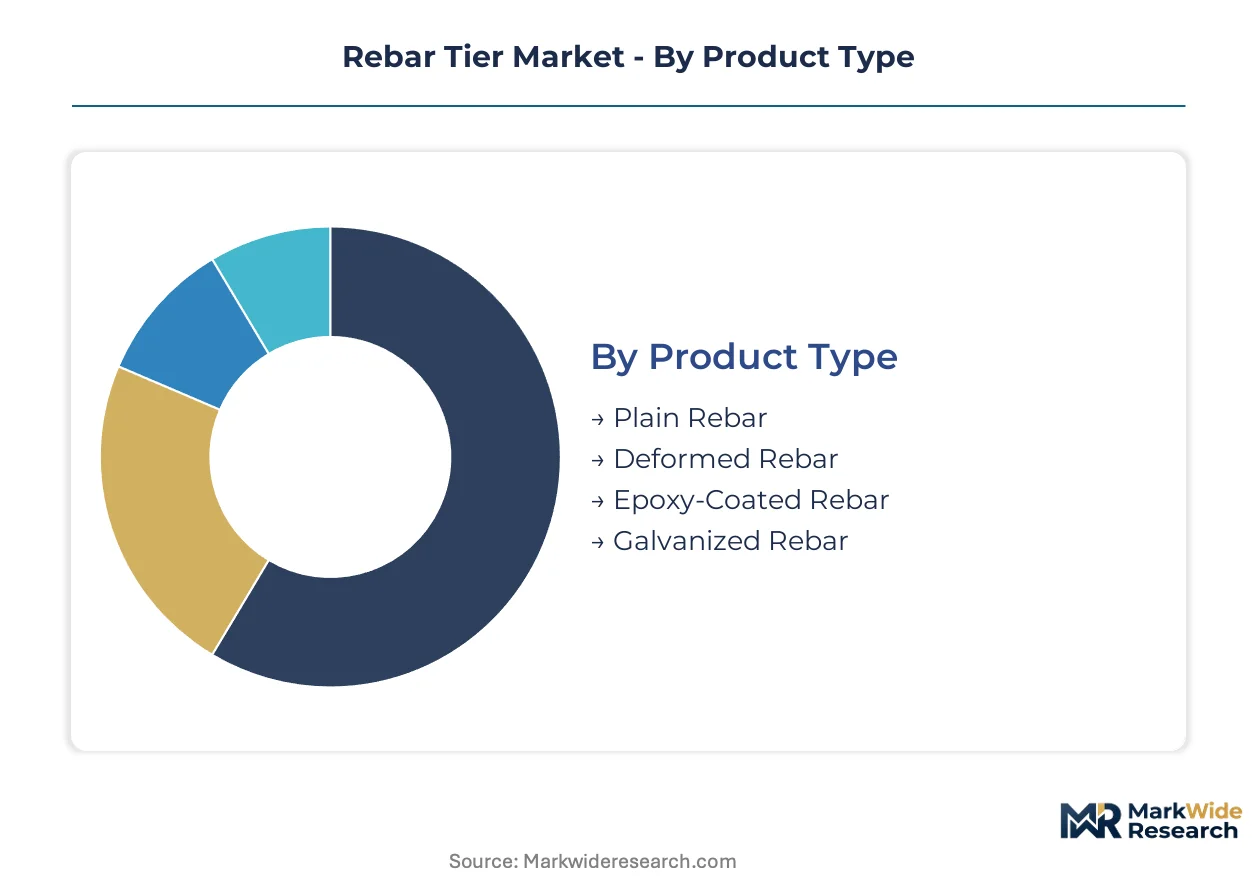
Segmentation in rebar tier equipment reveals how tying technology specifications align with reinforcement bar geometries and project scale. Contractors select tying systems based on rebar surface patterns, material tensile ratings, and procurement channel reliability rather than generic power ratings.
Product Type:
Supply concentration in tying equipment manufacturing clusters around deformed rebar compatibility, as ribbed surface geometries demand precise wire tension calibration that plain bar systems cannot deliver.
- Deformed Rebar:Ribbed surface patterns enhance concrete bond strength through mechanical interlock. Seismic design codes in Japan and California specify deformed grades exclusively, forcing contractors to deploy torque-calibrated tying systems for consistent embedment performance.
- Plain Rebar:Smooth cylindrical profiles suit low-load applications where bond stress remains minimal. Historical building restoration in Italy and heritage bridge repair in the United Kingdom sustains niche demand for compatible manual and semi-automatic tying tools.
- Epoxy-Coated Rebar:Polymer barrier protection against chloride intrusion commands premium tying equipment with non-marring wire guides. Coastal highway projects in Florida and marine infrastructure in the Netherlands specify coated reinforcement for durability.
- Galvanized Rebar:Zinc metallurgical coating extends service life in exposed environments. Australian mining infrastructure and Nordic tunnel projects drive procurement of tying systems compatible with slightly oversized bar diameters.
Deformed rebar absorbs the bulk of installed capacity; epoxy-coated rebar is expanding most quickly.
End User:
Application scale determines equipment mobility requirements, with infrastructure contractors prioritizing pneumatic durability while residential specialists favor battery portability.
- Infrastructure:Bridge decks, highway barriers, and rail systems demand continuous high-volume tying cycles. China's state-owned construction enterprises deploy pneumatic tiers on mega-projects where compressor infrastructure amortizes across multi-year timelines.
- Construction:General contracting encompasses mixed commercial and institutional builds requiring flexible equipment fleets. German mid-size contractors lease hybrid battery-pneumatic systems to match project-specific mobilization constraints.
- Commercial:High-rise concrete cores and parking structures favor battery-powered tools for vertical transport efficiency. Unionized job sites in New York and Chicago specify ergonomic tying equipment to satisfy OSHA workplace injury prevention mandates.
- Residential:Single-family foundations and low-rise framing sustain manual tying in cost-sensitive markets. Informal labor pools in Indonesia and Vietnam price powered equipment below viability thresholds for most residential developers.
Infrastructure commands the dominant equipment deployment volume; commercial applications are climbing the fastest as urban density intensifies.
Distribution Channel:
Channel selection reflects contractor scale and equipment sophistication, with direct relationships dominating fleet purchases while spot rentals flow through distributor networks.
- Direct Sales:Original equipment manufacturers engage national contractors and rental houses through dedicated account teams. Max Co., Ltd. and Makita Corporation maintain direct relationships with Japanese general contractors for bulk fleet procurement and service contract bundling.
- Distributors:Regional equipment dealers provide local inventory, technical training, and warranty administration. Wacker Neuson SE leverages European distributor density to reach infrastructure subcontractors in secondary German and Austrian markets.
- Retailers:Big-box construction supply chains serve small contractors and maintenance departments with standardized battery tier SKUs. Home Depot and Lowe's in the United States stock consumer-grade tying tools for residential concrete crews.
- E-commerce:Online procurement gains traction among independent contractors comparing specifications and pricing transparency. Alibaba and Amazon Business channels expand in China and North America for replacement parts and consumable wire coils.
Direct sales capture the majority of revenue value; e-commerce is gaining share fastest among independent operators.
Material Grade:
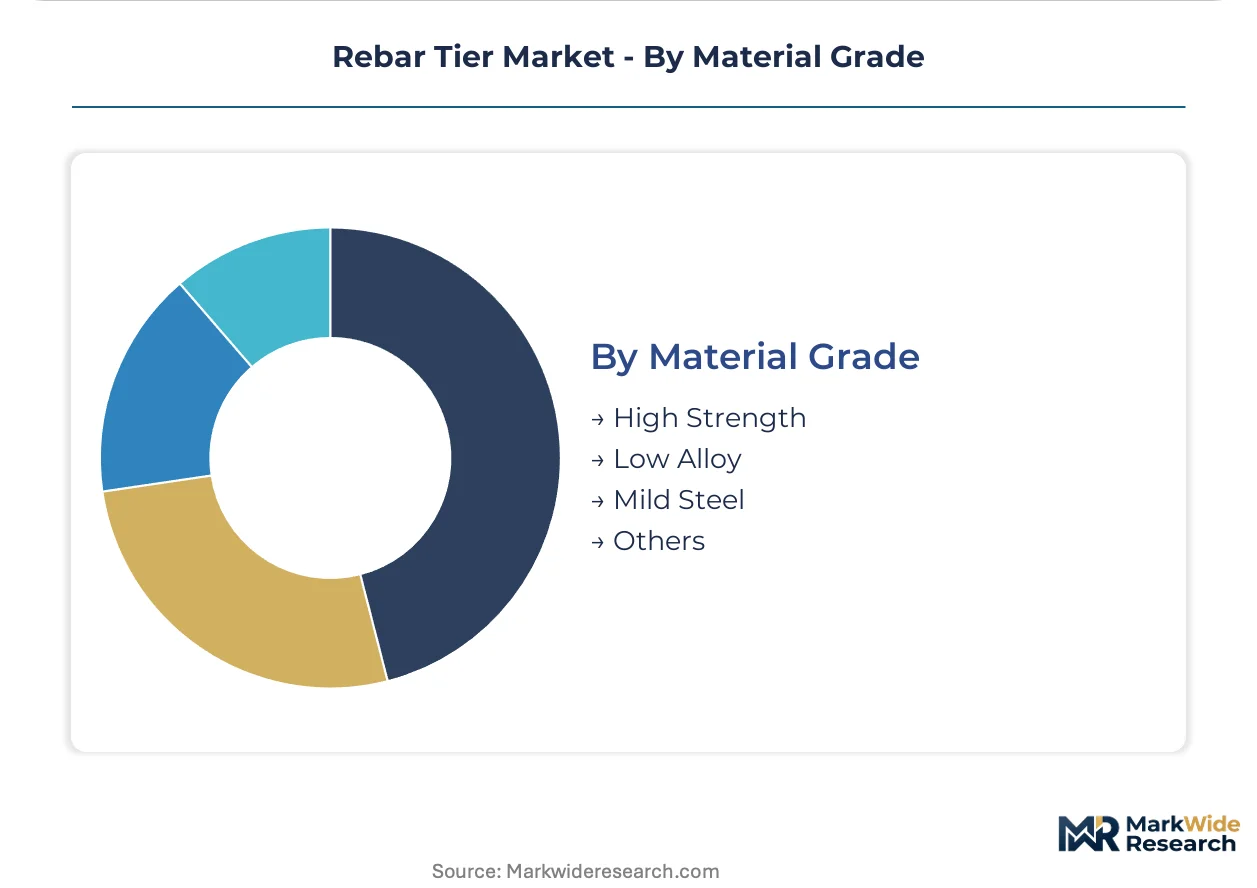
Strength specifications dictate tying torque requirements and wire gauge selection, with high-strength grades demanding reinforced equipment frames.
- High Strength:Grades exceeding 60 ksi yield strength require elevated tying tension to secure load-transfer integrity. Pacific Rim seismic zones in Taiwan and Chile specify high-strength reinforcement, driving demand for pneumatic tiers with calibrated pressure regulators.
- Low Alloy:Micro-alloyed compositions enhance weldability and ductility for complex structural geometries. Indian metro rail and Saudi giga-project specifications favor low-alloy grades compatible with mechanized tying uniformity.
- Mild Steel:Standard carbon grades suit non-critical structural elements where manual tying remains economically viable. Secondary construction markets in Bangladesh and Nigeria sustain mild steel demand with basic tying equipment.
- Others:Stainless and composite reinforcement bars occupy specialty niches requiring adapted tying mechanics. Swiss tunneling projects and Qatari coastal developments specify corrosion-resistant grades with modified wire compositions.
High strength grades dominate equipment specification intensity; low alloy grades are expanding most quickly in emerging infrastructure markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of battery cell supplies for cordless rebar tiers while the United States and India absorb the largest equipment deployment volumes. This production-consumption divide shapes trade flows and regional pricing structures.
United States
Commercial high-rise construction in New York and Chicago drives battery-powered tier adoption as unionized job sites enforce OSHA workplace ergonomics mandates. The Department of Labor's repetitive strain injury citation protocols pressure contractors to eliminate manual tying methods. Texas and Florida mid-rise concrete contractors now deploy cordless tiers exclusively, bypassing compressor logistics entirely.
China
State-owned construction enterprises on mega-bridge and highway projects sustain pneumatic tier demand where compressor infrastructure amortizes across multi-year timelines. MEE construction noise and dust regulations in Shanghai and Shenzhen now mandate powered equipment documentation in environmental impact filings. High-rise residential towers in these cities specify mechanical tying in bid documents, filtering subcontractor pools.
Germany
Infrastructure contractors lease hybrid battery-pneumatic systems through equipment-as-a-service contracts that convert capital expenditure to operational line items. CE marking requirements for battery-powered job site equipment extend conformity assessment periods, delaying product launches. Bavarian and North Rhine-Westphalian bridge specialists concentrate deployment across public-private partnership contracts.
India
National highway and metro rail expansion creates first-time mechanized tier demand among domestic contractors lacking legacy pneumatic infrastructure. Bureau of Indian Standards certification requirements for construction equipment filter import competition while elevating product liability standards. Maharashtra and Gujarat infrastructure corridors anchor equipment procurement clusters.
Japan
Seismic design codes specify deformed rebar grades exclusively, forcing contractors to deploy torque-calibrated tying systems for consistent embedment performance. METI industrial standards shape equipment specifications for domestic commercial construction. Tokyo and Osaka metropolitan high-rise cores favor battery-powered tools for vertical transport efficiency.
Rebar Tier Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the rebar tier market, with integrated manufacturers maintaining in-house compressor and motor production while specialist firms outsource component fabrication. The vendor base splits between diversified power tool conglomerates and dedicated tying equipment specialists. Three archetypes dominate: pneumatic system traditionalists, battery-powered innovators, and hybrid platform developers. Competitive moves concentrate on service contract bundling and regional certification partnerships rather than raw capacity expansion.
Among Japanese specialists, Max Co., Ltd. and Makita Corporation exemplify divergent strategic positions within the Pacific Rim equipment ecosystem. Wacker Neuson SE anchors European infrastructure contracting relationships through lifecycle support programs. These three firms represent distinct geographic anchoring strategies—Japanese precision engineering, German equipment-as-a-service models, and diversified power tool distribution networks—each occupying positions that shape regional procurement patterns.
| Leading Market Players |
|---|
| BN Products-USA, LLC |
| Rapid Tool Australia Ltd. |
| Max Co., Ltd. |
| Benner-Nawman Inc. |
| Pexgun |
| Makita Corporation |
| Wacker Neuson SE |
| Xyltron |
| DeWalt |
| Others |
Value Network & Pricing Analysis
State-owned construction enterprises in China anchor procurement volume for pneumatic rebar tiers, locking in project-based contract pricing that bundles equipment leasing with compressor infrastructure across multi-year highway and bridge timelines. This buyer concentration forces private contractors in North America and Europe toward subscription service models that convert capital expenditure to predictable operational line items.
Pricing Analysis
Cost-down pressure on battery-powered tiers accelerates because Chinese cell suppliers dominate lithium-ion power pack production, exposing OEMs to raw material volatility and export control risk. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European equipment from BIS-certified Indian variants and unbranded Chinese imports. Price differentiation hinges on ISO 9001 quality certification and bundled maintenance service intensity. Informal construction labor markets in Southeast Asia exhibit extreme price sensitivity, while unionized commercial contractors in the United States prioritize ergonomic compliance over unit cost.
Supply Chain Analysis
India's Bureau of Indian Standards certification requirements and China's domestic-content preferences for state-owned projects are reshaping sourcing patterns toward localized assembly partnerships. Battery cell production concentrates in China, South Korea, and Japan, while pneumatic compressor manufacturing draws from Germany and Italy. Brushless motor controllers and high-tensile tying wire represent critical component dependencies. Single-source vulnerability in Chinese lithium supply creates structural risk. Distribution runs through dedicated equipment dealers in Europe, direct OEM relationships in Japan, and big-box retail channels in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-powered tying systems are displacing pneumatic infrastructure across mid-rise commercial construction, compressing the performance gap that historically segmented job site equipment categories. This technology transition rewards vendors who bundle calibration services with cordless platforms while penalizing pure-play pneumatic specialists.
For Market Incumbents: To counter battery-powered entrants eroding pneumatic market share, Makita Corporation and Max Co., Ltd. must deepen backward integration into brushless motor production and secure captive cell supply agreements with Korean battery suppliers. Certification investment in India's BIS pathway and Europe's extended CE marking timelines locks out fast-followers from premium procurement channels. For New Entrants and Emerging Players: Mid-tier Indian contractors lacking legacy pneumatic infrastructure represent the most penetrable buyer archetype, with national highway and metro rail expansion creating first-time mechanized demand. Target Maharashtra and Gujarat infrastructure corridors through equipment-as-a-service leasing with bundled technician training. A direct sales model bypassing distributor markups captures price-sensitive domestic contractors. For Investors and Strategic Acquirers: Distressed-cycle entries favor European equipment-as-a-service specialists with established public-private partnership bridge contracts in Germany and Austria. Long-term viability hinges on recurring service revenue streams rather than transactional equipment sales. Monitor India's Bureau of Indian Standards enforcement intensity as the inflection signal for import substitution opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Service Contract Bundling | Maintenance subscriptions convert capital expenditure to recurring revenue across German infrastructure contractors. |
| Battery-Pneumatic Hybrid Development | Dual-power architectures bridge job site air supply gaps while preserving pneumatic speed for foundation work. |
| Regional Certification Partnerships | CE marking and BIS pathway investments filter import competition in Europe and India. |
| Backward Integration into Motors | In-house brushless controller production reduces dependency on Taiwanese semiconductor suppliers. |
| Equipment-as-a-Service Expansion | Leasing models with bundled maintenance raise switching costs among mid-tier commercial contractors. |
Research Methodology
Independent corroboration across equipment procurement managers at state-owned Chinese construction enterprises, aftermarket service directors at Japanese power tool manufacturers, and rental fleet managers in Texas and Florida underwrites the qualitative findings. Primary interviews with plant engineers, maintenance directors at commercial general contractors, and distributor technical training heads combined with secondary validation from OSHA enforcement databases, MEE environmental filing records, and customs trade data. Bottom-up equipment deployment estimates triangulate against top-down infrastructure budget appropriations.
Historical reference periods spanning pre-regulatory enforcement and post-mandate implementation anchor the forecast window across the projection horizon. Segmentation dimensions modeled include tying technology type, rebar surface geometry, end-use application scale, material strength grade, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and infrastructure budget elasticity. Battery chemistry cost curves and pneumatic compressor rental rate trajectories feed industry-specific forecast inputs.
Revisions become necessary when lithium export controls tighten, OSHA ergonomics enforcement intensity shifts, or India's BIS certification timelines accelerate. Forecasts reflect documented assumptions regarding infrastructure budget continuity and battery cell supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
India Transportation Infrastructure Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
Concrete Canvas Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Sweden Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Composite Railroad Tie Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Ship Port Infrastructure Market