
 Global Manhole Covers Market | 2026-2036
Global Manhole Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Manhole Covers Market Foresight
A skilled foundry labor shortage across traditional casting hubs is unwinding capacity expansion timelines for manhole cover producers. EJ Group sustains vertical integration from melt to finished casting across its European and North American plants. Saint-Gobain leverages materials science expertise to dominate high-performance composite cover segments. Fibrelite specializes in lightweight fiber-reinforced solutions that reduce manual-handling injuries for utility workers.
Manhole covers are load-rated access panels, typically cast from iron alloys or molded from polymer composites, designed to seal underground utility vaults while supporting vehicular and pedestrian traffic per EN 124 or ASTM A48/A536 standards. Ductile iron occupies the largest volume share due to its superior tensile strength and impact resistance versus gray cast iron alternatives. Composite covers represent the fastest-expanding material category as municipalities in coastal and chemically aggressive environments prioritize corrosion immunity and theft deterrence. Municipal infrastructure commands the dominant application share, though transportation networks are generating disproportionate specification upgrades as highway agencies adopt higher load-class covers for expanding truck corridors.
FDA oversight of polymer resins in potable-water-adjacent applications, EPA stormwater management mandates, and EN 124 load-class certification enforced by European national metrology institutes collectively shape product compliance costs and market access barriers. India's BIS IS 1726 standard and China's GB/T 23858 specifications create additional testing obligations for exporters serving Asian procurement tenders. Stakeholders must monitor evolving polymer recycling regulations and emerging digital asset-tagging requirements that will reshape material selection and supply chain traceability obligations.
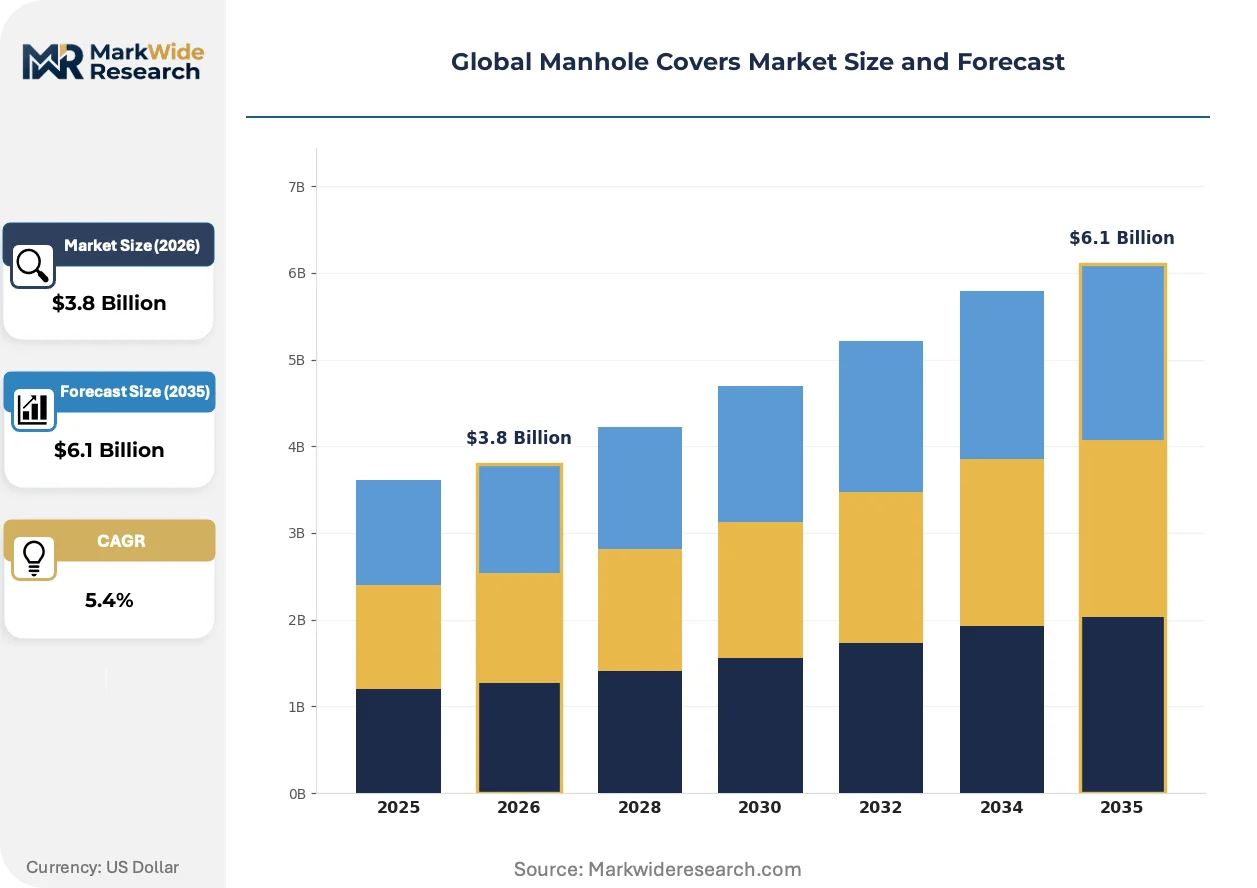
Market Dynamics
The manhole covers market faces a structural squeeze between foundry capacity constraints in traditional casting regions and accelerating specification upgrades toward corrosion-resistant composite materials. Municipal procurement offices in coastal cities now routinely specify polymer-based alternatives alongside legacy iron grades, bifurcating supplier qualification requirements.
Growth Catalysts
- India's Smart Cities Mission:Urban infrastructure agencies under this national directive are expanding sewer network coverage, driving tender volumes for ductile iron and composite access covers across 100 designated municipalities.
- EN 124 Load-Class Upgrades:European highway authorities are mandating higher certification tiers for truck corridor maintenance covers, forcing replacement cycles and specification migrations.
- Composite Theft Deterrence:Resin-based covers carry negligible scrap value versus cast iron, eliminating replacement costs from metal theft that plague utilities in volatile commodity environments.
Market Restraints
- Foundry Labor Scarcity:Traditional casting hubs in Germany and Japan face skilled mold-maker shortages that extend lead times for ductile iron orders beyond 16 weeks.
- Petrochemical Feedstock Volatility:Composite cover producers depend on epoxy and fiberglass resin supplies whose pricing tracks crude oil and natural gas derivatives.
- Legacy Asset Lock-In:Municipalities with decades-old iron cover inventories face budget constraints preventing synchronized material transitions, slowing composite penetration.
Strategic Opportunities
- Indonesia's Urbanization Wave:Jakarta and Surabaya infrastructure agencies lack established supplier relationships, creating first-mover positioning for certified exporters.
- RFID-Enabled Asset Tracking:Converging digital tagging with composite molding allows utilities to monitor cover displacement and maintenance history through centralized fleet management platforms.
- EU Green Public Procurement:Recycled-content mandates in municipal tenders favor manufacturers with closed-loop polymer reclamation capabilities.
Industry Challenges
- Multi-Jurisdiction Certification Burden:Exporters must simultaneously maintain EN 124, ASTM A48/A536, BIS IS 1726, and GB/T 23858 test documentation, stretching quality assurance teams across incompatible protocols.
- Casting Equipment Obsolescence:Gray iron foundries seeking ductile iron capability face seven-figure furnace and inoculation system investments with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Manhole Covers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cast Iron, Ductile Iron, Steel, Composite, Concrete, Plastic Installation Type: Surface Mounted, Recessed, Flush, Elevated Application: Municipal Infrastructure, Industrial Facilities, Commercial Complexes, Transportation Networks, Utility Services, Public Parks End User: Municipal Corporations, Utility Providers, Industrial Plants, Construction Companies |
| Companies Covered | EJ Group, Inc., Saint-Gobain, Fibrelite, Crescent Foundry, Neenah Foundry, Eagle Manufacturing Group, Ducast Factory, Polieco Group, U.S. Foundry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Manhole Covers Market Shifts & Advancements
Material science advances and digital infrastructure requirements are actively rewiring competitive advantage in access cover manufacturing. Suppliers now compete on corrosion immunity and telemetry integration rather than purely mechanical load ratings.
Glass-reinforced polymer formulations are fragmenting the traditional iron-dominated product hierarchy. These composites deliver one-third the weight of ductile iron equivalents while eliminating galvanic corrosion in coastal sewer environments. Water utilities in Florida and the Netherlands are specifying them for tidal zone vaults. The technology is fragmenting procurement categories by creating a parallel specification track that bypasses foundry supply chains entirely.
REACH chemical registration requirements are tightening monomer and additive disclosure obligations for European composite manufacturers. Formulators must now document Substances of Very High Concern across resin supply chains, elevating compliance costs for smaller molders. German utilities are responding by consolidating supplier panels toward vertically integrated polymer compounders with in-house toxicology documentation.
Specification-driven vendor consolidation is compressing qualified supplier lists in municipal procurement. Transportation agencies in California and Texas now require pre-approval through centralized engineering review before bid eligibility, displacing spot-market purchasing. This behavioral shift concentrates volume among incumbent certified producers and raises barriers for new market entrants lacking multi-year track records.
Global Manhole Covers Market Segmentation
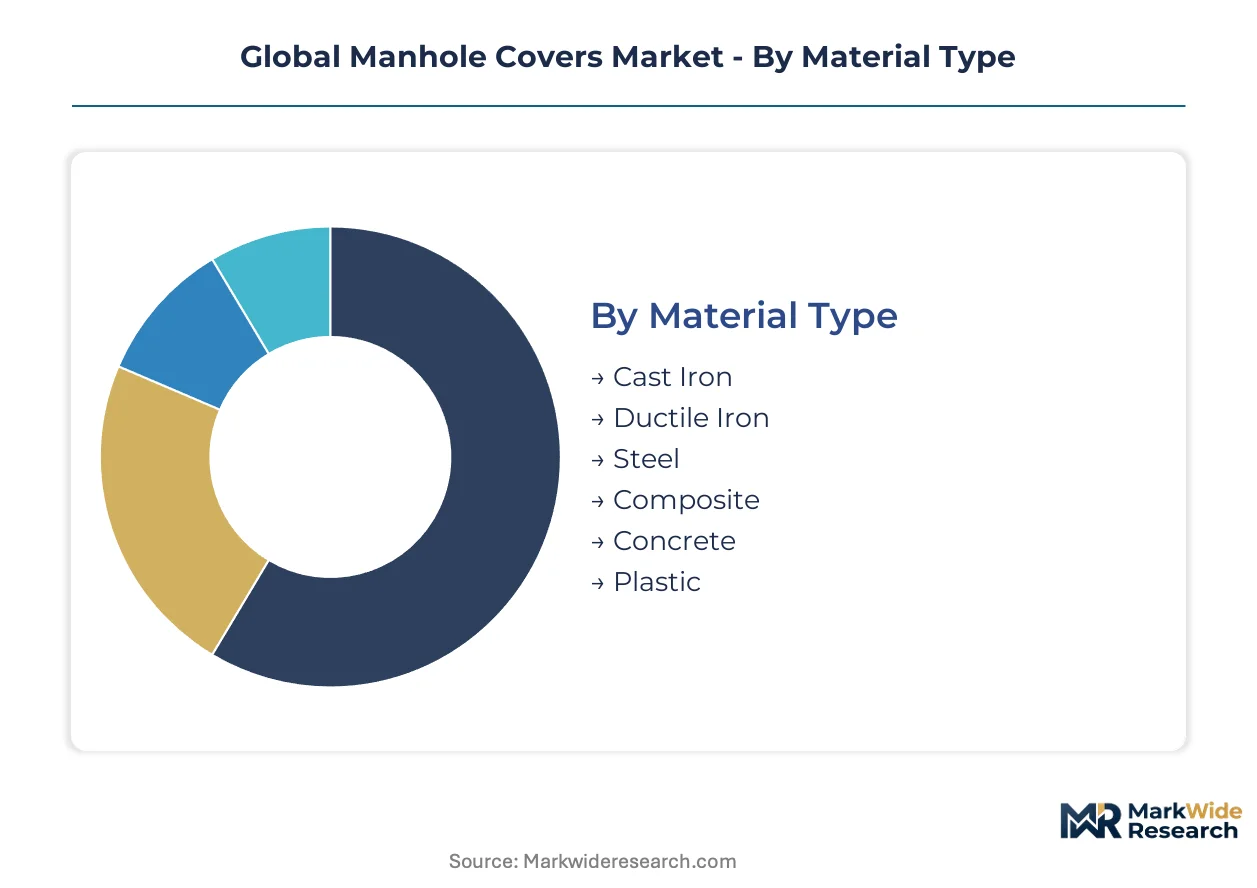
Material chemistry and installation geometry determine procurement economics for underground access systems. Specification engineers balance load ratings against corrosion exposure, theft risk, and crew handling ergonomics when segmenting supplier panels.
Material Type:
Margin pools concentrate in corrosion-resistant formulations that command specification premiums in coastal and chemically aggressive environments.
- Ductile Iron:Spheroidal graphite microstructure delivers tensile strength exceeding gray cast iron by 50% while maintaining castability for complex frame-and-cover geometries. India's Smart Cities Mission procurement offices specify this grade for urban sewer expansion across 100 designated municipalities, though foundry lead times now stretch beyond 16 weeks due to skilled mold-maker shortages.
- Composite:Glass-reinforced polymer matrices achieve one-third the weight of metallic equivalents while eliminating galvanic corrosion and scrap-value theft. Water utilities in Florida and the Netherlands specify these for tidal zone vaults where salt exposure degrades iron within service cycles.
- Cast Iron:Flake graphite structure suits static loads in low-corrosion inland environments where procurement budgets prioritize first-cost over lifecycle replacement.
- Steel:Fabricated plate construction serves temporary access and construction-phase applications requiring field-modifiable dimensions.
- Concrete:Precast reinforced sections handle non-trafficable utility vaults in pedestrian-only zones with minimal dynamic loading.
- Plastic:Injection-molded polypropylene covers address light-duty residential drainage where load ratings below EN 124 Class A suffice.
Cast Iron holds installed capacity. Composite is rotating up the share rankings.
Installation Type:
Volume concentration tracks urban surface renewal intensity, with flush-mount specifications expanding alongside pedestrian-priority street redesigns.
- Surface Mounted:Frame-and-cover assemblies sit proud of finished grade, simplifying replacement in legacy iron inventories where recess depths vary. German municipal maintenance crews favor this geometry for rapid swap-out during emergency sewer access.
- Recessed:Cover surfaces sit below frame level to receive infill matching surrounding pavement. European highway authorities mandate this configuration for truck corridor maintenance covers undergoing EN 124 load-class upgrades.
- Flush:Precise elevation matching eliminates trip hazards and accommodates shared pedestrian-cyclist surfaces. Urban designers in Copenhagen and Amsterdam specify these for complete streets projects.
- Elevated:Raised profiles manage stormwater ponding in flood-prone districts where surcharge events exceed standard frame heights.
Surface Mounted dominates replacement demand. Flush is climbing the fastest as streetscape integration standards tighten.
Application:
Customer procurement scale varies dramatically, with transportation agencies consolidating volume through centralized engineering pre-approval while municipal infrastructure fragments across thousands of independent purchasing offices.
- Municipal Infrastructure:Sewer, water, and stormwater networks constitute the foundational demand pool, with India's urban renewal directives expanding tender volumes across state-level public works departments.
- Transportation Networks:Highway agencies in California and Texas now require pre-approval through centralized engineering review before bid eligibility, concentrating volume among incumbent certified producers.
- Industrial Facilities:Petrochemical and power generation sites specify heavy-duty ductile iron or specialized composite formulations for process-area containment.
- Commercial Complexes:Private development projects balance aesthetic integration with loading dock access requirements.
- Utility Services:Telecommunications and electrical vaults prioritize non-conductive composite covers for worker safety in energized environments.
- Public Parks:Landscape-integrated designs emphasize visual continuity over load-bearing capacity in pedestrian-only zones.
Municipal Infrastructure anchors volume. Transportation Networks is gaining share fastest as highway specification upgrades accelerate replacement cycles.
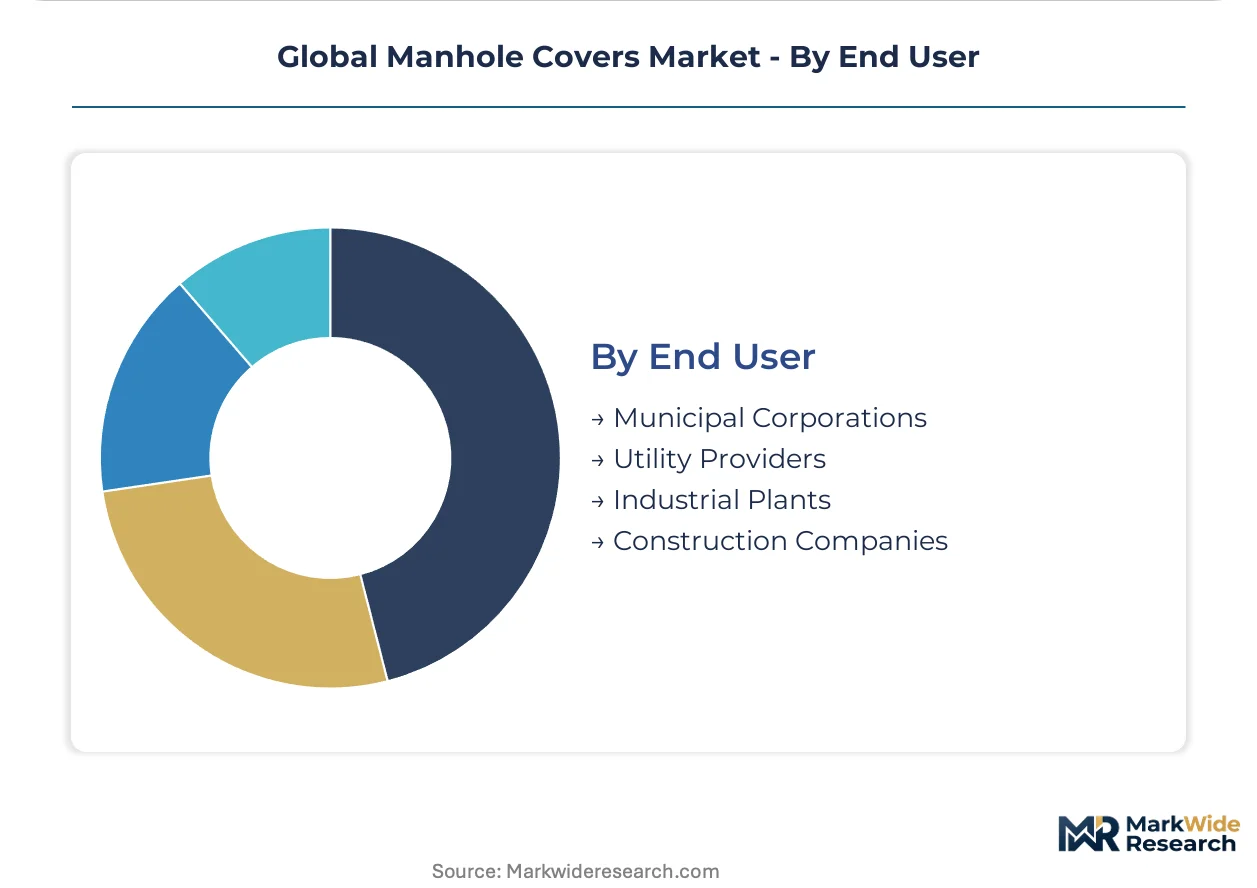
End User:
Procurement sophistication bifurcates between centralized utility fleets with predictive asset management and fragmented municipal corporations operating on annual budget cycles.
- Municipal Corporations:City and county public works departments manage heterogeneous inventories spanning decades of accumulated specifications, complicating synchronized material transitions.
- Utility Providers:Water, sewer, and electrical utilities with territory-scale operations consolidate supplier relationships and pilot RFID-enabled asset tracking through centralized fleet management platforms.
- Industrial Plants:Facility engineering teams specify corrosion-resistant composites for coastal and chemically aggressive process environments.
- Construction Companies:Project-based procurement favors surface-mounted temporary covers with rapid availability over optimized lifecycle performance.
Utility Providers hold technical specification leadership. Municipal Corporations remain the volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA stormwater management mandates and EN 124 load-class certification create divergent compliance obligations across municipal procurement offices. Foundry capacity constraints in Germany and Japan extend lead times for ductile iron orders. Composite cover specifications accelerate in coastal municipalities from Florida to the Netherlands.
United States
Highway agencies in California and Texas mandate centralized engineering pre-approval before bid eligibility, concentrating volume among incumbent certified producers. EPA stormwater management rules elevate specification tiers for truck corridor maintenance covers. Water utilities in Florida specify glass-reinforced polymer alternatives for tidal zone vaults where salt exposure degrades metallic components.
Germany
Municipal maintenance crews favor surface-mounted frame-and-cover geometries for rapid swap-out during emergency sewer access. REACH chemical registration requirements tighten monomer disclosure obligations for composite manufacturers, elevating compliance costs. German utilities consolidate supplier panels toward vertically integrated polymer compounders with in-house toxicology documentation.
India
Urban infrastructure agencies under the Smart Cities Mission expand sewer network coverage across 100 designated municipalities. BIS IS 1726 standard creates testing obligations for exporters serving state-level public works department tenders. Foundries in Gujarat and Maharashtra face capacity constraints as procurement volumes outpace skilled mold-maker availability.
Japan
Metropolitan water bureaus specify lightweight composite covers to reduce manual-handling injuries for utility maintenance crews. JIS standards and METI industrial guidance shape certification requirements for access cover suppliers. Industrial clusters in the Chubu region around Nagoya maintain specialized foundry capabilities for ductile iron casting.
Netherlands
Water utilities specify glass-reinforced polymer covers for tidal zone vaults where salt exposure accelerates metallic corrosion. EU Green Public Procurement recycled-content mandates favor manufacturers with closed-loop polymer reclamation capabilities. Urban designers in Amsterdam specify flush-mount covers for complete streets projects eliminating trip hazards.
Global Manhole Covers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the manhole covers market. The upper tier commands specification influence through captive foundry operations and materials science capabilities. The specialist tier fragments across regional foundries, composite molders, and fabrication shops serving localized procurement pools. Three archetypes dominate: vertically integrated metal casters, polymer compounders with formulation expertise, and lightweight composite specialists. Competitive moves center on backward integration into resin supply chains and RFID-enabled asset tracking partnerships with utility fleet operators.
Among the integrated casting tier, EJ Group and Saint-Gobain occupy positions exemplifying divergent strategic anchors. EJ Group represents the foundry-integrated archetype with melt-to-finished-casting operations across European and North American plants. Saint-Gobain exemplifies the materials science pathway, leveraging formulation expertise to serve high-performance composite segments. Fibrelite sits within the lightweight specialist tier, anchoring the fiber-reinforced category that targets manual-handling injury reduction for utility workforces.
| Leading Market Players |
|---|
| EJ Group, Inc. |
| Saint-Gobain |
| Fibrelite |
| Crescent Foundry |
| Neenah Foundry |
| Eagle Manufacturing Group |
| Ducast Factory |
| Polieco Group |
| U.S. Foundry |
| Others |
Supply & Pricing Matrix
Composite resin substitution for ductile iron is redrawing supply geography from foundry belts to polymer compounding clusters while compressing price premiums for corrosion-resistant grades. This material rotation simultaneously elevates logistics costs for fiberglass feedstock and fragments pricing power away from traditional casting hubs.
Pricing Analysis
Price spreads between Indian and German procurement tenders exceed fifty percent for equivalent EN 124 load-class ratings. Three-tier pricing structure across premium, standard, and economy levels tracks certification tier and geographic delivery cost rather than raw material grade alone. Cost compression in standard-grade ductile iron is intensifying because foundry labor scarcity extends lead times beyond procurement planning horizons. Municipal corporations in India's Smart Cities Mission remain most price-sensitive, while Dutch water utilities with tidal zone vault specifications show least sensitivity due to lifecycle replacement cost differentials.
Supply Chain Analysis
Strait of Hormuz transit underwrites epoxy resin supply security for composite molders serving European and Asian markets simultaneously. Manufacturing concentrates in China for fiberglass roving, Germany for ductile iron casting equipment, and India for gray iron foundry output. Raw material dependencies span petroleum-derived epoxy systems, scrap steel feedstock, and spheroidal graphite inoculants. Single-source vulnerability runs through Chinese fiberglass roving suppliers following capacity consolidation. Distribution runs through municipal procurement offices for iron covers and specialized utility fleet suppliers for composite alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from foundry capacity constraints that peaked during post-pandemic infrastructure stimulus waves. India's sustained urban renewal procurement provides the cyclical anchor.
For Market Incumbents: Shield specification influence by deepening backward integration into resin compounding capabilities before REACH disclosure obligations consolidate supplier panels. Defend against lightweight composite specialists by embedding RFID telemetry into frame-and-cover assemblies, creating switching costs for utility fleet operators. Prioritize certification maintenance across EN 124, ASTM A536, and BIS IS 1726 protocols to preserve bid eligibility in fragmented municipal procurement systems. For New Entrants and Emerging Players: Differentiate on closed-loop polymer reclamation capabilities that satisfy EU Green Public Procurement recycled-content mandates. Target Indonesia's urbanization wave in Jakarta and Surabaya where infrastructure agencies lack entrenched supplier relationships. Pursue pre-approval pathways through California and Texas highway authority engineering review processes as the primary go-to-market angle for North American penetration. For Investors and Strategic Acquirers: The market sits at a specification-upgrade phase that favors vertically integrated compounders with in-house toxicology documentation. Long-term viability hinges on material science capabilities rather than foundry asset ownership. Acquisition targets should demonstrate certified supplier status across multiple jurisdiction protocols. Monitor composite cover specification share in Florida and Netherlands municipal tenders as the inflection indicator for permanent material transition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | REACH compliance costs favor in-house toxicology documentation over outsourced formulation. |
| RFID-Enabled Asset Tracking Integration | Utilities in Japan and Germany pilot centralized fleet management platforms with embedded telemetry. |
| Multi-Jurisdiction Certification Investment | EN 124, ASTM A536, and BIS IS 1726 maintenance preserves bid eligibility across fragmented procurement. |
| Closed-Loop Polymer Reclamation Capability | EU Green Public Procurement mandates recycled-content thresholds for municipal tender participation. |
| Indonesia Market Entry Partnership | Jakarta infrastructure agencies lack established supplier relationships for first-mover positioning. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with municipal procurement officers, foundry operations managers, utility fleet maintenance directors, and composite formulation chemists; and secondary validation through customs trade databases, EPA stormwater management filings, EN 124 certification registries, and BIS standard documentation. Bottom-up volume estimates from state-level public works department tender aggregations were triangulated against top-down material flow analysis from scrap steel and epoxy resin consumption patterns.
Across the analysis window, forecasts were constructed using segmented modeling across material type, installation geometry, application sector, and end-user procurement sophistication. CAGRs were derived from regression analysis of historical tender volumes against infrastructure spending commitments. Key inputs included India's Smart Cities Mission project pipelines, European highway agency load-class upgrade schedules, and composite resin price elasticity coefficients from petrochemical derivative markets.
Forecasts assume regulatory continuity in REACH chemical registration, EPA stormwater mandates, and BIS IS 1726 testing protocols; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as polymer recycling regulations and digital asset-tagging requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
North America Pipeline Maintenance Market
Infrastructure Construction
Heavy Movable Bridges Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Overhead Conductor Market
Infrastructure Construction
Pipeline Network Market
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Infrastructure Investment Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market