
 South America Phytosterols Market | 2026-2036
South America Phytosterols Market Size, Share, and Industry Trends Forecast 2026-2036
South America Phytosterols Market Analytics
Direct sales channels serving pharmaceutical and nutraceutical compounders is rewriting procurement geography across the Andean ridge and Southern Cone. Cargill, Incorporated leverages its oilseed processing footprint to anchor raw sterol supply from Argentine soy complexes. BASF SE competes through refined esterification technology that extends shelf stability for tropical climate distribution. Advanced Organic Materials SA dominates regional toll manufacturing, occupying specialized capacity that larger multinationals navigate through partnership rather than ownership.
Phytosterols comprise plant-derived steroid alcohols—principally beta-sitosterol, campesterol, and stigmasterol—typically extracted from vegetable oil deodorizer distillates at purity thresholds between 95% and 99%, then employed to inhibit intestinal cholesterol absorption in functional foods and therapeutic preparations. Powder formulations lead volume throughput due to blending compatibility with flour and dairy matrices, though liquid emulsions capture expanding share in beverage applications where homogenization demands superior dispersibility. Beta-sitosterol sustains the largest position among isolated sterols given its prevalence in regional soybean and tall oil feedstocks, while sitostanol esters differentiate through enhanced fat-solubility for margarine and spread formulations.
ANVISA governs health claim substantiation for phytosterol-enriched products in Brazil, requiring minimum daily intake thresholds that shape dosage engineering and label architecture. Argentina's national food code and Chile's Ministry of Health standards create a patchwork compliance environment where cross-border formulation standardization remains unresolved. Colombia's INVIMA and Peru's DIGEMID add further registration layers for pharmaceutical-grade sterol intermediates. Stakeholders must monitor regulatory divergence between Mercosur harmonization talks and national sovereignty over novel food approvals.
Market Dynamics
ANVISA's evolving health claim framework for plant sterols is compressing formulation lead times and forcing simultaneous compliance engineering across multiple product categories in Brazil's functional food corridor.
Growth Catalysts
- Cholesterol-lowering functional food demand:Brazilian food and beverage manufacturers are accelerating phytosterol incorporation into margarines, yogurts, and dairy alternatives to meet cardiovascular wellness positioning.
- ANVISA health claim substantiation pathway:The regulator's clarified intake thresholds provide definitional clarity that reduces regulatory uncertainty for new market entrants.
- Tall oil and soybean distillate availability:Argentine oilseed processing complexes supply abundant raw sterol feedstock within regional freight economics.
Market Restraints
- High-purity extraction cost structure:Achieving 95-99% purity thresholds from deodorizer distillates requires capital-intensive molecular distillation that elevates unit economics for regional compounders.
- Cross-border formulation divergence:Argentina's national food code and Chile's Ministry of Health standards create incompatible labeling architectures that prevent product standardization across Mercosur.
- Sitostanol ester substitution pressure:Enhanced fat-solubility alternatives threaten powder formulation market share in margarine and spread applications.
Strategic Opportunities
- Colombian functional beverage white space:INVIMA registration pathways for pharmaceutical-grade sterol intermediates remain underdeveloped relative to Brazil's maturity.
- Liquid emulsion technology convergence:Homogenization advances are enabling beverage applications where powder dispersibility previously failed.
- Peruvian nutraceutical channel expansion:DIGEMID oversight of sterol intermediates creates structured entry for direct-to-compounder sales models.
Industry Challenges
- Regulatory affairs specialization scarcity:Few professionals possess simultaneous expertise in ANVISA novel food procedures and Mercosur harmonization protocols.
- Multi-jurisdiction certification timelines:Parallel registration with Colombia's INVIMA and Peru's DIGEMID extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Phytosterols Market |
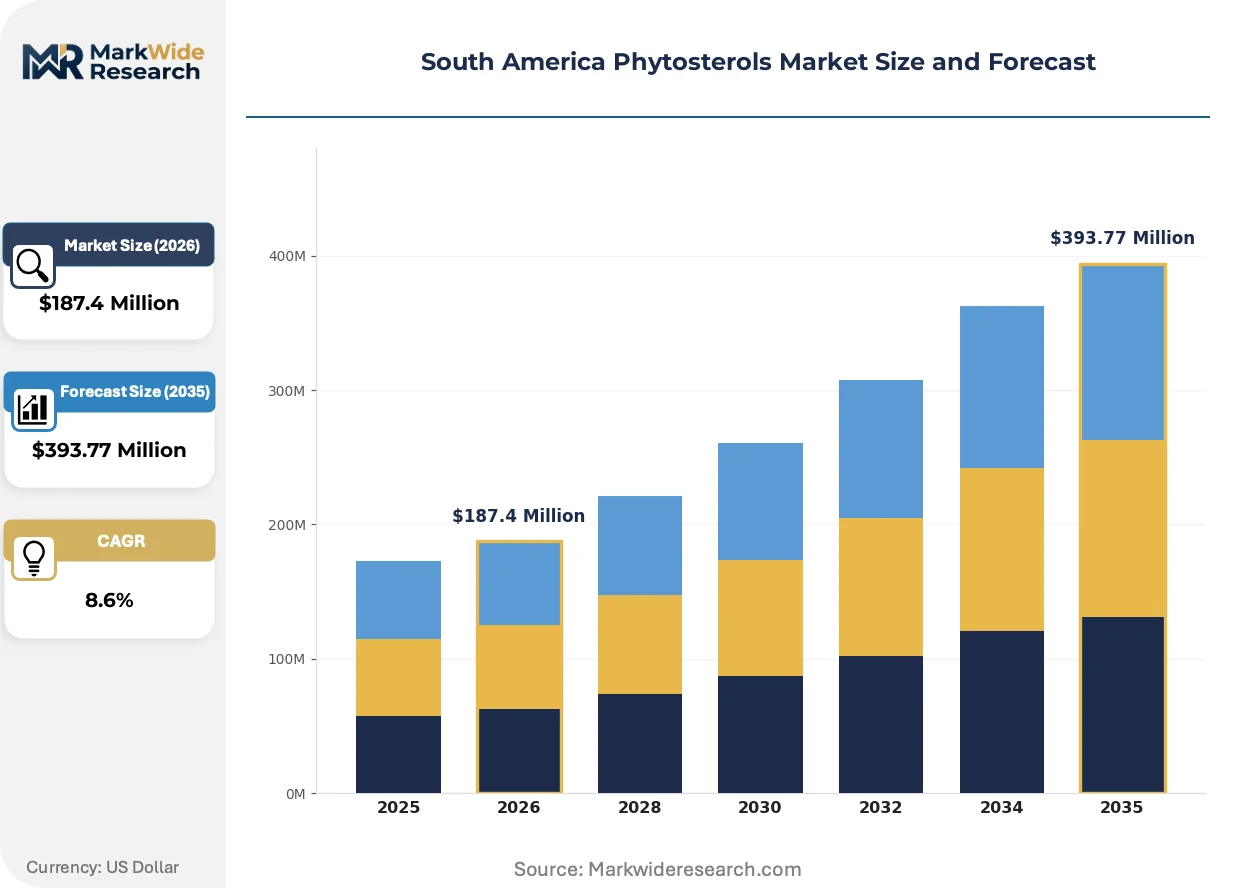
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-Sitosterol, Campesterol, Stigmasterol, Sitostanol End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Animal Feed Form: Powder, Liquid, Granule, Emulsion Distribution Channel: Online, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Cargill, Incorporated, BASF SE, Advanced Organic Materials SA, Matrix Fine Sciences Pvt Ltd, DuPont Nutrition & Biosciences, Archer Daniels Midland, Bunge Limited, Pharmachem Laboratories, Raisio Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Phytosterols Market Evolving Landscape
Digital process control and regulatory data transparency are compressing the gap between extraction optimization and health claim substantiation across South American phytosterol value chains.
Supercritical CO2 extraction technology is virtualizing traditional solvent-based purification by enabling temperature-sensitive sterol recovery with higher selectivity for beta-sitosterol. Argentine toll manufacturers are adopting these systems to serve pharmaceutical-grade demand from São Paulo-based compounders. This virtualization is collapsing the historical separation between food-grade and pharmaceutical-grade production assets.
ANVISA's updated Resolution RDC 340 establishes specific daily intake thresholds for cholesterol-lowering claims that reshape dosage engineering requirements. The regulation mandates dual-column labeling architecture that increases packaging complexity for multinational brand owners. Functional dairy and spread manufacturers in Minas Gerais state are responding with reformulated serving sizes that align claim eligibility with consumption patterns.
Direct procurement relationships between Brazilian nutraceutical compounders and Argentine oilseed processors are displacing traditional distributor intermediaries in regional sterol supply. This channel compression concentrates volume negotiation power with large formulation houses in São Paulo's industrial corridor. The shift is most visible in pharmaceutical-grade beta-sitosterol contracts where specification consistency outweighs spot-market price flexibility.
South America Phytosterols Market Segmentation
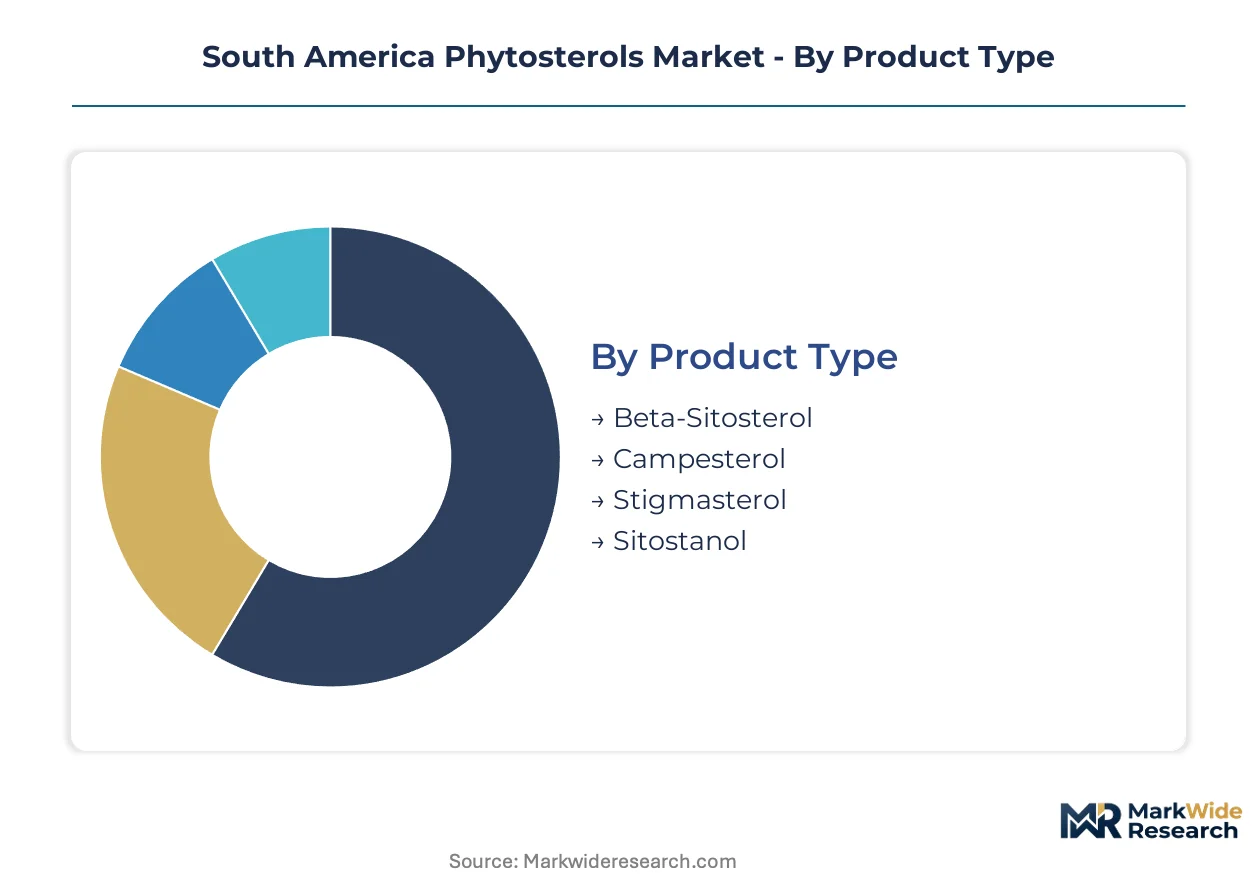
Phytosterol segmentation across South America reflects divergent purity requirements between pharmaceutical compounders and food manufacturers. Each dimension—sterol chemistry, application matrix, physical form, and procurement channel—carries distinct margin structures and regulatory exposure that shape supplier strategy.
Product Type:
Cost tier differentiation separates commodity distillate extracts from refined isolates commanding pharmaceutical-grade premiums.
- Beta-Sitosterol:Constitutes the principal sterol fraction in Argentine soybean and tall oil distillates, typically reaching 40-60% of raw sterol mass before purification. São Paulo-based nutraceutical compounders specify 95%+ purity for cholesterol-lowering capsules, with ANVISA's intake thresholds driving dosage engineering toward 2-3 gram daily servings.
- Campesterol:Represents the second-most abundant plant sterol in regional oilseed processing streams, distinguished by its C-24 methyl group that alters crystallization behavior during esterification. Brazilian margarine manufacturers in Minas Gerais incorporate campesterol-rich blends to achieve label claims without exceeding cost targets for mass-market spreads.
- Stigmasterol:Serves as a precursor for semi-synthetic hormone production, with Peruvian pharmaceutical intermediates demand creating a specialized procurement channel distinct from food-grade markets.
- Sitostanol:Hydrogenated derivative delivering enhanced fat solubility for tropical climate stability in margarine formulations.
Beta-sitosterol commands the established base. The steepest expansion runs through sitostanol esters.
End Use Industry:
Application maturity varies sharply across regulatory complexity and formulation sophistication requirements.
- Food & Beverage:ANVISA's Resolution RDC 340 compliance mandates dual-column labeling and defined daily intake thresholds for cholesterol-lowering claims. Brazilian dairy and spread manufacturers in the southeastern industrial corridor dominate volume procurement, with yogurt and margarine applications absorbing the majority of food-grade sterol supply.
- Pharmaceuticals:Requires 99% purity thresholds and INVIMA or DIGEMID registration for sterol intermediates used in therapeutic preparations. Argentine toll manufacturers with supercritical CO2 extraction capability serve São Paulo-based compounders through direct procurement relationships that bypass traditional distribution layers.
- Cosmetics:Leverages sterol emollient properties in topical formulations, with lower purity tolerances than pharmaceutical grades.
- Animal Feed:Absorbs lower-purity sterol fractions from deodorizer distillate processing, primarily for poultry cholesterol reduction claims.
Food and beverage commands the established base. The steepest expansion runs through pharmaceuticals.
Form:
Physical state determines blending compatibility and homogenization performance across divergent manufacturing processes.
- Powder:Dominates volume throughput due to dispersion compatibility with flour, dairy, and dry-mix matrices. Brazilian bakery and pasta manufacturers specify micronized particle sizes below 50 microns to prevent grittiness in fortified products.
- Liquid:Captures expanding share in beverage applications where homogenization demands superior dispersibility without sedimentation. Colombian functional drink manufacturers are adopting liquid emulsion technology to overcome previous powder dispersion failures in UHT processing.
- Granule:Serves intermediate processing stages where controlled dissolution rates matter for tablet compression.
- Emulsion:Enables water-dispersible sterol delivery for clear beverage systems and reduced-fat applications.
Powder commands the established base. The steepest expansion runs through liquid emulsions.
Distribution Channel:
Customer type and purchase scale determine channel economics and relationship intensity.
- Direct Sales:Pharmaceutical and nutraceutical compounders in São Paulo's industrial corridor are consolidating procurement through direct relationships with Argentine oilseed processors. This channel compression concentrates volume negotiation power with large formulation houses and eliminates distributor margins for specification-critical beta-sitosterol contracts.
- Health Stores:Serve finished consumer products with phytosterol claims, particularly cholesterol-lowering supplements in Brazil's pharmacy retail chains.
- Supermarkets:Move functional foods with front-of-pack sterol claims, including yogurts and spreads in southeastern Brazilian retail.
- Online:Emerging for specialized supplement brands targeting direct-to-consumer cardiovascular wellness positioning.
Direct sales commands the established base. The steepest expansion runs through health stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Paraná-Paraguay waterway anchors South American phytosterol logistics, enabling cost-efficient soybean distillate movement from Argentine crushing complexes to Brazilian formulation centers. This riverine infrastructure underwrites the region's integration into global sterol supply chains.
Brazil
Functional food manufacturers in São Paulo and Minas Gerais drive demand for cholesterol-lowering formulations. ANVISA's Resolution RDC 340 mandates dual-column labeling and defined daily intake thresholds that reshape dosage engineering. The southeastern industrial corridor concentrates pharmaceutical-grade toll manufacturing capacity serving both domestic and export compounders.
Argentina
Oilseed processing complexes in Rosario and Bahía Blanca supply abundant raw sterol feedstock from soybean and tall oil deodorizer distillates. The national food code creates labeling requirements distinct from Mercosur neighbors, complicating cross-border product standardization. Supercritical CO2 extraction adoption is virtualizing traditional solvent-based purification for pharmaceutical-grade output.
Chile
Ministry of Health standards govern sterol health claim substantiation with thresholds diverging from Brazilian and Argentine frameworks. Santiago-based nutraceutical importers navigate this regulatory patchwork to source refined isolates for domestic formulation. The metropolitan region's pharmacy retail chains represent an emerging channel for finished cholesterol-lowering supplements.
Colombia
INVIMA registration pathways for pharmaceutical-grade sterol intermediates remain underdeveloped relative to Brazil's maturity, creating white space for early entrants. Bogotá functional beverage manufacturers are adopting liquid emulsion technology to overcome previous powder dispersion failures in UHT processing. Caribbean port access offers freight advantages for imported refined isolates.
Peru
DIGEMID oversight of sterol intermediates structures entry for direct-to-compounder sales models bypassing traditional distribution. Lima-based pharmaceutical manufacturers source semi-synthetic hormone precursors from stigmasterol fractions distinct from food-grade markets. Andean toll manufacturing capacity serves regional demand for therapeutic-grade sterol derivatives.
South America Phytosterols Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction and esterification. The South American phytosterol market structures around three tiers: multinational agribusinesses with captive oilseed processing assets, European chemical conglomerates with refined esterification technology, and regional toll manufacturers occupying specialized capacity. Competitive moves concentrate on backward integration into deodorizer distillate supply and partnership structures that access pharmaceutical-grade purification without direct capital deployment.
Among the named players, Cargill, Incorporated and BASF SE exemplify contrasting archetypes: the former represents agribusiness platform integration from oilseed crush through raw sterol supply, while the latter anchors chemical-process specialization in esterification and shelf-stability engineering. Advanced Organic Materials SA occupies a distinct position as a regional toll manufacturer whose specialized capacity larger multinationals access through partnership rather than ownership. These three patterns—agribusiness integration, chemical-process premium, and regional toll specialization—define competitive positioning across the value chain.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| Advanced Organic Materials SA |
| Matrix Fine Sciences Pvt Ltd |
| DuPont Nutrition & Biosciences |
| Archer Daniels Midland |
| Bunge Limited |
| Pharmachem Laboratories |
| Raisio Group |
| Others |
Value Network & Pricing Analysis
Regulatory chokepoint divergence between ANVISA's Resolution RDC 340 and Mercosur harmonization delays determines both pricing tier spreads and supply chain shape across South American phytosterol markets. Pharmaceutical-grade sterol isolates command substantial premiums over food-grade distillates as Brazilian compounders absorb compliance engineering costs for dual-column labeling and intake threshold verification.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade isolates from commodity deodorizer distillate feedstocks. Three-tier pricing stratification across premium, standard, and economy levels reflects purity thresholds, with 99% pharmaceutical grades commanding multiples of 95% food-grade material. Cost compression in standard-tier margarine applications intensifies as sitostanol ester alternatives erode powder formulation share. Small Brazilian nutraceutical compounders exhibit highest price sensitivity, while São Paulo-based formulation houses with direct Argentine procurement relationships absorb margin pressure through volume concentration.
Supply Chain Analysis
Tariff exposure between Argentina and Brazil dominates supply chain risk calculations for regional sterol procurement. Raw sterol feedstock concentrates in Argentine Rosario and Bahía Blanca oilseed complexes, drawing from soybean and tall oil deodorizer distillates. Supercritical CO2 extraction equipment dependency rests on European and Asian technology suppliers, creating single-source vulnerability for pharmaceutical-grade toll manufacturers. Distribution runs through direct sales relationships between Argentine processors and Brazilian compounders, displacing traditional distributor intermediaries in specification-critical contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South American phytosterol market sits at a platform-economics inflection where ANVISA's clarified health claim pathway enables interoperability between food-grade and pharmaceutical-grade production assets. This regulatory transparency shift rewards ecosystem orchestrators who bridge extraction technology with formulation compliance.
For Market Incumbents: Entrench backward integration into Argentine deodorizer distillate supply through long-term offtake agreements with Rosario-based oilseed processors. Pharmaceutical-grade toll manufacturers must secure supercritical CO2 extraction capacity ahead of Brazilian compounder demand concentration, as sitostanol ester substitution threatens powder formulation margins in Minas Gerais spread applications. For New Entrants and Emerging Players: Establish a beachhead in Colombian functional beverage white space where INVIMA registration pathways remain underdeveloped relative to Brazilian maturity. Liquid emulsion technology convergence enables UHT-compatible sterol delivery that incumbent powder suppliers cannot match. Target direct-to-compounder sales models in Peru's DIGEMID-regulated channel, bypassing distributor markups through specification partnerships with Lima-based pharmaceutical manufacturers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional toll manufacturing specialists with ANVISA compliance expertise and Argentine feedstock access. Acquisition targets should demonstrate supercritical extraction capability and simultaneous food-grade and pharmaceutical-grade certification. Watch ANVISA-Mercosur harmonization progress as the inflection signal—successful regulatory convergence would collapse cross-border formulation divergence and unlock standardization economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Deodorizer Distillate Supply | Cargill's Argentine oilseed footprint secures captive raw sterol feedstock for Brazilian compounders. |
| Supercritical CO2 Extraction Adoption | Advanced Organic Materials' toll capacity virtualizes solvent-based purification for pharmaceutical-grade demand. |
| Liquid Emulsion Technology Development | Colombian beverage manufacturers overcome UHT powder dispersion failures through homogenization advances. |
| ANVISA Resolution RDC 340 Compliance Engineering | Dual-column labeling mandates reshape dosage architecture for Minas Gerais dairy and spread producers. |
| Direct Procurement Channel Consolidation | São Paulo compounders disintermediate distributors through volume concentration with Argentine processors. |
Research Methodology
Initial hypotheses were tested against primary input from extraction technology specialists, regulatory affairs directors at Brazilian functional food manufacturers, Argentine oilseed procurement leads, and pharmaceutical formulation scientists, then refined through secondary validation. Bottom-up demand modeling drew from ANVISA registration databases, INVIMA pharmaceutical intermediate filings, and Argentine customs trade records for deodorizer distillate movements. Top-down market sizing triangulated against regional oilseed processing capacity and sterol yield coefficients from soybean and tall oil feedstocks.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled by sterol chemistry, end-use application matrix, physical form, and procurement channel. CAGRs were derived from regression analysis of historical volume trajectories and projected intake threshold adoption under ANVISA's clarified pathway. Forecast inputs incorporated supercritical extraction technology diffusion rates and Mercosur harmonization probability assessments.
Sensitivities concentrate around ANVISA regulatory revision timelines, Argentine-Brazilian tariff regime shifts, and sitostanol ester substitution velocity in tropical margarine applications. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Calcium Caseinate Market
Ingredients
Functional Flours Market
Ingredients
Potato Flour Market
Ingredients
Lactase Enzyme Market
Ingredients
Rose Extract Market
Ingredients
Cooking Oils and Fats Market
Ingredients
Acetylated Starch Market
Ingredients
Safflower Oil Market
Ingredients
Roll-Dried Starch Market
Ingredients
Amylase Market
Ingredients
Fonio Flour Market
Ingredients
Agave Inulin Market
Ingredients
Mung Bean Protein Market
Ingredients
Fish Gelatin Market
Ingredients
Asia-Pacific Agar Market