
 Asia-Pacific Agar Market | 2026-2036
Asia-Pacific Agar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agar Market Outlook
Plant-based hydrocolloid extraction technology is tilting toward enzymatic refinement methods that yield higher gel strength with lower solvent residue. Meron Group anchors Indonesia's raw material supply through integrated seaweed farming operations. Fujian Global Ocean Biotechnology Co., Ltd. specializes in pharmaceutical-grade powder output for culture medium applications. Green Fresh Group extends its reach across direct sales channels to research laboratories throughout East Asia.
Agar comprises a heterogeneous polysaccharide complex extracted primarily from red algae genera Gracilaria and Gelidium, with gelation properties defined by agarose content exceeding 70 percent and sulfate levels below 5 percent in food-grade specifications. The product type dimension shows powder commanding the largest volume share due to solubility advantages in industrial formulations, while capsules are gaining traction in pharmaceutical applications where dosing precision matters. End user segmentation reveals food industry demand as mature and price-sensitive, whereas research laboratories generate premium margins for ultrapure grades.
China's SAMR enforces GB standards for food additive purity, while Japan's Ministry of Health, Labour and Welfare oversees pharmaceutical-grade specifications through PMDA guidelines. India's FSSAI and BIS frameworks are tightening import quality thresholds for hydrocolloids used in processed foods. Stakeholders must weigh raw material sourcing concentration against regulatory divergence when allocating capacity investments across the region.
Market Dynamics
Enzymatic refinement methods are compressing solvent residue tolerances across pharmaceutical-grade agar production, forcing processors to retrofit extraction lines or cede high-margin segments to integrated operators with captive biotechnology capabilities.
Growth Catalysts
- Pharmaceutical-grade specifications:Japan's PMDA guidelines and South Korea's MFDS standards are tightening purity benchmarks for cell culture applications, pulling ultrapure agarose demand from biopharmaceutical manufacturers.
- Coastal processing clusters:China's Fujian and Shandong provinces concentrate seaweed refining capacity with integrated cold-chain logistics, reducing gel degradation during extraction.
- Gracilaria cultivation expansion:Indonesia's Sulawesi and Bali farming zones are scaling raw material output through state-backed aquaculture permits.
Market Restraints
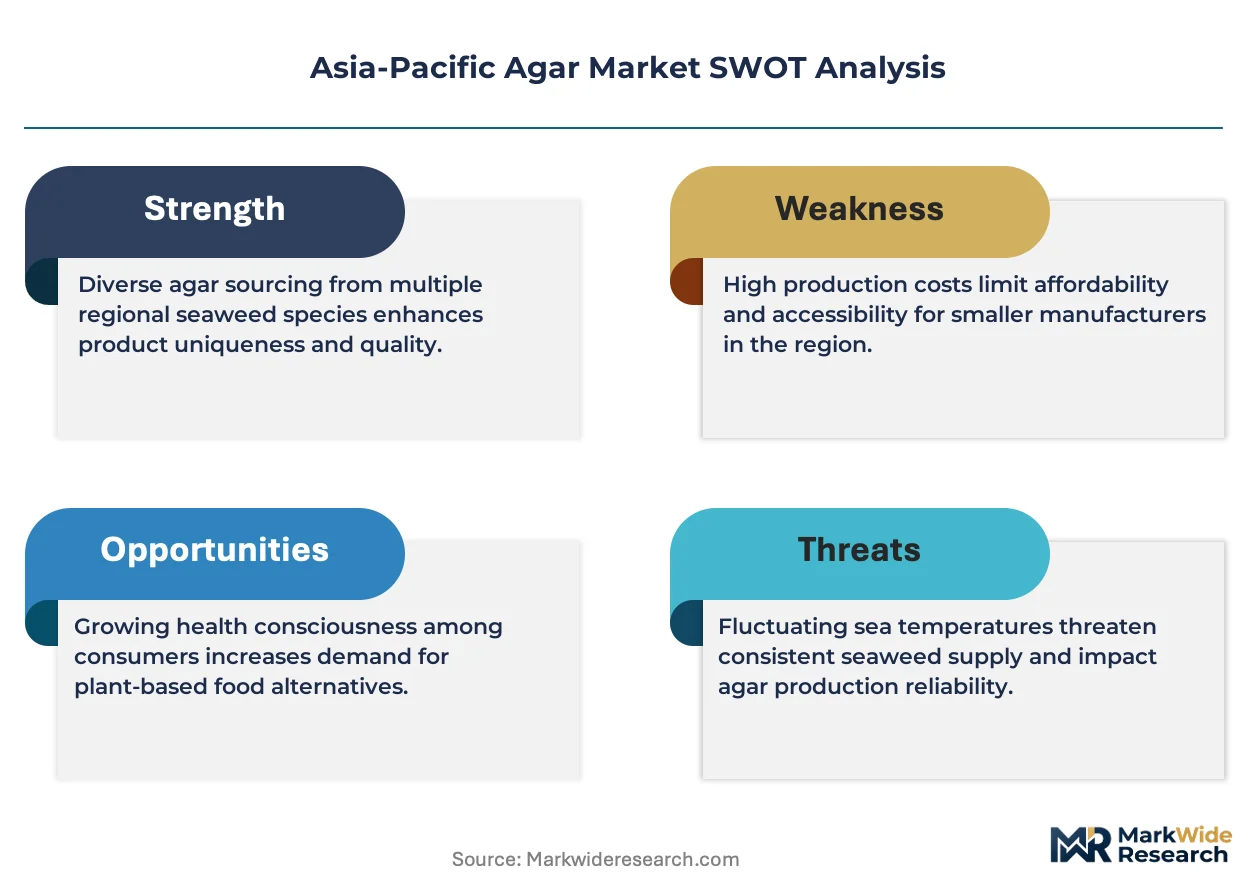
- Seaweed supply volatility:Gracilaria harvests fluctuate with El Niño cycles and coastal pollution events, compressing processor margins during poor yield seasons.
- China's GB standard enforcement:SAMR inspections for food additive purity create compliance friction for smaller Indonesian exporters lacking in-house testing laboratories.
- Carrageenan substitution:Food manufacturers in cost-sensitive segments are reformulating with kappa-carrageenan where gel strength requirements permit lower performance thresholds.
Strategic Opportunities
- Vietnam's underpenetrated aquaculture zones:Mekong Delta seaweed farming remains nascent, offering first-mover advantages for integrated farming-processing joint ventures.
- Research laboratory direct channels:East Asian biotech clusters in Shanghai, Osaka, and Seoul are consolidating vendor lists, rewarding suppliers with ISO 17025-certified quality systems.
- India's FSSAI import threshold tightening:New hydrocolloid purity requirements are disqualifying informal traders, creating structured procurement openings for GMP-certified exporters.
Industry Challenges
- Enzymology talent scarcity:Southeast Asian processors lack sufficient biochemists trained in polysaccharide-specific refinement protocols, slowing technology adoption curves.
- Pharmaceutical-grade certification timelines:PMDA and MFDS facility audits require 18-24 month preparation cycles, freezing capital in non-revenue-generating compliance activities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agar Market |
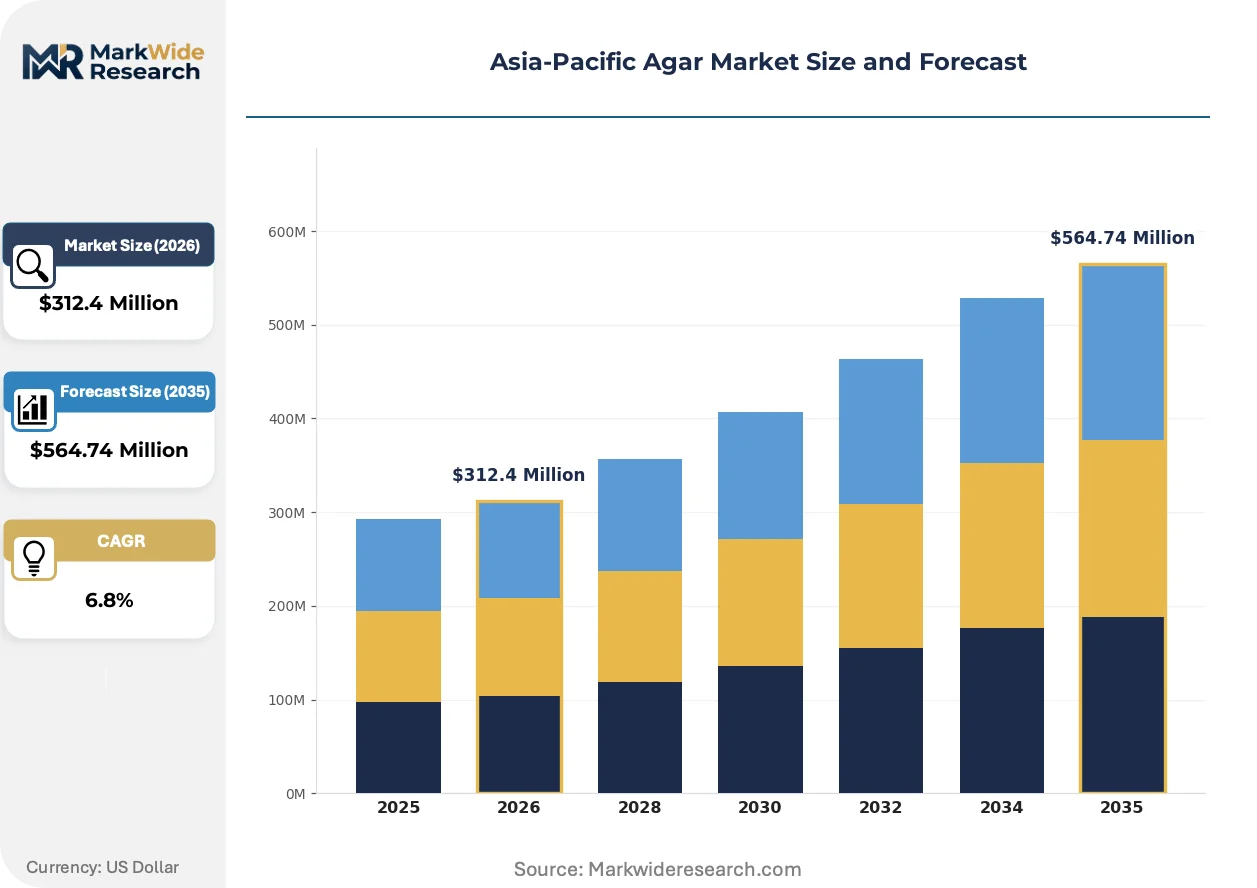
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Flakes, Strips, Capsules End User: Food Industry, Pharmaceuticals, Cosmetics, Research Laboratories Application: Thickening Agent, Clarifying Agent, Culture Medium, Stabilizer Distribution Channel: Online Retail, Direct Sales, Wholesalers, Supermarkets |
| Companies Covered | Meron Group, Agarindo Bogatama, MSC Co Ltd, Merck KGaA, HISPANAGAR, Green Fresh Group, Fujian Global Ocean Biotechnology Co., Ltd., Qingdao Gather Great Ocean Algae Industry Group Co., Ltd., Ina Food Industry Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agar Market Strategic Shifts
Biotechnology convergence and regulatory precision are restructuring how agar derivatives are extracted, certified, and procured across Asia-Pacific value chains.
Cellulase-assisted extraction protocols are hybridizing traditional alkali-based processing with enzymatic specificity, enabling higher agarose yields from Gracilaria species previously considered low-grade feedstock. Japanese and South Korean culture medium manufacturers are adopting these systems fastest, compressing the premium attached to legacy Gelidium-sourced material. The technology is hybridizing competitive positioning between integrated biotech operators and conventional seaweed processors lacking fermentation capabilities.
China's SAMR is enforcing sequential tightening of GB 1886.239 food additive standards, requiring heavy metal and sulfate documentation at batch level. This regulatory pressure is accelerating laboratory accreditation investments among Fujian and Shandong processors. Food-grade agar exports to India and ASEAN markets face elevated rejection risk where documentation gaps persist.
Research institutions across East Asia are consolidating supplier relationships around vendors offering certified reference materials and lot-traceable documentation. Direct procurement contracts are displacing distributor-mediated purchasing in Shanghai, Osaka, and Seoul biotech clusters. This concentration is most visible in cell culture medium applications where contamination liability outweighs modest price premiums for integrated supply assurance.
Asia-Pacific Agar Market Segmentation
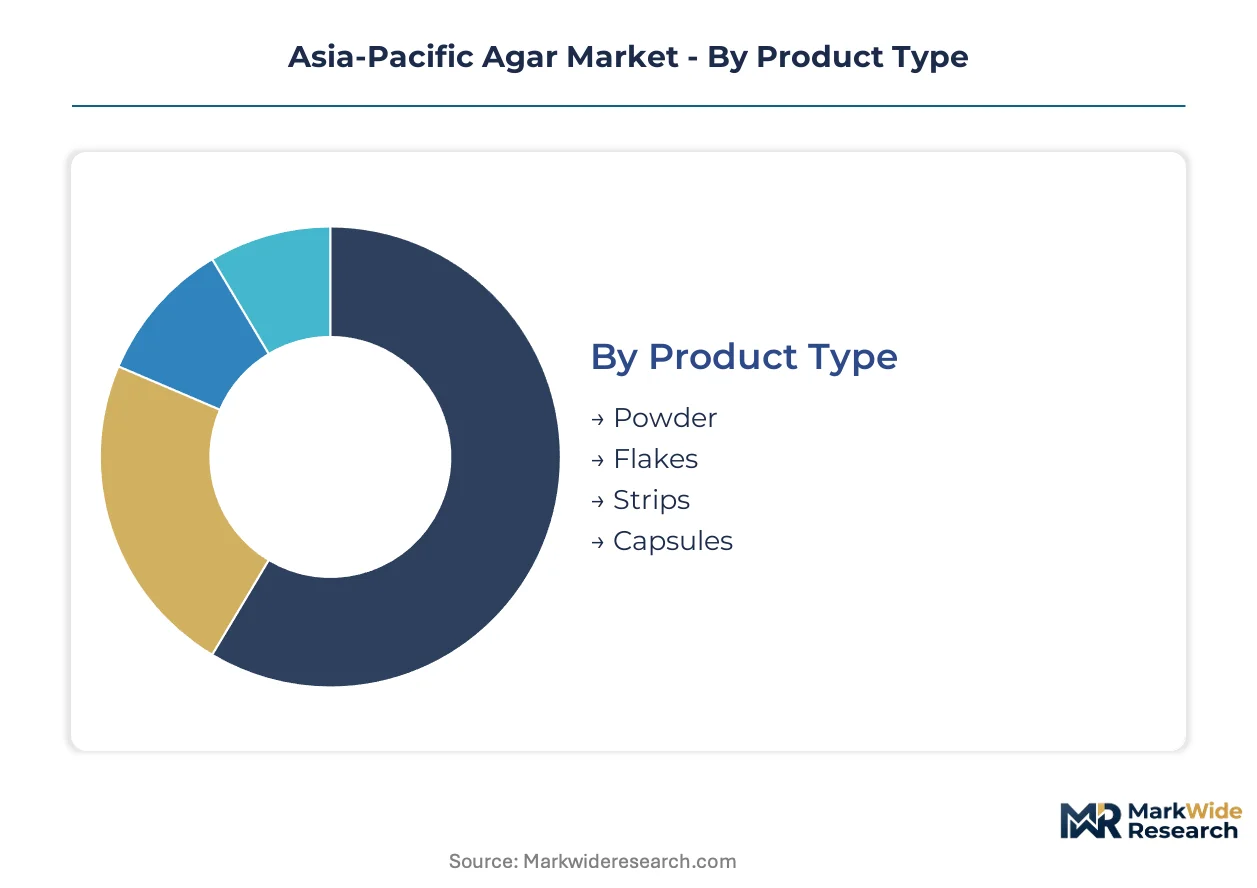
Segmentation in the Asia-Pacific agar market reveals divergent margin structures across purity grades and procurement channels. Pharmaceutical and food-grade specifications create distinct competitive arenas with incompatible certification requirements.
Product Type:
Powder and capsules anchor opposite ends of the maturity spectrum, with flakes and strips occupying intermediate positions in traditional food processing.
- Powder:Fine-grained particulate form with superior solubility kinetics in aqueous systems. Industrial formulators in China's Fujian and Shandong processing clusters favor powder for consistent hydration rates in large-batch confectionery and dairy applications.
- Capsules:Pre-measured gelatinous shells containing precise agar doses for cell culture and microbiological applications. Biopharmaceutical manufacturers in Osaka and Seoul specify capsule formats to eliminate weighing contamination risks in GMP cleanroom environments.
- Flakes:Irregular dehydrated sheets requiring longer hydration cycles. Traditional Japanese wagashi confectioners and Indonesian dessert processors maintain steady procurement of flake formats for texture-specific recipes.
- Strips:Longitudinal cut sections from compressed agar blocks. Limited demand persists in legacy culinary applications across Vietnam and Thailand where visual presentation traditions override processing efficiency.
Powder retains volume leadership; capsules hold the steepest expansion curve.
End User:
Customer type segmentation maps directly to certification burden and pricing tolerance, with research laboratories commanding premium multiples over commodity food buyers.
- Food Industry:Mature demand segment spanning confectionery, dairy, and processed meat applications. China's SAMR GB 1886.239 enforcement is disqualifying smaller Indonesian exporters lacking batch-level heavy metal documentation.
- Research Laboratories:Ultrahigh-purity requirements for cell culture and molecular biology. Direct procurement contracts are displacing distributor channels in Shanghai, Osaka, and Seoul biotech clusters.
- Pharmaceuticals:Culture medium and excipient applications under PMDA and MFDS jurisdiction. Certification timelines of 18-24 months freeze capital in compliance preparation.
- Cosmetics:Emerging segment for gel-based skincare formulations. South Korean cosmetic manufacturers are testing agar as a plant-derived alternative to synthetic thickeners.
Food Industry absorbs the largest absolute tonnage; Research Laboratories generate the highest unit margins.
Application:
Functional use cases separate commodity thickening from precision biological applications with irreconcilable purity thresholds.
- Thickening Agent:Volume-driven use in soups, sauces, and dairy desserts. Cost-sensitive food manufacturers in ASEAN markets face substitution pressure from kappa-carrageenan where gel strength requirements permit.
- Culture Medium:Gelled substrate for microbial and cell line propagation. Japanese and South Korean biopharmaceutical manufacturers are consolidating vendor lists around ISO 17025-certified suppliers.
- Clarifying Agent:Fining process for beverages and broths. Wineries and craft breweries across Australia's Margaret River and Yarra Valley represent niche demand pockets.
- Stabilizer:Freeze-thaw protection in ice cream and frozen desserts. Indonesian and Philippine processors favor stabilizer-grade agar for tropical climate distribution requirements.
Thickening Agent dominates tonnage throughput; Culture Medium commands the most rigorous specification discipline.
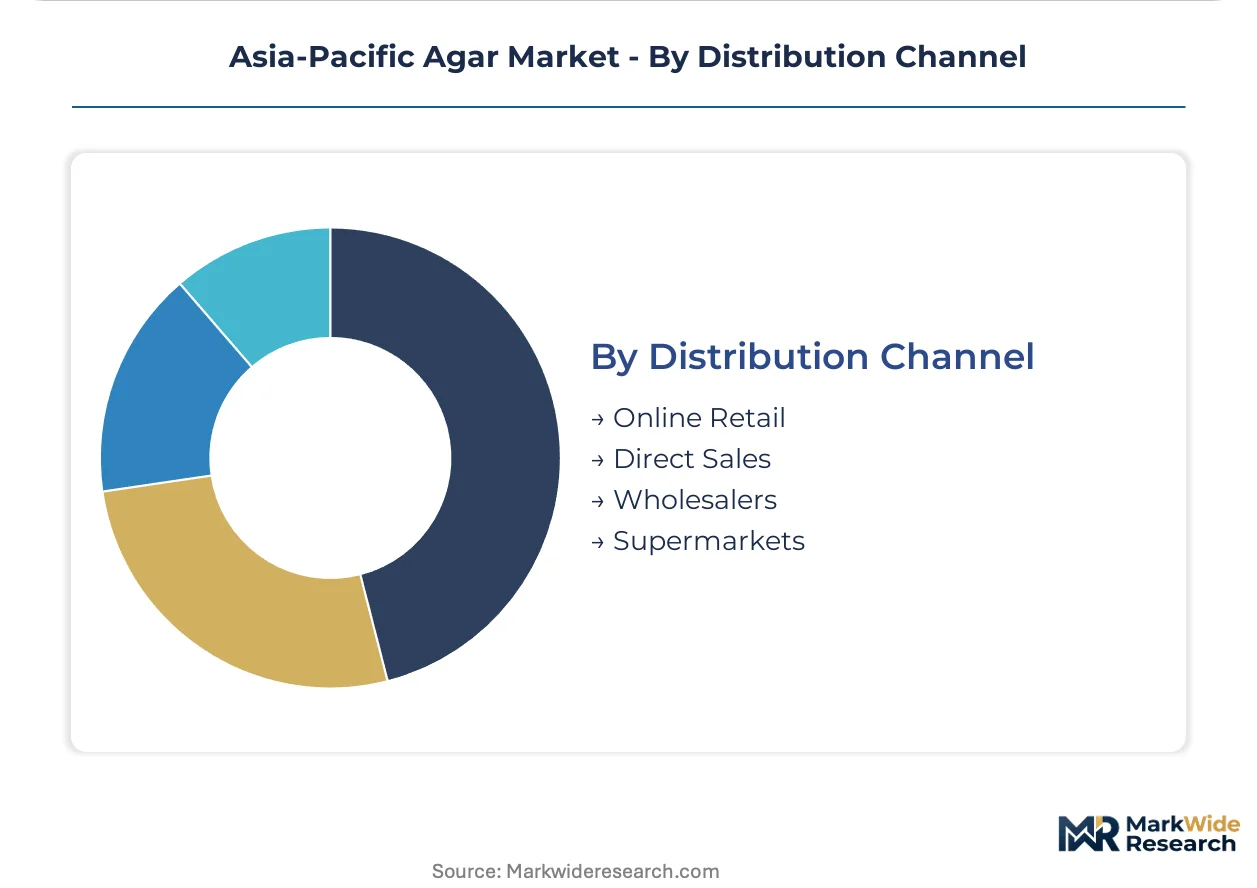
Distribution Channel:
Channel structure reflects customer scale and documentation requirements, with direct sales capturing institutional accounts and online retail penetrating small-batch researchers.
- Direct Sales:Long-term contracts with pharmaceutical manufacturers and research institutions. Fujian and Shandong processors are building dedicated account teams for East Asian biotech clusters.
- Online Retail:E-commerce platforms serving small laboratories and artisan food producers. Green Fresh Group extends reach through direct digital channels with lot-traceable documentation.
- Wholesalers:Traditional intermediaries for food industry volume buyers. Margin compression from SAMR documentation requirements is forcing consolidation among Indonesian export wholesalers.
- Supermarkets:Consumer-packaged goods for home cooking and hobbyist applications. Limited penetration outside Japan and South Korea where agar retains cultural familiarity.
Direct Sales captures the highest-value contracts; Online Retail is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian exporters ship raw Gracilaria to Fujian and Shandong processing clusters, where enzymatic refinement yields pharmaceutical-grade agarose for Japanese and South Korean biopharmaceutical buyers.
China
Fujian and Shandong provinces dominate seaweed refining with integrated cold-chain logistics preserving gel integrity. SAMR enforces GB 1886.239 standards requiring batch-level heavy metal documentation. Qingdao and Xiamen processors retrofit extraction lines to meet pharmaceutical-grade specifications.
Japan
PMDA guidelines tighten purity benchmarks for cell culture applications, pulling ultrapure agarose demand from Osaka and Tokyo biotech clusters. METI supports enzymatic extraction technology adoption. Kanto region laboratories consolidate vendor lists around ISO 17025-certified suppliers.
Indonesia
Sulawesi and Bali farming zones scale Gracilaria output through state-backed aquaculture permits. Coastal pollution events and El Niño cycles compress harvest reliability. Meron Group anchors raw material supply through integrated seaweed farming operations.
South Korea
MFDS standards drive pharmaceutical-grade certification requirements for Seoul biopharmaceutical manufacturers. Daegu-Gyeongbuk culture medium producers adopt cellulase-assisted extraction protocols fastest. Direct procurement contracts displace distributor channels in Songdo biotech cluster.
India
FSSAI and BIS frameworks tighten import quality thresholds for hydrocolloid processors in Maharashtra and Gujarat. New purity requirements disqualify informal traders, creating structured procurement openings. Mumbai and Ahmedabad food manufacturers face substitution pressure from kappa-carrageenan.
Asia-Pacific Agar Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent certification tiers. The vendor base separates into integrated biotech operators with captive fermentation capabilities and conventional processors dependent on third-party raw material sourcing. Three archetypes dominate: seaweed farming-integrated conglomerates, pharmaceutical-grade purification specialists, and regional food-grade commodity suppliers. Competitive moves concentrate on laboratory accreditation investments and direct sales channel development for research institution accounts.
Among Indonesia-based farming-integrated operators, Meron Group exemplifies upstream control over raw material supply. Fujian Global Ocean Biotechnology Co., Ltd. and Green Fresh Group represent Chinese processors occupying positions across food-grade and pharmaceutical-grade purification tiers. Merck KGaA anchors the premium-grade import segment serving East Asian biopharmaceutical clusters.
| Leading Market Players |
|---|
| Meron Group |
| Agarindo Bogatama |
| MSC Co Ltd |
| Merck KGaA |
| HISPANAGAR |
| Green Fresh Group |
| Fujian Global Ocean Biotechnology Co., Ltd. |
| Qingdao Gather Great Ocean Algae Industry Group Co., Ltd. |
| Ina Food Industry Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Fujian and Shandong processing clusters anchor Asia-Pacific agar supply capacity, with enzymatic refinement investments in Qingdao and Xiamen feeding downstream pricing power toward pharmaceutical-grade tiers. Coastal seaweed farming volatility in Indonesia compresses raw material negotiating leverage, forcing processors to index long-term contracts against Gracilaria harvest yields.
Pricing Analysis
Cost-plus contracts with Gracilaria harvest indexation dominate raw material procurement between Indonesian farming zones and Chinese processors. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade agar reflects certification burden divergence, with PMDA-audited facilities commanding 40-60% premiums over SAMR-compliant food additive tiers. Pricing pressure stems from kappa-carrageenan substitution in ASEAN confectionery applications, compressing standard-grade agar margins. Food manufacturers in Vietnam and Thailand exhibit highest price sensitivity, while Osaka and Seoul biotech clusters prioritize supply assurance over unit cost.
Supply Chain Analysis
Gracilaria biomass from Indonesia's Sulawesi and Bali farming zones feeds Chinese refining capacity, with Gelidium harvests from Morocco and Spain supplementing premium agarose production. Key inputs span seaweed feedstock, alkali processing chemicals, and cellulase enzymes for extraction hybridization. Single-source vulnerability concentrates in Indonesian raw material supply, where El Niño cycles and coastal pollution events disrupt harvest reliability. Distribution runs through direct sales contracts for pharmaceutical accounts, with Fujian and Shandong processors maintaining dedicated account teams for East Asian biotech clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific agar demand follows cyclical recovery patterns tied to biopharmaceutical manufacturing expansion in Japan and South Korea, with cell culture medium investments driving ultrapure agarose procurement waves.
For Market Incumbents: Pre-empt kappa-carrageenan substitution in ASEAN food applications by embedding batch-level heavy metal documentation systems ahead of SAMR enforcement waves. Defend pharmaceutical-grade positioning through captive enzymatic refinement capabilities, locking in PMDA and MFDS certification maintenance as rival processors face 18-24 month audit preparation cycles.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Mekong Delta seaweed farming zones through joint ventures with state aquaculture permit holders, capturing first-mover advantages in underpenetrated raw material supply. Target direct digital channels for small-batch research laboratory procurement, leveraging ISO 17025 accreditation as entry credential against incumbent distributor networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated biotech operators with captive fermentation capabilities over conventional alkali-based processors lacking enzymatic refinement expertise. Long-term viability hinges on backward integration into seaweed farming or forward integration into culture medium formulation. Watch PMDA audit queue lengths as inflection indicator for pharmaceutical-grade supply tightness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | Meron Group's Sulawesi operations demonstrate raw material security against El Niño harvest volatility. |
| Enzymatic Refinement Technology Adoption | Cellulase-assisted extraction protocols enable higher agarose yields from previously low-grade Gracilaria feedstock. |
| Pharmaceutical-Grade Certification Investment | PMDA and MFDS facility audits require 18-24 month preparation cycles, freezing capital in compliance activities. |
| Direct Sales Channel Development | Fujian processors build dedicated account teams for Shanghai, Osaka, and Seoul biotech cluster procurement consolidation. |
| Online Retail Platform Expansion | Green Fresh Group extends reach through digital channels with lot-traceable documentation for small laboratories. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, spanning seaweed farming cooperative managers in Sulawesi and Bali, extraction plant engineers in Fujian and Shandong provinces, procurement leads at Osaka and Seoul biopharmaceutical manufacturers, and regulatory affairs specialists navigating SAMR, PMDA, and MFDS frameworks. Secondary validation drew from customs trade databases, GB standard enforcement bulletins, aquaculture permit issuance records, and ISO 17025 accreditation registries. Bottom-up volume modeling triangulated against top-down value projections.
Calibration against historical Gracilaria harvest volumes and pharmaceutical-grade export trajectories anchored the analytical framework across the analysis window. Segmentation dimensions spanned product type, purity grade tier, end-use industry, and regional regulatory cluster. CAGRs were derived from slope analysis of indexed demand curves, with enzymatic technology adoption curves and certification timeline bottlenecks serving as industry-specific forecast inputs.
Stress conditions across El Niño severity, coastal pollution event frequency, and PMDA audit queue lengths were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding biopharmaceutical manufacturing expansion continuity and GB standard enforcement intensity. Cross-checking against MFDS import inspection data and culture medium producer inventory cycles is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Psyllium Husk Powder Market
Ingredients
Cheese Ingredients Market
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
South America Feed Yeast Market
Ingredients
Guar Gum Market
Ingredients
Glucomannan Market
Ingredients
Karaya Gum Market
Ingredients
Lentils Flour Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
Potato Flour Market
Ingredients
Global Pulse Flours Market
Ingredients
South America Vegetable Oil Market
Ingredients
Date Syrup Market
Ingredients
Lime Seed Oils Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Dry Malt Products Market