
 Roll-Dried Starch Market | 2026-2036
Roll-Dried Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Roll-Dried Starch Market Analytics
Thailand is reshaping competitive dynamics in roll-dried starch through expanded tapioca processing infrastructure. Archer Daniels Midland Company leverages its global grain sourcing network to sustain consistent supply volumes across multiple continents. Cargill Incorporated anchors its position through backward integration into corn wet milling operations. Ingredion competes by specializing in modified starch formulations tailored to pharmaceutical coating specifications.
Roll-dried starch refers to starch slurry that is spread on heated drums and flaked into dry, free-flowing particles with moisture content typically below 10 percent, yielding rapid hydration and cold-water solubility for industrial and food systems. Its primary purpose centers on providing instant viscosity, binding capacity, and film-forming properties without requiring heat activation. Modified starch commands the dominant value share due to premium pricing for cross-linked and stabilized grades engineered for acid and shear tolerance. Native starch maintains volume leadership in emerging markets where cost sensitivity favors unmodified tapioca and corn derivatives. Pharmaceutical applications represent the fastest-expanding demand pool as tablet disintegrants and capsule binders drive specification-grade procurement.
FDA food additive regulations and EFSA purity criteria govern ingredient safety and labeling claims for roll-dried starch entering food and pharmaceutical channels, while REACH compliance dictates chemical registration and migration limits for modified variants sold into European industrial adhesive markets. ISO standards for starch analytical methods provide cross-border quality benchmarks that reduce technical barriers to trade. Stakeholders must monitor evolving clean-label definitions and biobased certification schemes to align product portfolios with shifting procurement criteria.
Market Dynamics
Clean-label binding specifications from food manufacturers are compressing procurement cycles for roll-dried starch, forcing suppliers to revalidate native and modified grades under evolving purity benchmarks while tapioca supply chains in Southeast Asia absorb disproportionate capacity investment.
Growth Catalysts
- REACH compliance migration:European industrial adhesive buyers are accelerating specification-grade roll-dried starch procurement to meet ECHA registration deadlines for modified variants, tightening supplier qualification windows.
- Pharmaceutical tablet disintegrant demand:Capsule and oral solid dosage manufacturers are expanding cold-water soluble starch orders for rapid hydration binders in high-shear coating operations.
- Thailand tapioca processing expansion:New drum-drying capacity installations are lowering regional input costs for native starch exports to cost-sensitive emerging markets.
Market Restraints
- Corn wet milling concentration:Backward-integrated grain processors in the US Midwest control captive supply of high-amylose feedstocks, limiting independent roll-dried starch producer margin flexibility.
- Modified starch regulatory friction:FDA food additive petition requirements for cross-linked and stabilized grades create 18-24 month approval timelines that block rapid formulation pivots.
- Native starch substitution pressure:Unmodified tapioca derivatives from Vietnamese and Cambodian processors are displacing premium modified grades in basic binding applications.
Strategic Opportunities
- Pharmaceutical coating specialization:Specification-grade roll-dried starch for enteric and sustained-release tablet coatings commands pricing premiums unavailable in commodity food channels.
- ISO 17025 analytical certification:Third-party validated quality benchmarks reduce cross-border technical barriers for suppliers seeking multi-continental pharmaceutical contracts.
- Biobased adhesive feedstocks:Industrial binder manufacturers in Germany and the Netherlands are qualifying roll-dried starch as petrochemical replacement under EU Green Deal procurement mandates.
Industry Challenges
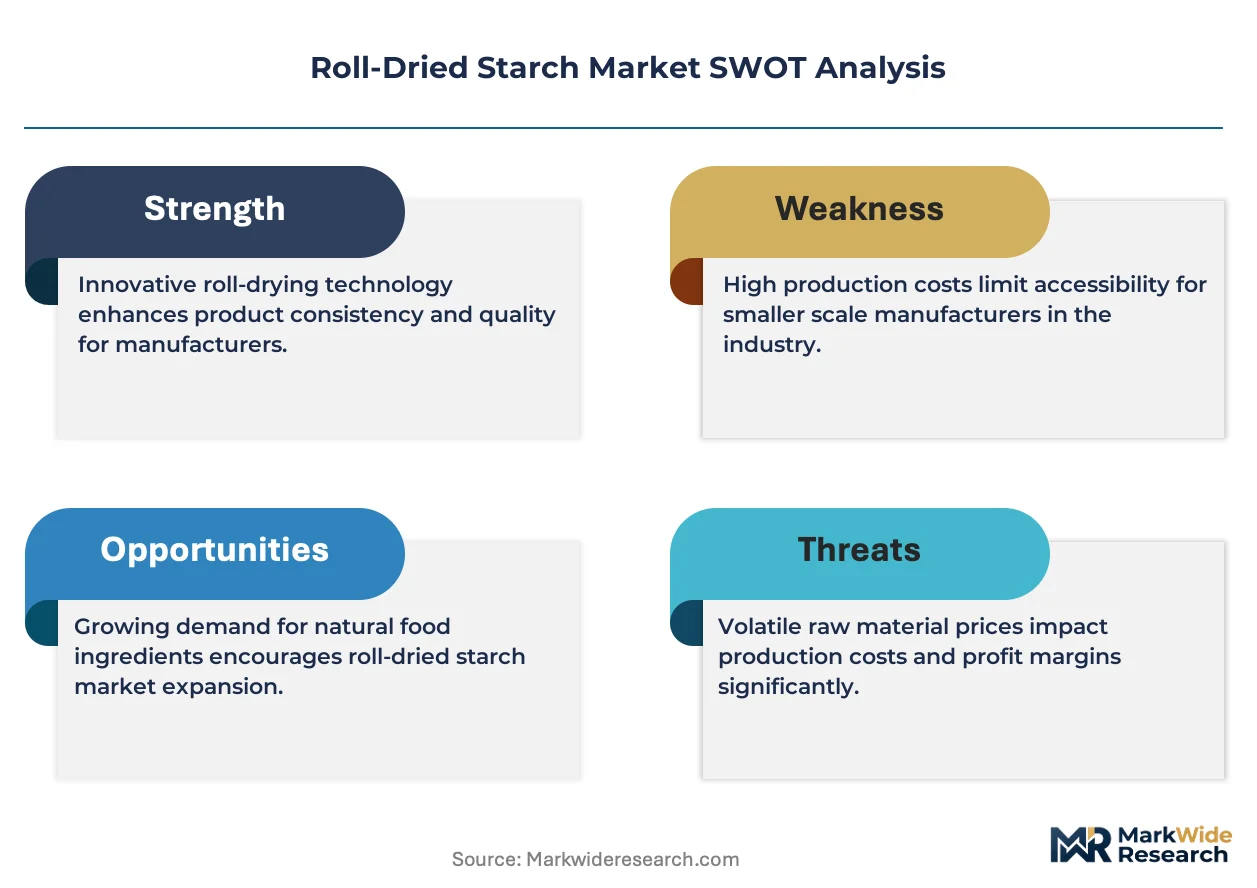
- Drum-drying energy intensity:Natural gas and electricity input volatility compresses operating margins for continuous-process roll-dried starch facilities requiring 24/7 thermal stability.
- Cross-functional formulation expertise:Food technologists with simultaneous starch chemistry and pharmaceutical excipient knowledge command scarcity premiums that inflate R&D team costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roll-Dried Starch Market |
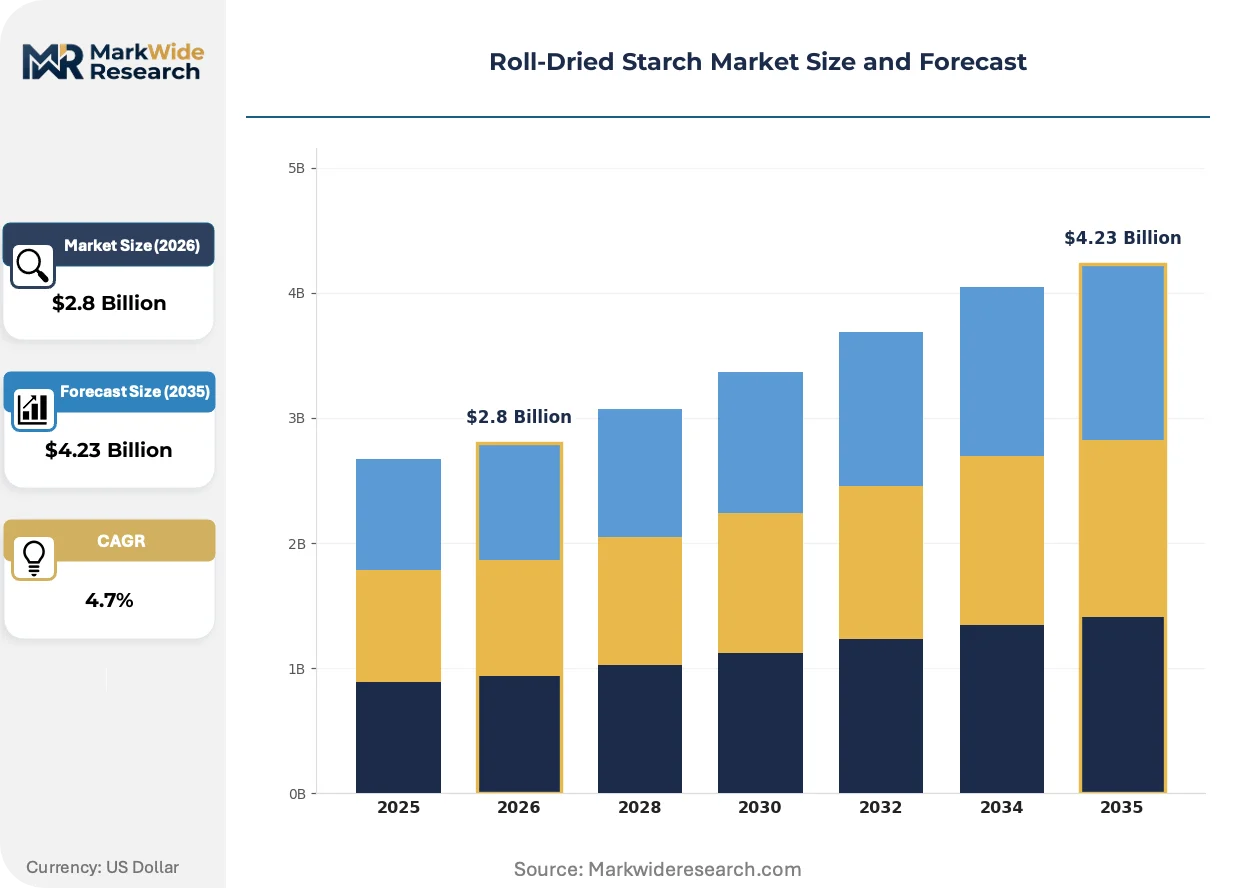
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Native Starch, Instant Starch, Pregelatinized Starch Application: Food Industry, Pharmaceutical, Cosmetics, Adhesives End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Industrial Users Packaging Type: Bags, Drums, Bulk Containers, Totes |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Ingredion, Roquette Frères, Tate & Lyle, Grain Processing Corporation, Banpong Tapioca Flour Industrial, Galam, Buhler AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roll-Dried Starch Market Evolving Landscape
Roll-dried starch processing is converging with precision drying control systems and real-time moisture analytics, compressing batch-to-batch variation while enabling just-in-time pharmaceutical qualification workflows.
Hybrid modified-native starch formulations are hybridizing cross-linked stability with unmodified label simplicity. Clean-label food manufacturers in Scandinavia and California are adopting these intermediate grades at pilot scale. The technology is hybridizing premium and economy tier boundaries, forcing suppliers to resegment pricing architectures.
EFSA purity criteria updates for food-grade starches are tightening heavy metal and solvent residue limits. European roll-dried starch importers are demanding certificate-of-analysis documentation from Thai and Indonesian processors. Pharmaceutical excipient channels face the steepest compliance cost escalation as audits extend to sub-tier tapioca cultivators.
Direct-procurement platforms are disintermediating traditional ingredient distributors for specification-grade roll-dried starch. Large food and pharma manufacturers are building captive supplier portals with real-time drum-drying capacity visibility. North American and Western European buyers are leading this channel compression, squeezing distributor margins while demanding faster lot-release documentation.
Roll-Dried Starch Market Segmentation
Roll-dried starch procurement decisions hinge on functional specifications that vary sharply across pharmaceutical excipient, food binding, and industrial adhesive channels. Suppliers must align drum-drying parameters and modification chemistries with distinct purity benchmarks and hydration kinetics demanded by each vertical.
Product Type:
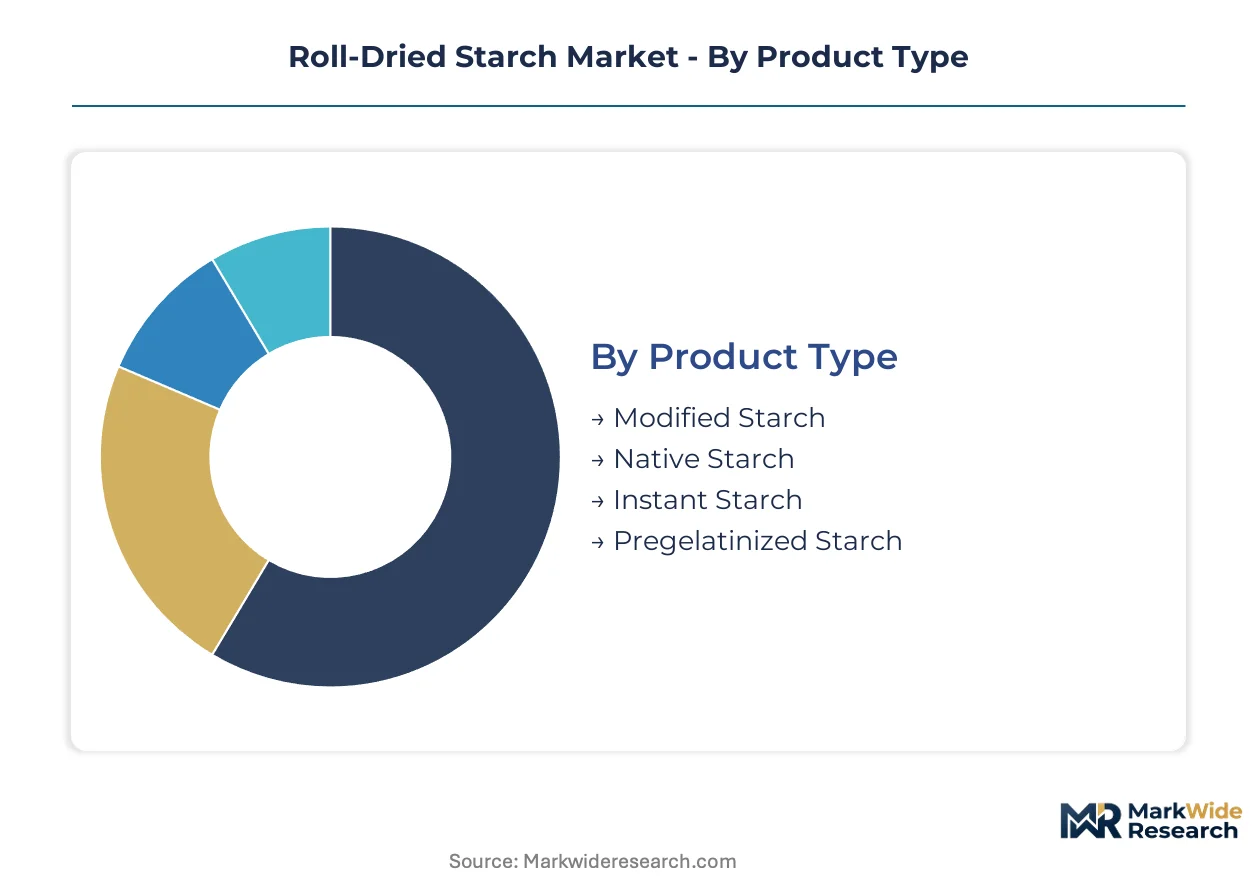
Cost tier stratification separates premium modified grades from economy native derivatives, with intermediate instant and pregelatinized variants capturing mid-market formulation flexibility.
- Modified Starch:Cross-linked and stabilized molecular architectures deliver acid tolerance and shear stability for high-temperature food processing. Pharmaceutical tablet coating operations in Germany and Switzerland drive specification-grade procurement under EMA excipient guidelines. FDA food additive petition requirements extend qualification timelines to 18-24 months.
- Native Starch:Unmodified tapioca and corn derivatives retain amylopectin structures in their natural state, offering label simplicity for clean-label food manufacturers. Southeast Asian drum-drying capacity expansion in Thailand and Vietnam compresses input costs for cost-sensitive emerging market buyers. REACH registration exemptions reduce compliance overhead for industrial adhesive applications.
- Instant Starch:Cold-water solubility enables rapid viscosity development without heat activation, serving convenience food manufacturers.
- Pregelatinized Starch:Partial starch gelatinization during drum-drying yields intermediate hydration rates for bakery and snack applications.
Modified starch commands the established base. The steepest expansion runs through native starch exports from Southeast Asian processing clusters.
Application:
Application focus determines regulatory pathway complexity, with pharmaceutical excipient channels imposing the steepest purity documentation requirements.
- Food Industry:Binding, thickening, and texturizing functions span bakery, dairy, and convenience food manufacturing. Scandinavian and California clean-label mandates are compressing procurement cycles toward native and hybrid modified-native grades. EFSA heavy metal limits are tightening certificate-of-analysis requirements for Thai-sourced tapioca derivatives.
- Pharmaceutical:Tablet disintegrants, capsule binders, and film-coating excipients demand ISO 17025-validated analytical documentation. Oral solid dosage manufacturers in Germany and the Netherlands are expanding cold-water soluble starch orders for high-shear coating operations. USP-NF monograph compliance separates specification-grade suppliers from commodity producers.
- Cosmetics:Powder binders and emulsion stabilizers utilize roll-dried starch for skin-feel modification in color cosmetics.
- Adhesives:Biobased binder formulations under EU Green Deal procurement mandates are qualifying starch as petrochemical replacement in German and Dutch industrial applications.
Food industry applications anchor volume procurement. Pharmaceutical specifications are climbing the fastest as lot-release documentation demands intensify.
End User:
Customer type segmentation reflects divergent technical support needs, with pharmaceutical firms requiring formulation partnership and industrial users prioritizing bulk logistics.
- Food Manufacturers:Clean-label binding specifications are forcing revalidation of native and modified grades under evolving purity benchmarks. Direct-procurement platforms with real-time drum-drying capacity visibility are disintermediating traditional ingredient distributors.
- Pharmaceutical Firms:Enteric and sustained-release tablet coating applications command pricing premiums unavailable in commodity channels. Cross-functional expertise spanning starch chemistry and excipient qualification commands scarcity premiums in R&D team assembly.
- Cosmetic Companies:Color cosmetic and skincare formulators utilize starch for oil absorption and texture modification.
- Industrial Users:Adhesive and paperboard manufacturers source bulk volumes with emphasis on consistent moisture content and particle size distribution.
Food manufacturers represent the volume foundation. Pharmaceutical firms are expanding procurement most aggressively as captive supplier portals proliferate.
Packaging Type:
Packaging configuration aligns with order scale and contamination sensitivity, from bulk logistics for industrial users to sealed containers for pharmaceutical excipients.
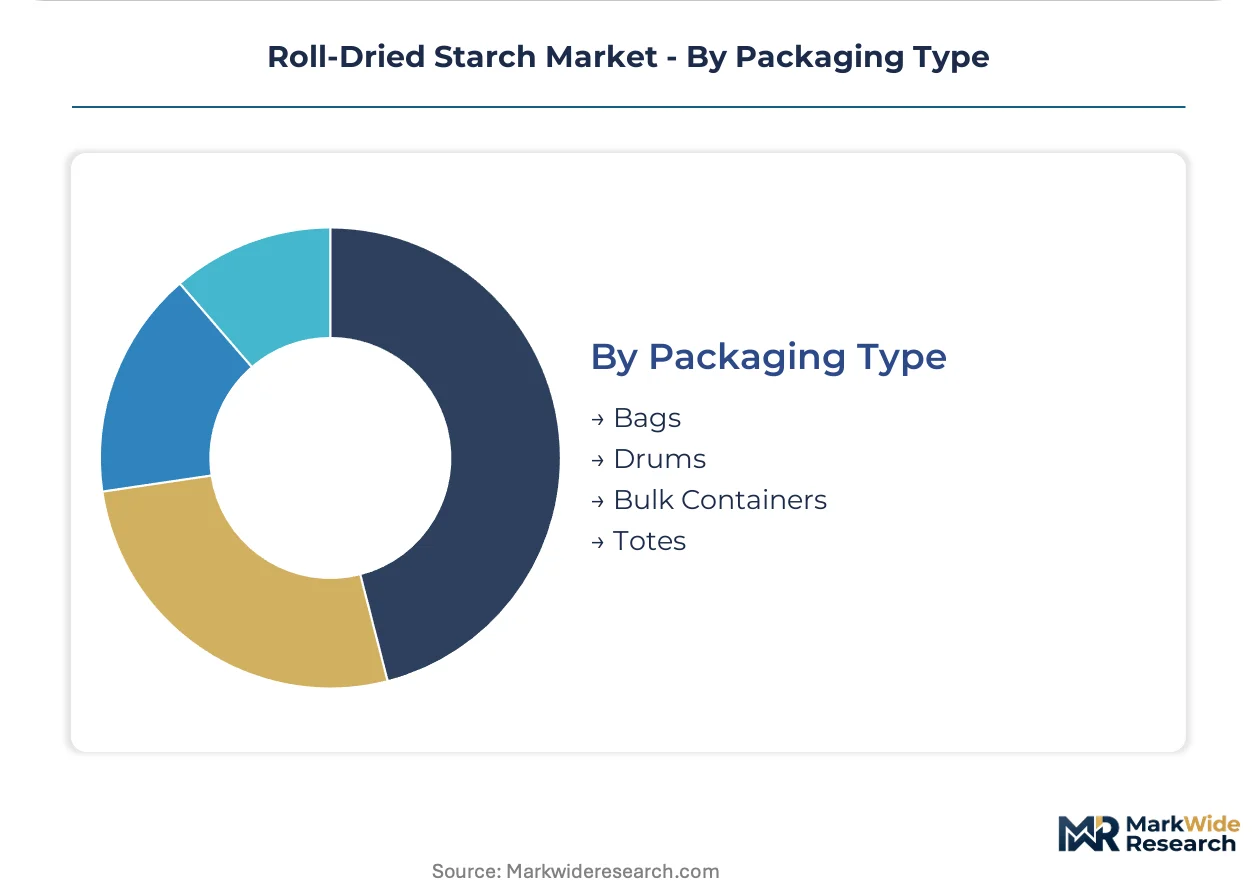
- Bags:Multi-wall paper and woven polypropylene configurations serve mid-scale food and cosmetic manufacturers with moderate throughput requirements.
- Drums:Steel and fiber drums with liner systems protect pharmaceutical-grade starch from moisture ingress during extended storage.
- Bulk Containers:Flexible intermediate bulk containers and silo truck deliveries minimize handling costs for high-volume adhesive and food processing operations.
- Totes:Intermediate rigid and flexible totes balance logistics efficiency with lot traceability for cosmetic and specialty food applications.
Bulk containers dominate industrial procurement. Drum packaging is gaining share fastest in pharmaceutical channels as contamination control standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Drum-drying capacity expansion in Thailand and Vietnam is compressing regional input costs while European pharmaceutical buyers tighten purity documentation under EMA guidelines. Corn wet milling concentration in the US Midwest limits independent processor flexibility. Tapioca supply chain investments across Southeast Asia are reshaping export flows toward cost-sensitive emerging markets.
United States
Pharmaceutical tablet coating operations in New Jersey and North Carolina drive specification-grade starch procurement for oral solid dosage applications. FDA food additive petition requirements for modified grades extend qualification timelines to 18-24 months. Corn wet milling clusters in Iowa and Illinois control captive high-amylose feedstock supply, constraining independent roll-dried starch producer margins.
Germany
Industrial adhesive manufacturers under EU Green Deal procurement mandates are qualifying starch as petrochemical replacement in biobased binder formulations. ECHA REACH registration deadlines for modified variants are accelerating specification-grade procurement from qualified suppliers. The Rhine-Ruhr industrial corridor hosts drum-drying facilities serving pharmaceutical excipient channels with ISO 17025-validated quality benchmarks.
Thailand
New drum-drying capacity installations in Kanchanaburi and Nakhon Ratchasima provinces are lowering regional input costs for native tapioca starch exports. EFSA heavy metal and solvent residue limits are tightening certificate-of-analysis documentation requirements for European-bound shipments. Bangkok-based processing clusters are expanding cold-water soluble starch output for convenience food manufacturers across ASEAN markets.
India
Domestic pharmaceutical firms in Hyderabad and Ahmedabad are expanding cold-water soluble starch orders for high-shear tablet coating operations. CDSCO excipient guidelines under ICH Q3D standards are imposing elemental impurity testing burdens on imported starch grades. Gujarat's corn processing belt is developing modified starch capabilities for acid-tolerant food applications.
Netherlands
Biobased adhesive feedstock procurement in Rotterdam and Eindhoven industrial zones is qualifying roll-dried starch under EU Green Deal chemical substitution mandates. ECHA migration limits for modified variants sold into industrial channels are dictating supplier qualification windows. The Randstad logistics hub enables just-in-time pharmaceutical qualification workflows with real-time drum-drying capacity visibility.
Roll-Dried Starch Market Competitive Landscape
Backward-integrated grain processors and Southeast Asian tapioca specialists split the market into distinct supply archetypes with divergent cost structures. The competitive terrain tiers around modification chemistry capabilities, with cross-linked and stabilized grades commanding premium positioning in pharmaceutical channels. Three strategic archetypes dominate: multinational agribusiness conglomerates with captive corn wet milling operations, Southeast Asian tapioca processors with drum-drying scale advantages, and pharmaceutical excipient specialists with ISO-certified analytical capabilities. Competitive moves concentrate on capacity expansion in Thai processing clusters and strategic partnerships for REACH-compliant European distribution.
Among North American agribusiness conglomerates, Archer Daniels Midland Company and Cargill Incorporated occupy positions anchored by global grain sourcing networks and in-house wet milling infrastructure. Ingredion represents the pharmaceutical-specialist archetype with modified starch formulation capabilities. These three companies exemplify the tiered competitive structure where captive feedstock control, regional processing scale, and excipient certification credentials determine market access across food, pharmaceutical, and industrial verticals.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Ingredion |
| Roquette Frères |
| Tate & Lyle |
| Grain Processing Corporation |
| Banpong Tapioca Flour Industrial |
| Galam |
| Buhler AG |
| Others |
Value Network & Pricing Analysis
Overcapacity in Thai drum-drying facilities is compressing regional native starch quotations while forcing European pharmaceutical buyers to absorb premium pricing for REACH-compliant modified grades. This utilization asymmetry between Southeast Asian export hubs and specification-grade Western markets creates divergent supplier behavior and pricing power dynamics.
Pricing Analysis
REACH registration requirements dictate the pricing tier structure across European industrial adhesive channels, separating qualified specification-grade suppliers from commodity exporters. Three-tier pricing structure across premium, standard, and economy levels reflects modification chemistry depth, with cross-linked pharmaceutical grades commanding substantial premiums over unmodified tapioca derivatives. Price differentiation hinges on ISO 17025 certification status and EFSA heavy metal compliance documentation. Cost compression in native starch tiers is intensifying because Vietnamese and Cambodian processors are expanding unmodified capacity. Food manufacturers in Scandinavia and California exhibit the highest price sensitivity, while pharmaceutical firms in Germany and Switzerland demonstrate inelastic demand for excipient-grade procurement.
Supply Chain Analysis
Extended payment terms from Thai processors to tapioca cultivators are stabilizing raw material flows through supply-chain finance facilities anchored in Bangkok banking networks. Geographic supply concentration centers on Thailand, Vietnam, and Indonesia for native starch exports, with the US Midwest and Germany serving modified grade production. Raw material dependencies include cassava root, corn wet-milled feedstocks, and natural gas for thermal drying operations. Single-source vulnerability runs through Southeast Asian tapioca cultivators facing EFSA audit extension to sub-tier suppliers. Distribution runs through direct-procurement platforms with real-time drum-drying capacity visibility, disintermediating traditional ingredient distributors for large food and pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roll-dried starch incumbents must defend against native starch substitution in basic binding applications, where unmodified tapioca derivatives from Vietnamese processors are displacing premium modified grades across cost-sensitive emerging markets.
For Market Incumbents: Entrench specification-grade positioning through ISO 17025 analytical certification investments that lock in pharmaceutical excipient contracts with German and Dutch oral solid dosage manufacturers. Deepen backward integration into corn wet milling operations to secure captive high-amylose feedstock supply against US Midwest processor concentration. The native starch substitution threat from Southeast Asian processors demands accelerated hybrid modified-native formulation development to capture clean-label food manufacturers in California and Scandinavia. For New Entrants and Emerging Players: Build out drum-drying capacity in Cambodian or Vietnamese processing clusters to exploit cost advantages in native starch exports toward African and South Asian emerging markets. Pharmaceutical coating specialization offers the most penetrable white-space target, as enteric and sustained-release tablet applications command pricing premiums unavailable in commodity food channels. A go-to-market angle anchored on EFSA-compliant certificate-of-analysis documentation with European importer partnerships bypasses established distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical excipient specialists with ISO-certified analytical capabilities and long-term supply agreements with German tablet coating operations. Long-term viability over the next decade hinges on biobased adhesive feedstock positioning under EU Green Deal procurement mandates. Acquisition targets should emphasize Thai or Vietnamese processors with existing drum-drying infrastructure and EFSA audit readiness. The signal to watch is CDSCO excipient guideline harmonization with ICH Q3D standards in India, which would accelerate specification-grade demand from Hyderabad and Ahmedabad pharmaceutical clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet Milling | Captive high-amylose feedstock supply secures margin control against US Midwest processor concentration. |
| ISO 17025 Analytical Certification | Third-party validated quality benchmarks unlock multi-continental pharmaceutical excipient contracts. |
| Thai Drum-Drying Capacity Expansion | Regional scale advantages compress input costs for native starch exports to emerging markets. |
| Hybrid Modified-Native Formulation Development | Intermediate grades capture clean-label food manufacturers seeking label simplicity with functional stability. |
| Direct-Procurement Platform Launch | Real-time capacity visibility disintermediates distributors and accelerates lot-release documentation for large manufacturers. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with starch industry stakeholders and secondary validation across regulatory and trade databases. Primary interviews captured perspectives from drum-drying plant managers in Thailand and Vietnam, procurement leads at German pharmaceutical manufacturers, food technology directors at Scandinavian clean-label brands, and distribution channel partners in European industrial adhesive markets. Secondary sources included FDA food additive petition filings, ECHA REACH registration databases, EFSA purity criteria updates, customs and trade flow data for tapioca-derived starch, and SEC 10-K disclosures from publicly traded agribusiness conglomerates. Bottom-up capacity assessments across Southeast Asian processing clusters were triangulated against top-down demand modeling from pharmaceutical and food end-use segments.
Forecast inputs considered drum-drying capacity utilization rates, modification chemistry adoption curves, and regulatory compliance cost trajectories across the projection horizon. Segmentation dimensions modeled included product type tier, application vertical, end-user archetype, and regional production hub. CAGRs were derived through trend extrapolation of historical procurement patterns and elasticity-adjusted demand projections. Industry-specific inputs encompassed EMA excipient guideline evolution and EU Green Deal biobased procurement mandate implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Thai tapioca processors or accelerated pharmaceutical qualification workflows by Indian domestic firms would shift outcomes. Macroeconomic volatility in natural gas pricing, regulatory deviation in FDA food additive petition requirements, or technological disruption in precision drying control systems would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Middle East and Africa Lipids Market
Ingredients
United Kingdom Protein Market
Ingredients
North America Phytosterols Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
China Gelatin Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Coconut Oil Market
Ingredients
North America Gelatin Market
Ingredients
Global Amaranth Oil Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Cocoa Fiber Market
Ingredients
Vegan Ingredients Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
Asia-Pacific Protein Market