
 Functional Flours Market | 2026-2036
Functional Flours Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Flours Market Intelligence
New processing capacity in Southeast Asia for rice and alternative grains is rebalancing the supply of specialty flours. Archer-Daniels-Midland Company leverages its vast global sourcing network to secure diverse raw materials. Ingredion Incorporated specializes in modified corn and rice flours for specific food processing applications, while Cargill Incorporated competes through its large-scale production and extensive distribution channels.
Functional flours are cereal or non-cereal-based powders that have been physically, enzymatically, or chemically modified to enhance specific properties like water absorption or viscosity. These flours are not just nutritional bases but active ingredients designed to improve texture, stability, and shelf-life in processed foods. Demand for gluten-free products drives growth in the almond and rice flour segments. The baking industry remains the largest end use, while applications in snacks and coatings represent a fast-growing area.
Regulatory frameworks from the US FDA and the European Food Safety Authority (EFSA) govern health claims and allergen labeling, directly influencing product formulation. Additionally, food safety standards like ISO 22000 are critical for market access in export-oriented supply chains. Millers and food processors must now navigate the dual pressures of achieving specific functional outcomes while ensuring compliance with evolving clean-label consumer expectations.
Market Dynamics
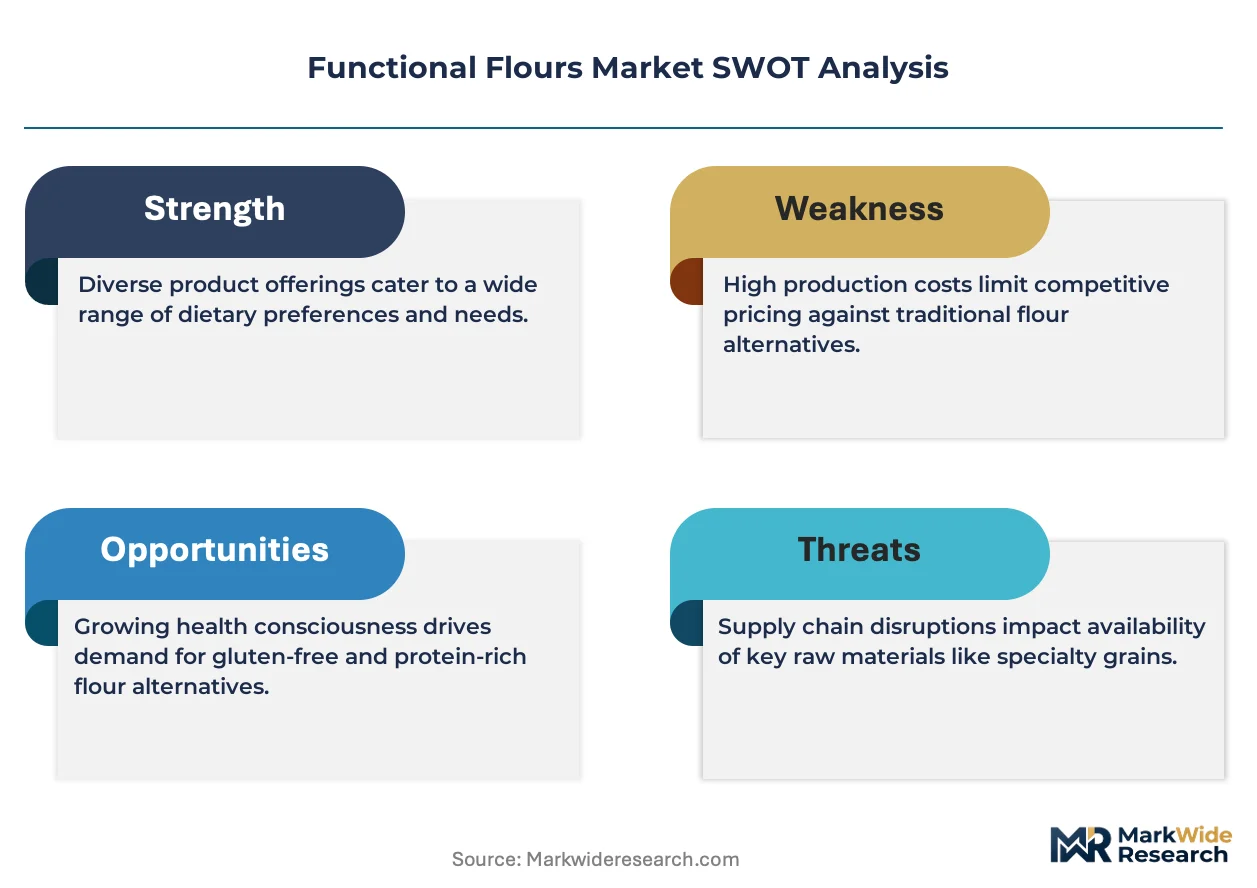
The central force shaping the functional flours market is the dual demand for clean-label, plant-based ingredients and the rigorous technical performance required by industrial food processing for texture, stability, and shelf-life in finished goods.
Growth Catalysts
- Gluten-Free Product Demand:Consumer health trends, particularly in the United States and European Union, drive expansion in the baking and snack sectors for non-wheat alternatives like almond, coconut, and rice flours.
- Processing Technology:Innovations in hydrothermal treatment and extrusion are creating flours with superior water absorption and viscosity, expanding their use beyond baking into sauces, soups, and coatings.
- Supply Chain Development:The establishment of new milling and processing facilities in Southeast Asia for rice and tapioca is improving the global supply and cost-competitiveness of key specialty flours.
Market Restraints
- Raw Material Price Volatility:Significant price fluctuations for agricultural inputs like tree nuts and specialty grains create margin uncertainty for millers and pass-through cost instability for food manufacturers.
- Functional Replication Gaps:Despite advances, many non-wheat flours still struggle to perfectly replicate the viscoelastic and leavening properties of gluten, limiting their use in certain artisanal bread applications.
- Allergen Management Costs:The need for dedicated production lines and stringent cleaning protocols to prevent cross-contamination in facilities handling both gluten and non-gluten grains imposes substantial operational costs.
Strategic Opportunities
- Plant-Based Food Formulation:The fast-growing plant-based meat and dairy analogue sector presents a major opportunity for pulse and legume flours to act as binders, texturizers, and protein fortifiers.
- Nutraceutical Applications:Developing flours with specific, scientifically validated health benefits, such as high-fiber variants for gut health, opens pathways into the high-margin functional food and dietary supplement markets.
- Emerging Market Penetration:Markets in Latin America and the Middle East show rising interest in healthier and more diverse food products, creating white space for functional flours in processed and packaged goods.
Industry Challenges
- Complex Regulatory Navigation:Millers and food processors face significant hurdles in aligning product formulations and marketing claims with the distinct regulatory frameworks of the US FDA and the European Food Safety Authority.
- Formulation Expertise Scarcity:A shortage of food scientists with the specialized skills to reformulate products using novel flours without sacrificing taste or texture creates a development bottleneck for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Flours Market |
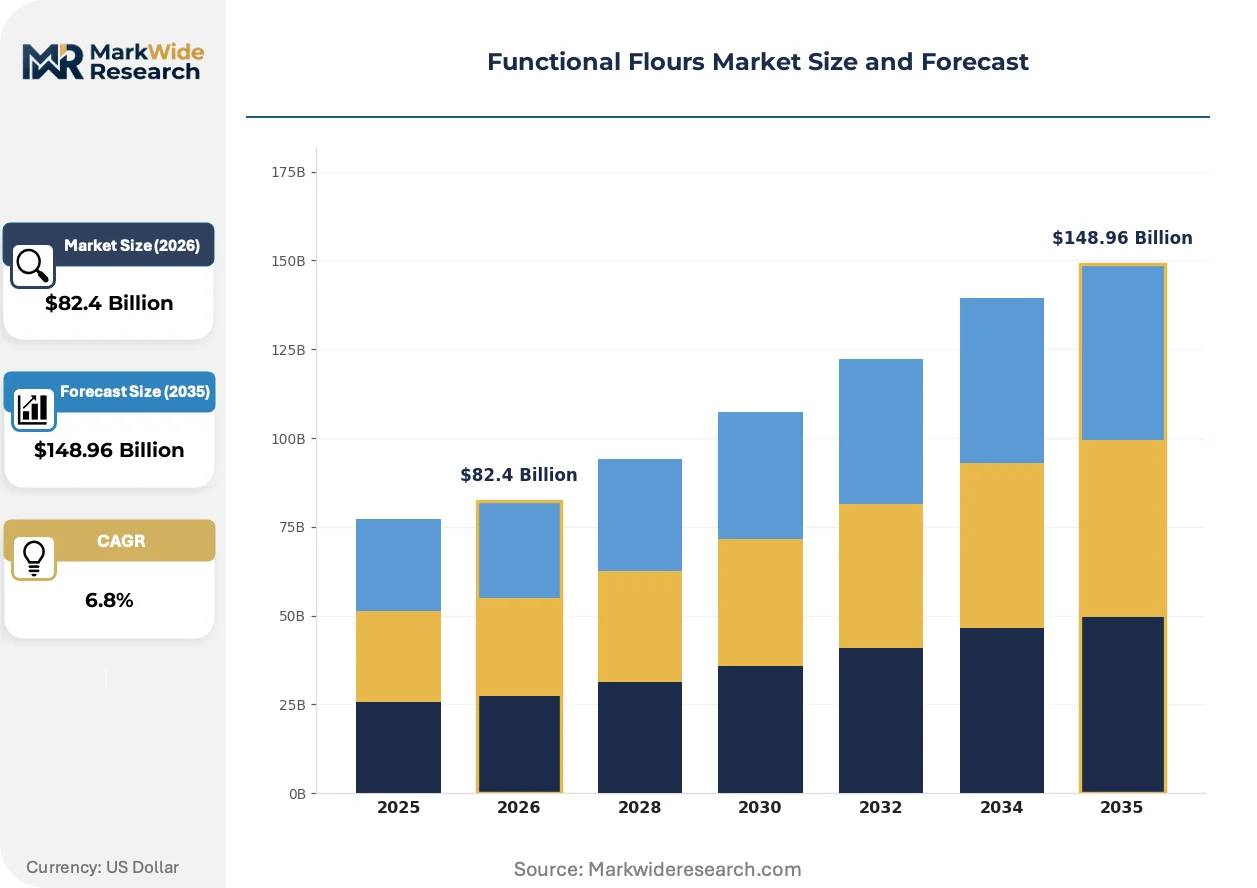
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $148.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Flour, Corn Flour, Rice Flour, Almond Flour End Use Industry: Baking, Confectionery, Snacks, Food Processing Application: Gluten-Free Products, Thickening Agents, Coatings, Breading Form: Powder, Granule, Paste, Blends |
| Companies Covered | Ingredion Incorporated, General Mills Inc., Cargill Incorporated, Parrish and Heimbecker Limited, SunOpta Inc., Archer-Daniels-Midland Company, Bunge Limited, The Scoular Company, Associated British Foods plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Flours Market Strategic Shifts & Innovations
Innovation is driven by the convergence of food science and consumer health demands. The market is shifting from using flours as simple bulk ingredients to engineering them as active components that deliver specific textural, nutritional, and processing outcomes.
Enzymatic modification provides a precise method for tailoring the functional properties of starch and protein within a flour. Industrial bakeries and processed food manufacturers are the primary adopters, seeking to improve dough rheology, moisture retention, and shelf stability. This advanced treatment is integrating principles of biotechnology into milling, creating highly specialized ingredients designed for specific applications.
The European Food Safety Authority's (EFSA) rigorous scrutiny of health claims directly impacts product development and marketing strategies. This forces manufacturers to fund extensive clinical research to substantiate any claims related to fiber content, glycemic response, or satiety. The functional food and beverage segments targeting health-conscious consumers in the EU are most affected by these evidence requirements.
A definitive shift toward "clean label" sourcing is altering procurement behavior among major food manufacturers and retailers. This trend prioritizes flours derived from physical modification processes over chemical ones and favors ingredients with certifications like non-GMO or organic. This purchasing pattern is most pronounced within the infant nutrition and premium baked goods categories in North America and Western Europe.
Functional Flours Market Segmentation
Understanding the functional flours market through its segmentation reveals the diverse applications and technological requirements across various industries. This granular view helps identify specific demand pockets and the specialized processing capacities needed to serve them. Each segment reflects distinct consumer preferences and industrial formulation challenges.
Product Type:
The capital intensity of milling and processing equipment varies significantly across different product types, influencing market entry barriers and scale. Producing specialty flours often requires dedicated lines to prevent cross-contamination.
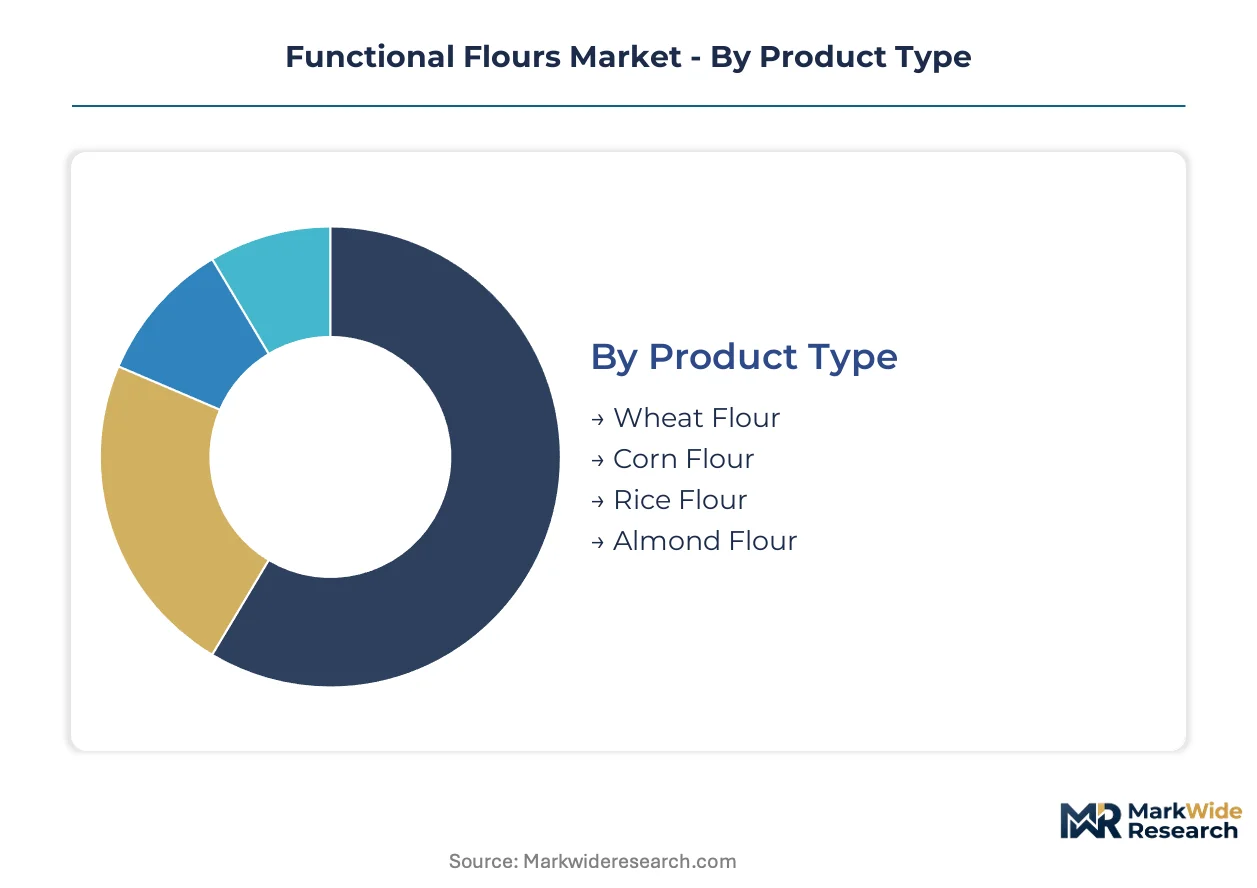
- Wheat Flour:This traditional flour provides viscoelastic properties essential for many baked goods and serves as a foundational ingredient in numerous food products. Its widespread availability and established supply chains maintain its market presence.
- Corn Flour:Derived from corn kernels, this flour offers unique textural attributes and is widely used as a thickening agent and binder in various food preparations. Global demand for corn flour is stable across diverse culinary traditions.
- Rice Flour:Produced from finely milled rice, this gluten-free alternative provides a neutral flavor profile and is crucial for gluten-intolerant consumers. Demand for rice flour is concentrating in the United States and European Union, driven by celiac disease prevalence.
- Almond Flour:This nutrient-dense, low-carbohydrate flour comes from blanched and ground almonds, offering a premium ingredient for gluten-free and keto-friendly products. Its high cost reflects the specialized processing and raw material expense.
Wheat Flour absorbs the bulk of installed capacity; Almond Flour is expanding most quickly.
End Use Industry:
Application diversity across end-use industries dictates the specific functional properties required from flours, from dough rheology to emulsion stabilization. Each sector presents distinct challenges for product formulation.
- Baking:This industry represents the largest consumer of functional flours, utilizing them for improved dough handling, texture, and shelf-life in bread, cakes, and pastries. Innovations in flour modification directly impact baking performance.
- Confectionery:Functional flours contribute to texture, moisture retention, and sugar crystallization control in candies, chocolates, and sweet snacks. Their use enhances product stability and mouthfeel.
- Snacks:Functional flours provide crispness, binding, and nutritional enhancement in extruded snacks, crackers, and savory bites. Consumer demand for healthier snack options drives ingredient innovation.
- Food Processing:This broad category encompasses a wide range of applications, including sauces, soups, dairy alternatives, and processed meats, where flours act as thickeners, binders, and texturizers. Technical performance and cost-effectiveness are paramount for industrial processors.
The baking industry consistently drives volume, while food processing applications exhibit dynamic innovation.
Application:
The consumer impact of specific applications shapes product development, particularly for health-focused attributes like gluten-free or improved digestive health. Regulatory frameworks also influence claim substantiation.
- Gluten-Free Products:This segment includes a wide array of foods formulated without wheat, barley, or rye, catering to individuals with celiac disease or gluten sensitivity. Demand in the United States and Germany fuels research into alternative flour blends.
- Thickening Agents:Functional flours are widely employed to increase viscosity and improve the body of liquids in soups, gravies, sauces, and dairy products. Their ability to stabilize emulsions is critical for food manufacturers.
- Coatings:Flours are used to create crispy or crunchy textures on fried foods, baked items, and snacks, providing adhesion and preventing moisture loss. Specialized flours enhance browning and oil absorption characteristics.
- Breading:This application involves using flours as a protective and textural layer for meats, vegetables, and seafood, improving cooking performance and sensory appeal. Consistent particle size is crucial for even coverage.
Gluten-Free Products demand specific formulations, whereas Thickening Agents offer broad utility across food types.
Form:
Processing flexibility across different forms of functional flours allows manufacturers to optimize ingredient incorporation and final product characteristics. The form can impact solubility, dispersion, and storage stability.
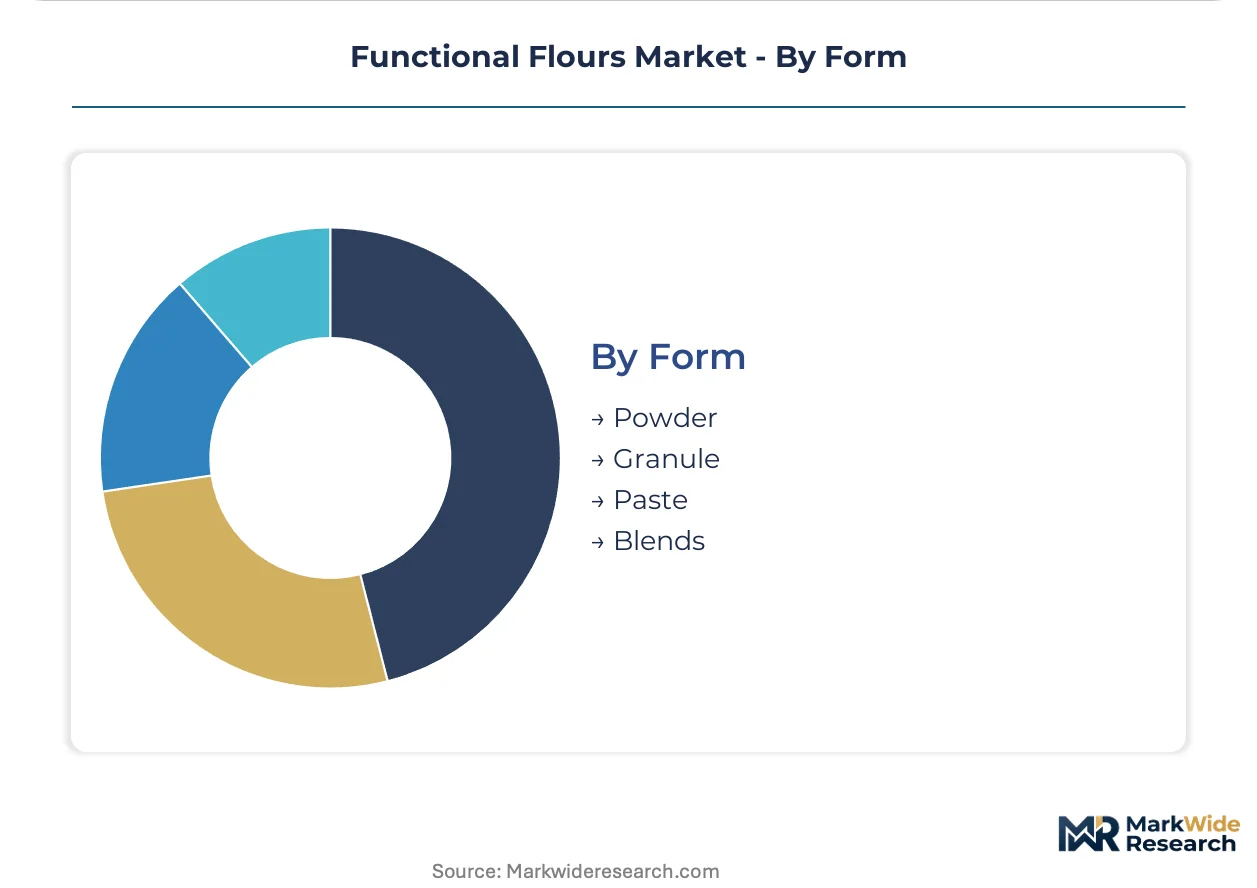
- Powder:The most common form, powdered functional flours offer ease of handling, blending, and storage stability for dry mixes and industrial formulations. Their fine particle size ensures uniform dispersion in many applications.
- Granule:Granulated flours provide reduced dustiness and improved flowability compared to powders, making them suitable for specific processing environments and applications requiring controlled dissolution. They are often used in beverage mixes.
- Paste:Flours in paste form offer pre-hydrated or pre-gelatinized options, simplifying incorporation into liquid systems and reducing processing time for certain food preparations. Pastes can provide immediate viscosity.
- Blends:Custom blends combine multiple functional flours or other ingredients to achieve specific textural, nutritional, or processing outcomes for a tailored solution. These blends address complex formulation challenges.
Powdered flours remain ubiquitous, while custom blends enable precise functional outcomes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors demand for functional flours, particularly for gluten-free and health-conscious food products. This market expansion is driven by consumer health trends and a robust food processing industry. Manufacturers actively seek specialized flours to meet evolving dietary preferences and functional requirements.
United States
Consumer demand for gluten-free and plant-based alternatives drives functional flour consumption in the United States. The US FDA regulates health claims and allergen labeling, directly impacting product formulation and marketing. California's food innovation hubs, particularly around San Francisco and Los Angeles, concentrate research into novel flour applications for plant-based meats and dairy analogues.
Germany
Germany exhibits strong demand for functional flours, fueled by a preference for organic and clean-label ingredients in baking and confectionery. The European Food Safety Authority (EFSA) sets stringent standards for food additives and novel foods, influencing product development. Munich and Berlin's food technology clusters are centers for developing specialized flour blends for artisanal bakeries and health food manufacturers.
China
China's functional flours market expands with increasing urbanization and a rising middle class seeking healthier processed foods. The NMPA (National Medical Products Administration) and SAMR (State Administration for Market Regulation) oversee food safety and ingredient approvals. Shanghai's expansive food manufacturing sector actively integrates functional flours into convenience foods and snack products.
India
India's functional flour consumption is growing due to dietary diversification and an expanding packaged food industry. The FSSAI (Food Safety and Standards Authority of India) establishes guidelines for food ingredients and labeling. The Delhi-NCR region, with its large consumer base and food processing facilities, shows significant adoption of flours for improved texture and nutritional profiles in traditional and modern foods.
Brazil
Brazil represents a significant market for functional flours, driven by the expansion of its processed food sector and growing health awareness. ANVISA (National Health Surveillance Agency) regulates food additives and ingredients, ensuring product safety and compliance. São Paulo's industrial food parks are key areas for the application of functional flours in bakery, confectionery, and meat alternative products.
Functional Flours Market Key Industry Players
Global majors compete with regional champions across raw material sourcing and processing capabilities within the functional flours market. The industry structure is moderately concentrated, with a few large players holding significant market share alongside numerous specialized producers. Key strategic archetypes include integrated agricultural processors, ingredient specialists, and niche product innovators. Companies primarily pursue market share through capacity expansion and portfolio diversification.
At the scale-driven end, Archer-Daniels-Midland Company and Cargill Incorporated exemplify integrated agricultural powerhouses. These firms leverage extensive global supply chains to source diverse raw materials and process them into a wide array of functional flours. Ingredion Incorporated occupies a position as a leading ingredient specialist, focusing on modified corn and rice flours for specific food processing applications. These entities collectively shape the competitive dynamics through their broad product offerings and extensive distribution networks.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| General Mills Inc. |
| Cargill Incorporated |
| Parrish and Heimbecker Limited |
| SunOpta Inc. |
| Archer-Daniels-Midland Company |
| Bunge Limited |
| The Scoular Company |
| Associated British Foods plc |
| Others |
Cost & Logistics Intelligence
The clear divergence between commodity and specialty functional flours dictates distinct pricing models and supply chain configurations. Premium flours demand specialized processing and certified raw materials, leading to higher costs and more controlled distribution. Commodity flours, conversely, compete on volume and efficiency through established agricultural networks.
Pricing Analysis
Service bundling with technical support and formulation expertise differentiates premium functional flour pricing. The dominant pricing structure for large industrial buyers is contract-based long-term offtake, while smaller customers often use spot pricing. Price differentiation stems from certification levels, such as organic or non-GMO, and the degree of customization for specific applications. Pricing pressure stems from oversupply in commodity wheat flour, whereas specialty flours maintain price strength due to specific demand. Industrial food processors are most price-sensitive for bulk ingredients, while premium baked goods manufacturers show less sensitivity for highly specialized flours.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks facilitate efficient delivery of functional flours to diverse end-users. Geographic supply concentrates in the United States for corn and wheat, Southeast Asia for rice and tapioca, and Europe for specialty grains. The market relies heavily on specific raw material inputs like tree nuts, pulses, and modified starches. Raw material price volatility for agricultural commodities presents a significant structural risk. Distribution runs through direct sales channels for major food manufacturers and specialized ingredient distributors for smaller customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The functional flours market operates within supply constraints. Specialized milling capacity for alternative grains remains a bottleneck, propping up pricing for niche products.
For Market Incumbents: Acquire specialized milling and processing facilities to expand alternative grain flour production. Invest in hydrothermal treatment technologies to enhance functional properties and secure long-term raw material contracts for stability. This mitigates threats from emerging plant-based protein suppliers. Prioritize capacity addition in Southeast Asia for rice flour to leverage regional supply advantages.
For New Entrants and Emerging Players: Launch via specialized ingredient distributors targeting emerging plant-based food startups. Target underpenetrated segments like nutraceutical applications and the fast-growing plant-based meat and dairy analogue sector. Focus on developing novel pulse and legume flours to address specific binding and texturizing needs. The small-batch artisanal bakery segment offers a penetrable entry point.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized ingredient producers with proprietary processing technologies. The market demonstrates strong long-term viability over the next decade, driven by health and clean-label trends. Identify mid-sized processors with unique intellectual property in enzymatic modification or sustainable sourcing as prime acquisition targets. Regulatory approvals for novel health claims will serve as a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Increases global supply of rice and tapioca flours, improving cost-competitiveness. |
| R&D in Enzymatic Modification | Develops flours with tailored functional properties for specific food applications. |
| Long-term Sourcing Contracts | Ensures raw material supply stability and mitigates price volatility for key inputs. |
| Certification Investment (e.g., Organic, Non-GMO) | Meets clean-label consumer preferences and regulatory requirements in key markets. |
| Digital Sales Platform for Small Businesses | Expands market reach to artisanal bakeries and niche food producers globally. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. This secondary research was rigorously validated through primary interviews with industry stakeholders. We engaged food scientists, procurement managers, R&D directors, and regulatory affairs specialists to gather qualitative insights. US FDA guidance, EFSA opinions, NMPA announcements, and FSSAI reports provided critical regulatory context and market intelligence. A robust bottom-up and top-down triangulation approach ensured data accuracy.
Volume and value were modeled at granular levels across product type, end-use industry, application, and key regional markets. The analytical framework segmented the market by product type, including wheat, corn, rice, and almond flours. End-use industries like baking and snacks, alongside applications such as gluten-free products and thickening agents, were also modeled. Compound annual growth rates were derived from historical data and projected growth drivers across the analysis window. Consumer health trends and technological advancements in processing served as key forecast inputs.
Raw material price volatility, shifts in regulatory frameworks, and unforeseen technological disruptions are the dominant revision risks for market forecasts. These forecasts reflect assumptions regarding market dynamics and competitive landscapes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Chickpea Fiber Market
Ingredients
Vegetable Concentrates Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Textured Soy Protein Market
Ingredients
North America Carrageenan Market
Ingredients
Oak Extract Market
Ingredients
North America Gelatin Market
Ingredients
Codonopsis Extract Market
Ingredients
Vitamin C Ingredients Market
Ingredients
Refined Coconut Oil Market
Ingredients
Jasmine Extract Market
Ingredients
United States Soy Protein Market
Ingredients
Fruit Concentrate Market
Ingredients
Edible Animal Fat Market
Ingredients
Dried Fruit Ingredients Market
Ingredients
Asia Pacific Vegetable Oil Market