
 Acetylated Starch Market | 2026-2036
Acetylated Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Acetylated Starch Market Outlook
Project finance for greenfield biorefineries is rewriting competitive entry barriers in acetylated starch manufacturing. Cargill, Incorporated leverages its integrated corn supply chain across the US Midwest to sustain cost leadership in food-grade output. Roquette Frères anchors European production through pea and potato starch specialization, while Ingredion Incorporated competes via global formulation partnerships with packaged food manufacturers.
Acetylated starch is a modified starch ester produced through acetic anhydride treatment of native starches, typically achieving a degree of substitution between 0.01 and 0.2 to confer freeze-thaw stability and reduced retrogradation. The compound functions primarily as a thickening agent, stabilizer, and texturizer across food systems, pharmaceutical binders, and adhesive formulations. Food Grade output dominates volume as clean-label reformulations drive replacement of synthetic additives in sauces and frozen desserts. Pharmaceutical Grade commands premium positioning due to stringent USP and EP compliance requirements for excipient applications. Industrial Grade segments in coatings and adhesives face margin compression from petrochemical substitute competition.
FDA food additive regulations under 21 CFR 172.892 govern acetylated starch purity thresholds for US market access, while REACH registration requirements in Europe enforce comprehensive toxicological dossiers for industrial applications. China's SAMR implements GB standards for modified starch labeling that constrain import flexibility for foreign suppliers. Stakeholders must monitor evolving EFSA re-evaluations of modified starch acceptable daily intakes and preemptively align manufacturing specifications with tightening cross-border regulatory convergence.
Market Dynamics
Clean-label reformulation mandates across packaged food manufacturing are compressing synthetic additive demand while expanding modified starch specification volumes in sauces, frozen desserts, and ready meals.
Growth Catalysts
- REACH compliance tightening:ECHA enforcement of comprehensive toxicological dossiers for industrial acetylated starch applications is elevating certified supplier premiums and consolidating procurement toward compliant manufacturers.
- Freeze-thaw stability specifications:Frozen dessert processors in Thailand and India are substituting acetylated starch for gelatin and carrageenan in clean-label ice cream formulations.
- Pea starch feedstock expansion:European pulse processing capacity is diversifying raw material bases beyond corn and potato, reducing input cost volatility for specialty acetylated grades.
Market Restraints
- Acetic anhydride cost volatility:Petrochemical feedstock price swings directly compress acetylated starch margin structures, particularly for industrial-grade adhesive applications.
- Supply concentration in US Midwest corn belt:Three integrated processors control approximately two-thirds of North American food-grade acetylated starch volume, creating procurement bottlenecks for mid-sized buyers.
- Native starch retrogradation limits:Unmodified starches remain technically viable for single-use ambient sauces, constraining premium pricing power for low-substitution acetylated grades.
Strategic Opportunities
- SAMR GB standard alignment:Foreign suppliers pre-certifying modified starch labeling compliance can capture share from domestic Chinese producers facing stricter enforcement.
- Pharmaceutical excipient grade expansion:USP and EP compliance investments open premium positioning in tablet binder and controlled-release matrix applications.
- Biorefinery co-location:Greenfield facilities integrating acetylation units with ethanol or protein extraction operations achieve energy and logistics cost advantages.
Industry Challenges
- Cross-functional regulatory expertise scarcity:Manufacturers struggle to staff teams conversant simultaneously in FDA 21 CFR 172.892, REACH dossier preparation, and SAMR GB implementation.
- Legacy equipment retrofit costs:Continuous acetylation reactor upgrades to meet tightening purity thresholds require capital deployment that mid-tier processors cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetylated Starch Market |
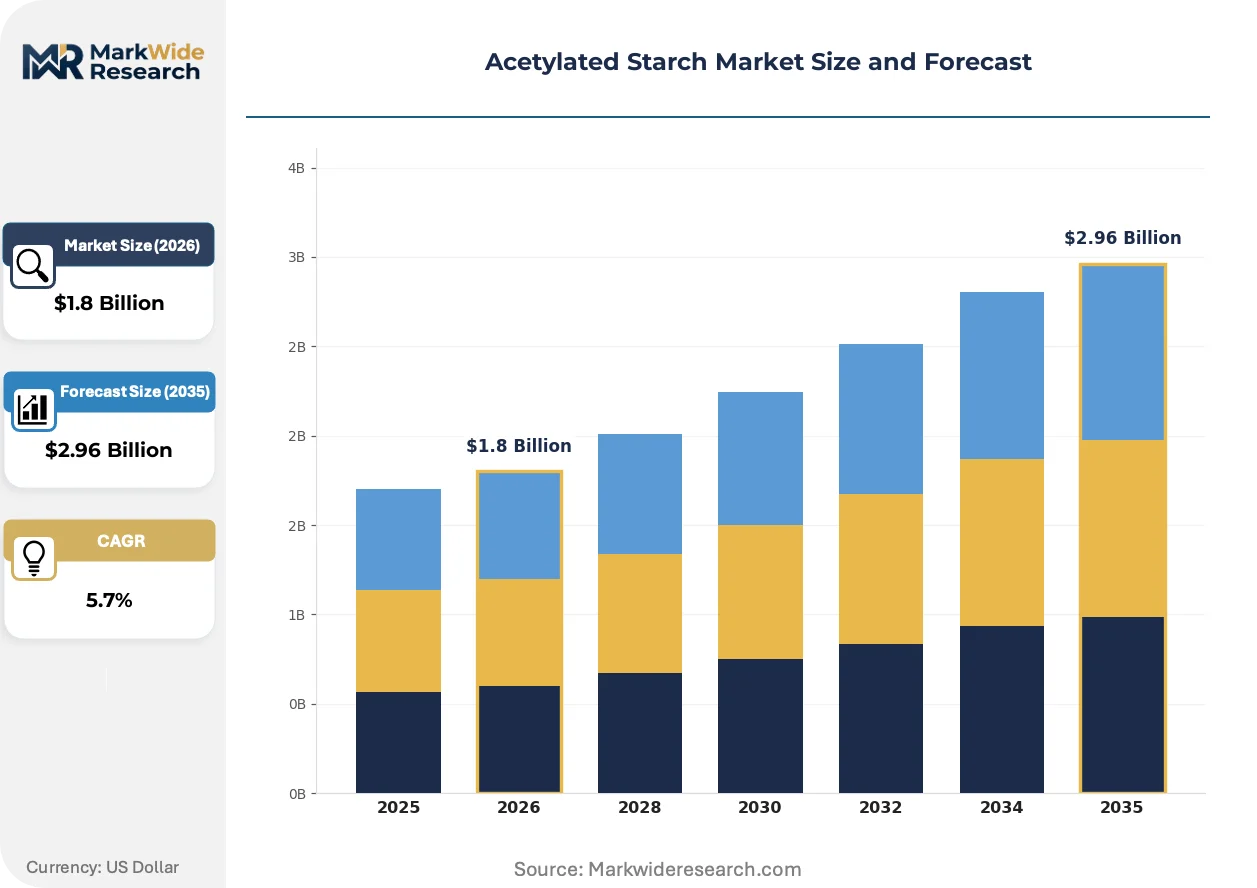
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Pharmaceutical Grade, Animal Feed Grade Application: Food Products, Coatings, Adhesives, Pharmaceuticals Form: Powder, Granules, Flakes, Tablets End User: Food Industry, Pharmaceutical Industry, Packaging Industry, Textile Industry |
| Companies Covered | Cargill, Incorporated, Ingredion Incorporated, Roquette Frères, Tate & Lyle PLC, Archer Daniels Midland (ADM), Avebe Group, Asia Fructose Co., Ltd., Banpong Tapioca Flour Industrial Co Ltd, Visco Starch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetylated Starch Market Strategic Shifts
Process analytical technology deployment is compressing batch-to-batch variability while enabling real-time degree-of-substitution control that was previously achievable only through offline laboratory verification.
Inline near-infrared spectroscopy is digitizing acetylation reaction monitoring. Food-grade manufacturers in Germany and the Netherlands are adopting these systems at pilot scale. Real-time substitution measurement is digitizing quality assurance workflows and reducing out-of-specification rework volumes.
EFSA re-evaluation of modified starch acceptable daily intakes is tightening purity thresholds for European market access. Industrial-grade processors face reformulation pressure to demonstrate toxicological dossier completeness. Adhesive and coating applications in Italy and Spain are accelerating supplier audits to preempt compliance gaps.
Direct procurement from biorefinery operators is displacing traditional distributor channels for large-volume food processors. Multinational packaged food manufacturers in China and India are negotiating long-term offtake agreements with acetylated starch producers. This channel compression is most visible in regional food processing clusters around Shanghai and Mumbai.
Acetylated Starch Market Segmentation
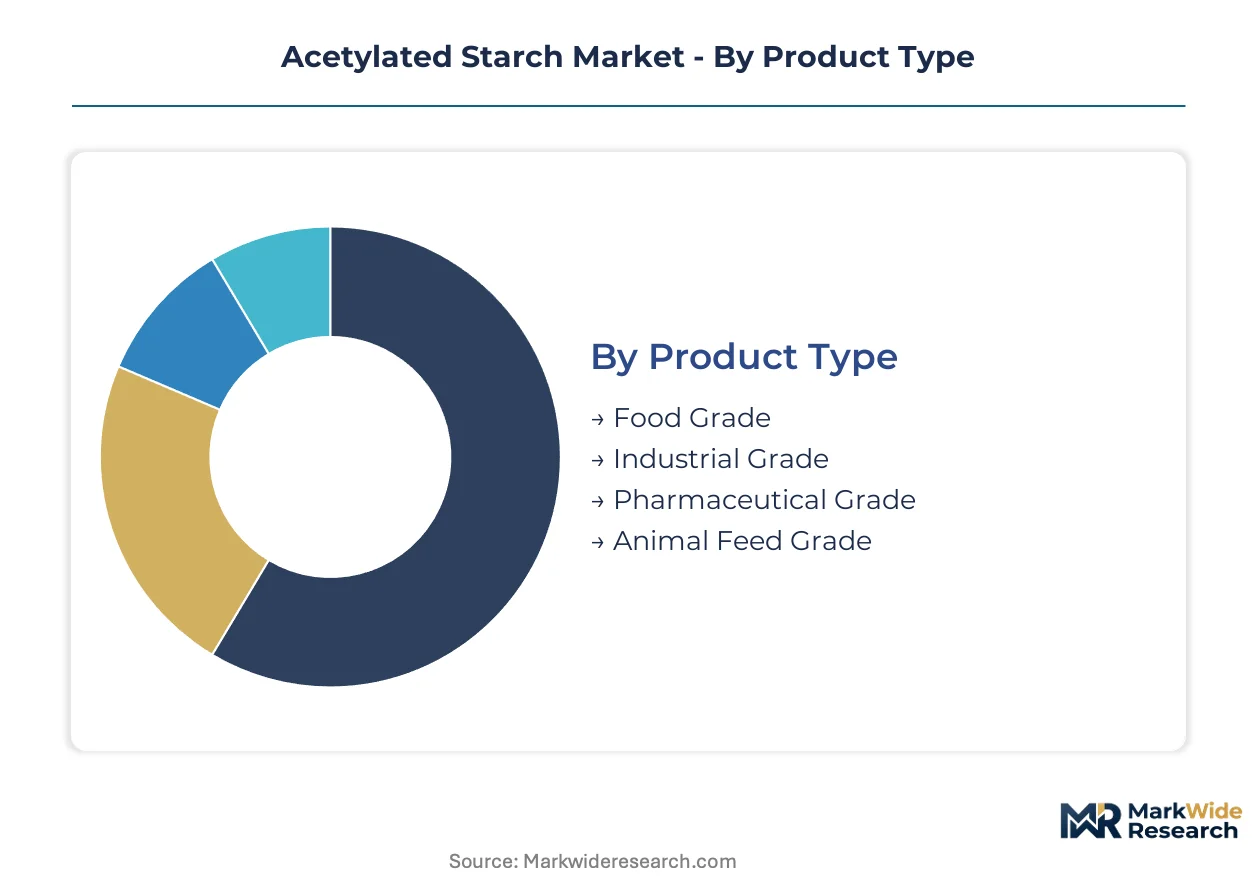
Segmentation in acetylated starch determines specification rigor, regulatory pathway, and margin architecture. Product grade purity thresholds separate food additive compliance from pharmaceutical excipient certification. Form factor and end-use concentration dictate reactor configuration and distribution economics.
Product Type:
After-sales technical service intensity escalates sharply from industrial to pharmaceutical grades, with USP and EP compliance documentation requiring dedicated regulatory support teams.
- Food Grade:Acetylated starch esters achieving degree of substitution between 0.01 and 0.2 confer freeze-thaw stability and reduced retrogradation for sauce and frozen dessert applications. FDA 21 CFR 172.892 compliance is mandatory for US market access, with clean-label reformulation in Thailand and India driving volume expansion as gelatin and carrageenan replacements.
- Pharmaceutical Grade:Stringent USP and EP compliance requirements for excipient applications command premium positioning in tablet binder and controlled-release matrix formulations. CDSCO in India and NMPA in China enforce parallel purity dossiers that extend approval timelines but protect margin structures for certified suppliers.
- Industrial Grade:Adhesive and coating applications face margin compression from petrochemical substitute competition.
- Animal Feed Grade:Lower substitution thresholds serve binder applications in pelletized feed formulations.
By volume, Food Grade leads. By growth pace, Pharmaceutical Grade is expanding most quickly.
Application:
Cost tier stratification separates commodity adhesive volumes from premium pharmaceutical and food system specifications.
- Food Products:Clean-label reformulation mandates across packaged food manufacturing compress synthetic additive demand. Sauce, frozen dessert, and ready meal processors in China and India specify acetylated starch for texture stability and freeze-thaw performance.
- Pharmaceuticals:Tablet binder and controlled-release matrix applications require USP and EP compliance investments that open premium positioning for certified manufacturers.
- Coatings:Industrial surface treatments leverage acetylated starch film-forming properties.
- Adhesives:Petrochemical substitute competition constrains margin recovery in industrial bonding applications.
Food Products commands the largest volume share. Pharmaceuticals shows the steepest expansion trajectory.
Form:
Customer handling requirements and dissolution kinetics determine powder versus granule specification splits across end-use segments.
- Powder:Standard milling achieves rapid hydration for sauce and pharmaceutical binder applications.
- Granules:Controlled particle size distribution reduces dusting and improves flow properties for high-speed tableting operations.
- Flakes:Intermediate dissolution profiles serve specialty coating formulations.
- Tablets:Pre-compressed excipient grades streamline direct-compression pharmaceutical manufacturing.
Powder dominates current shipment volumes. Granules are gaining share fastest in pharmaceutical contract manufacturing.
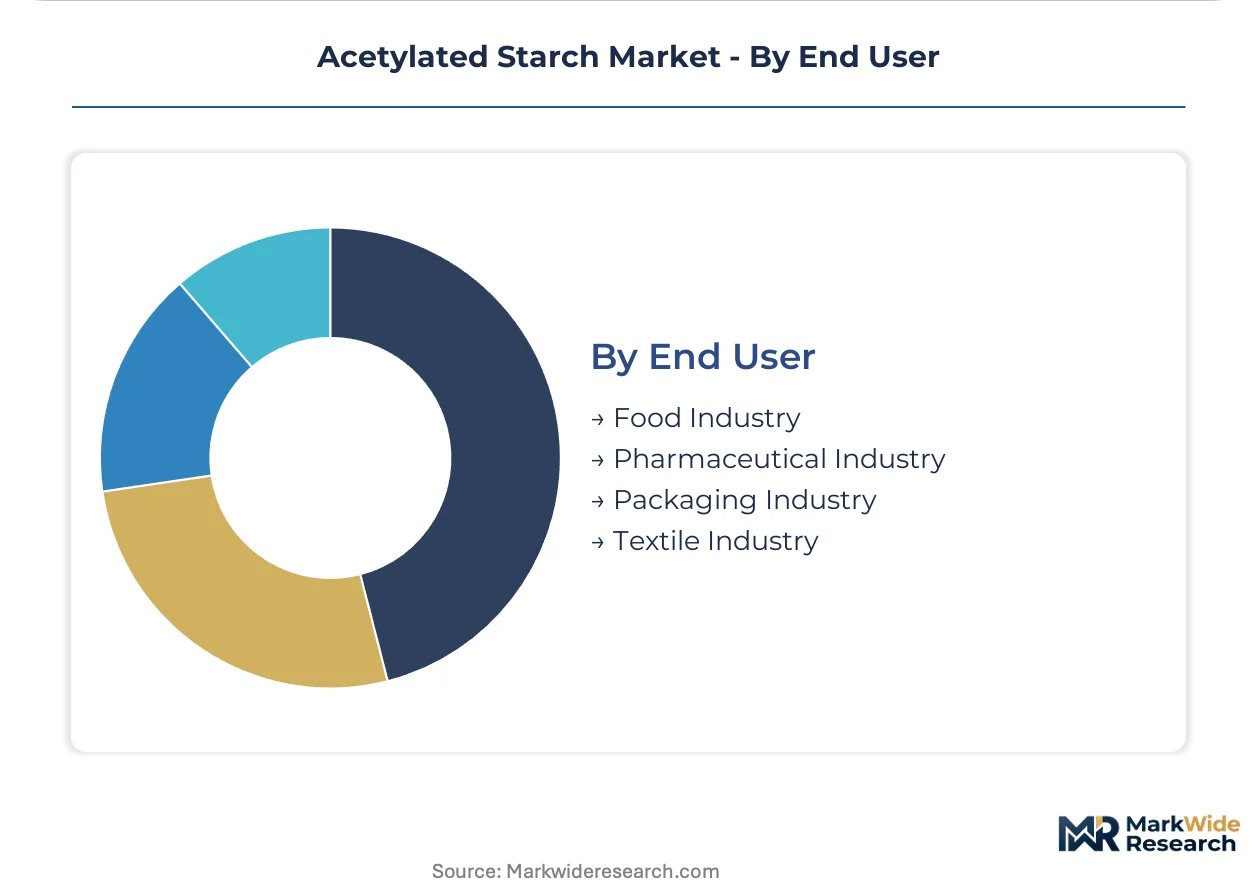
End User:
Supply concentration varies sharply across end-user segments, with food and pharmaceutical industries consolidating procurement toward integrated biorefinery operators.
- Food Industry:Clean-label reformulation mandates drive modified starch specification volumes in regional processing clusters around Shanghai and Mumbai. Direct procurement from biorefinery operators is displacing traditional distributor channels for large-volume processors.
- Pharmaceutical Industry:USP and EP compliance requirements concentrate procurement toward certified excipient manufacturers with established toxicological dossiers. CDSCO and NMPA parallel approvals extend supplier qualification timelines.
- Packaging Industry:Biodegradable film and coating applications leverage acetylated starch film-forming properties.
- Textile Industry:Sizing and finishing applications compete with petrochemical alternatives on cost-performance ratios.
Food Industry leads by volume. Pharmaceutical Industry climbs the fastest on compliance-driven premium grade demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in acetylated starch track divergent regulatory stringency and feedstock availability. Net importers in Southeast Asia source from corn-belt processors in North America while European traders arbitrage REACH-certified volumes across Mediterranean food manufacturing clusters.
United States
FDA 21 CFR 172.892 compliance thresholds shape formulation specifications for sauce and frozen dessert manufacturers. Corn belt processors in Iowa and Illinois leverage captive starch supply to dominate food-grade export volumes. Midwest biorefinery clusters around Des Moines and Cedar Rapids integrate acetylation units with ethanol production to compress logistics costs.
China
Food processors in Yangtze River Delta cities specify acetylated starch for clean-label reformulation of ready meals and dessert applications. SAMR GB standards for modified starch labeling constrain import flexibility while tightening domestic producer compliance timelines. Regional clusters around Shanghai negotiate direct procurement contracts with biorefinery operators, bypassing traditional distribution channels.
Germany
EFSA re-evaluation of modified starch acceptable daily intakes elevates purity documentation requirements for industrial adhesive applications. ECHA REACH enforcement concentrates procurement toward certified suppliers with complete toxicological dossiers. Process analytical technology deployment in North Rhine-Westphalia chemical parks enables real-time degree-of-substitution control for pharmaceutical-grade output.
India
Frozen dessert processors in Maharashtra and Gujarat substitute acetylated starch for gelatin in clean-label ice cream formulations. CDSCO parallel approval requirements for pharmaceutical excipient grades extend supplier qualification timelines but protect margin structures for certified manufacturers. Mumbai food processing clusters scale modified starch procurement as packaged sauce volumes expand.
Thailand
Cassava starch processors leverage regional tapioca supply to diversify feedstock bases beyond corn and potato origins. FSSAI-aligned import specifications from Indian buyers create arbitrage opportunities for Bangkok-based traders. Industrial zones around Rayong and Map Ta Phut host specialty starch modification facilities serving ASEAN food manufacturers.
Acetylated Starch Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in feedstock and modification technology. Three integrated processors control approximately two-thirds of North American food-grade volume, creating procurement bottlenecks for mid-sized buyers. Strategic archetypes span captive corn supply operators, pea and potato starch specialists, and pharmaceutical-grade certification holders. Competitive moves concentrate on biorefinery co-location investments and continuous reactor upgrades to meet tightening purity thresholds.
Among North American integrated processors, Cargill, Incorporated anchors the corn supply chain archetype through Midwest feedstock control. European specialists Roquette Frères and Ingredion Incorporated exemplify diversification strategies across pea, potato, and formulation partnership channels. These three occupy positions that represent the dominant competitive vectors: upstream feedstock capture, specialty crop diversification, and downstream customer integration.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Ingredion Incorporated |
| Roquette Frères |
| Tate & Lyle PLC |
| Archer Daniels Midland (ADM) |
| Avebe Group |
| Asia Fructose Co., Ltd. |
| Banpong Tapioca Flour Industrial Co Ltd |
| Visco Starch |
| Others |
Value Chain & Pricing Dynamics
Midwest biorefinery clusters around Des Moines and Cedar Rapids concentrate North American food-grade acetylated starch capacity, granting integrated processors leverage over contract pricing for mid-sized sauce and frozen dessert manufacturers. This geographic concentration amplifies margin capture when acetic anhydride feedstock costs swing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stabilize input cost exposure against petrochemical volatility. Pricing stratifies across pharmaceutical, food, and industrial grade tiers, with USP and EP certification commanding substantial premiums over commodity adhesive specifications. Cost compression in industrial-grade segments intensifies as petrochemical substitutes erode technical differentiation. Food processors in regional clusters around Shanghai and Mumbai exhibit highest price sensitivity due to direct procurement channel compression, while pharmaceutical excipient buyers accept premium positioning for compliance documentation security.
Supply Chain Analysis
Extended payment terms from integrated biorefinery operators are displacing traditional distributor financing for large-volume food processors in Asia-Pacific markets. Manufacturing concentration centers on the United States, Germany, and Thailand, with each hub leveraging distinct feedstock advantages: corn in Iowa and Illinois, pea and potato starches in European pulse processing zones, and cassava derivatives in Southeast Asian tapioca belts. Raw material sourcing draws from acetic anhydride petrochemical streams, native starch agricultural bases, and specialty pea protein co-location facilities. Single-source vulnerability runs through Midwest corn belt processor dominance, where three integrated operators control majority North American food-grade volume. Distribution runs through direct biorefinery offtake agreements that bypass traditional channel intermediaries for multinational packaged food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetylated starch markets are approaching a platform-economics inflection as direct procurement portals and real-time degree-of-substitution monitoring digitize buyer-supplier matching, collapsing traditional distributor margins and reconfiguring value capture toward integrated manufacturers with embedded analytics capabilities.
For Market Incumbents: Insulate food-grade margin structures by deepening captive corn supply control through Midwest biorefinery capacity additions, while preemptively investing in continuous acetylation reactor upgrades to meet tightening FDA 21 CFR 172.892 and EFSA purity thresholds before mid-tier competitors can access capital. Cross-functional regulatory expertise scarcity represents a defensive moat; build dedicated teams conversant in REACH dossier preparation, SAMR GB alignment, and USP compliance documentation to extend supplier qualification timelines for challengers. For New Entrants and Emerging Players: Pharmaceutical excipient grade production in India and China represents the most penetrable entry point, where CDSCO and NMPA parallel approval requirements extend incumbent certification timelines and protect margin structures for qualified entrants. Pea starch feedstock diversification in European pulse processing zones offers white-space positioning beyond corn and potato commodity competition. A go-to-market angle anchored in biorefinery co-location partnerships—integrating acetylation units with ethanol or protein extraction operations—achieves energy and logistics cost advantages that offset scale disadvantages against integrated giants. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded acetylated starch assets lacking pharmaceutical-grade certification infrastructure or direct procurement channel relationships with multinational food processors. Long-term viability favors operators with backward integration into specialty feedstocks and embedded process analytical technology capabilities. The signal to watch as inflection indicator is EFSA re-evaluation timing for modified starch acceptable daily intakes, which will accelerate consolidation toward dossier-complete suppliers and strand non-compliant industrial-grade capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Biorefinery Co-location Investment | Integrated ethanol-protein-acetylation facilities in Iowa and Illinois compress logistics costs and energy inputs. |
| Pharmaceutical Grade Certification | USP and EP compliance investments open premium tablet binder and controlled-release matrix positioning. |
| Process Analytical Technology Deployment | Inline near-infrared spectroscopy in German and Dutch plants enables real-time substitution control. |
| Direct Procurement Channel Development | Long-term offtake agreements with Shanghai and Mumbai food processors displace traditional distribution. |
| Pea Starch Feedstock Diversification | European pulse processing capacity expansion reduces corn and potato input cost volatility exposure. |
Study Parameters
The analysis maps food-grade, pharmaceutical-grade, industrial-grade, and animal feed-grade acetylated starch production, each validated through plant managers at biorefinery operations, procurement leads at multinational sauce and frozen dessert manufacturers, distribution channel partners in Asia-Pacific markets, and technical R&D directors at specialty starch modification facilities. Primary interview findings triangulate against secondary sources including FDA 21 CFR filings, ECHA REACH registration databases, SAMR GB standard documentation, customs and trade flow data, and SEC filings from publicly traded ingredient suppliers. Bottom-up capacity and utilization estimates reconcile with top-down demand modeling across end-use applications.
Assumptions held fixed include prevailing regulatory frameworks across FDA, ECHA, and SAMR jurisdictions, while feedstock cost trajectories and clean-label reformulation adoption rates varied across sensitivity scenarios. The analytical framework segments by product grade purity tier, end-use industry concentration, form factor handling requirements, and regional production hub regulatory cluster. CAGRs derive from installed capacity expansion schedules, substitution elasticity estimates for gelatin and carrageenan replacement, and pharmaceutical excipient demand growth tied to controlled-release formulation trends. Model inputs incorporate acetic anhydride petrochemical feedstock pricing correlations, degree-of-substitution specification spreads, and biorefinery integration economics.
Practitioners should monitor EFSA re-evaluation announcements, SAMR enforcement intensity against domestic Chinese producers, and Midwest corn belt processor capacity utilization rates for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Sweet Almond Oil Market
Ingredients
Macleaya Cordata Extract Market
Ingredients
Custom Dry Ingredients Blends Market
Ingredients
Agarwood Oil Market
Ingredients
Avocado Oil Market
Ingredients
Lentils Flour Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Europe Amino Acid Market
Ingredients
Hops Market
Ingredients
Chickpea Flour Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
US Plant-Based Oils Market
Ingredients
Flaxseed Derivatives Market