
 Rose Extract Market | 2026-2036
Rose Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Rose Extract Market Outlook
Multi-source procurement for Rosa damascena absolute is pivoting toward vertically integrated suppliers with captive Bulgarian and Turkish fields. Firmenich SA leverages backward integration into Grasse-region extraction facilities to secure fragrance-grade consistency. Symrise AG anchors its competitive position through R&D intensity in solvent-free supercritical CO2 processes. Givaudan SA differentiates via geographic dominance in Moroccan Rosa centifolia sourcing channels.
Rose extract comprises volatile and non-volatile fractions obtained from Rosa damascena or Rosa centifolia through steam distillation, solvent extraction, or hydrodistillation, yielding essential oil, absolute, or hydrosol with typical citronellol and geraniol concentrations exceeding 30 percent combined; the material serves primarily as a functional fragrance component, antimicrobial agent, and skin-conditioning active in cosmetic and therapeutic formulations. Essential oil and absolute segments lead value generation due to high input ratios of fresh flowers to finished extract, while hydrosol gains volume traction in clean-label skincare as a lower-concentration alternative. Powder forms occupy niche positions in dietary supplement encapsulation where standardization and shelf stability outweigh aromatic fidelity.
REACH registration requirements in Europe govern synthetic solvent residues and allergen labeling for fragrance applications, while FDA oversight in the United States classifies rose oil as generally recognized as safe for food use yet imposes strict purity thresholds for pharmaceutical-grade claims. BIS standards in India and GB standards in China set additional benchmarks for import acceptance of botanical extracts. Stakeholders must monitor evolving allergen disclosure mandates and carbon-accounting rules that could requalify established supply origins.
Market Dynamics
REACH compliance deadlines and EU Green Deal carbon-accounting mandates are forcing suppliers to requalify Bulgarian and Turkish field operations, consolidating procurement around vertically integrated producers with captive cultivation and documented solvent-free extraction.
Growth Catalysts
- Clean-label cosmetic formulation:Premium skincare brands in Western Europe specify certified organic Rosa damascena absolute to replace synthetic fragrance allergens, tightening supplier qualification protocols.
- REACH registration acceleration:ECHA disclosure requirements for synthetic solvent residues in fragrance applications favor producers with verified supercritical CO2 extraction capabilities.
- Hydrosol volume expansion:Lower-concentration rose water gains shelf space in mass-market skincare as a cost-accessible entry point for natural-positioned brands.
Market Restraints
- Input cost volatility:Fresh flower-to-extract ratios exceeding 3,000 kilograms per kilogram of absolute expose margins to weather-driven harvest fluctuations in Bulgaria's Kazanlak Valley.
- Supply concentration risk:Bulk Rosa damascena distillation capacity clusters in southern Bulgaria and Isparta Province, Turkey, creating single-origin vulnerability for fragrance-grade material.
- Substitution pressure:Synthetic citronellol-geraniol blends from petrochemical feedstocks undercut natural absolute pricing in mass-market soap and detergent applications.
Strategic Opportunities
- Underpenetrated Moroccan Rosa centifolia:The Dades Valley cultivation zone offers expansion headroom for solvent-extraction capacity serving Middle Eastern fragrance houses.
- Pharmaceutical-grade standardization:FDA-monographed rose oil for food and therapeutic use commands purity premiums over cosmetic-grade material.
- Carbon-labeled sourcing:EU Green Deal scope-3 disclosure requirements create first-mover advantage for suppliers with field-to-bottle emissions tracking.
Industry Challenges
- Skilled distiller scarcity:Traditional hydrodistillation expertise in Bulgarian cooperatives faces generational attrition as younger workers migrate to urban manufacturing.
- Multi-jurisdiction certification lag:Simultaneous pursuit of USDA Organic, ECOCERT, and BIS compliance extends product launch timelines by 12-18 months for Indian market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rose Extract Market |
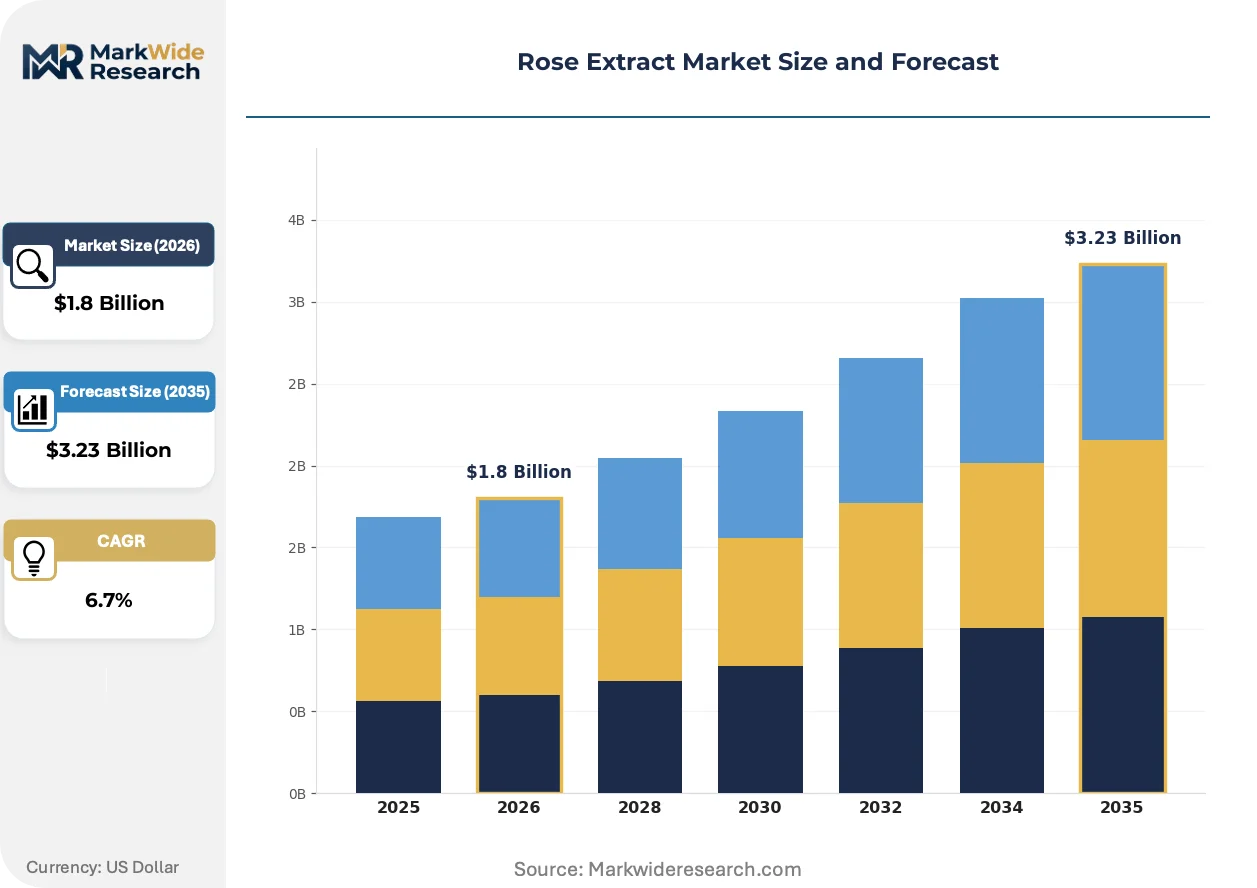
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute, Essential Oil, Powder, Hydrosol End User: Cosmetics, Pharmaceuticals, Food & Beverage, Aromatherapy Form: Liquid, Solid, Viscous, Crystalline Application: Skincare, Fragrance, Dietary Supplements, Natural Remedies |
| Companies Covered | Firmenich SA, Symrise AG, International Flavors & Fragrances Inc., Givaudan SA, Robertet Group, Takasago International Corporation, Alteya Organics, Mane SA, Synthite Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rose Extract Market Strategic Shifts
Extraction technology and regulatory disclosure frameworks are compressing the supplier base while opening premium tiers for traceable, low-residue material with documented carbon footprints.
Supercritical CO2 extraction is absorbing market share from traditional solvent-based absolute production in high-value fragrance applications. Givaudan SA and Firmenich SA have retrofitted Grasse-region facilities for solvent-free processing. This technology is absorbing the premium tier of the market by eliminating hexane residue concerns that complicate REACH registration.
ECHA's 2024 update to REACH Annex XVII allergen labeling requirements is mandating individual citronellol and geraniol disclosure above 0.001 percent in leave-on cosmetics. Fragrance compounders are reformulating to stay below disclosure thresholds or switching to certified low-allergen rose extracts. Small-batch Bulgarian producers with chromatographic certification are capturing reformulation contracts from Paris-based prestige houses.
Direct-to-brand procurement contracts are displacing traditional broker-mediated spot purchasing for certified organic material. Moroccan Rosa centifolia buyers in the Gulf States now contract directly with Dades Valley cooperatives, bypassing Marseille trading houses. This pattern is most visible in Saudi Arabia and UAE markets where MOHAP import documentation favors single-origin traceability over blended certificates.
Rose Extract Market Segmentation
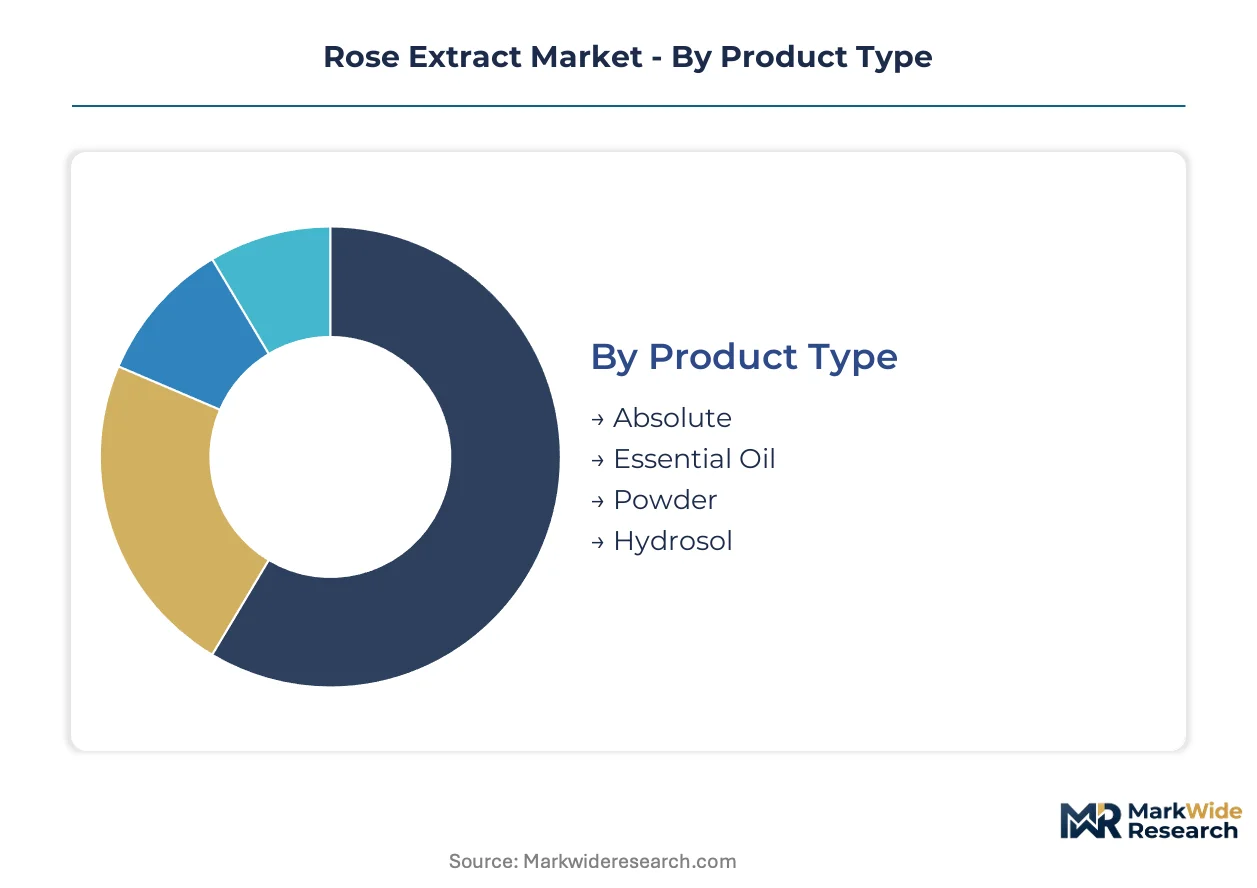
Rose extract procurement patterns shift decisively when buyers upgrade from commodity-grade hydrosol to certified organic absolute, resetting supplier qualification protocols and margin structures. Each segmentation dimension captures distinct trade-offs between aromatic fidelity, regulatory compliance, and formulation flexibility that determine competitive positioning across end-use verticals.
Product Type:
Buyers cycle through product grades as clean-label requirements intensify, with premium brands abandoning solvent-extracted absolute only when supercritical CO2 alternatives achieve comparable citronellol-geraniol profiles.
- Absolute:Solvent-extracted concentrate containing 30-40 percent combined citronellol and geraniol, prized for fragrance persistence. Western European prestige houses specify certified organic Bulgarian material to meet REACH Annex XVII disclosure thresholds. Input ratios exceeding 3,000 kilograms of fresh Rosa damascena flowers per kilogram of finished absolute constrain supply elasticity and amplify weather-driven price volatility.
- Essential Oil:Steam-distilled volatile fraction with terpene-rich aromatic character serving therapeutic and premium fragrance applications. Moroccan Rosa centifolia oil commands distinct geographic premiums in Middle Eastern markets where single-origin traceability satisfies MOHAP import documentation requirements. Traditional hydrodistillation in Bulgaria's Kazanlak Valley faces skilled labor attrition that threatens batch-to-batch consistency.
- Powder:Spray-dried or encapsulated form standardized for shelf stability in dietary supplement manufacturing.
- Hydrosol:Aqueous co-product of distillation, lower in aromatic concentration but gaining mass-market skincare volume as an accessible natural-positioning entry point.
Essential oil sits at the top of the volume ranking, with hydrosol climbing the fastest as clean-label accessibility expands addressable demand.
End User:
Margin structures diverge sharply across end-use verticals, with pharmaceutical-grade claims requiring FDA-monographed purity thresholds that cosmetic formulators rarely pursue.
- Cosmetics:Dominant value contributor specifying certified organic absolute and hydrosol for skin-conditioning and fragrance functions. ECHA's updated allergen labeling mandates are forcing reformulation cycles among Paris-based prestige houses, favoring suppliers with chromatographic certification of individual citronellol and geraniol levels.
- Pharmaceuticals:Highest purity tier governed by FDA oversight for therapeutic and food-use claims, commanding substantial premiums over cosmetic-grade material. Standardization protocols and documentation requirements extend procurement timelines and consolidate supplier relationships around qualified producers with captive Bulgarian or Turkish cultivation.
- Food & Beverage:Flavoring applications leveraging GRAS status of rose oil in confectionery and beverage formulations.
- Aromatherapy:Wellness-positioned consumption requiring batch-specific chromatographic profiles for practitioner credibility.
Cosmetics generates the dominant revenue share, though pharmaceuticals maintains the steepest expansion trajectory as therapeutic standardization protocols mature.
Form:
Physical state determines compatibility with formulation infrastructure, with liquid forms dominating fragrance compounding while solid and powder variants serve encapsulation and tableting operations.
- Liquid:Essential oil and absolute in fluid state, the default for fragrance compounding and cosmetic formulation requiring homogeneous dispersion.
- Solid:Concreted or wax-based preparations for controlled-release applications.
- Viscous:Semi-fluid absolute at ambient temperature, requiring heated handling equipment in manufacturing settings.
- Crystalline:Isolated constituent forms for pharmaceutical standardization and research applications.
Liquid forms dominate current procurement volumes, with powder gaining share fastest as dietary supplement encapsulation scales.
Application:
Application-level demand concentrates where regulatory disclosure requirements intersect with consumer willingness to pay for natural-positioned efficacy claims.
- Skincare:Hydrosol and absolute deployment for antimicrobial and skin-conditioning functions, with Western European clean-label brands specifying certified organic Rosa damascena to replace synthetic fragrance allergens.
- Fragrance:Absolute and essential oil serving fine fragrance, personal care, and home scent applications. Supercritical CO2 extraction is absorbing premium-tier volume by eliminating hexane residue concerns that complicate REACH registration.
- Dietary Supplements:Powder and encapsulated oil forms for antioxidant and wellness-positioned products.
- Natural Remedies:Traditional therapeutic applications in Middle Eastern and South Asian markets.
Fragrance commands the largest value share, while skincare demonstrates the most rapid volume expansion as mass-market clean-label adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bulgaria's Kazanlak Valley anchors the global Rosa damascena supply base, with Turkey's Isparta Province and Morocco's Dades Valley forming secondary concentration zones. Procurement patterns now favor suppliers with documented carbon footprints and captive field operations.
Bulgaria
Prestige fragrance houses in Paris and Grasse source certified organic absolute from Kazanlak Valley cooperatives. ECHA's REACH Annex XVII allergen disclosure mandates favor Bulgarian producers with chromatographic certification of citronellol and geraniol levels. Traditional hydrodistillation expertise faces generational attrition as younger workers migrate to Sofia's manufacturing sector.
Turkey
Isparta Province distillation capacity serves both European fragrance compounders and Middle Eastern traditional medicine markets. The country's national agricultural ministry supports organic conversion programs for rose cultivation zones. Vertically integrated suppliers with captive Isparta fields capture reformulation contracts from clean-label skincare brands.
Morocco
Dades Valley Rosa centifolia cultivation supplies solvent-extraction capacity for Gulf State fragrance houses. MOHAP import documentation in the UAE and Saudi Arabia favors single-origin traceability over blended certificates. Direct-to-brand procurement contracts now bypass traditional Marseille trading houses.
France
Grasse-region extraction facilities retrofitted for supercritical CO2 processing serve premium fragrance applications. ANSM cosmetic safety regulations align with ECHA disclosure thresholds for leave-on products. Firmenich SA leverages backward integration into Grasse production to secure fragrance-grade consistency.
United States
FDA-monographed rose oil for food and therapeutic use commands purity premiums over cosmetic-grade material. Dietary supplement manufacturers in Utah and California drive powder-form demand for encapsulation. GRAS status enables flavoring applications in confectionery and beverage formulations.
Rose Extract Market Competitive Environment
Global majors compete with regional champions across extraction technology and captive cultivation access. The supplier base compresses around vertically integrated producers with documented solvent-free processing and field-to-bottle emissions tracking. Three archetypes dominate: Swiss and French fragrance houses with Grasse-region retrofit capacity, Bulgarian and Turkish field-integrated specialists, and Indian extract standardizers serving pharmaceutical-grade demand. Consolidation pressures favor M&A activity targeting captive Bulgarian and Turkish cultivation assets.
Within the premium fragrance tier, Firmenich SA and Givaudan SA exemplify scale-driven positioning through backward integration into extraction facilities. Symrise AG anchors the technology-specialist archetype with R&D intensity in solvent-free supercritical CO2 processes. These Swiss and French entities represent the consolidated end of a market that also includes regional Bulgarian cooperatives and Indian standardizers like Synthite Industries Ltd.
| Leading Market Players |
|---|
| Firmenich SA |
| Symrise AG |
| International Flavors & Fragrances Inc. |
| Givaudan SA |
| Robertet Group |
| Takasago International Corporation |
| Alteya Organics |
| Mane SA |
| Synthite Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII allergen disclosure mandates from ECHA are compelling Paris-based prestige houses to specify certified organic Bulgarian absolute with chromatographic certification, forcing supply consolidation around vertically integrated producers and amplifying price premiums for documented low-residue material.
Pricing Analysis
Input-cost pass-through from fresh Rosa damascena harvests dominates pricing structures. Three-tier pricing stratifies across certified organic absolute, conventional solvent-extracted grades, and hydrosol alternatives. Price differentiation hinges on citronellol-geraniol certification precision and supercritical CO2 processing capability. Pricing pressure intensifies upward as weather-driven harvest shortfalls in Bulgaria's Kazanlak Valley constrain supply elasticity. Mass-market soap and detergent manufacturers exhibit highest price sensitivity, while fragrance compounders for prestige skincare demonstrate lowest sensitivity to absolute premiums.
Supply Chain Analysis
Rosa damascena absolute supply rests on fresh flower inputs from Bulgaria, Turkey, and Morocco. Distillation capacity draws from copper alembic networks in Kazanlak Valley, Isparta Province, and Dades Valley cooperatives. Hexane solvent availability and supercritical CO2 equipment feedstock constrain extraction throughput. Single-origin vulnerability clusters in southern Bulgarian field operations exposed to climatic volatility. Distribution runs through direct-to-brand procurement contracts displacing Marseille trading houses for Gulf State buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rose extract market reads as a late-cycle quality story as Western European clean-label brands abandon synthetic fragrance allergens for certified organic Rosa damascena absolute with documented carbon footprints.
For Market Incumbents: Cement fragrance-grade consistency through backward integration into Grasse-region extraction facilities retrofitted for solvent-free processing. Secure captive Bulgarian and Turkish field operations before skilled distiller attrition accelerates. Lock in multi-year direct procurement contracts with Paris-based prestige houses facing ECHA-mandated reformulation cycles. For New Entrants and Emerging Players: Begin with underpenetrated Moroccan Rosa centifolia solvent-extraction capacity serving Middle Eastern fragrance houses in Saudi Arabia and UAE markets. Target Dades Valley cooperatives bypassed by direct-to-brand procurement trends. Lead with single-origin traceability documentation satisfying MOHAP import requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap specialists with captive Bulgarian cultivation and chromatographic certification capabilities. Five-to-ten year viability favors suppliers with field-to-bottle emissions tracking aligned with EU Green Deal scope-3 disclosure requirements. Watch for ECHA regulatory tightening on synthetic solvent residues as inflection signal for supercritical CO2 retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Retrofit Investment | Eliminates hexane residue concerns complicating REACH registration for fragrance-grade absolute. |
| Captive Cultivation Acquisition | Secures Kazanlak Valley or Isparta Province field operations against weather-driven supply volatility. |
| Chromatographic Certification Program | Enables citronellol-geraniol disclosure precision for ECHA Annex XVII compliance. |
| Carbon-Labeling Infrastructure | Documents field-to-bottle emissions for EU Green Deal scope-3 procurement requirements. |
| Direct-to-Brand Contracting | Bypasses Marseille trading houses to capture margin from Gulf State fragrance house demand. |
Study Parameters
Multiple input streams — primary interviews with extraction facility operators, fragrance house procurement directors, and Bulgarian cooperative distillation specialists; secondary validation through ECHA regulatory filings, customs trade data, and ECOCERT certification databases; plus bottom-up and top-down triangulation — were reconciled to construct market estimates.
Data-stream reconciliation across product type, end-use vertical, extraction technology, and geographic sourcing cluster dimensions shaped the analytical framework. CAGRs were derived from modeled volume and value progression throughout the forecast period. Forecast inputs incorporated fresh flower-to-extract yield ratios, REACH compliance cost pass-through assumptions, and hydrosol volume expansion trajectories in mass-market skincare.
Several conditions sit outside the modeled scope, including synthetic citronellol-geraniol blend substitution rates in commodity detergent applications and generational attrition timelines for traditional hydrodistillation expertise. Forecasts reflect documented assumptions subject to revision from ECHA regulatory updates, EU Green Deal carbon-accounting enforcement intensity, and climatic disruption patterns in Bulgaria's Kazanlak Valley. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Middle East and Africa Dairy Ingredients Market
Ingredients
European Brewing Enzymes Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Barley Malt Extract Market
Ingredients
Europe Phytosterols Market
Ingredients
Fish Peptones Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Fig Ingredient Market
Ingredients
Bay Leaf Oil Market
Ingredients
China Cane Sugar Market
Ingredients
Global Infant Nutrition Ingredients Market
Ingredients
North America Milk Protein Market
Ingredients
United States Protein Market
Ingredients
India Gelatin Market
Ingredients
Rennet Market