
 Potato Flour Market | 2026-2036
Potato Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Potato Flour Market Analytics
Clean-label dehydration technology is fragmenting the traditional potato processing stack, enabling smaller batch sizes and gentler heat profiles that preserve native starch functionality. Royal Avebe U.A. leverages its cooperative farmer network to secure raw potato supply across the Netherlands and Germany. Emsland Group anchors Central European production capacity with integrated starch modification capabilities. Roquette Frères differentiates through pharmaceutical-grade potato starch certifications that command premium positioning in excipient markets.
Potato flour consists of dried, ground potato tubers, typically containing 6-8% moisture and 70-80% native starch by dry weight, produced through drum drying or flash dehydration for use as a thickening agent, binder, or wheat flour substitute in formulated foods. Modified potato starch carries the highest margin pool among product type segments due to its tailored viscosity and freeze-thaw stability in industrial sauce applications. Gluten-free products represent the fastest-growing application segment as celiac-safe formulations displace traditional wheat-based alternatives in retail baking mixes and ready meals.
FDA gluten-free labeling standards and EU REACH chemical registration requirements shape ingredient compliance costs for North American and European manufacturers seeking cross-border market access. EFSA novel food assessments and USDA organic certification protocols further stratify supplier qualification tiers. Stakeholders must monitor evolving clean-label definitions and carbon footprint disclosure rules as procurement criteria harden across institutional foodservice and packaged goods channels.
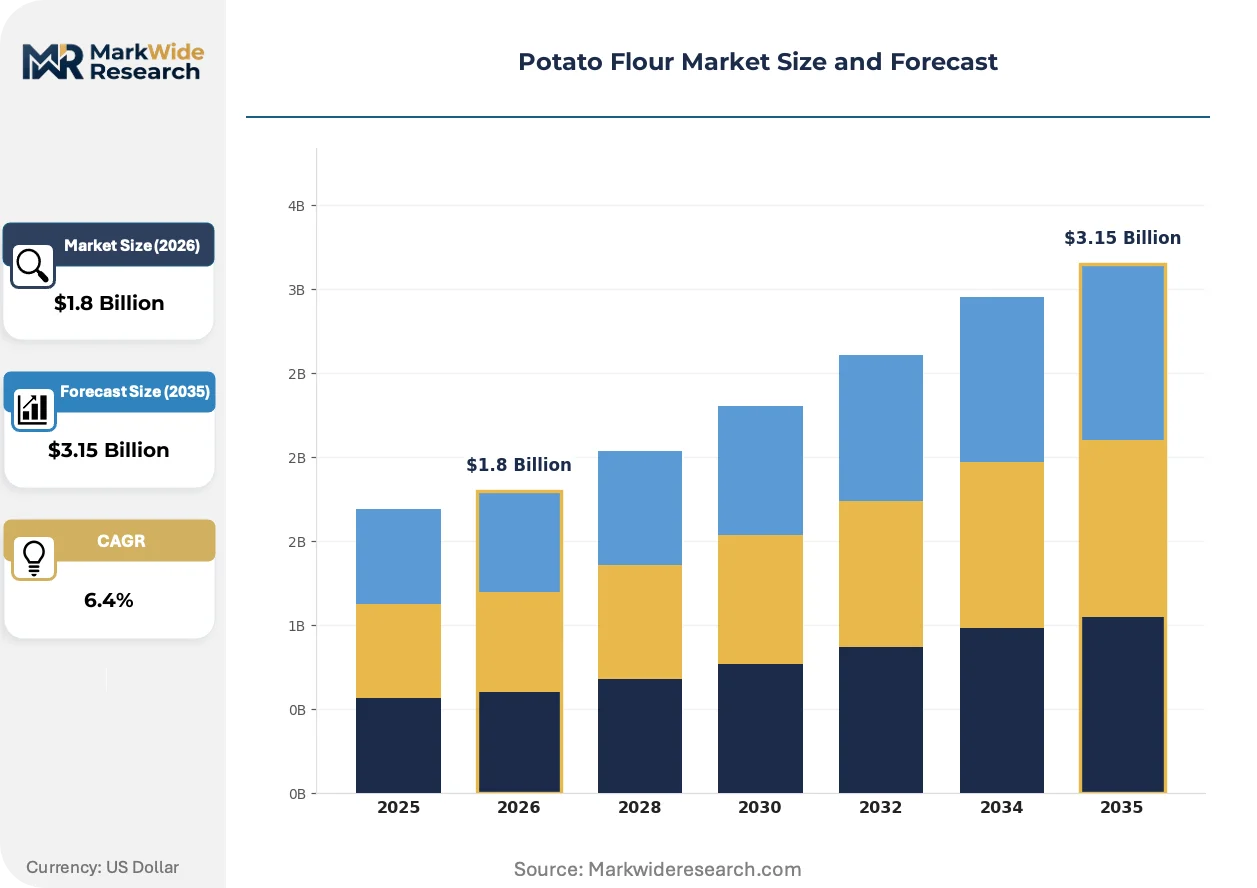
Market Dynamics
Clean-label dehydration technology is fragmenting the traditional potato processing stack, enabling smaller batch sizes and gentler heat profiles that preserve native starch functionality. This structural shift is redistributing competitive advantage from commodity-scale processors toward flexible manufacturing networks capable of serving reformulation demands in gluten-free and clean-label channels.
Growth Catalysts
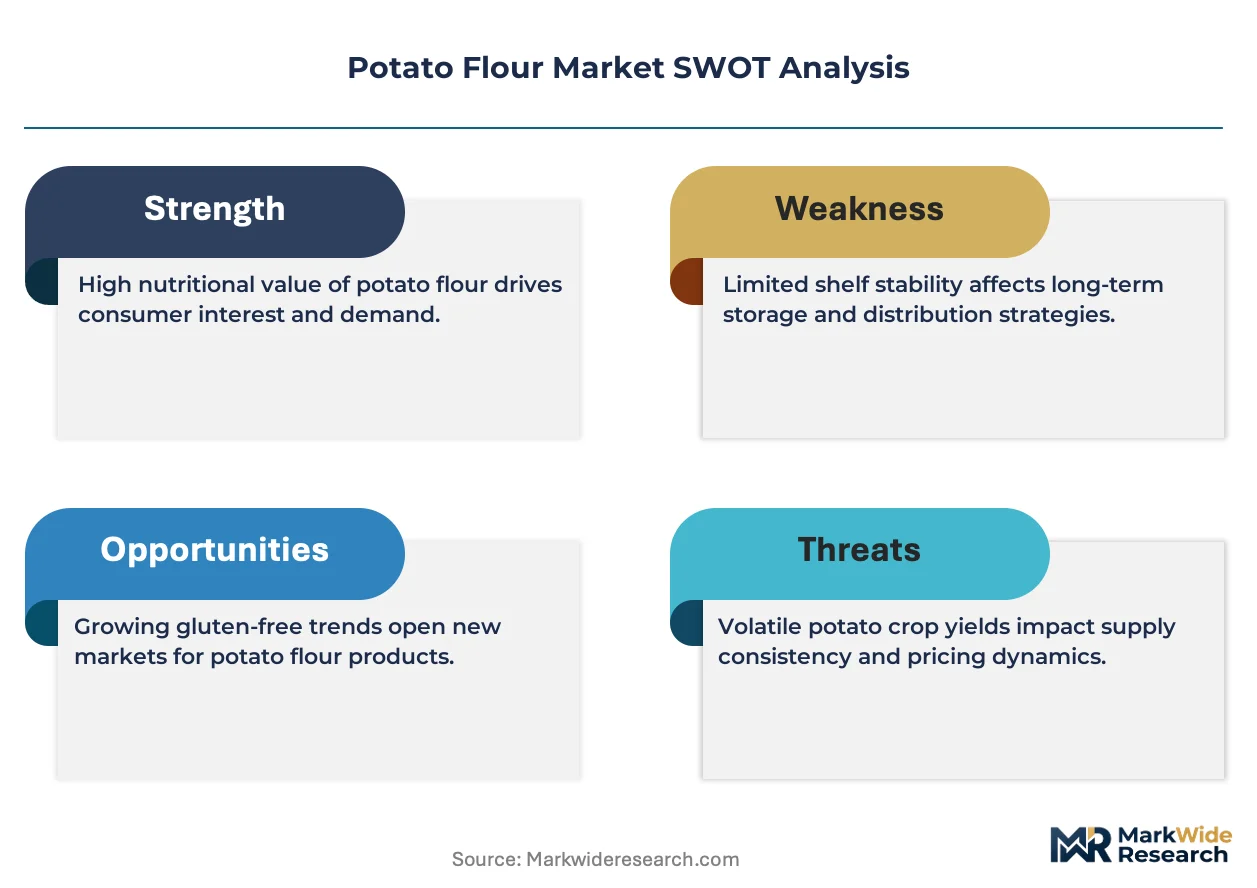
- EU Green Deal traceability mandates:Sustainable sourcing requirements are tightening standards for imported starch commodities, favoring processors with verified supply chain documentation and cooperative farmer networks.
- Celiac-safe formulation demand:Gluten-free retail baking mixes and ready meals are displacing wheat-based alternatives, pulling potato-derived thickeners and binders into mainstream packaged goods.
- Drum drying efficiency gains:Heat recovery systems and continuous belt designs are reducing energy intensity per kilogram of dehydrated output, improving unit economics for mid-scale producers.
Market Restraints
- Raw potato input volatility:Weather-driven yield fluctuations in the Netherlands and Germany concentrate supply risk for processors dependent on specific starch potato cultivars.
- Modified starch technical ceiling:Freeze-thaw stability in industrial sauce applications requires chemical cross-linking that conflicts with clean-label positioning, creating formulation trade-offs.
- Tapioca and rice flour substitution:Alternative gluten-free starches compete on price and neutral flavor profiles, pressuring potato flour margin pools in cost-sensitive applications.
Strategic Opportunities
- Pharmaceutical excipient certification:USP-NF and EP compliance for potato starch creates premium positioning in tablet disintegrant and capsule filler markets with higher barriers to entry.
- Flash dehydration technology convergence:Integration of infrared pre-drying with pneumatic conveying is enabling gentler moisture removal that preserves amylose crystallinity for specialty applications.
- Organic channel expansion:USDA organic certification protocols and EU organic regulation are opening differentiated positioning in natural foods retail with limited qualified supplier pools.
Industry Challenges
- Food safety certification timelines:FSSC 22000 and BRCGS audits require 12-18 month implementation cycles that delay market entry for new processing facilities.
- Starch modification IP complexity:Proprietary cross-linking and esterification chemistries create licensing friction for processors seeking to match incumbent performance specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potato Flour Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Potato Flour, Dehydrated Potato Granules, Instant Potato Flour, Modified Potato Starch Application: Baking, Snack Foods, Sauces & Gravies, Gluten-Free Products End User: Food Manufacturers, Cuisines, Retail, HoReCa Packaging Type: Bags, Boxes, Bulk, Sachets |
| Companies Covered | Royal Avebe U.A., Emsland Group, King Arthur Baking Company, Keystone Potato Products, Idaho Pacific Holdings, Bob’s Red Mill Natural Foods, Roquette Frères, Ingredion Incorporated, AGRANA Beteiligungs-AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potato Flour Market Evolving Landscape
Processing technology is virtualizing quality control and batch customization, compressing the traditional gap between commodity production and specialty ingredient manufacturing. These shifts are enabling new competitive positioning across dehydration, modification, and distribution layers.
Advanced drum drying systems equipped with real-time moisture sensors and automated gap adjustment are virtualizing the traditional art of operator-dependent dehydration. Gluten-free contract manufacturers in Germany and the Netherlands are adopting these systems to reduce batch-to-batch variability. The technology is virtualizing quality assurance labor while enabling lot-specific customization previously reserved for pilot-scale operations.
EFSA novel food assessments and evolving EU REACH chemical registration requirements are extending compliance timelines for new starch modifications. Industrial sauce manufacturers face reformulation delays as modified potato starch suppliers await safety opinion publication. The regulatory friction is concentrating procurement among incumbents with established dossiers, disadvantaging innovative entrants.
Buyer consolidation among European retail private-label programs is compressing supplier qualification cycles and favoring multi-site processors with redundant capacity. Foodservice distributors are unbundling technical service from ingredient supply, forcing potato flour vendors to demonstrate standalone formulation support capabilities. This procurement evolution is most visible in German and French retail channels where centralized buying desks now mandate pan-European supply security.
Potato Flour Market Segmentation
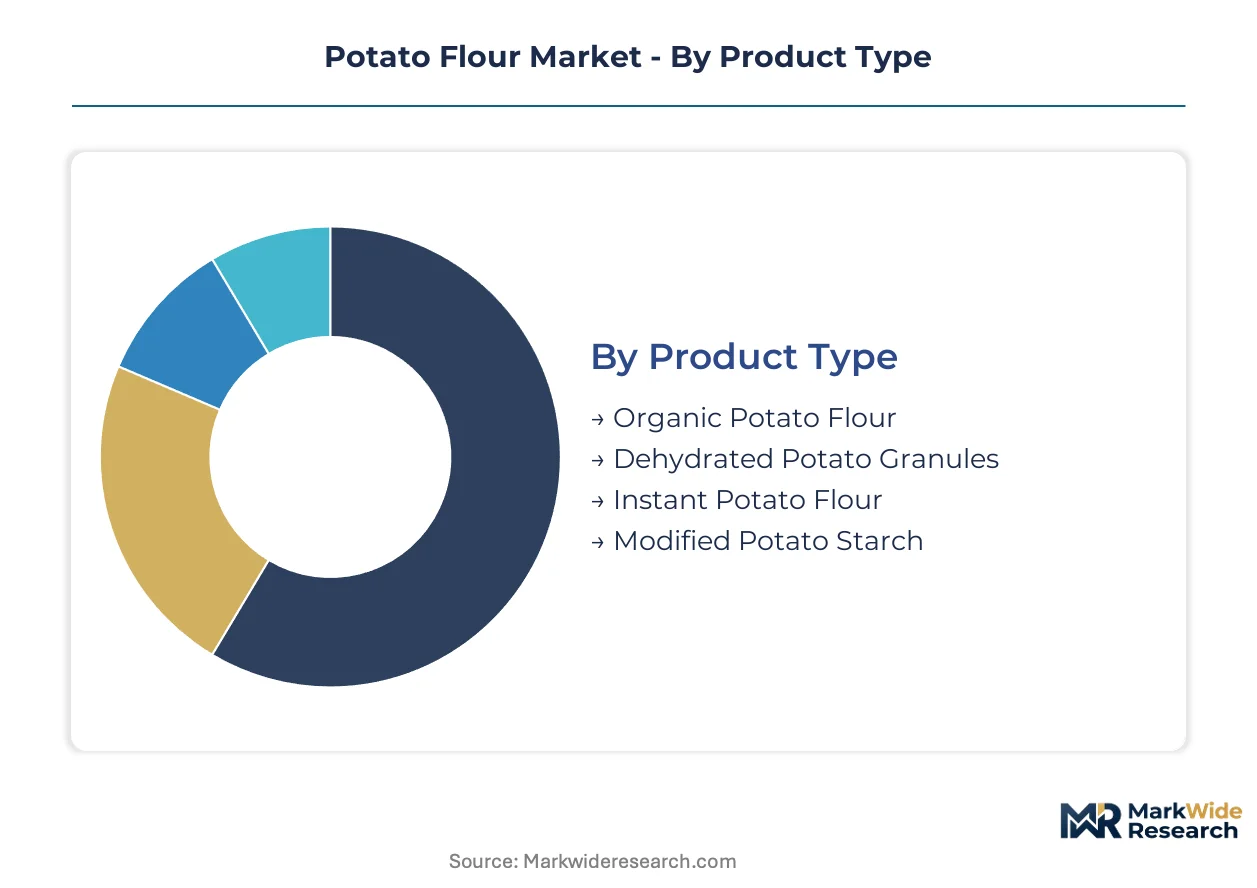
Potato flour segmentation reflects divergent value capture across processing intensity and certification tiers. Supply chain configuration varies sharply between commodity dehydrated products and pharmaceutical-grade modified starches with audited traceability.
Product Type:
Cost tier stratification separates minimally processed commodity grades from chemically modified specialty starches with premium positioning.
- Modified Potato Starch:Chemically cross-linked or esterified to achieve tailored viscosity, freeze-thaw stability, and acid resistance for industrial sauce applications. Demand concentrates in German and French ready-meal manufacturing where Emsland Group and Roquette Frères hold established dossiers under EU REACH registration requirements. Clean-label conflicts with chemical modification create formulation trade-offs that limit penetration in natural foods channels.
- Organic Potato Flour:Certified under USDA organic protocols and EU organic regulation, requiring starch potato cultivation without synthetic pesticides and processing without prohibited additives. Procurement is tightening among Netherlands-based gluten-free specialists seeking verified supply chain documentation for North American export compliance.
- Dehydrated Potato Granules:Agglomerated particles produced through drum drying with intermediate granulation, offering faster rehydration than standard flour for mashed potato applications and instant soup bases.
- Instant Potato Flour:Pre-gelatinized through flash dehydration to enable cold-water swelling, serving convenience-focused foodservice operations and shelf-stable bakery fillings.
Modified Potato Starch holds installed capacity. Organic Potato Flour is rotating up the share rankings.
Application:
End-use concentration tracks reformulation waves in celiac-safe packaged goods and clean-label retail channels.
- Gluten-Free Products:Celiac-safe baking mixes, pasta, and bread formulations displacing wheat-based alternatives in Germany, France, and US retail channels. FDA gluten-free labeling standards and EU implementing regulations for gluten-free claims create dual compliance burdens that favor suppliers with established certification protocols.
- Sauces & Gravies:Industrial manufacturers of ready meals and foodservice concentrates specifying native or modified potato starch for viscosity control and sheen. Freeze-thaw stability requirements in frozen sauce applications pull toward modified starches despite clean-label trade-offs.
- Baking:Partial wheat flour substitution in artisan and commercial bread formulations seeking moisture retention and extended shelf life without gluten network disruption.
- Snack Foods:Extruded and sheeted applications including potato-based crisps and fabricated snacks where native starch functionality supports texture development.
Gluten-Free Products command the steepest expansion trajectory. Sauces & Gravies retains volume concentration.
End User:
Customer type determines specification stringency, with food manufacturers imposing technical audits that exclude smaller processors.
- Food Manufacturers:Branded packaged goods companies and private-label suppliers operating centralized procurement with pan-European supply security mandates. FSSC 22000 and BRCGS certification requirements create 12-18 month qualification timelines that concentrate sourcing among incumbent processors.
- HoReCa:Hotel, restaurant, and catering distributors unbundling technical service from ingredient supply, forcing standalone formulation support demonstrations from potato flour vendors.
- Retail:Supermarket private-label programs and natural foods channels specifying organic or clean-label grades with carbon footprint disclosure requirements under EU Green Deal procurement criteria.
- Cuisines:Ethnic and specialty food producers in concentrated urban markets seeking authentic texture profiles for regional applications.
Food Manufacturers hold installed capacity. HoReCa is rotating up the share rankings.
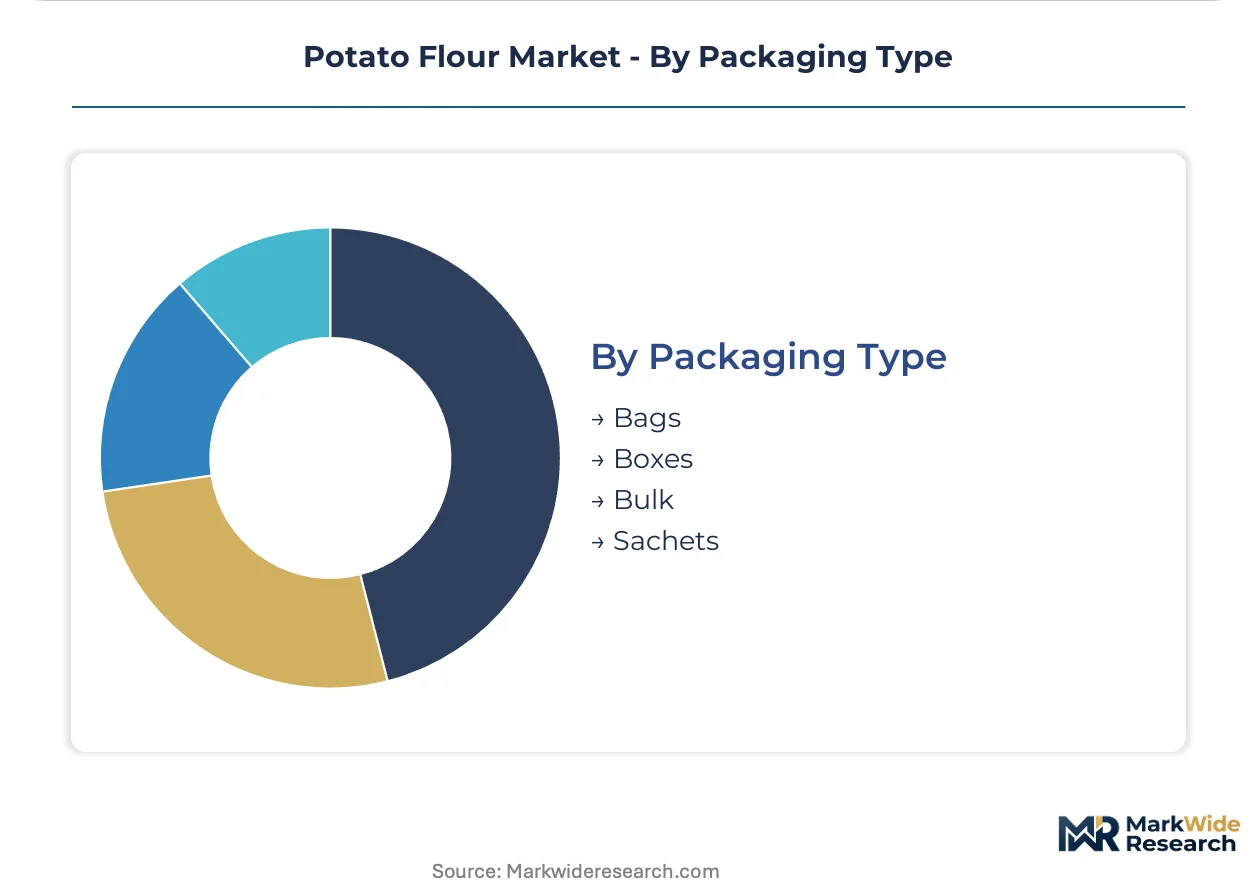
Packaging Type:
Volume tier and handling economics segment procurement between bulk industrial supply and unitized retail formats.
- Bulk:Tanker and silo delivery to large-scale food manufacturers with integrated pneumatic conveying systems, minimizing unit packaging cost but requiring dedicated handling infrastructure.
- Bags:Multi-wall paper or woven polypropylene sacks serving mid-scale processors and distributor repackaging operations with palletized logistics.
- Boxes:Corrugated cases with inner liners for retail-ready distribution and foodservice portion control applications.
- Sachets:Single-serve foil or laminate pouches for instant product formats and sampling programs in consumer channels.
Bulk holds installed capacity. Bags is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands-based cooperatives export dehydrated potato derivatives to German and French food manufacturers under EU Green Deal traceability protocols. German processing clusters absorb the majority of Central European starch potato output for modified starch applications.
Germany
Ready-meal manufacturers in Lower Saxony and North Rhine-Westphalia specify modified potato starch for freeze-thaw stability in frozen sauce applications. EU REACH registration requirements for chemically modified starches extend compliance timelines for new entrants. Emsland Group operates integrated processing facilities in Emlichheim serving pan-European industrial sauce producers.
Netherlands
Gluten-free specialists in the Randstad region procure organic-certified potato flour for North American export compliance. EFSA novel food assessments govern the approval timeline for new starch modifications entering EU food channels. Royal Avebe U.A. leverages its cooperative farmer network across Friesland and Groningen to secure raw potato supply.
France
Industrial sauce manufacturers in the Hauts-de-France region demand acid-resistant modified starches for retort-stable formulations. EU implementing regulations for gluten-free claims create dual compliance burdens with FDA standards for exporters. Roquette Frères maintains pharmaceutical-grade certification facilities in Lestrem supplying excipient markets.
United States
FDA gluten-free labeling standards drive reformulation in retail baking mixes across the Midwest and Northeast corridors. USDA organic certification protocols stratify supplier qualification tiers for natural foods channels. Idaho Pacific Holdings processes starch potatoes in the Snake River Plain for domestic gluten-free product manufacturers.
Canada
Health Canada and PMRA regulate pesticide residue limits in imported starch potato cultivars entering Ontario and Quebec food manufacturing. Clean-label dehydration technology adoption concentrates in Toronto-area contract manufacturers serving US private-label programs. Keystone Potato Products supplies dehydrated granules to North American foodservice distributors.
Potato Flour Market Competitive Landscape
On the supply side, the industry is consolidating around processors with integrated modification capabilities and certified traceability documentation. Cooperative structures dominate raw material procurement in Northwestern Europe. Three archetypes define competitive positioning: commodity-scale dehydrators, specialty modified starch producers, and organic-certified niche suppliers. Capacity expansion and pharmaceutical-grade certification represent the dominant competitive moves.
Within the cooperative processor tier, Royal Avebe U.A. and Emsland Group exemplify supply-side consolidation through farmer-owned structures. Among specialty chemical modifiers, Roquette Frères occupies a position representing the premium certification vector for excipient markets. These three entities anchor the competitive structure across dehydration, modification, and pharmaceutical-grade segments.
| Leading Market Players |
|---|
| Royal Avebe U.A. |
| Emsland Group |
| King Arthur Baking Company |
| Keystone Potato Products |
| Idaho Pacific Holdings |
| Bob's Red Mill Natural Foods |
| Roquette Frères |
| Ingredion Incorporated |
| AGRANA Beteiligungs-AG |
| Others |
Value Network & Pricing Analysis
Rhine-Alpine corridor freight costs shape margin allocation across the potato flour value chain, compressing delivered-price spreads between Dutch cooperative processors and German industrial buyers while amplifying price differentiation between commodity dehydrators and certified organic suppliers.
Pricing Analysis
Drum-drying technology generations create pricing stratification across the market, with legacy steam-heated systems anchoring economy-tier commodity flour and infrared-integrated flash dehydration commanding premium positioning for native starch preservation. Certification tiers separate organic-certified supply from conventional grades, while pharmaceutical-grade modified starches with USP-NF compliance capture the highest price positioning. Cost compression in standard dehydrated flour intensifies as tapioca and rice flour alternatives gain formulation share in cost-sensitive gluten-free applications. Private-label retail programs exhibit greatest price sensitivity, whereas pharmaceutical excipient buyers prioritize supply security over unit cost.
Supply Chain Analysis
Extended payment terms from German ready-meal manufacturers and supply-chain finance facilities from Dutch cooperative banks lubricate working capital across the starch potato belt. Raw material supply concentrates in the Netherlands, Germany, and France, where starch potato cultivation regions feed integrated processing clusters. Processor output draws from specific cultivar dependencies, including high-amylose varieties for modified starch applications and waxy types for instant flour production. Single-source vulnerability concentrates in the Emsland-Emlichheim processing corridor, where weather-driven yield fluctuations transmit directly to industrial sauce manufacturer procurement. Distribution runs through pan-European food ingredient distributors with regional silo networks and direct bulk delivery to large-scale manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label dehydration technology disruption accelerates competitive restructuring, with EU Green Deal traceability mandates creating qualification barriers that favor processors with cooperative farmer networks and verified carbon footprint documentation.
For Market Incumbents: Harden supply security through backward integration into starch potato cultivation in Friesland and Groningen, securing cultivar-specific volumes against weather-driven yield volatility. Expand pharmaceutical-grade certification capacity at existing modification facilities to defend margin pools against commodity-grade price erosion from alternative gluten-free starches.
For New Entrants and Emerging Players: Organic-certified potato flour for North American gluten-free export represents the most penetrable entry point, given limited qualified supplier pools and USDA organic protocol compliance requirements. Flash dehydration technology convergence with infrared pre-drying offers a technical differentiation angle for specialty native starch applications serving clean-label reformulation demand.
For Investors and Strategic Acquirers: Mid-scale processors with established FSSC 22000 certification and flexible batch capabilities present acquisition targets positioned to capture share from rigid commodity-scale operators. Monitor EFSA novel food assessment publication timelines as an inflection signal for modified starch supplier consolidation, as regulatory friction concentrates procurement among incumbents with established dossiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | USP-NF and EP compliance opens tablet disintegrant markets with premium positioning and limited qualified competition. |
| Cooperative Farmer Network Expansion | EU Green Deal traceability requirements favor processors with verified supply chain documentation across Netherlands and Germany. |
| Flash Dehydration Technology Adoption | Infrared pre-drying integration preserves amylose crystallinity for specialty applications demanding native starch functionality. |
| Organic Certification Protocol Compliance | USDA organic and EU organic regulation alignment enables differentiated positioning in natural foods retail channels. |
| Pan-European Supply Security Infrastructure | Multi-site processing capacity satisfies German and French retail private-label procurement mandates for redundant supply. |
Research Methodology
The analysis maps modified starch, organic flour, dehydrated granules, and instant flour segments, each validated through procurement directors at industrial sauce manufacturers, gluten-free product formulators, pharmaceutical excipient buyers, and cooperative processing executives. Primary interviews combined with secondary validation from EFSA novel food assessment databases, EU REACH registration filings, USDA organic certification records, and customs trade data for starch potato derivatives. Bottom-up capacity and utilization estimates triangulated against top-down consumption modeling across end-use applications.
Forecast assumptions held EU Green Deal implementation timelines and FDA gluten-free labeling standards fixed while varying clean-label adoption rates and pharmaceutical excipient demand growth across the projection horizon. Segmentation dimensions modeled include product type, application category, end-user archetype, and packaging format alongside regional production cluster dynamics. CAGRs derived from elasticity-adjusted consumption projections and capacity expansion schedules, with specific inputs for drum-drying energy efficiency gains and starch potato yield volatility patterns.
Macroeconomic conditions sit as an overlay; deviation in agricultural input costs, energy pricing, or trans-European freight rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance timelines and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Millet Protein Market
Ingredients
Sea Salt Market
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
China Gelatin Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Hydrolyzed Corn Protein Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Global Pine Pollen Powder Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Mineral Premix Market
Ingredients
Cosmetic Ingredients Market
Ingredients
Hydrogenated Starch Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
White Mulberry Leaves Extract Market