
 Lactase Enzyme Market | 2026-2036
Lactase Enzyme Market Size, Share, and Industry Trends Forecast 2026-2036
Lactase Enzyme Market Outlook
Food-grade enzyme certification is collapsing as the baseline for commercial viability, pushing suppliers toward pharmaceutical-grade purity thresholds. Novozymes leverages its precision fermentation platform to sustain cost leadership in high-activity liquid formulations. Chr. Hansen anchors the premium segment through strain-banking capabilities and dairy co-processing partnerships across Northern Europe. Kerry Group competes on application-specific blending, embedding lactase into integrated enzyme systems for cheese and yogurt manufacturers.
Lactase is a beta-galactosidase enzyme typically derived from Aspergillus oryzae or Kluyveromyces lactis, hydrolyzing lactose into glucose and galactose at optimal pH ranges of 6.0–7.0 and temperatures near 35–40°C; its primary commercial purpose is enabling lactose-free or reduced-lactose dairy products for populations with primary or secondary hypolactasia. Liquid lactase dominates industrial dairy processing due to ease of inline dosing and lower unit economics at scale, while powdered lactase captures margin pools in dietary supplements and infant formula where stability and shelf life command premium positioning. Food manufacturers represent the fastest-growing end-user channel as private-label lactose-free portfolios expand across retail dairy cases.
FDA GRAS determinations and EFSA food enzyme evaluations shape strain approval timelines and cross-border trade eligibility for suppliers serving multiple jurisdictions. ISO 22000 and FSSC 22000 certifications function as de facto market access requirements for contract manufacturing relationships with multinational dairy processors. Stakeholders must monitor evolving enzyme activity labeling standards and dual-use pharmaceutical-food regulatory boundaries as purity thresholds diverge across application segments.
Market Dynamics
Precision fermentation scale-up is compressing production costs for high-activity lactase formulations, forcing legacy extraction-based suppliers to reposition toward application-specific blends or exit commodity-grade supply entirely.
Growth Catalysts
- FDA GRAS Streamlining:The FDA's GRAS notification pathway for food enzymes is collapsing approval timelines from 24 months to under 12 months, accelerating commercialization for precision-fermented strains.
- German Dairy Clusters:Bavaria and Lower Saxony host concentrated lactose-free processing infrastructure, creating procurement pull for enzyme suppliers with inline dosing capabilities.
- Infant Formula Premiumization:Powdered lactase formulations for hypoallergenic neonatal nutrition command 3-4x unit economics versus industrial liquid grades, attracting formulation investment.
Market Restraints
- Strain Banking Concentration:Three European culture collections control access to high-yield Kluyveromyces lactis variants, creating licensing bottlenecks for new entrants.
- Input Volatility:Pharmaceutical-grade dextrose for precision fermentation feedstock fluctuates with corn ethanol policy, compressing margin predictability.
- Technical Ceiling:Thermostability above 50°C remains elusive for fungal-derived lactase, excluding the enzyme from UHT milk applications without costly process reconfiguration.
Strategic Opportunities
- Brazil Underpenetration:Lactose-free dairy represents under 5% of fluid milk sales versus 25% in Germany, creating whitespace for enzyme-treated private label expansion.
- EFSA Enzyme Re-Evaluation:The 2024-2026 food enzyme catalog consolidation is grandfathering existing approvals while raising purity thresholds, advantaging suppliers with pre-positioned pharmaceutical-grade capacity.
- Precision Fermentation Convergence:Integration of AI-driven strain optimization with continuous bioprocessing is collapsing batch-to-batch variability, enabling contract manufacturing at pharmaceutical-grade scale.
Industry Challenges
- FSSC 22000 Audit Burden:Multinational dairy processors require dual-site certification for enzyme suppliers, extending qualification timelines by 8-14 months for contract manufacturers.
- Activity Standardization Gaps:Inconsistent FCC (Food Chemicals Codex) unit labeling across US and EU pharmacopeia creates procurement friction and price opacity in cross-border trade.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactase Enzyme Market |
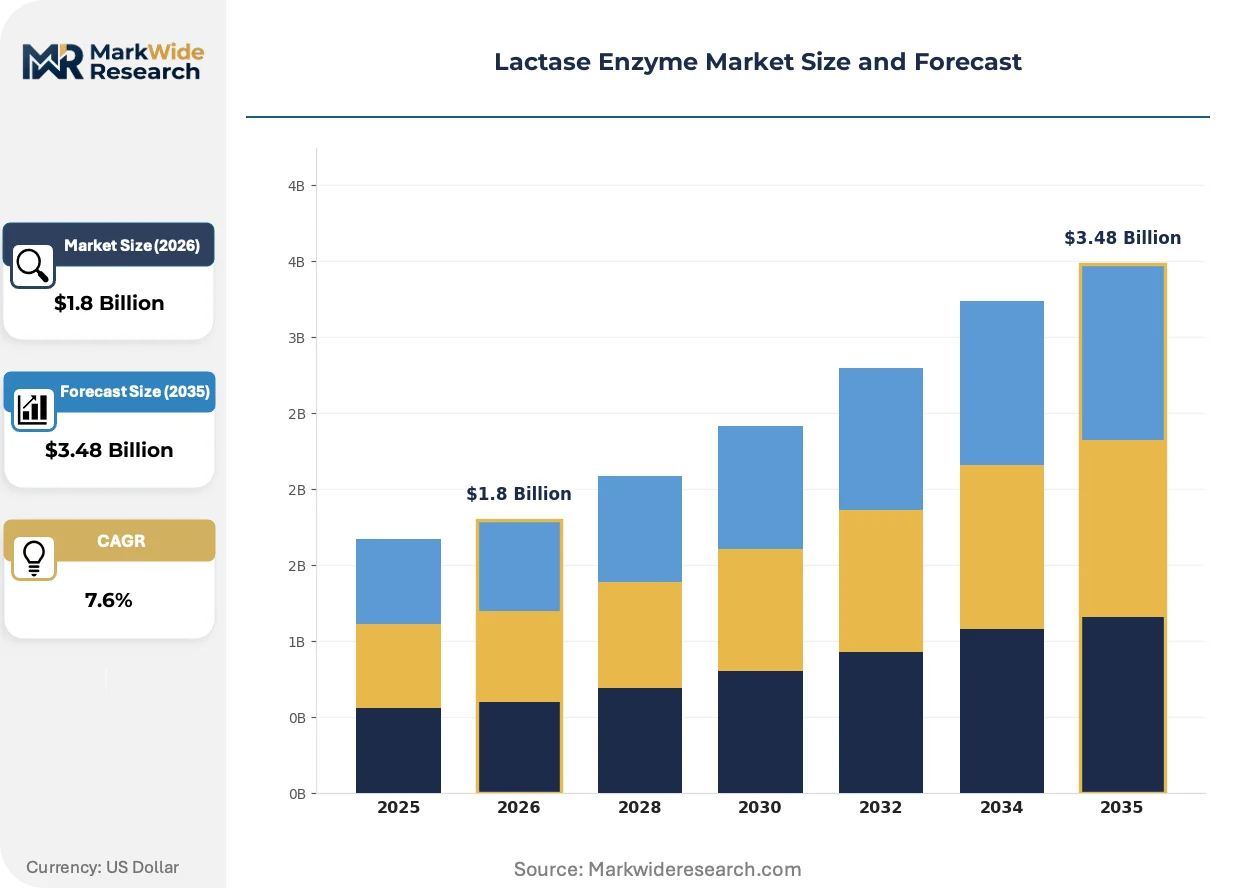
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Lactase, Powdered Lactase, Tablets, Capsules Application: Dairy Products, Dietary Supplements, Infant Formulas, Bakery Products Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Home Consumers, Food Manufacturers, Healthcare Providers, Nutraceutical Companies |
| Companies Covered | Chr. Hansen, Amano Enzyme, Novozymes, Kerry Group, Enzyme Development Corporation, DuPont/IFF, Advanced Enzymes, Merck KGaA, DSM-Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactase Enzyme Market Strategic Shifts
Bioprocess intensification and regulatory data harmonization are simultaneously compressing production economics and expanding addressable application segments for enzyme suppliers.
Continuous perfusion bioreactor technology is decomposing the batch-size constraints that historically limited precision-fermented lactase output. Mid-scale dairy processors in Denmark and the Netherlands are adopting this infrastructure to secure captive enzyme supply. The technology is decomposing the historical economies-of-scale advantage held by 50,000+ liter commodity fermenters.
EFSA's 2023-2026 food enzyme re-evaluation program is mandating toxicological dossiers for all pre-2009 approvals, forcing suppliers to resubmit safety data under contemporary standards. Industrial lactase from Aspergillus oryzae faces particular scrutiny due to allergen cross-reactivity concerns. German and Dutch suppliers are accelerating pharmaceutical-grade purification investments to preempt compliance gaps.
Buyers in the yogurt and fresh cheese segments are consolidating procurement around full-service enzyme system providers who bundle lactase with protease and lipase for texture optimization. This bundling is displacing standalone lactase tenders among mid-tier dairy cooperatives. The pattern is most pronounced in Northern Italy and Wisconsin, where private-label lactose-free yogurt portfolios are expanding fastest.
Lactase Enzyme Market Segmentation
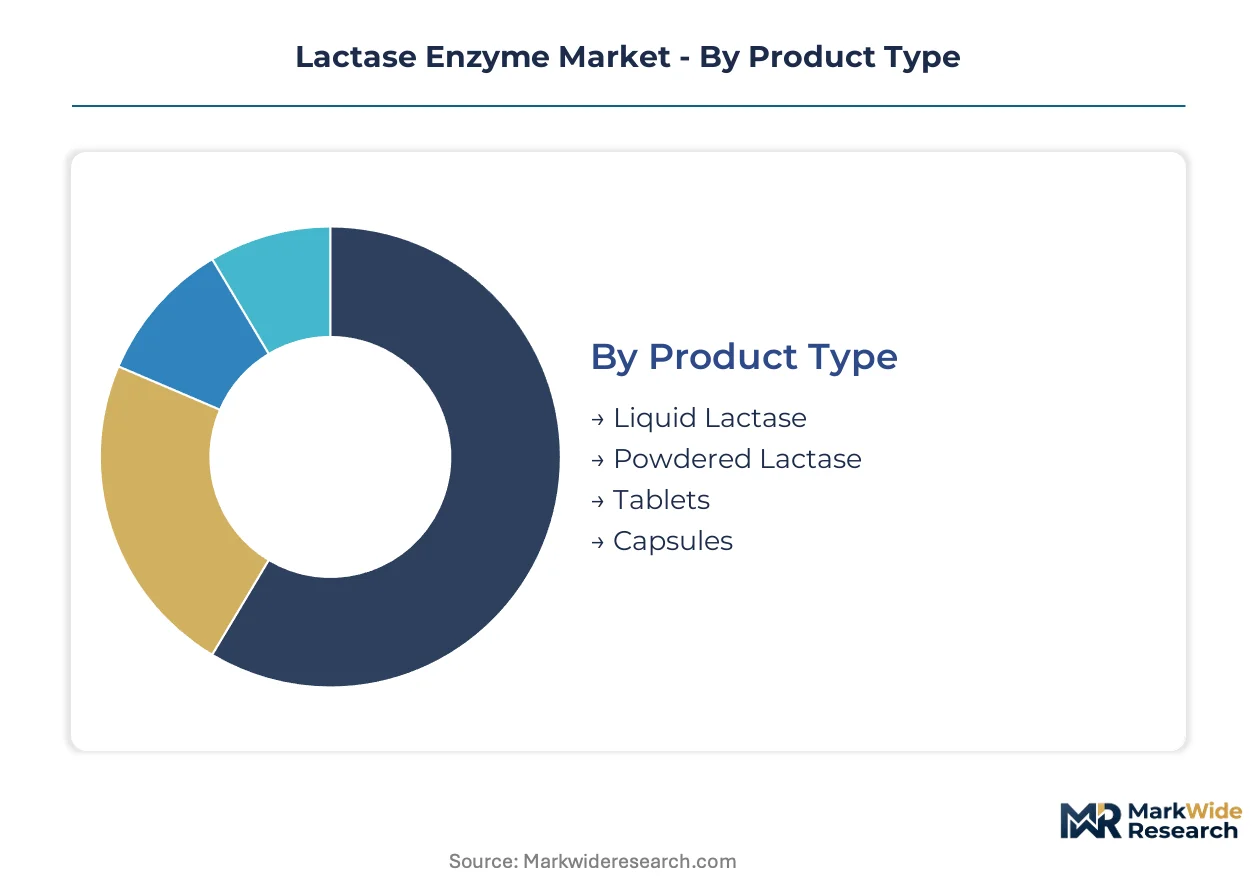
Segmentation in the lactase enzyme market reveals how formulation formats and procurement channels create divergent margin structures. Suppliers must configure production assets and certification pathways around distinct purity requirements and dosing technologies across each category.
Product Type:
Substitution pressure from synthetic enzyme alternatives and non-dairy milk products varies sharply across formulation formats, with liquid grades facing the most acute competitive threat from precision-fermented alternatives.
- Liquid Lactase:High-activity beta-galactosidase solutions optimized for inline dosing at pH 6.0–7.0 and 35–40°C processing temperatures. Dairy processors in Germany and Wisconsin concentrate procurement here for fluid milk and yogurt applications, driven by unit economics that favor continuous flow systems over batch processing.
- Powdered Lactase:Spray-dried or lyophilized formulations with extended shelf stability for dry-blend applications. Demand clusters in infant formula manufacturing, where hypoallergenic neonatal nutrition commands premium positioning and pharmaceutical-grade purity thresholds.
- Tablets:Compressed dosage forms for direct consumer use, typically standardized to FCC lactase units for digestive support claims.
- Capsules:Encapsulated enzyme powder targeting supplement channels, with gelatin and vegetarian shell variants.
Liquid lactase retains volume leadership; powdered lactase holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity-grade dairy processing from premium pharmaceutical-adjacent segments, with purity thresholds creating divergent supplier qualification requirements.
- Dairy Products:Lactose-free and reduced-lactose fluid milk, yogurt, cheese, and ice cream manufacturing. Private-label expansion across US and German retail chains drives formulation standardization.
- Infant Formulas:Hypoallergenic neonatal nutrition requiring pharmaceutical-grade enzyme purity and toxicological dossier compliance. EFSA re-evaluation timelines are compressing supplier windows for grandfathered approvals.
- Dietary Supplements:Over-the-counter digestive aids in tablet, capsule, and powder formats for lactose-intolerant consumers.
- Bakery Products:Enzyme-treated dairy ingredients for reduced-lactose baked goods, a niche segment with limited dedicated supplier investment.
Dairy products anchor procurement volume; infant formulas generate the highest margin capture per activity unit.
Distribution Channel:
Customer type fragmentation splits procurement between institutional buyers seeking technical service integration and consumers prioritizing convenience and unit pricing.
- Supermarkets:Mass-market retail placement for lactose-free dairy and consumer enzyme products, with private-label penetration expanding fastest in Northern Europe.
- Online Retail:Direct-to-consumer and B2B procurement platforms capturing share in supplement segments and small-scale dairy equipment bundling.
- Health Stores:Specialty retail channel for premium-positioned enzyme supplements with organic or non-GMO certification claims.
- Pharmacies:Regulated channel for infant formula and medical-grade digestive aids, requiring pharmacist consultation in some jurisdictions.
Supermarkets dominate transaction volume; online retail is gaining share fastest among nutraceutical buyers.
End User:
Supply concentration among precision fermentation specialists favors large-scale food manufacturers, while fragmented nutraceutical buyers face sourcing bottlenecks for pharmaceutical-grade supply.
- Food Manufacturers:Industrial dairy processors operating inline enzyme dosing systems, with Bavaria and Lower Saxony hosting concentrated lactose-free production infrastructure.
- Nutraceutical Companies:Supplement formulators requiring FCC-standardized activity labeling and stability data for product registration.
- Home Consumers:Individual purchasers of over-the-counter digestive aids, price-sensitive and brand-loyal within limited repertoires.
- Healthcare Providers:Hospitals and clinics prescribing enzyme supplements for secondary hypolactasia and post-surgical digestive support.
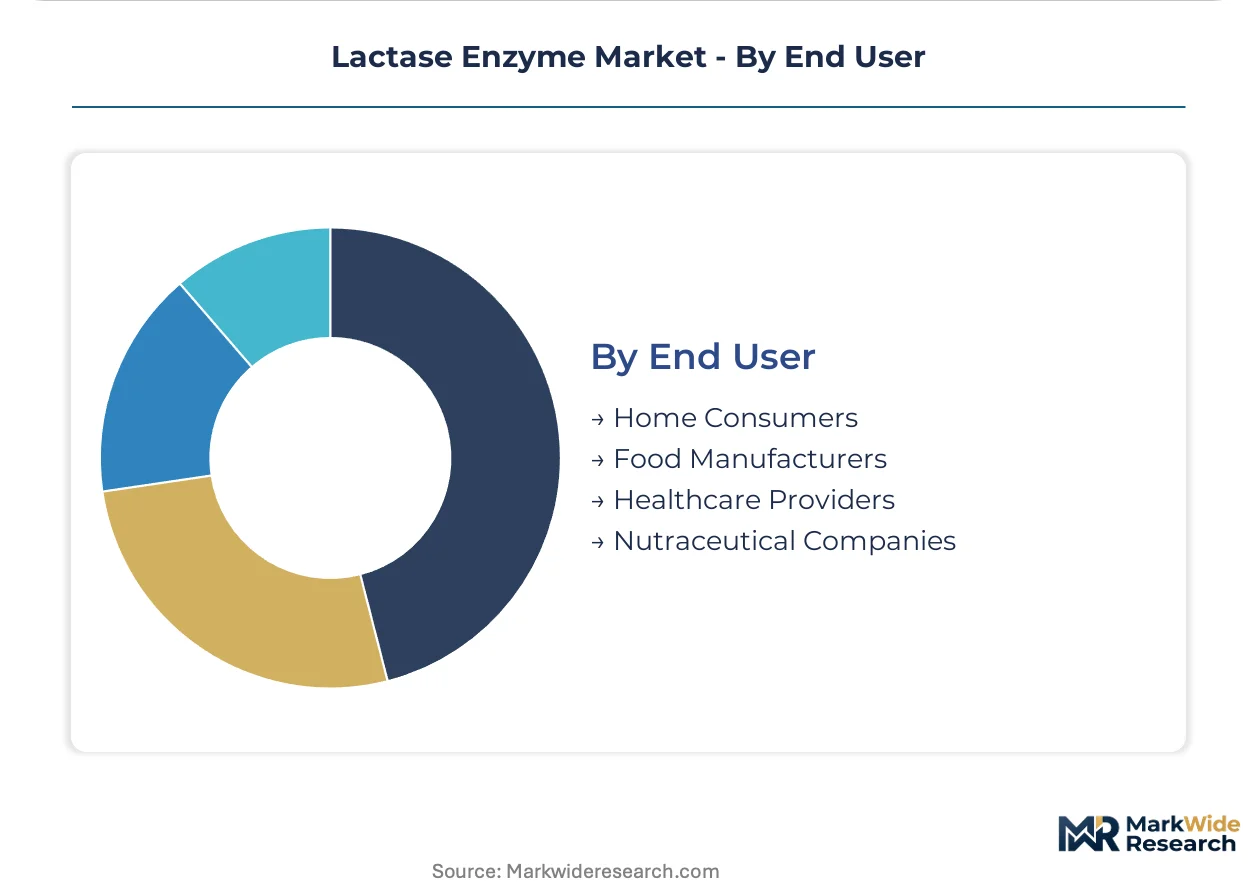
Food manufacturers command procurement volume; nutraceutical companies are climbing the fastest on reformulation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision fermentation infrastructure concentrates in Northern Europe and select North American dairy clusters, with regulatory harmonization efforts creating divergent compliance burdens across jurisdictions. FDA GRAS streamlining in the United States contrasts with EFSA's re-evaluation rigor, fragmenting supplier qualification pathways.
Germany
Bavaria and Lower Saxony host Europe's densest lactose-free dairy processing infrastructure, driving procurement pull for high-activity liquid formulations. EFSA's food enzyme re-evaluation program mandates toxicological dossiers for grandfathered approvals, compressing supplier windows. The Munich-Hamburg corridor anchors precision fermentation scale-up for captive enzyme supply among mid-tier cooperatives.
United States
Wisconsin and California dairy processors expand private-label lactose-free portfolios, accelerating inline dosing system adoption. FDA GRAS notifications collapse approval timelines below twelve months for precision-fermented strains. The Midwest cheese belt concentrates demand for application-specific enzyme blends targeting texture optimization.
Netherlands
Danish and Dutch mid-scale processors adopt continuous perfusion bioreactor technology to secure captive lactase supply outside commodity fermenter networks. REACH compliance for fermentation feedstock sourcing creates documentation overhead for cross-border suppliers. The Randstad region clusters formulation R&D for integrated enzyme systems bundling lactase with protease and lipase.
Brazil
Lactose-free dairy represents under five percent of fluid milk sales, creating whitespace for enzyme-treated private label expansion. ANVISA's food additive approval pathways lag FDA and EFSA timelines, extending commercialization lead times for new entrants. São Paulo's dairy processing corridor concentrates import-dependent enzyme procurement amid local precision fermentation underinvestment.
India
FSSAI's food enzyme notification requirements are formalizing as the lactose-free dairy segment emerges in urban markets. Advanced Enzymes and domestic suppliers target pharmaceutical-grade extraction capabilities for infant formula export qualification. Maharashtra and Gujarat host emerging dairy processing clusters with nascent enzyme dosing infrastructure.
Lactase Enzyme Market Competitive Environment
Concentration sits with precision fermentation specialists and integrated enzyme system providers, creating a tiered structure where pharmaceutical-grade purity capabilities separate premium positioning from commodity supply. Three strategic archetypes dominate: precision fermentation scale leaders, application-specific blenders, and extraction-based legacy suppliers. Competitive moves center on backward integration into strain banking and geographic expansion into underpenetrated lactose-free dairy markets.
Within the precision fermentation tier, Novozymes and Chr. Hansen exemplify divergent positioning strategies—Danish specialists leveraging continuous bioprocessing scale against strain-banking partnerships across Northern Europe. Kerry Group occupies a position among application-specific blenders, embedding lactase into integrated enzyme systems. DuPont/IFF represents the consolidated life sciences conglomerate archetype, spanning food and pharmaceutical-grade supply through diversified fermentation assets.
| Leading Market Players |
|---|
| Chr. Hansen |
| Amano Enzyme |
| Novozymes |
| Kerry Group |
| Enzyme Development Corporation |
| DuPont/IFF |
| Advanced Enzymes |
| Merck KGaA |
| DSM-Firmenich |
| Others |
Value Chain & Pricing Dynamics
FDA GRAS notification timelines and EFSA food enzyme re-evaluation requirements simultaneously gate supply qualification and stratify price tiers across pharmaceutical-grade and food-grade lactase formulations. These regulatory frameworks compress supplier windows for grandfathered approvals while creating premium capture opportunities for pre-certified precision fermentation capacity.
Pricing Analysis
FDA GRAS and EFSA food enzyme regulations dictate the pricing tier structure across pharmaceutical-grade, food-grade, and commodity-grade lactase segments. Three-tier pricing structure across premium, standard, and economy levels separates infant formula-grade powder from industrial liquid formulations and generic tablet supplements. Cost compression in commodity liquid grades is intensifying because precision fermentation scale-up collapses batch production economics. Food manufacturers represent the most price-sensitive buyer segment due to volume procurement and inline dosing standardization, while infant formula producers accept steep premiums for toxicological dossier compliance.
Supply Chain Analysis
Inventory cycles for high-activity liquid lactase run 6-10 weeks from Danish and Dutch precision fermentation facilities to German dairy processors, with powdered pharmaceutical-grade formats extending lead times due to lyophilization bottlenecks. Supply concentrates in Denmark, Germany, and the Netherlands for precision-fermented strains, while extraction-based legacy capacity clusters in India and Japan. Pharmaceutical-grade dextrose feedstock, specialized bioreactor vessels, and strain banking licenses anchor upstream dependencies. Single-source vulnerability sits with three European culture collections controlling Kluyveromyces lactis variant access. Distribution runs through direct technical service relationships with multinational dairy processors and enzyme system integrators rather than commodity chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from plant-based dairy alternatives and precision-fermented enzyme platforms that bypass traditional strain banking networks entirely.
For Market Incumbents: Compound defensive positioning through backward integration into captive strain banking and continuous perfusion bioreactor capacity in Bavaria or Lower Saxony. Secure grandfathered EFSA approvals ahead of re-evaluation deadlines to lock out fermentation-only entrants lacking toxicological dossiers. Precision fermentation specialists without pharmaceutical-grade purification assets represent the immediate competitive threat. For New Entrants and Emerging Players: Anchor in Brazil's underpenetrated lactose-free dairy corridor, where ANVISA approval lags create first-mover windows for imported enzyme-treated private label expansion. Target mid-scale dairy cooperatives in São Paulo's processing corridor seeking technical service partnerships absent from commodity suppliers. Lead with application-specific blending capabilities bundling lactase with texture-optimizing protease systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous perfusion bioprocessing as AI-driven strain optimization collapses batch-to-batch variability. Long-term viability favors precision fermentation specialists with pre-positioned pharmaceutical-grade capacity and grandfathered EFSA dossiers. Monitor EFSA re-evaluation completion rates as the signal to watch for regulatory moat crystallization versus commoditization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Banking | Captive access to high-yield Kluyveromyces lactis variants locks out licensing-dependent competitors in Germany. |
| Continuous Perfusion Bioreactor Deployment | Mid-scale Danish and Dutch processors secure supply independence from 50,000-liter commodity fermenter networks. |
| Pharmaceutical-Grade Purification Investment | Pre-positioned capacity captures EFSA re-evaluation premium as purity thresholds grandfather existing approvals. |
| Application-Specific Enzyme System Bundling | Integrated lactase-protease-lipase formulations displace standalone tenders among Northern Italian yogurt cooperatives. |
| Brazil Market Development Partnership | Technical service relationships with São Paulo dairy processors establish beachhead before local precision fermentation matures. |
Study Parameters
The analysis maps liquid lactase, powdered lactase, infant formula-grade, and dietary supplement enzyme segments, each validated through enzyme procurement managers at multinational dairy processors, regulatory affairs leads at precision fermentation specialists, and FSSC 22000 audit consultants. Primary interviews with Bavarian dairy cooperative technical directors, Dutch continuous bioprocessing engineers, and Brazilian ANVISA regulatory specialists combined with secondary validation through FDA GRAS notification databases, EFSA food enzyme evaluation records, and German dairy industry association processing statistics. Bottom-up fermentation capacity modeling and top-down dairy industry enzyme consumption estimates triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include formulation format, application purity tier, end-user procurement scale, and regional regulatory cluster. CAGRs derive from enzyme activity demand curves tied to lactose-free dairy portfolio expansion rates and precision fermentation cost compression trajectories. Forecast inputs incorporate EFSA re-evaluation timeline scenarios and Brazilian private-label penetration assumptions.
Decision-makers should treat outputs as directional under sustained precision fermentation scale-up and stable FDA GRAS notification timelines; material deviation in strain banking access or feedstock volatility would warrant model refresh. Forecasts reflect base-case assumptions regarding EFSA grandfathering provisions and German dairy cluster concentration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Cocoa Products Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Fruit Pectin Market
Ingredients
Acetylated Starch Market
Ingredients
Europe Gelatin Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Canada Sodium Reduction Ingredients Market
Ingredients
Marine Collagen Ingredients Market
Ingredients
Heart Health Ingredients Market
Ingredients
South America Fermented Ingredients Market
Ingredients
North America Protein Ingredients Market
Ingredients
Asia-Pacific Protein Market
Ingredients
GCC Egg Powder Market
Ingredients
Organic Edible Oil Market
Ingredients
Wort Concentrate Market
Ingredients
Canola Protein Market