
 Mung Bean Protein Market | 2026-2036
Mung Bean Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Mung Bean Protein Market Analysis
Buyer concentration in the mung bean protein space is shifting from fragmented specialty ingredient distributors toward consolidated food manufacturers and sports nutrition formulators seeking direct supply relationships. Prinova Group LLC leverages its global ingredient sourcing infrastructure to secure premium mung bean protein lots for North American and European customers. FUJI Plant Protein Labs anchors its position through deep specialization in Asian-origin legume extraction protocols. Axiom Foods Inc. differentiates via vertically integrated control over non-GMO and organic certification tiers.
Mung bean protein refers to the isolated or concentrated protein fraction derived from Vigna radiata seeds, typically containing 80-90% protein by dry weight when processed into isolate form, with a balanced amino acid profile notable for lysine and leucine content. The ingredient functions primarily as a functional binder and emulsifier in plant-based meat systems and as a hypoallergenic base in nutritional powders. Isolate formats command premium positioning due to superior solubility and neutral flavor relative to concentrate grades, while textured variants are gaining traction in meat alternative applications where fibrous mouthfeel determines purchase intent. Flour segments retain volume dominance in traditional Asian bakery and noodle applications, though margin pools have migrated toward isolate and textured categories.
The FDA oversees allergen labeling and GRAS notification pathways for novel plant protein ingredients entering the US food supply. EFSA and EMA frameworks in Europe govern novel food approvals and nutritional claim substantiation, with REACH compliance required for any solvent-based extraction processes. China's SAMR and GB standards enforce domestic food safety thresholds that foreign suppliers must meet for market access. Stakeholders should monitor evolving protein content claim thresholds and extraction solvent restrictions, as these will determine which processing technologies sustain commercial viability.
Market Dynamics
Clean-label protein sourcing mandates from EU Green Deal and F-Gas Regulation are forcing extraction technology upgrades across mung bean protein supply chains. Buyers now audit carbon intensity and solvent residues before awarding volume contracts.
Growth Catalysts
- EU Green Deal sustainability benchmarks:Food manufacturers in Germany and France now require deforestation-free mung bean sourcing with verified carbon accounting, pulling premium isolate demand.
- Sports nutrition formulators:Clean-label protein powder brands are replacing soy and whey with hypoallergenic mung bean isolates in recovery formulations.
- Wet fractionation advances:Novel aqueous extraction protocols developed in Jiangsu province are reducing hexane dependency and unlocking organic certification tiers.
Market Restraints
- Input cost volatility:Mung bean raw material prices fluctuate with monsoon patterns across Indian growing regions, compressing processor margins during poor harvests.
- Supply concentration risk:Over 60% of global mung bean crushing capacity sits within 200 kilometers of Yancheng, creating single-point vulnerability.
- Regulatory friction:EFSA novel food approval timelines for new protein extraction variants extend 18-24 months, freezing product pipeline velocity.
Strategic Opportunities
- Brazilian bakery sector:Traditional wheat-flour applications in São Paulo industrial bakeries remain underpenetrated for protein fortification.
- Cell-culture media applications:Biopharma serum-free formulations are testing plant-derived hydrolysates as fetal bovine serum replacements.
- USDA BioPreferred procurement:Federal purchasing mandates for biobased products create guaranteed offtake channels for certified suppliers.
Industry Challenges
- Specialized extraction engineering talent:Food protein processors lack personnel trained in membrane filtration and isoelectric precipitation at commercial scale.
- Organic certification timelines:Three-year field conversion periods and multi-step supply chain audits delay premium product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mung Bean Protein Market |
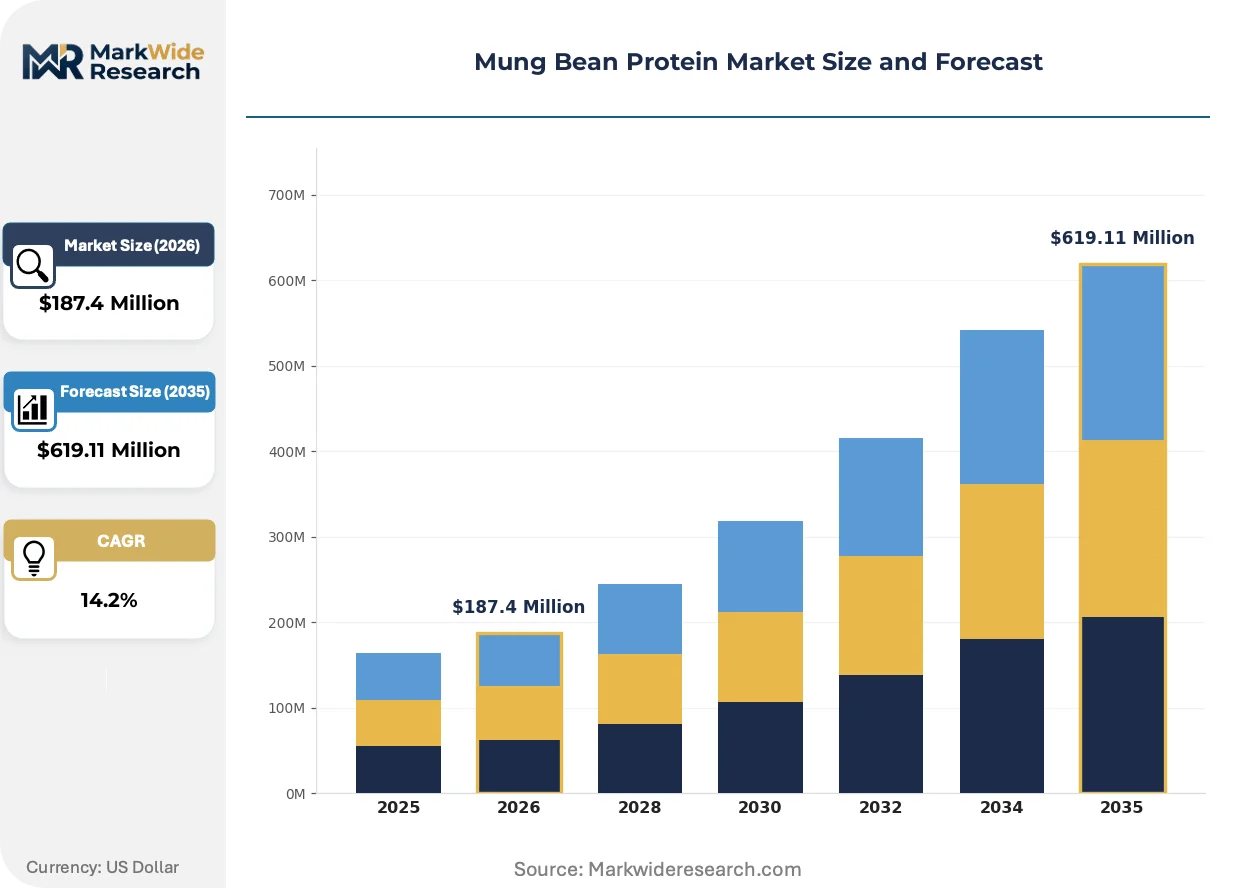
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Textured, Flour Application: Food & Beverages, Nutritional Supplements, Animal Feed, Meat Alternatives End User: Food Manufacturers, Health Conscious Consumers, Vegan Products, Sports Nutrition Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Prinova Group LLC, FUJI Plant Protein Labs, ET-chem Natural Ingredients, Laybio, Henry Broch Foods, Organicway Inc., ETprotein, 3B Keto, Axiom Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mung Bean Protein Market Emerging Trajectories
Extraction technology convergence with precision fermentation is compressing traditional protein isolation economics. Regulatory carbon accounting and buyer sustainability audits are reshaping competitive positioning.
Membrane filtration systems are integrating with traditional aqueous extraction lines to recover protein fractions previously lost in wash water. Sports nutrition contract manufacturers in California and British Columbia are retrofitting facilities at 15-20% annual rates. This convergence is integrating high-value isolate recovery into commodity flour operations, eroding the historical premium between grade tiers.
REACH solvent restrictions and F-Gas Regulation phase-down schedules are banning hexane-based extraction for EU-bound ingredients. Processors must deploy supercritical CO2 or enzyme-assisted aqueous methods by 2027. German and Dutch ingredient traders are now rejecting non-compliant lots, forcing Asian suppliers to dual-track certification or exit premium segments.
Direct procurement from origin processors is displacing layered distributor networks. North American plant-based meat brands now source mung bean protein through dedicated supply agreements rather than spot markets. This pattern concentrates most visibly in Pacific Northwest manufacturing clusters, where buyers co-locate technical staff with Jiangsu extraction facilities to monitor quality in real time.
Mung Bean Protein Market Segmentation
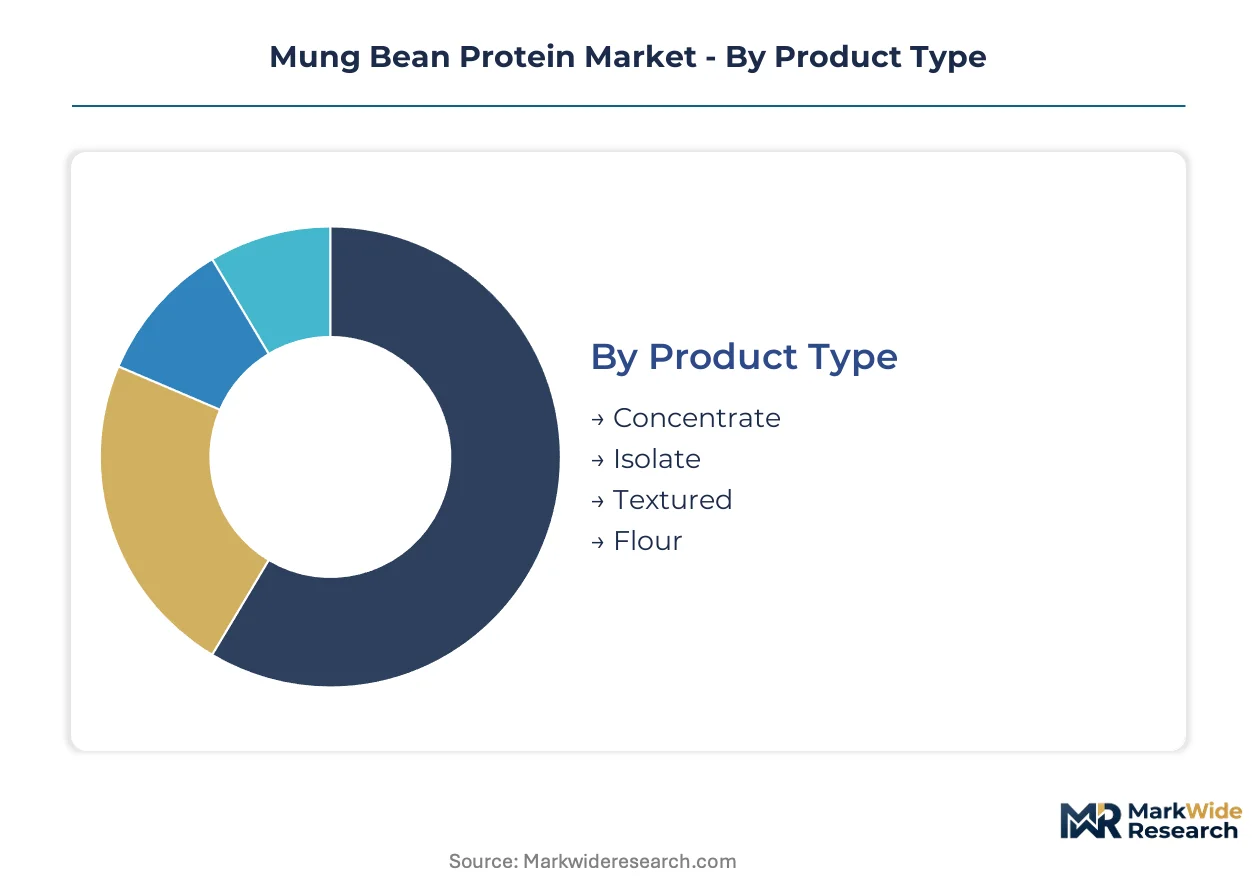
Segmentation in mung bean protein reveals how certification burdens and functional specifications reshape procurement patterns across buyer categories. Manufacturers navigate divergent regulatory pathways depending on which product grade and end-use channel they target.
Product Type:
EU REACH solvent restrictions and organic certification tiers impose sharply different compliance costs across protein grades. EFSA novel food pathways apply selectively to isolate variants entering functional food applications.
- Isolate:Refined to 80-90% protein content through aqueous or membrane filtration methods. Sports nutrition formulators in Germany and France now mandate deforestation-free sourcing with verified carbon accounting for premium recovery powder lines.
- Concentrate:Contains 50-70% protein with retained fiber and starch fractions. Plant-based meat manufacturers in California favor this grade for cost-sensitive burger and sausage applications where emulsification properties matter more than solubility.
- Textured:Extruded variants engineered for fibrous mouthfeel in meat alternatives. Requires additional GRAS notification in the US for novel texture-modified ingredients.
- Flour:Whole-seed milled product retaining complete nutritional matrix. Traditional Asian bakery and noodle applications in Jiangsu province dominate volume offtake with minimal regulatory friction.
Leading the category by volume: Flour. Growing fastest: Isolate.
Application:
End-use channels diverge sharply in margin structure and technical support requirements. Nutritional supplements command premium positioning while commodity food applications compete on scale economies.
- Nutritional Supplements:Hypoallergenic protein powders and recovery formulations. Clean-label brands in British Columbia and California are replacing soy and whey with mung bean isolates to serve allergen-sensitive athletes.
- Meat Alternatives:Functional binder and fibrous texture applications. Direct procurement agreements now link Pacific Northwest plant-based meat brands to Jiangsu extraction facilities for real-time quality monitoring.
- Food & Beverages:Beverage fortification and bakery protein enrichment. Brazilian industrial bakeries in São Paulo remain underpenetrated despite technical suitability for wheat-flour replacement.
- Animal Feed:Aquaculture and pet nutrition formulations. Lower protein specifications reduce certification burden but compress margins relative to human-grade segments.
Volume leadership: Food & Beverages. Steepest expansion trajectory: Meat Alternatives.
End User:
Customer sophistication determines contract structure and technical service intensity. Sports nutrition buyers demand batch-level traceability while commodity food manufacturers prioritize supply security.
- Sports Nutrition:Contract manufacturers and branded powder companies. California and British Columbia facility retrofits are proceeding at 15-20% annual rates to accommodate aqueous extraction lines.
- Food Manufacturers:Industrial bakery, beverage, and prepared food producers. Procurement is consolidating toward direct origin relationships and away from layered distributor networks.
- Vegan Products:Plant-based specialty brands and clean-label positioning. EFSA nutritional claim substantiation requirements extend 18-24 months for novel extraction variants.
- Health Conscious Consumers:Direct-to-purchaser brands and functional food startups. Three-year organic field conversion periods delay premium product launches for this segment.
Dominant by contract value: Food Manufacturers. Gaining share fastest: Sports Nutrition.
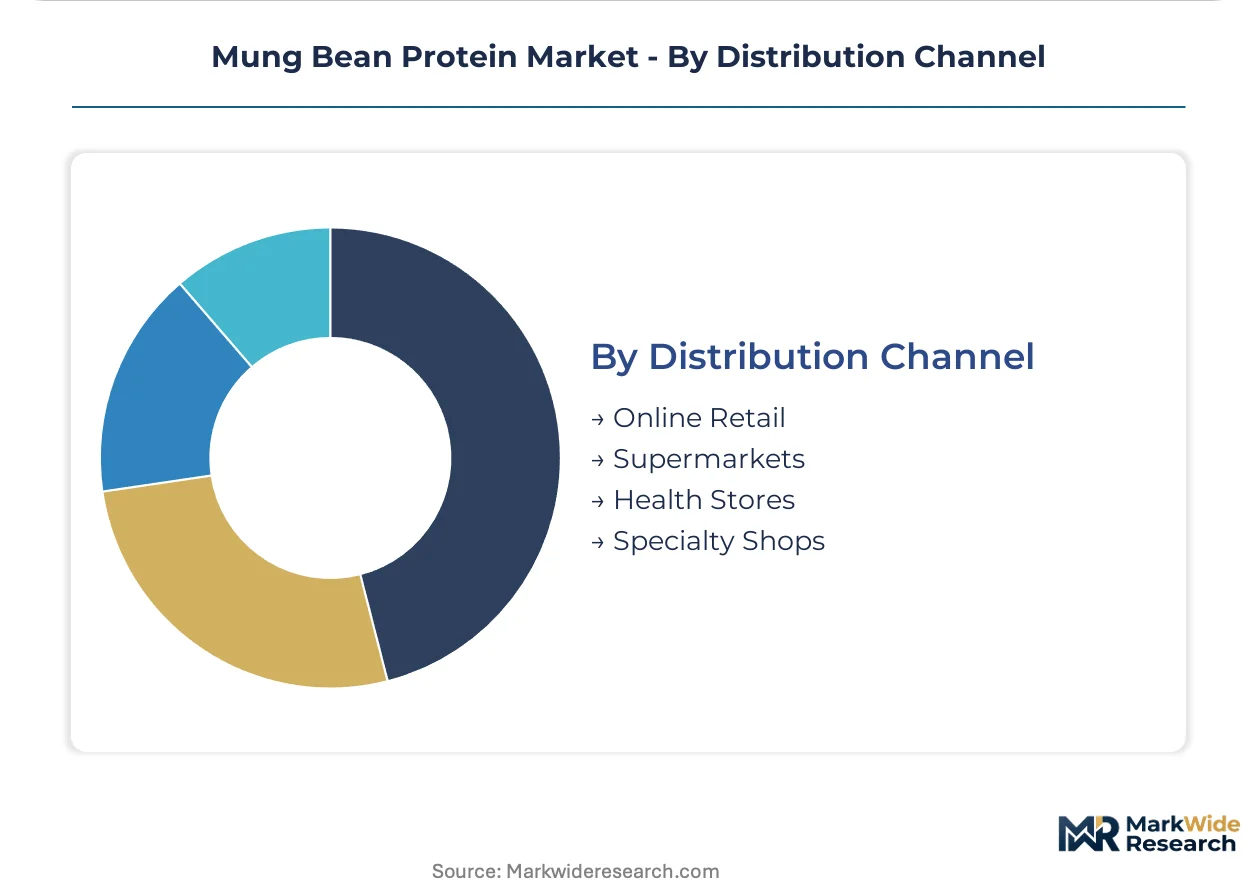
Distribution Channel:
Channel selection reflects buyer scale and technical support needs. Large manufacturers bypass intermediaries while smaller formulators rely on specialized distributors for certification documentation.
- Online Retail:Direct-to-consumer protein powders and specialty ingredients. Enables small-batch organic certification tiers that command 30-40% price premiums over conventional grades.
- Supermarkets:Mass-market plant-based meat and fortified bakery products. Requires shelf-stable packaging specifications that favor textured and flour segments over isolate.
- Health Stores:Premium supplement and specialty diet positioning. Staff technical knowledge supports higher-margin isolate sales to educated consumers.
- Specialty Shops:Ethnic food and traditional Asian ingredient channels. Jiangsu-origin flour products move through this channel with minimal regulatory documentation.
Highest throughput: Supermarkets. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates structural demand for mung bean protein through domestic processing capacity and traditional legume consumption patterns. Germany and France impose sustainability benchmarks that pull premium isolate volumes. Brazil, India, and the United States each present distinct procurement and regulatory environments that shape supplier strategies.
China
Jiangsu province hosts over 60% of global mung bean crushing capacity within 200 kilometers of Yancheng. SAMR and GB standards enforce domestic food safety thresholds that foreign suppliers must satisfy for market access. Yancheng extraction facilities now co-locate technical staff from Pacific Northwest plant-based meat brands to enable real-time quality monitoring.
Germany
Industrial bakery and sports nutrition formulators in Bavaria and North Rhine-Westphalia now mandate deforestation-free sourcing with verified carbon accounting. REACH solvent restrictions and the EU Green Deal ban hexane-based extraction for EU-bound ingredients by 2027. Munich and Cologne trading houses reject non-compliant lots, forcing Asian suppliers to dual-track certification.
France
Clean-label protein powder brands in Île-de-France are replacing soy and whey with hypoallergenic mung bean isolates for allergen-sensitive athletes. EFSA novel food approval timelines extend 18-24 months for new extraction variants, freezing product pipeline velocity. Paris-region contract manufacturers retrofit facilities at 15-20% annual rates to accommodate aqueous extraction lines.
Brazil
São Paulo industrial bakeries remain underpenetrated for protein fortification despite technical suitability for wheat-flour replacement. ANVISA governs novel food approvals and nutritional claim substantiation for imported plant protein ingredients. The country's national agricultural regulator monitors mung bean import volumes for domestic processing capacity planning.
United States
California and British Columbia sports nutrition contract manufacturers drive isolate demand through clean-label recovery formulations. FDA allergen labeling and GRAS notification pathways govern novel plant protein ingredients entering the food supply. USDA BioPreferred procurement mandates create guaranteed offtake channels for certified biobased product suppliers.
Mung Bean Protein Market Vendor Landscape
Asian producers anchor one tier; North American and European specialists hold differentiated positions through certification and sourcing infrastructure. The vendor base spans vertically integrated processors, ingredient distributors with global sourcing networks, and extraction technology specialists. Three archetypes dominate: origin-integrated processors controlling non-GMO and organic tiers, global distributors securing premium lots through established relationships, and regional specialists deploying proprietary Asian-origin extraction protocols. Capacity expansion and direct procurement partnerships constitute the dominant competitive moves, with buyers bypassing layered distributor networks.
Within the origin-integrated tier, Axiom Foods Inc. and FUJI Plant Protein Labs exemplify contrasting geographic specializations. Axiom Foods Inc. occupies a position tied to North American certification infrastructure, while FUJI Plant Protein Labs anchors Japanese expertise in Asian-origin legume extraction. Prinova Group LLC sits within the global distributor archetype, leveraging its infrastructure to secure premium mung bean protein lots for transatlantic customers. ET-chem Natural Ingredients and Organicway Inc. represent Chinese specialists with proximity to Yancheng processing clusters.
| Leading Market Players |
|---|
| Prinova Group LLC |
| FUJI Plant Protein Labs |
| ET-chem Natural Ingredients |
| Laybio |
| Henry Broch Foods |
| Organicway Inc. |
| ETprotein |
| 3B Keto |
| Axiom Foods Inc. |
| Others |
Supply Flow & Price Mechanics
Consolidated food manufacturers and sports nutrition formulators now dominate procurement volumes, compressing pricing power toward contract-based long-term offtake agreements rather than spot-market transactions. This buyer concentration in North American and European markets rewards suppliers with certified organic tiers and verified carbon accounting, while penalizing commodity-grade processors.
Pricing Analysis
Volume leadership sits with flour segments serving traditional Asian applications, while margin pools concentrate in isolate grades for sports nutrition. Pricing stratifies across premium, standard, and economy tiers based on certification level and protein purity specifications. Cost compression in concentrate grades is intensifying because wet fractionation advances are eroding historical premiums between grade tiers. Contract manufacturers exhibit highest price sensitivity; premium isolate buyers in Germany and France show lowest sensitivity when deforestation-free sourcing is guaranteed.
Supply Chain Analysis
Freight cost escalation from Jiangsu province to Atlantic ports now represents a material share of delivered isolate pricing for European buyers. Raw material supply draws from Chinese crushing clusters near Yancheng, Indian monsoon-dependent growing regions, and emerging Brazilian cultivation trials. Hexane solvent restrictions under REACH and F-Gas Regulation phase-down schedules create regulatory chokepoint risk for EU-bound shipments. Distribution runs through direct procurement agreements linking Pacific Northwest plant-based meat brands to origin processors, displacing layered distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
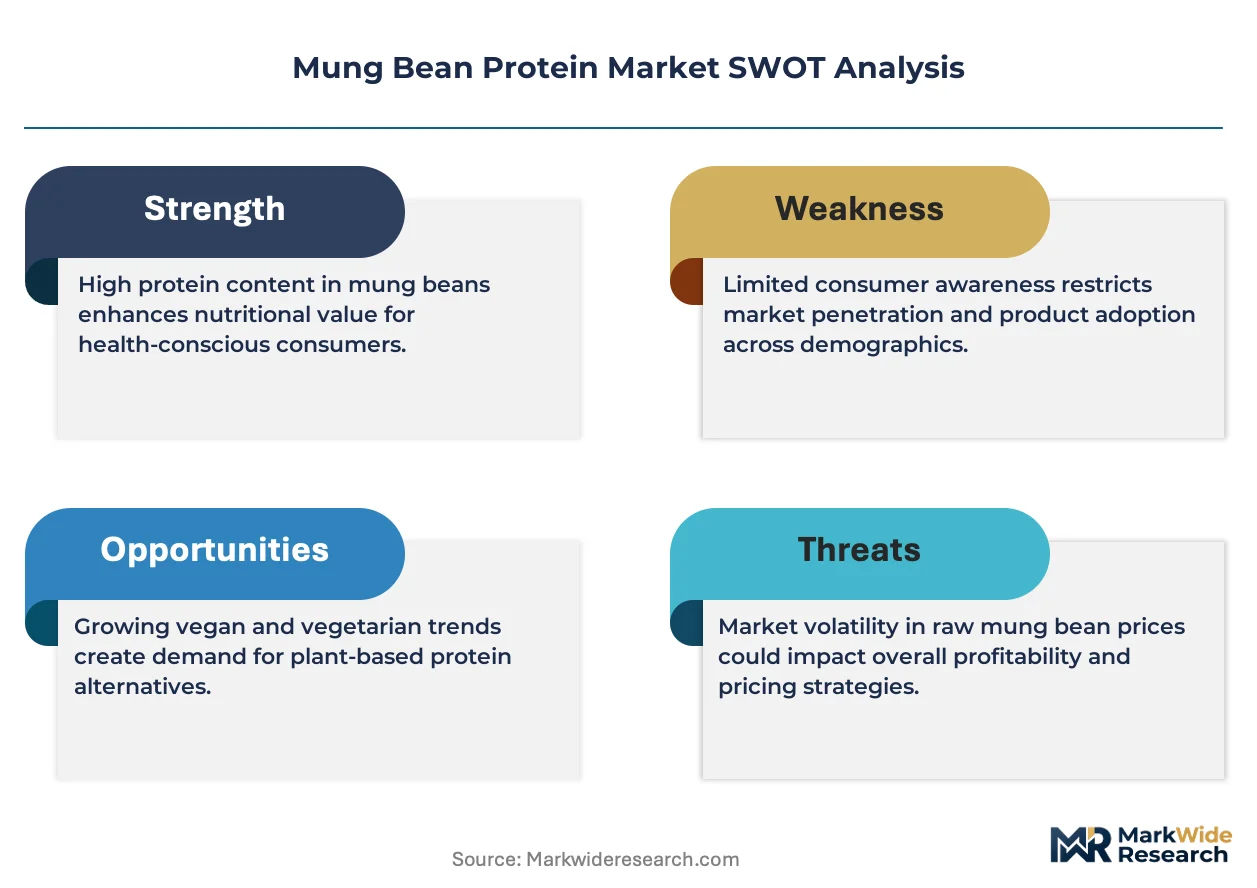
This market operates as a cost-of-compliance story where REACH solvent restrictions and EFSA novel food pathways erect barrier-to-entry moats. Players with certified aqueous extraction infrastructure capture premium positioning; those dependent on legacy hexane methods face forced exit from EU segments.
For Market Incumbents: Deploy dual-track certification investment to maintain EU market access while expanding organic tier capacity. Axiom Foods Inc. and FUJI Plant Protein Labs demonstrate how backward integration into non-GMO seed sourcing defends margin position against commodity-grade entrants. Incumbents should co-locate technical staff with Jiangsu extraction facilities to enable real-time quality monitoring for direct procurement relationships. For New Entrants and Emerging Players: Enter via aqueous extraction technology licensing partnerships to bypass three-year organic field conversion timelines. São Paulo industrial bakeries present the most penetrable white-space target for protein fortification applications. A go-to-market angle anchored in Brazilian ANVISA novel food approval expertise unlocks Latin American volume channels without competing directly for EU sports nutrition share. For Investors and Strategic Acquirers: The window for entry favors origin-integrated processors with captive organic certification infrastructure and established SAMR compliance for Chinese market access. Long-term viability rests on extraction technology portfolios compatible with F-Gas Regulation phase-down schedules. The signal to watch is EFSA approval velocity for novel aqueous extraction variants, as pipeline acceleration indicates competitive repositioning opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Seed Supply | Captures three-year field conversion premiums and locks non-GMO certification tiers. |
| Aqueous Extraction Facility Retrofit | Enables REACH compliance and unlocks EFSA novel food pathways for EU-bound isolate. |
| Direct Procurement Partnership | Links Pacific Northwest plant-based meat brands to Jiangsu processors for quality control. |
| Cell-Culture Media Hydrolysate Development | Positions mung bean protein as fetal bovine serum replacement in biopharma applications. |
| USDA BioPreferred Certification | Secures guaranteed federal offtake channels for certified biobased product suppliers. |
Methodological Framework
Multi-period observation of extraction technology patent filings, EFSA novel food submission timelines, and Jiangsu province capacity utilization anchored the trend analysis, supplemented by interviews with extraction plant managers, sports nutrition formulators, organic certification auditors, and EU ingredient trading house procurement leads. Secondary validation drew from SAMR GB standard updates, REACH restriction proposal documents, USDA BioPreferred program disclosures, and customs trade data. Bottom-up facility capacity estimates triangulated against top-down demand segmentation across application channels.
Segment-weighting across product type, application, end user, and distribution channel dimensions shaped the analytical framework, with isolate and textured categories receiving differential growth coefficients based on sports nutrition and meat alternative demand trajectories. CAGRs were derived from slope-consistency testing against historical protein ingredient adoption curves. Forecast inputs incorporated monsoon pattern volatility indices for Indian growing regions and EFSA approval pipeline velocity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory acceleration scenarios or sustained drought conditions in Indian mung bean cultivation zones. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Roll-Dried Starch Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
China Cane Sugar Market
Ingredients
Soy Lecithin Market
Ingredients
Astragalus Root Extract Market
Ingredients
Dried Tomato Lycopene-Rich Flake Ingredients Market
Ingredients
Mastic Gum Market
Ingredients
Meat Extract Market
Ingredients
Edible Animal Fat Market
Ingredients
Anhydrous Caffeine Market
Ingredients
Pine Needle Oil Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Pomegranate Peel Polyphenol Complex Market
Ingredients
Terminalia Extract Market
Ingredients
China Corn Glucose Market
Ingredients
Milk Mineral Concentrate Market