
 Amylase Market | 2026-2036
Amylase Market Size, Share, and Industry Trends Forecast 2026-2036
Amylase Market Analysis
Enzyme-as-a-service contracting is broadening what industrial buyers purchase, shifting transactions from bulk powder orders to performance-guaranteed supply agreements with embedded technical support. Novozymes A/S dominates this transition with dedicated fermentation capacity and application laboratories across three continents. BASF SE anchors its position through backward integration into genetically modified strain development. AB Enzymes GmbH differentiates via specialty formulations for high-temperature brewing processes.
Amylases constitute a class of hydrolase enzymes that catalyze the endohydrolysis of alpha-D-glucosidic linkages in starch polysaccharides, typically operating optimally between 50°C and 90°C depending on source organism and calcium cofactor concentration. These enzymes serve primarily to reduce viscosity, generate fermentable sugars, or modify textural properties in industrial substrate processing. Alpha-amylase leads the type category due to its established role in liquefaction stages across ethanol and sweetener production, while glucoamylase captures the fastest growth trajectory as cellulosic biofuel facilities seek saccharification efficiency gains. The powder form retains margin strength in emerging-market animal feed compounding, though liquid concentrates are displacing it in automated European bakery dosing systems.
The FDA evaluates food-grade amylases through GRAS self-affirmation or petition pathways, while REACH obliges European manufacturers to register enzyme protein substances and characterize respiratory sensitization hazards. China's SAMR enforces GB standards for enzyme preparations used in food processing, creating divergent testing burdens for multinational suppliers. Stakeholders must monitor how diverging regulatory data requirements for novel protein engineering techniques reshape registration timelines and competitive access across major demand centers.
Market Dynamics
Enzyme-as-a-service contracting is compressing traditional bulk powder transactions into performance-guaranteed supply agreements with embedded technical support, forcing suppliers to reconfigure fermentation capacity and application laboratory networks around technical outcome accountability rather than commodity volume.
Growth Catalysts
- Clean-label bakery mandates:Germany and the United States are expanding enzyme procurement for additive-free bread production, pulling demand toward microbial-origin amylases that replace chemical conditioners.
- REACH framework compliance:Industrial enzyme registration requirements across the European Union are raising barriers for marginal suppliers, concentrating procurement among registered producers with characterized respiratory sensitization data.
- Cellulosic biofuel saccharification:Glucoamylase adoption is accelerating in second-generation ethanol facilities seeking improved starch-to-sugar conversion efficiency at lower enzyme loadings.
Market Restraints
- Calcium cofactor dependency:Thermostable alpha-amylase performance requires consistent calcium ion concentration, creating formulation complexity and stability challenges in soft-water processing regions.
- Shandong Province supply concentration:China's starch-processing corridor concentrates both demand and intermediate enzyme distribution, exposing buyers to regional logistics disruptions and provincial policy shifts.
- Protein engineering regulatory lag:Novel strain development through CRISPR and directed evolution faces divergent approval timelines across FDA GRAS, EFSA, and SAMR pathways, delaying commercialization.
Strategic Opportunities
- High-temperature brewing specialization:Specialty glucoamylase formulations for mashing above 75°C remain underdeveloped, offering margin capture for suppliers with thermostability engineering capabilities.
- Automated liquid dosing systems:European bakery automation is displacing powder reconstitution, creating pull for stabilized liquid concentrates with extended ambient shelf life.
- India FSSAI enzyme standardization:Pending food-grade enzyme classification guidelines will clarify import and local manufacturing requirements ahead of formal sector dairy and starch processing expansion.
Industry Challenges
- Fermentation scale-up biology:Translating laboratory strain productivity to industrial bioreactor consistency requires rare expertise in fungal morphology control and contamination management.
- Cross-border data package assembly:Multinational suppliers must reconcile divergent toxicology study requirements between FDA GRAS self-affirmation, REACH Annex VIII, and China's GB 1886.174 standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amylase Market |
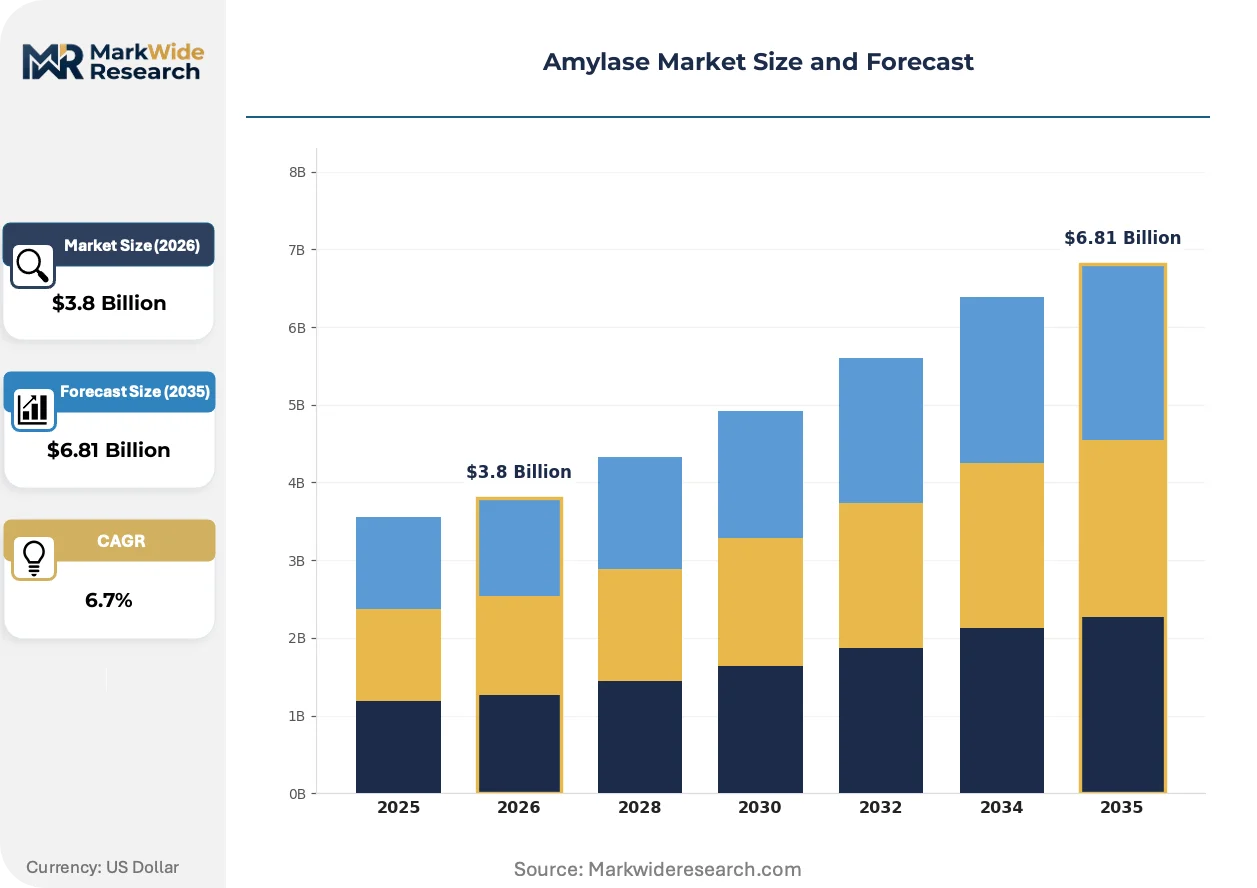
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Alpha-Amylase, Glucoamylase, Beta-Amylase, Liquefying Enzyme Application: Baking, Brewing, Biofuels, Pharmaceuticals Form: Liquid, Powder, Granule, Tablet End User: Food Industry, Textile Industry, Animal Feed, Biotechnology |
| Companies Covered | BASF SE, AB Enzymes GmbH, Novozymes A/S, Advanced Enzyme Technologies Ltd., International Flavors & Fragrances Inc., DuPont de Nemours, Inc., Amano Enzyme Inc., Merck KGaA, DSM-Firmenich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amylase Market Emerging Trajectories
Protein engineering and digital fermentation control are compressing development cycles and enabling application-specific enzyme customization that was previously uneconomical at commercial scale.
Immobilized enzyme systems for continuous starch processing are decentralizing unit operations from large centralized liquefaction trains toward modular, skid-mounted reactors that food manufacturers can deploy adjacent to existing production lines. Mid-sized European maltose syrup producers are piloting these systems to reduce energy intensity and water consumption. This architecture is compressing minimum efficient scale requirements and opening entry points for regional enzyme suppliers without billion-liter fermentation assets.
REACH Annex VIII amendments on respiratory sensitization testing are forcing enzyme manufacturers to characterize protein allergenicity through standardized inhalation exposure protocols before industrial registration. The compliance burden falls heaviest on powder-form products used in animal feed compounding, where dust generation creates occupational exposure risk. Suppliers are responding with granular formulation engineering and closed-system transfer designs that reduce airborne protein levels below classification thresholds.
Performance-based contracting is displacing traditional bulk powder purchasing in ethanol and sweetener processing, with buyers paying per ton of fermentable sugar generated rather than per kilogram of enzyme delivered. This model transfers yield risk to suppliers and demands real-time process analytics integration. The shift is most visible in North American corn ethanol, where plant operators seek to lock in conversion economics against volatile enzyme input costs.
Amylase Market Segmentation
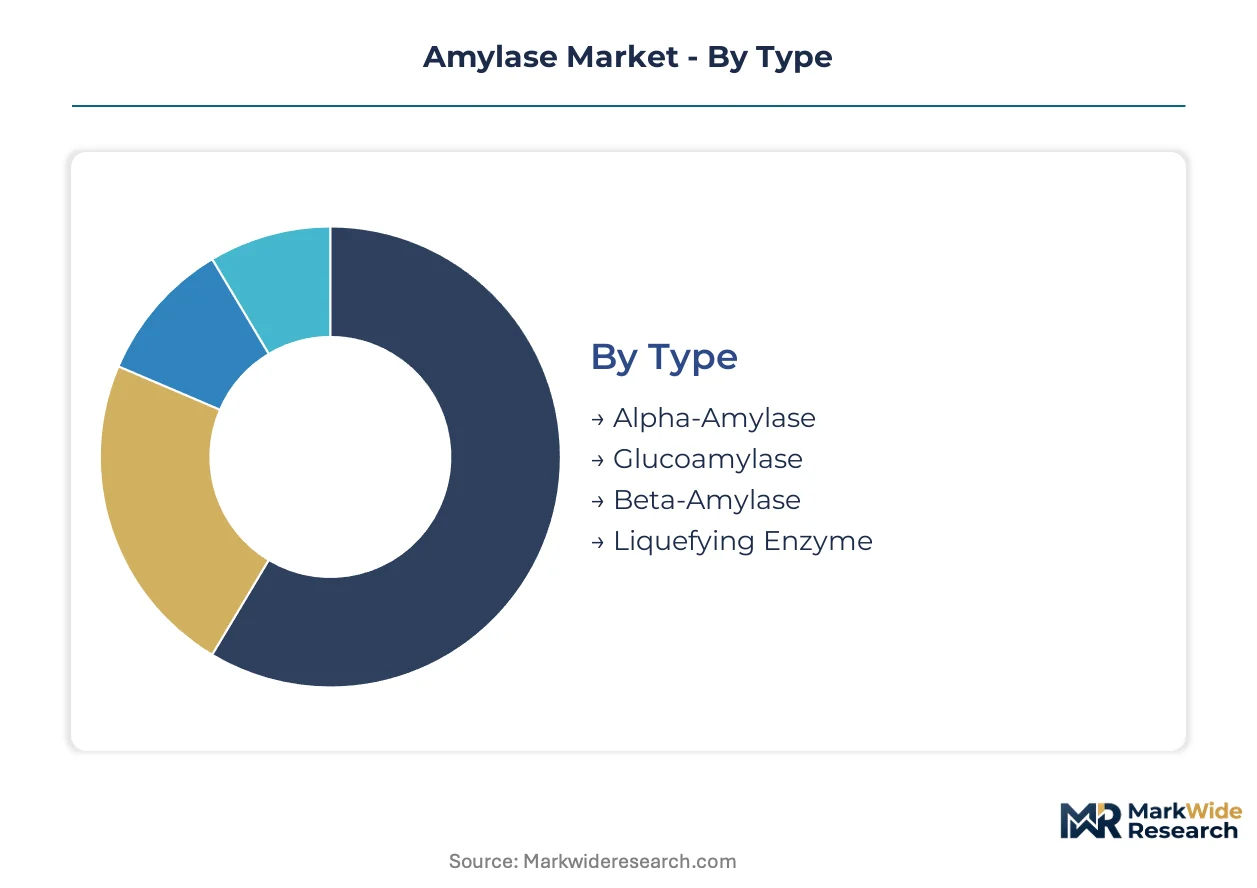
Amylase segmentation reflects divergent technical requirements across starch conversion stages and end-use specifications. Buyers select enzyme types based on hydrolysis targets, operating temperatures, and downstream processing constraints.
Type:
Volume concentration sits with established liquefaction workhorses, while premium capture shifts toward saccharification specialists with thermostability engineering.
- Alpha-Amylase:Endohydrolase attacking internal alpha-1,4-glycosidic bonds to reduce starch viscosity and produce oligosaccharide mixtures. Demand clusters in Shandong Province starch-processing corridors where biofuel mandates and modified starch exports pull consumption upward. Calcium cofactor dependency creates formulation complexity in soft-water regions.
- Glucoamylase:Exohydrolase releasing glucose units from non-reducing chain ends with highest specificity for complete saccharification. Cellulosic biofuel facilities in North America are adopting this type for improved starch-to-sugar conversion efficiency at reduced enzyme loadings, transferring yield risk to suppliers through performance-guaranteed contracts.
- Beta-Amylase:Exo-acting enzyme producing maltose via systematic hydrolysis from chain termini, favored in traditional brewing applications requiring specific sugar profiles.
- Liquefying Enzyme:Broad-spectrum preparation combining multiple amylolytic activities for rapid viscosity reduction in high-solids starch slurries.
Today's leader: Alpha-Amylase. Tomorrow's challenger: Glucoamylase.
Application:
End-use selection hinges on regulatory compliance burdens and automation readiness across divergent processing environments.
- Baking:Clean-label bread production in Germany and the United States drives microbial-origin amylase procurement to replace chemical conditioners, with automated dosing systems favoring liquid concentrates over powder reconstitution.
- Brewing:Mashing temperature tolerance above 75°C remains underdeveloped, offering margin capture for suppliers with thermostability engineering capabilities in high-temperature specialty formulations.
- Biofuels:Performance-based contracting in North American corn ethanol shifts transactions from bulk powder orders to per-ton-of-sugar payment structures with embedded technical support.
- Pharmaceuticals:Stringent purity requirements and respiratory sensitization testing under REACH Annex VIII create registration barriers for non-specialized suppliers.
Biofuels command volume scale. Baking captures premium expansion through clean-label positioning.
Form:
Physical presentation determines supply chain configuration, occupational exposure risk, and dosing automation compatibility.
- Liquid:Stabilized concentrates with extended ambient shelf life are displacing powder in European bakery automation, enabling precise metered dosing without reconstitution labor.
- Powder:Retains margin strength in emerging-market animal feed compounding, though REACH respiratory sensitization protocols impose granular formulation engineering to reduce airborne protein levels below classification thresholds.
- Granule:Engineered particle size distribution minimizes dust generation during closed-system transfer operations in high-exposure occupational environments.
- Tablet:Unit-dose presentation for small-scale pharmaceutical and laboratory applications requiring precise activity standardization.
Liquid leads automation adoption. Powder defends feed compounding volume.
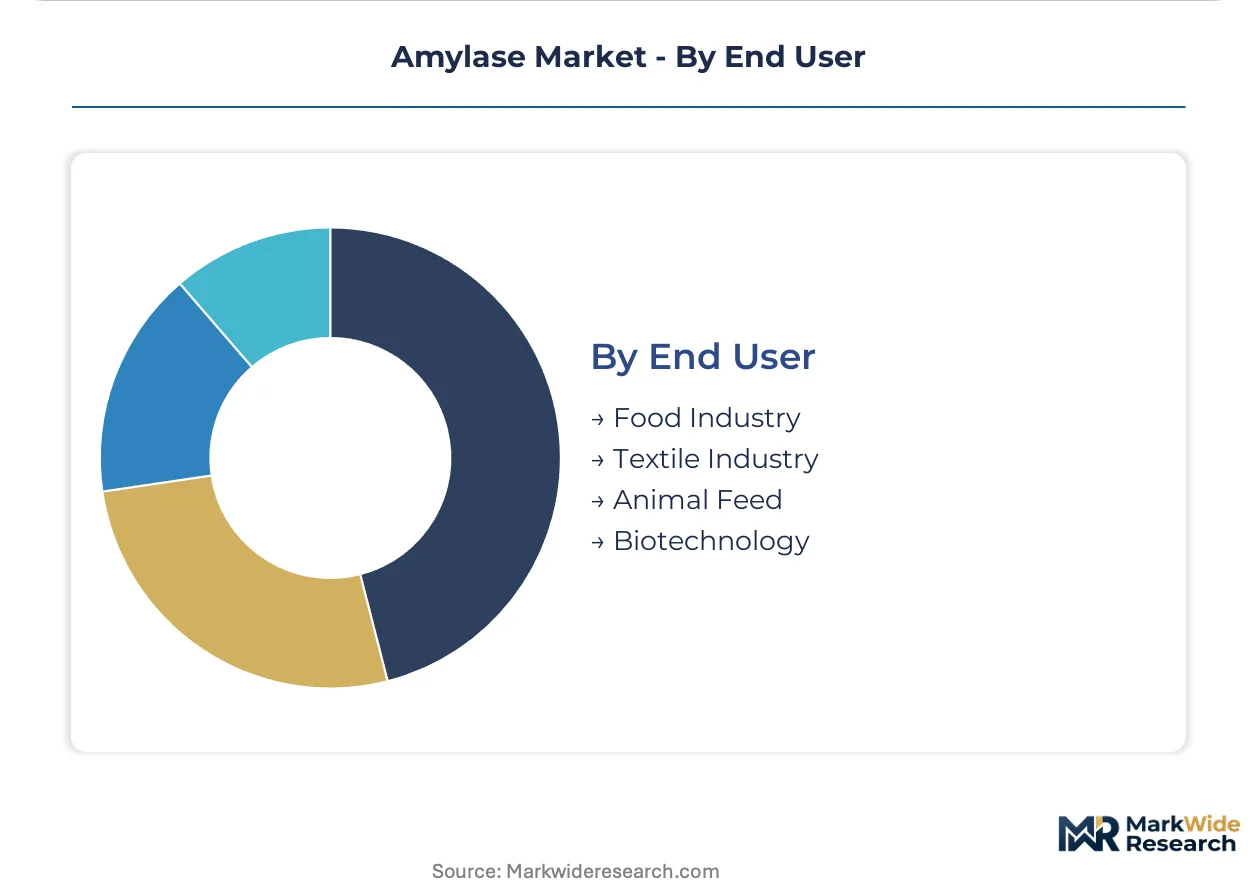
End User:
Customer type shapes procurement sophistication, from commodity spot purchasing to embedded technical service contracts.
- Food Industry:FDA GRAS self-affirmation and EU REACH registration requirements concentrate supply among characterized producers with toxicology data packages spanning multiple jurisdictions.
- Textile Industry:Desizing applications leverage amylase specificity for starch-based size removal without fiber damage, operating under divergent national chemical safety frameworks.
- Animal Feed:Powder formulations face REACH Annex VIII compliance burden for respiratory sensitization, driving granular engineering and closed-system transfer designs.
- Biotechnology:Protein engineering through CRISPR and directed evolution encounters divergent approval timelines across FDA GRAS, EFSA, and China's SAMR pathways.
Food Industry anchors regulatory-compliant supply. Biotechnology offers steepest expansion trajectory through strain engineering premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's clean-label bakery sector demands microbial-origin amylases at premium contract values, while China's Shandong Province starch-processing corridor pulls comparable tonnage at tighter margins through biofuel mandates.
United States
Corn ethanol producers in Iowa and Illinois negotiate performance-based contracts paying per ton of fermentable sugar generated. The FDA's GRAS self-affirmation pathway concentrates supply among characterized producers with toxicology data packages. Automated liquid dosing systems in commercial bakeries across Chicago and Minneapolis displace powder reconstitution.
China
Shandong Province's modified starch exporters and cellulosic biofuel facilities consume thermostable alpha-amylase at industrial scale. SAMR enforces GB 1886.174 standards for food-grade enzyme preparations, creating divergent testing burdens. Regional logistics concentration around Jinan and Qingdao exposes buyers to provincial policy shifts.
Germany
Bakery manufacturers in Bavaria and North Rhine-Westphalia expand enzyme procurement for additive-free bread production. REACH Annex VIII mandates respiratory sensitization characterization before industrial registration. Munich-based application laboratories support technical outcome accountability in performance-guaranteed supply agreements.
India
Dairy cooperatives in Maharashtra and Gujarat await FSSAI enzyme standardization guidelines to clarify import requirements. The pending classification will formalize local manufacturing ahead of organized sector starch processing expansion. Ahmedabad and Pune house emerging toll fermentation capacity.
Japan
Specialty brewing applications in Osaka and Tokyo demand glucoamylase formulations with mashing tolerance above 75°C. METI industrial biotechnology programs support thermostability engineering research. Kansai region maltose syrup producers pilot immobilized enzyme systems for continuous processing.
Amylase Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated supply in food-grade registrations and fragmented competition in industrial desizing applications. Three archetypes dominate: multinational enzyme houses with captive fermentation assets, regional toll manufacturers serving single-application niches, and biotechnology startups engineering novel thermostable strains. Capacity expansion and backward integration into strain development represent the dominant competitive moves.
Within the multinational tier, Novozymes A/S and BASF SE exemplify divergent strategic positioning. Novozymes A/S anchors performance-guaranteed contracting through dedicated fermentation capacity across three continents. BASF SE occupies a position emphasizing genetically modified strain development through in-house biotechnology infrastructure. AB Enzymes GmbH represents the specialty formulation archetype, with its German GmbH structure signaling focused regional engineering capabilities.
| Leading Market Players |
|---|
| BASF SE |
| AB Enzymes GmbH |
| Novozymes A/S |
| Advanced Enzyme Technologies Ltd. |
| International Flavors & Fragrances Inc. |
| DuPont de Nemours, Inc. |
| Amano Enzyme Inc. |
| Merck KGaA |
| DSM-Firmenich AG |
| Others |
Supply Flow & Price Mechanics
Performance-guaranteed contracting in North American corn ethanol simultaneously compresses supplier margins and concentrates procurement power among fermentation-integrated multinationals with real-time process analytics capabilities. This shift from bulk powder transactions to per-ton-of-sugar payment structures rewards technical outcome accountability over commodity volume, reshaping cost economics across the value chain.
Pricing Analysis
Capacity additions in China's Shandong Province are reshaping price floors for thermostable alpha-amylase through regional supply concentration and biofuel mandate pull. Three-tier pricing structure across premium, standard, and economy levels stratifies by REACH registration status and respiratory sensitization data completeness. Cost compression in standard-grade powder formulations is intensifying because REACH Annex VIII compliance burdens fall heaviest on non-specialized suppliers. Animal feed compounders exhibit highest price sensitivity due to thin margins and dust-exposure regulatory risks, while pharmaceutical buyers accept premium positioning for characterized toxicology packages.
Supply Chain Analysis
Direct-to-bakery channels handle automated liquid concentrate demand from European manufacturers seeking metered dosing without reconstitution labor. Fermentation capacity concentrates in Denmark, Germany, and China, with strain development expertise anchored in Basel and Copenhagen biotechnology clusters. Downstream supply rests on calcium salt inputs for thermostability cofactor formulation, corn starch feedstock for substrate engineering, and specialized filtration membranes for protein recovery. Single-source vulnerability in Shandong Province logistics corridors exposes buyers to provincial policy shifts and regional disruption. Distribution runs through technical service-embedded contracts rather than spot commodity exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH Annex VIII respiratory sensitization mandates and FDA GRAS pathway divergence continuously raise compliance barriers that concentrate supply among characterized producers.
For Market Incumbents: Extend fermentation capacity into application laboratory networks across three continents to anchor performance-guaranteed contracting. Deepen backward integration into CRISPR strain development to compress novel protein engineering timelines before EFSA-SAMR regulatory lag widens competitive gaps. Threat substitution from immobilized enzyme systems demands technical service bundling that transfers yield risk from buyers. For New Entrants and Emerging Players: India's pending FSSAI enzyme standardization opens a window for toll fermentation partnerships ahead of formal sector dairy and starch processing expansion. Target high-temperature brewing specialization above 75°C mashing tolerance, where thermostability engineering capabilities remain underdeveloped and margin capture potential sits highest. Go-to-market through regional maltose syrup producers piloting modular continuous processing systems. For Investors and Strategic Acquirers: Roll-up economics work for regional toll manufacturers with captive fermentation assets because minimum efficient scale requirements are compressing under immobilized enzyme decentralization. Acquisition focus: mid-cap specialists with SAMR-registered toxicology packages spanning food-grade and industrial segments. Signal to watch: FSSAI guideline finalization triggering import substitution investment in Maharashtra and Gujarat dairy cooperatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive CRISPR capabilities compress regulatory lag across FDA GRAS and EFSA pathways. |
| Performance-Guaranteed Supply Agreements | Per-ton-of-sugar contracts transfer yield risk to suppliers with embedded technical support. |
| Application Laboratory Network Expansion | Munich-based facilities anchor technical outcome accountability in European bakery automation. |
| Granular Formulation Engineering | Engineered particle size distribution reduces airborne protein below REACH Annex VIII thresholds. |
| Immobilized Enzyme System Deployment | Modular skid-mounted reactors open entry points for regional suppliers without billion-liter assets. |
Methodological Framework
Direct dialogue with fermentation plant managers, bakery procurement leads, ethanol plant operators, regulatory affairs directors, and enzyme application specialists grounded qualitative assessment in operational constraints. Secondary validation drew from FDA GRAS notifications, ECHA REACH registrations, SAMR GB standards filings, customs trade data for enzyme protein imports, and SEC disclosures from listed biotechnology suppliers. Bottom-up strain productivity estimates and top-down sector consumption models were cross-referenced for triangulation.
Segment-level outputs across the analysis window reflect modeled projections for alpha-amylase, glucoamylase, beta-amylase, and liquefying enzyme types by application in baking, brewing, biofuels, and pharmaceuticals, further split by liquid, powder, granule, and tablet forms. CAGRs were derived from regression against biofuel mandate trajectories, clean-label bakery penetration curves, and REACH compliance cost functions. Industry-specific inputs included Shandong Province starch-processing capacity utilization and North American corn ethanol plant automation adoption rates.
Revisions become necessary when regulatory timeline divergence across FDA GRAS, EFSA, and SAMR pathways widens unexpectedly, or when cellulosic biofuel facility commissioning accelerates glucoamylase demand beyond base assumptions. Forecasts reflect documented assumptions about calcium cofactor cost stability and fungal morphology control consistency at industrial bioreactor scale. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Protein Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
Sunflower Meal Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
Caramel Malt Market
Ingredients
Clean Label Starch Market
Ingredients
Modified Maize Starch Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Corn Gluten Meal Market
Ingredients
Global Edible Oil Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
Europe Malt Extract Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
GCC Egg Powder Market
Ingredients
Marine Peptides Market
Ingredients
Boysenberry Extract Market