
 North America Phytosterols Market | 2026-2036
North America Phytosterols Market Size, Share, and Industry Trends Forecast 2026-2036
North America Phytosterols Market Analytics
Canada is tilting toward expanded phytosterol extraction capacity as domestic oilseed processors upgrade refining infrastructure. BASF SE leverages its integrated sterol production network to supply North American nutraceutical formulators. Archer Daniels Midland Company anchors its position through backward integration into corn and soybean processing streams. Cargill Incorporated competes by controlling raw material flows from Midwest grain elevators to finished sterol esters.
Phytosterols comprise plant-derived steroid alcohols—primarily beta-sitosterol, campesterol, and stigmasterol—typically extracted from vegetable oil deodorizer distillates at purity grades exceeding ninety-five percent. These compounds structurally mimic cholesterol and competitively inhibit intestinal cholesterol absorption, forming the basis for FDA-authorized coronary heart disease risk reduction claims. Beta-sitosterol dominates volume owing to its abundance in soy and tall oil sources, while campesterol commands premium positioning in pharmaceutical-grade applications. Functional foods represent the most mature revenue pool, whereas nutraceuticals and dietary supplements concentrate growth as direct-to-consumer brands expand online retail penetration.
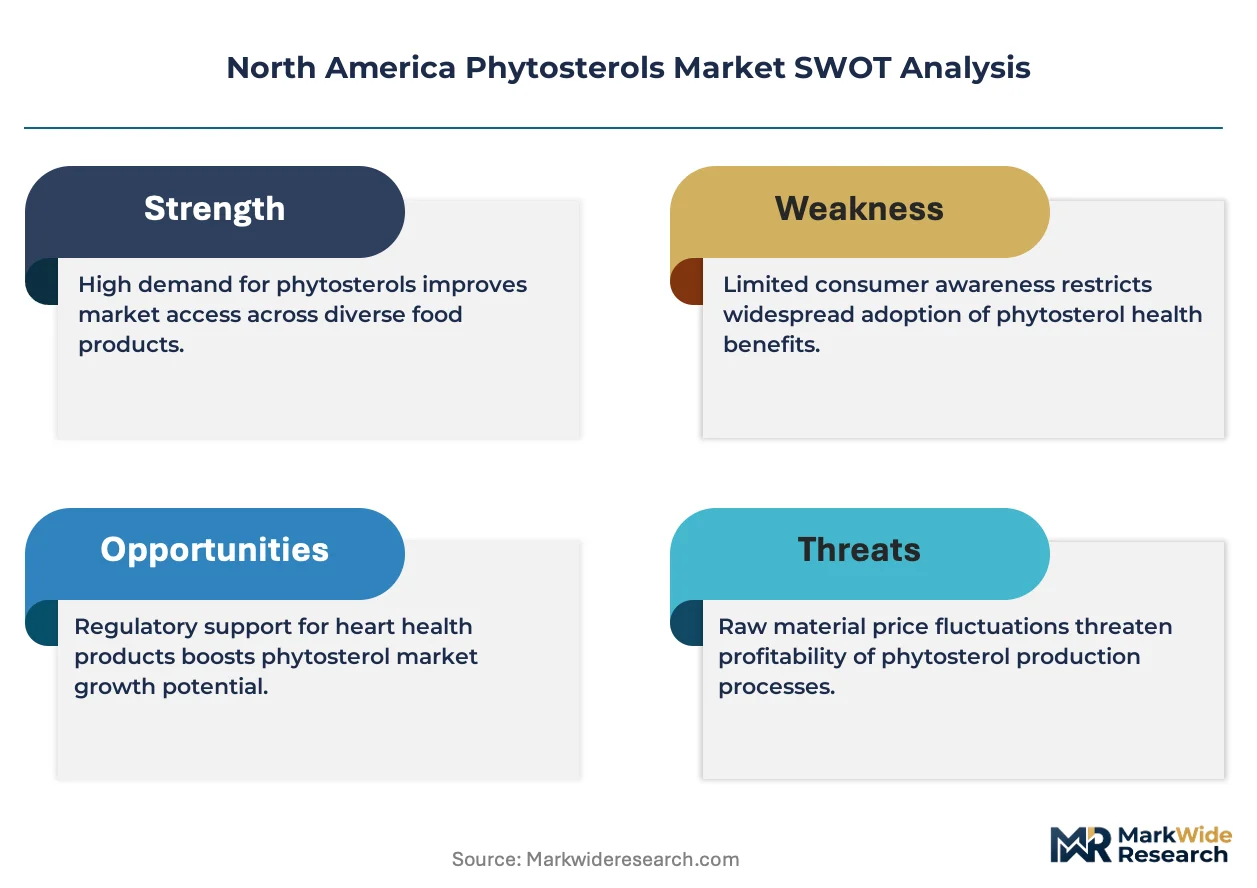
The FDA's qualified health claim framework permits specific cholesterol-lowering language on phytosterol-fortified foods, directly shaping product development and label strategy. Health Canada maintains parallel approval requirements through its Natural and Non-prescription Health Products Directorate, creating a dual-compliance environment for cross-border suppliers. USDA organic certification and non-GMO verification standards further segment market access tiers. Stakeholders must monitor evolving FDA enforcement discretion on structure-function claims and anticipate potential harmonization pressures between US and Canadian labeling regimes.
Market Dynamics
FDA-qualified health claims for cholesterol reduction anchor product positioning across functional food and supplement categories, while Health Canada's parallel NNHPD framework creates compliance complexity for cross-border suppliers.
Growth Catalysts
- FDA Health Claim Authorization:The qualified health claim framework permits specific coronary heart disease risk reduction language on phytosterol-fortified foods, directly validating consumer-facing marketing strategies and accelerating retail shelf placement.
- Oilseed Processor Upgrades:Canadian domestic refiners are expanding deodorizer distillate extraction capacity, tightening supply integration between prairie canola crushing and sterol purification operations.
- Direct-to-Consumer Channel Expansion:Supplement brands in California and Texas production clusters are bypassing traditional wholesale distribution through proprietary e-commerce platforms, compressing customer acquisition costs.
Market Restraints
- Tall Oil Supply Concentration:Pulp and paper industry byproduct dependency concentrates raw material sourcing in southeastern US kraft mills, exposing processors to forestry sector cyclicality.
- Non-GMO Verification Cost Structure:USDA organic certification and third-party non-GMO Project verification impose recurring audit burdens that disproportionately burden mid-tier formulators.
- Plant Sterol Ester Stability Limitations:Oxidative degradation during thermal processing restricts application in baked goods and frying applications, capping addressable food manufacturing segments.
Strategic Opportunities
- Midwest Grain Belt Proximity:Corn and soybean processing infrastructure in Iowa and Illinois offers captive feedstock access for integrated sterol ester production, reducing logistics exposure.
- Pharmaceutical-Grade Campesterol:High-purity campesterol for prescription therapeutic applications remains underdeveloped relative to beta-sitosterol dominance, creating margin expansion potential.
- Health Canada Harmonization Pressure:Cross-border label alignment initiatives may simplify dual-compliance burdens, reducing regulatory overhead for US-Canada integrated suppliers.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Gas chromatography and mass spectrometry expertise for sterol fingerprinting and adulteration detection remains concentrated in legacy pharmaceutical testing labs.
- Deodorizer Distillate Quality Variance:Incoming raw material heterogeneity from vegetable oil refiners forces batch-to-batch process adjustment, complicating continuous manufacturing scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Phytosterols Market |
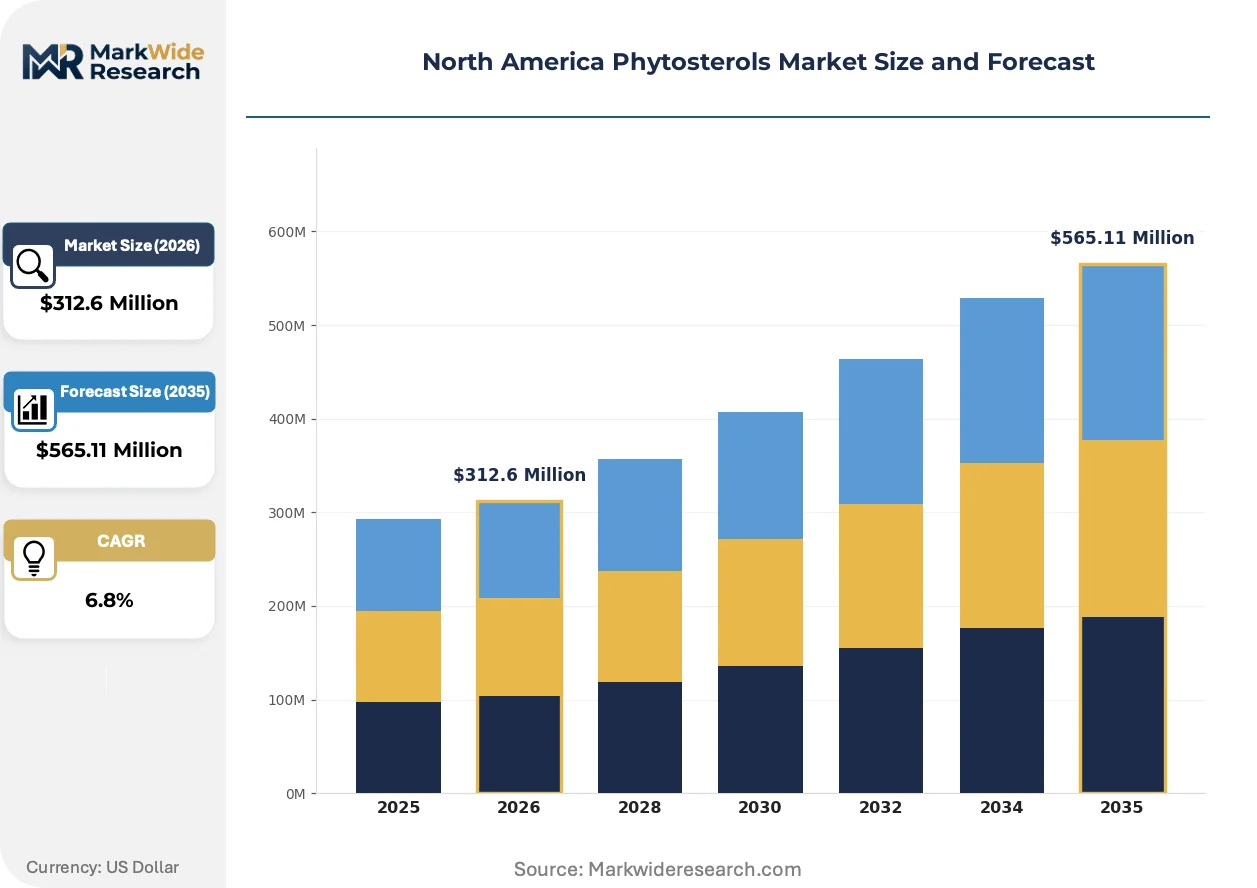
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-Sitosterol, Campesterol, Stigmasterol, Brassicasterol Application: Functional Foods, Nutraceuticals, Dietary Supplements, Cosmetics End User: Food Manufacturers, Pharmaceutical Companies, Personal Care Brands, Health Stores Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | BASF SE, Archer Daniels Midland Company, Cargill Incorporated, Arboris LLC, Ashland Global Holdings Inc, Pharmachem Laboratories, The Lubrizol Corporation, Berkshire Hathaway Inc, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Phytosterols Market Evolving Landscape
Supercritical CO2 extraction technology is collapsing capital barriers for mid-scale processors, while regulatory precision on structure-function claims tightens and direct-to-consumer brands rewire traditional distribution hierarchies.
Supercritical CO2 extraction systems are replacing solvent-based purification in deodorizer distillate processing, eliminating hexane residual concerns. Regional toll processors in Ontario and Ohio are adopting these units to serve contract manufacturing demand. This technology is collapsing the minimum efficient scale for pharmaceutical-grade sterol production, fragmenting supply concentration among legacy integrated producers.
Health Canada's NNHPD is tightening evidentiary requirements for cholesterol-lowering claims on natural health products, demanding randomized controlled trial data. This regulatory compression is forcing reformulation toward standardized sterol ester concentrations with documented bioavailability. Dietary supplement SKUs are consolidating as smaller brands retreat from claim substantiation costs.
Subscription-based replenishment models are displacing pharmacy and mass retail stocking for phytosterol supplements, capturing recurring revenue and consumer loyalty data. Direct-to-consumer brands in Austin and Toronto are pioneering personalized dosing algorithms based on self-reported lipid panels. This channel shift is most visible among millennial and Gen-X demographics in coastal US metros and Ontario urban centers.
North America Phytosterols Market Segmentation
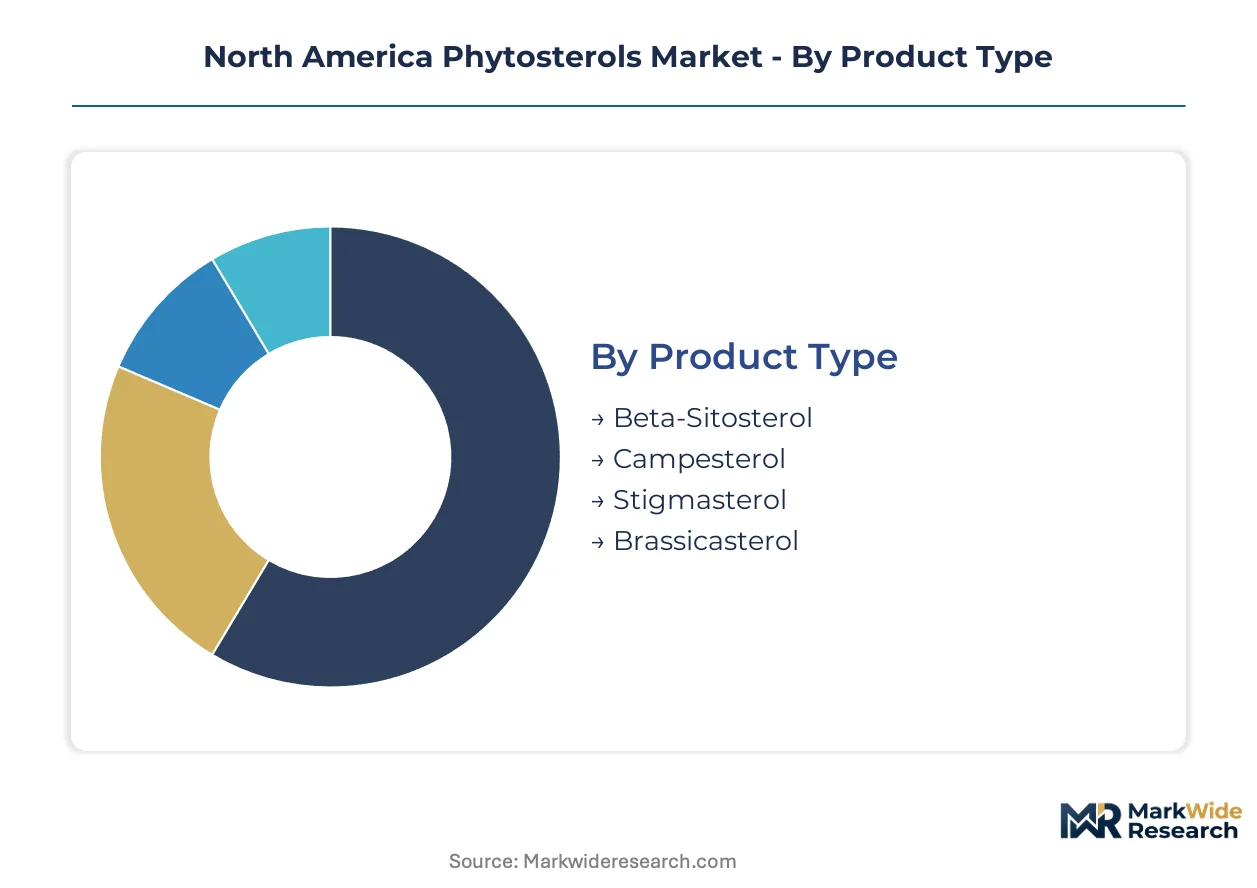
Phytosterol segmentation in North America reflects divergent technical specifications across product types and sharply contrasting channel velocities between institutional procurement and direct-to-consumer fulfillment. Understanding these fracture lines enables suppliers to align purification capacity with the shortest cash-conversion cycles.
Product Type:
Beta-sitosterol turns inventory fastest due to its abundance in soy and tall oil feedstocks, while brassicasterol sits longest given its rapeseed-specific sourcing and narrower formulation compatibility.
- Beta-Sitosterol:This C28H50O steroid alcohol constitutes the dominant phytosterol fraction in deodorizer distillates from soybean and tall oil processing. Demand concentrates in functional food fortification across Midwest manufacturing clusters, driven by FDA-qualified health claim authorization for cholesterol reduction labeling.
- Campesterol:A C28H48O isomer distinguished by its methyl group positioning, campesterol commands premium positioning in pharmaceutical-grade applications requiring higher purity thresholds. Texas and California nutraceutical formulators are concentrating procurement of this segment for prescription therapeutic development.
- Stigmasterol:Sourced primarily from soybean and calabar bean distillates, this compound serves as a key intermediate for steroid hormone synthesis in pharmaceutical manufacturing.
- Brassicasterol:Unique to cruciferous oil sources including canola and rapeseed, this sterol finds limited application in specialized cosmetic formulations and niche nutraceutical positioning.
Beta-sitosterol anchors the volume base while campesterol gains share at the steepest rate.
Application:
Cost-tier stratification separates high-volume commodity fortification from precision-dosed supplement positioning, with cosmetics commanding the widest margin spreads.
- Functional Foods:Margarine, yogurt, and orange juice fortification represent the most mature revenue pool, with Kroger and Safeway shelf placement validating consumer acceptance. Midwest dairy processors and California beverage co-packers are expanding sterol ester incorporation lines.
- Nutraceuticals:Softgel and tablet formulations targeting lipid management are climbing the fastest, with Austin and Toronto direct-to-consumer brands bypassing traditional wholesale distribution through proprietary subscription platforms.
- Dietary Supplements:Standalone phytosterol capsules and combination formulations with omega-3 fatty acids concentrate demand in specialty retail and practitioner channels.
- Cosmetics:Anti-aging topical applications leverage phytosterol emollient properties, with premium positioning in Sephora and Ulta Beauty retail networks.
Functional foods dominate absolute revenue contribution while nutraceuticals expand most quickly through digital channel migration.
End User:
Customer-type concentration varies from high-volume, price-sensitive food manufacturing procurement to specification-intensive pharmaceutical qualification protocols.
- Food Manufacturers:Unilever and Nestlé North American divisions anchor institutional demand for sterol ester concentrates, with annual contracting cycles and stringent supplier audit requirements.
- Pharmaceutical Companies:Prescription therapeutic developers are driving pharmaceutical-grade campesterol demand, with FDA active pharmaceutical ingredient qualification timelines extending procurement cycles.
- Personal Care Brands:L'Oréal and Estée Lauder subsidiaries are incorporating phytosterols into premium skincare lines, with clean beauty positioning requiring non-GMO verification.
- Health Stores:GNC and Vitamin Shoppe retail networks are ceding shelf space to direct-to-consumer brands, compressing wholesale margin structures.
Food manufacturers anchor the volume base while pharmaceutical companies gain share at the steepest rate.
Distribution Channel:
Geography-driven fulfillment speed separates same-day metro delivery from multi-day rural coverage, with channel selection directly constraining customer acquisition economics.
- Online Retail:Amazon and Shopify-powered brand storefronts are displacing pharmacy stocking for supplement categories, with California and Ontario fulfillment centers enabling next-day delivery to coastal metros.
- Specialty Stores:Independent natural products retailers in Boulder and Portland maintain curated phytosterol assortments, with trained staff consultation supporting premium pricing.
- Supermarkets:Kroger, Safeway, and Loblaws chains dominate functional food placement, with slotting fee structures favoring established CPG suppliers.
- Direct Sales:Practitioner-exclusive and multi-level marketing channels serve lipid panel-conscious consumers through personalized dosing guidance.
Supermarkets anchor the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deodorizer distillate availability clusters around soybean crushing and tall oil recovery operations, with Midwest grain infrastructure and southeastern pulp mills anchoring raw material flows. FDA and Health Canada claim frameworks create distinct compliance zones that shape cross-border product positioning.
United States
Midwest soybean processors in Iowa and Illinois supply beta-sitosterol feedstock through integrated crushing and refining networks. FDA-qualified health claims for cholesterol reduction validate functional food fortification strategies. California and Texas nutraceutical clusters concentrate direct-to-consumer brand development and subscription platform scaling.
Canada
Prairie canola crushing expansion in Alberta and Saskatchewan is tightening deodorizer distillate extraction integration. Health Canada's NNHPD maintains parallel cholesterol-lowering claim requirements, creating dual-compliance overhead for integrated suppliers. Ontario toll processors are adopting supercritical CO2 systems to serve contract manufacturing demand.
Mexico
Edible oil refining growth in Jalisco and Nuevo León is generating incremental sterol-rich byproduct streams. Mexico's national health regulator COFEPRIS maintains distinct natural health product registration pathways. Bajío Region oilseed processors are evaluating sterol recovery investments to capture value from deodorizer distillates.
North America Phytosterols Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying purified sterol fractions to formulators. The North American market exhibits tiered concentration, with integrated agribusiness conglomerates controlling raw material flows and mid-scale processors occupying toll purification niches. Three archetypes dominate: backward-integrated oilseed processors, pharmaceutical-grade specialty refiners, and direct-to-consumer brand operators. Capacity expansion and regulatory claim substantiation represent the dominant competitive vectors, with players investing in deodorizer distillate processing upgrades and bioavailability documentation.
Among German-headquartered chemical conglomerates, BASF SE exemplifies the integrated platform archetype through its sterol production network spanning feedstock to finished esters. Archer Daniels Midland Company and Cargill Incorporated represent the agribusiness-integrated tier, with both anchoring positions through captive control over Midwest grain elevator flows and in-house processing infrastructure.
| Leading Market Players |
|---|
| BASF SE |
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Arboris LLC |
| Ashland Global Holdings Inc |
| Pharmachem Laboratories |
| The Lubrizol Corporation |
| Berkshire Hathaway Inc |
| DuPont |
| Others |
Value Network & Pricing Analysis
Iowa and Illinois soybean processing clusters anchor North American beta-sitosterol feedstock availability, concentrating upstream capacity among integrated agribusiness operators and amplifying pricing power for pharmaceutical-grade campesterol fractions. FDA-qualified health claim authorization for cholesterol reduction creates tiered demand segmentation, with deodorizer distillate quality variance forcing batch-adjustment premiums that ripple through contract negotiations.
Pricing Analysis
FDA's qualified health claim framework dictates the pricing tier structure across North American phytosterol markets, separating pharmaceutical-grade campesterol from standard food-grade beta-sitosterol through purity thresholds and bioavailability documentation. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with USDA organic and non-GMO Project verification commanding recurring audit premiums. Pricing pressure stems from mid-tier formulators absorbing disproportionate compliance burdens, while direct-to-consumer nutraceutical brands exhibit lowest price sensitivity due to subscription-based recurring revenue models.
Supply Chain Analysis
Deodorizer distillate feedstock draws from United States, Canada, and Mexico vegetable oil refining operations, with Midwest soybean crushing and southeastern tall oil recovery anchoring raw material flows. Soybean deodorizer distillates, canola processing byproducts, and pulp mill tall oil fractions constitute the primary input streams. Single-source vulnerability concentrates in southeastern US kraft mill tall oil dependency, exposing processors to forestry sector cyclicality. Distribution runs through integrated oilseed processors controlling captive elevator-to-ester infrastructure alongside regional toll processors serving contract manufacturing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized gas chromatography and mass spectrometry expertise for sterol fingerprinting remains concentrated in legacy pharmaceutical testing infrastructure, creating bottlenecks for quality verification and adulteration detection that constrain mid-scale processor expansion.
For Market Incumbents: Pre-empt supercritical CO2 extraction technology adoption among Ontario and Ohio toll processors by securing exclusive equipment partnerships or acquisition options before capital barriers collapse further. Anchor backward integration into prairie canola crushing capacity as Canadian refiners expand deodorizer distillate extraction, denying feedstock access to emerging competitors. FDA enforcement discretion on structure-function claims represents the critical regulatory threat requiring proactive legal and scientific affairs investment. For New Entrants and Emerging Players: Pharmaceutical-grade campesterol for prescription therapeutic applications represents the most penetrable entry point, with Texas and California nutraceutical clusters showing unmet demand for high-purity fractions exceeding beta-sitosterol dominance. Midwest grain belt proximity offers captive corn and soybean feedstock access for integrated sterol ester production, reducing logistics exposure relative to coastal competitors. A go-to-market angle emphasizing documented bioavailability through randomized controlled trial partnerships addresses Health Canada NNHPD tightening evidentiary requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms with proprietary dosing algorithms and lipid panel data capture, positioning these archetypes for premium valuation multiples. Acquisition targets should prioritize toll processors with supercritical CO2 capacity and Health Canada dual-compliance infrastructure. The signal to watch is cross-border label harmonization momentum between FDA and Health Canada frameworks, which would reduce regulatory overhead and expand addressable market for integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Adoption | Eliminates hexane residual concerns while collapsing minimum efficient scale for pharmaceutical-grade production. |
| Backward Integration into Oilseed Crushing | Captive feedstock access from Midwest grain elevators tightens cost control against volatile deodorizer distillate spot markets. |
| Health Canada NNHPD Compliance Investment | Dual-certification infrastructure creates defensive moat as evidentiary requirements tighten for cholesterol-lowering claims. |
| Direct-to-Consumer Subscription Platform | Proprietary e-commerce channels bypass wholesale margin compression while capturing recurring revenue and consumer lipid data. |
| Pharmaceutical-Grade Campesterol Capacity | High-purity fraction production addresses underdeveloped prescription therapeutic segment relative to beta-sitosterol saturation. |
Research Methodology
The analysis maps deodorizer distillate extraction, sterol purification, esterification, and finished formulation sub-sectors, each validated through plant managers at oilseed processors, procurement leads at nutraceutical formulators, and regulatory affairs specialists navigating FDA and Health Canada frameworks. Primary interviews with toll processing operators and direct-to-consumer brand founders combined with secondary validation against USDA organic certification databases, FDA qualified health claim filings, and Health Canada NNHPD product registrations. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the forecast period.
Assumptions held fixed include FDA enforcement discretion patterns and Health Canada evidentiary requirement stability, while oilseed crush rates and tall oil recovery yields were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, application, end user, and distribution channel, with regional regulatory cluster effects incorporated. CAGRs were derived from installed capacity expansion timelines and channel velocity shifts, incorporating supercritical CO2 technology diffusion curves and subscription platform adoption rates as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in edible oil commodity prices, forestry sector output, or cross-border trade friction would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and technology adoption rates. Quarterly review of FDA enforcement actions, Health Canada NNHPD guidance updates, and supercritical equipment installation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Distillers Grains Market
Ingredients
Ben Oil Market
Ingredients
Europe Vegetable Oil Market
Ingredients
South America Protein Market
Ingredients
Alginate Market
Ingredients
Agar Market
Ingredients
Brazil Starch Derivatives Market
Ingredients
Protein Extracts from Single Cell Protein and Other Conventional Sources Market
Ingredients
Dill Seed Oil Market
Ingredients
China Beer Adjuncts Market
Ingredients
Plant Extracts Market
Ingredients
Valerian Root Oil Market
Ingredients
Brewer's Yeast Market
Ingredients
Europe Malt Extract Market
Ingredients
Farnesene Market
Ingredients
Asia-Pacific Gelatin Market