
 Fonio Flour Market | 2026-2036
Fonio Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Fonio Flour Market Analytics
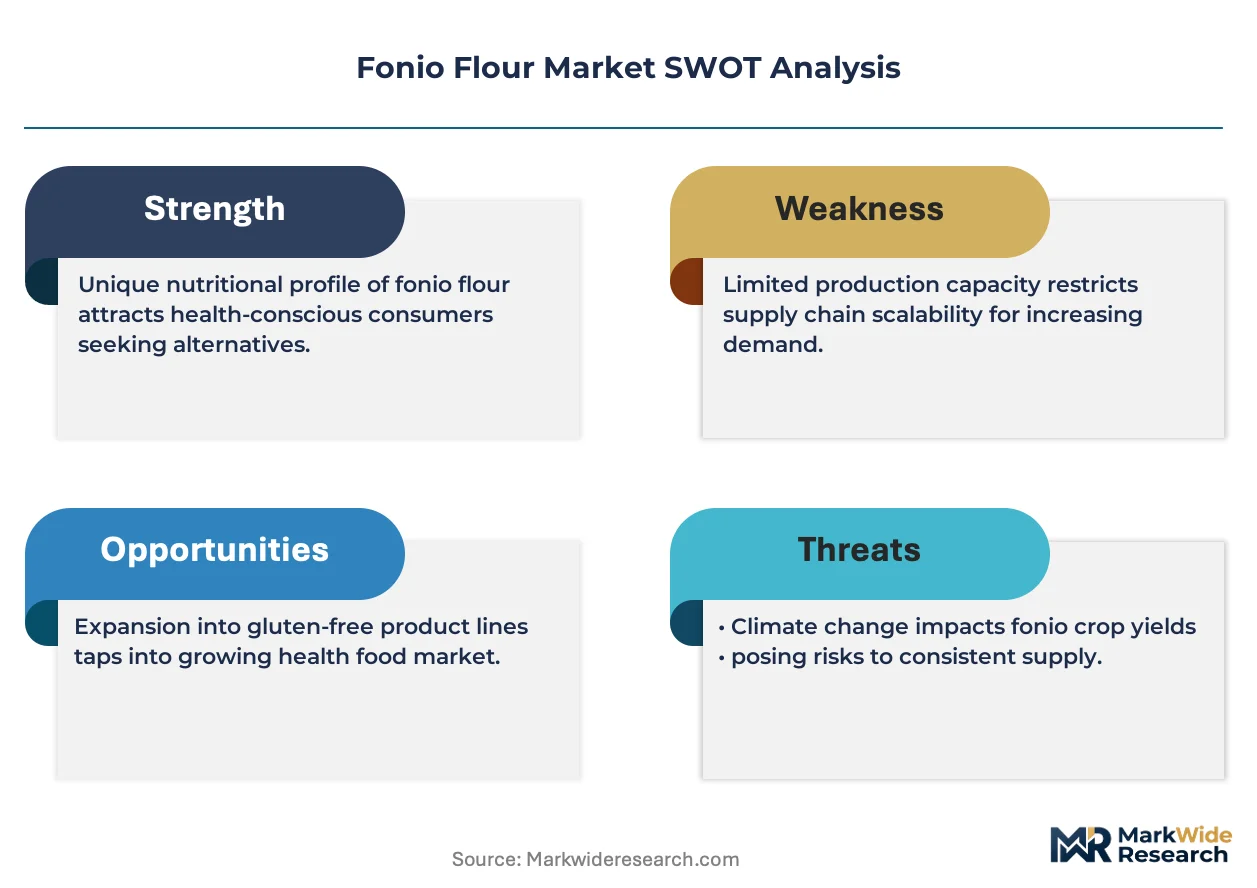
Specialty grain ingredient sourcing is tilting from commodity distributors toward vertically integrated processors with African origin control. Yolélé Foods leverages direct farmer partnerships in the Sahel to secure supply consistency. Terra Ingredients anchors its position through certified gluten-free milling infrastructure in the United States. Planet Fonio differentiates via organic certification and ethnic retail channel penetration across European metropolitan markets.
Fonio flour consists of milled seeds from Digitaria exilis, a drought-tolerant cereal native to West Africa, with protein content ranging from seven to nine percent and low glycemic index properties suited to diabetic-friendly and gluten-free formulations. The product serves industrial bakeries and specialty food manufacturers seeking ancient grain credentials and allergen-free ingredient alternatives. Organic fonio flour commands premium positioning in European and North American specialty retail, while instant fonio flour targets convenience-oriented home cooks through online retail channels. Baby food applications represent an emerging growth vector as clean-label infant nutrition brands seek novel carbohydrate sources with established cultural safety profiles.
FDA gluten-free labeling standards and EU Novel Food Catalogue determinations govern market access for fonio flour in major Western economies, with EFSA safety assessments enabling expanded foodservice use. West African export authorities coordinate phytosanitary certification with USDA and ECHA compliance requirements for pesticide residue thresholds. Stakeholders must monitor evolving organic equivalence agreements between African origin countries and destination regulators to protect supply chain eligibility.
Market Dynamics
West African supply concentration and EU Novel Food regulatory clearance are compressing sourcing timelines while expanding commercial access for specialty grain processors seeking ancient grain credentials.
Growth Catalysts
- FDA Gluten-Free Labeling Standards:Certified allergen-free positioning unlocks bakery and infant nutrition formulations in the United States, creating pull-through from industrial buyers.
- Clean-Label Processing Technologies:Stone-milling and cold-press methods preserve nutritional integrity while meeting premium positioning requirements in French and German retail channels.
- West African Export Corridors:Phytosanitary infrastructure investments in Senegal and Mali reduce transit variability for European and North American importers.
Market Restraints
- Sahel Rainfall Volatility:Drought-tolerant Digitaria exilis still faces yield compression during extended dry spells, constraining raw material availability.
- EU Novel Food Catalogue Compliance Costs:EFSA safety assessment requirements impose documentation burdens that exclude smaller West African cooperatives from direct market access.
- Quinoa and Te Substitution:Established ancient grain alternatives with deeper supply chains and lower price points capture shelf space in mainstream grocery.
Strategic Opportunities
- United States Baby Food Segment:Clean-label infant nutrition brands seek novel carbohydrate sources with established cultural safety profiles for premium positioning.
- Organic Equivalence Agreements:Negotiated recognition between African origin countries and USDA/EU organic frameworks would unlock premium tier access for certified producers.
- Instant Flour Convenience Formats:Pre-cooked fonio flour targeting online retail channels addresses time-constrained home cooks in metropolitan France and the United States.
Industry Challenges
- Phytosanitary Certification Timelines:Coordination between West African export authorities and USDA compliance requirements creates documentation bottlenecks.
- Specialized Milling Equipment Scarcity:Gluten-free certified infrastructure requires capital investment that mid-scale processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fonio Flour Market |
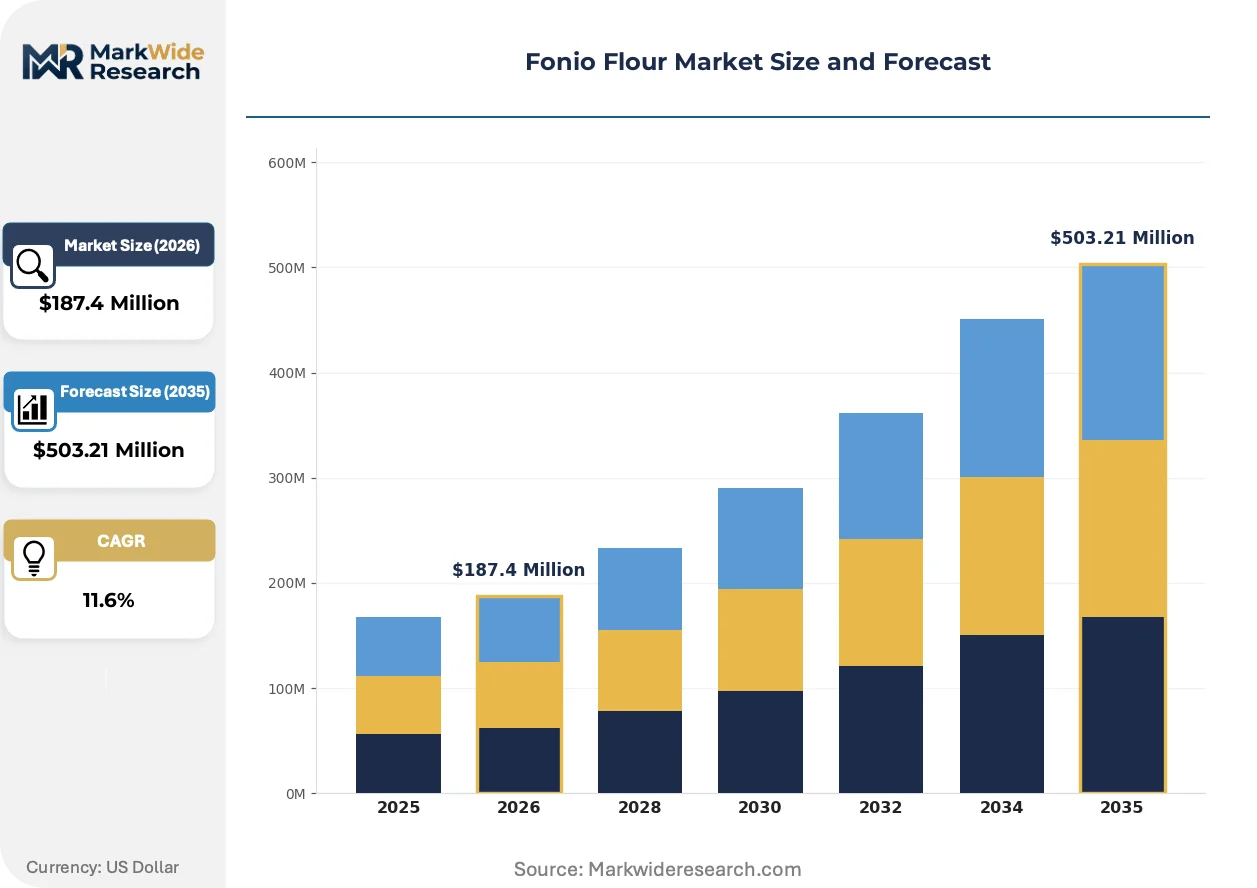
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Fonio Flour, Gluten-Free Fonio Flour, Regular Fonio Flour, Instant Fonio Flour End User: Bakeries, Food Manufacturers, Restaurants, Home Cooks Application: Baking, Snacks, Pasta, Baby Food Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Planet Fonio, Woodland Foods, Yolélé Foods, Amaati, Farafena, Terra Ingredients, IYA Foods, Quay Naturals, Aduna, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fonio Flour Market Evolving Landscape
Processing automation and regulatory harmonization are compressing time-to-market for ancient grain ingredients while reshaping how specialty flours reach industrial and retail buyers.
Near-infrared spectroscopy is digitizing quality control protocols at West African collection points. French and German importers now demand real-time moisture and protein verification before shipment release. This technology is digitizing trust mechanisms between origin suppliers and destination buyers, reducing rejection rates and accelerating payment cycles.
EU Novel Food Catalogue determinations governing Digitaria exilis have expanded foodservice use permissions across member states. Industrial bakery procurement teams in France and Germany now specify fonio flour in clean-label product development. The regulatory clarity is compressing formulation timelines for manufacturers previously hesitant to invest in unapproved ingredients.
Direct-to-manufacturer contracting is displacing commodity distributor intermediation for specialty grain sourcing. Vertically integrated processors with Sahel origin control now negotiate directly with United States and European bakery R&D teams. This channel compression is most visible in the gluten-free and organic segments where provenance verification commands price premiums.
Fonio Flour Market Segmentation
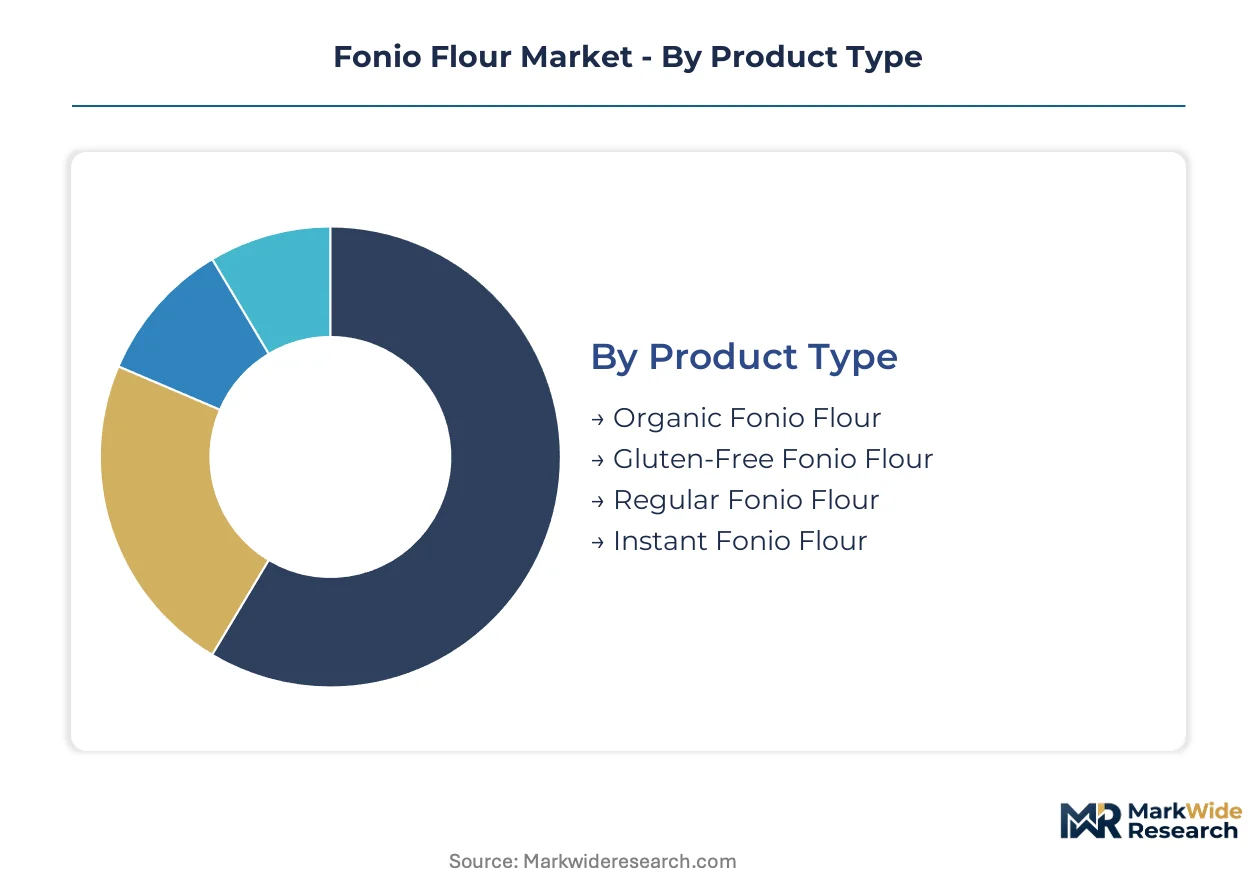
Segmentation in the fonio flour market reveals how certification tiers, end-use applications, and channel strategies create distinct commercial battlegrounds. Each dimension exposes where value concentrates and where new entrants can displace incumbents.
Product Type:
Certification tier and processing intensity segment the market into four distinct value propositions, with organic and gluten-free credentials commanding premium positioning.
- Organic Fonio Flour:Cultivated without synthetic inputs and certified under USDA or EU organic frameworks, this tier targets clean-label infant nutrition and premium bakery segments in France and Germany. Supply scarcity limits volume, locking in price premiums for processors with backward integration into certified Sahel farming cooperatives.
- Gluten-Free Fonio Flour:Milled in dedicated allergen-free facilities with batch testing protocols, this specification serves celiac-safe product lines and FDA-compliant labeling requirements. Industrial bakeries in the United States specify this grade for reformulation projects replacing wheat in ancient grain bread.
- Regular Fonio Flour:Standard milled product without certification overlays, serving ethnic retail and foodservice channels where provenance matters more than third-party verification.
- Instant Fonio Flour:Pre-cooked and dehydrated for rapid reconstitution, targeting convenience-oriented home cooks through direct-to-consumer online channels.
Organic fonio flour commands the established base. The steepest expansion runs through gluten-free certification tiers.
End User:
Customer scale and technical capability determine procurement patterns, with industrial buyers driving specification standards while household demand fragments across channels.
- Bakeries:Artisan and industrial producers seeking ancient grain differentiation and allergen-free formulations, particularly in gluten-free specialty segments across metropolitan France.
- Food Manufacturers:CPG companies integrating fonio into clean-label snack and cereal lines, with R&D teams prioritizing supply security through direct processor contracts.
- Restaurants:Farm-to-table and West African cuisine establishments featuring fonio in signature dishes, creating visibility-driven pull through retail.
- Home Cooks:Health-conscious consumers discovering fonio through recipe content and specialty retail discovery, with purchase frequency rising through instant format availability.
Food manufacturers anchor volume commitments. Restaurants generate the fastest awareness-to-trial conversion.
Application:
Functional requirements and formulation complexity create divergent demand profiles across food categories, with infant nutrition imposing the strictest safety protocols.
- Baking:Primary volume driver encompassing bread, pastry, and gluten-free alternative formulations where fonio's binding properties and mild flavor profile enable partial wheat replacement.
- Snacks:Extruded and puffed applications in ancient grain chip and cracker segments, with texture optimization driving processor R&D investment.
- Pasta:Noodle and couscous analogs targeting gluten-free and heritage grain positioning in Italian and French retail.
- Baby Food:Emerging segment where EFSA Novel Food clearance and established West African consumption history support clean-label carbohydrate sourcing for premium infant nutrition brands.
Baking absorbs the bulk of current supply. Baby food applications are climbing the fastest as regulatory barriers fall.
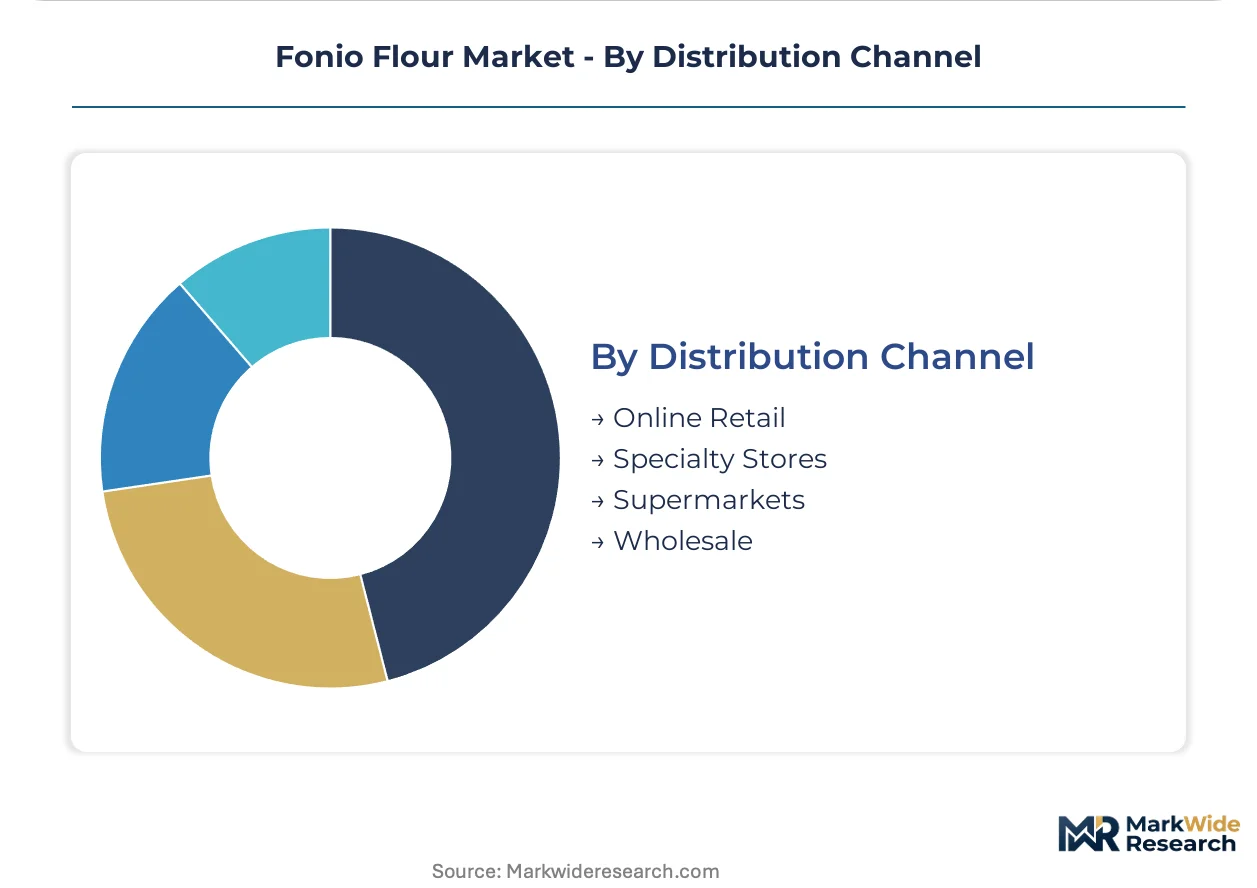
Distribution Channel:
Channel selection reflects customer sophistication and purchase urgency, with digital discovery reshaping how specialty grains reach new adopters.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription models and educational content integration, critical for instant format penetration among time-constrained urban households.
- Specialty Stores:Independent grocers and natural food retailers where staff expertise and sampling drive trial among health-motivated shoppers seeking ancient grain discovery.
- Supermarkets:Mainstream grocery placement remains limited to dedicated gluten-free or international aisles, with expansion contingent on consumer education investment.
- Wholesale:Foodservice distributors and industrial ingredient suppliers serving bakery and restaurant accounts with volume pricing and technical support.
Specialty stores maintain the core customer relationship. Online retail is expanding most quickly through convenience format alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States buyers absorb premium pricing for certified gluten-free grades, while West African procurement remains volume-sensitive and price-driven. European markets split between France's heritage-grain willingness-to-pay and Germany's specification-driven industrial sourcing.
United States
FDA gluten-free labeling standards and clean-label infant nutrition trends pull certified fonio flour into bakery and baby food formulations. The agency's enforcement of allergen-free claims creates compliance barriers that favor established importers with dedicated milling infrastructure. Brooklyn and Oakland anchor specialty food manufacturing clusters where ancient grain R&D teams specify Sahel-origin supply.
France
EU Novel Food Catalogue clearance for Digitaria exilis expanded foodservice permissions, accelerating restaurant and artisan bakery adoption. ANSM and DGCCRF oversight of novel ingredient safety documentation favors processors with EFSA-compliant dossiers. Paris and Marseille metropolitan areas concentrate West African diaspora demand and farm-to-table restaurant experimentation with heritage grains.
Germany
Industrial bakery procurement teams specify fonio for clean-label reformulation projects, driven by BfR guidance on ancient grain safety assessments. REACH-compliant processing additives and organic certification equivalence requirements filter supplier eligibility. Berlin and Hamburg house gluten-free CPG innovation labs where technical buyers evaluate binding properties against quinoa benchmarks.
Senegal
Sahel rainfall patterns and phytosanitary infrastructure investments determine raw material availability for export corridors. The country's national food safety authority coordinates USDA and ECHA compliance certification with Dakar port logistics. Thiès and Kaolack processing zones concentrate dehulling and pre-cleaning capacity serving European and North American importers.
Mali
Drought-tolerant Digitaria exilis cultivation faces yield compression during extended dry spells, constraining supply scalability for international buyers. The national agricultural regulator manages organic equivalence documentation gaps that limit premium tier access. Ségou and Sikasso farming cooperatives supply collection points where near-infrared spectroscopy digitizes quality verification for French importers.
Fonio Flour Market Competitive Landscape
Origin-anchored processors and certification-specialized millers split the market along supply security versus technical compliance vectors. The vendor base concentrates among vertically integrated Sahel operators, United States-based gluten-free infrastructure owners, and European organic certification holders. Three archetypes dominate: backward-integrated African origin controllers, allergen-free facility operators, and ethnic channel specialists. Competitive moves center on direct-to-manufacturer contracting displacement of distributors, and organic equivalence agreement lobbying to unlock premium tier access.
Within the origin-control archetype, Yolélé Foods and Planet Fonio exemplify divergent geographic anchoring strategies. Yolélé Foods represents the direct farmer partnership model with Sahel supply base integration. Planet Fonio occupies the European metropolitan penetration position with organic certification emphasis. Terra Ingredients anchors the United States gluten-free milling infrastructure tier, serving industrial bakery specification requirements through certified allergen-free batch protocols. These three illustrate how certification tier and geographic control combine into defensible positioning.
| Leading Market Players |
|---|
| Planet Fonio |
| Woodland Foods |
| Yolélé Foods |
| Amaati |
| Farafena |
| Terra Ingredients |
| IYA Foods |
| Quay Naturals |
| Aduna |
| Others |
Value Network & Pricing Analysis
Dakar-to-Marseille freight corridors impose cost volatility that amplifies price spreads between certified organic tiers and conventional grades, compressing margins for mid-scale processors while rewarding backward-integrated operators with captive Sahel farming networks.
Pricing Analysis
After-sales technical service and formulation consulting drive lifetime value for industrial bakery accounts. Three-tier pricing structure across organic-certified, gluten-free, and conventional grades separates premium positioning from commodity alternatives. Price differentiation rests on EU Novel Food dossier completeness and USDA organic equivalence status. Pricing pressure stems from quinoa and teff substitution in mainstream gluten-free aisles. Food manufacturers exhibit lowest price sensitivity due to reformulation lock-in costs, while ethnic retail channels remain highly elastic.
Supply Chain Analysis
Supplier-financing facilities extended by French and German importers enable Sahel cooperatives to bridge harvest-to-shipment cash gaps. Geographic concentration centers on Senegal, Mali, and Burkina Faso for raw fonio grain. Processing draws from dehulling equipment, gluten-free certified milling infrastructure, and phytosanitary testing protocols. Single-source vulnerability runs through Dakar port capacity constraints during peak export windows. Distribution runs through direct-to-manufacturer contracting displacing commodity distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand through technical formulation support and EFSA compliance consulting, recurring revenue layers that outpace raw ingredient growth as industrial bakeries seek ancient grain certification expertise.
For Market Incumbents: Harden supply security through certified organic farming cooperative equity stakes in Mali and Senegal, insulating against Sahel rainfall volatility. Deepen EFSA dossier capabilities to accelerate Novel Food clearance timelines for emerging applications. Quinoa substitution in German retail channels demands defensive pricing discipline.
For New Entrants and Emerging Players: United States baby food manufacturers represent the most penetrable white-space target, with clean-label infant nutrition brands actively sourcing novel carbohydrates. Instant flour convenience formats unlock direct-to-consumer online channels with lower regulatory barriers than industrial supply. Lead with organic certification and West African provenance storytelling to differentiate.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified African agricultural conglomerates with underutilized fonio processing assets and dormant EU organic certifications. Long-term viability hinges on organic equivalence agreement negotiation success between West African regulators and USDA frameworks. Watch EFSA safety assessment expansion into novel foodservice categories as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | Unlocks premium tier access through USDA and EU organic framework compliance. |
| Direct Farmer Partnership Expansion | Secures supply consistency against Sahel rainfall volatility for industrial accounts. |
| Gluten-Free Facility Certification | Enables FDA-compliant labeling for celiac-safe bakery formulations. |
| Instant Flour Format Development | Captures convenience-oriented home cooks through direct-to-consumer channels. |
| EFSA Dossier Completion | Accelerates foodservice permissions across EU member states for Digitaria exilis. |
Research Methodology
Operator-level perspectives from fonio mill operations managers, EU Novel Food regulatory consultants, industrial bakery procurement directors, and West African export authority officials anchored the qualitative base. Secondary validation drew from EFSA safety assessment databases, USDA organic certification records, EU Novel Food Catalogue determinations, and West African customs export statistics. Bottom-up volume modeling triangulated against top-down category spend analysis.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across certification tier, end-use application, and distribution channel dimensions. CAGRs derived from historical growth pattern extrapolation adjusted for regulatory inflection points. Forecast inputs incorporated phytosanitary infrastructure investment timelines and organic equivalence agreement negotiation status.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by quinoa and teff suppliers would shift outcomes. Macroeconomic volatility in West African export corridors, regulatory delays in EFSA determinations, or technological breakthroughs in alternative ancient grain cultivation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Dietary Fibers Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Cocoa Maker Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Bread Flour Market
Ingredients
Brewer's Yeast Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
Blackcurrant Concentrate Market
Ingredients
US Choline Bitartrate Market
Ingredients
Dried Tomato Lycopene-Rich Flake Ingredients Market
Ingredients
Kilned Malt Market
Ingredients
Horehound Extract Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
United States Avocado Oil Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Blue Light Protection Ingredients Market